
 Semi-Autonomous and Autonomous Bus Market | 2026-2036
Semi-Autonomous and Autonomous Bus Market Size, Share, and Industry Trends Forecast 2026-2036
Semi-Autonomous and Autonomous Bus Market Analytics
The EU Green Deal's zero-emission fleet mandates is rebalancing procurement criteria across European municipal buyers. AB Volvo leverages its integrated electric drivetrain and autonomous software stack to dominate Nordic pilot deployments. Daimler Truck AG sustains engineering intensity in Level-4 highway coaching applications. NVIDIA Corporation anchors the perception-layer supply chain through its DRIVE platform partnerships with multiple OEMs.
Semi-autonomous and autonomous buses integrate sensor fusion architectures—combining LiDAR point-cloud mapping, stereo camera arrays, and 4D imaging radar—to execute path planning in mixed-traffic environments without human intervention. Their primary purpose is to reduce per-kilometer operating costs while expanding transit coverage in low-density corridors where conventional fixed-route service is economically unviable. Fully autonomous buses command premium valuation in closed-campus deployments where geofencing simplifies regulatory approval. Semi-autonomous platforms with driver-assist functionality occupy the largest near-term revenue pool as transit authorities phase in automation gradually. On-demand autonomous shuttles represent the fastest-expanding deployment model, with LiDAR systems capturing the dominant share of technology spending.
The US National Highway Traffic Safety Administration and the European Union's Vehicle General Safety Regulation jointly shape homologation pathways, with NHTSA's exemption process governing pilot scale and the EU's type-approval framework dictating cross-border fleet deployment. China's Ministry of Industry and Information Technology issues GB standards for connected vehicle data security that constrain foreign platform access. Stakeholders must monitor which regulatory jurisdiction first mandates driver-out operation in mixed traffic, as that precedent will cascade into procurement specifications across all three markets.
Market Dynamics
The EU Green Deal's zero-emission fleet mandates are compressing electrification timelines for autonomous platforms, forcing transit authorities to synchronize battery-electric drivetrain procurement with sensor-suite upgrades in single capital cycles.
Growth Catalysts
- EU Green Deal mandates:Zero-emission urban fleet requirements in Oslo, Copenhagen, and Amsterdam are accelerating combined electric-autonomous procurement tenders.
- China's tier-one municipal funding:Dedicated autonomous bus corridors in Beijing, Shanghai, and Shenzhen provide infrastructure certainty that reduces operator deployment risk.
- Sensor fusion maturation:LiDAR-stereo camera-4D radar integration is reaching cost thresholds that enable mixed-traffic operation without safety-driver redundancy.
Market Restraints
- LiDAR supply concentration:High-performance solid-state units depend on a narrow supplier base in North American and Israeli component ecosystems.
- GB standards data localization:China's MIIT-connected vehicle regulations constrain foreign autonomous platform access to domestic transit procurement.
- Homologation timeline fragmentation:NHTSA's exemption process and the EU's type-approval framework create divergent certification pathways that inflate engineering overhead.
Strategic Opportunities
- Closed-campus geofencing:University and corporate campus deployments in Singapore and Dubai bypass mixed-traffic regulatory complexity.
- On-demand shuttle models:Dynamic routing algorithms enable service in low-density corridors where fixed-route economics fail.
- Battery-electric convergence:Shared thermal management between autonomous compute racks and electric drivetrains reduces per-vehicle packaging volume.
Industry Challenges
- Functional safety engineer scarcity:ISO 26262 and SOTIF certification expertise concentrates in automotive Tier-1 supplier workforces, not transit operator organizations.
- Legacy fleet integration:CAN bus protocol mismatches between autonomous retrofit kits and existing diesel-electric hybrid inventories delay pilot scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semi-Autonomous and Autonomous Bus Market |
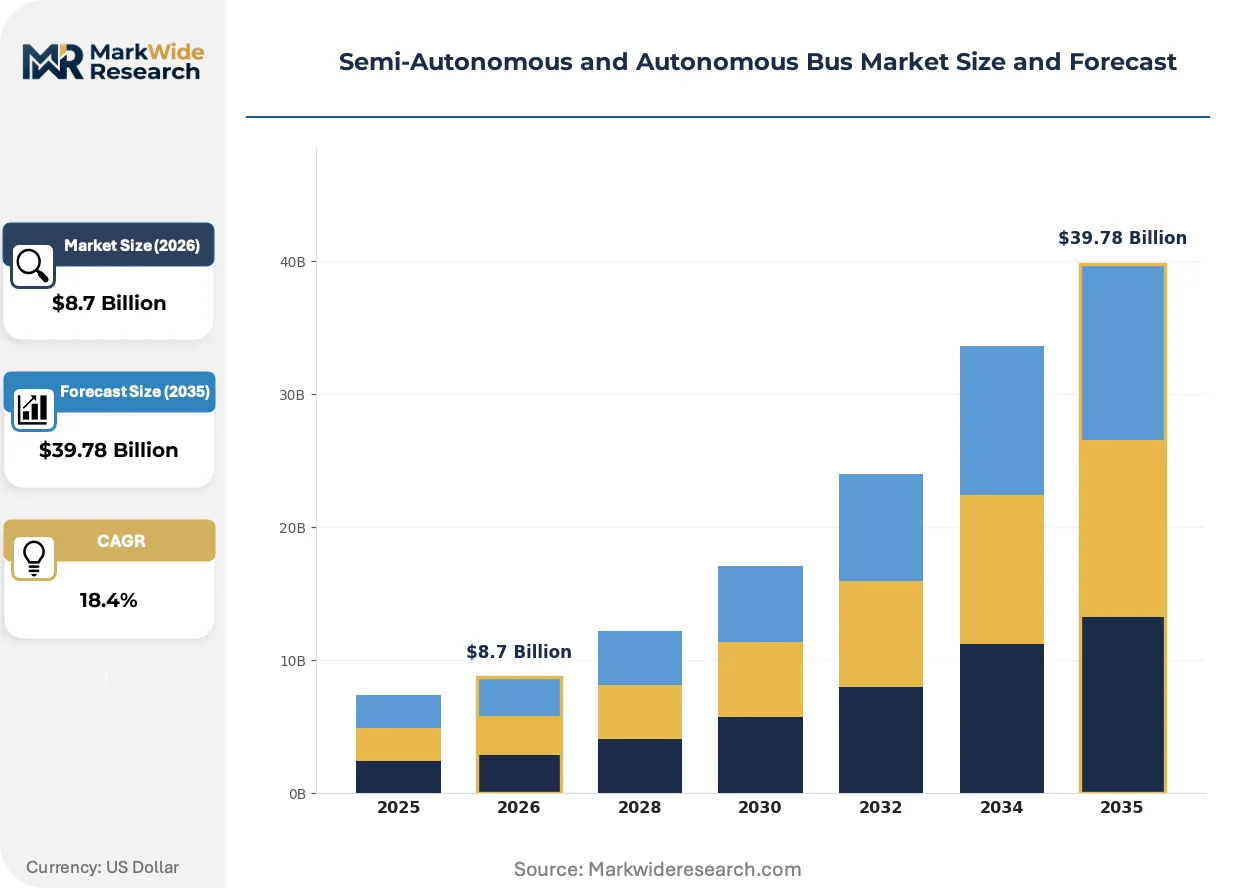
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fully Autonomous Buses, Semi-Autonomous Buses, Electric Buses, Hybrid Buses Deployment Model: On-Demand Services, Scheduled Services, Public Transit, Shuttle Services End User: Public Transport Authorities, Private Fleet Operators, Schools, Corporate Transport Services Technology: LiDAR Systems, Computer Vision, Radar, V2X Communication |
| Companies Covered | AB Volvo, Daimler Truck AG, Proterra, Robert Bosch GmbH, Continental AG, NVIDIA Corporation, NFI Group Inc., Iveco S.p.A., Navya, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semi-Autonomous and Autonomous Bus Market Evolving Landscape
Autonomous bus development is pivoting from technology demonstration to operational economics, with sensor architectures and regulatory frameworks converging to enable driver-out revenue service.
LiDAR point-cloud processing hardware is modularizing into swappable edge-compute units that transit authorities can upgrade without full vehicle replacement. Nordic pilot operators in Oslo and Gothenburg are deploying these field-replaceable perception modules to extend fleet depreciation schedules. This modularity is compressing technology obsolescence risk and enabling incremental capability upgrades across 12-year asset lifecycles.
The EU's Vehicle General Safety Regulation is mandating automated emergency braking and lane-keeping as baseline requirements, creating regulatory scaffolding that eases subsequent Level-4 approvals. This harmonization is reducing homologation duplication costs for OEMs targeting cross-border fleet sales. German and French transit authorities are leveraging this framework to consolidate procurement specifications across municipal boundaries.
Service contracting is fragmenting from vehicle purchase toward availability-based performance agreements. Dutch and Singaporean operators now specify uptime guarantees and per-kilometer service fees rather than capital asset ownership. This transfer of operational risk to technology integrators is most advanced in airport and campus shuttle segments where route predictability simplifies liability allocation.
Semi-Autonomous and Autonomous Bus Market Segmentation
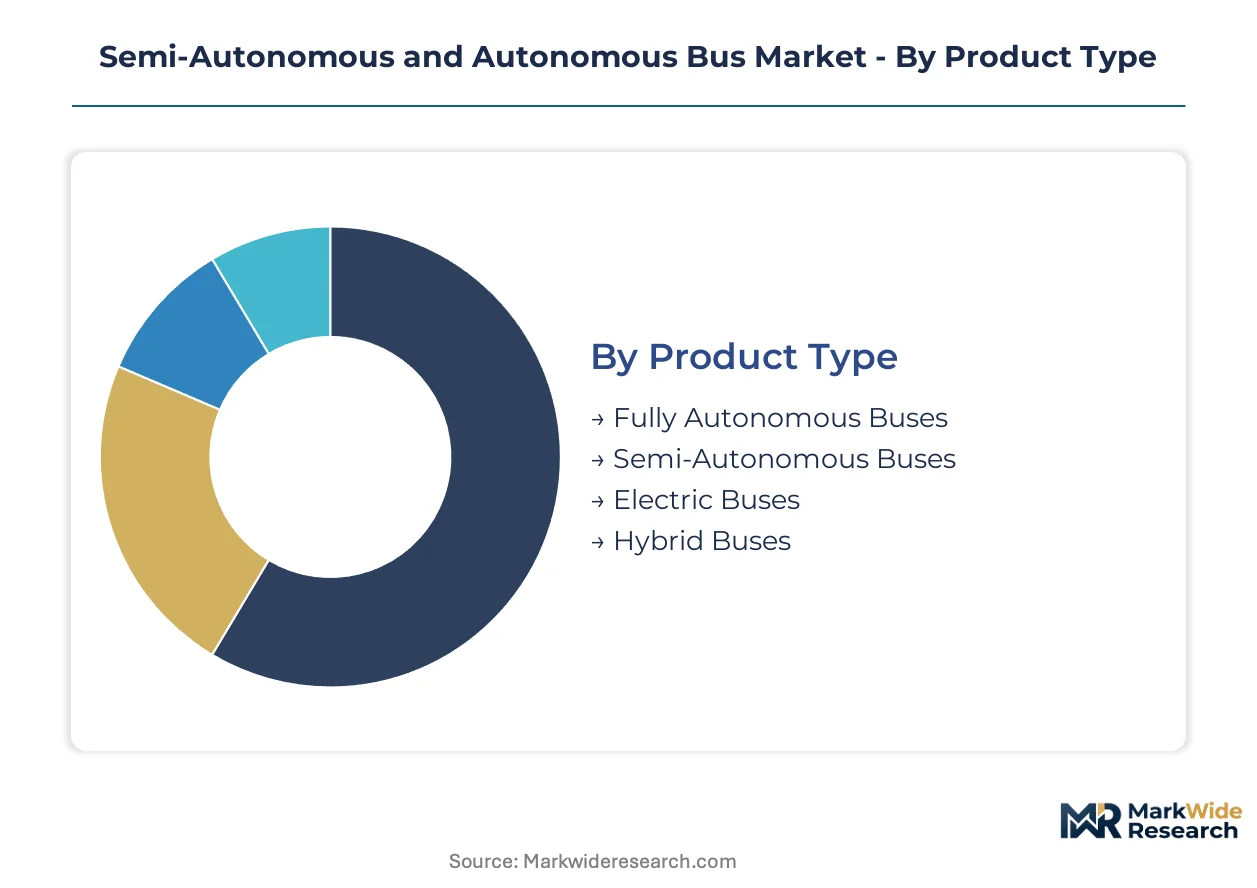
Segmentation in the semi-autonomous and autonomous bus market reveals how procurement decisions split between automation maturity levels and operational deployment contexts. Transit authorities weigh capital intensity against route predictability when selecting across these dimensions.
Product Type:
Automation maturity and powertrain architecture define procurement specifications across municipal and private fleet tenders.
- Fully Autonomous Buses:Level-4 automation platforms eliminate driver positions through sensor fusion stacks integrating LiDAR, camera arrays, and redundant compute. Singapore's Nanyang Technological University and Dubai's Expo City deploy these in geofenced environments where regulatory approval pathways are streamlined.
- Semi-Autonomous Buses:Driver-assist systems with automated emergency braking and lane-keeping dominate near-term procurement volumes. Oslo's Ruter and Amsterdam's GVB phase these in as transitional technology before full automation, reducing per-kilometer labor costs while retaining safety-driver redundancy.
- Electric Buses:Battery-electric platforms with integrated autonomous compute thermal management address EU Green Deal zero-emission mandates.
- Hybrid Buses:Diesel-electric or hydrogen-electric configurations serve corridors where charging infrastructure remains underdeveloped.
Mature deployment sits with semi-autonomous platforms. Newer deployment is concentrated in fully autonomous configurations.
Deployment Model:
Service architecture determines sensor suite specifications and regulatory complexity for operators.
- On-Demand Services:Dynamic routing algorithms adjust vehicle paths based on real-time passenger requests rather than fixed schedules. Beijing's Baidu Apollo and Shenzhen's WeRide pilot these in designated autonomous corridors where municipal infrastructure investment reduces operational uncertainty.
- Shuttle Services:Closed-loop campus and airport routes with predictable traffic patterns enable earlier driver-out operation. Singapore's Changi Airport and Dubai's Mohammed Bin Rashid Aerospace Hub specify uptime-guaranteed performance contracts for these deployments.
- Scheduled Services:Fixed-route operation with predetermined stops matches conventional transit planning frameworks.
- Public Transit:Open-road municipal service faces the steepest regulatory barriers and liability complexity.
Shuttle services carry the steepest expansion trajectory. Public transit conversion lags due to mixed-traffic homologation requirements.
End User:
Procurement authority type shapes automation adoption timelines and risk tolerance.
- Public Transport Authorities:Municipal agencies in Oslo, Copenhagen, and Amsterdam consolidate zero-emission and automation requirements into single tender cycles under EU Green Deal compliance pressure.
- Corporate Transport Services:Private campus operators at technology parks and industrial zones bypass public-road regulatory frameworks through geofenced deployments.
- Private Fleet Operators:Contracted service providers assume technology risk through availability-based agreements rather than capital ownership.
- Schools:Dedicated student transport routes with enhanced safety requirements drive demand for redundant sensor architectures.
Public transport authorities dominate committed procurement volumes. Corporate transport services are gaining share fastest through simplified deployment pathways.
Technology:
Perception-layer component selection determines system cost and environmental robustness.
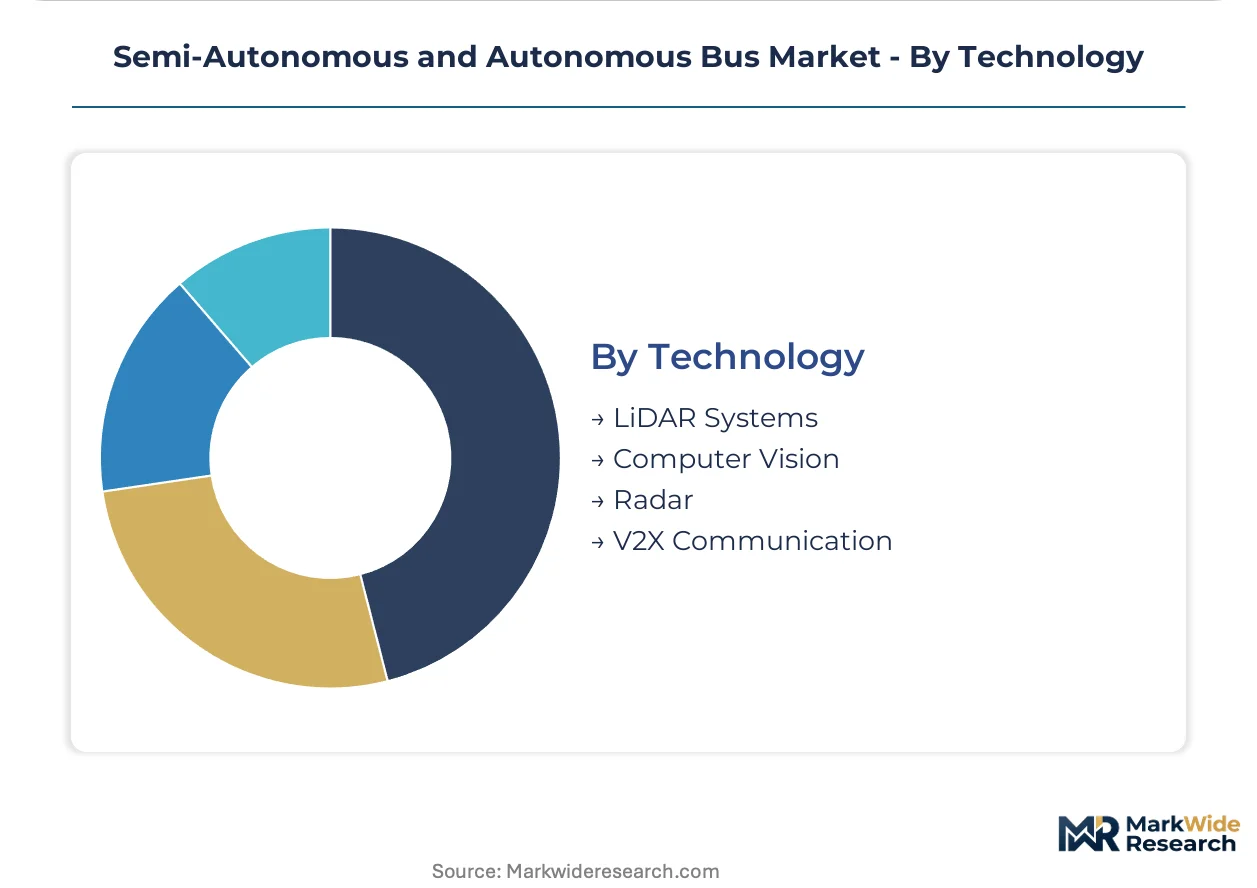
- LiDAR Systems:Solid-state and mechanical spinning units generate high-resolution point clouds for 3D environmental mapping. High-performance units from North American and Israeli suppliers command premium positioning in mixed-traffic pilot specifications.
- Computer Vision:Stereo camera arrays with neural network processing handle object classification and traffic signal recognition. Chinese tier-one city deployments leverage domestic camera supply chains constrained by MIIT data localization requirements.
- Radar:4D imaging radar provides velocity detection and adverse-weather redundancy where optical sensors degrade.
- V2X Communication:Vehicle-to-infrastructure and vehicle-to-vehicle protocols enable cooperative perception beyond onboard sensor range.
LiDAR systems anchor technology spending in premium deployments. Computer vision is climbing fastest through cost reduction and domestic supply expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beijing's dedicated autonomous bus corridors anchor the most concentrated deployment activity worldwide, with municipal infrastructure investment reducing operator risk across multiple pilot zones.
China
Baidu Apollo and WeRide operate extensive pilot fleets in Beijing, Shanghai, and Shenzhen where tier-one municipal governments fund dedicated autonomous corridors. MIIT's GB standards for connected vehicle data security constrain foreign platform access while privileging domestic technology stacks. The Yangtze River Delta cluster around Shanghai hosts the densest concentration of sensor fusion engineering talent.
Singapore
Nanyang Technological University and Changi Airport deploy fully autonomous shuttles in geofenced environments with streamlined regulatory approval. The Land Transport Authority consolidates procurement specifications across campus and airport segments. Jurong Island's industrial zone hosts corporate fleet pilots bypassing mixed-traffic complexity.
Germany
Daimler Truck AG sustains Level-4 highway coaching development from Stuttgart engineering centers. The EU's Vehicle General Safety Regulation harmonizes type-approval frameworks across German-French transit authority procurement. Hamburg and Berlin municipal operators phase semi-autonomous platforms into fixed-route service under EU Green Deal zero-emission mandates.
Norway
Oslo's Ruter and Gothenburg pilots deploy field-replaceable LiDAR perception modules to extend fleet depreciation schedules. AB Volvo dominates Nordic deployments through integrated electric drivetrain and autonomous software offerings. The Oslofjord corridor concentrates Europe's most advanced mixed-traffic autonomous bus testing.
United Arab Emirates
Dubai's Expo City and Mohammed Bin Rashid Aerospace Hub specify uptime-guaranteed performance contracts for closed-campus autonomous shuttle service. The Roads and Transport Authority accelerates pilot scaling through geofencing simplification. Dubai South's logistics corridor hosts the Gulf's largest concentration of autonomous fleet trials.
Semi-Autonomous and Autonomous Bus Market Competitive Landscape
The competitive structure tilts toward integrated automotive OEMs with captive electric drivetrain capabilities. Consolidation pressure concentrates among European and Asian manufacturers with established transit authority relationships. Three archetypes dominate: full-stack OEMs controlling sensor-to-software integration; Tier-1 component suppliers anchoring perception-layer supply chains; and technology platforms licensing compute architectures across multiple vehicle programs. Dominant competitive moves include strategic partnerships between drivetrain manufacturers and autonomous software developers, plus geographic expansion through municipal pilot tenders.
Among European-based integrated manufacturers, AB Volvo and Daimler Truck AG exemplify the full-stack OEM archetype with combined electric-autonomous offerings. NVIDIA Corporation anchors the technology platform tier through its DRIVE compute architecture licensed across multiple OEM programs. These three occupy positions spanning hardware integration, regulatory homologation expertise, and software scalability respectively.
| Leading Market Players |
|---|
| AB Volvo |
| Daimler Truck AG |
| Proterra |
| Robert Bosch GmbH |
| Continental AG |
| NVIDIA Corporation |
| NFI Group Inc. |
| Iveco S.p.A. |
| Navya |
| Others |
Value Network & Pricing Analysis
Lithium carbonate spot indices cascade through battery-electric drivetrain procurement into tiered autonomous bus pricing, with EU Green Deal compliance premiums compressing mid-tier margins while solid-state LiDAR modules anchor premium configurations.
Pricing Analysis
Uptime-guaranteed availability contracts dominate municipal procurement, replacing capital asset ownership with per-kilometer service fees. Price differentiation hinges on sensor redundancy tiers and ISO 26262 certification levels, with mixed-traffic-ready platforms commanding substantial premiums over geofenced campus configurations. Cost compression in semi-autonomous platforms is intensifying because Chinese domestic camera supply chains undercut Western LiDAR dependencies. Public transport authorities exhibit highest price sensitivity due to consolidated tender cycles, while corporate campus operators absorb premium pricing for streamlined regulatory pathways.
Supply Chain Analysis
Ocean freight rate volatility from Asia-Pacific manufacturing hubs disrupts just-in-time delivery of solid-state LiDAR units and autonomous compute modules. Component sourcing concentrates in China, South Korea, and Israel, with high-performance perception hardware drawing from narrow North American and Israeli supplier ecosystems. Single-source vulnerability permeates solid-state LiDAR fabrication, where specialized foundry capacity rests on a handful of component vendors. Distribution runs through Tier-1 automotive supplier networks rather than direct OEM relationships, extending lead times for transit authority fleet integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sensor fusion architectures are displacing legacy driver-assist systems, with LiDAR-stereo camera-4D radar integration becoming the baseline specification for mixed-traffic revenue service.
For Market Incumbents: Anchor integrated electric-autonomous platform dominance through captive battery supply agreements and field-replaceable perception module roadmaps. Consolidate procurement relationships with Nordic and German transit authorities facing synchronized EU Green Deal compliance deadlines. Defend against technology platform licensors by deepening software-defined vehicle investment in thermal management integration.
For New Entrants and Emerging Players: The premium-to-economy price gap in semi-autonomous retrofit kits opens white-space targeting of Latin American and Southeast Asian diesel fleet conversions. Campus shuttle availability contracts offer the most penetrable entry point, with performance-based liability structures reducing operator adoption friction. Pursue municipal corridor partnerships in tier-two Chinese cities outside Beijing-Shanghai-Shenzhen saturation.
For Investors and Strategic Acquirers: Distressed-cycle entries favor perception-layer component specialists with automotive-grade manufacturing certifications in South Korea and Taiwan. Long-term viability hinges on regulatory jurisdiction first mandating driver-out mixed-traffic operation, which will cascade procurement specifications across all three major markets. Monitor NHTSA exemption volume acceleration as the inflection signal for commercial scaling readiness.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Stack Integration | LiDAR-camera-radar convergence enables safety-driver elimination in EU type-approval pathways. |
| Battery Supply Agreement | CATL and LG Energy Solution partnerships secure thermal management compatibility with autonomous compute racks. |
| Geographic Manufacturing Footprint | Stuttgart and Shanghai engineering centers anchor Daimler Truck AG's Level-4 highway coaching development. |
| Software-Defined Vehicle Investment | NVIDIA DRIVE platform licensing scales perception-layer architecture across multiple OEM programs. |
| Charging Infrastructure Partnership | Municipal corridor funding in Oslo and Shenzhen reduces operator deployment risk through infrastructure certainty. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving transit authority procurement directors, autonomous platform engineering leads, Tier-1 supplier account managers, and municipal infrastructure planners. NHTSA exemption databases, EU Vehicle General Safety Regulation implementation reports, and MIIT GB standard disclosures provided regulatory trajectory validation. Bottom-up fleet deployment tracking and top-down market sizing triangulated volume estimates across the analysis window.
Data-stream reconciliation between pilot fleet deployment counts and technology spending allocations informed the analytical framework. Segmentation dimensions modeled include automation maturity level, deployment model architecture, powertrain configuration, and regional regulatory cluster. CAGRs were derived from deployment trajectory extrapolation weighted against infrastructure investment cycles. Industry-specific inputs incorporated LiDAR unit cost curves and battery-electric drivetrain penetration timelines across municipal procurement cycles.
Inputs from NHTSA, EU type-approval registries, and MIIT certification databases were available through the study window; gaps in real-time pilot fleet operational data introduce uncertainty bands around near-term deployment velocity. Forecasts reflect assumptions regarding regulatory harmonization timelines and sensor cost reduction curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Autonomous Bike Market
Autonomous Vehicles
Predictive Automobile Technology Market
Autonomous Vehicles
Middle East and Africa Automated Guided Vehicles Market
Autonomous Vehicles
Autonomous Emergency Braking System (AEBS) Market
Autonomous Vehicles
Italy Autonomous Navigation Market
Autonomous Vehicles
Europe Autonomous Navigation Market
Autonomous Vehicles
Vehicle Intelligence System Market
Autonomous Vehicles
Global Connected, Autonomous, Shared, and Electric (CASE) Market
Autonomous Vehicles
L4 Autonomous Driving Market
Autonomous Vehicles
Automotive Automated Parking System Market
Autonomous Vehicles
Autonomous Vehicle Management Services Market
Autonomous Vehicles
Semi Autonomous and Autonomous Vehicles Market
Autonomous Vehicles
Autonomous Navigation Sensing System Market
Autonomous Vehicles
Self-Driving Truck Market
Autonomous Vehicles
Self-Driving Electric Vehicle Market
Autonomous Vehicles
Autonomous Haulage Truck Market