
 Global Adaptive Cruise Control Market | 2026-2036
Global Adaptive Cruise Control Market Size, Share, and Industry Trends Forecast 2026-2036
Global Adaptive Cruise Control Market Analysis
ISO 26262 functional safety certification is redrawing competitive boundaries in the adaptive cruise control supply base. Robert Bosch GmbH leverages its in-house semiconductor capabilities to sustain radar module production at scale. Continental AG anchors European OEM relationships through integrated domain controller architectures. Denso Corporation dominates Japanese keiretsu supply chains with specialized millimeter-wave sensor portfolios.
Adaptive cruise control constitutes an advanced driver-assistance system that automatically adjusts vehicle speed to maintain safe following distances using radar, lidar, camera, or ultrasonic sensor fusion, typically operating between 0-200 km/h with deceleration capabilities up to full stop. Radar-based technology leads volume deployment due to proven all-weather reliability, while camera-based systems capture margin pools through AI-enhanced object classification. Passenger vehicles occupy the dominant installation base, though commercial vehicle fleets represent the fastest-growing demand channel as logistics operators pursue liability reduction.
NHTSA, ECE R79 regulations, and China's GB/T standards collectively mandate performance benchmarks for automatic speed adaptation and emergency braking interoperability. These frameworks shape demand by disqualifying non-compliant suppliers from OEM qualification programs and forcing sensor redundancy architectures. Stakeholders must monitor evolving type-approval harmonization between European UNECE protocols and emerging national standards in high-volume production jurisdictions.
Market Dynamics
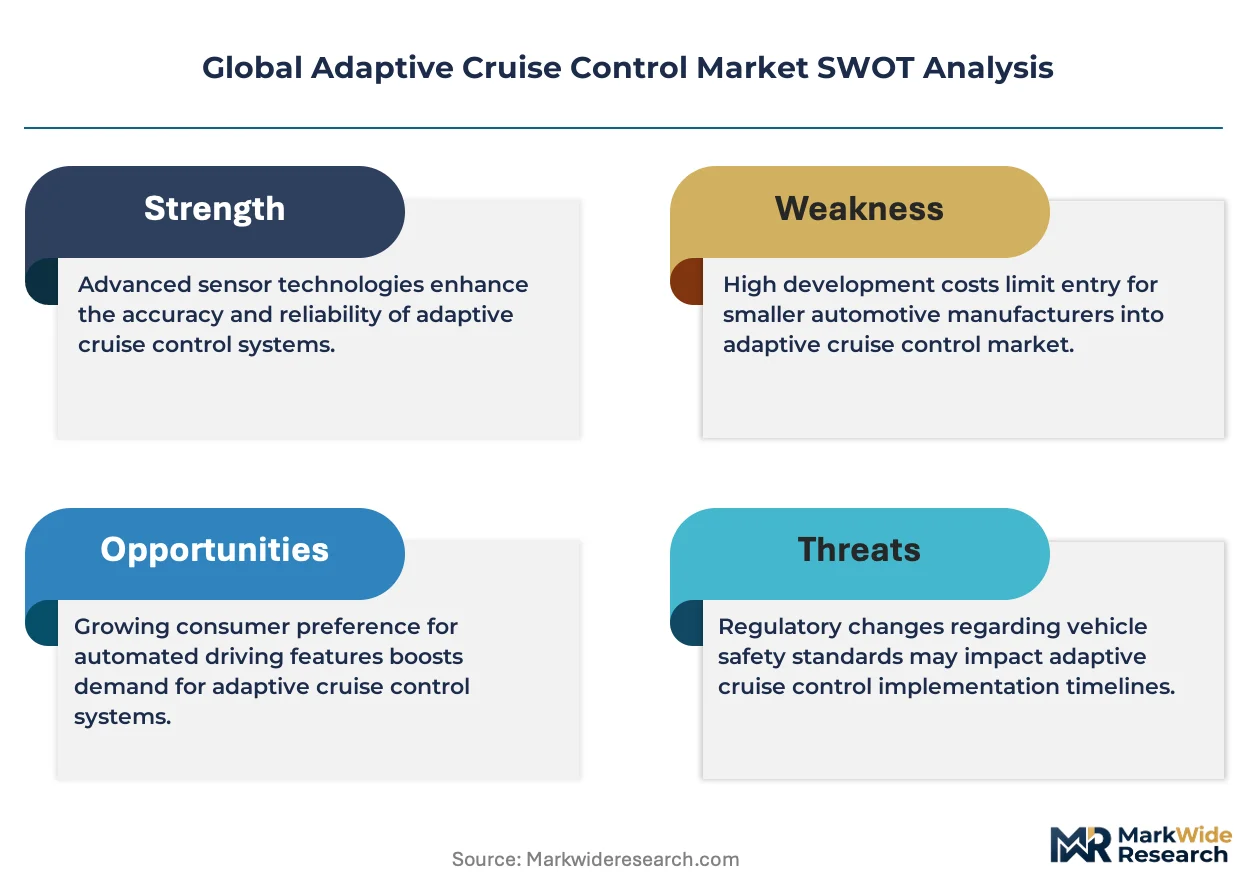
Sensor fusion architectures are compressing supplier margins as OEMs consolidate radar, camera, and lidar inputs into unified domain controllers, forcing component vendors to reposition around software stacks or exit volume segments entirely.
Growth Catalysts
- NHTSA automatic emergency braking mandates:US passenger vehicle OEMs must integrate adaptive cruise control with AEB systems by model year requirements, accelerating radar module procurement cycles.
- Commercial fleet liability reduction:Logistics operators in long-haul trucking are deploying ACC to mitigate rear-end collision exposure and insurance premium escalation.
- EU Green Deal vehicle safety regulations:European type-approval standards under UN ECE R79 are mandating intelligent speed adaptation interoperability, requiring sensor redundancy in new vehicle platforms.
Market Restraints
- Millimeter-wave radar chip supply concentration:Foundry capacity for 77GHz RF semiconductors concentrates in Taiwan and South Korea, exposing tier-one module suppliers to allocation risk.
- Camera system performance degradation:Adverse weather and low-light conditions limit pure vision-based ACC reliability, constraining deployment in Nordic and alpine markets.
- LiDAR cost structure:Solid-state and MEMS-based ranging sensors remain four to six times the bill-of-materials cost of radar alternatives, blocking mass-market penetration.
Strategic Opportunities
- China GB/T standard localization:Domestic OEMs and joint ventures are qualifying local sensor fusion suppliers under national intelligent vehicle regulations, creating captive demand for indigenous radar and camera module producers.
- Truck platooning integration:V2V communication protocols enabling cooperative adaptive cruise control in heavy-duty convoys represent untapped hardware and software attach rates.
- India BIS automotive safety roadmap:Proposed mandatory advanced driver-assistance features for passenger vehicles above defined engine displacement thresholds will unlock first-wave ACC adoption in premium segments.
Industry Challenges
- ISO 26262 ASIL-D functional safety certification:Achieving highest automotive safety integrity levels for ACC systems requires eighteen to thirty-six month validation cycles, compressing product development windows.
- Legacy vehicle electrical architecture integration:Retrofitting ACC into platforms with limited CAN-FD bandwidth or absent redundant power domains forces expensive harness redesigns.
- Sensor calibration workforce scarcity:Precision alignment of multi-modal perception systems demands specialized technicians, creating bottlenecks at OEM assembly plants and aftermarket service centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Adaptive Cruise Control Market |
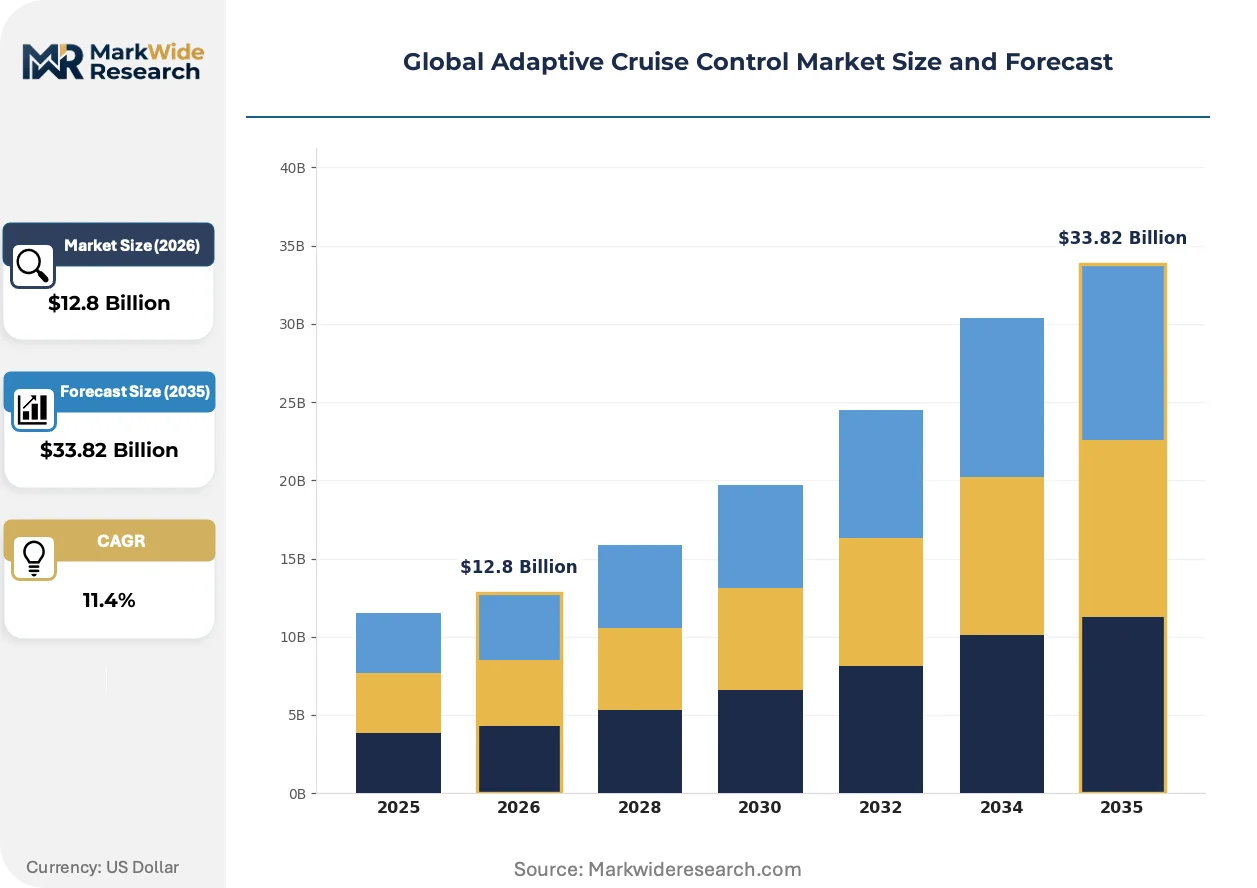
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $33.82 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Systems, Integrated Systems, Upgraded Systems, Original Equipment Technology: Radar-Based, Lidar-Based, Camera-Based, Ultrasonic Vehicle Type: Passenger Vehicles, Commercial Vehicles, SUVs, Luxury Cars End User: Fleet Operators, Private Users, Car Manufacturers, Automotive OEMs |
| Companies Covered | Continental AG, Robert Bosch GmbH, ZF Friedrichshafen AG, Denso Corporation, Magna International Inc, Valeo SA, Hyundai Motor Company, Aptiv, Autoliv Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Adaptive Cruise Control Market Emerging Trajectories
Software-defined perception stacks are decoupling hardware refresh cycles from feature deployment, enabling over-the-air updates that extend ACC capability without physical sensor replacement.
4D imaging radar is displacing conventional 3D radar modules in premium vehicle segments by delivering elevation data and Doppler velocity resolution sufficient for static object classification. German and Japanese OEMs are qualifying these sensors for highway pilot functions. The technology is displacing front-facing lidar in mid-range price bands where point-cloud density requirements remain modest.
EU AI Act risk classification frameworks are imposing documentation and conformity assessment burdens on machine-learning components within ACC systems, particularly neural networks performing cut-in prediction and trajectory planning. Tier-one suppliers must maintain algorithmic audit trails and human oversight protocols. European premium OEMs are responding by segregating AI-driven features into separately certifiable software modules.
Fleet procurement of ACC-enabled vehicles is consolidating around total cost of ownership metrics rather than upfront equipment pricing, weighing fuel efficiency gains from predictive speed management against sensor maintenance costs. Leasing companies and logistics operators are negotiating service-level agreements covering calibration and firmware updates. This shift is most visible in Germany and the United States where commercial vehicle operating economics dominate acquisition decisions.
Global Adaptive Cruise Control Market Segmentation
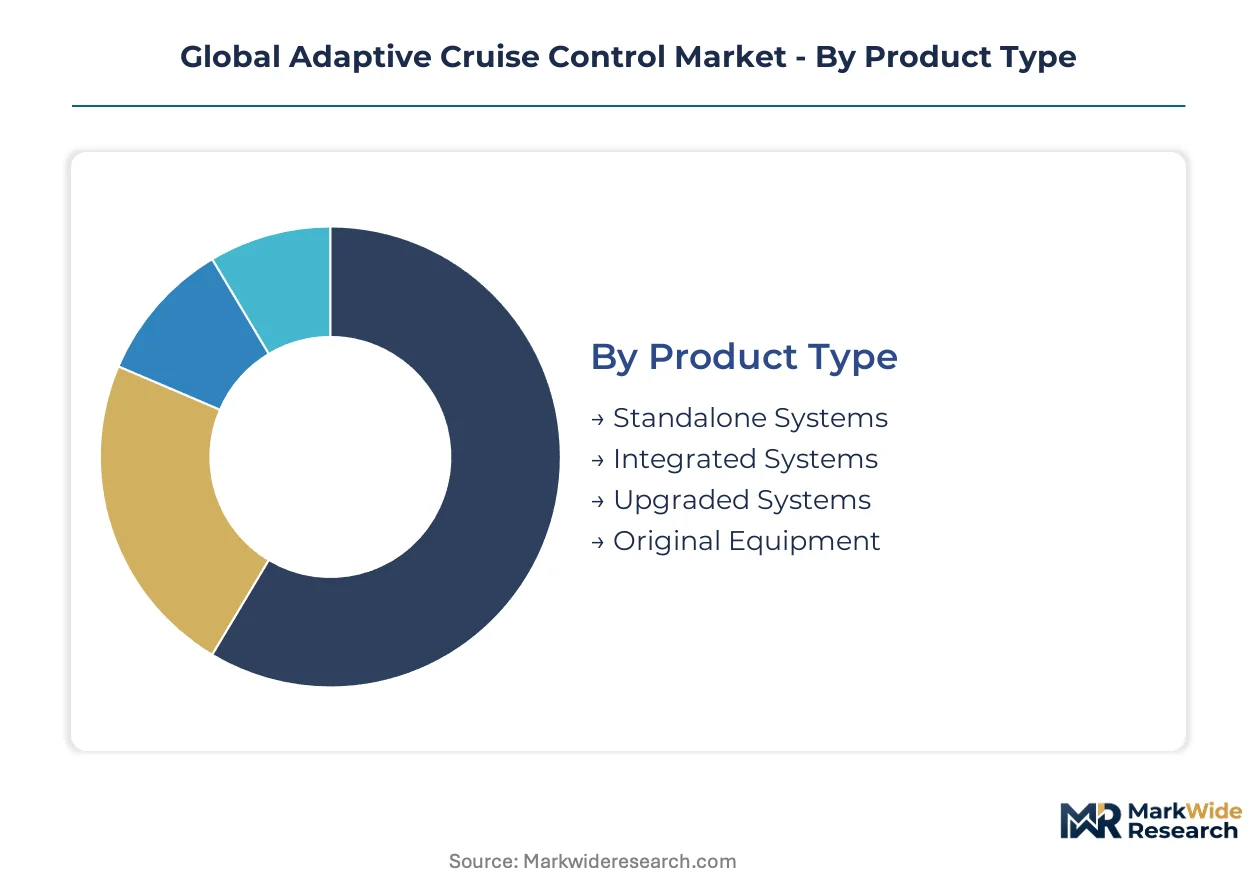
Adaptive cruise control procurement patterns diverge sharply across product configurations and technology platforms. OEM integration strategies, aftermarket retrofit demand, and fleet operator specifications each favor distinct segment combinations.
Product Type:
Fleet procurement concentrates in integrated and upgraded systems, while private replacement demand sustains standalone module sales through aftermarket channels.
- Standalone Systems:Self-contained radar or camera modules designed for retrofit installation on vehicles without factory ACC capability. Demand clusters among commercial fleet operators in Germany and the United States seeking liability reduction without full platform replacement.
- Integrated Systems:ACC functionality embedded within domain controller architectures alongside lane-keeping and emergency braking. German and Japanese OEMs specify these for new passenger vehicle platforms to consolidate sensor fusion processing.
- Upgraded Systems:Mid-cycle platform enhancements adding ACC to existing electrical architectures. Chinese joint ventures deploy these to meet GB/T intelligent vehicle standards without complete redesign.
- Original Equipment:Factory-installed ACC specified at vehicle configuration. Premium segments in Japan and Germany specify these as standard equipment.
Integrated systems dominate installed base. Upgraded systems are where expansion concentrates.
Technology:
Cost tiers separate all-weather radar deployment from camera-based margin capture in premium classifications.
- Radar-Based:77GHz millimeter-wave modules providing velocity measurement and all-weather reliability. Volume deployment concentrates in China and the United States where NHTSA and GB/T mandates prioritize proven sensor redundancy.
- Camera-Based:Machine-vision systems enabling AI-enhanced object classification and traffic sign recognition. European premium OEMs specify these for intelligent speed adaptation under EU Green Deal requirements.
- Lidar-Based:Solid-state and MEMS ranging sensors delivering dense point clouds. German highway pilot programs qualify these for conditional automation above ACC functionality.
- Ultrasonic:Short-range sensors limited to low-speed following and parking assistance. Japanese keiretsu suppliers integrate these as gap-fillers in multi-modal fusion architectures.
Radar-based technology commands volume leadership. Lidar-based configurations are climbing the fastest as solid-state costs compress.
Vehicle Type:
Application requirements dictate sensor specification intensity across mass-market and premium classifications.
- Passenger Vehicles:Mid-size sedans and hatchbacks specifying radar-camera fusion for highway driving assistance. Chinese domestic brands localize these configurations for cost-sensitive segments.
- Commercial Vehicles:Heavy-duty trucks and long-haul tractors deploying cooperative ACC for platooning. German and US logistics operators specify these for insurance premium reduction.
- SUVs:Higher ride heights requiring adjusted sensor mounting and calibration protocols. Premium German OEMs specify these for all-terrain ACC capability.
- Luxury Cars:Full-sensor-stack configurations combining radar, camera, and lidar for traffic jam pilot functions. Japanese and German flagships compete on perception redundancy.
Passenger vehicles anchor production volumes. Commercial vehicles are gaining share fastest as fleet electrification accelerates ADAS specification.
End User:
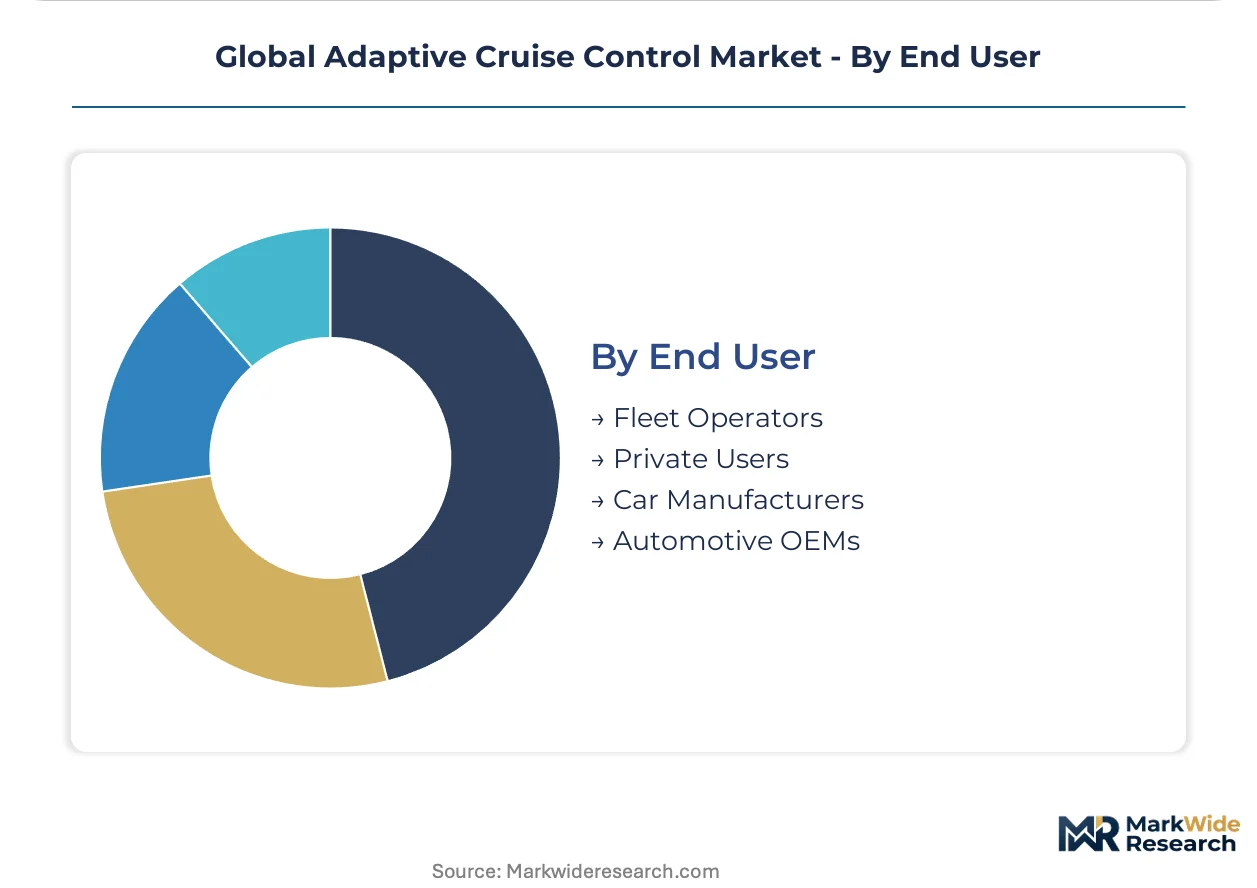
Customer type determines procurement modality, service-level expectations, and firmware update responsibility.
- Fleet Operators:Logistics and leasing companies negotiating total-cost-of-ownership contracts with calibration and update provisions. German and US commercial fleets specify these arrangements.
- Private Users:Individual purchasers selecting ACC through dealership option packages. Chinese and Japanese markets show concentration in first-time premium buyers.
- Car Manufacturers:Volume OEMs sourcing modules through tier-one supplier contracts with platform exclusivity clauses. Domestic Chinese brands qualify local sensor fusion producers.
- Automotive OEMs:Premium manufacturers with in-house perception stack development integrating ACC within unified automated driving architectures. German and Japanese OEMs maintain these capabilities.
Automotive OEMs control technology roadmaps. Fleet operators are where specification authority is shifting most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai anchors Asia-Pacific sensor module flows, while German autobahn infrastructure and US interstate corridors shape distinct ACC deployment patterns across mature automotive markets.
United States
NHTSA automatic emergency braking mandates drive radar module procurement at domestic OEMs. The Infrastructure Investment and Jobs Act funds intelligent transportation corridors along I-75 and I-95. Michigan's Detroit-Warren corridor concentrates tier-one supplier engineering centers for integrated domain controller development.
Germany
EU Green Deal vehicle safety regulations mandate intelligent speed adaptation for type approval. UN ECE R79 harmonization efforts proceed through UNECE working groups in Geneva. Bavaria's Munich-Ingolstadt corridor hosts premium OEM automated driving campuses qualifying 4D imaging radar for highway pilot functions.
China
GB/T intelligent vehicle standards accelerate sensor fusion localization at domestic brands and joint ventures. MIIT new energy vehicle mandates prioritize ADAS specification in subsidy-eligible platforms. Yangtze River Delta manufacturing clusters around Shanghai and Suzhou scale millimeter-wave radar production for cost-sensitive segments.
Japan
METI carbon neutrality roadmaps embed ACC within commercial vehicle electrification timelines. JIS automotive safety standards govern keiretsu supplier qualification protocols. Kanto region OEM headquarters in Tokyo and Yokohama coordinate tier-one Denso and Continental AG module integration for domestic flagship platforms.
South Korea
Ministry of Trade, Industry and Energy intelligent vehicle initiatives fund cooperative ACC research for truck platooning. Korea Expressway Corporation V2X infrastructure deployment proceeds along Gyeongbu Expressway. Seoul Capital Area OEMs qualify local radar suppliers under KSA safety certification frameworks.
Global Adaptive Cruise Control Market Vendor Landscape
Listed leaders compete with private specialists across functional safety certification depth and semiconductor integration capability. The supply base concentrates around tier-one module suppliers with captive radar chip design or exclusive keiretsu relationships. Three archetypes dominate: integrated semiconductor-module vendors, domain controller architects, and regional sensor fusion specialists. Competitive moves center on ISO 26262 ASIL-D validation acceleration and foundry partnerships for 77GHz RF capacity security.
Within the integrated semiconductor tier, Robert Bosch GmbH and Continental AG exemplify vendors with in-house chip capabilities and European OEM anchor positions. Denso Corporation represents the keiretsu-embedded archetype with specialized millimeter-wave portfolios and Japanese domestic supply chain integration.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| ZF Friedrichshafen AG |
| Denso Corporation |
| Magna International Inc |
| Valeo SA |
| Hyundai Motor Company |
| Aptiv |
| Autoliv Inc |
| Others |
Supply Flow & Price Mechanics
Foundry scale economies at Taiwan Semiconductor Manufacturing and Samsung Electronics anchor 77GHz RF chip production costs, compressing radar module price floors while simultaneously concentrating supply leverage among tier-one integrators with captive wafer allocation. This scale dynamic forces smaller module vendors toward software differentiation or exit, as volume procurement contracts at Robert Bosch GmbH and Continental AG lock in multi-year price bands that secondary suppliers cannot match.
Pricing Analysis
Volume-discount tiering structures separate OEM direct contracts from aftermarket standalone module sales, with three-tier pricing stratification across premium ASIL-D certified systems, standard radar-camera fusion configurations, and economy single-sensor retrofit kits. Price differentiation rests on ISO 26262 certification grade and bundled calibration service terms, with premium tiers commanding sustained margins through liability coverage provisions. Cost compression in economy tiers is intensifying because Chinese domestic brands are qualifying local sensor fusion suppliers under GB/T standards. Fleet operators in Germany and the United States show lowest price sensitivity due to total-cost-of-ownership contracting, while private aftermarket purchasers in India and Southeast Asia drive hardest bargain hunting.
Supply Chain Analysis
Taiwan Strait transit risk underwrites semiconductor supply security for 77GHz millimeter-wave radar chips, with foundry capacity concentrated in Hsinchu and Tainan science parks alongside Seoul-area Samsung Electronics fabs. Raw material dependencies span gallium arsenide substrates, RF semiconductor wafers, and specialized automotive-grade epoxy resins for sensor housing. Single-source vulnerability concentrates at TSMC's 28nm RF process nodes, where alternative qualification cycles stretch eighteen to twenty-four months. Distribution runs through tier-one module suppliers with exclusive OEM platform contracts, bypassing open-channel component markets entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined perception stacks threaten hardware-centric ACC suppliers with feature disintermediation, forcing incumbents to defend integrated domain controller positions against pure-play algorithm vendors.
For Market Incumbents: Secure captive foundry allocation for 77GHz RF capacity through multi-year wafer agreements with TSMC or Samsung Electronics, insulating against allocation shocks that could disqualify from OEM qualification programs. Accelerate ISO 26262 ASIL-D certification pipelines to compress validation cycles below competitor timelines, leveraging existing European and Japanese OEM relationships to lock in platform exclusivity clauses before software-defined architectures commoditize sensor hardware. For New Entrants and Emerging Players: Anchor in India's BIS automotive safety roadmap implementation, where proposed mandatory ADAS features for premium passenger vehicles create first-wave adoption without entrenched incumbent saturation. Target commercial vehicle fleet procurement in South Korea's truck platooning pilots, qualifying cooperative ACC modules under Korea Expressway Corporation V2X infrastructure standards. Pursue white-label sensor fusion software licensing to Chinese domestic brands seeking rapid GB/T compliance without in-house perception stack investment. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among tier-one module suppliers with embedded firmware update obligations and fleet service-level agreements, positioning these archetypes for sustained cash flow quality across electrification transitions. Prioritize acquisition targets with validated 4D imaging radar roadmaps and existing ASIL-D certification, as solid-state lidar cost compression threatens to displace premium radar configurations. Watch NHTSA rulemaking on automatic emergency braking interoperability as the inflection signal—accelerated mandate timelines would trigger immediate capacity expansion cycles among qualified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Domain controller consolidation at German and Japanese OEMs reduces sensor module count per vehicle while raising software content value. |
| Software-Defined Vehicle Investment | Over-the-air ACC capability extension decouples hardware refresh from feature deployment, extending module lifecycle revenue. |
| Geographic Manufacturing Footprint | Yangtze River Delta localization serves Chinese domestic brand demand under MIIT new energy vehicle subsidy frameworks. |
| Battery Supply Agreement | Commercial fleet electrification timelines at US and German logistics operators synchronize ACC specification with zero-emission platform procurement. |
| Charging Infrastructure Partnership | Highway corridor V2X deployment by Korea Expressway Corporation enables cooperative ACC validation for heavy-duty truck platooning. |
Methodological Framework
The analysis maps radar-based, camera-based, lidar-based, and ultrasonic ACC technology platforms, each validated through tier-one supplier procurement directors, OEM platform engineers, aftermarket distributor operations heads, and fleet operator specification managers. Primary fieldwork combined structured interviews with secondary validation against vehicle production databases, IHS Markit registration data, NHTSA rulemaking dockets, and UN ECE R79 working group proceedings. Bottom-up module shipment estimates triangulated against top-down OEM platform ADAS penetration assumptions.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with segmentation modeled across technology type, product configuration, vehicle class, and regional production cluster. CAGRs derived from fitted growth curves anchored to known mandate implementation dates and OEM platform cycle timing, incorporating sensor content per vehicle trajectories and fleet electrification adoption curves as industry-specific forecast inputs.
Material uncertainties — foundry capacity allocation shocks, regulatory harmonization delays between UNECE and national type-approval frameworks, and solid-state lidar cost compression velocity — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding mandate enforcement timelines and OEM integration cycle commitments. Revision becomes warranted when GB/T standard implementation pace or NHTSA rulemaking acceleration crosses thresholds that would compress or extend OEM qualification windows.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Autonomous Bike Market
Autonomous Vehicles
Autonomous Emergency Braking (AEB) Market
Autonomous Vehicles
Driverless Taxi Market
Autonomous Vehicles
Self-Driving Cars and Trucks Market
Autonomous Vehicles
Adaptive Cruise Control (ACC) System Market
Autonomous Vehicles
Self Driving Car Market
Autonomous Vehicles
Autonomous Bus Market
Autonomous Vehicles
Europe Autonomous Navigation Market
Autonomous Vehicles
India Automotive Advanced Driver Assistance Systems Market
Autonomous Vehicles
Global Autonomous Trucks Market
Autonomous Vehicles
France Autonomous Navigation Market
Autonomous Vehicles
Battery-Electric Self-Driving Car Market
Autonomous Vehicles
Automated Valet Parking (AVP) Market
Autonomous Vehicles
Global Robot Cars and Trucks Market
Autonomous Vehicles
Connected Vehicle Technology Market
Autonomous Vehicles
Self-Driving Shuttle Market