
 Germany Autonomous Navigation Market | 2026-2036
Germany Autonomous Navigation Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Autonomous Navigation Market Insights
A shortage of systems engineers with embedded AI and functional safety expertise is unwinding development timelines across the supplier base. Robert Bosch GmbH leverages its sensor manufacturing depth to anchor hardware-software integration for Level 3 highway systems. Continental AG sustains R&D intensity through its dedicated autonomous mobility division in Hanover. NVIDIA Corporation competes by extending its DRIVE platform licensing to German OEM development programs.
Germany autonomous navigation encompasses real-time positioning, path planning, and obstacle avoidance systems that fuse LiDAR point clouds, camera feeds, and GNSS signals with sub-10-centimeter accuracy for ground and aerial vehicles. The primary commercial purpose is to enable self-directed movement without continuous human operator intervention in structured and semi-structured environments. Sensor systems dominate current revenue as OEMs prioritize redundant perception hardware for homologation, while software solutions represent the fastest-expanding margin pool as over-the-air update architectures mature. Machine learning competes with rule-based sensor fusion for core algorithmic share, though GPS systems remain the baseline positioning layer across all application tiers.
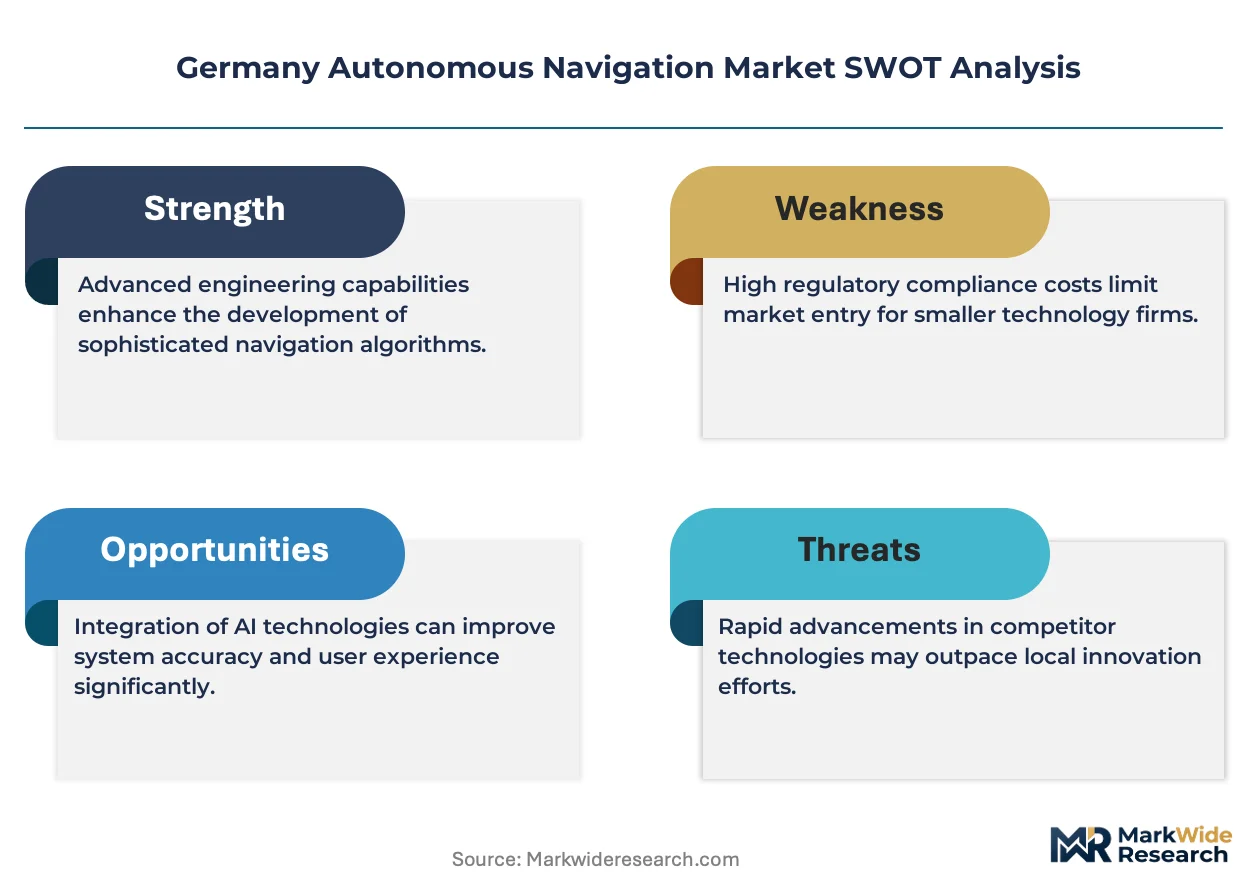
Germany's Kraftfahrt-Bundesamt enforces type approval under UN ECE regulations for automated driving functions, while the EU AI Act classifies autonomous navigation in transport as high-risk and mandates conformity assessment before market placement. The country's national data protection regulator scrutinizes real-time mapping data flows under GDPR, constraining cloud-based fleet learning architectures. Stakeholders must monitor how the StVO amendment process resolves liability allocation between vehicle operators and algorithmic system providers as conditional automation expands beyond highway pilot programs.
Market Dynamics
The EU AI Act's high-risk classification for autonomous transport systems is compressing development timelines as German OEMs race to complete conformity assessments before mandatory enforcement phases begin.
Growth Catalysts
- StVO Traffic Code Amendments:Germany's revised road traffic regulations clarify liability frameworks for conditional automation, reducing legal uncertainty that previously stalled fleet procurement decisions.
- LiDAR Cost Curves:Solid-state sensor manufacturing advances are collapsing perception hardware expenses, enabling tier-one suppliers to spec redundant sensing arrays for mid-range vehicle platforms.
- Munich-Stuttgart Corridor Concentration:Proximity of OEM engineering centers to tier-one development facilities in Bavaria and Baden-Württemberg accelerates hardware-software iteration cycles.
Market Restraints
- Rare Earth Magnet Dependency:Electric drive motors for autonomous platforms rely on neodymium supply chains concentrated in Chinese processing facilities, exposing German manufacturers to export restriction risks.
- GDPR Mapping Data Constraints:Real-time environmental data collection for fleet learning architectures faces scrutiny under Germany's federal data protection framework, limiting cloud-based algorithmic improvement.
- Functional Safety Engineering Scarcity:ISO 26262-certified systems engineers command premium compensation that inflates R&D cost structures across the supplier base.
Strategic Opportunities
- Commercial Fleet Electrification Mandates:Germany's national commercial vehicle CO2 reduction targets create captive demand for autonomous logistics platforms in long-haul freight corridors.
- Edge Computing Convergence:On-vehicle inference hardware paired with 5G network slicing enables split-architecture perception systems that reduce sensor payload costs.
- Rhineland-Palatinate Testing Corridors:State-level autonomous vehicle proving grounds around Kaiserslautern offer underutilized infrastructure for validation beyond saturated Bavarian facilities.
Industry Challenges
- Embedded AI Talent Gap:Shortages of engineers combining machine learning expertise with automotive functional safety certification are extending development schedules by 8-14 months at tier-one suppliers.
- UN ECE Type Approval Complexity:Homologation timelines for automated driving functions under KBA enforcement stretch 18-24 months, delaying revenue recognition for new platform launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Autonomous Navigation Market |
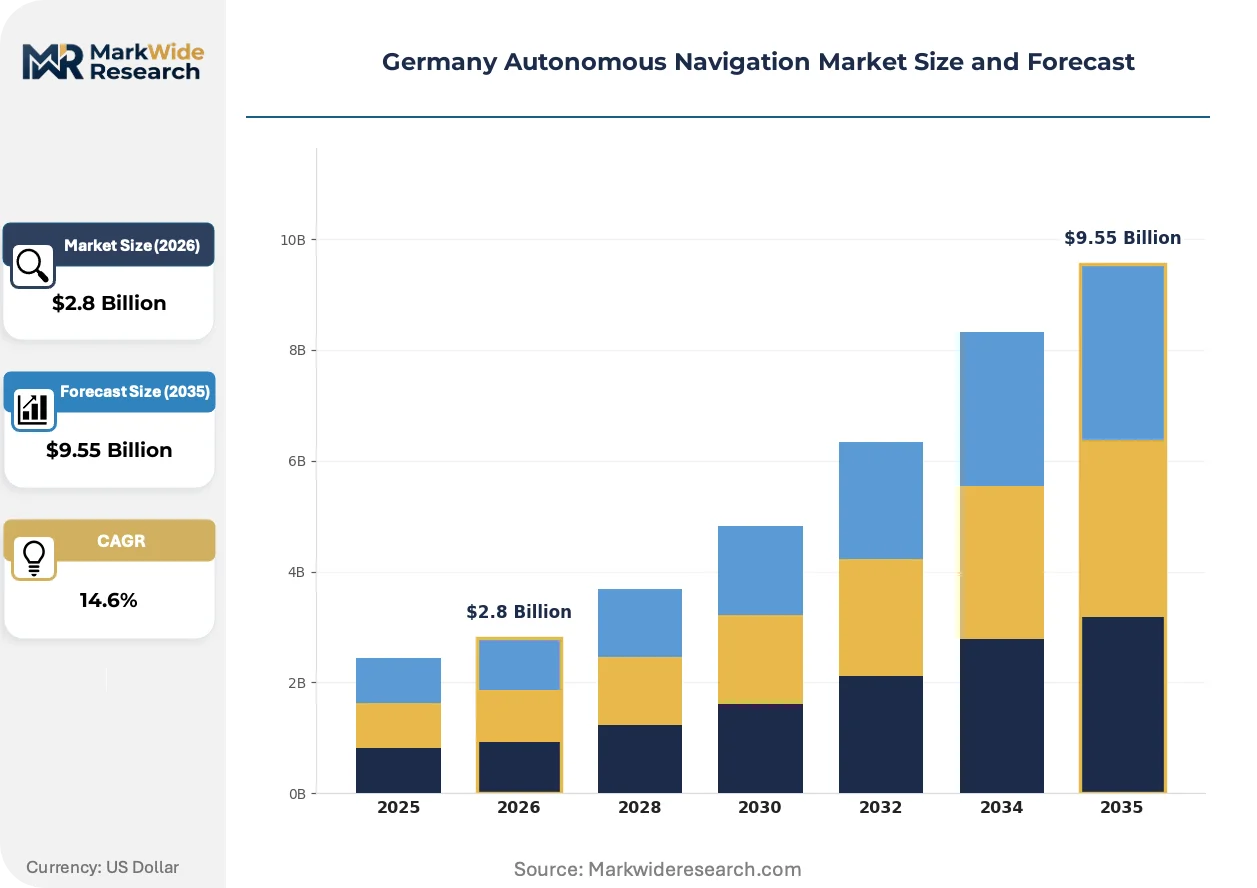
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sensor Systems, Software Solutions, Cloud-Based Services, Navigation Devices Technology: Machine Learning, Computer Vision, Sensor Fusion, GPS Systems Application: Urban Mobility, Maritime Navigation, Delivery Drones, Industrial Automation End User: Logistics Providers, Automotive Manufacturers, Public Transport Operators, Research Institutions |
| Companies Covered | Robert Bosch GmbH, Continental AG, BMW Group, Mercedes-Benz Group AG, Volkswagen Group, Audi AG, ZF Friedrichshafen, Mobileye Global Inc., NVIDIA Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Autonomous Navigation Market Trends and Innovations
Algorithmic approaches to sensor fusion are diverging sharply as German OEMs place diverging bets on neural network architectures versus deterministic rule-based systems for safety-critical decision layers.
LiDAR-based perception stacks are fragmenting across the German supplier ecosystem. Robert Bosch GmbH and Continental AG pursue divergent solid-state beam-steering technologies for highway pilot systems. Bavarian OEM development programs favor frequency-modulated continuous-wave architectures, while Stuttgart-area engineering centers prioritize optical phased array approaches. This technical bifurcation is fragmenting procurement patterns as tier-twos face dual qualification requirements.
Germany's Kraftfahrt-Bundesamt is tightening type approval scrutiny under UN ECE R79 and R157 regulations for automated lane-keeping and highway pilot functions. The regulator now demands extended real-world validation datasets before granting series production permits. Munich-based premium OEMs are responding by expanding proving ground operations to accumulate mandated mileage thresholds.
Fleet operators in North Rhine-Westphalia are consolidating vendor relationships around integrated navigation stack providers rather than assembling point solutions. Purchasing departments now require single-source accountability for perception, planning, and control subsystems. This concentration is visible in Düsseldorf-based logistics contracts that specify full-stack performance guarantees rather than component-level specifications.
Germany Autonomous Navigation Market Segmentation
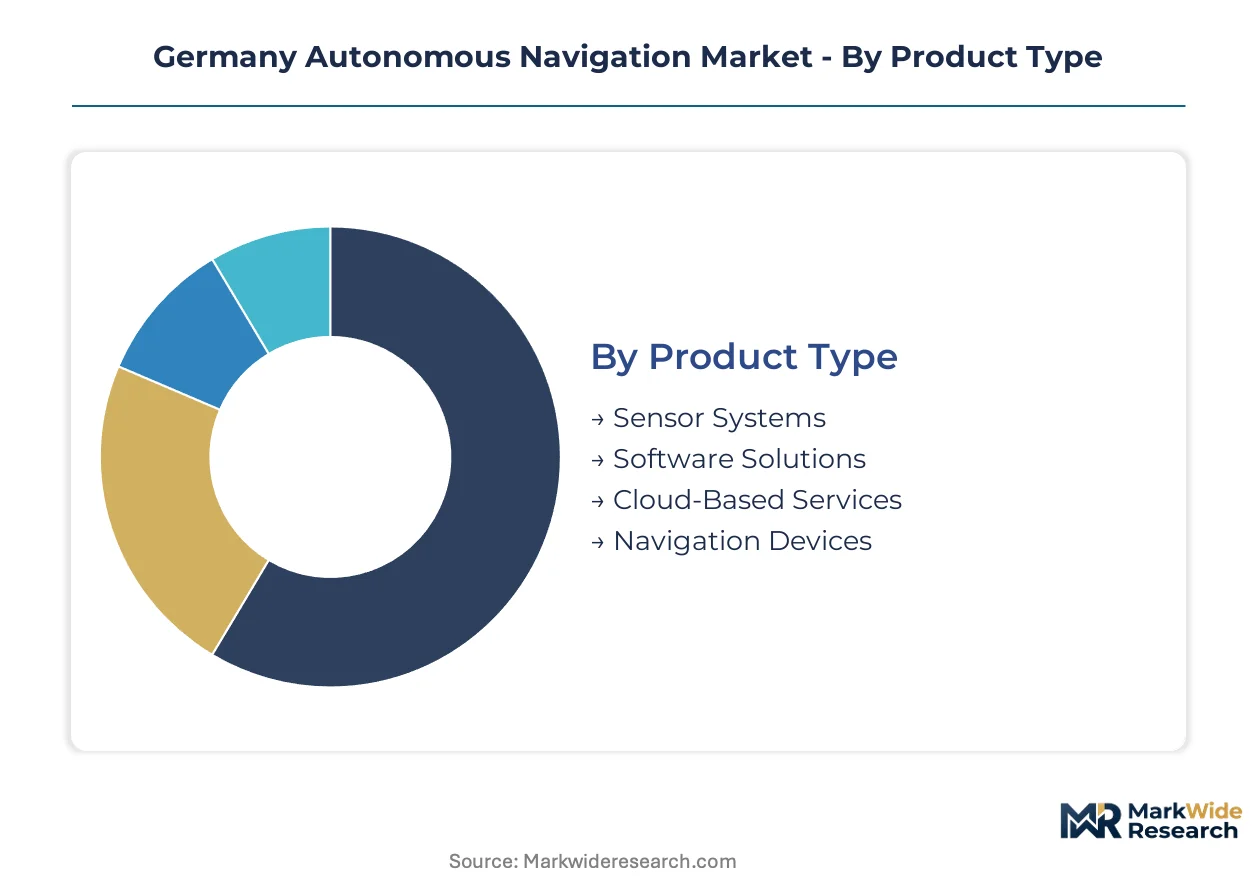
German OEM procurement patterns reveal divergent technology bets across product tiers, while regulatory pressure from KBA homologation requirements forces segment-specific validation strategies. Understanding where substitution threats concentrate helps suppliers defend margin pools against adjacent category encroachment.
Product Type:
Sensor systems face acute substitution pressure from software-centric perception architectures as edge computing maturation enables camera-first navigation stacks.
- Sensor Systems:LiDAR, radar, and camera arrays configured for redundant environmental perception. Bavarian OEM development centers around Munich prioritize solid-state LiDAR specs for highway pilot programs, though solid-state cost curves remain volatile.
- Software Solutions:Embedded algorithm stacks handling sensor fusion, path planning, and decision logic. Stuttgart-area engineering teams concentrate procurement here as over-the-air update architectures mature, enabling post-homologation capability expansion.
- Cloud-Based Services:Fleet learning infrastructure and HD map updates subject to GDPR constraints on real-time data flows.
- Navigation Devices:Standalone GNSS receivers and inertial measurement units for retrofit applications in commercial fleets.
Sensor systems retain volume leadership; software solutions hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium neural network deployments from baseline positioning layers, with mid-market platforms mixing deterministic and probabilistic approaches.
- Machine Learning:Deep neural networks trained on fleet-collected driving datasets for end-to-end navigation. Tier-one suppliers in Hanover face ISO 26262 certification bottlenecks when deploying ML in safety-critical paths.
- Computer Vision:Convolutional and transformer architectures processing camera feeds for lane detection and object classification. Demand concentrates in urban mobility applications across Berlin and Hamburg pilot zones.
- Sensor Fusion:Deterministic algorithms combining LiDAR point clouds, radar returns, and camera streams. Industrial automation end-users in Baden-Württemberg favor this approach for predictable failure modes.
- GPS Systems:GNSS receivers with RTK correction providing sub-meter baseline positioning across all application tiers.
Sensor fusion dominates current procurement volumes; machine learning is expanding most quickly as functional safety tooling improves.
Application:
Customer type fragmentation splits procurement between passenger vehicle OEMs seeking homologation speed and fleet operators demanding total cost of ownership guarantees.
- Urban Mobility:Autonomous shuttles and robotaxi services operating in geofenced city centers. Public transport operators in North Rhine-Westphalia issue bundled procurement tenders here.
- Maritime Navigation:Autonomous vessel systems for inland waterway freight on the Rhine corridor. Port authorities in Hamburg and Duisburg validate collision avoidance algorithms under specific waterway conditions.
- Delivery Drones:Aerial last-mile platforms subject to Luftfahrt-Bundesamt operational altitude restrictions.
- Industrial Automation:Automated guided vehicles and mobile robots in manufacturing facilities. Logistics providers specify these for warehouse-to-factory floor movement.
Industrial automation retains volume leadership; urban mobility holds the steepest expansion curve.
End User:
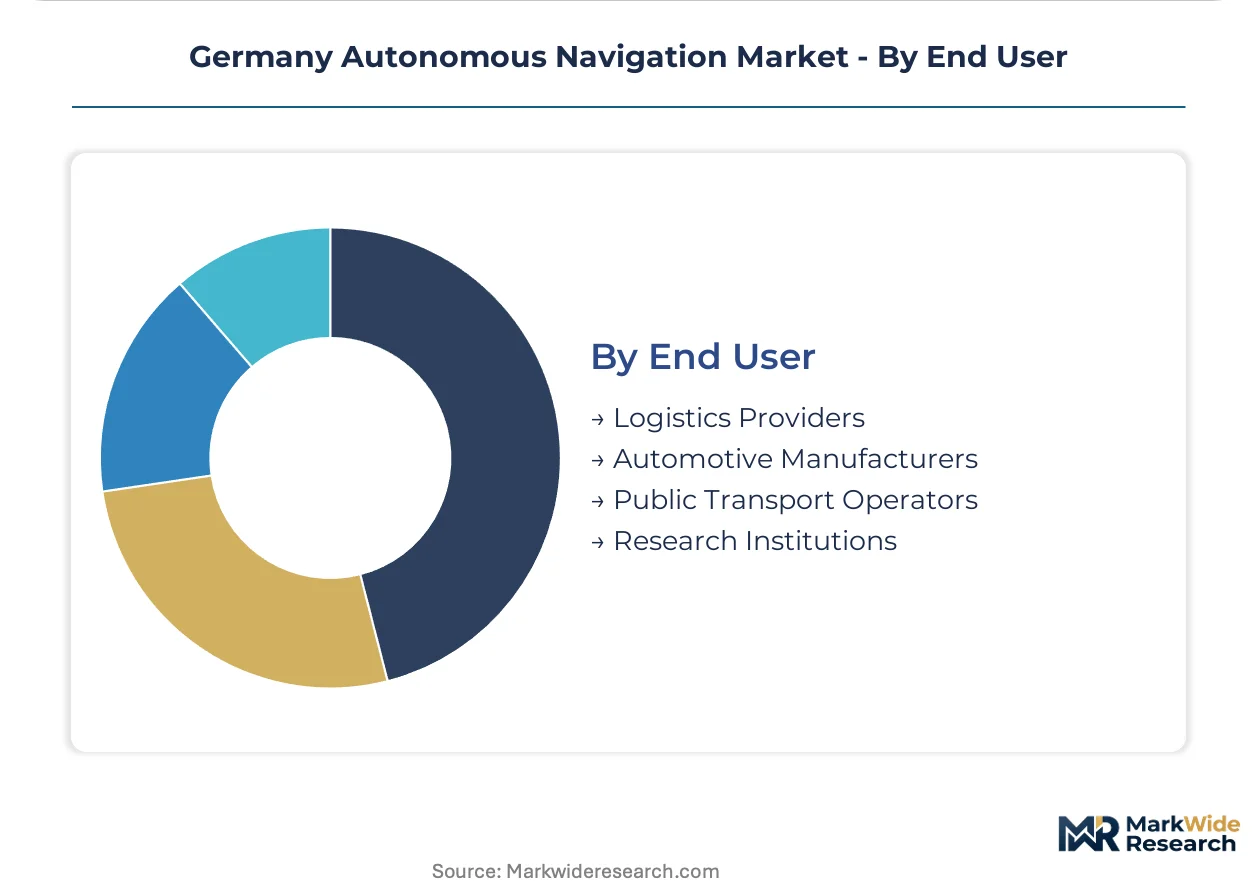
Supply concentration among tier-one integrators shapes how different buyer types access autonomous navigation capability, with automotive manufacturers capturing earliest access to production-grade stacks.
- Logistics Providers:Düsseldorf-based freight operators consolidating vendor relationships around full-stack performance guarantees rather than component sourcing.
- Automotive Manufacturers:Premium OEMs in Munich and Stuttgart driving sensor system procurement for Level 3 highway homologation under UN ECE R157.
- Public Transport Operators:Municipal authorities in Berlin, Hamburg, and Cologne piloting autonomous shuttle services with single-source accountability requirements.
- Research Institutions:Technical University of Munich and Karlsruhe Institute of Technology accessing pre-commercial stacks for algorithmic validation.
Automotive manufacturers retain volume leadership; logistics providers hold the steepest expansion curve as fleet electrification mandates deepen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
KBA enforcement of UN ECE regulations shapes development priorities across Germany's federal states, with procurement patterns clustering around established automotive engineering centers and emerging testing infrastructure.
Bavaria
Premium OEM development programs in Munich anchor sensor system procurement for Level 3 highway homologation. The state's Ministry of Economic Affairs funds autonomous vehicle testing corridors between Munich and Ingolstadt. Technical University of Munich operates validation partnerships with tier-one suppliers in the Munich-Stuttgart corridor.
Baden-Württemberg
Stuttgart-area engineering centers prioritize software solutions procurement as over-the-air architectures mature for post-homologation expansion. The state's automotive cluster supports solid-state LiDAR qualification programs for optical phased array approaches. Karlsruhe Institute of Technology maintains pre-commercial stack partnerships with regional suppliers.
North Rhine-Westphalia
Düsseldorf-based logistics providers consolidate vendor relationships around full-stack performance guarantees for commercial fleet deployment. The state's commercial vehicle CO2 reduction targets create captive demand for autonomous long-haul platforms. Port authorities in Duisburg validate inland waterway navigation systems under specific Rhine corridor conditions.
Lower Saxony
Continental AG's dedicated autonomous mobility division in Hanover sustains R&D intensity through state-backed innovation programs. The region's supplier ecosystem faces ISO 26262 certification bottlenecks when deploying machine learning in safety-critical paths. Wolfsburg-area OEM engineering centers concentrate on sensor fusion procurement for predictable failure modes.
Rhineland-Palatinate
State-level proving grounds around Kaiserslautern offer underutilized validation infrastructure beyond saturated Bavarian facilities. The Ministry of Transport supports edge computing convergence trials pairing on-vehicle inference with 5G network slicing. Regional technical universities access federal funding for split-architecture perception research.
Germany Autonomous Navigation Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with market structure reflecting the dominance of established automotive suppliers alongside semiconductor platform licensors. Tier-one integrators capture earliest access to production-grade stacks through captive OEM relationships, while hardware-software bundling requirements compress margins for point-solution vendors. Two strategic archetypes define positioning: sensor manufacturing depth anchors versus AI platform licensing models. Competitive moves concentrate on hardware-software integration partnerships and regulatory pre-qualification racing under KBA enforcement timelines.
Within the integrated supplier tier, Robert Bosch GmbH and Continental AG exemplify archetypes combining manufacturing scale with embedded systems expertise, while NVIDIA Corporation occupies a position representing semiconductor platform licensing approaches to German OEM development programs.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| BMW Group |
| Mercedes-Benz Group AG |
| Volkswagen Group |
| Audi AG |
| ZF Friedrichshafen |
| Mobileye Global Inc. |
| NVIDIA Corporation |
| Others |
Pricing and Supply Chain Analysis
Solid-state LiDAR displacing mechanical scanning arrays is redrawing procurement geography toward Chinese wafer-fabrication centers while compressing per-unit sensor economics for German tier-one suppliers. This substitution dynamic simultaneously erodes legacy pricing premiums anchored in European precision-manufacturing heritage and forces OEMs to renegotiate long-term supply agreements.
Pricing Analysis
Long-term offtake contracts dominate procurement between Bavarian OEMs and LiDAR suppliers, though spot-market purchasing for evaluation units persists during platform development phases. Price differentiation rests on ISO 26262 ASIL certification tier and volume-scale commitments, with ASIL-D qualified sensors commanding substantial premiums over ASIL-B alternatives. Cost compression in mid-range sensor tiers is intensifying because solid-state manufacturing yields are improving faster than projected. Fleet operators in North Rhine-Westphalia exhibit highest price sensitivity, while Munich-based premium OEMs prioritize homologation speed over unit economics.
Supply Chain Analysis
Rare earth magnet processing in Chinese facilities represents a critical chokepoint for electric drive motors powering autonomous navigation platforms. German manufacturers draw from China, Vietnam, and Malaysia for neodymium-dysprosium alloys, with silicon photonics and indium phosphide wafers feeding LiDAR emitter production. Single-source vulnerability concentrates in Chinese rare earth separation capacity, exposing the supply chain to export restriction risks. Distribution runs through tier-one integrator hubs in Hanover and Munich before final assembly at OEM vehicle plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory pre-qualification under KBA enforcement creates formidable switching costs for established suppliers. The entrenchment of UN ECE type approval expertise constitutes a structural barrier that rewards early-mover investment in homologation infrastructure.
For Market Incumbents: Fortify position by deepening captive LiDAR manufacturing through backward integration into solid-state emitter production, while accelerating ISO 26262 functional safety certification pipelines to outpace emerging AI-native entrants. The threat of software-centric perception stacks from semiconductor platform licensors demands preemptive hardware-software bundling investments that lock OEM relationships. For New Entrants and Emerging Players: Lead with edge-computing inference hardware targeting Rhineland-Palatinate proving ground partnerships, where underutilized validation infrastructure offers lower competitive density than saturated Bavarian corridors. The commercial fleet electrification mandate creates the most penetrable entry vector, with logistics providers in Düsseldorf seeking single-source accountability rather than incumbent point solutions. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated sensor manufacturers possessing embedded AI talent pipelines and established KBA regulatory relationships, as these assets compound defensibility across the analysis window. The signal to watch is StVO amendment finalization, which will clarify liability allocation and trigger fleet procurement acceleration or delay.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | BMW Group's consolidated sensor architecture reduces tier-two qualification burden across Munich-Stuttgart corridor. |
| Software-Defined Vehicle Investment | Mercedes-Benz Group AG's over-the-air update infrastructure enables post-homologation navigation capability expansion. |
| Battery Supply Agreement | North Rhine-Westphalia fleet operators secure captive cell capacity for autonomous electric commercial vehicle deployment. |
| Geographic Manufacturing Footprint | Continental AG's Hanover facility anchors R&D intensity through proximity to Wolfsburg OEM engineering centers. |
| Charging Infrastructure Partnership | Autonomous logistics corridors along Rhine freight routes require coordinated high-power charging network densification. |
Research Methodology
The analysis maps sensor systems, software solutions, cloud-based services, and navigation devices, each validated through procurement directors at tier-one suppliers, OEM platform engineers, KBA regulatory affairs specialists, and fleet operations managers at Düsseldorf logistics providers. Primary interview insights were cross-referenced against UN ECE regulatory filings, KBA type approval databases, German federal transport ministry policy documents, and automotive supplier SEC disclosures. Bottom-up segment sizing was reconciled with top-down market triangulation to ensure internal consistency.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled technology substitution patterns, application-tier adoption curves, and end-user procurement concentration, with CAGRs derived from segment-level growth trajectory synthesis. Industry-specific forecast inputs incorporated LiDAR cost curve trajectories and EU AI Act enforcement phase timing assumptions.
The analysis sits within stated boundaries; outcomes outside sustained KBA regulatory capacity or stable rare earth supply conditions would require recalibration. Practitioners should keep alternative scenarios live as StVO liability amendment finalization and GDPR mapping data enforcement interpretations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Automated Truck Technology Market
Autonomous Vehicles
Automotive Autonomous Shuttle Market
Autonomous Vehicles
North America ADAS Market
Autonomous Vehicles
China Autonomous Navigation Market
Autonomous Vehicles
India Automotive Advanced Driver Assistance Systems Market
Autonomous Vehicles
Vehicle Intelligence System Market
Autonomous Vehicles
Autonomous Electric Bus Market
Autonomous Vehicles
Greece Autonomous Navigation Market
Autonomous Vehicles
Global Connected, Autonomous, Shared, and Electric (CASE) Market
Autonomous Vehicles
Singapore Autonomous Navigation Market
Autonomous Vehicles
Autonomous Emergency Braking (AEB) Market
Autonomous Vehicles
Automotive AI Market
Autonomous Vehicles
Global Robot Cars and Trucks Market
Autonomous Vehicles
Connected Vehicle Technology Market
Autonomous Vehicles
Autonomous Bus Market
Autonomous Vehicles
Autonomous Truck Technology Market