
 Middle East and Africa ADAS Market | 2026-2036
Middle East and Africa ADAS Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa ADAS Market Foresight
Silicon carbide is shifting power electronics economics in ADAS sensor arrays across the Middle East and Africa, trimming thermal management costs while extending component lifespans in desert climates. Continental AG leverages its regional manufacturing footprint to supply integrated radar-camera modules to Gulf OEM assembly lines. Robert Bosch GmbH anchors its position through localized calibration centers in Dubai and Johannesburg that reduce post-installation failure rates. Mobileye competes on mapping density, having extended its Road Experience Management coverage to major Saudi and Emirati highway networks.
Advanced Driver Assistance Systems (ADAS) comprise sensor fusion architectures that process real-time inputs from radar emitters operating at 76-81 GHz, image sensors with dynamic range exceeding 130 dB, and ultrasonic transducers for near-field object detection to execute semi-autonomous vehicle control functions. Camera-based systems lead installation volumes across the Middle East and Africa due to lower unit costs and compatibility with existing vehicle electrical architectures, while radar systems dominate premium commercial vehicle configurations where all-weather reliability is non-negotiable. Automatic Emergency Braking occupies the fastest-expanding product category as Saudi Arabia's SASO and the UAE's ESMA incorporate AEB compliance into new vehicle type-approval protocols.
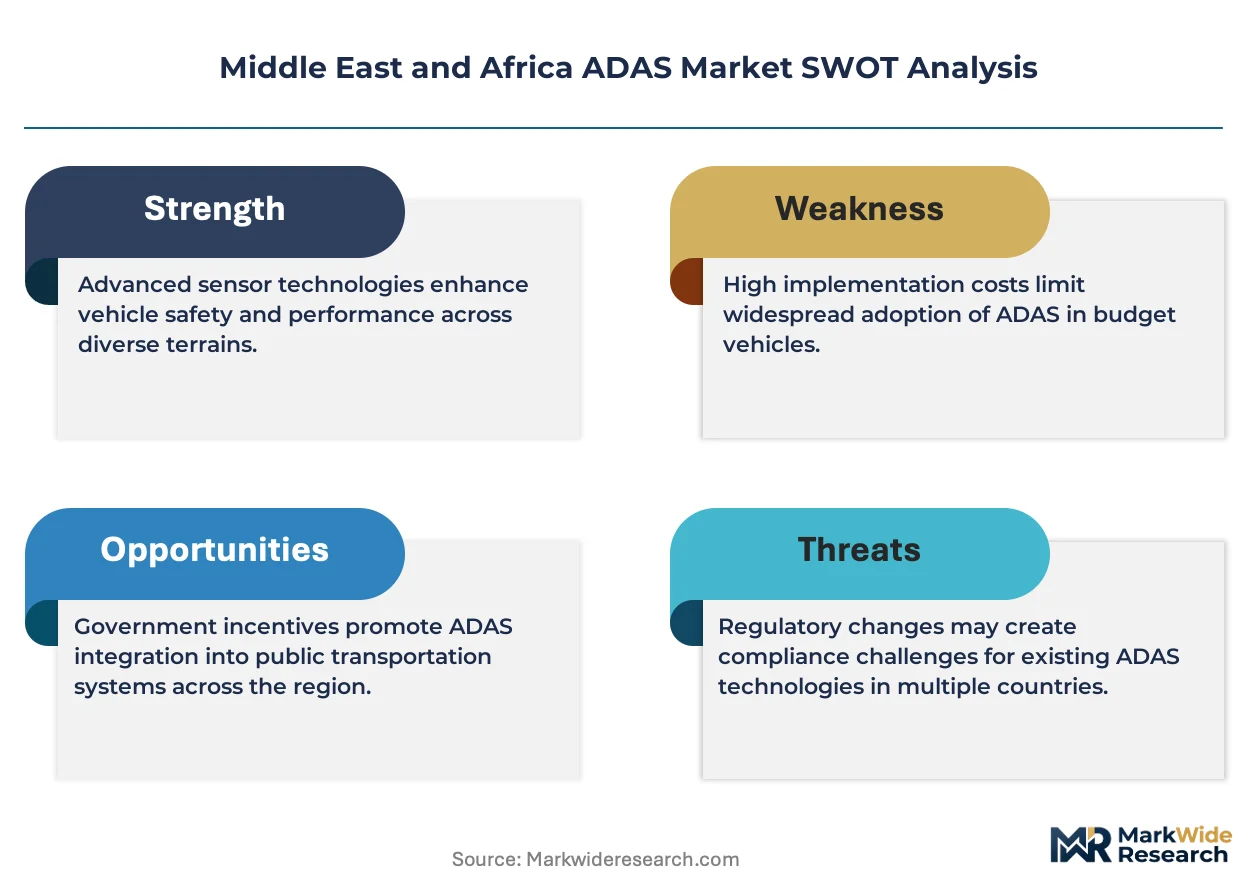
SASO, ESMA, and South Africa's NRCS collectively shape product standards through harmonized Gulf technical regulations and local homologation requirements that mandate specific sensor performance thresholds for vehicles sold in their jurisdictions. The UAE's ESMA has accelerated demand by requiring lane departure warning systems on heavy commercial vehicles imported after specified regulatory phase-ins, while SASO's evolving safety framework is forcing Tier-1 suppliers to pre-certify components before Saudi market entry. Stakeholders must monitor divergence between Gulf harmonization initiatives and South Africa's NRCS-specific testing protocols, as misalignment risks fragmenting procurement strategies across the region's two largest automotive demand clusters.
Market Dynamics
Silicon carbide power electronics is compressing thermal management costs in desert-deployed ADAS sensor arrays, while Gulf regulatory harmonization under unified technical regulations is accelerating fleet-wide collision avoidance mandates.
Growth Catalysts
- SASO AEB Mandates:Saudi Arabia's type-approval protocols now embed automatic emergency braking compliance, forcing OEMs to pre-integrate radar-camera fusion before market entry.
- Silicon Carbide Semiconductors:Wide-bandgap materials slash cooling overhead in 76-81 GHz radar arrays, extending component lifespans where ambient temperatures exceed 50°C.
- Heavy Commercial Fleets:UAE-based logistics operators face ESMA lane departure warning requirements on imported trucks, creating concentrated demand for integrated driver monitoring systems.
Market Restraints
- Sensor Calibration Infrastructure:Post-installation failure rates remain elevated where localized calibration centers are absent, particularly in secondary Saudi cities outside Riyadh and Jeddah.
- Platinum Group Metal Volatility:Radar module substrates depend on palladium and rhodium supply chains concentrated in South Africa's Bushveld Complex, exposing Tier-1 suppliers to input cost spikes.
- Homologation Fragmentation:Divergence between Gulf harmonization initiatives and South Africa's NRCS-specific testing protocols forces dual certification tracks, inflating compliance overhead for multi-market suppliers.
Strategic Opportunities
- Ethiopia's Commercial Corridor:Underpenetrated heavy truck fleets along the Addis Ababa-Djibouti route lack collision avoidance coverage, creating first-mover positioning for radar-integrated platforms.
- V2X Highway Deployment:Convergence between roadside units and onboard sensor fusion is converging with cellular-V2X spectrum allocation in Saudi Arabia's NEOM corridor, enabling cooperative perception architectures.
- Aftermarket Channel Expansion:Independent service centers in Nigeria's Lagos-Ibadan expressway cluster now retrofit camera-based lane keeping systems on used Japanese imports, bypassing OEM-controlled distribution.
Industry Challenges
- Sensor Fusion Engineering Talent:Shortages of embedded systems engineers capable of integrating 130+ dB dynamic range image sensors with millimeter-wave radar outputs constrain Tier-1 expansion timelines in Johannesburg and Dubai.
- Legacy Electrical Architectures:Pre-2020 vehicle platforms across Egypt's taxi fleet lack CAN-FD bandwidth for real-time ADAS data throughput, forcing expensive gateway module retrofits.
- Desert Dust Ingress Certification:IP6K9K sealing validation for camera housings requires extended testing cycles at NRCS facilities, delaying product launches by 4-6 months versus European homologation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa ADAS Market |
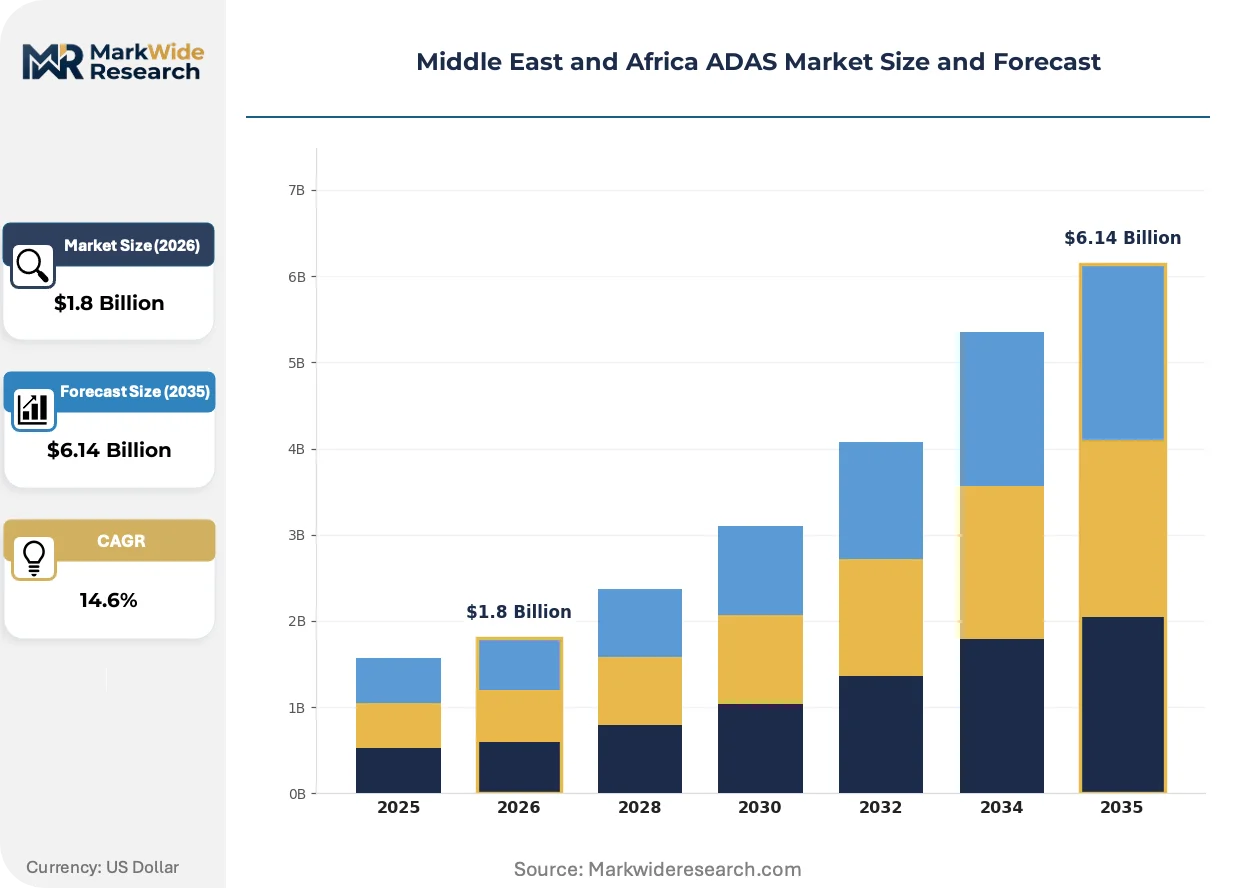
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adaptive Cruise Control, Lane Departure Warning, Automatic Emergency Braking, Parking Assistance End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Commercial Vehicles Technology: Radar Systems, Lidar Technology, Camera-Based Systems, Ultrasonic Sensors Installation Type: Integrated Systems, Retrofitted Solutions, Modular Kits, Vehicle-Specific Installations |
| Companies Covered | Continental AG, Robert Bosch GmbH, Mobileye, Autoliv Inc., ZF Friedrichshafen AG, Denso Corporation, Aptiv PLC, Valeo SA, Hyundai Mobis Co., Ltd., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa ADAS Market Shifts & Advancements
Radar-camera sensor fusion architectures are displacing single-modality systems across Gulf commercial fleets, while regulatory phase-ins are compressing supplier certification windows. Procurement patterns simultaneously pivot toward pre-certified component sourcing.
Silicon carbide MOSFETs in 77 GHz radar front-ends is converging with gallium nitride power amplifiers to slash thermal dissipation by 40% in ambient temperatures exceeding 50°C. Saudi fleet operators deploying these modules across long-haul corridors report 30% reduction in sensor array maintenance intervals. The technology is converging with integrated antenna-in-package designs that compress module footprints for behind-grille mounting.
ESMA's lane departure warning mandates for heavy commercial vehicles is forcing OEMs to redesign electrical architectures before UAE type-approval. The regulation compresses supplier qualification timelines from 18 months to 9 months for integrated driver monitoring systems. Dubai-based assembly plants now require pre-certified radar modules from Tier-1s, shifting compliance burden upstream.
Long-term service contracts bundling sensor calibration with hardware procurement are displacing transactional component sales in South Africa's mining transport sector. Anglo American Platinum's haul truck fleet now sources radar maintenance through 5-year performance agreements with Johannesburg-based integrators. The model concentrates procurement authority with fleet engineering departments rather than decentralized maintenance units.
Middle East and Africa ADAS Market Segmentation
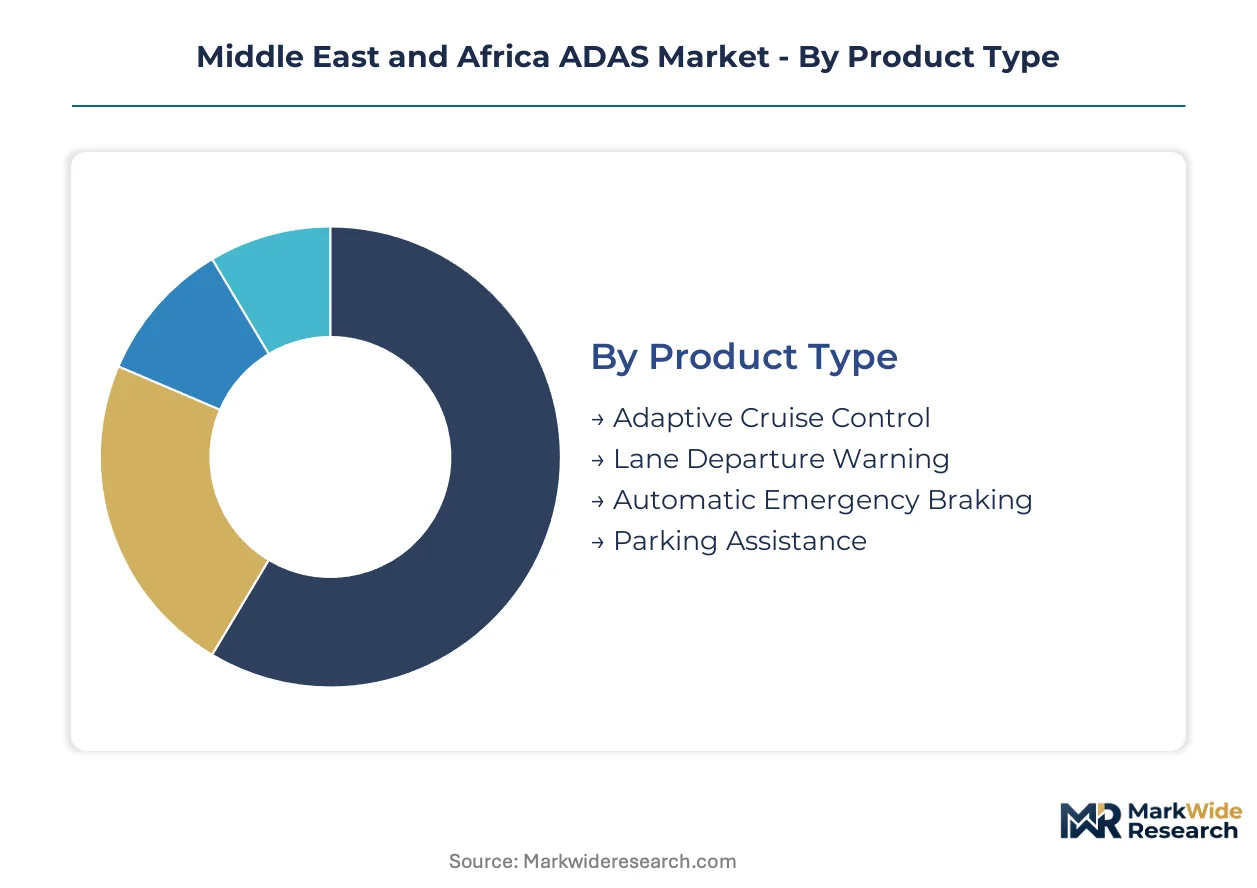
ADAS procurement across the Middle East and Africa fragments along certification pathways, with Gulf harmonization under SASO and ESMA protocols diverging from South Africa's NRCS homologation tracks. Suppliers must map segment-specific approval requirements to avoid dual-certification overhead in multi-market deployments.
Product Type:
SASO type-approval protocols mandate distinct sensor performance thresholds for each product category, with AEB compliance now compulsory for Saudi market entry while LDW requirements phase in separately under UAE ESMA regulations.
- Automatic Emergency Braking:Radar-camera fusion architectures process 76-81 GHz millimeter-wave inputs alongside 130+ dB dynamic range imaging to execute collision avoidance. Fleet operators in Saudi Arabia face SASO-mandated pre-integration timelines, compressing supplier qualification windows from 18 months to 9 months.
- Lane Departure Warning:Image sensors with lane-edge detection algorithms trigger haptic steering feedback or audible alerts. ESMA mandates for heavy commercial vehicles imported into the UAE concentrate demand among Dubai-based logistics operators managing long-haul Gulf corridors.
- Adaptive Cruise Control:Longitudinal speed management through radar-maintained following distances.
- Parking Assistance:Ultrasonic transducer arrays for near-field obstacle detection in confined maneuvering.
Leading the category by volume: Lane Departure Warning. Growing fastest: Automatic Emergency Braking.
End User:
Procurement authority concentrates differently across the value chain, with Gulf OEM assembly lines demanding pre-certified modules while South African mining fleets shift toward performance-based service contracts.
- OEMs:Vehicle manufacturers in Dubai and Jeddah assembly plants specify integrated radar-camera modules with behind-grille mounting compatibility. Pre-certification requirements upstream to Tier-1 suppliers are reshaping contract structures toward long-term hardware-service bundles.
- Commercial Vehicles:Heavy truck fleets along the Addis Ababa-Djibouti corridor and UAE logistics operators face the steepest regulatory compliance burdens. ESMA lane departure mandates and SASO AEB protocols force simultaneous architecture redesigns before type-approval.
- Tier-1 Suppliers:Component integrators managing sensor fusion calibration and localized testing protocols.
- Aftermarket Providers:Independent retrofitters serving used vehicle imports in Nigeria's Lagos-Ibadan cluster.
Dominating procurement volume: OEMs. Expanding most quickly: Commercial Vehicles.
Technology:
Desert climate thermal management requirements favor wide-bandgap semiconductors, with silicon carbide MOSFETs gaining preference in high-temperature deployment zones.
- Camera-Based Systems:Image sensors with dynamic range exceeding 130 dB capture lane markings and traffic signage across variable lighting conditions. Lower unit costs and compatibility with legacy electrical architectures drive installation volumes across price-sensitive African markets.
- Radar Systems:76-81 GHz emitters deliver all-weather reliability through dust, precipitation, and darkness. Premium commercial vehicle configurations in Saudi long-haul corridors specify radar-dominant fusion where ambient temperatures exceed 50°C.
- Lidar Technology:Laser-based ranging for high-resolution 3D environmental mapping.
- Ultrasonic Sensors:Short-range detection for parking and low-speed maneuvering applications.
Highest installation base: Camera-Based Systems. Steepest expansion trajectory: Radar Systems.
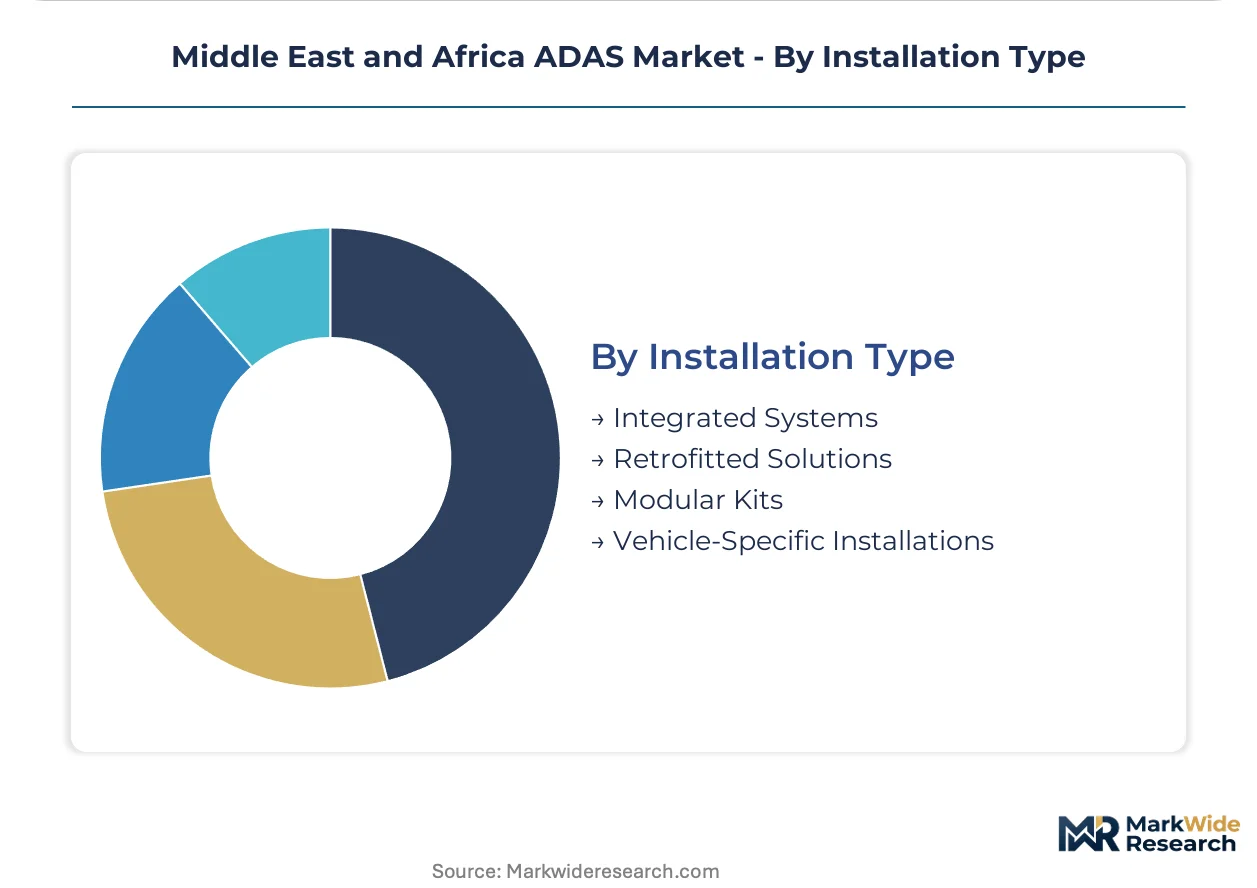
Installation Type:
Electrical architecture bandwidth constraints in pre-2020 vehicle platforms determine retrofit feasibility, with CAN-FD compatibility requirements filtering addressable markets.
- Integrated Systems:Factory-installed sensor fusion architectures with dedicated power and data pathways. Gulf OEM assembly lines require these configurations to satisfy SASO and ESMA pre-integration mandates without post-assembly calibration complexity.
- Retrofitted Solutions:Aftermarket installations on legacy platforms demand gateway module upgrades to accommodate real-time ADAS data throughput. Egypt's taxi fleet and Nigeria's used Japanese import market face the steepest technical barriers.
- Modular Kits:Standardized component packages for multi-platform deployment.
- Vehicle-Specific Installations:Custom-engineered mounting and calibration for discrete model years.
Capturing dominant share: Integrated Systems. Gaining share fastest: Retrofitted Solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial fleet operators in Saudi Arabia and the UAE concentrate procurement authority for collision avoidance systems, while South Africa's mining transport sector anchors radar-integrated platform demand across the continent.
Saudi Arabia
Long-haul trucking fleets along the Riyadh-Jeddah corridor deploy automatic emergency braking systems under SASO type-approval mandates. The Saudi Standards, Metrology and Quality Organization requires pre-integrated radar-camera fusion for all new commercial vehicle registrations. NEOM's northwest corridor hosts cellular-V2X roadside unit trials that converge with onboard sensor fusion architectures.
United Arab Emirates
Dubai-based logistics operators face compressed supplier qualification timelines as ESMA mandates lane departure warning systems on heavy commercial vehicle imports. The Emirates Authority for Standardization and Metrology's regulatory phase-ins force OEMs to redesign electrical architectures within nine-month windows. Abu Dhabi assembly plants now require pre-certified radar modules from Tier-1 suppliers.
South Africa
Platinum mining haul truck fleets source radar maintenance through performance-based service agreements with Johannesburg-based integrators. The National Regulator for Compulsory Specifications enforces IP6K9K sealing validation for camera housings, extending product launch timelines versus European benchmarks. The Bushveld Complex's platinum group metal supply chains expose radar module substrate producers to input cost volatility.
Egypt
Cairo's taxi fleet operators confront legacy electrical architecture barriers when retrofitting ADAS capabilities on pre-2020 vehicle platforms. The country's national automotive regulator mandates gateway module upgrades to accommodate CAN-FD bandwidth requirements for real-time sensor data throughput. Alexandria's port facilities handle used vehicle imports that lack factory-integrated collision avoidance systems.
Nigeria
Independent service centers along the Lagos-Ibadan expressway cluster retrofit camera-based lane keeping systems on used Japanese vehicle imports. Aftermarket providers bypass OEM-controlled distribution channels to serve price-sensitive private vehicle owners. The absence of harmonized federal safety standards fragments procurement strategies across state-level enforcement variations.
Middle East and Africa ADAS Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated module suppliers capturing Gulf OEM assembly line contracts while independent calibration centers serve aftermarket retrofit demand. The vendor base organizes around three archetypes: German-engineered Tier-1 integrators with regional manufacturing footprints, Israeli algorithm specialists competing on mapping density, and diversified Asian component conglomerates leveraging scale economics. M&A activity concentrates on sensor fusion calibration capabilities, while strategic partnerships target V2X infrastructure convergence.
Among German-engineered Tier-1 integrators, Continental AG and Robert Bosch GmbH anchor the premium module supply tier, with the former leveraging regional manufacturing footprints and the latter operating localized calibration centers in Dubai and Johannesburg. Mobileye represents the algorithm-centric archetype, extending Road Experience Management coverage across Saudi and Emirati highway networks to compete on mapping density rather than hardware integration.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| Mobileye |
| Autoliv Inc. |
| ZF Friedrichshafen AG |
| Denso Corporation |
| Aptiv PLC |
| Valeo SA |
| Hyundai Mobis Co., Ltd. |
| Others |
Supply & Pricing Matrix
IP6K9K sealing certification for camera housings gates qualified supply access and premium-tier pricing power across Middle East and Africa ADAS procurement. SASO and ESMA regulatory mandates compress supplier qualification timelines while concentrating procurement authority with fleet operators capable of absorbing pre-certified component premiums.
Pricing Analysis
Volume concentration among Gulf commercial fleets splits margin capture between hardware suppliers and calibration service providers. Three-tier pricing structure across premium radar-camera fusion, standard camera-dominant systems, and economy ultrasonic-only configurations reflects certification grade and after-sales bundling differentiation. Cost compression in economy tiers intensifies as Nigerian aftermarket retrofitters bypass OEM channels. Mining fleet operators in South Africa exhibit lowest price sensitivity due to performance-based contracting models.
Supply Chain Analysis
Embedded systems engineering shortages in Johannesburg and Dubai constrain module assembly capacity expansion. Germany, Japan, and South Korea anchor Tier-1 radar module supply. Silicon carbide substrates and platinum group metals for radar substrates feed from Bushveld Complex extraction. Single-source vulnerability in palladium supply chains exposes cost volatility. Distribution runs through Dubai-based logistics hubs serving Gulf assembly plants and Johannesburg integrators for mining sector contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa ADAS market sits in a sensor fusion technology transition, with radar-camera fusion architectures displacing single-modality legacy systems across commercial fleet procurement.
For Market Incumbents: Acquire calibration center networks in secondary Saudi cities and Ethiopia's Addis Ababa corridor to defend against elevated post-installation failure rates. Pre-certify radar modules under SASO and ESMA protocols simultaneously to neutralize homologation fragmentation overhead. Long-term service contracts bundling hardware and maintenance displace transactional sales in South African mining. For New Entrants and Emerging Players: Begin with aftermarket retrofit channels serving Nigeria's Lagos-Ibadan expressway cluster, where independent service centers bypass OEM distribution on used Japanese imports. Ethiopia's underpenetrated heavy truck fleet along the Addis Ababa-Djibouti route offers first-mover positioning for radar-integrated platforms. Partner with cellular-V2X infrastructure developers in Saudi Arabia's NEOM corridor for cooperative perception architecture access. For Investors and Strategic Acquirers: ESMA's nine-month supplier qualification compression is the leading indicator that regulatory velocity is accelerating market consolidation toward pre-certified component specialists. Acquisition targets should exhibit dual SASO-ESMA certification capability and localized calibration infrastructure. Watch for cellular-V2X spectrum allocation announcements as inflection signals for cooperative perception investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Center Network Expansion | Localized calibration in Riyadh and Jeddah reduces post-installation failure rates for SASO-compliant fleets. |
| Dual Certification Investment | Simultaneous SASO and ESMA pre-certification neutralizes homologation fragmentation across Gulf markets. |
| Silicon Carbide Module Development | Wide-bandgap semiconductors extend component lifespans where ambient temperatures exceed 50°C in desert deployment. |
| Long-Term Service Contracting | Performance-based agreements with Johannesburg integrators concentrate procurement authority in South African mining. |
| V2X Infrastructure Partnership | Cooperative perception architectures in NEOM corridor converge roadside units with onboard sensor fusion. |
Research Methodology
Multi-period observation of SASO type-approval protocol evolution, ESMA regulatory phase-in timelines, and NRCS testing backlog durations anchored the trend analysis, supplemented by interviews with Tier-1 supplier procurement managers, OEM platform engineers in Dubai and Jeddah assembly plants, aftermarket distributors in Nigeria's Lagos-Ibadan cluster, and fleet engineering directors at Saudi logistics operators. Secondary validation drew from vehicle production databases, Gulf customs and trade data, SEC filings of listed automotive suppliers, and IHS Markit registration data across the analysis window. Bottom-up component demand modeling and top-down fleet penetration estimates underwent triangulation.
Segment-weighting across product type, end user, technology, and installation type dimensions shaped the analytical framework, with additional weighting for regional regulatory cluster divergence between Gulf harmonization and South African NRCS protocols. CAGRs derived from installed base growth trajectories and content-per-vehicle expansion across the projection horizon. Forecast inputs incorporated silicon carbide adoption curves in radar front-ends and cellular-V2X deployment timelines in Saudi infrastructure planning.
Platinum group metal price volatility, regulatory timeline delays at NRCS facilities, and embedded systems engineering talent shortages are the dominant revision risks to model outputs. Forecasts reflect assumptions regarding ESMA and SASO mandate adherence schedules without contingency for enforcement variation. Material deviation in palladium supply chain stability or calibration infrastructure deployment warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Autonomous Commercial Vehicles Market
Autonomous Vehicles
Mexico Autonomous Navigation Market
Autonomous Vehicles
Germany Autonomous Navigation Market
Autonomous Vehicles
Autonomous System Market
Autonomous Vehicles
Self Driving Car Market
Autonomous Vehicles
Automotive Autonomous Emergency Braking System Market
Autonomous Vehicles
Autonomous Vehicles and Car Patent Market
Autonomous Vehicles
Autonomous Ride-Sharing Services Market
Autonomous Vehicles
North America Adaptive Steering Market
Autonomous Vehicles
India Automotive Advanced Driver Assistance Systems Market
Autonomous Vehicles
Automatic Steering System Market
Autonomous Vehicles
Autonomous Haulage Truck Market
Autonomous Vehicles
Autonomous Driving Technology Market
Autonomous Vehicles
Spain Autonomous Navigation Market
Autonomous Vehicles
Connected Vehicle Market
Autonomous Vehicles
Autonomous Freight Trains Market