
 Autonomous Vehicle Simulation Software Market | 2026-2036
Autonomous Vehicle Simulation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Vehicle Simulation Software Market Insights
The EU AI Act is expanding the compliance burden for autonomous system deployers across Europe. Ansys leverages physics-based sensor modeling to anchor its position in safety-critical validation workflows. Siemens Digital Industries Software sustains deep integration with automotive OEM toolchains through its Xcelerator portfolio. MathWorks competes by embedding MATLAB and Simulink into university and Tier 1 supplier curricula worldwide.
Autonomous vehicle simulation software encompasses physics engines, sensor models, traffic scenario generators, and hardware-in-the-loop interfaces that replicate real-world driving conditions with sub-millisecond fidelity for algorithm training and safety verification. Full mission simulation dominates procurement budgets as OEMs seek end-to-end virtual proving grounds before physical prototype deployment. Cloud-based deployment is capturing the fastest expansion as elastic compute resources enable parallel execution of millions of edge-case scenarios. Hardware-in-the-loop configurations retain premium pricing due to FPGA and real-time processor requirements that validate ECU behavior under fault injection.
NHTSA in the United States, EMA through its broader machinery safety frameworks, and Germany's KBA collectively shape test protocol harmonization and data logging mandates that simulation vendors must embed. China's MIIT and SAMR are drafting domestic autonomous vehicle certification standards that will require localized simulation evidence packages for market access. Stakeholders must monitor which regulatory jurisdictions first mandate specific scenario coverage minimums, as these rulings will determine where software vendors prioritize compliance engineering investments.
Market Dynamics
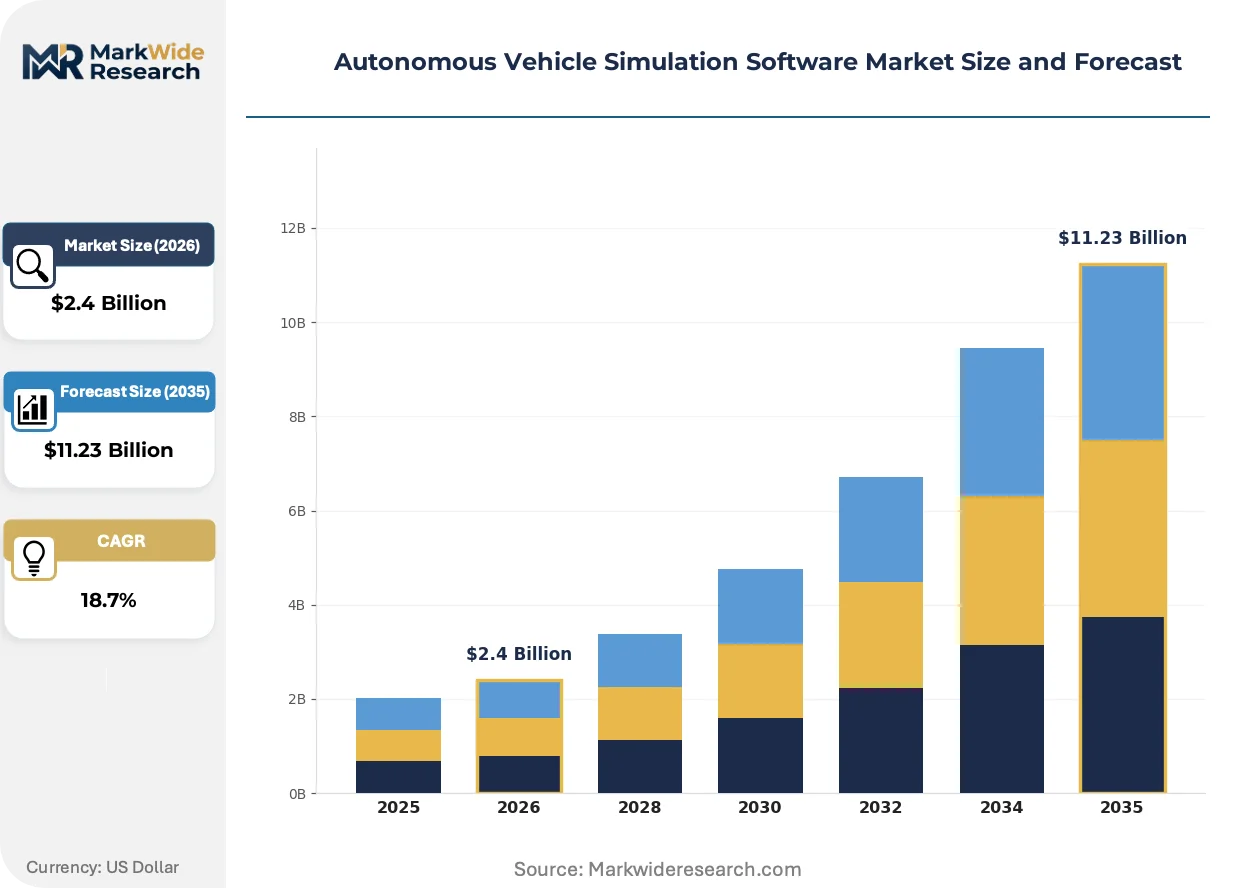
Physics-based sensor fidelity requirements under NHTSA and EU AI Act mandates are compressing development timelines while inflating validation budgets, forcing OEMs to consolidate vendor relationships around platforms that embed regulatory evidence generation natively.
Growth Catalysts
- EU AI Act compliance mandates:Automated driving system deployers must demonstrate traceable safety validation, creating procurement pull for simulation platforms with embedded audit trails.
- Edge-case scenario explosion:Training algorithms for rare traffic events requires millions of synthetic miles that physical proving grounds cannot replicate.
- Germany:KBA testing protocols are harmonizing with Euro NCAP, concentrating vendor engineering resources on TÜV-certified toolchain integration.
Market Restraints
- FPGA and real-time processor costs:Hardware-in-the-loop configurations require specialized silicon that locks procurement into premium pricing tiers.
- Cloud compute dependency:Elastic scenario execution concentrates vendor margins on hyperscaler partnerships, squeezing independent software margins.
- Sensor model calibration drift:Physics fidelity degrades without continuous real-world data feedback, creating validation gaps that regulators flag.
Strategic Opportunities
- China's MIIT certification pathway:Domestic OEMs require localized simulation evidence packages, opening captive market access for compliant platforms.
- Digital twin convergence:Manufacturing execution systems are merging with virtual validation environments, enabling unified lifecycle data models.
- Subscription-based access models:Tier 1 suppliers are replacing perpetual licenses with usage-based contracts that reduce upfront capital barriers.
Industry Challenges
- Systems safety engineering talent scarcity:ISO 26262 functional safety expertise remains concentrated among legacy automotive suppliers.
- Multi-domain toolchain integration:Bridging MATLAB legacy codebases with modern game-engine renderers creates technical debt.
- Cross-jurisdiction evidence portability:NHTSA scenario logs do not automatically satisfy KBA or MIIT submission requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Vehicle Simulation Software Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $11.23 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full Mission Simulation, Software Development Kit, Hardware-In-the-Loop, Driver Simulation Deployment: Cloud-Based, On-Premise, Hybrid, Virtual Environment End User: OEMs, Research Institutions, Government Agencies, Academics Application: Testing, Training, Validation, Data Generation |
| Companies Covered | Siemens Digital Industries Software, Ansys, Dassault Systèmes, MathWorks, dSPACE, PTC, Altair Engineering, Autodesk, ESI Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Vehicle Simulation Software Market Trends and Innovations
Generative AI is compressing scenario authoring timelines while regulatory bodies race to codify acceptable synthetic data thresholds for type approval.
Neural radiance fields (NeRF) are decentralizing environmental asset creation by enabling reconstruction of real-world locations from commodity camera footage. Tier 1 suppliers are adopting NeRF pipelines to populate virtual proving grounds without manual 3D modeling. This capability is decentralizing content production away from specialized studios toward OEM internal teams.
The EU AI Act's risk-based classification system is mandating conformity assessments for autonomous decision-making components. Simulation vendors must embed explainability logging that traces algorithmic outputs to specific scenario inputs. German OEMs are responding by procuring platforms with built-in evidence package generation.
Automotive procurement departments are unbundling validation software from hardware-in-the-loop hardware, creating separate vendor selection processes. Tier 1 electronics suppliers are winning simulation contracts independently from traditional HIL integrators. This shift is most visible in the United States, where NHTSA timeline pressures favor software agility over bundled system procurement.
Autonomous Vehicle Simulation Software Market Segmentation
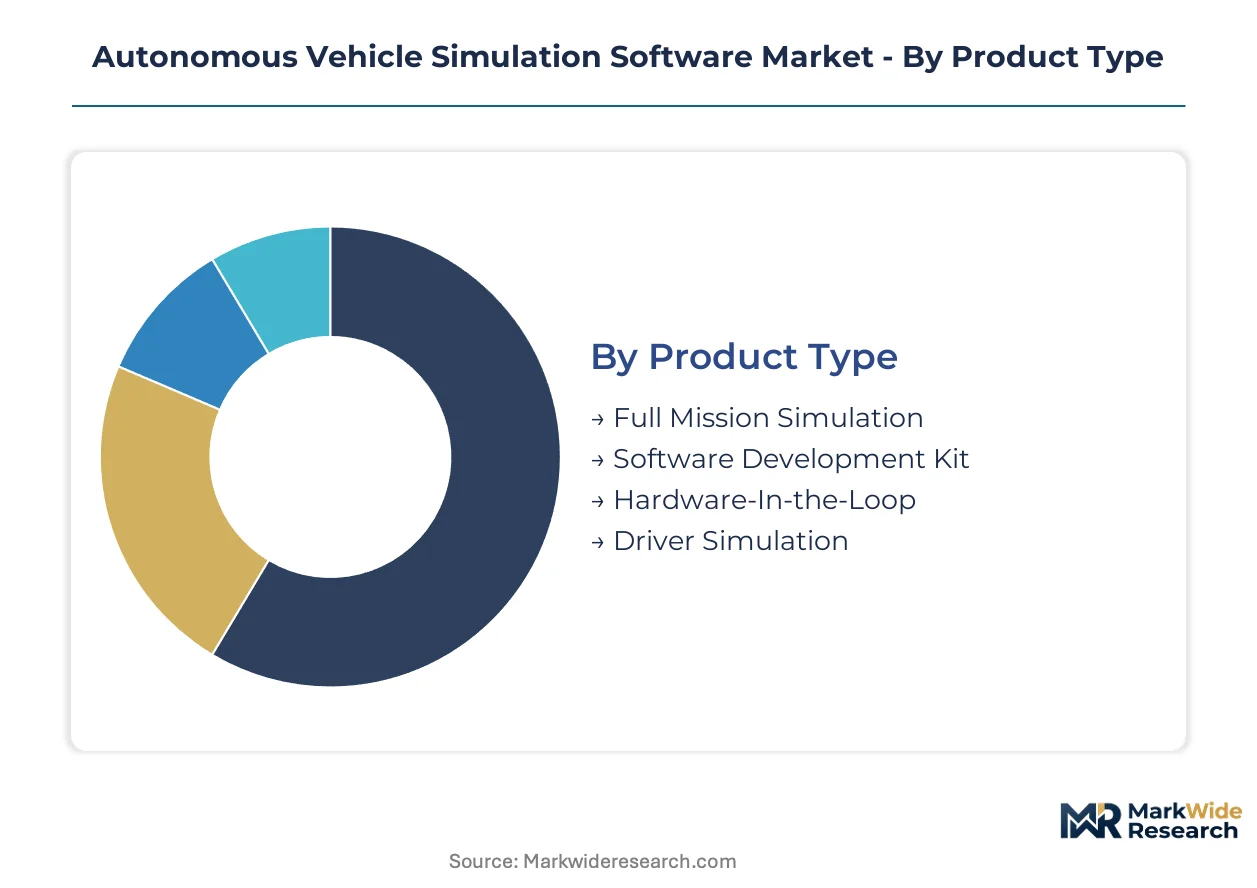
Segmentation in autonomous vehicle simulation software reveals how procurement priorities diverge between integrated platform buyers and modular tool adopters. OEM consolidation strategies favor end-to-end environments, while research institutions assemble best-of-breed components.
Product Type:
Integration depth separates standalone validation suites from embedded development components that plug into broader automotive toolchains.
- Full Mission Simulation:End-to-end virtual proving grounds replicate complete driving missions with physics engines, traffic scenarios, and environmental conditions in unified environments. German OEMs dominate procurement here, driven by KBA certification requirements that demand traceable scenario coverage across entire vehicle operating domains.
- Hardware-In-the-Loop:Real-time processor and FPGA configurations validate ECU behavior under fault injection with sub-millisecond synchronization. Premium pricing reflects specialized silicon requirements, though automotive procurement departments increasingly unbundle this hardware from software validation platforms.
- Software Development Kit:Modular APIs and sensor libraries enable custom algorithm integration into existing automotive development pipelines.
- Driver Simulation:Human-in-the-loop configurations assess occupant interaction with automated systems during handover events.
Full Mission Simulation leads volumes today; Hardware-In-the-Loop is gaining share fastest as procurement unbundling accelerates.
Deployment:
Cost tier structures separate capital-intensive infrastructure investments from operational expenditure models that scale with validation workload.
- Cloud-Based:Elastic compute resources enable parallel execution of millions of edge-case scenarios without fixed infrastructure commitment. United States OEMs concentrate procurement here, pressured by NHTSA timeline compression that favors rapid scenario iteration over capital deployment cycles.
- Hybrid:Sensitive algorithm development runs on-premise while massive scenario sweeps burst to cloud infrastructure. China's domestic OEMs favor this architecture as MIIT certification requirements mandate localized data handling for certain validation evidence types.
- On-Premise:Dedicated server clusters maintain complete data sovereignty for classified or competitive-sensitive development programs.
- Virtual Environment:Containerized deployments abstract hardware dependencies for portable toolchain consistency across engineering sites.
Cloud-Based deployments capture steepest expansion trajectory; Hybrid configurations show strongest pipeline growth among China-facing suppliers.
End User:
Customer type determines scenario complexity requirements and regulatory evidence standards that shape platform selection criteria.
- OEMs:Full-stack automotive manufacturers procure integrated platforms spanning concept validation through homologation support. Procurement concentrates in Germany, the United States, and China as these jurisdictions deploy the most stringent autonomous system certification frameworks.
- Government Agencies:National regulators and research institutes establish benchmark scenarios and protocol harmonization standards. Demand clusters around NHTSA in the United States and KBA in Germany as these bodies actively draft scenario coverage minimums.
- Research Institutions:Universities and technical institutes advance algorithmic methods without production homologation constraints.
- Academics:Curricula-focused procurement emphasizes accessible interfaces and educational licensing structures.
OEMs dominate procurement budgets today; Government Agencies are expanding fastest as regulators internalize validation capabilities.
Application:
Maturity stages separate established use cases with codified methodologies from emerging applications where standards remain in flux.
- Testing:Systematic exercise of autonomous functions against defined pass-fail criteria with reproducible scenario libraries. German KBA protocols and Euro NCAP harmonization drive standardization investment here.
- Data Generation:Synthetic sensor outputs train perception algorithms when real-world edge-case collection proves uneconomical. NeRF pipelines from commodity camera footage are decentralizing content production toward OEM internal teams.
- Validation:Formal evidence packages demonstrating regulatory compliance through traceable simulation execution.
- Training:Human operator preparation for supervised automation modes and failure response protocols.
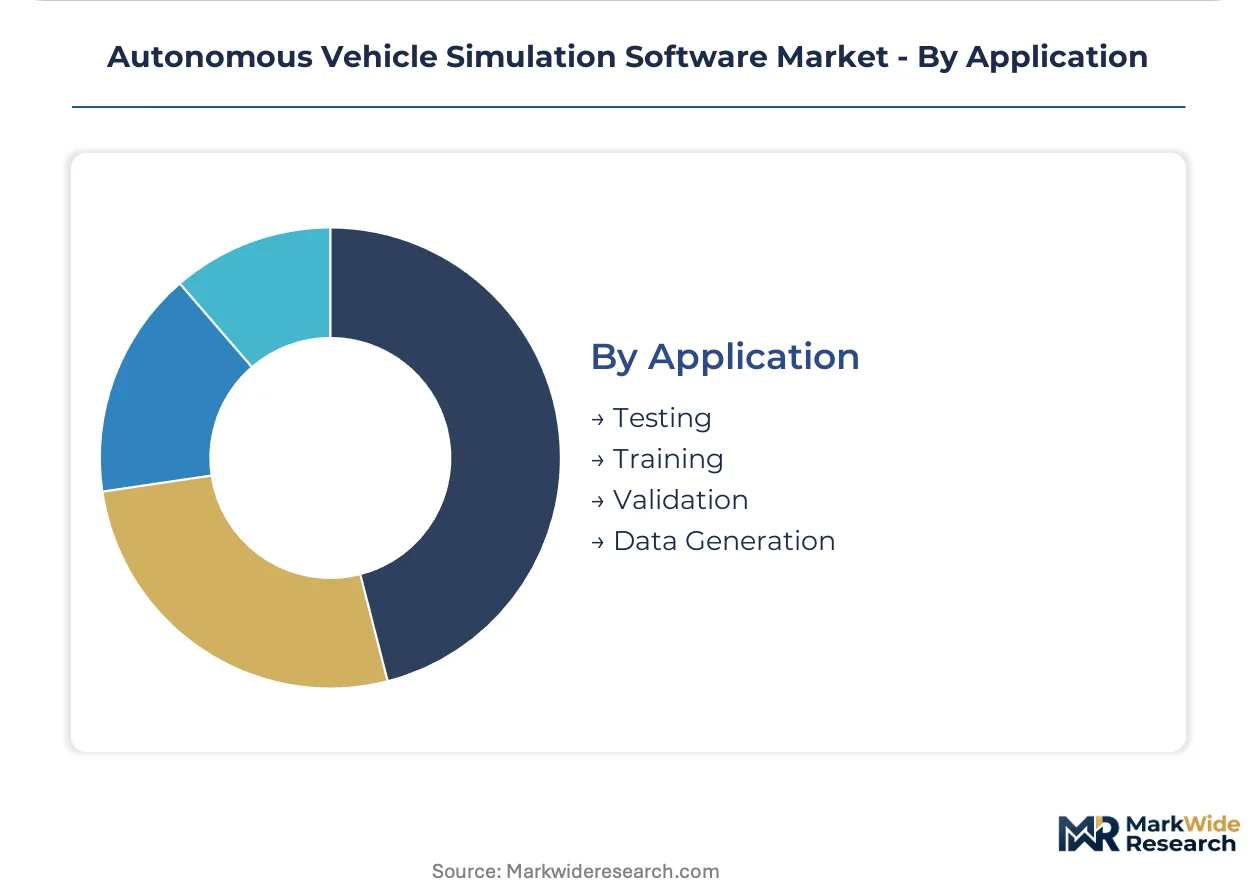
Testing commands the largest installed base; Data Generation is climbing the fastest as training dataset requirements expand exponentially.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Autonomous vehicle simulation software originated from German automotive engineering traditions, where KBA certification protocols first mandated virtual validation for safety-critical systems. This heritage established Germany as the foundational market before regulatory complexity spread procurement demand to the United States and China.
United States
NHTSA timeline pressures compress development cycles for Detroit and Silicon Valley engineering centers. The agency's testing mandates require traceable scenario coverage that favors cloud-elastic simulation platforms. Procurement concentrates in Michigan's automotive corridor and California's autonomous vehicle testing zones.
Germany
KBA harmonization with Euro NCAP drives TÜV-certified toolchain integration across Munich, Stuttgart, and Wolfsburg engineering clusters. The EU AI Act's risk-based classification system mandates conformity assessments that embed explainability logging into platform requirements. German OEMs procure end-to-end virtual proving grounds with native evidence generation.
China
MIIT and SAMR certification standards require localized simulation evidence packages for domestic market access. Yangtze River Delta OEMs favor hybrid deployment architectures that keep sensitive algorithm development on-premise while bursting massive scenario sweeps to cloud infrastructure. Shanghai and Beijing host the dominant validation engineering concentrations.
Japan
METI guidance on automated driving safety frameworks shapes domestic procurement criteria for Tokyo and Nagoya-based manufacturers. JIS standards alignment with international homologation requirements drives investment in high-fidelity sensor modeling. Tier 1 suppliers in the Chubu region integrate simulation platforms into legacy MATLAB development pipelines.
South Korea
Seoul Capital Area OEMs expand virtual validation procurement to meet MFDS-aligned functional safety expectations for export markets. Government-funded autonomous vehicle testbeds in Pangyo and Hwaseong establish benchmark scenarios that influence platform selection criteria. Domestic suppliers prioritize hardware-in-the-loop configurations for ECU validation.
Autonomous Vehicle Simulation Software Market Competitive Landscape
The competitive structure tilts toward diversified industrial software conglomerates with deep automotive tool chain integration. Siemens Digital Industries Software, Ansys, and Dassault Systèmes anchor the premium tier through physics-based modeling heritage and regulatory compliance engineering. MathWorks occupies a distinct position embedding development environments into university curricula and Tier 1 supplier workflows. Three archetypes dominate: diversified industrial software platforms, specialized automotive validation suites, and embedded algorithm development environments. Competitive moves concentrate on unbundling hardware-in-the-loop hardware from software validation platforms, and embedding generative AI for scenario compression.
Within the diversified industrial software tier, Siemens Digital Industries Software and Ansys exemplify platform consolidation strategies that span manufacturing execution through virtual validation. MathWorks represents the embedded development environment archetype with curriculum-driven ecosystem lock-in. dSPACE anchors the specialized automotive validation segment with heritage in real-time processor configurations.
| Leading Market Players |
|---|
| Siemens Digital Industries Software |
| Ansys |
| Dassault Systèmes |
| MathWorks |
| dSPACE |
| PTC |
| Altair Engineering |
| Autodesk |
| ESI Group |
| Others |
Pricing and Supply Chain Analysis
EU AI Act conformity assessment mandates gate qualified supply access and premium-tier pricing for simulation platforms embedding native audit trails and explainability logging. KBA certification requirements in Germany and NHTSA testing mandates in the United States concentrate procurement budgets on vendors with proven regulatory evidence generation, compressing price competition at the top tier while opening mid-market gaps.
Pricing Analysis
Subscription-based SaaS tiers with usage-scaling contracts dominate procurement, separating premium full-mission simulation platforms from standard SDK modules and economy-tier academic licenses. Price differentiation hinges on TÜV-certified toolchain integration and FPGA real-time processor inclusion. Cost compression in standard tiers intensifies as hyperscaler partnerships squeeze independent software margins. Tier 1 suppliers exhibit highest price sensitivity; German OEMs prioritize compliance-grade platforms regardless of premium positioning.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for integrated validation platforms, while value-added resellers serve research institutions and Tier 2 suppliers. Supply concentrates in Germany, the United States, and China as regulatory complexity drives engineering resource localization. Component dependencies include specialized FPGA silicon from Taiwan, physics engine licensing from European specialized studios, and cloud compute infrastructure from hyperscaler partnerships. Single-source vulnerability in TÜV-certified hardware configurations elevates procurement risk. Distribution runs through automotive procurement departments increasingly unbundling software from hardware-in-the-loop systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU AI Act compliance engineering costs in Germany run substantially higher than NHTSA-aligned development in the United States, creating margin capture opportunities for platforms with modular jurisdiction-specific evidence packages.
For Market Incumbents: To counter unbundling pressure from automotive procurement departments, deepen native regulatory evidence generation for KBA and MIIT certification pathways while embedding generative AI scenario compression to defend price premiums against cloud-native entrants. For New Entrants and Emerging Players: Launch via hybrid deployment architectures targeting China's domestic OEMs seeking localized data handling with MIIT-compliant evidence packages, exploiting the gap between international platform localization capabilities and domestic certification speed requirements. For Investors and Strategic Acquirers: Roll-up economics work for specialized automotive validation suites because toolchain integration complexity creates sticky OEM relationships that resist displacement. Target mid-cap platforms with proven TÜV-certified integration and established university curriculum presence. Monitor EU AI Act scenario coverage minimum rulings as the inflection signal for compliance engineering investment prioritization.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration with Manufacturing Execution Systems | Digital twin convergence enables unified lifecycle data models from concept through production. |
| Generative AI Scenario Compression Investment | NeRF pipelines from commodity camera footage decentralize content production toward OEM internal teams. |
| Regulatory Evidence Package Standardization | Cross-jurisdiction portability gaps between NHTSA, KBA, and MIIT requirements create first-mover advantage for unified compliance engines. |
| Hybrid Deployment Architecture Development | Localized data handling for China's MIIT certification requirements opens captive market access. |
| University Curriculum Ecosystem Lock-in | MATLAB-embedded educational licensing creates pipeline capture for Tier 1 supplier procurement decisions. |
Research Methodology
Coverage spans Germany, the United States, China, Japan, and South Korea, with primary inputs from each jurisdiction combining structured interviews with OEM platform engineers, Tier 1 supplier procurement leads, regulatory affairs specialists at KBA and NHTSA, and university curriculum directors. Secondary validation draws from vehicle production databases, SEC filings of diversified industrial software conglomerates, hyperscaler capex disclosures, and EU regulatory submission documentation. Bottom-up segment sizing triangulates against top-down market aggregation.
Granularity-level modeling disaggregates revenue across product type, deployment architecture, end-user category, and application use case, with additional dimensioning by regional regulatory cluster and certification tier. CAGRs derive from scenario-weighted growth trajectory analysis across the projection horizon. Industry-specific forecast inputs include OEM virtual validation procurement cycle timing and regulatory mandate implementation schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under MIIT certification standard acceleration or EU AI Act scenario coverage threshold revisions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Autonomous Commercial Vehicles Market
Autonomous Vehicles
Norway Autonomous Navigation Market
Autonomous Vehicles
North America Autonomous Navigation Market
Autonomous Vehicles
Europe Autonomous Navigation Market
Autonomous Vehicles
Robotaxi Market
Autonomous Vehicles
Driverless Cab Service Market
Autonomous Vehicles
Zonal Vehicle Control Unit Architectures Market
Autonomous Vehicles
Europe ADAS Market
Autonomous Vehicles
Global Adaptive Cruise Control Market
Autonomous Vehicles
Global Connected, Autonomous, Shared, and Electric (CASE) Market
Autonomous Vehicles
Middle East and Africa Automated Guided Vehicles Market
Autonomous Vehicles
Automotive Lidar Market
Autonomous Vehicles
Autonomous Vehicle ECU Market
Autonomous Vehicles
Automated Valet Parking (AVP) Market
Autonomous Vehicles
Advanced Driver Assistance System (ADAS) Market
Autonomous Vehicles
Autonomous Delivery Vehicle Market