
 Autonomous Truck Technology Market | 2026-2036
Autonomous Truck Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Truck Technology Market Insights
The migration from rule-based perception stacks to end-to-end neural network architectures is reshaping how autonomous driving systems process sensor fusion and path planning. Waymo LLC leverages its extensive simulation infrastructure to validate safety-critical scenarios before road deployment. Aurora Innovation Inc. sustains development momentum through partnerships with tier-one automotive suppliers for hardware integration. Kodiak Robotics differentiates through a focused highway-autonomy strategy that limits operational design domains to controlled interstate corridors.
Autonomous truck technology encompasses the integrated hardware and software systems enabling commercial freight vehicles to operate without human driver intervention, incorporating LiDAR point-cloud densities exceeding 5 million points per second, radar arrays for all-weather object detection, and camera-based semantic segmentation for lane-keeping and traffic-sign recognition. The primary industrial purpose centers on reducing per-mile logistics costs while extending permissible daily driving hours beyond human regulatory limits. LiDAR and camera systems command the largest share of technology spending as OEMs pursue redundant perception architectures, while fleet management services generate recurring revenue streams that offset upfront sensor platform costs. Highway deployment dominates current testing volumes, though urban infrastructure applications remain constrained by edge-case complexity and regulatory uncertainty.
NHTSA in the United States, Germany's KBA, and Japan's METI each maintain distinct certification pathways for autonomous commercial vehicles, creating fragmented market access conditions that favor multi-jurisdictional testing programs. The EPA's evolving emissions standards for heavy-duty trucks indirectly shape technology roadmaps, as autonomous system power consumption affects overall vehicle efficiency compliance. Stakeholders must monitor how regulatory divergence between federal and state authorities in the United States influences interstate freight corridor standardization.
Market Dynamics
The migration from rule-based perception to end-to-end neural architectures is compressing development timelines while demanding entirely new validation protocols for safety-critical freight operations.
Growth Catalysts
- NHTSA Level 4 Certification Pathway:The evolving federal framework for commercial autonomous vehicle operation accelerates interstate testing permissions across Arizona, Texas, and New Mexico corridors.
- Hub-to-Hub Freight Model:Logistics operators concentrate investment on controlled interstate segments where operational design domains remain predictable and edge-case density stays manageable.
- LiDAR Point-Cloud Density Thresholds:Sensor platforms exceeding 5 million points per second enable redundant perception architectures that satisfy carrier liability requirements.
Market Restraints
- Multi-Jurisdictional Certification Friction:Divergent approval pathways between NHTSA, Germany's KBA, and Japan's METI fragment market access and inflate compliance overhead for international fleets.
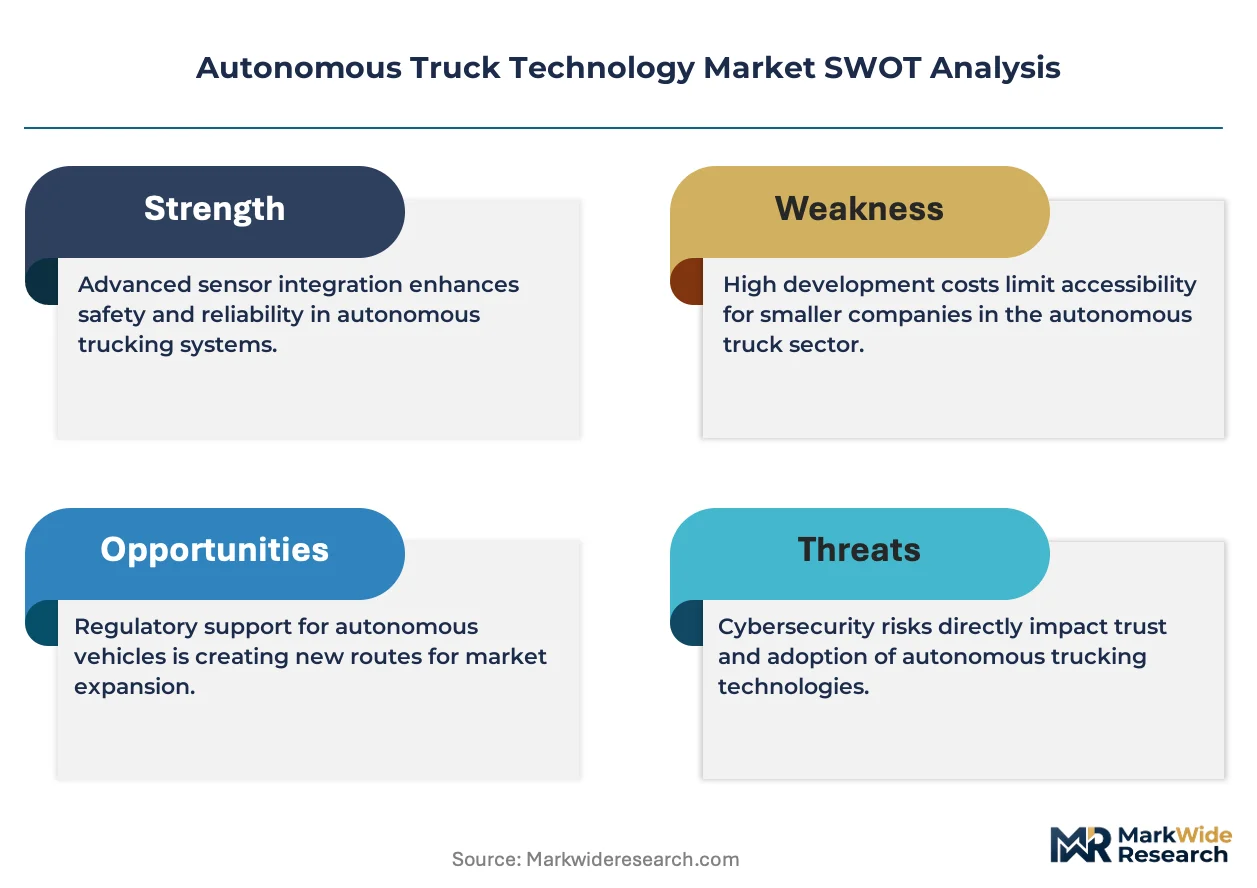
- Sensor Hardware Cost Concentration:LiDAR and camera arrays command disproportionate technology spending, limiting adoption among mid-size freight operators with constrained capital deployment capacity.
- Urban Edge-Case Complexity:Unstructured environments with irregular traffic patterns and construction zones remain technically prohibitive for current perception stacks.
Strategic Opportunities
- Southwestern United States Corridor Density:Permissive regulatory environments in Arizona, Texas, and New Mexico enable extended driverless testing that accelerates safety validation datasets.
- EPA Heavy-Duty Efficiency Integration:Autonomous system power optimization creates compliance synergies with evolving emissions standards for Class 8 trucks.
- Fleet Management Service Unbundling:Recurring revenue platforms for remote monitoring and predictive maintenance offset upfront sensor platform costs for asset-light operators.
Industry Challenges
- Simulation-to-Reality Validation Gap:Safety-critical scenario testing requires bridging synthetic environment outputs with physical road performance without exhaustive mileage accumulation.
- Tier-One Hardware Integration Complexity:Deep partnerships with automotive suppliers demand synchronized development cycles that conflict with software iteration velocities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Truck Technology Market |
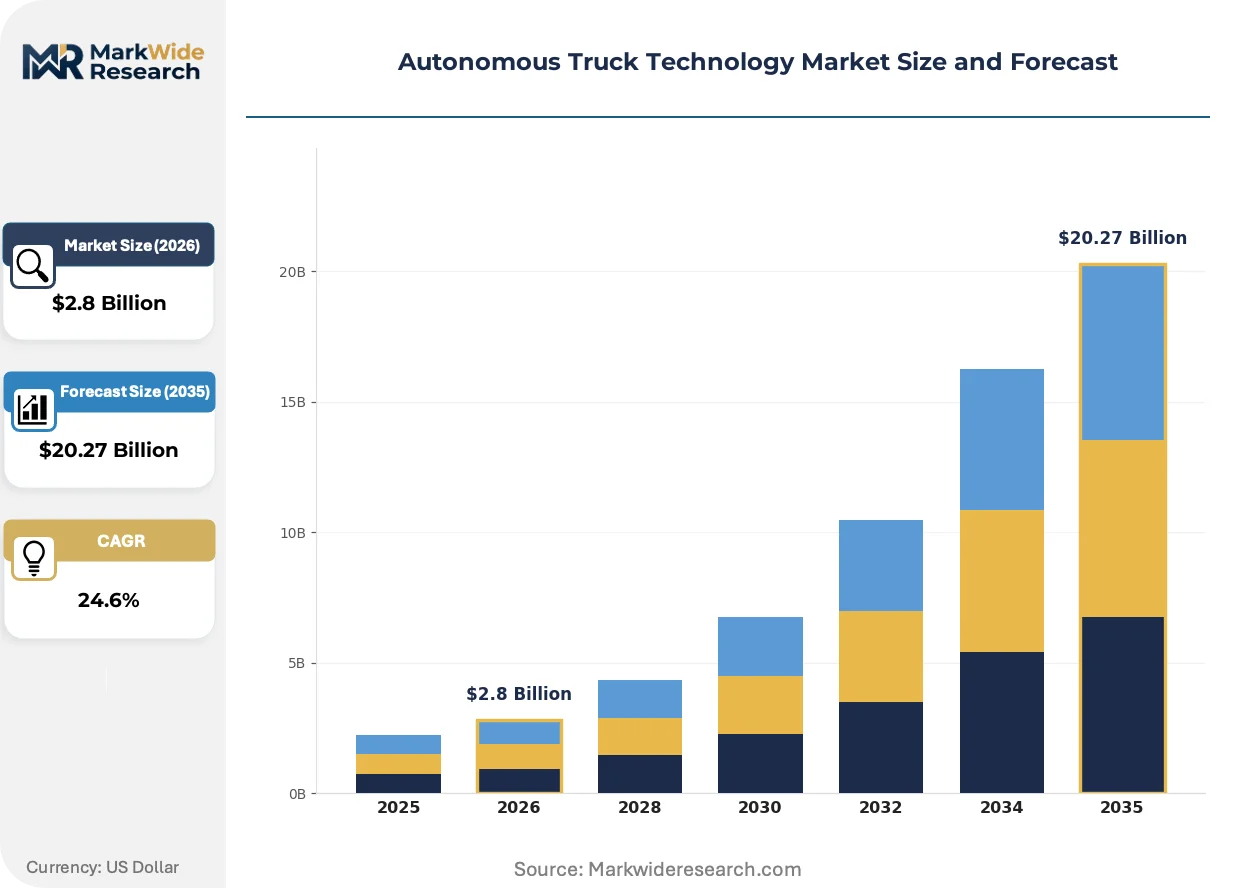
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $20.27 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: LiDAR, Radar, Camera Systems, Ultrasonic Sensors End User: Logistics Providers, Freight Carriers, Retailers, OEMs Deployment: On-Road, Off-Road, Urban Infrastructure, Highway Systems Service Type: Fleet Management, Route Optimization, Maintenance Services, Data Analytics |
| Companies Covered | Waymo LLC, Aurora Innovation Inc., TuSimple Holdings Inc., Embark Trucks Inc., Kodiak Robotics, PlusAI Inc., Daimler Truck AG, AB Volvo, PACCAR Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Truck Technology Market Trends and Innovations
Computational architectures and regulatory frameworks are converging to redefine how autonomous freight systems achieve commercial deployment at scale.
End-to-end neural networks are migrating from modular perception stacks that separately process LiDAR, radar, and camera inputs. Tier-one automotive suppliers and technology developers adopt these unified architectures to compress path-planning latency. This migration from discrete component optimization to holistic scene understanding is enabling real-time decision-making in dynamic highway environments.
NHTSA's evolving framework for Level 4 commercial vehicle operation creates accelerated certification timelines for interstate freight corridors. The regulatory consequence shifts liability frameworks toward manufacturers and fleet operators while reducing driver-hour restrictions. Southwestern United States freight routes respond with expanded pilot programs targeting hub-to-hub autonomous corridors.
Freight carriers now demand performance-based contracting structures that tie vendor compensation to operational uptime metrics rather than hardware delivery. Traditional equipment procurement channels face displacement from integrated mobility service agreements. This shift concentrates among long-haul operators in the southwestern United States where regulatory clarity permits extended driverless testing commitments.
Autonomous Truck Technology Market Segmentation
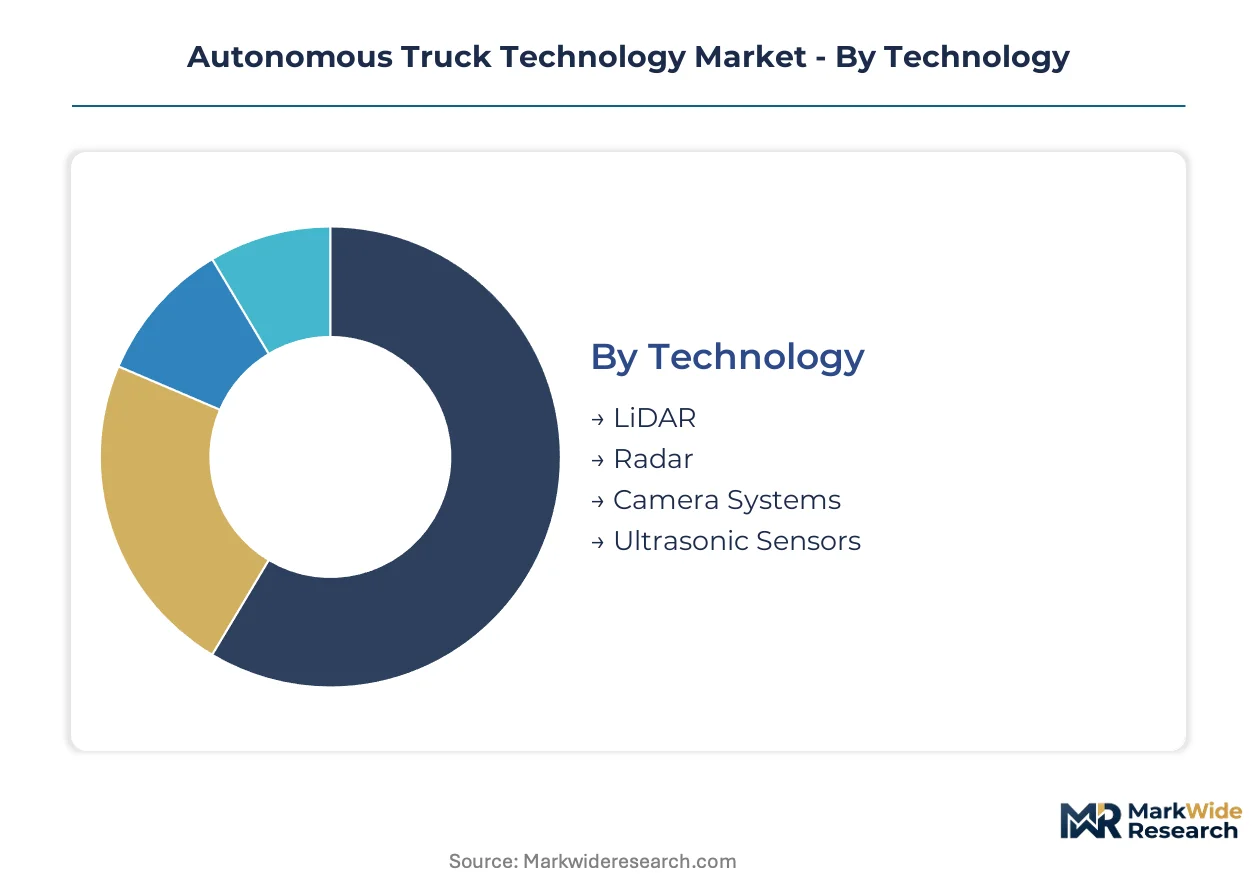
Autonomous truck technology segments reflect divergent hardware economics and operational maturity levels. Fleet procurement decisions increasingly favor integrated technology bundles over standalone sensor procurement. Deployment constraints vary sharply between controlled highway corridors and unstructured urban environments.
Technology:
Cost tier differentiation separates premium redundant perception stacks from single-sensor economy configurations.
- LiDAR:Point-cloud densities exceeding 5 million points per second enable centimeter-level object detection at highway speeds. Demand concentrates among Class 8 freight carriers operating Arizona-Texas corridors where NHTSA Level 4 certification requirements mandate redundant perception architectures.
- Camera Systems:Semantic segmentation algorithms process visual inputs for lane-keeping and traffic-sign recognition. Logistics providers in the southwestern United States specify camera arrays as primary sensors where clear weather conditions predominate and LiDAR cost thresholds strain capital deployment capacity.
- Radar:All-weather detection capabilities penetrate fog, rain, and dust particulates that blind optical sensors.
- Ultrasonic Sensors:Short-range proximity detection supports low-speed maneuvering in depot and loading dock environments.
LiDAR holds installed capacity. Camera Systems is rotating up the share rankings.
End User:
Customer type determines procurement scale and service integration depth.
- Freight Carriers:Asset-heavy operators pursue hub-to-hub autonomy to extend daily driving hours beyond regulatory limits. Concentrated demand emerges from long-haul fleets operating interstate corridors in Arizona, Texas, and New Mexico where state regulations permit extended driverless testing.
- Logistics Providers:Third-party operators integrate autonomous technology through mobility service agreements rather than capital purchase. These asset-light structures concentrate in southwestern United States freight corridors where performance-based contracting ties vendor compensation to operational uptime metrics.
- Retailers:Private fleet operators pilot last-mile and distribution center automation.
- OEMs:Vehicle manufacturers develop proprietary autonomous platforms for factory integration.
Freight Carriers dominate current deployment volumes. Logistics Providers is expanding most quickly through service-based adoption models.
Deployment:
Application environment dictates technical complexity and regulatory clearance requirements.
- Highway Systems:Controlled interstate corridors with predictable traffic patterns and standardized infrastructure markings. Demand clusters in southwestern United States routes where NHTSA frameworks and state-level permissions converge to enable extended driverless testing.
- On-Road:Mixed-traffic arterial roads with signalized intersections and variable lane configurations. Freight carriers in Texas pilot on-road segments connecting highway corridors to distribution hubs.
- Urban Infrastructure:Unstructured environments with irregular traffic patterns, construction zones, and pedestrian interaction.
- Off-Road:Mining, agriculture, and closed industrial sites with geofenced operational boundaries.
Highway Systems commands validated safety datasets. On-Road is climbing the fastest as corridor networks expand.
Service Type:
Revenue model maturity separates hardware-dependent sales from recurring service platforms.
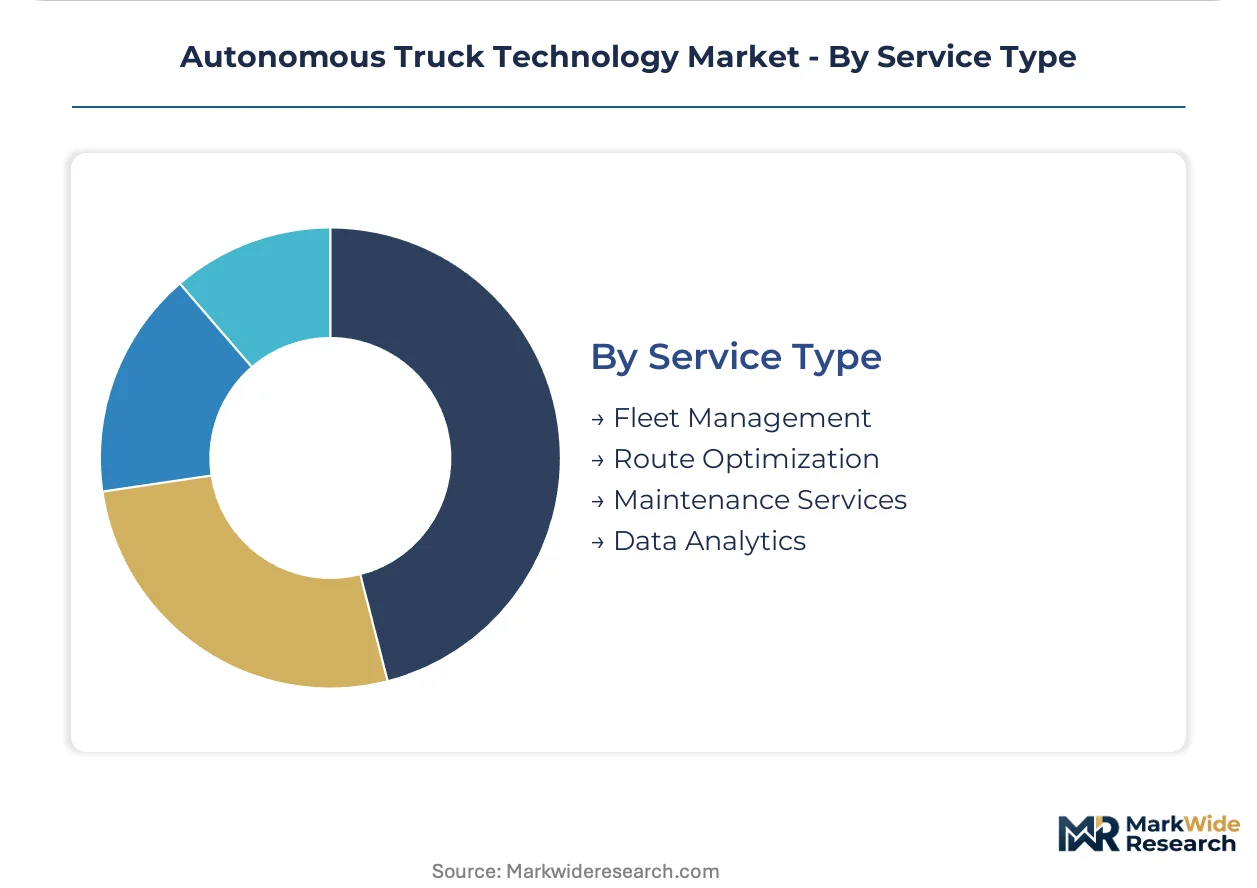
- Fleet Management:Remote monitoring, vehicle health diagnostics, and predictive maintenance scheduling. Asset-light operators in the southwestern United States adopt these services to offset upfront sensor platform costs.
- Data Analytics:Operational performance optimization through fuel consumption analysis and route efficiency modeling. Logistics providers specify analytics bundles to justify autonomous technology investments.
- Route Optimization:Dynamic path planning integrating real-time traffic, weather, and regulatory data.
- Maintenance Services:Specialized technician networks for sensor calibration and software updates.
Fleet Management holds recurring revenue concentration. Data Analytics is gaining share fastest as performance-based contracting expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based freight technology developers export autonomous driving systems to logistics operators across Germany, Japan, and Australia. Interstate freight corridors in the southwestern United States generate concentrated demand for hub-to-hub automation solutions.
United States
Class 8 carriers and third-party logistics providers drive deployment across Arizona-Texas-New Mexico corridors. NHTSA's evolving Level 4 commercial vehicle framework accelerates interstate testing permissions. The Dallas-Fort Worth metroplex anchors pilot programs connecting distribution hubs to highway autonomous segments.
Germany
Daimler Truck AG and AB Volvo channel European R&D investment through Stuttgart and Gothenburg engineering centers. Germany's KBA maintains distinct certification pathways for autonomous commercial vehicles that diverge from NHTSA timelines. The A9 digital test field between Munich and Nuremberg validates truck platooning and sensor fusion architectures.
China
Domestic freight volume and port automation projects concentrate demand in the Yangtze River Delta and Pearl River Delta regions. MIIT guidelines for intelligent connected vehicles shape OEM development roadmaps. Shenzhen and Shanghai municipal authorities permit closed-loop autonomous logistics within bonded port zones and industrial parks.
Japan
Precision manufacturing supply chains and aging driver demographics accelerate interest in highway automation. METI's regulatory framework for autonomous commercial vehicles emphasizes safety validation through simulation-to-road bridging protocols. The Chubu region around Nagoya hosts testing corridors linking automotive supplier clusters to port facilities.
Australia
Mining sector automation and remote freight corridors create demand for off-highway autonomous haulage. The country's national transport regulator coordinates state-level permits for heavy vehicle automation trials. Western Australia's Pilbara region operates commercial autonomous haul trucks that inform technology transfer to on-road freight applications.
Autonomous Truck Technology Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. Consolidation pressure intensifies as capital requirements for sensor hardware and simulation infrastructure favor scaled operators. Three archetypes dominate: technology developers with end-to-end neural architectures, tier-one automotive suppliers with manufacturing integration capabilities, and fleet operators pursuing captive autonomy platforms. Competitive moves concentrate on strategic partnerships for hardware integration and geographic expansion into permissive regulatory corridors.
Within the technology developer tier, Waymo LLC and Aurora Innovation Inc. occupy positions defined by simulation infrastructure depth and automotive supplier relationships respectively. Kodiak Robotics exemplifies corridor-focused specialization that limits operational design domains to controlled interstate segments. Daimler Truck AG and AB Volvo anchor the OEM-integrated tier through captive development of factory-installed autonomous platforms.
| Leading Market Players |
|---|
| Waymo LLC |
| Aurora Innovation Inc. |
| TuSimple Holdings Inc. |
| Embark Trucks Inc. |
| Kodiak Robotics |
| PlusAI Inc. |
| Daimler Truck AG |
| AB Volvo |
| PACCAR Inc. |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on high-density LiDAR emitters determines both three-tier pricing spreads across premium, standard, and economy sensor bundles and the geographic clustering of tier-one integration partners in southwestern United States manufacturing corridors.
Pricing Analysis
Current-generation LiDAR arrays command substantial premiums over prior-generation mechanical spinning units and emerging solid-state alternatives. The dominant pricing structure runs through subscription-tied hardware bundles that amortize upfront sensor costs against recurring fleet management fees. Price differentiation centers on certification grade—NHTSA Level 4 validation tier versus state-permitted testing tier—and volume scale commitments from Class 8 carriers. Cost compression in economy-tier camera-primary configurations is intensifying because logistics providers in the southwestern United States strain capital deployment capacity. Asset-light operators exhibit highest price sensitivity; premium-tier freight carriers with hub-to-hub autonomy mandates show lowest.
Supply Chain Analysis
Export-control restrictions on high-performance computing chips and advanced laser emitters limit technology flows between United States, China, and Germany development centers. Component manufacturing concentrates in Taiwan, South Korea, and Japan for LiDAR photonics, with final assembly tethered to tier-one automotive supplier facilities in Mexico and the United States. Raw material dependencies span gallium arsenide substrates, rare-earth magnet arrays, and specialized optical coatings. Single-source vulnerability in high-purity semiconductor substrates poses structural risk. Distribution runs through captive OEM channels and direct-to-fleet technology developer partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive outcomes as freight carriers demand interoperable autonomy stacks that decouple hardware procurement from software service layers.
For Market Incumbents: Insulate core positions through backward integration into LiDAR emitter manufacturing and captive development of simulation-to-road validation protocols that emerging entrants cannot replicate. The threat of modular perception-stack commoditization by software-native competitors demands accelerated certification investment in NHTSA Level 4 pathways. Vertical integration into high-density sensor production anchors pricing power. For New Entrants and Emerging Players: Build out corridor-specific operational design domains in permissive regulatory environments before incumbents consolidate southwestern United States route access. The most penetrable white space sits in on-road segments connecting highway autonomous corridors to distribution hubs, where technical complexity remains manageable and performance-based contracting structures are emerging. A fleet-management-first go-to-market angle bypasses capital-intensive hardware procurement barriers. For Investors and Strategic Acquirers: NHTSA's evolving Level 4 commercial vehicle framework reshapes the acquisition landscape toward technology developers with validated safety datasets rather than hardware component suppliers. Long-term viability centers on recurring revenue platform economics over five-to-ten year deployment horizons. Acquisition targets should demonstrate simulation infrastructure depth and tier-one automotive supplier relationships. The signal to watch is state-level regulatory divergence that fragments interstate corridor standardization.| Strategic Initiative | Industry Significance |
|---|---|
| Simulation Infrastructure Investment | Waymo's synthetic environment validation compresses road-testing requirements before NHTSA certification. |
| Tier-One Hardware Integration | Aurora's automotive supplier partnerships synchronize sensor platform manufacturing with OEM production cycles. |
| Corridor-Specific Deployment | Kodiak's highway-autonomy focus limits operational design domains to controlled interstate segments in Arizona. |
| Fleet Management Service Launch | Asset-light operators adopt remote monitoring platforms to offset upfront LiDAR and camera array costs. |
| Multi-Jurisdictional Testing Expansion | Pilot programs across Texas and New Mexico generate safety validation datasets for federal certification pathways. |
Research Methodology
A standing panel of autonomous vehicle engineering directors, freight carrier fleet managers, tier-one automotive supplier procurement leads, and NHTSA regulatory affairs specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from SEC filings of publicly traded technology developers, NHTSA autonomous vehicle testing disclosure databases, state-level permitting records from Arizona and Texas transportation authorities, and commercial vehicle production data from IHS Markit. Bottom-up sensor platform shipment estimates triangulated against top-down fleet operator technology spending surveys.
Scenario-bracketing framed projections across the analysis window, with segmentation modeling across technology tier, end-user archetype, deployment environment, and service type. CAGRs derived from logistic diffusion curves fitted to observed pilot program expansion rates and regulatory clearance timelines. Industry-specific forecast inputs incorporated LiDAR point-cloud density adoption thresholds and NHTSA Level 4 certification velocity assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by capital-flush technology developers or rapid regulatory harmonization would shift outcomes. Material shifts in federal-state regulatory divergence, export-control enforcement on laser emitter technology, or carrier liability framework revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Automotive Autonomous Emergency Braking System Market
Autonomous Vehicles
China Autonomous Navigation Market
Autonomous Vehicles
Autonomous Vehicle ECU Market
Autonomous Vehicles
Connected Vehicle Technology Market
Autonomous Vehicles
Autonomous Emergency Braking System (AEBS) Market
Autonomous Vehicles
Autopilot Systems Market
Autonomous Vehicles
Autonomous (Driverless) Car Market
Autonomous Vehicles
Connected Vehicle Market
Autonomous Vehicles
Self-Driving Shuttle Market
Autonomous Vehicles
Autonomous Vehicle Simulation Software Market
Autonomous Vehicles
Fully Autonomous Driving Market
Autonomous Vehicles
AI in Transportation Market
Autonomous Vehicles
Automotive Predictive Technology Market
Autonomous Vehicles
Autonomous Haulage Truck Market
Autonomous Vehicles
Self-Driving Truck Market
Autonomous Vehicles
Autonomous Electric Bus Market