
 Latin America ADAS Market | 2026-2036
Latin America ADAS Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America ADAS Market Foresight
Level 2 autonomy specifications is bifurcating the competitive landscape into premium sensor-fusion providers and cost-optimized camera-centric suppliers. Bosch Group leverages its radar manufacturing footprint in the region to anchor supply contracts with major OEM assembly plants. Continental AG specializes in integrated camera-lidar modules for highway-assist applications, while ZF Friedrichshafen AG competes through its braking-system integration capabilities that reduce tier-one procurement complexity.
Advanced Driver Assistance Systems encompass sensor arrays, control units, and actuation mechanisms that perform partial vehicle automation through environmental perception and real-time decision algorithms; these systems typically operate within functional safety classifications up to ASIL-D and rely on fused inputs from radar, camera, and ultrasonic modalities to execute lane-keeping, adaptive speed maintenance, and collision mitigation. Automatic Emergency Braking dominates current OEM fitment rates due to regulatory pressure and insurance cost incentives, while Camera Systems represent the fastest-expanding technology segment as semiconductor costs decline and image-processing algorithms improve nighttime detection accuracy. Fleet Operators constitute an emerging end-user category with distinct procurement patterns favoring subscription-based pricing models that convert capital expenditure into operational budgets.
Brazil's CONTRAN resolutions and Mexico's NOM safety standards, alongside NCAP harmonization efforts, are compelling automakers to pre-fit adaptive cruise control and lane departure warning across vehicle classes rather than offering these as optional packages. ANFAVEA and AMIA industry associations coordinate with regulators to phase in compliance timelines that respect local supply chain readiness. Stakeholders must monitor how Lidar cost curves and domestic semiconductor packaging capabilities reshape technology sourcing decisions across the Andean and Southern Cone production networks.
Market Dynamics
Fleet operators in Brazil and Mexico are converting capital expenditure into operational budgets through subscription-based ADAS procurement, fundamentally altering how sensor-fusion technology reaches commercial vehicle segments.
Growth Catalysts
- CONTRAN Resolution 970:Brazil's mandatory automatic emergency braking requirement for heavy commercial vehicles creates baseline demand for radar and camera modules across OEM assembly lines.
- NCAP alignment pressure:Latin American New Car Assessment Program protocols are compelling automakers to standardize lane departure warning and adaptive cruise control rather than offering these as optional packages.
- Bajío automotive cluster concentration:Mexico's Guanajuato-Querétaro industrial corridor hosts expanding Tier-1 sensor manufacturing, reducing import dependency and shortening supplier lead times.
Market Restraints
- Semiconductor packaging deficit:Limited domestic capability for automotive-grade chip assembly forces reliance on Asian packaging houses, exposing supply chains to shipping volatility.
- Lidar cost structure:Solid-state lidar units remain prohibitively expensive for mass-market vehicle classes, constraining Level 3 deployment to premium segments.
- AMIA compliance timeline friction:Mexico's phased NOM-194 implementation creates uncertainty for OEMs balancing inventory builds against regulatory deadlines.
Strategic Opportunities
- Andean corridor penetration:Colombia and Chile exhibit minimal ADAS fitment rates in commercial fleets, presenting first-mover advantage for subscription-based collision avoidance providers.
- Camera-lidar convergence:Integrated perception modules combining complementary sensor modalities are opening pathways for highway-assist features in mid-price vehicle segments.
- ANFAVEA coordination mechanisms:Brazil's industry association is streamlining homologation pathways for imported sensor systems, reducing time-to-market for foreign technology suppliers.
Industry Challenges
- Functional safety engineer scarcity:ASIL-D certification expertise concentrates in São Paulo and Mexico City, creating recruitment bottlenecks for suppliers locating in secondary industrial zones.
- Legacy vehicle integration complexity:Retrofitting camera and radar systems onto existing fleet vehicles requires custom mounting solutions and calibration protocols that erode margin structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America ADAS Market |
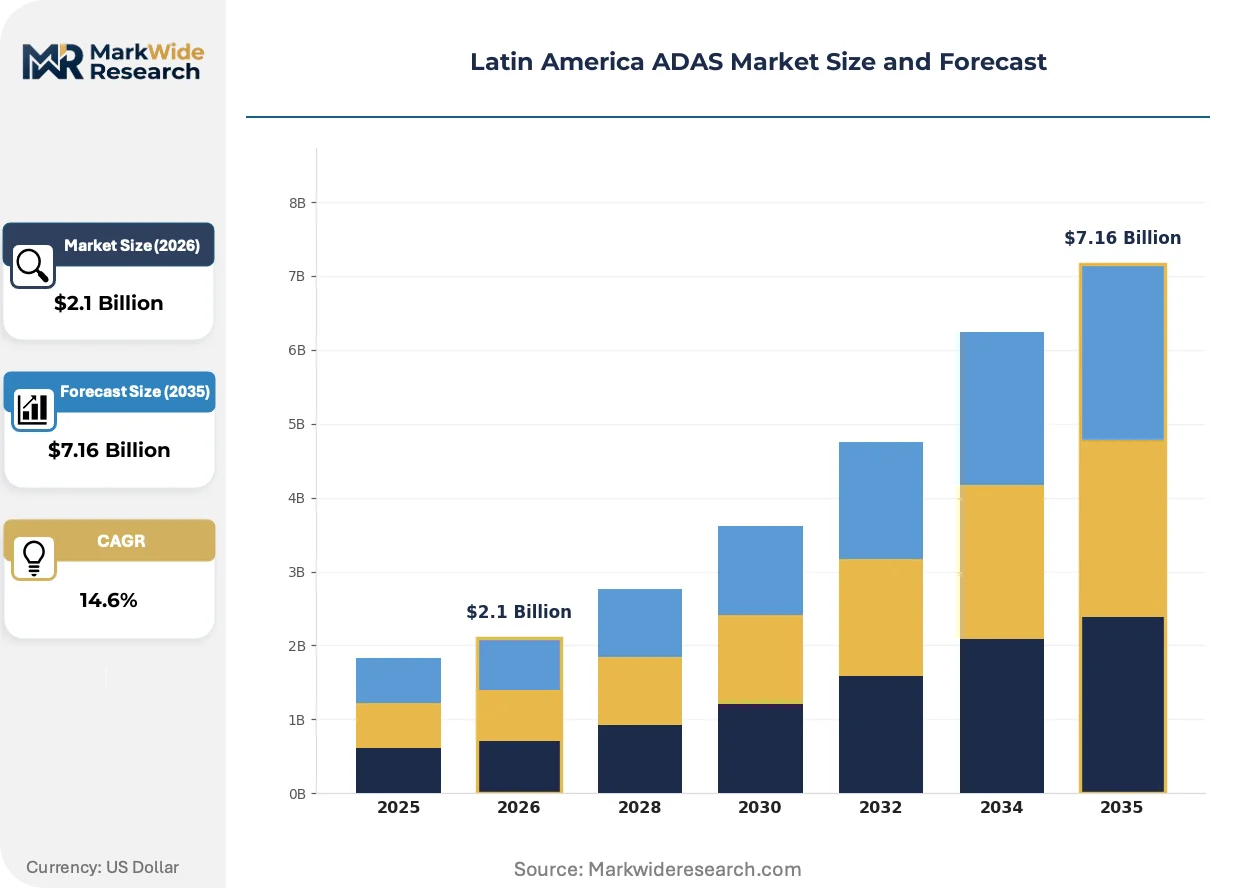
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $7.16 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adaptive Cruise Control, Lane Departure Warning, Automatic Emergency Braking, Parking Assistance Technology: Radar, Lidar, Camera Systems, Ultrasonic Sensors End User: OEMs, Aftermarket Providers, Fleet Operators, Private Vehicle Owners Pricing Model: Subscription-Based, One-Time Purchase, Lease, Pay-Per-Use |
| Companies Covered | Autoliv AB, Magna International, Bosch Group, Ford Motor Company, Delphi Automotive, Continental AG, DENSO Corporation, General Motors, ZF Friedrichshafen AG, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America ADAS Market Shifts & Advancements
Sensor modality preferences are bifurcating as semiconductor cost curves and algorithmic advances reshape what perception stacks OEMs specify for different vehicle price tiers.
Camera-centric perception stacks are supplanting radar-dominant configurations in entry-level and mid-market vehicles. Brazilian and Mexican OEMs are specifying single-camera automatic emergency braking systems for compact car platforms to meet CONTRAN mandates at lowest bill-of-materials cost. This shift is compressing Tier-1 radar supplier margins and redirecting engineering resources toward image-processing algorithm development.
CONTRAN Resolution 970 and Mexico's NOM-194 safety standards are synchronizing compliance timelines across the region's two largest automotive markets. Automakers serving both countries are consolidating platform engineering to single specification sets, eliminating variant complexity. Heavy commercial vehicle segments face the steepest adaptation requirements as these regulations mandate fitment ahead of passenger car schedules.
Fleet procurement departments are unbundling ADAS hardware from maintenance contracts and negotiating direct sensor subscriptions with technology providers. Large logistics operators in São Paulo's industrial corridor are bypassing traditional OEM service networks for over-the-air software updates and remote diagnostics. This channel disintermediation is most pronounced in Brazil's long-haul trucking segment where vehicle utilization rates maximize the value of predictive maintenance alerts.
Latin America ADAS Market Segmentation
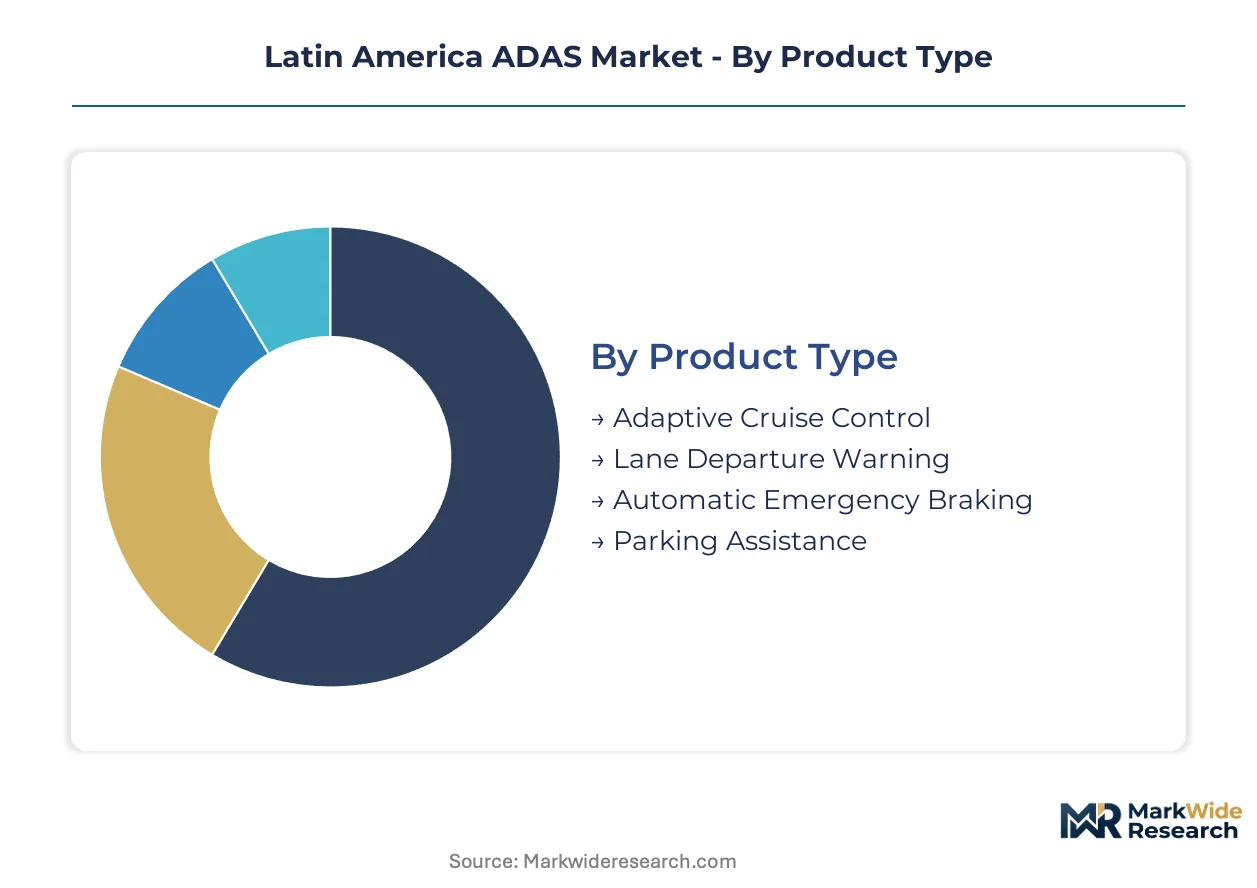
ADAS procurement patterns across Latin America diverge sharply between regulatory-mandated fitments and discretionary technology upgrades. Fleet operators and OEMs specify entirely different sensor configurations, pricing mechanisms, and integration timelines.
Product Type:
Substitution pressure intensifies as camera-based systems displace radar-dominant architectures in cost-sensitive vehicle classes.
- Automatic Emergency Braking:Radar-camera fusion systems execute collision mitigation through object detection algorithms calibrated to CONTRAN Resolution 970 thresholds. Brazilian heavy commercial vehicle assembly lines in São Paulo's industrial corridor anchor regional demand as fleet operators face insurance premium penalties for non-compliance.
- Lane Departure Warning:Single-camera perception stacks identify road markings through edge-detection processing at substantially lower bill-of-materials cost than lidar alternatives. Mexican OEMs serving the Bajío automotive cluster are standardizing this feature across compact car platforms to preempt NCAP alignment requirements.
- Adaptive Cruise Control:Longitudinal speed maintenance through millimeter-wave radar maintains premium positioning in mid-market sedans.
- Parking Assistance:Ultrasonic sensor arrays dominate low-speed maneuvering applications with minimal computational overhead.
Automatic Emergency Braking retains volume leadership; Lane Departure Warning holds the steepest expansion curve.
Technology:
Cost tier stratification determines which sensor modalities OEMs specify for different vehicle price brackets.
- Camera Systems:Complementary metal-oxide-semiconductor imagers paired with convolutional neural networks enable nighttime pedestrian detection and traffic sign recognition. Semiconductor cost declines are accelerating adoption in Brazil's entry-level vehicle segments previously served by radar-only configurations.
- Radar:Frequency-modulated continuous-wave transmitters provide all-weather velocity measurement and range determination. Long-haul fleet operators in Mexico's Guanajuato-Querétaro corridor specify 77GHz units for highway-assist functionality where camera performance degrades in precipitation.
- Ultrasonic Sensors:Short-range proximity detection for parking and low-speed collision avoidance.
- Lidar:Solid-state units remain confined to premium segments due to packaging cost constraints.
Camera Systems command the broadest addressable market; Radar maintains defensive positioning in commercial vehicle specifications.
End User:
Customer type segmentation reveals divergent procurement rhythms between capital-intensive OEM programs and operational-budget fleet conversions.
- Fleet Operators:Subscription-based ADAS procurement converts sensor hardware into monthly operational expenditures. São Paulo-based logistics conglomerates negotiate direct contracts with Tier-1 suppliers for over-the-air software updates, bypassing traditional OEM service networks entirely.
- OEMs:Original equipment manufacturers integrate sensor fusion modules at assembly for new vehicle platforms. Pre-fitting requirements under Brazil's CONTRAN resolutions and Mexico's NOM-194 standards are eliminating optional-package economics across both passenger and commercial vehicle lines.
- Aftermarket Providers:Retrofit specialists face margin compression from custom mounting and calibration complexity.
- Private Vehicle Owners:Discretionary upgrade demand concentrates in premium segments with limited mass-market penetration.
Fleet Operators are gaining share fastest in commercial vehicle ADAS deployment; OEMs retain structural control over new vehicle technology integration.
Pricing Model:
Application context determines whether end-users capitalize hardware or expense technology through recurring payments.
- Subscription-Based:Monthly per-vehicle fees bundle sensor hardware, software licensing, and predictive maintenance alerts. Brazil's long-haul trucking segment maximizes utilization rates that justify operational-budget treatment of collision avoidance technology.
- One-Time Purchase:Upfront capital expenditure for sensor modules and installation dominates private vehicle aftermarket transactions.
- Lease:Structured financing aligns payment schedules with fleet replacement cycles.
- Pay-Per-Use:Mileage-indexed billing remains experimental with limited commercial deployment.
Subscription-Based pricing is climbing the fastest in fleet procurement; One-Time Purchase retains dominance in consumer aftermarket channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sensor manufacturing and Tier-1 assembly concentrate in Brazil's São Paulo industrial corridor and Mexico's Bajío automotive cluster, with cross-border supply chains synchronizing around CONTRAN and NOM regulatory timelines. These two markets generate the bulk of regional ADAS hardware demand through fleet operator procurement and OEM pre-fitting mandates.
Brazil
Heavy commercial vehicle fleet operators in São Paulo's industrial corridor drive collision avoidance system procurement to comply with insurance premium penalties and safety mandates. ANFAVEA coordinates homologation pathways that streamline imported sensor system approvals for foreign technology suppliers. The São Paulo-ABC automotive belt hosts expanding radar and camera module assembly operations serving both domestic OEM lines and export programs.
Mexico
The Guanajuato-Querétaro Bajío corridor anchors Tier-1 sensor manufacturing investments that reduce import dependency for North American vehicle platforms. AMIA's phased NOM-194 implementation timeline creates inventory planning complexity for OEMs balancing production builds against regulatory deadlines. Assembly plants in this cluster increasingly specify integrated perception modules for highway-assist features in vehicles destined for US and Canadian markets.
Argentina
Commercial fleet modernization programs in Buenos Aires and Córdoba provinces generate retrofit demand for camera-based driver assistance systems. The country's national automotive regulator maintains alignment with Mercosur safety standards that reference NCAP protocols for new vehicle assessments. Rosario's logistics hub exhibits emerging interest in subscription-based collision avoidance procurement among grain transport operators.
Chile
Mining fleet operators in the Atacama Desert corridor specify ruggedized radar systems for haul truck collision avoidance in low-visibility conditions. The national transportation safety agency enforces commercial vehicle inspection regimes that increasingly reference ADAS functionality. Santiago's metropolitan bus operators pilot lane departure warning retrofits on existing articulated vehicle platforms.
Colombia
Bogotá's urban freight operators face congestion pricing incentives that favor vehicles equipped with automatic emergency braking for insurance rate reductions. The national infrastructure ministry coordinates with Andean corridor trade partners on cross-border vehicle safety standard harmonization. Medellín's automotive assembly zone hosts emerging Tier-2 component sourcing for camera module subassemblies.
Latin America ADAS Market Competitive Landscape
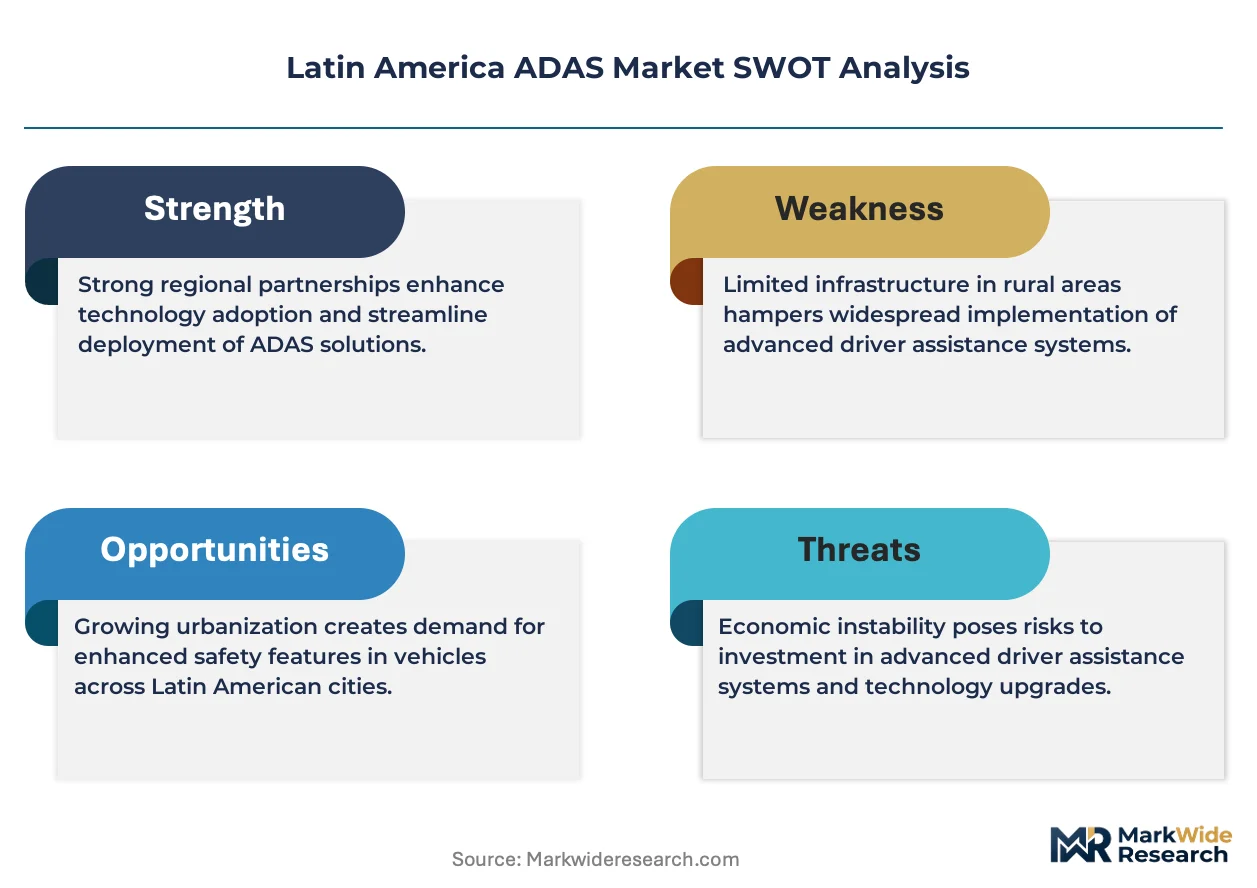
Concentration sits with diversified automotive Tier-1 suppliers that leverage existing OEM relationships and braking-system integration capabilities. The competitive structure tiers into radar manufacturing specialists, camera-lidar integrators, and braking-system fusion providers. Consolidation pressure favors suppliers with in-house semiconductor packaging partnerships and functional safety certification expertise. Strategic moves center on sensor modality convergence and geographic expansion into Andean markets with minimal incumbent presence.
Among European-headquartered diversified suppliers, Bosch Group, Continental AG, and ZF Friedrichshafen AG occupy positions across the sensor fusion and actuation technology stack. Bosch exemplifies the radar manufacturing archetype with regional production footprints, while Continental represents integrated camera-lidar module specialization. ZF anchors the braking-system integration tier where control unit and hydraulic actuator bundling reduces procurement complexity for OEM assembly plants.
| Leading Market Players |
|---|
| Autoliv AB |
| Magna International |
| Bosch Group |
| Ford Motor Company |
| Delphi Automotive |
| Continental AG |
| DENSO Corporation |
| General Motors |
| ZF Friedrichshafen AG |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day sensor module lead times concentrate pricing power with Tier-1 suppliers anchoring Brazil's São Paulo corridor and Mexico's Bajío cluster, while fleet operators leverage subscription contracts to compress upfront capital requirements into operational budgets.
Pricing Analysis
CONTRAN Resolution 970 dictates the pricing tier structure across the Latin America ADAS landscape. Three-tier pricing structure across premium, standard, and economy levels separates radar-fusion highway-assist systems from single-camera AEB configurations and ultrasonic parking modules. Price differentiation stems from ASIL-D certification grade and volume scale commitments from OEM assembly lines. Cost compression in camera-centric entry-level tiers is intensifying because Brazilian compact car platforms are eliminating radar content to meet mandates at lowest bill-of-materials. Fleet procurement departments exhibit highest price sensitivity through subscription negotiations, while premium OEM platforms retain lowest sensitivity due to pre-fitted regulatory requirements.
Supply Chain Analysis
Brazil and Mexico anchor Tier-1 sensor module assembly and braking-system integration for the regional automotive industry. China and Taiwan feed semiconductor packaging and CMOS imager supply. The supply chain draws from Asian chip assembly houses for automotive-grade radar transceivers and camera processors. Single-source vulnerability concentrates in 77GHz radar MMIC supply where domestic packaging capability remains limited. Distribution runs through OEM assembly plant procurement with direct Tier-1 contracting increasingly displacing distributor intermediation in fleet subscription channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator consolidation across São Paulo's logistics corridor and Mexico's Guanajuato-Querétaro belt is shifting buyer power toward subscription-based procurement, fragmenting traditional OEM-Tier-1 dyads.
For Market Incumbents: Shield radar manufacturing margins by accelerating backward integration into semiconductor packaging partnerships that reduce dependency on Asian assembly houses. Anchor braking-system bundling contracts with OEM assembly plants in the Bajío corridor to lock out camera-only competitors. Defend against subscription-based channel disintermediation by embedding predictive maintenance software into hardware contracts. For New Entrants and Emerging Players: ANFAVEA's streamlined homologation fast-track enables foreign sensor suppliers to compress time-to-market for imported camera-lidar modules. Target Chile's mining fleet segment with ruggedized radar configurations where incumbent presence remains minimal. Penetrate Colombia's urban freight operators through insurance-rate-reduction value propositions tied to automatic emergency braking retrofits. Pursue direct fleet contracting models that bypass OEM service networks entirely. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because CONTRAN and NOM mandates are structurally embedding ADAS content per vehicle regardless of consumer preference. Acquisition candidates center on Tier-2 camera module subassembly specialists with ANFAVEA homologation pathways and ASIL-D certification capabilities. The signal to watch is Lidar cost curve inflection that would unlock Level 3 deployment into mid-market vehicle segments.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Modality Convergence | Integrated camera-lidar modules open highway-assist penetration in mid-price segments. |
| Subscription Platform Launch | Operational-budget conversion captures fleet procurement departments bypassing OEM channels. |
| Domestic Packaging Partnership | Automotive-grade semiconductor assembly reduces Asian supply chain exposure. |
| Andean Corridor Expansion | First-mover positioning in Chilean mining and Colombian urban freight segments. |
| Functional Safety Certification Investment | ASIL-D expertise scarcity in secondary industrial zones creates recruitment moats. |
Research Methodology
A spread of perspectives from Tier-1 supplier procurement directors, OEM platform engineers, fleet operations managers, and aftermarket retrofit specialists converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through ANFAVEA production statistics, AMIA regulatory filings, and vehicle registration databases. Bottom-up sensor shipment analysis triangulated against top-down OEM platform content estimates.
Segmentation dimensions modeled include vehicle class, sensor modality architecture, end-user procurement type, and regional regulatory cluster across the analysis window. CAGRs derived from unit shipment trajectories weighted by average content per vehicle and pricing tier mix. Forecast inputs incorporated CONTRAN and NOM implementation timelines, semiconductor cost curve assumptions, and fleet replacement cycle patterns.
Decision-makers should treat outputs as directional under sustained regulatory enforcement and stable logistics cost assumptions; material deviation in tariff exposure or domestic packaging capability buildout would warrant model refresh. Recalibration cycles align with material shifts in safety mandate implementation schedules and Lidar cost structure inflections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Predictive Automobile Technology Market
Autonomous Vehicles
Connected Vehicle Technology Market
Autonomous Vehicles
North America Autonomous Navigation Market
Autonomous Vehicles
In-Vehicle AI Robot Market
Autonomous Vehicles
Automotive Predictive Technology Market
Autonomous Vehicles
HD Map for Autonomous Vehicle Market
Autonomous Vehicles
Driverless Taxi Market
Autonomous Vehicles
Autonomous Emergency Braking (AEB) Market
Autonomous Vehicles
Adaptive Cruise Control (ACC) System Market
Autonomous Vehicles
Automotive Lidar Market
Autonomous Vehicles
Semi Autonomous and Autonomous Vehicles Market
Autonomous Vehicles
Driverless Cab Service Market
Autonomous Vehicles
Autonomous Intelligent Vehicle Market
Autonomous Vehicles
Automated Valet Parking (AVP) Market
Autonomous Vehicles
Australia Autonomous Navigation Market
Autonomous Vehicles
China Autonomous Navigation Market