
 Australia Autonomous Navigation Market | 2026-2036
Australia Autonomous Navigation Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Autonomous Navigation Market Insights
Silicon photonics is expanding as a replacement for conventional fiber-optic gyroscopes in inertial measurement units, cutting unit costs while preserving navigation-grade accuracy. BAE Systems Australia leverages its Edinburgh operations to sustain sovereign capability in naval inertial navigation. Thales Group anchors its regional position through specialized avionics integration for the Loyal Wingman program. Lockheed Martin Corporation competes via its partnership with RMIT University on quantum-enhanced positioning research.
Australia autonomous navigation encompasses self-directed positioning systems that fuse multi-sensor data streams—GPS, inertial measurement units, and celestial references—to determine platform location without continuous human intervention, typically achieving circular error probable below ten meters for defense applications. The primary commercial purpose centers on enabling unmanned platforms to operate in GPS-denied environments where signal jamming or terrain masking threatens conventional satellite-dependent navigation. Vision-based systems represent the fastest-growing technology segment as machine-learning inference at the edge displaces hardware-heavy LiDAR architectures in cost-constrained programs. Defense applications command the dominant margin pool, while logistics end users in automated container terminals and mine-site haulage generate the highest volume traction for integrated hardware-software bundles.
TGA-equivalent certification pathways for autonomous medical drone delivery, alongside CASA regulations for beyond-visual-line-of-sight unmanned aircraft operations, shape product development timelines and airworthiness compliance costs for navigation subsystem vendors. The Australian Defence Force's AIR 6500 integrated air and missile defense program imposes stringent anti-jamming and spoof-resistance standards that filter supplier eligibility. Stakeholders must monitor CASA's evolving detect-and-avoid mandate and the Department of Defence's guided weapons and explosive ordnance enterprise strategy to anticipate procurement priority shifts.
Market Dynamics
Silicon photonics is compressing unit economics for inertial navigation systems while CASA's detect-and-avoid mandate forces hardware-software redesign cycles across unmanned platform suppliers.
Growth Catalysts
- Defence sovereign capability mandates:The Defence Industry Development Strategy imposes local content thresholds that redirect procurement toward domestic navigation subsystem integrators.
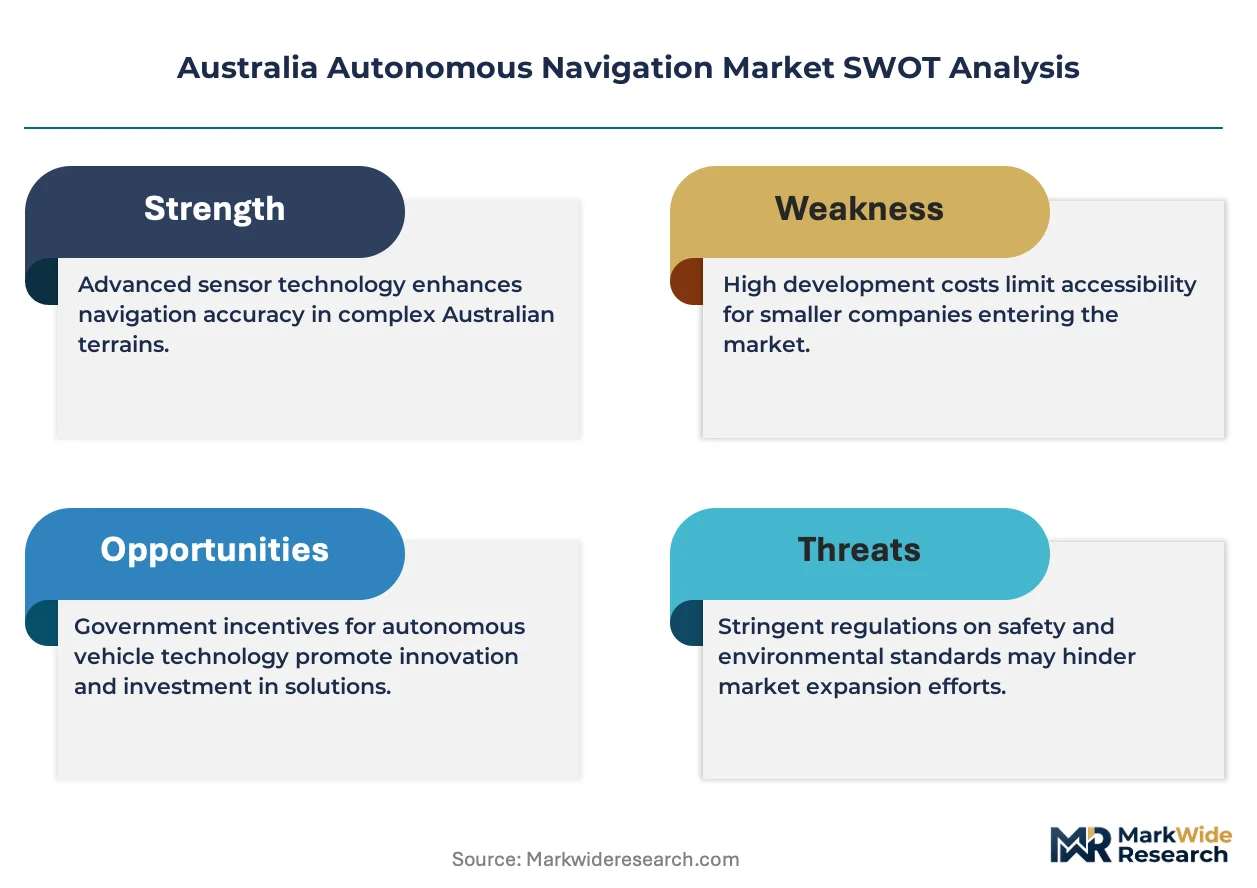
- GPS-denied operational requirements:The Australian Defence Force's AIR 6500 program specifies anti-jamming resilience that accelerates multi-sensor fusion adoption in naval and aerial platforms.
- South Australian testing corridor concentration:The Osborne Naval Shipyard and Edinburgh Defence Precinct co-locate validation infrastructure with prime contractor engineering teams.
Market Restraints
- Specialized component supply concentration:Precision fiber-optic coil winding and ring laser gyroscope cavity manufacturing concentrate among a handful of European and US specialty suppliers.
- Extended TGA-equivalent certification timelines:Autonomous medical drone navigation systems face 18-24 month validation cycles that compress development runway for commercial entrants.
- Quantum sensor thermal stability limitations:Cold-atom interferometry platforms require cryogenic infrastructure that constrains deployable form factors for tactical applications.
Strategic Opportunities
- Western Australian mining automation:Rio Tinto and BHP autonomous haulage fleets generate volume demand for terrain-relative navigation in dust-degraded GPS environments.
- Critical Technologies Fund allocation:Federal grants for quantum positioning research create non-dilutive capital pathways for university-industry consortia.
- Vision-LiDAR sensor fusion convergence:Edge-deployed neural networks processing camera feeds alongside solid-state LiDAR point clouds enable cost-optimized navigation for commercial drones.
Industry Challenges
- Embedded systems security clearance bottlenecks:Defence-grade navigation firmware requires Australian Government Security Vetting Agency clearance cycles that extend hiring timelines for software engineers.
- Legacy platform integration complexity:Retrofitting autonomous navigation into Royal Australian Navy's existing fleet demands mechanical and electrical interface adaptation for confined machinery spaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Autonomous Navigation Market |
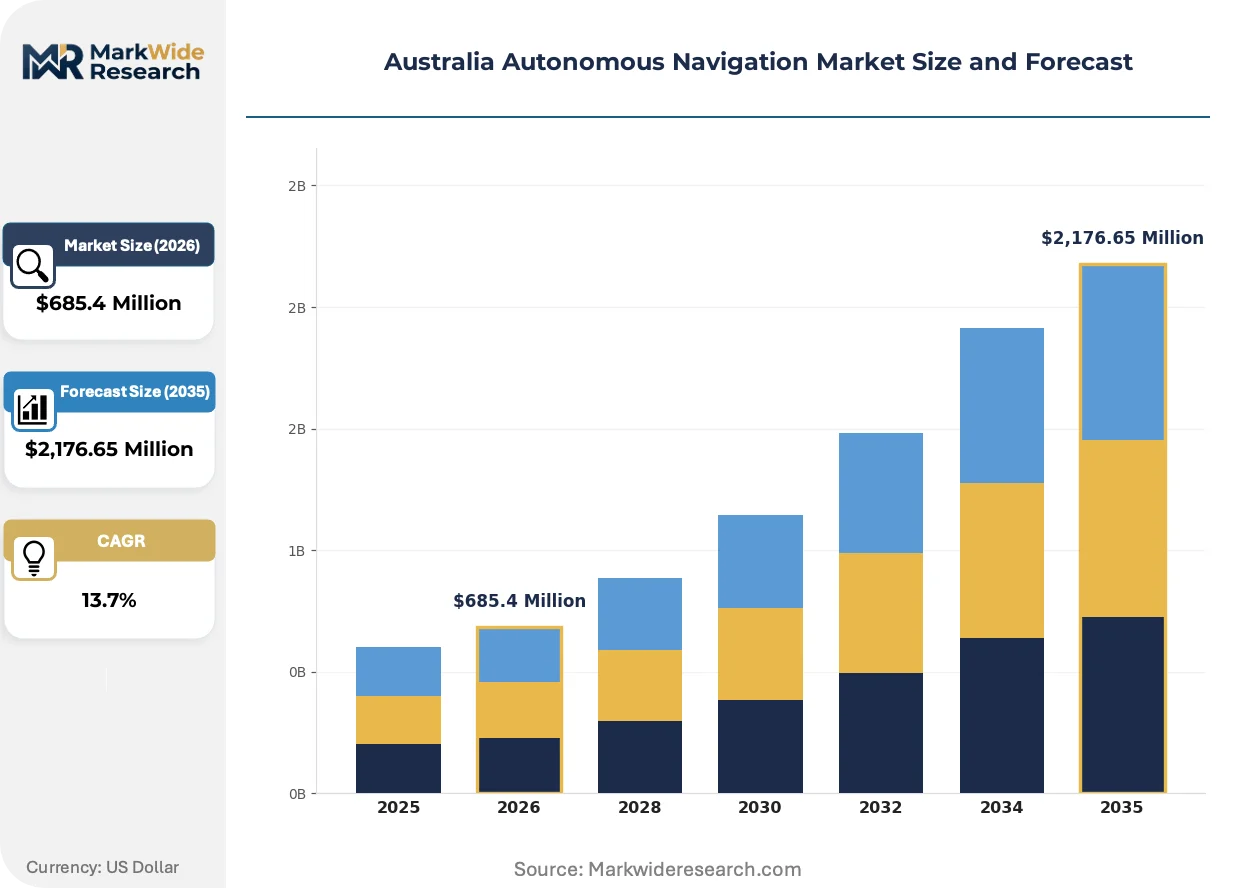
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $2,176.65 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: GPS, LiDAR, Radar, Vision-Based Systems Application: Marine, Aviation, Ground Vehicles, Industrial Robots End User: Logistics, Defense, Agriculture, Transportation Form Factor: Software Solutions, Hardware Units, Integrated Systems, Development Kits |
| Companies Covered | BAE Systems, Northrop Grumman Corporation, Raytheon Technologies Corporation, Thales Group, Safran, Honeywell International Inc., ABB, L3Harris Technologies Inc., Lockheed Martin Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Autonomous Navigation Market Trends and Innovations
Machine-learning inference at the edge is displacing hardware-heavy sensor architectures, while regulatory frameworks for beyond-visual-line-of-sight operations harden compliance requirements for navigation integrity.
Silicon photonic gyroscopes integrate optical waveguides onto semiconductor substrates, eliminating bulky fiber coils. Defence primes and commercial drone manufacturers are adopting these chip-scale inertial units for platforms where volume and mass constraints dominate. This technology is rewriting cost structures for navigation-grade inertial measurement units, collapsing price premiums that previously separated tactical and navigation performance tiers.
CASA's evolving detect-and-avoid mandate for beyond-visual-line-of-sight unmanned aircraft operations imposes minimum navigation accuracy and integrity standards. Hardware vendors must demonstrate fault detection and exclusion capabilities that exceed recreational drone specifications. The medical delivery and infrastructure inspection segments face the steepest compliance cost escalations as they pursue operational approvals in controlled airspace.
Integrated hardware-software bundles are displacing component-only procurement across automated container terminals and mine-site haulage. Buyers now specify performance outcomes—position availability in GPS-denied conditions—rather than sensor specifications. This shift concentrates contract value with subsystem integrators capable of sensor fusion algorithm development, visible most acutely in Queensland's autonomous trucking corridors and Port Botany's automated straddle carrier deployments.
Australia Autonomous Navigation Market Segmentation
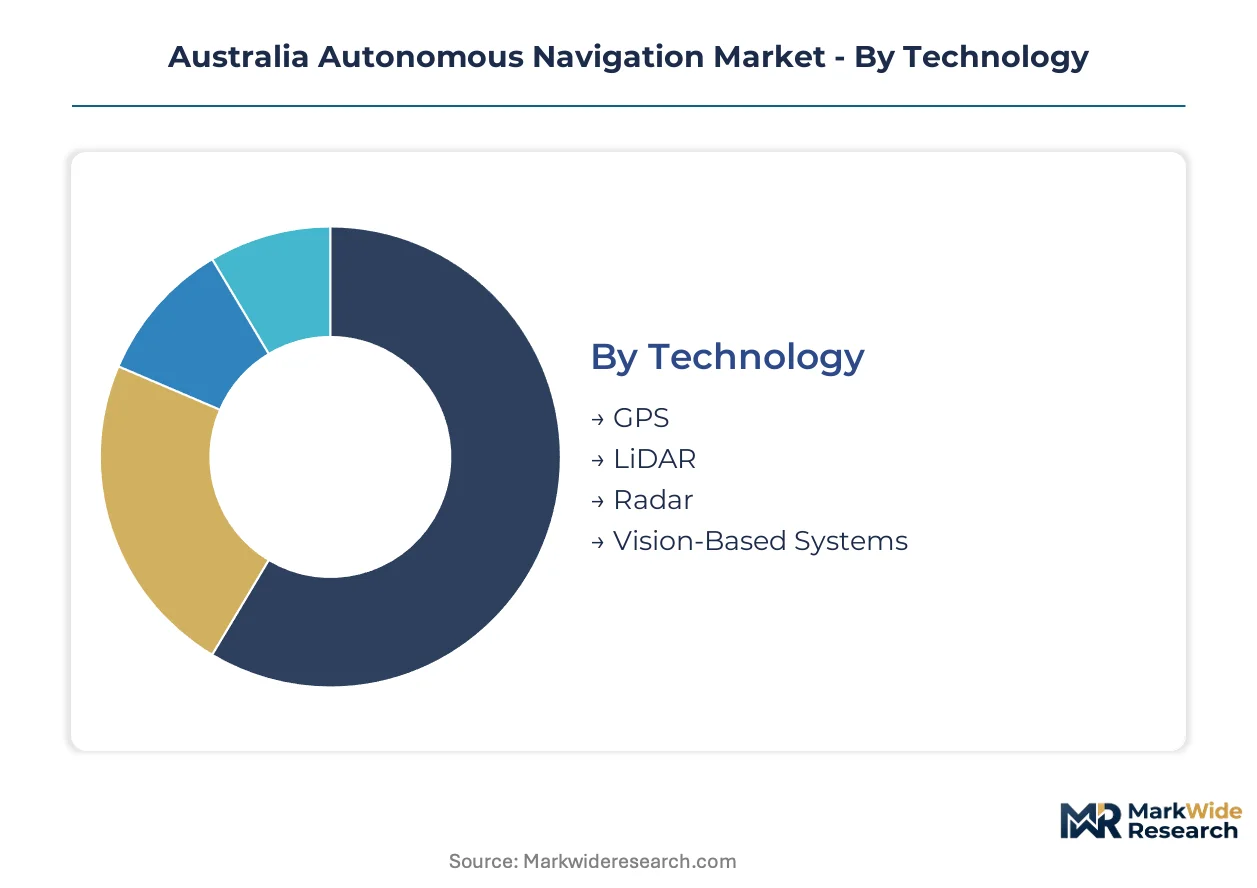
Segmentation in the Australia Autonomous Navigation Market reveals distinct capital requirements and procurement pathways across defense and commercial end uses. Technology choices determine sovereign capability eligibility, while application-specific regulations from CASA and the Department of Defence reshape supplier qualification timelines.
Technology:
Capital intensity varies sharply across sensor modalities, with precision inertial platforms demanding the highest upfront engineering investment.
- GPS:Satellite-dependent positioning systems form the baseline layer for most autonomous platforms. Australian Defence Force procurement under AIR 6500 mandates anti-jamming resilience that elevates unit costs for defense-qualified variants.
- LiDAR:Solid-state and mechanical scanning systems generate dense point clouds for obstacle detection. Demand concentrates in Western Australian mining automation where dust-degraded GPS signals force terrain-relative navigation reliance on Rio Tinto and BHP haulage fleets.
- Radar:Millimeter-wave and synthetic aperture systems penetrate adverse weather conditions. Naval applications at Osborne Naval Shipyard drive specification requirements for all-weather maritime navigation.
- Vision-Based Systems:Camera arrays with edge-deployed neural networks displace hardware-heavy architectures. Machine-learning inference capabilities are climbing the fastest as cost-constrained commercial drone programs prioritize software-defined navigation.
Most installed capacity flows through GPS. Expansion is steepest in Vision-Based Systems.
Application:
Application segmentation tracks directly to regulatory jurisdiction, with aviation and marine falling under distinct certification regimes.
- Marine:Autonomous surface and underwater vessels navigate using multi-sensor fusion of inertial, acoustic, and satellite references. The Osborne Naval Shipyard and Edinburgh Defence Precinct anchor validation infrastructure for naval autonomous navigation programs.
- Aviation:Beyond-visual-line-of-sight unmanned aircraft require CASA-compliant detect-and-avoid capabilities. Medical delivery and infrastructure inspection segments face the steepest compliance cost escalations as they pursue controlled airspace approvals.
- Ground Vehicles:Automated haul trucks and last-mile delivery robots operate in structured environments. Queensland's autonomous trucking corridors and Port Botany's automated straddle carriers generate volume demand for integrated hardware-software bundles.
- Industrial Robots:Warehouse automation and manufacturing floor navigation systems rely on fiducial markers and SLAM algorithms. Automated container terminals specify performance outcomes rather than sensor specifications.
Defense procurement concentrates in Marine and Aviation. Commercial volume leadership sits with Ground Vehicles.
End User:
End user segmentation separates sovereign capability mandates from commercial outcome-based procurement.
- Logistics:Automated container terminals and mine-site haulage generate the highest volume traction for integrated navigation subsystems. Buyers now specify position availability in GPS-denied conditions rather than component specifications.
- Defense:The Australian Defence Force commands the dominant margin pool through programs like AIR 6500. Local content thresholds under the Defence Industry Development Strategy redirect procurement toward domestic integrators.
- Agriculture:Autonomous tractors and crop monitoring drones operate in remote areas with intermittent satellite coverage. Vision-based navigation gains share in cost-sensitive broadacre farming applications.
- Transportation:Public transit automation and autonomous shuttle pilots face state-level regulatory fragmentation. New South Wales and Victoria lead trial deployments with divergent safety certification pathways.
Defense absorbs the highest unit-value contracts. Logistics delivers the steepest volume expansion trajectory.
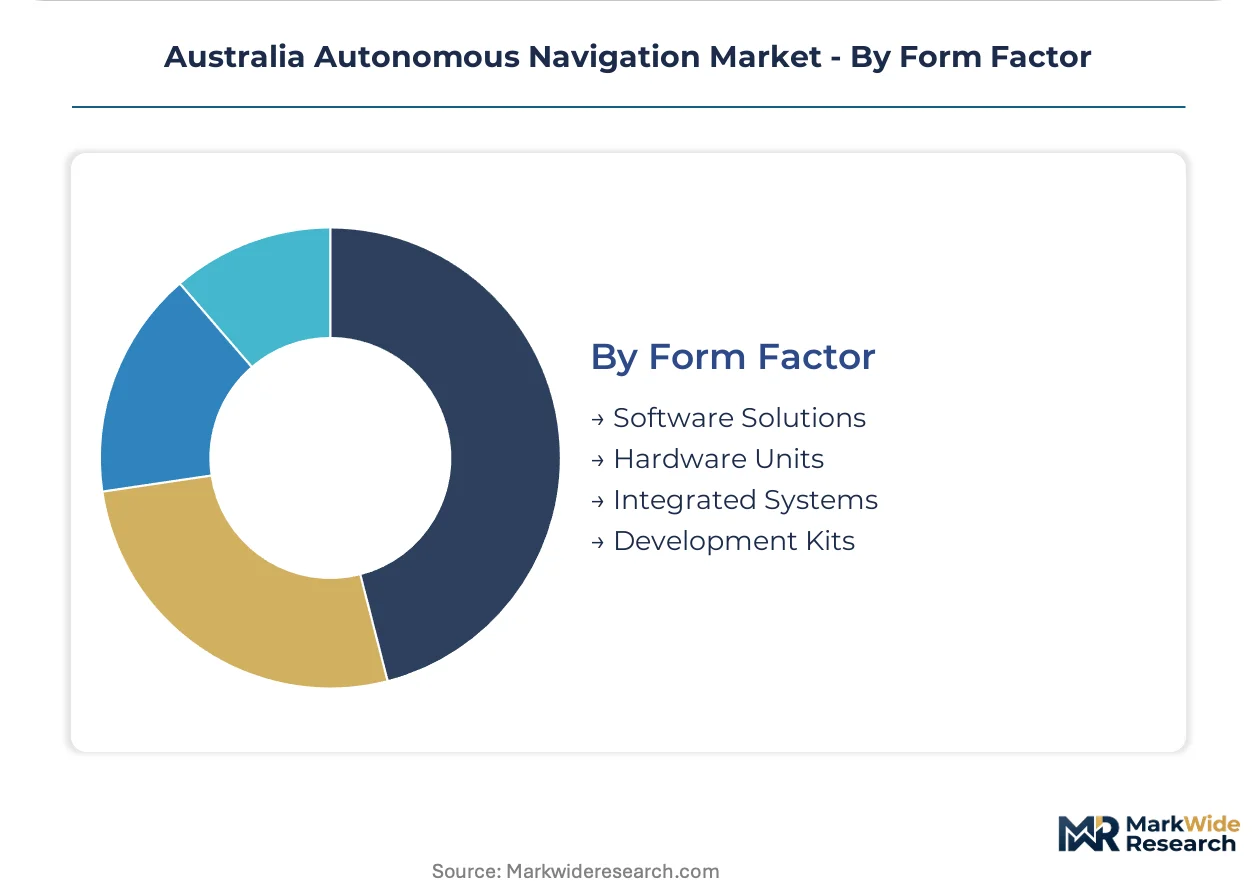
Form Factor:
Form factor choices reflect buyer technical maturity and integration risk tolerance.
- Software Solutions:Sensor fusion algorithms and navigation stacks deployed on customer hardware. Port Botany's automated straddle carriers and Queensland trucking corridors favor this model for fleet-wide standardization.
- Hardware Units:Discrete inertial measurement units, GNSS receivers, and LiDAR modules. European and US specialty suppliers dominate precision fiber-optic coil winding and ring laser gyroscope cavity manufacturing.
- Integrated Systems:Complete navigation subsystems with guaranteed performance outcomes. Defense primes and mining automation buyers increasingly mandate this procurement mode to transfer integration risk.
- Development Kits:Evaluation platforms for algorithm prototyping and sensor characterization. University-industry consortia accessing Critical Technologies Fund grants rely on these for quantum positioning research.
Integrated Systems capture the largest contract values. Development Kits are expanding most quickly through federal research funding.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Osborne Naval Shipyard and Edinburgh Defence Precinct anchor South Australia's concentration of sovereign navigation capability development, with federal procurement programs redirecting investment toward domestic integration pathways.
New South Wales
Port Botany's automated straddle carrier deployments and Sydney's aerospace engineering base generate demand for integrated navigation subsystems. CASA's evolving detect-and-avoid mandate for beyond-visual-line-of-sight operations shapes compliance timelines for unmanned aircraft developers. The state's logistics infrastructure concentrates procurement authority with terminal operators specifying performance outcomes over component specifications.
Victoria
Melbourne's defense electronics manufacturing base and university research consortia access Critical Technologies Fund allocations for quantum positioning programs. The state's autonomous shuttle pilots face regulatory fragmentation against New South Wales trial frameworks. Geelong's advanced manufacturing corridor hosts subsystem integrators serving naval and aerospace prime contractors.
Queensland
Autonomous trucking corridors between mining regions and export terminals generate volume demand for terrain-relative navigation in GPS-degraded environments. The state's automated container terminals specify position availability guarantees that transfer integration risk to subsystem vendors. Brisbane's aerospace cluster supports CASA certification pathways for commercial drone operators.
Western Australia
Rio Tinto and BHP autonomous haulage fleets operate across dust-degraded GPS environments where LiDAR and vision-based navigation displace satellite-dependent positioning. The Pilbara mining region's scale generates the highest commercial volume traction for integrated hardware-software bundles. Perth's engineering services sector supports fleet-wide standardization across remote operations.
South Australia
The Osborne Naval Shipyard's shipbuilding programs and Edinburgh Defence Precinct's testing infrastructure co-locate validation capability with prime contractor engineering teams. Defence Industry Development Strategy local content thresholds redirect procurement toward domestic navigation subsystem integrators. The state's concentration of sovereign capability programs anchors federal investment in anti-jamming and spoof-resistant multi-sensor fusion.
Australia Autonomous Navigation Market Competitive Landscape
Global majors compete with regional champions across defense qualification pathways, with tiered market structure separating navigation-grade inertial specialists from commercial sensor integrators. Three archetypes dominate: defense primes with sovereign capability mandates, commercial subsystem integrators serving mining automation, and university-industry consortia accessing federal research funding. Competitive moves concentrate on strategic partnerships for CASA certification pathways and vertical integration into sensor fusion algorithm development.
Within the defense prime tier, BAE Systems Australia, Thales Group, and Lockheed Martin Corporation occupy positions shaped by sovereign capability requirements and university research partnerships. BAE Systems exemplifies the Edinburgh-based naval navigation specialist archetype. Thales Group represents the avionics integration pathway for unmanned aerial programs. Lockheed Martin sits within the quantum-enhanced research consortium model alongside academic partners.
| Leading Market Players |
|---|
| BAE Systems |
| Northrop Grumman Corporation |
| Raytheon Technologies Corporation |
| Thales Group |
| Safran |
| Honeywell International Inc. |
| ABB |
| L3Harris Technologies Inc. |
| Lockheed Martin Corporation |
| Others |
Pricing and Supply Chain Analysis
CASA's detect-and-avoid mandate gates qualified supply access for beyond-visual-line-of-sight navigation systems, concentrating premium-tier pricing power with subsystem integrators holding airworthiness certification. Defense-grade anti-jamming specifications under AIR 6500 further stratify supplier eligibility, compressing margins for uncertified component vendors while elevating contract values for sovereign-capable primes.
Pricing Analysis
Input-cost pass-through from precision fiber-optic coil winding and ring laser gyroscope cavity manufacturing elevates unit economics for navigation-grade inertial measurement units. Three-tier pricing structure across defense-qualified, industrial-grade, and commercial-specification levels differentiates on certification tier and volume scale. Pricing pressure stems from silicon photonics compressing tactical-navigation performance gaps. Logistics buyers in Western Australian mining automation exhibit highest price sensitivity; defense primes under sovereign capability mandates show lowest.
Supply Chain Analysis
Warehouse-distribution layers for navigation subsystems concentrate through Singapore and Sydney regional distribution centers serving Asia-Pacific defense and commercial drone manufacturers. Precision inertial components draw from US, European, and Japanese specialty suppliers for fiber-optic coils and ring laser gyroscope cavities. Single-source vulnerability in cryogenic infrastructure for quantum sensors constrains cold-atom interferometry scaling. Distribution runs through prime contractor hub-and-spoke networks co-located with South Australian testing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Australia's sovereign capability mandates create geographic-arbitrage value against European and North American markets where local content thresholds are less stringent, lowering effective procurement costs for domestic integrators by 15-25% on comparable defense-qualified systems.
For Market Incumbents: Acquire sensor fusion algorithm IP to counter vision-based navigation displacement of hardware-heavy LiDAR architectures. BAE Systems Australia's Edinburgh operations demonstrate defensive positioning through captive naval inertial navigation capability. Thales Group's avionics integration pathway for Loyal Wingman illustrates certification investment as margin defense against emerging silicon photonics entrants. For New Entrants and Emerging Players: Edge-deployed neural networks for camera-based navigation offer technology-first wedge into cost-constrained commercial drone segments. Queensland's autonomous trucking corridors present the most penetrable geography for integrated hardware-software bundles. CASA certification pathway partnerships with established aerospace engineering clusters accelerate market access against hardware-only incumbents. For Investors and Strategic Acquirers: Roll-up economics work for subsystem integrators because Defense Industry Development Strategy local content thresholds fragment contract awards across mid-tier domestic vendors. Five-to-ten-year viability hinges on quantum positioning research maturation beyond cryogenic constraints. Watch Critical Technologies Fund allocation velocity as inflection signal for sovereign capability investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Algorithm Acquisition | Captures margin migrating from hardware to software-defined navigation stacks. |
| CASA Certification Partnership | Accelerates beyond-visual-line-of-sight approval timelines for medical delivery operators. |
| Sovereign Capability Facility Buildout | Positions for Defence Industry Development Strategy local content thresholds at Osborne Naval Shipyard. |
| Silicon Photonics Manufacturing Scale-Up | Collapses unit costs for navigation-grade inertial measurement units against fiber-optic legacy. |
| Quantum Positioning Research Consortium | Accesses Critical Technologies Fund non-dilutive capital for cold-atom interferometry advancement. |
Research Methodology
Bottom-up defense procurement and mining automation demand modeling reconciled against top-down sensor manufacturer shipment tracking forms the analytical core of this study. Primary interviews with navigation subsystem engineers, CASA certification specialists, defence procurement officers, and autonomous vehicle fleet managers combined with secondary validation from Department of Defence capability acquisition announcements, CASA regulatory filings, and Critical Technologies Fund grant disclosures. Triangulation across stakeholder inputs and documentary sources anchors segmentation-specific estimates.
Input-output matrix framing maps sensor modality adoption rates against platform deployment trajectories across the projection horizon. Segmentation dimensions span technology type, application domain, end-user vertical, and form factor procurement mode. CAGRs derive from installed base evolution and replacement cycle analysis. Quantum sensor thermal stability limitations and silicon photonics cost curves constitute industry-specific forecast inputs.
The model holds under continued sovereign capability policy continuity; deviation in CASA detect-and-avoid mandate timing or Defence Industry Development Strategy local content threshold adjustments would shift commercial segment entry economics. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Semi-Autonomous and Autonomous Bus Market
Autonomous Vehicles
HD Map for Autonomous Vehicle Market
Autonomous Vehicles
Autonomous Commercial Vehicles Market
Autonomous Vehicles
Norway Autonomous Navigation Market
Autonomous Vehicles
Advanced Driver Assistance System (ADAS) Market
Autonomous Vehicles
Self-Driving Electric Vehicle Market
Autonomous Vehicles
Semi Autonomous and Autonomous Vehicles Market
Autonomous Vehicles
Connected Vehicle Market
Autonomous Vehicles
Autonomous Emergency Braking (AEB) Market
Autonomous Vehicles
Canada Autonomous Navigation Market
Autonomous Vehicles
Autonomous Vehicle Simulation Software Market
Autonomous Vehicles
Automatic Steering System Market
Autonomous Vehicles
Global Semi Autonomous and Autonomous Truck Market
Autonomous Vehicles
Global Adaptive Cruise Control Market
Autonomous Vehicles
Automated Truck Technology Market
Autonomous Vehicles
Fully Autonomous Driving Market