
 North America Autonomous Navigation Market | 2026-2036
North America Autonomous Navigation Market Size, Share, and Industry Trends Forecast 2026-2036
North America Autonomous Navigation Market Analytics
A widening capital-intensity gap between sensor-suite developers and platform integrators is reorganizing competitive tiers across the North America Autonomous Navigation Market. Raytheon Technologies Corporation leverages its defense electronics heritage to dominate military-grade LIDAR and radar integration for autonomous platforms. Waymo LLC anchors commercial autonomous vehicle navigation through sustained investment in computer vision and mapping infrastructure.
Autonomous navigation encompasses self-directed positioning and path-planning systems that fuse GPS, LIDAR, computer vision, and radar inputs to enable operation without continuous human intervention, typically achieving positional accuracy within centimeters for industrial applications. The technology serves defense surveillance, agricultural automation, logistics routing, and marine surveying by replacing manual piloting with algorithmic decision loops. Automated vehicles command the largest product-type revenue pool due to automotive OEM procurement scale, while marine vessels represent the fastest-growing segment driven by offshore energy and naval unmanned surface vessel programs. Defense end users capture premium pricing for hardened systems, whereas logistics applications expand volume through warehouse robotics and last-mile delivery drones.
The FAA governs commercial unmanned aircraft system operations and beyond-visual-line-of-sight waivers, directly constraining drone delivery scalability across US airspace. Transport Canada and the Canadian Coast Guard shape maritime autonomous vessel standards for Arctic passage and coastal surveillance, while the Department of Defense mandates MIL-STD interoperability for defense contractors supplying autonomous platforms. Stakeholders must monitor evolving certification timelines and cross-border regulatory harmonization to align product roadmaps with operable domains.
Market Dynamics
Defense procurement from the Department of Defense is reorganizing supplier tiers across the North America Autonomous Navigation Market, concentrating platform integration contracts among firms with MIL-STD certification while fragmenting sensor-component supply.
Growth Catalysts
- FAA Beyond-Visual-Line-of-Sight Waivers:Expanding commercial drone operations across logistics and agricultural survey applications accelerates platform deployment timelines for autonomous aerial systems.
- Offshore Energy Sector Demand:Unmanned surface vessels for subsea inspection and platform maintenance drive marine autonomous navigation procurement from Gulf Coast operators.
- Arctic Passage Monitoring:Canadian Coast Guard requirements for autonomous maritime surveillance create dedicated procurement channels for ice-capable navigation systems.
Market Restraints
- LIDAR Component Supply Concentration:Dependence on specialized photonics manufacturers creates input bottlenecks for mid-tier platform integrators lacking backward integration into sensor production.
- Cross-Border Certification Friction:Divergent Transport Canada and FAA unmanned aircraft standards force redundant compliance investments for vendors serving both US and Canadian operators.
- GPS Denial Vulnerability:Military-grade autonomous platforms require alternative positioning infrastructure, elevating system cost and technical complexity for defense contractors.
Strategic Opportunities
- Canadian Arctic Sovereignty Programs:Federal investment in autonomous maritime patrol creates dedicated demand for ice-hardened navigation systems with extended operational endurance.
- Agricultural Automation Convergence:Integration of computer vision with precision planting equipment opens autonomous navigation deployment in row-crop operations across the US Midwest.
- Last-Mile Distribution Channel Innovation:Direct-to-fleet sales models bypass traditional automotive dealership networks for autonomous delivery vehicle procurement.
Industry Challenges
- Embedded Systems Engineering Talent Scarcity:Shortage of specialists in real-time sensor fusion algorithms constrains product development velocity for mid-size platform developers.
- MIL-STD Certification Timeline Compression:Extended validation cycles for defense-grade autonomous systems delay revenue recognition and strain working capital for suppliers.
- Legacy Fleet Retrofit Integration Complexity:Agricultural and marine operators face technical barriers incorporating autonomous navigation into existing equipment without full platform replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Autonomous Navigation Market |
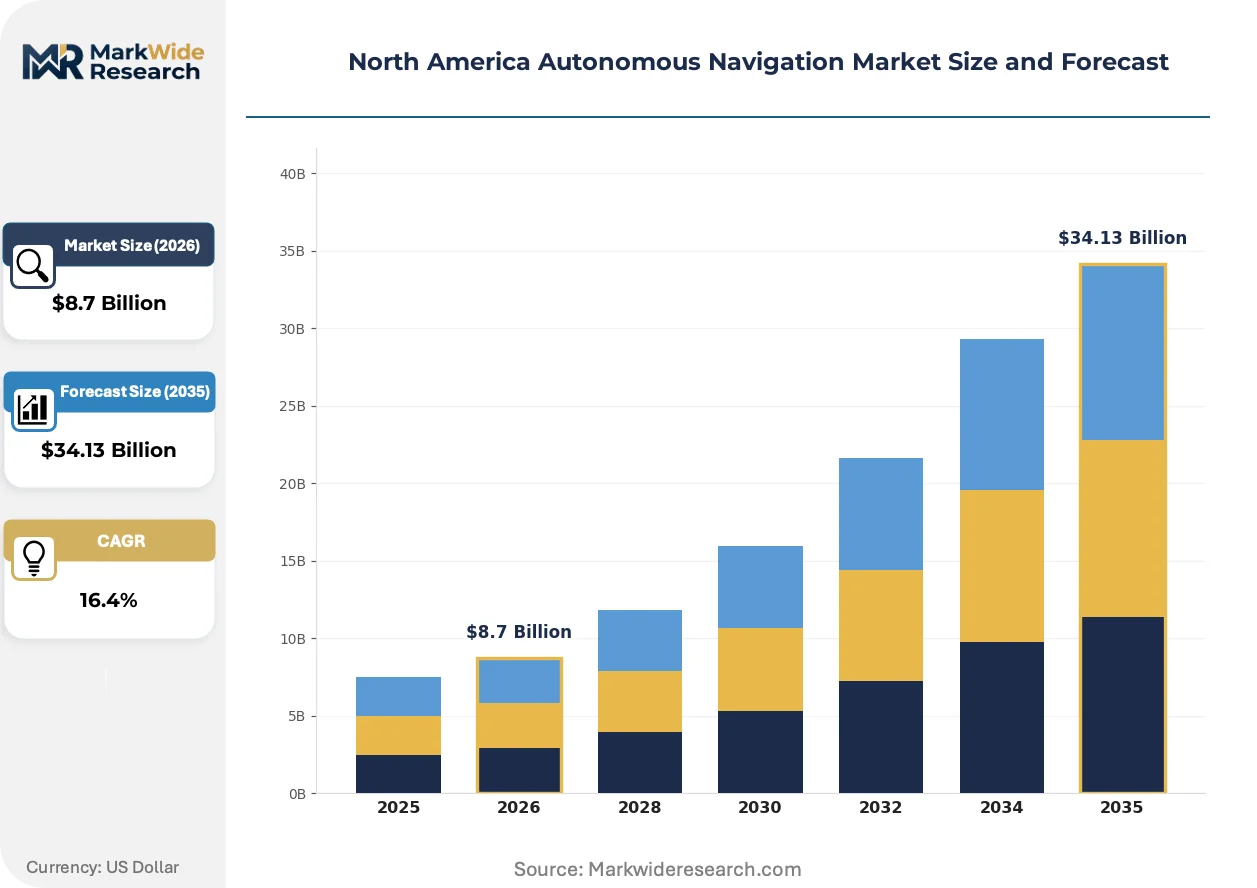
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Consumer Drones, Industrial Robots, Automated Vehicles, Marine Vessels Technology: GPS, LIDAR, Computer Vision, Radar End User: Aerospace, Agriculture, Logistics, Defense Application: Delivery Services, Surveillance, Mapping, Surveying |
| Companies Covered | Raytheon Technologies Corporation, Northrop Grumman Corporation, Honeywell International Inc., L3Harris Technologies Inc., Lockheed Martin Corporation, General Dynamics Corporation, BAE Systems, Waymo LLC, RTX Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Autonomous Navigation Market Evolving Landscape
Solid-state LIDAR architectures are compressing sensor cost curves while edge-computing deployments enable real-time path planning without continuous cloud connectivity. These shifts are restructuring competitive positioning between hardware specialists and software-centric platform developers.
Solid-state LIDAR utilizing MEMS mirror arrays and optical phased arrays is displacing mechanical spinning units in commercial autonomous vehicle programs. Automotive OEMs in the United States are adopting these compact units for production vehicle integration at scale. This displacement is collapsing the historical premium commanded by high-end mechanical LIDAR suppliers and compressing component sourcing decisions to semiconductor fabrication partnerships.
The FAA Reauthorization Act provisions governing unmanned aircraft system remote identification and traffic management are mandating broadcast capabilities for all commercial drone operations above specified weight thresholds. Logistics operators and agricultural service providers must retrofit or replace existing fleets to maintain airspace access. Agricultural spraying contractors in California and Texas are accelerating procurement of compliant platforms ahead of enforcement phase-ins.
Outcome-based service contracts for autonomous navigation capabilities are replacing traditional equipment purchase models in precision agriculture. Fleet operators now contract for acreage-covered or task-completed metrics rather than owning navigation hardware directly. This shift concentrates most visible in large-scale Midwest grain operations where equipment utilization rates justify performance-guarantee pricing structures.
North America Autonomous Navigation Market Segmentation
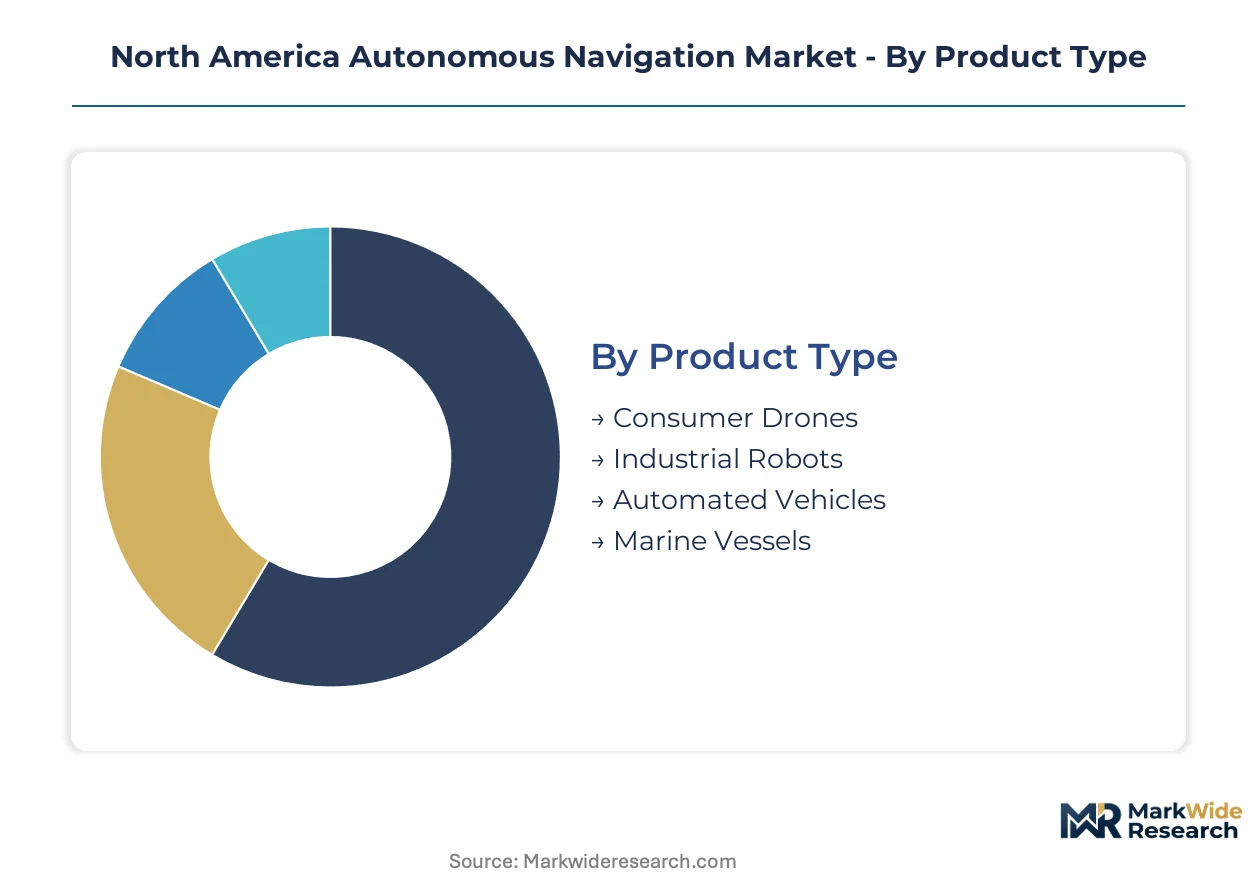
Segmentation in the North America Autonomous Navigation Market reveals how FAA certification requirements, defense procurement standards, and commercial deployment timelines create divergent revenue pools across platform categories. Each dimension exposes distinct technical specifications, customer concentration patterns, and regulatory compliance burdens that shape supplier strategy.
Product Type:
FAA Part 107 waivers and MIL-STD certification timelines create divergent market access conditions across platform categories, with defense-grade systems commanding extended validation cycles and commercial aerial systems facing airspace integration constraints.
- Automated Vehicles:These platforms integrate solid-state LIDAR, high-definition mapping, and redundant sensor arrays to achieve SAE Level 4 autonomy on designated routes. Automotive OEM procurement in Michigan, California, and Texas concentrates demand for production-scale navigation systems, though NHTSA regulatory uncertainty around deployment permissions constrains fleet expansion timelines.
- Marine Vessels:Unmanned surface and underwater vehicles deploy INS-GPS fusion, maritime radar, and acoustic positioning for offshore energy inspection and naval operations. Gulf Coast operators and Canadian Arctic programs drive procurement, with Transport Canada ice-classification requirements adding certification layers for northern deployment.
- Consumer Drones:Lightweight GPS-vision fusion platforms serve recreational and light commercial aerial photography markets.
- Industrial Robots:Warehouse AGVs and manufacturing floor autonomous mobile robots navigate via LIDAR and magnetic tape fusion.
Established volume favors automated vehicles; emerging adoption favors marine vessels.
Technology:
Cost tier differentiation separates premium defense-grade sensor fusion from commercial-grade single-modality solutions, with software margins concentrating in perception-stack developers while hardware margins compress at component level.
- LIDAR:Solid-state MEMS and optical phased array architectures displace mechanical spinning units, collapsing unit costs for automotive integration. Semiconductor fabrication partnerships in Arizona and New Mexico determine supply security for tier-one automotive programs.
- Computer Vision:Deep learning-based perception systems process camera inputs for object detection, lane keeping, and obstacle avoidance. California agricultural automation and last-mile logistics operators in Texas prioritize vision-heavy platforms for cost-sensitive deployment.
- GPS:Multi-constellation receivers provide foundational positioning for consumer and commercial aerial systems.
- Radar:Automotive and marine applications deploy 77GHz and 24GHz units for all-weather detection.
Hardware commoditization favors GPS; perception-stack differentiation favors computer vision.
End User:
Customer procurement authority separates centralized defense acquisition from fragmented commercial adoption, with prime contractor relationships determining market access for platform integrators.
- Defense:Department of Defense unmanned ground, aerial, and maritime programs mandate MIL-STD-810 environmental hardening and anti-jam positioning. Pentagon budget concentration in Virginia, California, and Texas procurement offices shapes supplier geographic clustering.
- Logistics:Warehouse operators and last-mile delivery services deploy autonomous navigation for inventory movement and package distribution. Midwest distribution hubs and California e-commerce fulfillment centers concentrate demand for indoor and short-haul outdoor systems.
- Aerospace:Commercial aviation and satellite operators utilize autonomous navigation for unmanned cargo and inspection platforms.
- Agriculture:Row-crop and specialty crop operators adopt precision planting and spraying automation.
Contract concentration favors defense; volume scaling favors logistics.
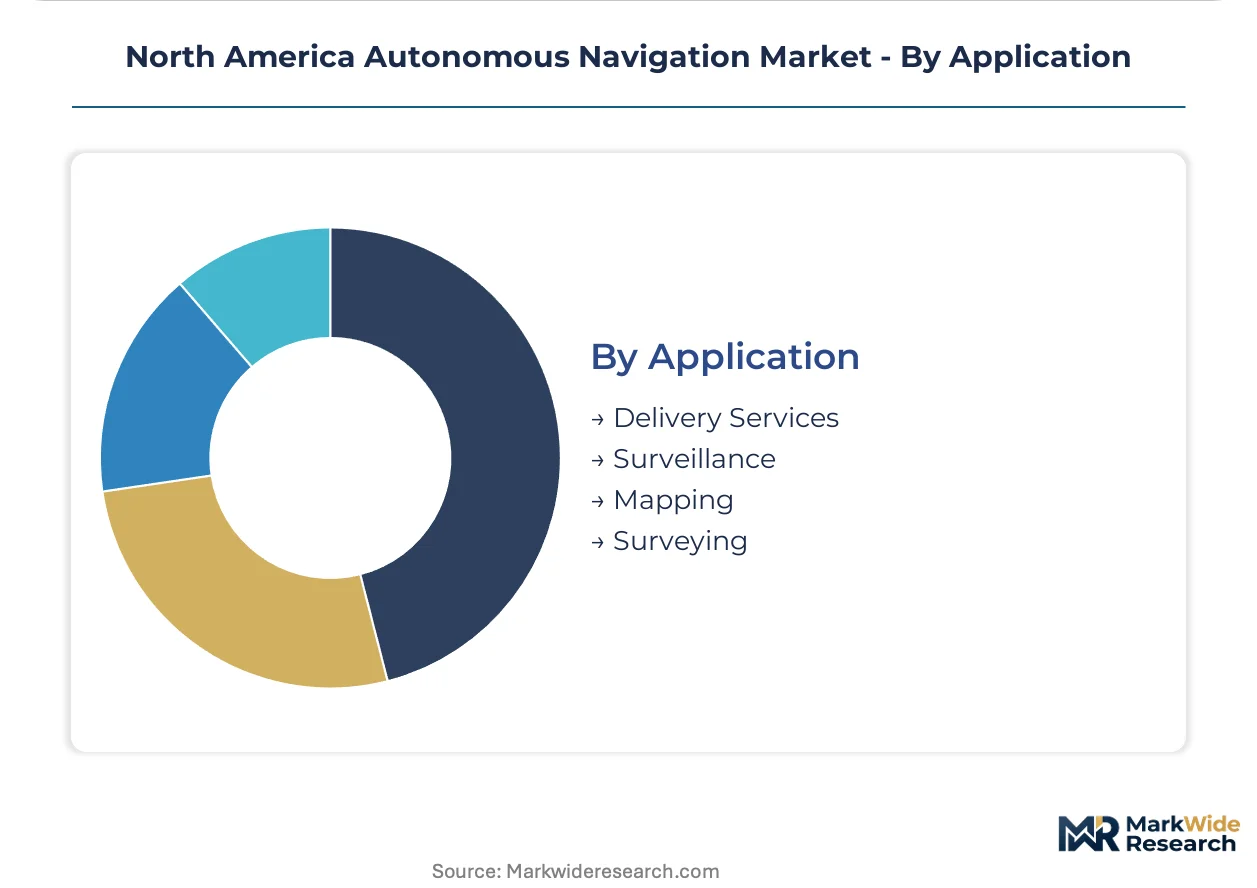
Application:
Maturity gradient separates established surveying workflows from emerging delivery service deployments, with regulatory clearance timelines determining commercial viability across use cases.
- Surveillance:Border patrol, infrastructure monitoring, and perimeter security applications fuse multi-spectral imaging with autonomous platform control. CBP programs along the US-Mexico border and Canadian Coast Guard Arctic patrol create dedicated procurement channels.
- Delivery Services:Medical supply, retail, and food logistics operators pilot drone and ground robot last-mile distribution. FAA beyond-visual-line-of-sight waiver scarcity in dense urban airspace limits scaling beyond rural and suburban test corridors.
- Mapping:Topographic, cadastral, and utility corridor survey operations utilize autonomous aerial and ground platforms.
- Surveying:Construction, mining, and environmental monitoring applications deploy autonomous navigation for repetitive data collection.
Regulatory clarity favors mapping; operational complexity favors delivery services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement premiums in the United States command pricing multiples unavailable to Canadian platform developers, creating a two-tier revenue structure across the North American market. This asymmetry shapes supplier geographic clustering and certification investment priorities.
United States
Department of Defense unmanned systems programs and FAA beyond-visual-line-of-sight waivers drive procurement concentration. NHTSA regulatory uncertainty around autonomous vehicle deployment permissions constrains fleet expansion timelines for commercial operators. Michigan, California, and Texas host automotive OEM navigation system development clusters.
Canada
Canadian Coast Guard Arctic sovereignty programs and Transport Canada ice-classification requirements create dedicated demand for hardened maritime navigation systems. Federal investment in autonomous maritime patrol generates procurement channels unavailable to US suppliers lacking cold-weather certification. Quebec and Atlantic Canada concentrate marine autonomous system developers serving polar operations.
Mexico
Cross-border logistics automation and agricultural precision spraying applications expand commercial navigation deployment in northern border states. Mexican federal aviation regulations lag FAA modernization, limiting aerial autonomous system scaling. Baja California and Chihuahua host assembly operations for US-bound autonomous agricultural equipment.
North America Autonomous Navigation Market Competitive Landscape
Concentration sits with defense electronics heritage firms commanding MIL-STD certification barriers. The supplier base organizes into three tiers: prime contractors integrating full platform navigation suites, sensor-component specialists supplying LIDAR and radar subsystems, and software-centric perception-stack developers. Strategic moves center on semiconductor fabrication partnerships for solid-state sensor supply security and outcome-based service contracting for agricultural automation.
Within the defense electronics tier, Raytheon Technologies Corporation and Northrop Grumman Corporation exemplify platform integrators leveraging MIL-STD heritage. Waymo LLC occupies a distinct position anchoring commercial autonomous vehicle navigation through sustained mapping infrastructure investment. These three entities represent divergent competitive vectors: defense certification depth, commercial scale deployment, and software-centric perception differentiation.
| Leading Market Players |
|---|
| Raytheon Technologies Corporation |
| Northrop Grumman Corporation |
| Honeywell International Inc. |
| L3Harris Technologies Inc. |
| Lockheed Martin Corporation |
| General Dynamics Corporation |
| BAE Systems |
| Waymo LLC |
| RTX Corporation |
| Others |
Value Network & Pricing Analysis
FAA Part 107 certification requirements and MIL-STD validation protocols simultaneously gate supplier qualification and stratify price tiers across the North America Autonomous Navigation Market. Defense contractors absorb extended validation cycles into premium pricing for hardened systems, while commercial aerial platform developers face compressed margins from rapid FAA waiver expansion.
Pricing Analysis
Configured-to-order pricing for defense-grade autonomous navigation systems commands substantial premiums over standard commercial configurations. Three-tier pricing structure across premium, standard, and economy levels separates MIL-810 hardened platforms from FAA Part 107 compliant commercial systems and consumer-grade GPS-vision units. Cost compression in solid-state LIDAR components is intensifying because semiconductor fabrication scale economics are collapsing mechanical sensor premiums. Agricultural automation operators in the US Midwest exhibit highest price sensitivity, whereas Department of Defense procurement offices demonstrate lowest sensitivity due to mission-critical performance requirements.
Supply Chain Analysis
Inbound logistics costs from Asian semiconductor fabrication centers through West Coast ports constrain component availability for domestic platform integrators. Sensor supply concentrates in Taiwan, South Korea, and the United States for MEMS mirror arrays and optical phased array production. Raw material dependencies include gallium arsenide substrates, indium phosphide wafers, and precision optical coatings. Single-source vulnerability in photonics foundry capacity elevates supply risk for tier-one automotive programs. Distribution runs through direct OEM partnerships for defense contracts and agricultural equipment dealer networks for precision farming applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Autonomous Navigation Market sits in early-cycle expansion, with FAA beyond-visual-line-of-sight waiver proliferation accelerating commercial aerial deployment timelines beyond prior regulatory constraints.
For Market Incumbents: Secure semiconductor fabrication partnerships in Arizona and New Mexico to guarantee solid-state LIDAR supply security against photonics foundry bottlenecks. Deepen backward integration into sensor production to defend margin position from component cost volatility. Lock in MIL-STD certification pipelines to maintain defense procurement access against emerging platform integrators lacking environmental hardening heritage. For New Entrants and Emerging Players: Lead with Canadian Arctic maritime applications where ice-classification requirements create defensible niches against US defense electronics heritage firms. Target agricultural automation convergence in Midwest row-crop operations through outcome-based service contracting rather than capital equipment sales. Deploy direct-to-fleet sales models for last-mile delivery vehicle procurement to bypass entrenched automotive dealership networks. For Investors and Strategic Acquirers: FAA Reauthorization Act remote identification mandates reshape the acquisition landscape toward perception-stack developers with broadcast-compliant software architectures. Long-term viability centers on platform-agnostic navigation software vendors capable of spanning defense, logistics, and agricultural end uses. Watch NHTSA autonomous vehicle deployment permission signals as the critical inflection for commercial automotive navigation scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Semiconductor Fabrication Partnership | Arizona and New Mexico foundry access secures solid-state LIDAR supply for automotive OEM programs. |
| MIL-STD Certification Investment | Environmental hardening validation opens Department of Defense unmanned platform procurement channels. |
| Outcome-Based Service Contracting | Acreage-covered pricing models align equipment utilization with Midwest grain operator cash flows. |
| Arctic Ice-Classification Compliance | Transport Canada certification creates dedicated demand from Canadian Coast Guard sovereignty programs. |
| Perception-Stack Software Licensing | Platform-agnostic navigation algorithms enable cross-vertical deployment across defense and commercial applications. |
Research Methodology
A standing panel of autonomous platform engineering directors, defense procurement officers, agricultural equipment fleet managers, FAA certification consultants, and semiconductor supply chain specialists provided ongoing calibration throughout the study. Primary interviews with these stakeholders combined with secondary validation from SEC 10-K filings, FAA waiver databases, Department of Defense budget justification documents, and customs trade data. Bottom-up sensor shipment analysis and top-down defense procurement aggregation triangulated market sizing across the projection horizon.
Consistency checks against external benchmarks validated volume and value outputs throughout the modeling period. The analytical framework modeled product type, technology modality, end-user procurement authority, application maturity, and regional regulatory cluster dimensions across the analysis window. CAGRs derived from segment-level growth rate reconciliation with macroeconomic drivers and technology adoption curves. Industry-specific forecast inputs included FAA waiver approval velocity and Department of Defense unmanned systems budget allocation patterns.
Underlying assumptions cover sustained FAA modernization momentum and stable defense procurement prioritization for autonomous platforms, with deviation risk concentrated in cross-border certification harmonization failures and GPS denial vulnerability mitigation timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Singapore Autonomous Navigation Market
Autonomous Vehicles
Autonomous (Driverless) Car Market
Autonomous Vehicles
Autonomous Vehicle ECU Market
Autonomous Vehicles
North America Adaptive Steering Market
Autonomous Vehicles
Autonomous Vehicle Management Services Market
Autonomous Vehicles
Battery-Electric Self-Driving Car Market
Autonomous Vehicles
Self-Balancing Mobility Market
Autonomous Vehicles
Predictive Automobile Technology Market
Autonomous Vehicles
Semi Autonomous and Autonomous Vehicles Market
Autonomous Vehicles
Autonomous Electric Bus Market
Autonomous Vehicles
Europe Autonomous Navigation Market
Autonomous Vehicles
Unmanned Traffic Management Market
Autonomous Vehicles
Fully Autonomous Driving Market
Autonomous Vehicles
Automated Valet Parking (AVP) Market
Autonomous Vehicles
Africa Autonomous Navigation Market
Autonomous Vehicles
Autonomous Delivery Vehicle Market