
 Automotive Automated Parking System Market | 2026-2036
Automotive Automated Parking System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Automated Parking System Market Analysis
The EU Green Deal's urban mobility targets is hardening requirements for space-efficient parking infrastructure in dense European cities. Robotic Parking Systems leverages its mechanical stacking expertise to dominate high-rise garage installations across German metropolitan zones. Westfalia Technologies anchors its position through sustained R&D intensity in automated material-handling architectures adapted for vehicle storage. ShinMaywa Industries competes on manufacturing scale, drawing from its industrial equipment heritage to supply Japanese OEM integrated systems.
Automotive automated parking systems encompass electromechanical platforms, sensor arrays, and control software that autonomously maneuver vehicles into parking bays without human intervention, typically achieving positioning accuracy within centimeters through fusion of ultrasonic and camera-based detection. These systems serve commercial and residential developers seeking to maximize vehicle capacity per square meter while reducing circulation space in structurally constrained sites. Camera-based systems occupy the premium tier of the technology segment due to their superior object recognition and lane-marking fidelity in low-light conditions. Robotic parking systems lead the product type category in revenue per installation, though hybrid configurations that blend self-parking with remote valet activation represent the fastest-expanding configuration as OEMs seek flexible consumer interfaces.
The UNECE World Forum for Harmonization of Vehicle Regulations shapes type-approval pathways for automated parking functions across European markets, while Japan's MLIT establishes domestic safety benchmarks for autonomous maneuvering in confined structures. In the United States, NHTSA guidelines on automated driving system oversight influence how suppliers validate sensor redundancy and fail-safe protocols for commercial deployment. Stakeholders must monitor evolving liability frameworks as jurisdictions determine whether system operators, facility owners, or vehicle manufacturers assume responsibility for parking-incident claims.
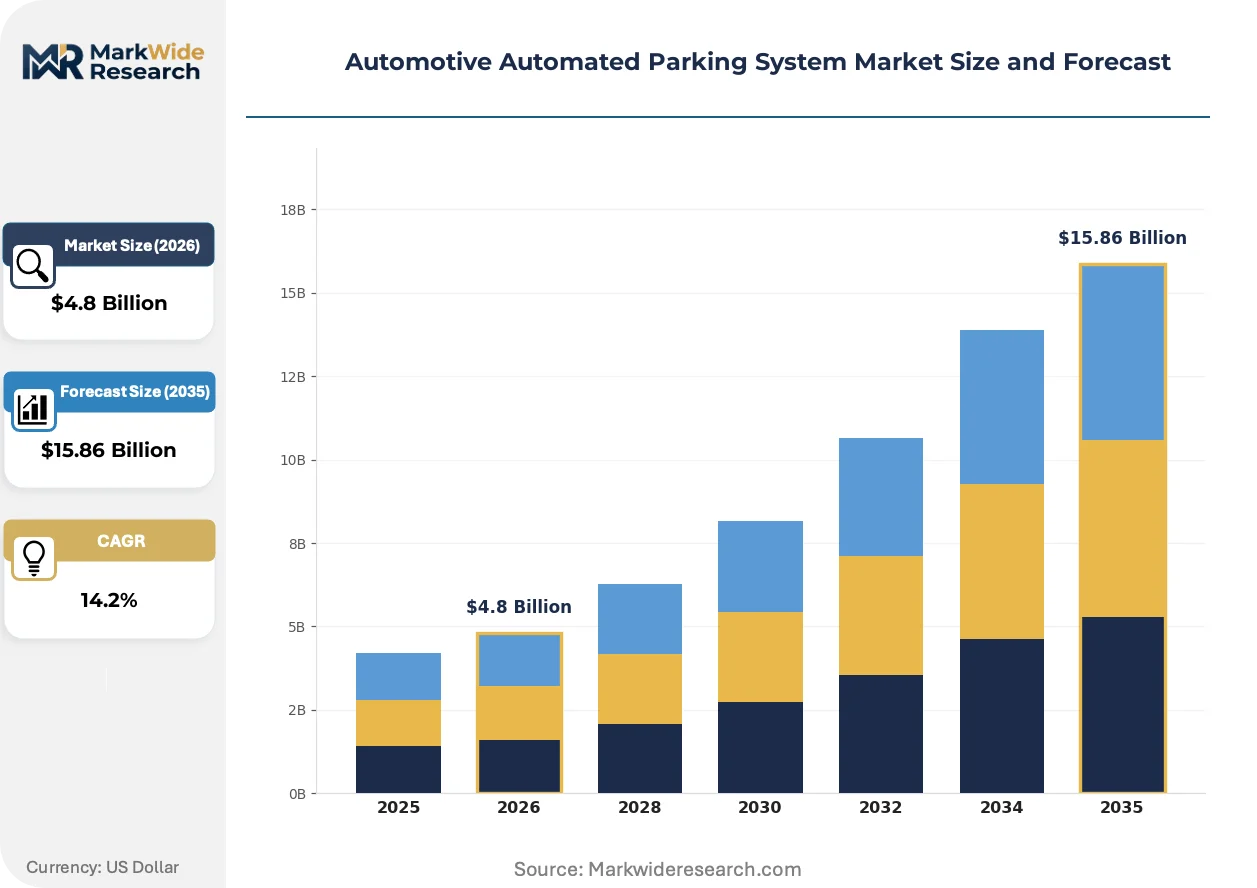
Market Dynamics
Sensor fusion architectures are compressing development cycles for automated parking platforms as OEMs consolidate ultrasonic, camera, and lidar inputs into unified perception stacks. The EU AI Act's risk-classification framework is forcing suppliers to revalidate algorithmic decision pathways ahead of type-approval deadlines.
Growth Catalysts
- UNECE Regulation 79:Harmonized technical requirements for steering equipment enable single-homologation pathways across European markets, reducing certification overhead for tier-1 suppliers.
- Urban densification in German metropolitan zones:Municipal zoning reforms prioritize automated mechanical parking in high-rise residential developments to maximize vehicle capacity per square meter.
- Camera-based perception:Low-light image processing improvements expand operational envelopes for valet-style systems in underground structures where ultrasonic sensors face multipath interference.
Market Restraints
- LiDAR component concentration:Sourcing vulnerability persists for solid-state scanning modules manufactured primarily in East Asian foundries, exposing supply continuity risk.
- Structural steel volatility:Robotic parking installations face input cost pressure from fluctuating commodity prices for high-grade structural alloys used in mechanical stacking platforms.
- UNECE liability ambiguity:Unclear fault attribution between vehicle manufacturers and facility operators in parking-incident scenarios delays insurance product development for commercial deployments.
Strategic Opportunities
- Japan's MLIT autonomous maneuvering standards:Domestic safety benchmarks for confined-structure operation create regulatory runway for integrated OEM-facility partnerships in Tokyo and Osaka.
- Retrofit channel expansion:Aftermarket installation networks for existing parking structures represent untapped revenue streams as hardware-agnostic software platforms mature.
- 5G-V2X convergence:Ultra-reliable low-latency communication between vehicles and garage infrastructure enables cooperative positioning without dedicated on-vehicle sensor suites.
Industry Challenges
- Functional safety engineering scarcity:ISO 26262 ASIL-D certification expertise remains concentrated among specialized consultancies, extending development timelines for new market entrants.
- Legacy facility integration:Electromechanical retrofitting of pre-2010 parking structures requires structural reinforcement assessments that compress project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Automated Parking System Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Valet Parking System, Self-Parking System, Hybrid Parking System, Robotic Parking System Technology: Ultrasonic Sensors, Infrared Sensors, LiDAR, Camera-Based Systems End User: Residential Complexes, Shopping Malls, Commercial Buildings, Airports Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing |
| Companies Covered | Robotic Parking Systems, AJ Automated Parking Systems, Westfalia Technologies, ShinMaywa Industries, Lodige Industries, Wohr Parking Systems, CityLift Parking, Skyline Parking AG, Klaus Multiparking, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Automated Parking System Market Emerging Trajectories
Edge computing migration is redistributing processing loads from centralized garage servers to vehicle-mounted controllers, altering hardware procurement patterns for facility operators. This architectural shift is compressing infrastructure capital requirements while elevating onboard compute specifications.
Neural network-based trajectory planning is rewriting how automated parking systems negotiate tight maneuvering envelopes. German luxury OEMs are deploying these algorithms across flagship electric vehicle lines with minimal human oversight. The technology is compressing positioning tolerances to sub-5-centimeter accuracy in multi-level structures.
The EU AI Act's high-risk system classification is mandating algorithmic transparency documentation for autonomous parking functions. Suppliers must now maintain technical file repositories demonstrating traceable decision logic for type-approval authorities. Camera-based perception stacks face the steepest compliance burden given their reliance on black-box neural classifiers.
Facility operators in South Korea are unbundling parking management software from mechanical hardware procurement, selecting control platforms on subscription terms rather than capital purchase. This purchasing pattern shift is displacing turnkey system vendors who historically bundled electromechanical and software components. Seoul's commercial real estate developers are driving adoption of modular, API-first parking architectures.
Automotive Automated Parking System Market Segmentation
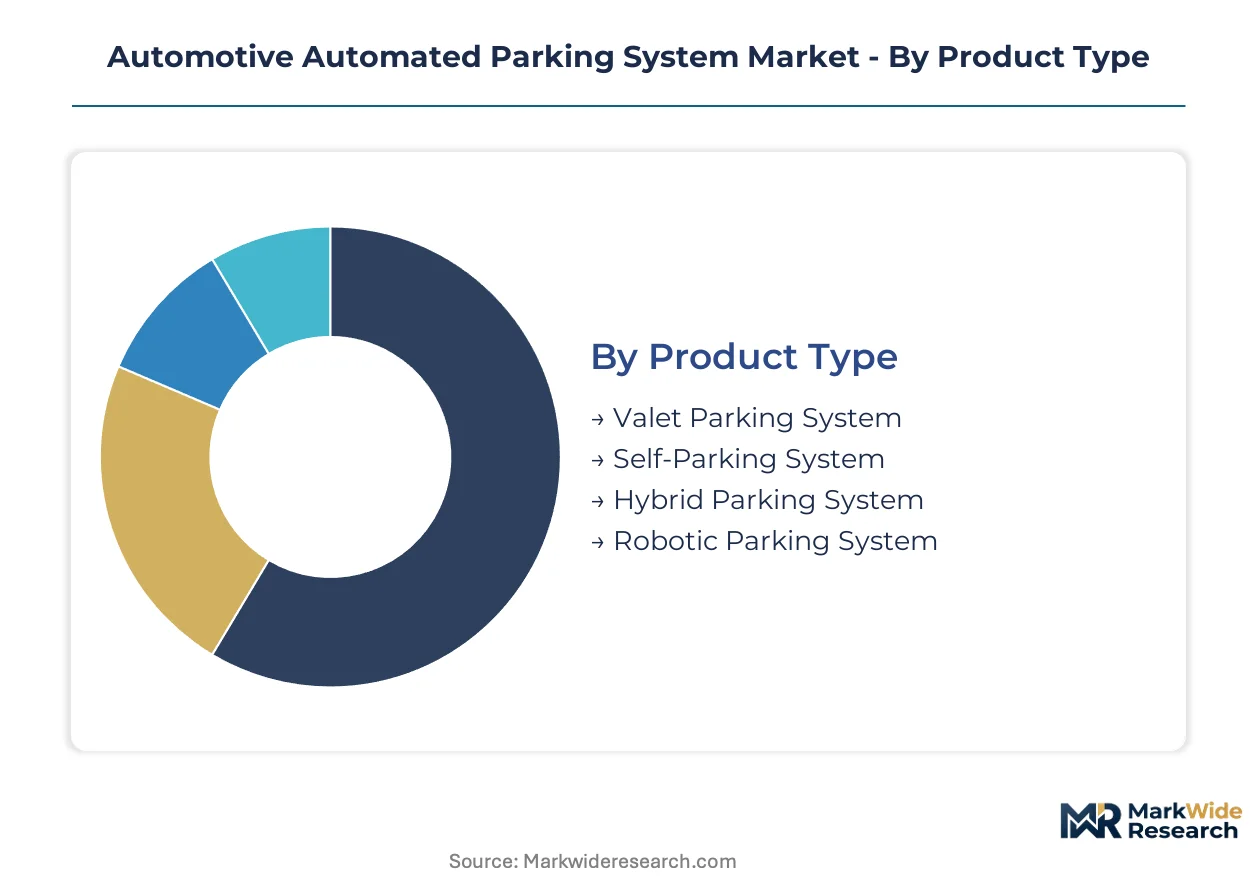
Segmentation in the Automotive Automated Parking System Market reveals how hardware specifications, software architectures, and facility types create distinct procurement patterns. Suppliers must align sensor configurations and deployment models with the operational constraints of target installations.
Product Type:
Electromechanical complexity and human-vehicle interaction models define the product architecture axis.
- Valet Parking System:Fully autonomous platforms relocate vehicles to storage bays without driver presence, utilizing centralized garage controllers and mechanical shuttles. Demand concentrates in German luxury automotive lines where OEMs bundle remote activation with flagship electric vehicle subscriptions.
- Robotic Parking System:Multi-level mechanical stacking platforms maximize vehicle density through vertical storage matrices, achieving positioning precision within centimeters via electromechanical actuators. South Korean commercial developers in Seoul prioritize these installations for high-rise residential projects facing municipal zoning pressure.
- Self-Parking System:Onboard vehicle controllers execute parking maneuvers with driver supervision, requiring minimal garage infrastructure modification.
- Hybrid Parking System:Configurations blend self-parking autonomy with remote valet activation, offering flexible consumer interfaces across variable facility conditions.
Mature deployment sits with Robotic Parking System installations in established metropolitan zones. Newer deployment is concentrated in Hybrid Parking System configurations as OEMs seek adaptable activation modes.
Technology:
Perception modality determines environmental adaptability and regulatory compliance burden across installation environments.
- Camera-Based Systems:Visual perception stacks deliver superior object recognition and lane-marking fidelity in low-light underground structures, leveraging neural network classifiers for trajectory planning. The EU AI Act's high-risk system classification imposes algorithmic transparency documentation requirements on these implementations, extending type-approval timelines.
- LiDAR:Solid-state scanning modules generate precise three-dimensional spatial maps for multi-level maneuvering, though sourcing concentration in East Asian foundries exposes supply continuity vulnerabilities.
- Ultrasonic Sensors:Cost-effective proximity detection for basic parking assistance in surface lots and low-complexity structures.
- Infrared Sensors:Thermal-based detection systems supplement primary perception in specialized environmental conditions.
Volume concentration favors Ultrasonic Sensors in economy-tier installations. Value capture is climbing the fastest in Camera-Based Systems as low-light processing improvements expand operational envelopes.
End User:
Facility throughput requirements and capital expenditure profiles shape technology selection across installation categories.
- Shopping Malls:High-turnover retail environments demand rapid vehicle retrieval cycles and intuitive consumer interfaces, driving adoption of subscription-based software platforms that unbundle control systems from mechanical hardware.
- Commercial Buildings:Corporate facilities prioritize space efficiency and premium user experience, supporting investment in fully automated valet configurations with integrated building management systems.
- Residential Complexes:Multi-unit housing developments balance density maximization against per-unit cost constraints.
- Airports:Long-duration storage facilities with predictable retrieval patterns suit mechanical stacking architectures.
Procurement scale peaks in Commercial Buildings with integrated smart building initiatives. Deployment velocity is expanding most quickly in Shopping Malls as South Korean developers adopt API-first parking architectures.
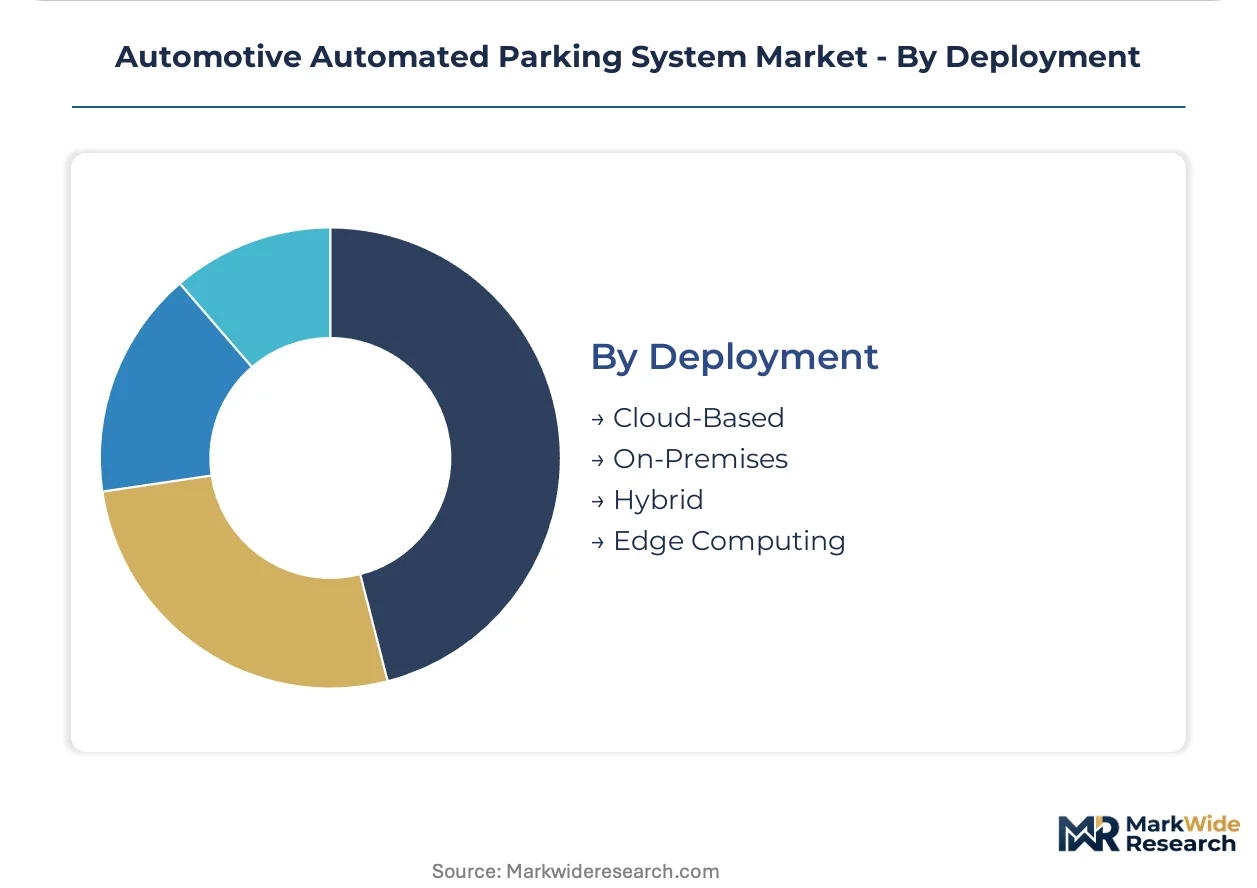
Deployment:
Compute location and data sovereignty requirements determine infrastructure capital allocation and ongoing operational expenditure structures.
- Edge Computing:Vehicle-mounted controllers redistribute processing loads from centralized garage servers, compressing infrastructure capital requirements while elevating onboard compute specifications for German luxury OEM flagship lines.
- Cloud-Based:Centralized algorithm updates and predictive maintenance analytics reduce facility-side hardware investment, appealing to retrofit channel operators managing distributed asset portfolios.
- On-Premises:Localized data processing satisfies stringent facility operator security requirements in sensitive installations.
- Hybrid:Architectures partition critical real-time control from analytics workloads across edge and cloud resources.
Established installations favor On-Premises deployment for operational predictability. Architectural migration is gaining share fastest in Edge Computing as processing redistribution alters hardware procurement patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul anchors deployment velocity for automotive automated parking systems, with commercial real estate developers driving API-first parking architectures across the capital region. German metropolitan zones concentrate valet-style autonomous parking in luxury electric vehicle lines. Japanese OEMs integrate these systems into flagship platforms through domestic safety benchmarks.
Germany
Municipal zoning reforms in Frankfurt and Munich prioritize automated mechanical parking in high-rise residential developments to maximize vehicle capacity per square meter. The KBA enforces UNECE Regulation 79 harmonized technical requirements for steering equipment, enabling single-homologation pathways across European markets. Stuttgart's automotive corridor hosts OEM integration facilities where sensor fusion architectures undergo type-approval validation.
South Korea
Facility operators in Seoul unbundle parking management software from mechanical hardware procurement, selecting control platforms on subscription terms rather than capital purchase. The country's national automotive regulator establishes domestic safety benchmarks for autonomous maneuvering in confined structures. Busan-Ulsan industrial zones supply electromechanical actuators for vertical storage matrices in high-rise residential projects.
Japan
MLIT autonomous maneuvering standards for confined-structure operation create regulatory runway for integrated OEM-facility partnerships in Tokyo and Osaka. The Ministry of Land, Infrastructure, Transport and Tourism benchmarks safety protocols for multi-level mechanical stacking. Nagoya's industrial belt manufactures precision electromechanical components for robotic parking installations.
United States
NHTSA guidelines on automated driving system oversight influence how suppliers validate sensor redundancy and fail-safe protocols for commercial deployment across California and Texas metropolitan zones. The National Highway Traffic Safety Administration shapes liability frameworks as jurisdictions determine fault attribution for parking-incident claims. Silicon Valley clusters host edge computing development for vehicle-mounted controllers redistributing processing loads.
Automotive Automated Parking System Market Vendor Landscape
Premium-margin players sit above commodity-margin players across technology integration depth and certification complexity. The vendor base stratifies between mechanical stacking specialists, sensor fusion platform developers, and facility-software integrators. Three archetypes dominate: electromechanical hardware fabricators with industrial equipment heritage, perception-stack technology licensors, and turnkey system bundlers. Competitive moves center on strategic partnerships with luxury OEMs and geographic expansion into German and South Korean metropolitan zones.
Among Germany-based fabricators, Wohr Parking Systems and Klaus Multiparking occupy positions within the mechanical stacking tier, while Westfalia Technologies exemplifies sustained R&D intensity in automated material-handling architectures. Robotic Parking Systems represents the electromechanical specialist archetype leveraging stacking expertise for high-rise garage installations. ShinMaywa Industries anchors the manufacturing-scale segment, drawing from industrial equipment heritage to supply Japanese OEM integrated systems.
| Leading Market Players |
|---|
| Robotic Parking Systems |
| AJ Automated Parking Systems |
| Westfalia Technologies |
| ShinMaywa Industries |
| Lodige Industries |
| Wohr Parking Systems |
| CityLift Parking |
| Skyline Parking AG |
| Klaus Multiparking |
| Others |
Supply Flow & Price Mechanics
Facility operators in South Korea unbundling parking management software from mechanical hardware procurement force suppliers toward subscription-based revenue models that compress upfront capital recognition while extending customer lifetime value capture. This procurement shift concentrates pricing power with control-platform developers and fragments margins for electromechanical fabricators locked into project-based contracting.
Pricing Analysis
Value-based pricing anchored to vehicle throughput per square meter dominates commercial installations, with facility operators paying premium rates for systems achieving sub-5-centimeter positioning accuracy in multi-level structures. Price differentiation stratifies across premium camera-based perception stacks, standard ultrasonic-sensor configurations, and economy-tier basic assistance modules. Pricing pressure stems from structural steel volatility in robotic parking installations, compressing project margins for mechanical stacking specialists. Residential developers exhibit highest price sensitivity due to per-unit cost constraints, while commercial building operators prioritize uptime guarantees over capital expenditure minimization.
Supply Chain Analysis
ISO 26262 ASIL-D certification requirements gate supplier qualification, concentrating electromechanical component sourcing in Germany, Japan, and South Korea where precision manufacturing heritage supports functional safety documentation. Solid-state LiDAR modules draw from East Asian foundries, exposing supply continuity risk for perception-stack developers. Structural steel and high-grade aluminum alloys for mechanical platforms face commodity price volatility. Distribution runs through facility operators and OEM integration channels, with turnkey bundlers losing share to unbundled software procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Functional safety engineering scarcity props pricing for certified suppliers, creating a supply-constrained market structure where ASIL-D capability commands sustained premium positioning.
For Market Incumbents: Lock in long-term supply agreements for solid-state LiDAR modules before East Asian foundry capacity tightens further. Deepen backward integration into electromechanical actuator production to offset structural steel volatility. Prioritize certification investment in EU AI Act algorithmic transparency documentation to defend positioning against emerging perception-stack developers lacking regulatory affairs depth. For New Entrants and Emerging Players: Capture the retrofit channel for existing parking structures in German metropolitan zones where municipal zoning reforms accelerate demand but incumbent turnkey vendors lack hardware-agnostic software platforms. Target subscription-based control platforms as the most penetrable segment, leveraging API-first architectures that displace bundled electromechanical procurement. Lead with 5G-V2X cooperative positioning as a go-to-market angle requiring minimal on-vehicle sensor suites. For Investors and Strategic Acquirers: The window for entry favors perception-stack technology licensors with EU AI Act compliance documentation already filed. Long-term viability rests on algorithmic transparency capabilities becoming mandatory across European markets. Watch for inflection when Japan's MLIT standards harmonize with UNECE frameworks, signaling accelerated OEM-facility partnership formation.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Sensor fusion architectures consolidating ultrasonic, camera, and LiDAR inputs compress development cycles for Tier-1 suppliers seeking single-homologation pathways. |
| Software-Defined Vehicle Investment | Edge computing migration elevates onboard compute specifications for German luxury OEM flagship lines while reducing garage infrastructure capital requirements. |
| Geographic Manufacturing Footprint | Busan-Ulsan industrial zones supply electromechanical actuators for vertical storage matrices serving Seoul high-rise residential projects under municipal zoning pressure. |
| Charging Infrastructure Partnership | Integrated OEM-facility partnerships in Tokyo and Osaka leverage MLIT autonomous maneuvering standards for confined-structure operation in flagship electric vehicle platforms. |
| Strategic Partnership | API-first parking architectures in South Korea enable facility operators to unbundle control platforms from mechanical hardware procurement on subscription terms. |
Methodological Framework
Multi-period observation of sensor fusion architecture deployment, regulatory filing timelines, and OEM integration patterns anchored the trend analysis, supplemented by interviews with Tier-1 supplier procurement directors, OEM platform engineers, facility operator technology officers, and automated parking system integration specialists. Secondary validation drew from UNECE World Forum documentation, KBA type-approval records, MLIT safety benchmark publications, and NHTSA automated driving system guidelines. Bottom-up installation data triangulated against top-down OEM platform deployment estimates.
Input-output matrices modeled volume and value projections across product type, technology modality, end-user facility category, and deployment architecture dimensions throughout the forecast period. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion. Industry-specific inputs included electromechanical component lead times, certification timeline benchmarks, and municipal zoning reform implementation schedules.
The model holds under stable regulatory harmonization trajectories; deviation in UNECE liability framework resolution or EU AI Act enforcement intensity would shift competitive positioning assumptions. A model refresh is warranted upon material change in solid-state LiDAR foundry capacity allocation or structural steel commodity price regime.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Self-Balancing Mobility Market
Autonomous Vehicles
Self-Driving Truck Market
Autonomous Vehicles
Canada Autonomous Navigation Market
Autonomous Vehicles
Autonomous Haulage Truck Market
Autonomous Vehicles
Global Semi Autonomous and Autonomous Truck Market
Autonomous Vehicles
Latin America ADAS Market
Autonomous Vehicles
Autonomous Bike Market
Autonomous Vehicles
Luxury Autonomous Vehicle Market
Autonomous Vehicles
Autonomous Parking System Market
Autonomous Vehicles
Autonomous Intelligent Vehicle Market
Autonomous Vehicles
Zonal Vehicle Control Unit Architectures Market
Autonomous Vehicles
North America Adaptive Steering Market
Autonomous Vehicles
Global Adaptive Cruise Control Market
Autonomous Vehicles
Self-Driving Electric Vehicle Market
Autonomous Vehicles
Global Connected, Autonomous, Shared, and Electric (CASE) Market
Autonomous Vehicles
AI in Transportation Market