
 Electric Vehicle Control Unit Market | 2026-2036
Electric Vehicle Control Unit Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Control Unit Market Analytics
Modular bundling of battery management systems with motor controllers is restructuring buyer procurement patterns across passenger and commercial vehicle programs. Bosch leverages in-house semiconductor capabilities to sustain margin capture on integrated powertrain platforms. Continental AG anchors European supply relationships through its specialized digital control architectures. Tesla differentiates via proprietary vertical stack control over charging, thermal, and drive systems.
An electric vehicle control unit is an embedded electronic module that manages power distribution, motor torque response, and energy flow through real-time processing of sensor inputs at operating frequencies exceeding 100 MHz. Its primary purpose is to optimize vehicle efficiency, safety, and drivability by coordinating subsystems across the high-voltage architecture. Battery management systems command the largest value pool due to cell balancing complexity and safety certification requirements, while motor controllers represent the fastest-expanding segment as silicon carbide inverters displace insulated-gate bipolar transistor designs. Digital control technology leads implementation across OEM programs, though hybrid control retains share in cost-sensitive two-wheeler applications where analog redundancy satisfies emerging market regulations.
The US NHTSA and EPA jointly shape control unit demand through crashworthiness electrical isolation rules and fleet efficiency mandates that require precision energy management. China's MIIT and GB standards authorities enforce functional safety and software update protocols that dictate architecture choices for suppliers serving domestic OEMs and export programs. Europe's ECHA REACH restrictions and CE marking requirements constrain material selection for thermal interface components and housing alloys. Stakeholders must monitor how cybersecurity regulations evolve across these jurisdictions to determine certification investment sequencing and platform standardization strategy.
Market Dynamics
Silicon carbide power semiconductors are compressing inverter architectures and forcing tier-one suppliers to consolidate motor control and battery management functions into unified domain controllers, eliminating redundant processing layers across high-voltage platforms.
Growth Catalysts
- China MIIT Software-Defined Vehicle Mandates:Domestic OEMs must adopt over-the-air update architectures, accelerating procurement of centralized control units with redundant computing cores.
- Silicon Carbide Inverter Adoption:800V architectures in premium passenger vehicles require faster switching frequencies that legacy insulated-gate bipolar transistor designs cannot support.
- Germany's Automotive Manufacturing Corridor:ZF, Bosch, and Continental AG anchor supplier ecosystems that feed integrated control platforms into European and export vehicle programs.
Market Restraints
- Wafer Supply Concentration:Silicon carbide substrate production concentrates among a handful of specialized foundries, creating input bottlenecks for inverter-grade semiconductors.
- Functional Safety Certification Burden:ISO 26262 ASIL-D compliance requires 18-24 month validation cycles that delay platform launches and lock in design choices early.
- Analog Redundancy Persistence:Cost-sensitive two-wheeler markets in South Asia retain hybrid control architectures that limit addressable volume for fully digital suppliers.
Strategic Opportunities
- Commercial Vehicle Fleet Electrification:Heavy-duty truck and bus operators in North America are consolidating vendor relationships around single-source powertrain control suppliers.
- India PLI Scheme for Auto Components:Domestic manufacturing incentives are attracting control unit assembly investments to serve two-wheeler and compact car export programs.
- Thermal-Drive-Charging Integration:Unified domain controllers that coordinate battery thermal management with DC fast charging profiles are commanding premium positioning in 800V platforms.
Industry Challenges
- Embedded Software Talent Scarcity:Functional safety engineering and real-time operating system expertise concentrates among automotive suppliers in Germany and Japan, constraining expansion timelines.
- Legacy Vehicle Integration Friction:Retrofit control architectures into existing internal combustion platforms require custom harnessing and sensor adaptation that erode margin on low-volume programs.
- Cybersecurity Certification Complexity:UN R155 and R156 homologation demands separate validation tracks for intrusion detection and secure boot protocols, extending development schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Control Unit Market |
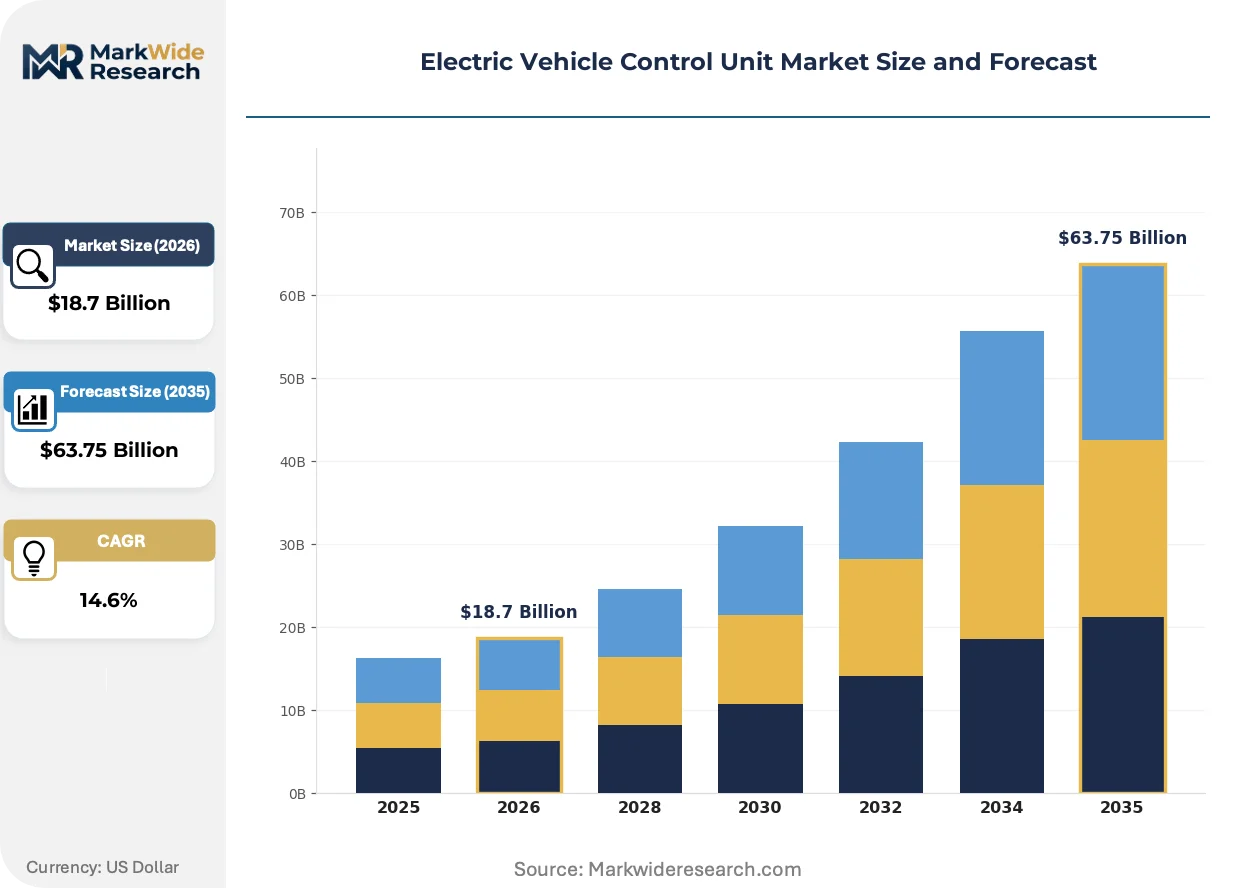
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $63.75 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery Management Systems, Power Distribution Units, Motor Controllers, On-Board Chargers Technology: Digital Control, Analog Control, Hybrid Control, Wireless Control End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Heavy-Duty Vehicles |
| Companies Covered | ZF, Denso, Tesla, Inovance Automotive, Continental AG, BYD, BorgWarner, NXP Semiconductors, Bosch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Control Unit Market Evolving Landscape
Domain consolidation is collapsing discrete electronic control units into centralized compute platforms, while regulatory pressure on functional safety and cybersecurity is hardening architecture requirements faster than supplier development cycles can adapt.
Silicon carbide metal-oxide-semiconductor field-effect transistors are consolidating inverter, DC-DC converter, and onboard charger functions into single power stages. Tier-one suppliers serving 800V passenger vehicle programs are eliminating separate enclosures and cooling loops that silicon-based designs required. This consolidation is compressing bill-of-material counts by 40% and reducing high-voltage cabling mass in premium electric architectures.
China's MIIT GB standards for software-defined vehicles now mandate encrypted firmware update pipelines and standardized diagnostic interfaces. Domestic OEMs must revalidate entire control stacks against these protocols to maintain sales licenses. Export-oriented manufacturers are dual-certifying platforms against both Chinese GB requirements and European UN ECE regulations, adding compliance layers but preserving market access.
Fleet operators in North America and Europe are unbundling control unit procurement from complete powertrain system purchases. Large commercial vehicle buyers now source battery management systems and motor controllers separately, then integrate through third-party software layers. This disintermediation is eroding traditional tier-one supplier lock-in and opening volume contracts to specialized control module vendors with open-architecture software stacks.
Electric Vehicle Control Unit Market Segmentation
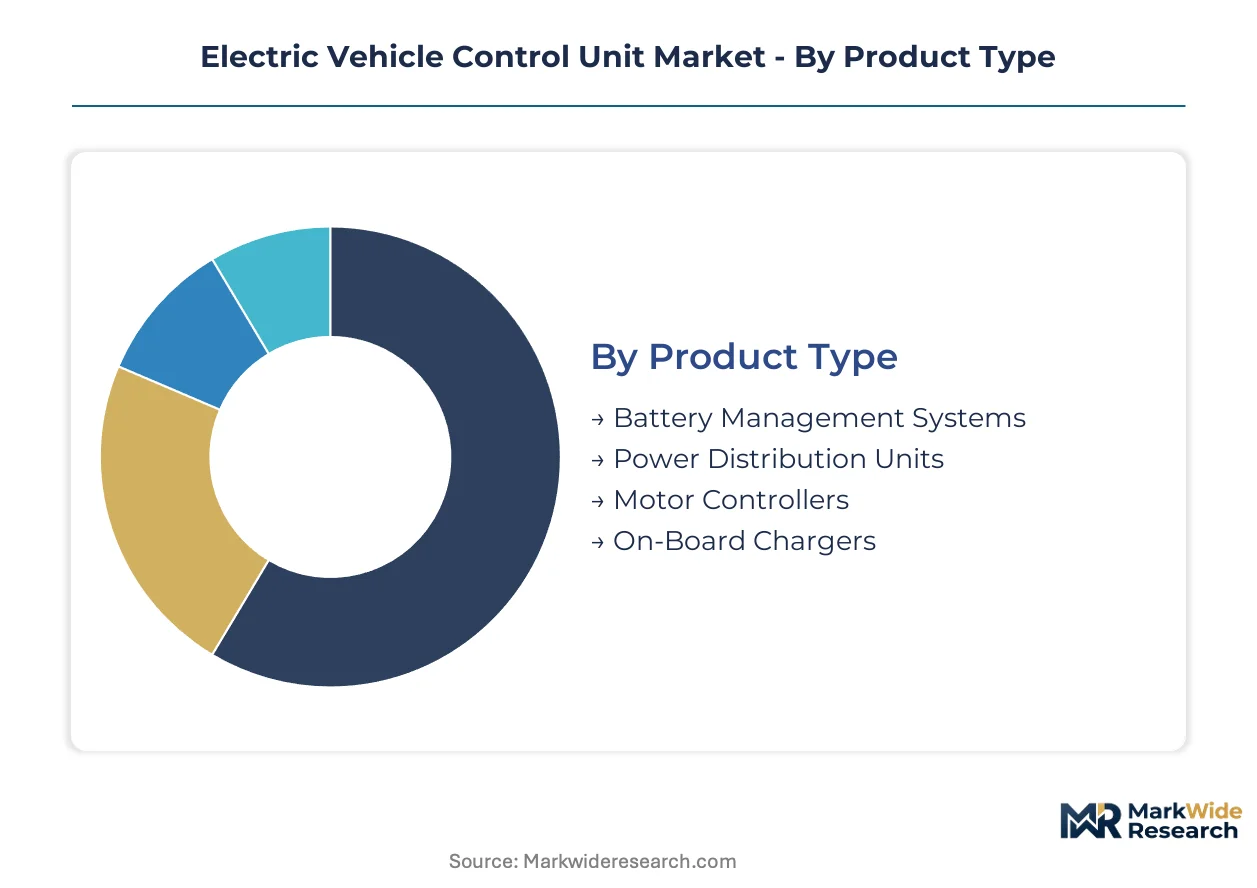
Control unit procurement patterns diverge sharply across product architectures and voltage classes. Technology choices cascade into certification requirements and supplier selection criteria. End-user concentration determines pricing leverage and platform standardization pressure.
Product Type:
Standardization dominates high-volume battery and motor platforms while customization persists in power distribution integration.
- Battery Management Systems:Cell balancing circuitry and state-of-charge algorithms process sensor arrays exceeding 200 inputs per pack. Demand concentrates in Germany's automotive corridor where cell-to-pack architectures require ASIL-D certified monitoring layers.
- Motor Controllers:Silicon carbide inverter stages switch at frequencies above 50 kHz, enabling 800V traction systems. China's premium passenger EV programs are scaling procurement fastest as domestic OEMs pursue export certification.
- Power Distribution Units:Solid-state relay matrices replace electromechanical contactors in next-generation architectures.
- On-Board Chargers:Bidirectional V2H capability is becoming mandatory in Japanese residential energy programs.
Leading the category by volume: Battery Management Systems. Growing fastest: Motor Controllers.
Technology:
Cost tiers separate safety-critical digital implementations from legacy analog retention in emerging markets.
- Digital Control:Multi-core processors execute real-time operating systems with deterministic response below 10 milliseconds. OEMs in Germany and Japan specify these architectures for ISO 26262 compliance across passenger vehicle programs.
- Hybrid Control:Analog redundancy layers provide fail-safe backup when primary digital paths fault. India's two-wheeler manufacturers retain this approach to satisfy cost targets under PLI scheme localization requirements.
- Analog Control:Discrete component designs persist in commercial vehicle retrofit applications.
- Wireless Control:NFC-enabled diagnostic interfaces are gaining traction in fleet management systems.
Digital Control commands the largest installed base. Hybrid Control is expanding most quickly in cost-sensitive segments.
End User:
Volume concentration shapes margin structures differently across captive production versus merchant supply.
- OEMs:Vertical integration into control unit design preserves software stack ownership and over-the-air update revenue streams. Tesla and BYD operate captive semiconductor packaging facilities to secure supply continuity.
- Tier-1 Suppliers:Bosch and Continental AG aggregate multi-OEM demand to amortize functional safety certification costs across platform variants.
- Aftermarket Providers:Diagnostic tool compatibility determines addressable scope in repair networks.
- Vehicle Assemblers:Contract manufacturers in Thailand and Mexico source control modules through open-architecture procurement.
Tier-1 Suppliers lead by production volume. OEMs are gaining share fastest through backward integration.
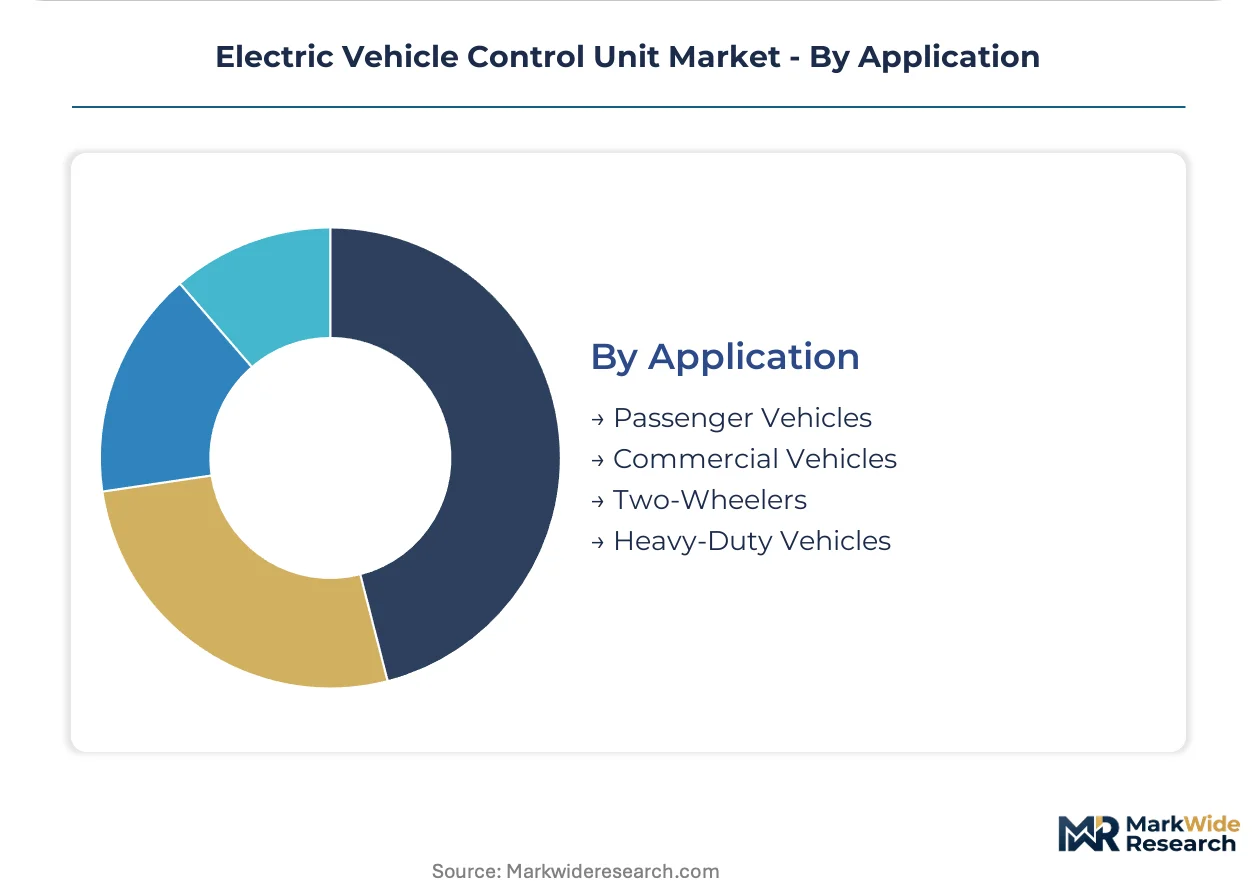
Application:
Vehicle mass and duty cycle dictate thermal management complexity and semiconductor specification.
- Passenger Vehicles:Integrated domain controllers consolidate battery, motor, and thermal functions into single compute enclosures. China's MIIT software-defined vehicle mandates are accelerating this consolidation in domestic and export programs.
- Heavy-Duty Vehicles:800V architectures with liquid-cooled inverter stages sustain continuous power delivery for long-haul trucking. North American fleet operators are specifying these systems for depot-charging corridor deployment.
- Commercial Vehicles:Route-predictive energy management is becoming standard in European urban delivery specifications.
- Two-Wheelers:Simplified control architectures with passive cooling dominate South Asian volume production.
Passenger Vehicles lead the category by unit volume. Heavy-Duty Vehicles show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of EV control units while Germany and the United States absorb premium volumes for passenger and commercial vehicle integration. Production clusters concentrate around semiconductor packaging capabilities and automotive OEM assembly corridors.
China
Domestic OEMs are scaling 800V platform procurement for export certification to Europe and Southeast Asia. MIIT mandates on software-defined vehicle architectures and encrypted over-the-air update pipelines are reshaping supplier qualification requirements. The Yangtze River Delta anchors control unit assembly investments serving BYD and Tesla Shanghai export programs.
Germany
Premium passenger vehicle programs drive integrated domain controller demand from BMW, Mercedes-Benz, and Volkswagen. KBA type-approval processes and ECHA REACH material restrictions constrain thermal interface component selection for suppliers. Baden-Württemberg and Bavaria host Bosch and Continental AG development centers feeding European and North American OEM supply chains.
United States
Heavy-duty truck fleet electrification is consolidating vendor relationships around single-source powertrain control suppliers for depot-charging corridor deployment. NHTSA crashworthiness electrical isolation rules and EPA fleet efficiency mandates shape precision energy management requirements. Michigan and Texas anchor control module integration facilities serving Detroit Three and Tesla Austin manufacturing.
Japan
Hybrid control architectures retain share in cost-sensitive two-wheeler applications where analog redundancy satisfies domestic regulations. METI residential energy programs mandate bidirectional V2H capability in onboard charger specifications. The Kanto region around Tokyo concentrates Denso and tier-one supplier engineering resources for real-time operating system development.
India
Two-wheeler manufacturers retain hybrid control approaches to satisfy cost targets under PLI scheme localization requirements. BIS safety standards and CEA grid integration protocols are accelerating domestic assembly investments for compact car export programs. Gujarat and Tamil Nadu are attracting control module fabrication to serve Southeast Asian and African markets.
Electric Vehicle Control Unit Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the EV control unit landscape. Tier-one automotive suppliers leverage multi-OEM demand aggregation to amortize ISO 26262 certification costs across platform variants. Three strategic archetypes dominate: integrated powertrain conglomerates with captive semiconductor capabilities, domain controller specialists with software stack ownership, and open-architecture module vendors serving fleet disintermediation trends. Competitive moves center on M&A for silicon carbide semiconductor access and strategic partnerships for thermal-drive-charging integration.
Among diversified conglomerates, Bosch and Continental AG exemplify the integrated powertrain archetype with in-house packaging capabilities and European supply relationships. Tesla occupies a distinct position through proprietary vertical stack control over charging, thermal, and drive systems. These three anchors represent divergent strategic bets on domain consolidation versus functional specialization.
| Leading Market Players |
|---|
| ZF |
| Denso |
| Tesla |
| Inovance Automotive |
| Continental AG |
| BYD |
| BorgWarner |
| NXP Semiconductors |
| Bosch |
| Others |
Value Network & Pricing Analysis
Passenger vehicle OEMs in Germany and China anchor procurement volume for integrated domain controllers, concentrating pricing power among tier-one suppliers with ISO 26262 certification and silicon carbide packaging capabilities. This buyer concentration enforces three-tier pricing stratification across premium 800V architectures, standard 400V passenger platforms, and cost-optimized two-wheeler modules.
Pricing Analysis
Cost-down pressure on standard 400V motor controllers accelerates because silicon carbide inverter adoption in premium segments is forcing legacy insulated-gate bipolar transistor suppliers to absorb margin compression. Pricing stratifies across premium, standard, and economy tiers based on ASIL-D certification grade and volume scale, with two-wheeler manufacturers in India exhibiting highest price sensitivity due to PLI scheme localization targets. Battery management systems command lowest buyer price elasticity given cell balancing complexity and safety liability exposure.
Supply Chain Analysis
Refurbishment flows for end-of-life battery management systems are emerging in European markets as ECHA REACH restrictions constrain virgin material access for thermal interface components. Silicon carbide substrate production concentrates in the United States, Japan, and Germany, creating single-source vulnerability for inverter-grade wafers. The supply chain draws from copper busbar suppliers in China, semiconductor packaging facilities in South Korea, and specialized thermal materials from European chemical processors. Distribution runs through tier-one supplier consolidation points in Baden-Württemberg and the Yangtze River Delta.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
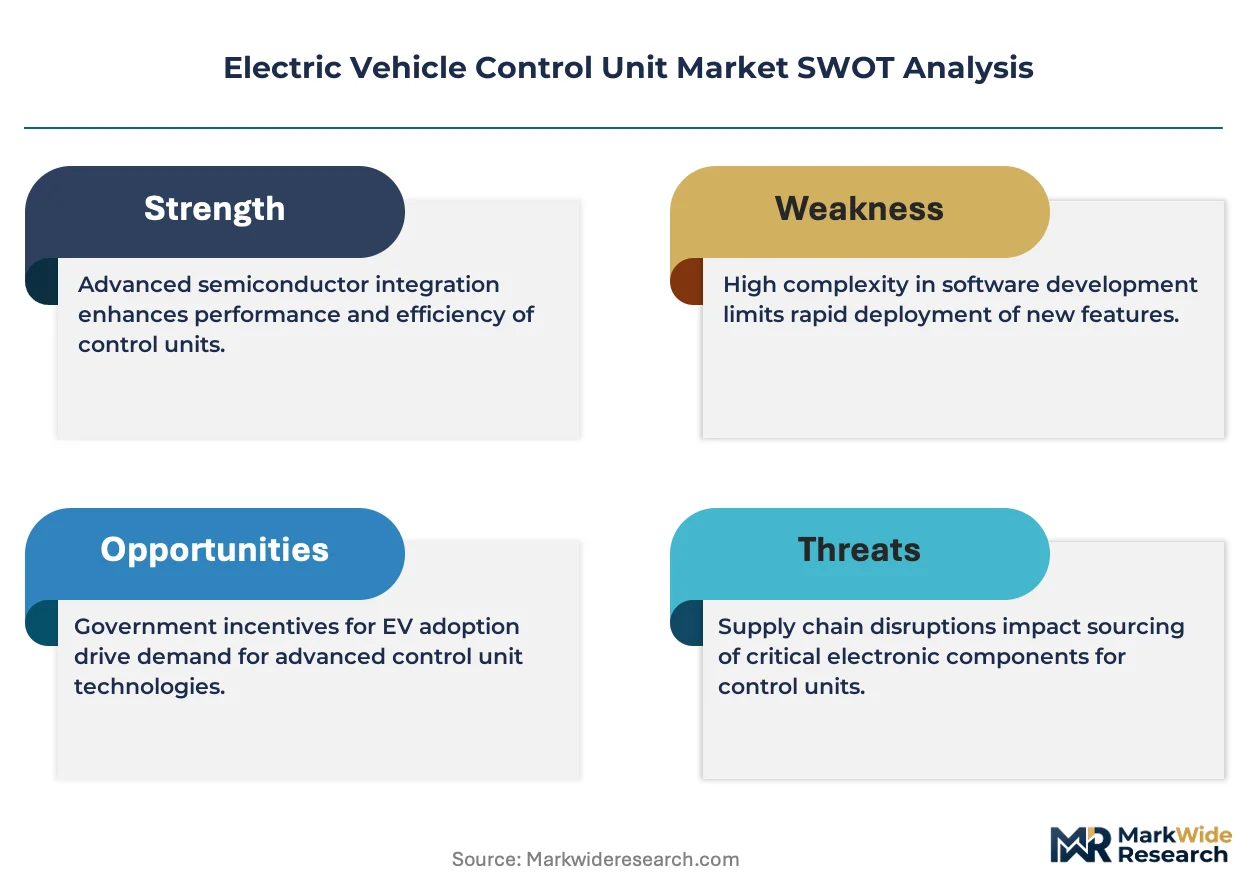
This market functions as a cost-of-compliance story where China's MIIT software-defined vehicle mandates erect barrier-to-entry moats for suppliers with encrypted over-the-air update capabilities and redundant computing core architectures.
For Market Incumbents: Deploy captive semiconductor packaging investments to defend against silicon carbide substrate supply bottlenecks threatening production continuity. Consolidate motor control and battery management functions into unified domain controllers to capture margin from architecture simplification, while accelerating ISO 26262 ASIL-D certification pipelines to outpace validation cycle delays locking in competitor design choices.
For New Entrants and Emerging Players: Launch via open-architecture software stacks targeting North American commercial vehicle fleet operators disintermediating traditional tier-one supplier relationships. Penetrate India's two-wheeler control module assembly under PLI scheme incentives, with Gujarat and Tamil Nadu offering lowest landed cost for Southeast Asian export programs. Lead with thermal-drive-charging integration specialization for 800V platform premium positioning.
For Investors and Strategic Acquirers: The window for entry favors domain controller specialists with software stack ownership and functional safety engineering talent concentration in Germany or Japan. Long-term viability hinges on acquisition targets possessing silicon carbide inverter design capabilities and MIIT GB standard pre-certification. Monitor China export certification volumes to Europe as early inflection signal for platform consolidation winners.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Semiconductor Access | Secures substrate supply from specialized foundries in Germany and Japan for 800V traction systems. |
| Software-Defined Vehicle Investment | Aligns control architectures with MIIT GB standards mandating encrypted over-the-air update pipelines. |
| Thermal-Drive-Charging Integration | Commands premium positioning by coordinating battery thermal management with DC fast charging profiles. |
| Functional Safety Certification Acceleration | Compresses ISO 26262 ASIL-D validation cycles to outpace competitor platform launch timelines. |
| Commercial Vehicle Fleet Partnership | Captures volume contracts from North American operators consolidating vendor relationships around single-source suppliers. |
Research Methodology
Multi-period observation of silicon carbide inverter adoption rates, MIIT software-defined vehicle mandate implementation timelines, and tier-one supplier consolidation patterns anchored the trend analysis, supplemented by interviews with OEM platform engineers, Tier 1 supplier procurement leads, functional safety certification auditors, and commercial vehicle fleet operations managers. Secondary validation drew from vehicle production databases, semiconductor packaging capacity disclosures, IHS Markit registration data, and customs records for control module trade flows. Bottom-up segment sizing triangulated against top-down OEM procurement budget analysis.
Segment-weighting across vehicle class, propulsion architecture, voltage tier, and regional production cluster shaped the analytical framework. CAGRs were derived from installed base evolution and content-per-vehicle trajectories across the projection horizon. Forecast inputs incorporated silicon carbide penetration curves in 800V platforms, PLI scheme localization requirements in India, and ECHA REACH material restriction compliance costs in European supply chains.
Silicon carbide substrate supply disruptions, MIIT regulatory timeline acceleration, and cybersecurity certification complexity extensions are the dominant revision risks that could compress or extend the projection horizon. Practitioners should monitor China-Europe export certification volumes, silicon carbide foundry capacity announcements, and UN R155 homologation processing times for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Vehicle on Board Charger Market
Electric Vehicles
Special Purpose Electric Vehicle Market
Electric Vehicles
Belgium Solar E-Bike Market
Electric Vehicles
Electric Vehicle Helmet Market
Electric Vehicles
US Electric Vehicle Market
Electric Vehicles
Train Battery Market
Electric Vehicles
E-Bike Lithium-Ion Battery Market
Electric Vehicles
India E-Bike Market
Electric Vehicles
Commercial Electric Vehicle Dynamic Braking Resistors Market
Electric Vehicles
US Automotive High Performance Electric Vehicle Market
Electric Vehicles
Global Automotive High-Performance Electric Vehicles Market
Electric Vehicles
Luxury Electric Vehicle Market
Electric Vehicles
Middle-East and Africa Electric Vehicle (EV) Fluids Market
Electric Vehicles
France Solar E-Bike Market
Electric Vehicles
Fuel-Cell Electric Vehicle Insulation Market
Electric Vehicles
Global Automotive Inductive Wireless Charging Systems Market