
 Self Driving Car Market | 2026-2036
Self Driving Car Market Size, Share, and Industry Trends Forecast 2026-2036
Self Driving Car Market Intelligence
The ISO 26262 functional safety standard is unwinding the traditional automotive development cycle, demanding new verification and validation processes. Waymo leverages its extensive data from billions of miles of simulation to refine its driving software. NVIDIA specializes in providing the core AI computing hardware and software stacks for autonomous systems. Concurrently, Tesla positions its integrated hardware and software approach as a key differentiator for its consumer vehicles.
A self-driving car is a vehicle equipped to operate without human intervention by using a suite of sensors like Lidar, radar, and cameras. These systems create a 360-degree view to navigate and react to the environment. Level 4 autonomy, which allows for full self-driving in designated areas, constitutes the most significant long-term commercial opportunity. Within the technology stack, sensor fusion algorithms are critical for creating a reliable and redundant perception model from multiple data streams.
Regulatory frameworks from the US National Highway Traffic Safety Administration (NHTSA) and the European Union's General Safety Regulation are establishing critical safety and testing protocols. In parallel, China's Ministry of Industry and Information Technology (MIIT) is creating national standards to guide domestic development and deployment. Future market leaders will be defined by their ability to achieve certifiable safety at scale across these varied international regulatory landscapes.
Market Dynamics
The central dynamic shaping the self-driving car market is the immense gap between rapid software and sensor advancements and the slower, more deliberative pace of establishing certifiable safety standards and regulatory frameworks across key global jurisdictions.
Growth Catalysts
- Maturing Sensor Technology:Improvements in sensor fusion algorithms, which intelligently combine data from Lidar, radar, and cameras, are creating more reliable and redundant perception systems, directly enabling higher levels of vehicle autonomy.
- Ride-Hailing Economics:The demand from ride-hailing and mobility-as-a-service (MaaS) providers for vehicles with lower operational costs acts as a significant commercial pull, as autonomy promises to eliminate driver-related expenses.
- Government Initiatives:National and municipal-level support, exemplified by China's large-scale smart city projects and dedicated testing zones, provides critical infrastructure and regulatory sandboxes for technology validation and deployment.
Market Restraints
- High Component Costs:The substantial cost of core components, particularly high-resolution Lidar sensors and the powerful AI-specific computing hardware required for real-time data processing, remains a structural barrier to mass-market adoption.
- Adverse Weather Performance:A persistent technical limitation is the degraded performance and reliability of perception systems, especially cameras and Lidar, in adverse weather conditions like heavy rain, snow, and dense fog.
- Regulatory Fragmentation:The lack of harmonized safety and testing standards between major markets, including protocols from the NHTSA in the US, the EU's General Safety Regulation, and China's MIIT, complicates global platform development.
Strategic Opportunities
- Autonomous Logistics:Expanding beyond passenger cars into long-haul trucking and last-mile delivery presents a major commercial opportunity, offering clear ROI through fuel efficiency optimization and continuous operation.
- V2X Communication Integration:The convergence of 5G connectivity with vehicle-to-everything (V2X) communication systems opens new possibilities for cooperative perception and collision avoidance, enhancing safety beyond onboard sensors.
- Aftermarket ADAS Upgrades:There is an opportunity to provide advanced driver-assistance systems (ADAS) as retrofits or software upgrades for existing vehicle fleets, creating a new service-based revenue stream and a bridge to full autonomy.
Industry Challenges
- Functional Safety Certification:Navigating the complex and lengthy process to achieve certifiable safety according to standards like ISO 26262 poses a significant operational hurdle, requiring new engineering processes and extensive documentation.
- Massive Data Infrastructure:The operational challenge of collecting, storing, and processing the petabytes of data generated from test fleets and simulations is immense, demanding significant investment in data center and cloud computing resources.
- Building Public Trust:Overcoming public skepticism and liability concerns following any incidents involving autonomous vehicles is a critical non-technical challenge that directly impacts the pace of regulatory approval and widespread adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self Driving Car Market |
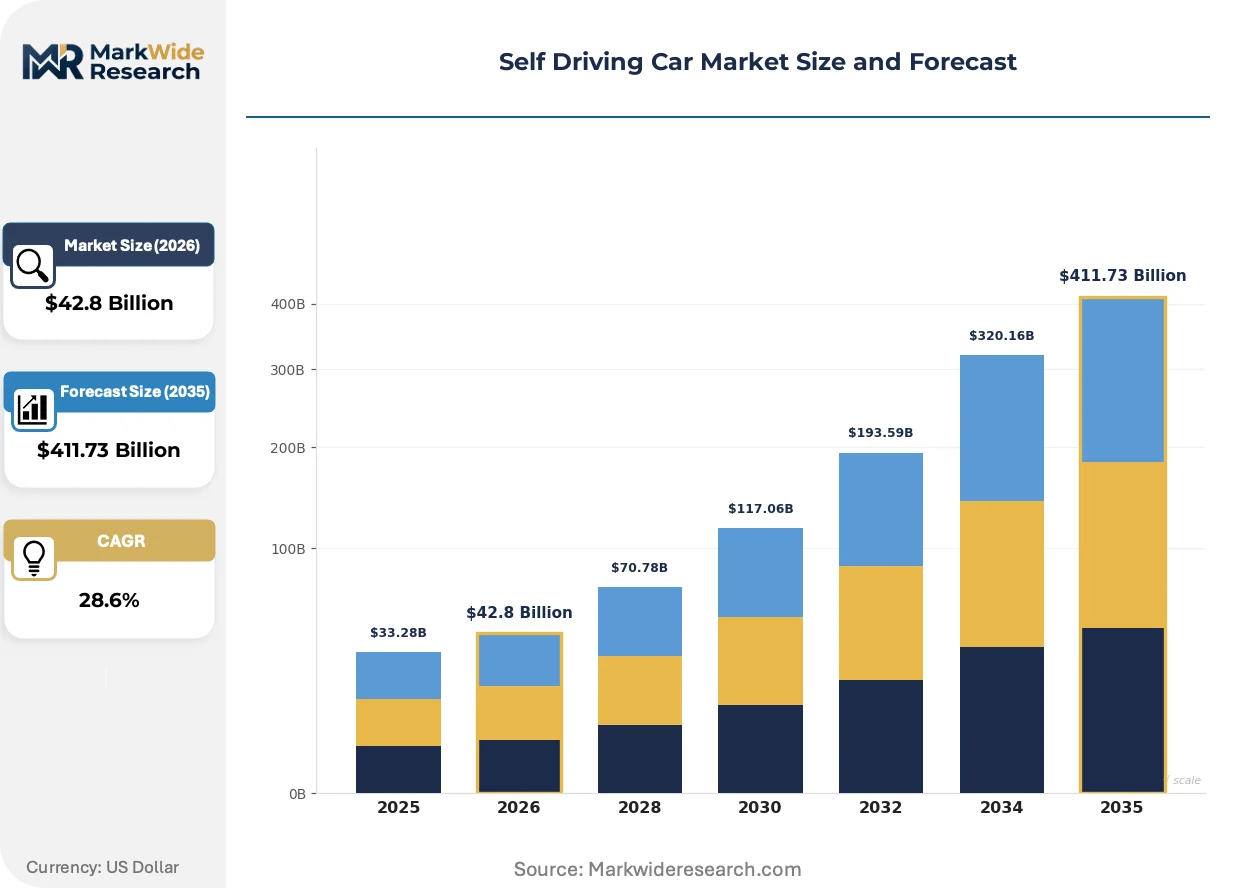
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $411.73 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Passenger Cars, Light Trucks, SUVs, Commercial Vehicles Technology: Sensor Fusion, Deep Learning, Lidar, Computer Vision End User: Fleet Operators, Ride Hailing Services, Logistics Companies, Personal Users Level of Autonomy: Level 1, Level 2, Level 3, Level 4 |
| Companies Covered | Waymo, Tesla, Cruise, Zoox, NVIDIA, Motional, Pony.ai, Mercedes-Benz Group, Aptiv, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self Driving Car Market Strategic Shifts & Innovations
Software-defined architectures are fundamentally changing vehicle development, shifting value from mechanical components to updatable software and centralized computing. This trend prioritizes the creation of scalable, certifiable systems capable of supporting progressively higher levels of automation over the vehicle's lifecycle.
Lidar (Light Detection and Ranging) technology functions by emitting laser pulses to generate a precise, three-dimensional map of the vehicle's environment. Automakers and robotaxi developers are integrating solid-state Lidar due to its improved durability and lower cost profile compared to older mechanical scanners. The core sensor technology itself is miniaturizing, which permits seamless integration into vehicle body panels, headlights, and rooflines.
The European Union's General Safety Regulation (GSR) is creating a new baseline for vehicle safety technology. This rule mandates a suite of advanced driver-assistance systems (ADAS) in all new vehicle models, effectively standardizing features like intelligent speed assistance and emergency lane-keeping. As a result, European automakers are accelerating their integration of camera and radar systems, which form the building blocks for future Level 4 autonomous systems.
A clear behavioral shift toward transportation-as-a-service (TaaS) models is altering vehicle procurement patterns in dense urban centers. This trend deemphasizes personal car ownership in favor of subscription or pay-per-use access to mobility, disrupting the traditional automaker-to-consumer sales channel. Fleet operators for ride-hailing and car-sharing services are becoming the primary customers for autonomous vehicles, a pattern most visible in major cities across North America and Europe.
Self Driving Car Market Segmentation
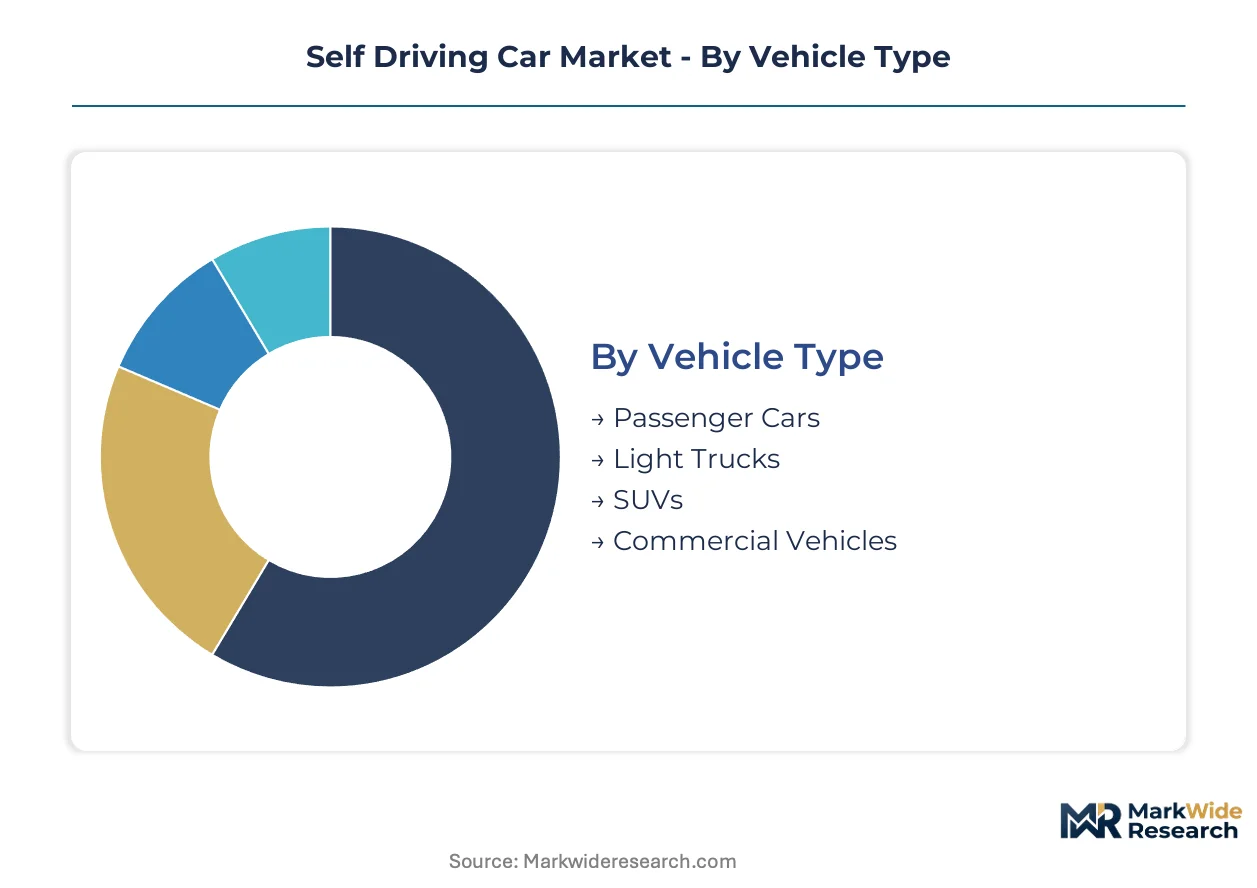
The self-driving car market delineates into several key segments, reflecting diverse technological approaches, application areas, and levels of autonomous capability. Understanding these distinctions is critical for stakeholders to navigate the complex landscape of regulatory compliance and technological adoption.
Vehicle Type:
Regulatory differentiation significantly impacts the development and deployment of various vehicle types within the autonomous sector. Different safety standards apply to passenger transport versus heavy-duty commercial operations, influencing design and testing protocols.
- Passenger Cars:These vehicles are designed for individual or small-group transport, focusing on urban and suburban environments. Demand from personal users in major metropolitan areas drives innovation in sensor integration and user interface.
- Commercial Vehicles:This category includes trucks and specialized vehicles used for freight and logistics, primarily on highways or designated routes. Operational cost reductions through driverless operation create a strong commercial pull for these applications.
- Light Trucks:Vehicles like vans and pickups, often used for last-mile delivery or utility services, present unique challenges for autonomous navigation in diverse urban settings.
- SUVs:Sport utility vehicles offer greater payload capacity and versatility, making them suitable for various autonomous applications, including ride-hailing and family transport.
Established volume favors Passenger Cars; emerging adoption favors Commercial Vehicles.
Technology:
The application of advanced technologies forms the bedrock of autonomous driving systems, enabling vehicles to perceive, plan, and act without human input.
- Lidar:This technology uses pulsed laser light to measure distances, generating precise 3D maps of the surrounding environment. Its robust performance in varying lighting conditions makes it essential for high-level autonomy systems.
- Sensor Fusion:This process combines data from multiple sensors, including cameras, radar, and Lidar, to create a comprehensive and redundant perception model. The integration of diverse data streams improves system reliability and object detection accuracy.
- Deep Learning:Artificial intelligence algorithms, particularly neural networks, process vast amounts of sensor data to recognize patterns, predict behaviors, and make real-time driving decisions.
- Computer Vision:This technology extracts meaningful information from digital images and videos captured by cameras, enabling tasks like lane detection, traffic sign recognition, and pedestrian identification.
The integration of Sensor Fusion remains foundational, while Lidar drives advanced capabilities.
End User:
Customer type defines the operational models and specific requirements for autonomous vehicle deployment, influencing vehicle design and service offerings.
- Ride Hailing Services:Companies like Waymo and Cruise utilize autonomous fleets to provide on-demand transportation, aiming to reduce operational costs by eliminating human drivers. The economic incentive for these services is substantial, particularly in dense urban centers.
- Logistics Companies:These firms deploy autonomous trucks and delivery vehicles for freight transport and last-mile delivery, seeking improved efficiency, reduced labor costs, and continuous operation. Regulatory progress in specific corridors accelerates this segment's growth.
- Fleet Operators:This segment includes companies managing large vehicle pools for various commercial purposes, such as corporate shuttles or rental services, seeking optimized asset utilization.
- Personal Users:Individual consumers purchasing autonomous vehicles for private ownership represent a long-term market, driven by convenience and enhanced safety features.
Commercial applications by Ride Hailing Services and Logistics Companies dictate near-term investment.
Level of Autonomy:
The maturity of autonomous driving systems categorizes vehicles based on their human intervention requirements, progressing from driver assistance to full self-driving capabilities.
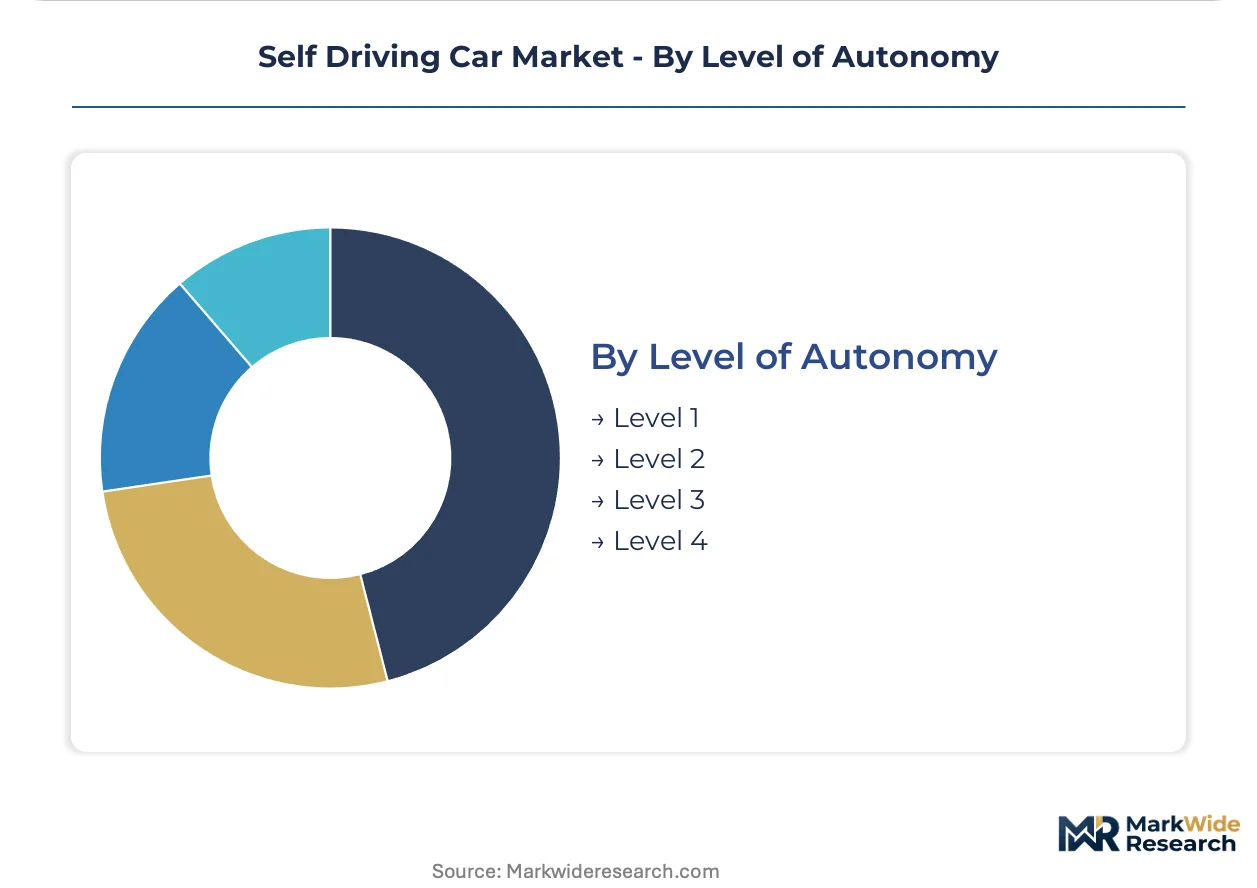
- Level 4:These vehicles can perform all driving tasks under specific conditions or in designated operational design domains without human intervention. This level represents a significant commercial opportunity for robotaxi services.
- Level 2:These systems provide partial automation, offering advanced driver assistance features like adaptive cruise control and lane-keeping assistance, requiring constant driver supervision. European Union regulations are standardizing these features.
- Level 1:Basic driver assistance systems, such as cruise control or automatic emergency braking, assist the driver but do not take control of the vehicle.
- Level 3:Conditional automation allows the vehicle to handle most driving tasks in certain environments, but a human driver must be ready to intervene when prompted.
Basic driver assistance (Level 1) sets the foundation, with full autonomy (Level 4) representing the ultimate goal.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer-archetype concentration significantly influences the regional deployment of self-driving car technologies, with ride-hailing services and logistics companies driving initial investment. These commercial operators prioritize areas with supportive regulatory frameworks and high population density. Urban centers and designated testing zones are therefore becoming early adoption hubs for autonomous vehicle development.
United States
The demand for robotaxis and autonomous delivery services propels market growth in major US cities. The National Highway Traffic Safety Administration (NHTSA) establishes safety guidelines and testing protocols for autonomous vehicles. California and Arizona serve as key development and deployment zones, attracting significant investment in autonomous driving technology.
China
Robust government initiatives and smart city projects fuel the expansion of autonomous mobility solutions. China's Ministry of Industry and Information Technology (MIIT) actively develops national standards for intelligent connected vehicles. Large-scale testing and deployment efforts concentrate in cities like Beijing and Shanghai, supported by extensive infrastructure.
Germany
Automotive manufacturers and technology providers in Germany drive innovation in high-level autonomous driving systems. European Union's General Safety Regulation (GSR) mandates advanced driver-assistance features, influencing development trajectories. Munich and Stuttgart remain central to automotive R&D, focusing on certifiable safety and premium vehicle integration.
Japan
Aging populations and labor shortages stimulate demand for autonomous public transport and logistics solutions. Japan's Ministry of Economy, Trade and Industry (METI) supports the development of autonomous vehicle technology through various programs. Tokyo and other major metropolitan areas are piloting autonomous shuttle services and delivery robots.
South Korea
Rapid technological advancement and a strong IT infrastructure underpin the nation's self-driving car market. South Korea's regulatory bodies are establishing frameworks for autonomous vehicle testing and commercialization. Seoul and Pangyo Techno Valley act as primary innovation centers, fostering collaboration between tech firms and automakers.
Self Driving Car Market Key Industry Players
Player mix skews toward established automotive manufacturers and specialized technology developers, creating a tiered market structure. This landscape features a blend of companies focused on full vehicle integration and those specializing in critical software and hardware components. Strategic partnerships and technology licensing are dominant competitive moves, enabling broader market penetration and shared development costs.
Specialists in autonomous driving software and hardware, such as NVIDIA, provide foundational computing platforms and AI stacks for the industry. Companies like Waymo exemplify the dedicated robotaxi operator archetype, leveraging extensive real-world and simulated driving data for system refinement. Tesla, on the other hand, represents an integrated approach, developing proprietary hardware and software for its consumer vehicles.
| Leading Market Players |
|---|
| Waymo |
| Tesla |
| Cruise |
| Zoox |
| NVIDIA |
| Motional |
| Pony.ai |
| Mercedes-Benz Group |
| Aptiv |
| Others |
Cost & Logistics Intelligence
Long-term supply agreements for specialized sensors and AI computing hardware lock in both supply access and price visibility for autonomous vehicle developers. These forward contracts mitigate volatility in component costs.
Pricing Analysis
Cost-plus contracts, often indexed to raw material costs for semiconductor fabrication, govern the pricing of critical AI processors. The subscription pricing model dominates for software stacks and mapping services, reflecting ongoing updates and data provision. Price differentiation arises from certification level, particularly ISO 26262 compliance, and the volume scale of procurement. Pricing softness stems from intense competition among sensor manufacturers and software providers. Commercial fleet operators are the most price-sensitive buyers, while premium passenger vehicle OEMs exhibit less sensitivity for advanced features.
Supply Chain Analysis
China and South Korea produce a substantial share of the world's Lidar components and AI-specific semiconductors. The global supply chain draws from specialized foundries for advanced chips and optical sensor manufacturers. Raw material dependencies include rare earth elements for magnets in electric motors and specialized glass for camera lenses. Single-source vulnerability for high-performance computing hardware presents a structural risk. Distribution runs through a tiered supplier network, with Tier 1 suppliers integrating components into modular systems for vehicle manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a significant service-attach opportunity, with recurring software updates and feature subscriptions expanding faster than the initial vehicle hardware sales. Continuous software refinement for autonomous capabilities generates ongoing revenue streams for developers.
For Market Incumbents: Fortify core intellectual property in sensor fusion algorithms and AI decision-making to counter emerging software-centric challengers. Invest in vertical integration into critical component manufacturing to mitigate supply chain risks, especially for high-resolution Lidar and advanced computing units. The threat of regulatory fragmentation demands robust, adaptive validation platforms. Prioritize R&D in all-weather perception systems to expand operational design domains.
For New Entrants and Emerging Players: Differentiate on specialized operational design domains, such as autonomous logistics for specific industrial campuses or last-mile delivery in controlled urban zones. Target the commercial fleet operator segment, which prioritizes clear return on investment and operational efficiency. A go-to-market angle focusing on purpose-built, cost-optimized autonomous platforms for specific B2B applications offers a penetrable entry point.
For Investors and Strategic Acquirers: Software and AI algorithm specialists represent a key acquisition target archetype, offering long-term viability by owning the scalable intelligence layer. These firms possess proprietary data sets and machine learning models that are difficult to replicate. A signal to watch is the successful deployment of Level 4 autonomy in multiple, diverse urban environments, indicating maturity and scalability. This demonstrates the ability to navigate complex real-world scenarios.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Enables continuous feature upgrades and over-the-air performance enhancements for autonomous systems. |
| Sensor Technology Miniaturization | Facilitates seamless integration into vehicle designs, reducing aesthetic and aerodynamic impact. |
| Strategic Partnership with Mapping Providers | Ensures access to high-definition maps crucial for Level 4 autonomous navigation. |
| Certifiable Safety Platform Development | Accelerates regulatory approval and builds public trust in autonomous driving systems. |
| Fleet Management Software Integration | Optimizes operational efficiency and utilization rates for autonomous ride-hailing services. |
Research Approach
A standing panel of automotive engineers, AI architects, regulatory affairs specialists, and fleet operations managers provided ongoing calibration and validation for primary data. This involved in-depth interviews and expert consultations, complemented by extensive secondary research from industry reports, government publications, and academic studies. Bottom-up data collection was triangulated with top-down market sizing to ensure accuracy.
Consistency checks against external benchmarks and established industry forecasts validated the quantitative model outputs across the analysis window. The analytical framework modeled segmentation dimensions including vehicle type, technology, end-user, and level of autonomy, alongside regional adoption patterns. Compound annual growth rates were derived from historical trends and projected technological advancements. Key forecast inputs included sensor cost trajectories and regulatory approval timelines.
Decision-makers should treat outputs as directional under current regulatory frameworks and technological adoption rates; material deviation would warrant model refresh. Forecasts reflect assumptions regarding Lidar cost reductions and the pace of public trust building. Unforeseen breakthroughs in AI or significant policy shifts represent specific risk factors. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Battery-Electric Self-Driving Car Market
Autonomous Vehicles
Semi Autonomous and Autonomous Vehicles Market
Autonomous Vehicles
Automated Truck Technology Market
Autonomous Vehicles
Self-Balancing Mobility Market
Autonomous Vehicles
India Autonomous Navigation Market
Autonomous Vehicles
Autonomous Parking System Market
Autonomous Vehicles
North America Adaptive Steering Market
Autonomous Vehicles
Europe IoT Connected Cars Market
Autonomous Vehicles
Autonomous Vehicle Simulation Software Market
Autonomous Vehicles
Global Robot Cars and Trucks Market
Autonomous Vehicles
L4 Autonomous Driving Market
Autonomous Vehicles
Vehicle Intelligence System Market
Autonomous Vehicles
Singapore Autonomous Navigation Market
Autonomous Vehicles
Autonomous Driving Component Market
Autonomous Vehicles
Autonomous Freight Trains Market
Autonomous Vehicles
Semi-Autonomous and Autonomous Bus Market