
 High Temperature Ceramics Market | 2026-2036
High Temperature Ceramics Market Size, Share, and Industry Trends Forecast 2026-2036
High Temperature Ceramics Market Outlook
Ultra-high-purity grade specifications is rotating demand toward advanced processing capabilities. Morgan Advanced Materials leverages vertical integration across raw material refining and finished component fabrication. Saint-Gobain Performance Ceramics & Refractories anchors European supply through specialized melting and casting operations. CoorsTek Inc. dominates North American technical ceramics with concentrated capacity for semiconductor-grade alumina.
High temperature ceramics are inorganic, non-metallic materials engineered to maintain structural integrity above 1,000°C, typically produced through sintering of oxides, nitrides, or carbides under controlled atmospheric conditions. These materials serve critical functions as thermal barriers, electrical insulators, and wear-resistant surfaces in extreme environments. Silicon nitride leads aerospace applications due to fracture toughness and thermal shock resistance, while alumina powders command the largest volume share in semiconductor manufacturing substrates. Mullite furnace linings represent a mature, replacement-driven segment with compressed margins, whereas zirconia coatings in energy turbines capture expanding margin pools from performance-linked contracts.
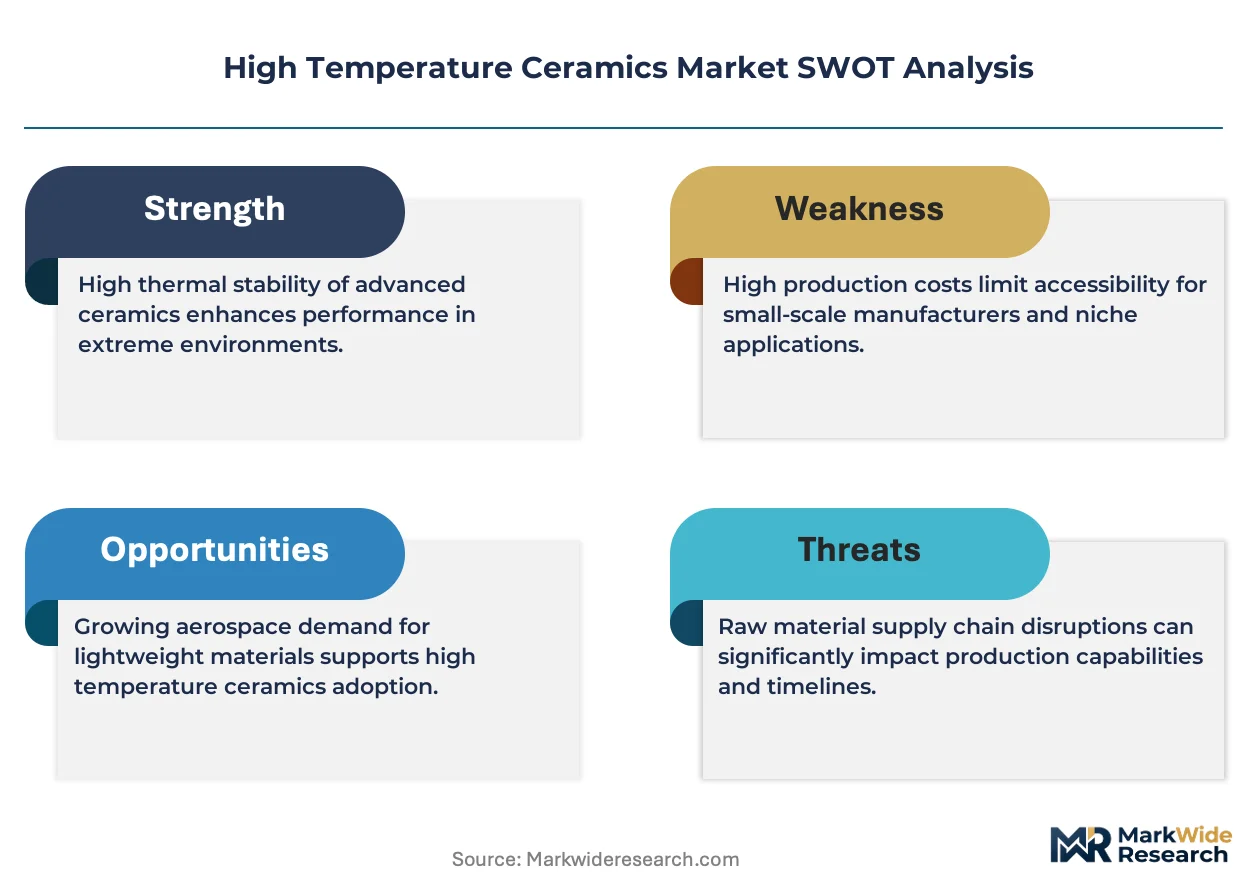
EPA industrial emissions rules and OSHA workplace exposure limits are tightening allowable contaminant thresholds, forcing furnace operators toward certified refractory upgrades. REACH compliance in Europe and FDA material safety requirements for medical-device-adjacent electronics further constrain supplier qualification. Stakeholders must monitor regulatory divergence between jurisdictions, as dual certification burdens will reshape competitive cost structures and determine which producers retain cross-border access.
Market Dynamics
EPA emissions standards for industrial furnaces are compressing refractory replacement cycles and forcing certified upgrades across North American manufacturing bases. This regulatory pressure is redistributing procurement budgets toward qualified suppliers capable of documented compliance.
Growth Catalysts
- Silicon nitride turbine components:Aerospace manufacturers are expanding procurement of fracture-tough ceramic rotors and vanes for next-generation engines.
- REACH compliance mandates:European furnace operators must replace legacy linings with certified low-emission refractories, accelerating upgrade timelines.
- German precision ceramics clusters:Concentrated tooling expertise around automotive and semiconductor manufacturers is pulling advanced alumina and zirconia demand.
Market Restraints
- Rare earth oxide volatility:Yttria and ceria price swings destabilize zirconia coating cost structures for energy turbine producers.
- Chinese powder supply concentration:Overreliance on Shanxi and Henan provinces for high-purity alumina feedstock creates geographic vulnerability.
- Sintering temperature ceilings:Conventional gas-fired kilns cannot achieve ultra-high-purity grades without electric furnace retrofits.
Strategic Opportunities
- India's PLI scheme for semiconductors:Domestic fab construction is creating first-mover demand for indigenous ceramic substrate supply.
- Hydrogen combustion linings:Furnace operators retrofitting for hydrogen fuel need thermal shock-resistant mullite grades.
- Additive manufacturing convergence:Binder jet printing of silicon carbide preforms enables near-net-shape turbine component production.
Industry Challenges
- ISO 9001 and AS9100 certification timelines:Aerospace qualification cycles extend 18-24 months, freezing out unproven suppliers.
- Electric kiln capex intensity:Inert atmosphere sintering infrastructure requires capital deployment that mid-tier producers struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Temperature Ceramics Market |
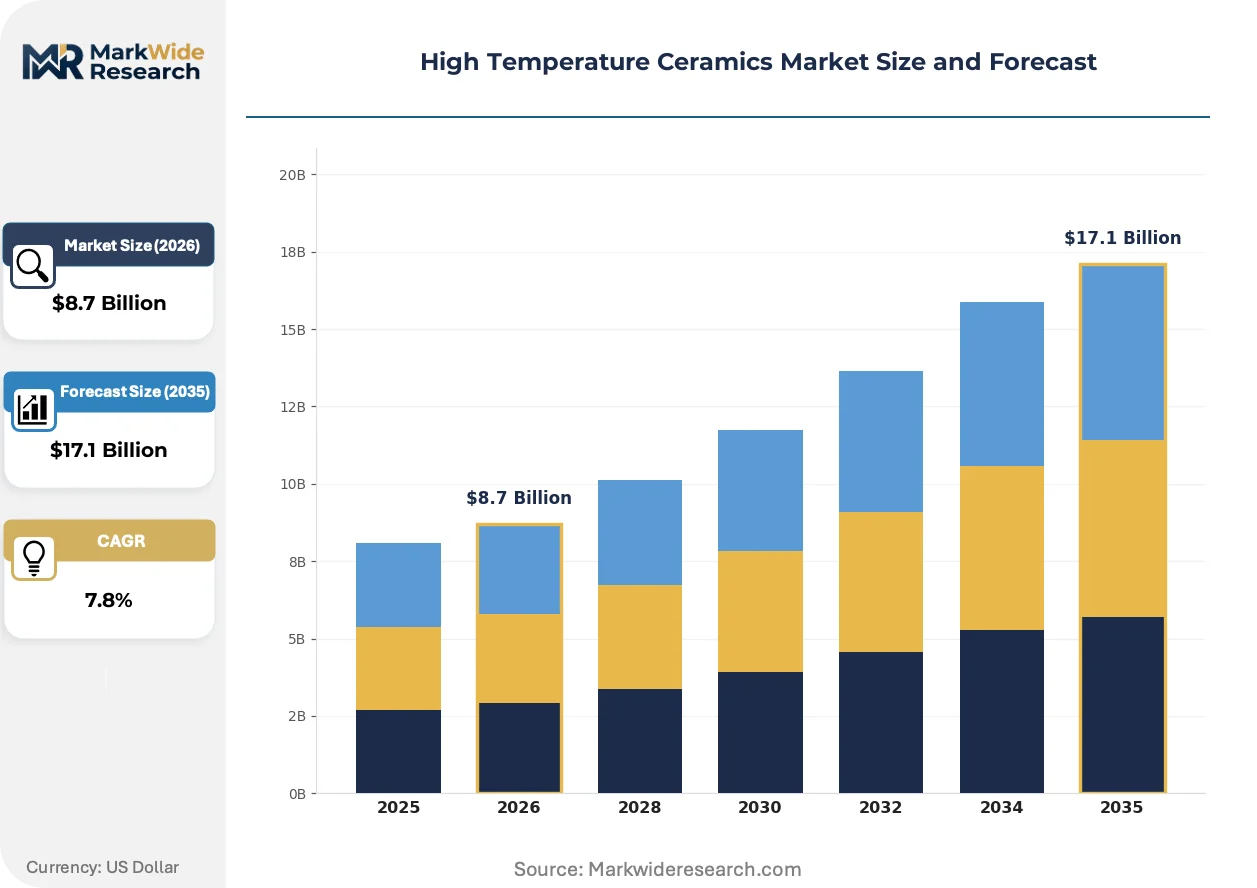
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alumina, Zirconia, Silicon Nitride, Mullite Application: Aerospace Components, Industrial Furnace Linings, Electrical Insulation, Semiconductor Manufacturing Form: Powders, Ceramics, Coatings, Composites End User: Aerospace, Electronics, Automotive, Energy |
| Companies Covered | Morgan Advanced Materials, Saint-Gobain Performance Ceramics & Refractories, CoorsTek Inc., CeramTec GmbH, 3M Company, Kyocera Corporation, ZIRCAR Ceramics Inc., COI Ceramics Inc., U.S. Ceramics LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Temperature Ceramics Market Strategic Shifts
Advanced processing capabilities are resegmenting competitive tiers as purity specifications tighten across aerospace, semiconductor, and energy applications. Technical differentiation now hinges on atmospheric control during sintering rather than raw material sourcing alone.
Gas pressure sintering of silicon nitride is displacing conventional hot pressing for aerospace turbine blades by achieving full density with minimal grain boundary phases. GE Aerospace and Rolls-Royce procurement teams have qualified these grades for high-pressure compressor rotors since 2023. The shift is compressing margins for hot-press equipment manufacturers while rewarding furnace operators with inert atmosphere capabilities.
EPA's updated Maximum Achievable Control Technology standards for hazardous air pollutants from refractory manufacturing are forcing kiln emission retrofits across Ohio, Pennsylvania, and Alabama production corridors. Smaller lining producers lacking scrubber infrastructure face operational shutdowns until compliance investment. The rule is accelerating consolidation toward vertically integrated refractory suppliers with captive environmental controls.
Semiconductor toolmakers are unbundling ceramic component procurement from OEM equipment contracts, establishing direct supplier relationships for chamber liners and electrostatic chucks. This disintermediation bypasses traditional equipment vendor markups and enables specification customization for 3nm process nodes. Taiwan and South Korean fabs are leading this pattern, with procurement teams now qualifying secondary ceramic suppliers independently of lithography equipment vendors.
High Temperature Ceramics Market Segmentation
Margin pools in high temperature ceramics concentrate where purity specifications intersect with qualification barriers. Aerospace and semiconductor end users now segment suppliers by atmospheric control capabilities rather than geographic proximity alone.
Product Type:
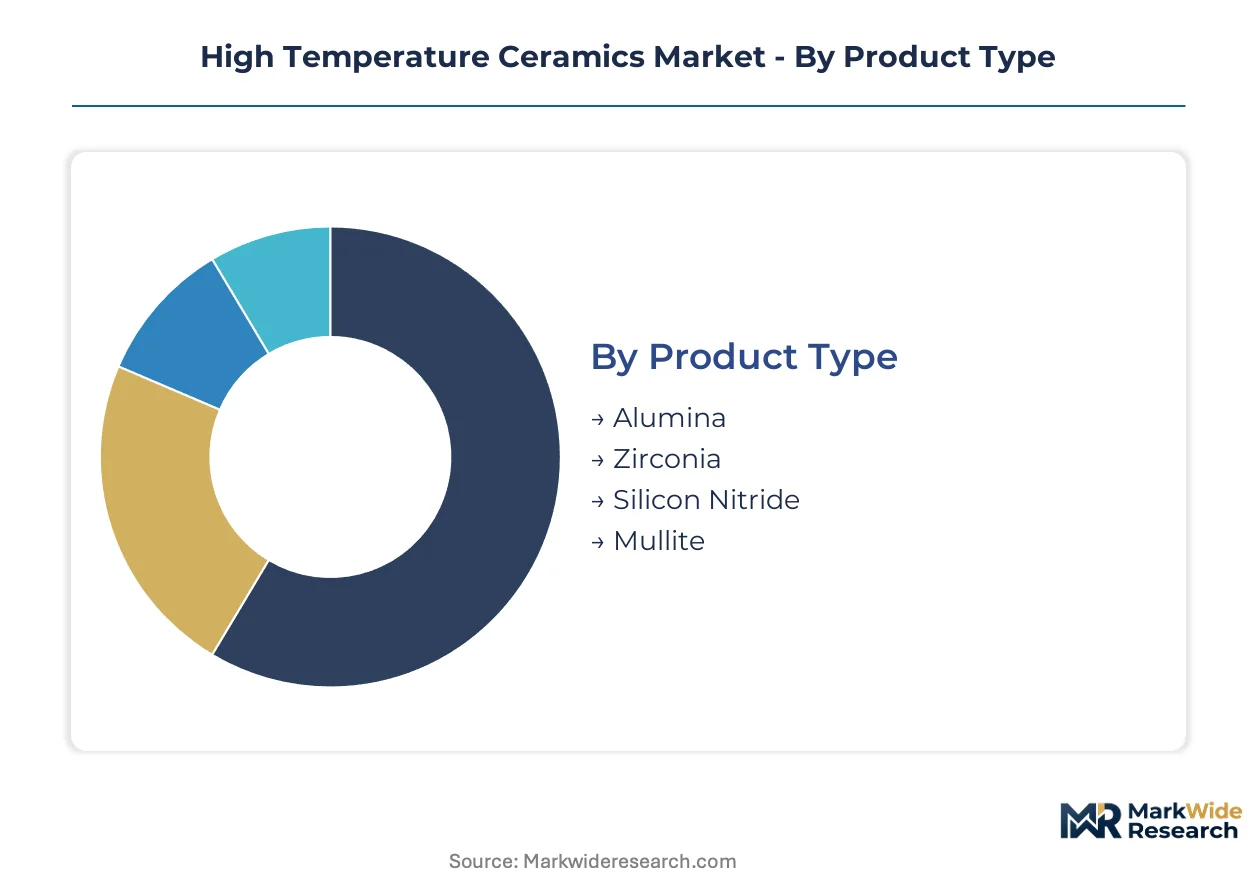
Margin concentration follows thermal shock resistance and fracture toughness specifications, with aerospace-grade silicon nitride commanding premium multiples over commodity alumina.
- Alumina:Alpha-phase aluminum oxide serves as the volume foundation for semiconductor substrates and electrical insulators. Procurement from German precision ceramics clusters and Japanese toolmakers concentrates in 99.9%+ purity grades for 3nm lithography nodes, with REACH compliance costs filtering out mid-tier Chinese suppliers.
- Silicon Nitride:Covalent-bonded ceramic delivers the highest fracture toughness among non-oxide systems. Gas pressure sintering grades qualified by GE Aerospace and Rolls-Royce for high-pressure compressor rotors are displacing hot-pressed alternatives, with inert atmosphere furnace operators capturing expanded margin pools.
- Zirconia:Yttria-stabilized tetragonal polycrystals provide transformation-toughened surfaces for energy turbine thermal barriers. Yttria price volatility from Chinese rare earth supply chains compresses coating producer margins.
- Mullite:Alumina-silica composite dominates mature furnace lining replacement cycles. Compressed margins reflect commodity procurement patterns and compressed EPA-driven replacement timelines.
The dominant share belongs to Alumina, while Silicon Nitride is closing the gap fastest.
Application:
Application segmentation tracks capital deployment intensity, with semiconductor manufacturing equipment driving the steepest specification escalation.
- Aerospace Components:Turbine rotors, vanes, and combustor liners demand AS9100-certified silicon nitride with documented thermal fatigue resistance. GE Aerospace procurement expansion for next-generation engine programs is accelerating qualification timelines.
- Semiconductor Manufacturing:Chamber liners, electrostatic chucks, and focus rings require 99.99%+ purity alumina with controlled metallic contamination. Taiwan and South Korean fabs are disintermediating OEM equipment vendors to establish direct ceramic supplier relationships.
- Industrial Furnace Linings:Refractory replacement cycles are compressing under EPA Maximum Achievable Control Technology standards. Ohio and Pennsylvania producers face scrubber infrastructure investments to maintain operational status.
- Electrical Insulation:High-voltage bushings and spark plug substrates utilize alumina and steatite ceramics. Automotive electrification is pulling demand for 800V-compatible insulating grades.
Semiconductor Manufacturing captures the steepest margin expansion, though Aerospace Components maintains the highest absolute price points.
Form:
Form segmentation reflects processing technology differentiation, with near-net-shape capabilities separating premium from commodity tiers.
- Ceramics:Sintered monolithic components represent the revenue core across all end-use sectors. Hot isostatic pressing and gas pressure sintering capabilities determine supplier tier placement.
- Coatings:Plasma-sprayed and electron-beam physical vapor deposited thermal barriers protect turbine superalloys. Energy sector performance-linked contracts are expanding margin pools beyond material supply into service provision.
- Powders:High-purity feedstock for semiconductor substrates and additive manufacturing preforms concentrates supply in Shanxi and Henan provinces, creating geographic vulnerability.
- Composites:Ceramic matrix composites with silicon carbide fibers enable lightweight turbine components. Binder jet printing of silicon carbide preforms is emerging as a production alternative to chemical vapor infiltration.
Ceramics retains the largest volume position, while Composites is expanding most quickly through additive manufacturing convergence.
End User:
End user segmentation maps to certification burden intensity, with aerospace and medical-adjacent electronics imposing the longest qualification cycles.
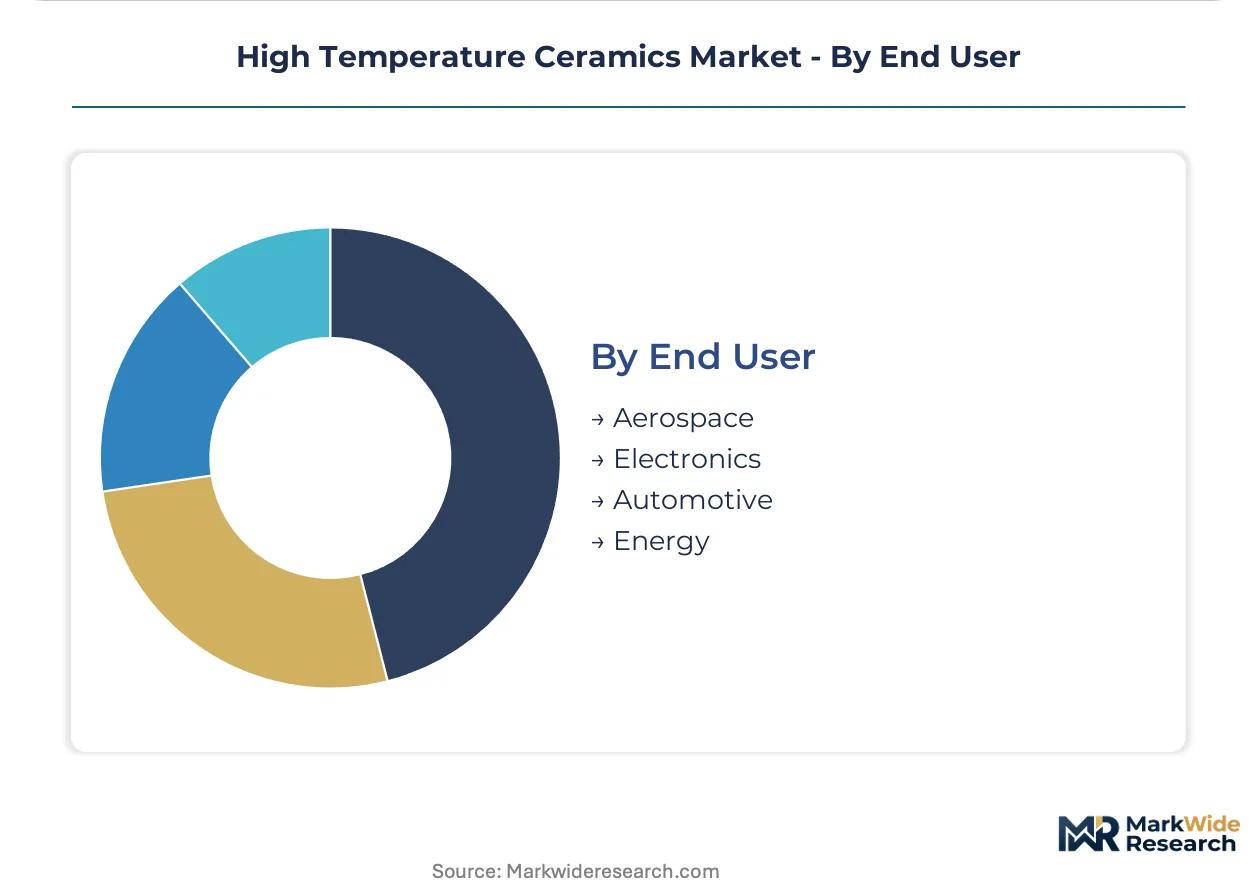
- Aerospace:Engine OEMs and tier-one suppliers drive silicon nitride demand through AS9100 and FAA qualification requirements. 18-24 month certification timelines freeze out unproven entrants.
- Electronics:Semiconductor toolmakers and medical device manufacturers require FDA material safety documentation and ISO 9001 traceability. Direct procurement unbundling from OEM contracts is reshaping supplier relationships.
- Energy:Gas turbine operators and hydrogen furnace retrofitters need thermal shock-resistant mullite and zirconia grades. Performance-linked service contracts are displacing commodity material sales.
- Automotive:Spark plug substrates and electrification insulation components utilize cost-optimized alumina grades. German automotive clusters are pulling precision ceramic demand from local tooling networks.
Aerospace commands the highest entry barriers, while Electronics is gaining share fastest through semiconductor fab construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision ceramics clusters export high-purity alumina substrates to Taiwan and South Korean semiconductor fabs, establishing a critical trade corridor between European raw material refining and Asian manufacturing demand.
United States
EPA Maximum Achievable Control Technology standards are compressing refractory replacement cycles across Ohio and Pennsylvania industrial corridors. The agency's hazardous air pollutant rules force kiln emission retrofits that smaller lining producers cannot fund. Cleveland and Pittsburgh production hubs are consolidating toward vertically integrated suppliers with captive scrubber infrastructure.
Germany
Automotive and semiconductor toolmakers in Bavaria and Baden-Württemberg pull advanced alumina and zirconia demand through precision ceramics clusters. REACH compliance mandates accelerate certified low-emission refractory upgrades across European furnace operators. Stuttgart and Munich tooling networks anchor supply relationships for 3nm lithography node components.
China
Shanxi and Henan provinces concentrate high-purity alumina feedstock supply for global semiconductor substrate production. The country's dual carbon goals are forcing electric furnace retrofits that conventional gas-fired kilns cannot achieve for ultra-high-purity grades. Zhengzhou and Luoyang processing centers face geographic vulnerability from overreliance on domestic powder supply chains.
Japan
Tokyo and Osaka-based toolmakers drive specification escalation for 99.99%+ purity alumina chamber liners and electrostatic chucks. METI industrial standards enforce contamination thresholds that filter mid-tier suppliers from 3nm process node qualification. Nagoya aerospace clusters source AS9100-certified silicon nitride for turbine component programs.
India
The PLI scheme for semiconductors is creating first-mover demand for indigenous ceramic substrate supply as domestic fab construction accelerates. BIS certification requirements for industrial materials constrain rapid supplier qualification. Karnataka and Telangana emerging fab zones are establishing procurement relationships outside traditional equipment vendor channels.
High Temperature Ceramics Market Competitive Environment
Listed leaders compete with private specialists across atmospheric control capabilities and certification infrastructure. The vendor base separates into consolidated refractory suppliers with environmental compliance assets and fragmented ceramic component specialists with niche furnace capabilities. Three archetypes dominate: vertically integrated oxide refiners, inert-atmosphere sintering operators, and precision machining subcontractors. M&A activity concentrates scrubber-equipped production assets, while strategic partnerships bridge raw material refining with finished component fabrication.
Among UK-based material science groups, Morgan Advanced Materials occupies a position reflecting captive supply chain control. Saint-Gobain Performance Ceramics & Refractories anchors European supply through specialized melting operations. CoorsTek Inc. exemplifies the North American technical ceramics archetype with concentrated capacity positioning.
| Leading Market Players |
|---|
| Morgan Advanced Materials |
| Saint-Gobain Performance Ceramics & Refractories |
| CoorsTek Inc. |
| CeramTec GmbH |
| 3M Company |
| Kyocera Corporation |
| ZIRCAR Ceramics Inc. |
| COI Ceramics Inc. |
| U.S. Ceramics LLC |
| Others |
Value Chain & Pricing Dynamics
Electric furnace utilization rates above 85 percent in German precision ceramics clusters compress unit economics for ultra-high-purity alumina, forcing smaller operators toward tolling arrangements or exit. This scale concentration simultaneously elevates price floors for AS9100-certified silicon nitride and erodes margin buffers in commodity mullite linings.
Pricing Analysis
Gas pressure sintering grades for aerospace rotors command substantial premiums over hot-pressed legacy alternatives, while standard alumina substrates for automotive insulation trade near commodity floors. Three-tier pricing structure across premium, standard, and economy levels reflects certification burden differentiation: AS9100 and FDA material safety documentation tiers separate qualified from unqualified supply. Pricing pressure stems from yttria volatility in Chinese rare earth markets, which compresses zirconia coating producer margins. Semiconductor toolmakers exhibit lowest price sensitivity due to contamination threshold requirements, whereas furnace lining procurement teams face acute budget constraints under compressed EPA replacement cycles.
Supply Chain Analysis
Shanxi and Henan province concentration for high-purity alumina feedstock creates single-source vulnerability for global semiconductor substrate production. Raw material flows draw from Chinese oxide refining, German precision machining clusters, and Japanese toolmaker specification setting. Supply chain risk centers on tariff exposure for yttria-stabilized zirconia crossing Pacific routes. Distribution runs through direct procurement relationships that Taiwan and South Korean fabs are establishing outside traditional OEM equipment vendor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Metal matrix composites and advanced superalloys threaten ceramic turbine component incumbents in next-generation engine programs, demanding active substitution defense through performance-linked contracting and qualification speed.
For Market Incumbents: Fortify atmospheric control capabilities through captive inert atmosphere sintering infrastructure rather than tolling dependence. Morgan Advanced Materials and Saint-Gobain demonstrate how backward integration into raw material refining defends margin pools against rare earth oxide volatility. Accelerate AS9100 certification pipelines for emerging aerospace programs before GE Aerospace and Rolls-Royce freeze supplier lists for next-generation rotors. For New Entrants and Emerging Players: BIS fast-track certification for India's PLI semiconductor scheme offers entry path around established Japanese and German qualification barriers. Target hydrogen combustion lining retrofits in European furnace operators where REACH compliance mandates create immediate demand for thermal shock-resistant mullite grades. Position through additive manufacturing convergence for silicon carbide preforms rather than competing on conventional sintering scale. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among scrubber-equipped refractory suppliers with EPA compliance assets and long-term service contracts. Five-to-ten year viability favors electric furnace operators capable of ultra-high-purity grades without gas-fired retrofit limitations. Monitor India's domestic fab construction velocity as inflection indicator for indigenous ceramic substrate supply chain emergence.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Material Refining | Morgan Advanced Materials controls yttria supply chains against Chinese rare earth volatility. |
| Inert Atmosphere Sintering Capacity Expansion | Gas pressure sintering qualification by GE Aerospace rewards furnace operators with premium tier access. |
| AS9100 Certification Fast-Track Investment | Eighteen-month aerospace qualification cycles freeze out competitors without documented thermal fatigue resistance. |
| Hydrogen Combustion Lining Development | European furnace retrofit demand under REACH accelerates thermal shock-resistant mullite adoption. |
| Direct Procurement Relationship Establishment | Taiwan fabs bypass OEM equipment vendor markups through independent ceramic supplier qualification. |
Study Parameters
Cross-validation between primary interviews with refractory plant managers, aerospace procurement leads, semiconductor toolmaker engineers, and EPA compliance officers anchors the qualitative findings against secondary validation. SEC 10-K filings from Morgan Advanced Materials and Kyocera Corporation, ECHA REACH registration databases, and FAA certification records provide triangulation points. Bottom-up capacity utilization data from Ohio and Pennsylvania production corridors converges with top-down trade flow analysis from German precision ceramics clusters.
Sensitivity analysis across yttria price volatility scenarios, electric furnace retrofit adoption curves, and aerospace engine program delays tests forecast robustness. Segmentation dimensions modeled include purity grade tier, atmospheric control capability, end-use certification burden, and regional regulatory framework cluster. CAGRs derive from installed base replacement cycle compression, semiconductor fab construction pipelines, and additive manufacturing technology diffusion curves.
The analysis sits within stated boundaries; outcomes outside sustained EPA enforcement intensity or Chinese dual carbon goal implementation would require recalibration. Practitioners should keep alternative scenarios live as hydrogen furnace retrofit adoption and India's PLI scheme disbursement velocity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Activated Alumina Market
Ceramics
Relaxor Ferroelectric Ceramics Market
Ceramics
Brazil Ceramic Tiles Market
Ceramics
Cerium Carbonate Market
Ceramics
Global Barium Carbonate Market
Ceramics
Mullite Market
Ceramics
Zirconium Dioxide Market
Ceramics
White Fused Alumina Market
Ceramics
Europe Aluminum Oxide Market
Ceramics
Ceramic Binders Market
Ceramics
Lithium Silicate Market
Ceramics
Refractory Material Market
Ceramics
Global Pseudo Boehmite Market
Ceramics
Ball Clay Market
Ceramics
Advanced Ceramic Additives Market
Ceramics
Glazed Ceramic Tile Market