
 Low Calorie Muffins Market | 2026-2036
Low Calorie Muffins Market Size, Share, and Industry Trends Forecast 2026-2036
Low Calorie Muffins Market Analytics
Fitness enthusiasts are redrawing purchasing patterns across the low calorie muffins category, pulling volume away from traditional weight watchers segments. General Mills leverages its R&D infrastructure to sustain innovation pipelines in protein-enriched formats. Grupo Bimbo anchors Latin American production networks while competing in European gluten-free lines through ARYZTA's specialized bakery operations.
Low calorie muffins are formulated baked goods containing reduced caloric density through modified fat systems, alternative sweeteners, and fiber enrichment, typically manufactured via controlled moisture retention processes to preserve texture despite lower sugar and fat content. The product serves commercial and retail channels seeking compliant options for regulated nutrition environments. Gluten-free and protein-enriched product types command premium positioning as manufacturing complexity elevates barriers, while sugar-free formats occupy mainstream retail shelves through supermarket distribution channels. Online retail channels represent the fastest-growing distribution pathway as direct-to-consumer logistics mature for perishable bakery.
FDA nutrition labeling requirements and EFSA health claims regulations constrain formulation choices while creating compliance-based differentiation among producers. USDA organic standards and EU Green Deal sustainability frameworks further shape ingredient sourcing decisions across multinational supply chains. Stakeholders must monitor evolving sweetener approval pathways and clean-label certification thresholds to preserve market access and margin structure.
Market Dynamics
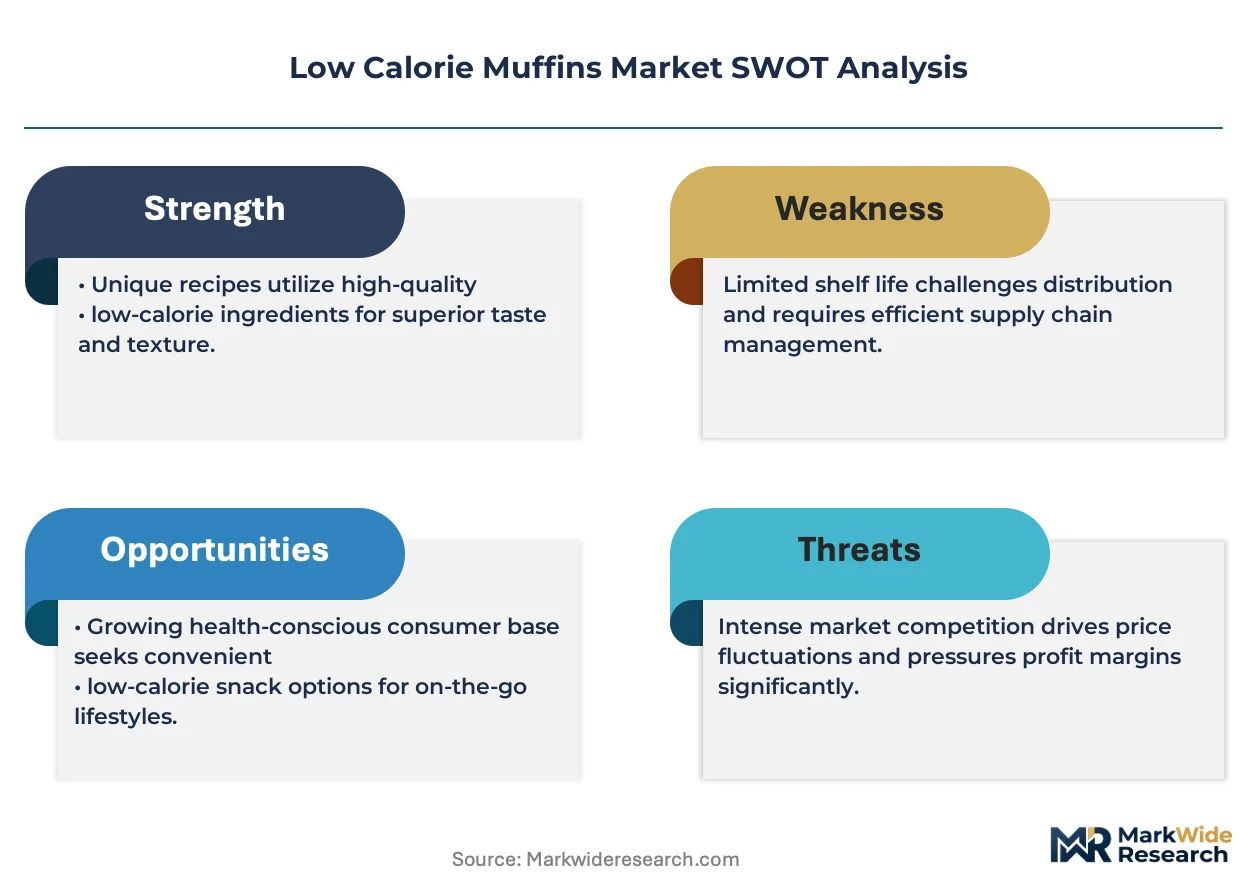
Clean-label reformulation mandates from FDA and EFSA are compressing formulation freedom while forcing ingredient suppliers to validate novel sweetener systems through accelerated approval pathways. This regulatory tightening concentrates R&D budgets among producers with dedicated regulatory affairs infrastructure.
Growth Catalysts
- Corporate wellness procurement mandates:Large employers in the United States now specify sub-200-calorie bakery options in cafeteria contracts, creating institutional demand pull that retail channels follow.
- EU Green Deal agricultural incentives:Sustainability-linked sourcing requirements favor domestic oat and legume fiber suppliers over imported alternatives, reshaping regional supply networks.
- Enzymatic fat-mimetic technologies:Novel lipase-modified starches enable 40% fat reduction without texture degradation, expanding acceptable product formats.
Market Restraints
- Erythritol and allulose price volatility:Bulk alternative sweetener costs fluctuate with corn and sugar beet harvest yields, compressing margin predictability for mid-tier producers.
- Midwestern US ingredient concentration:Three states dominate domestic wheat protein and modified starch production, creating geographic supply vulnerability.
- Moisture-retention technical ceiling:Current hydrocolloid systems hit stability limits beyond 35% sugar reduction, constraining ultra-low-calorie product development.
Strategic Opportunities
- Japanese convenience store channels:Lawson and 7-Eleven Japan are expanding fresh bakery sections with dedicated health-positioned shelving, offering first-mover positioning.
- USDA organic certification tailwinds:Dual organic-low-calorie positioning commands 15-20 point shelf price premiums in natural retail channels.
- Direct-to-consumer frozen subscription models:Flash-frozen muffin delivery bypasses retail slotting fees while capturing recurring revenue through personalized nutrition algorithms.
Industry Challenges
- Clean-label formulation expertise scarcity:Food scientists with simultaneous sweetener chemistry and bakery process engineering experience command premium compensation, constraining mid-cap hiring pipelines.
- Co-manufacturer certification timelines:Third-party bakery facilities face 18-24 month audits for organic and allergen-free dual certification, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Calorie Muffins Market |
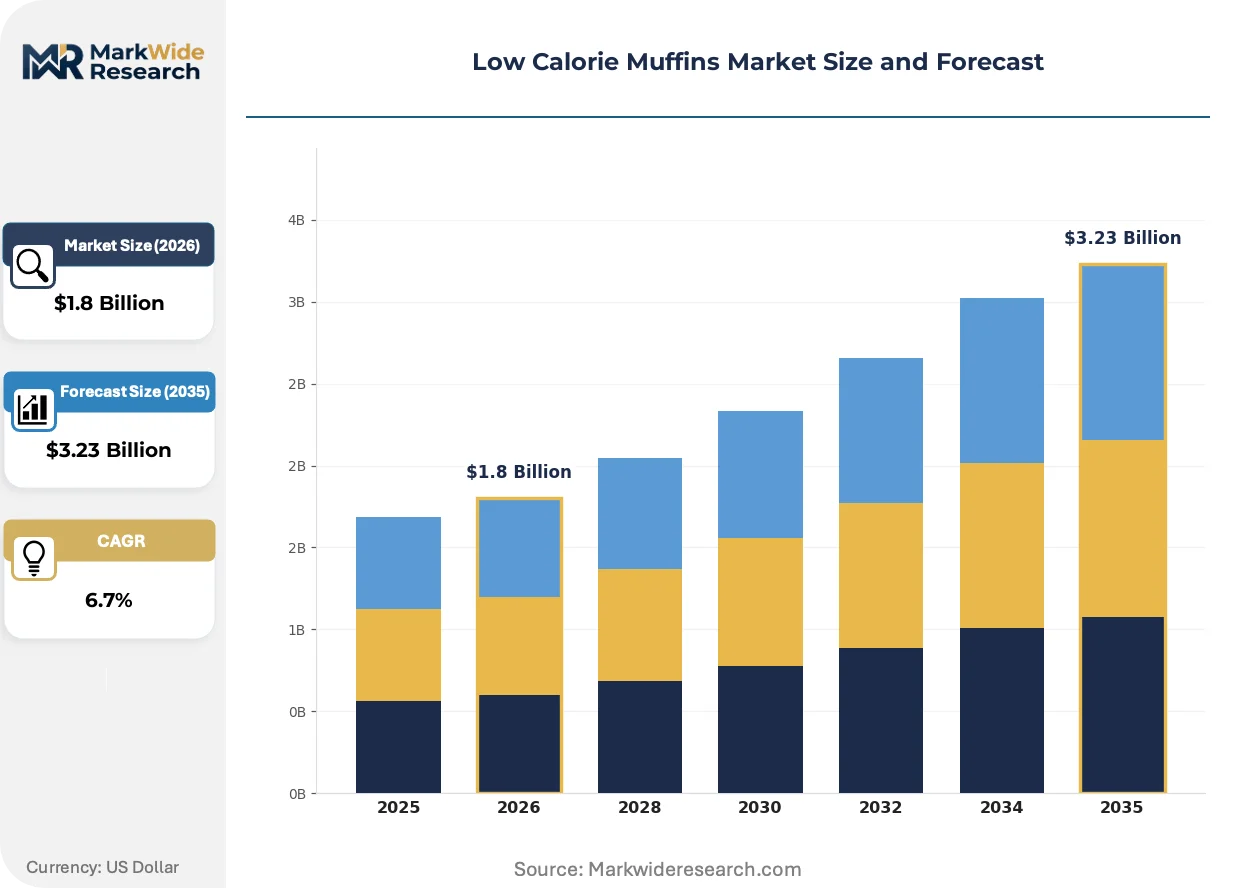
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gluten-Free, Vegan, Protein-Enriched, Sugar-Free Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Cafés Target Customer Type: Health-Conscious Consumers, Fitness Enthusiasts, Diabetics, Weight Watchers Flavor Profile: Chocolate Chip, Blueberry, Banana Nut, Cinnamon Spice |
| Companies Covered | General Mills, Grupo Bimbo, Hostess Brands, McKee Foods, Flowers Foods, ARYZTA, Britannia Industries, Kellogg Company, Otis Spunkmeyer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Calorie Muffins Market Evolving Landscape
Active reformulation science and channel-specific product architecture are displacing one-size-fits-all portfolio strategies. Producers now engineer distinct SKUs for institutional, retail, and direct channels rather than stretching single formulations across divergent shelf-life and price requirements.
Precision fermentation-derived proteins are miniaturizing the functional gap between animal-derived and plant-based texture systems. Bakery R&D teams at multinational CPG manufacturers are adopting these ingredients at pilot-scale throughput. The technology is miniaturizing the premium price gap that has historically separated conventional and protein-enriched muffin categories.
EFSA's 2023 guidance on novel food allergenicity assessments is extending approval timelines for emerging protein sources. Industrial consequence includes delayed European launches for fermentation-derived and insect-protein formulations. Gluten-free and protein-enriched segments face the steepest compliance burdens, with several producers pivoting R&D budgets toward US FDA pathways where GRAS self-determination offers faster market entry.
Subscription-based replenishment purchasing is displacing impulse-driven supermarket bakery selection among fitness-oriented consumers. Direct-to-consumer brands capture recurring orders through macro-nutrient customization portals, while traditional retail loses frequency among this high-value cohort. Germany and the United States exhibit the strongest channel shift velocity, with urban centers showing 30-40% of low-calorie muffin volume migrating to scheduled delivery models.
Low Calorie Muffins Market Segmentation
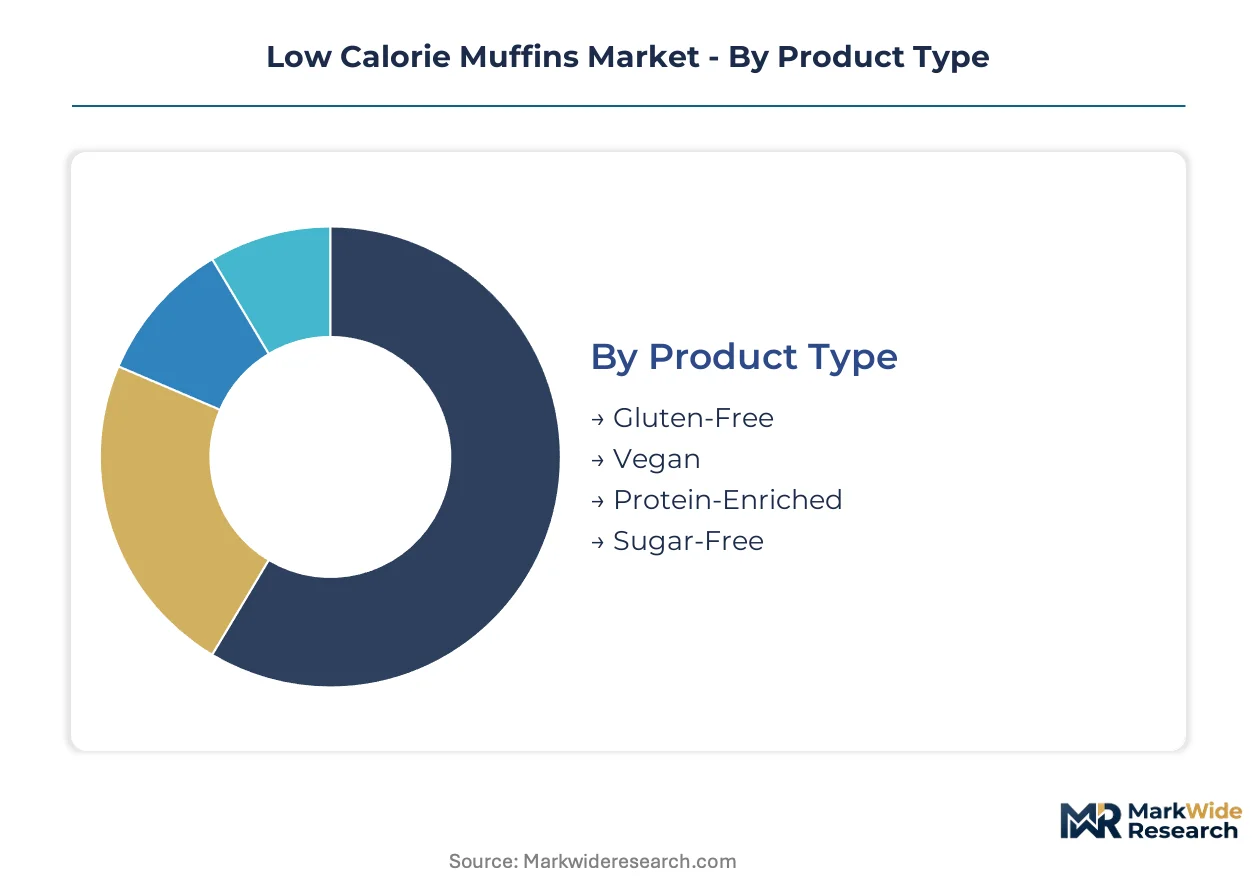
Segmentation in low calorie muffins determines formulation architecture, shelf-life engineering, and channel-specific pricing. Each category carries distinct margin profiles and regulatory burdens that reshape competitive positioning across institutional and retail pathways.
Product Type:
Supermarkets anchor volume for mainstream formats while health food stores and online retail concentrate premium-tier protein-enriched and gluten-free SKUs with extended shelf-price positioning.
- Gluten-Free:Formulated with rice flour, tapioca starch, and xanthan gum systems to replicate wheat gluten networks. Demand clusters in Germany and United States natural retail channels where celiac diagnosis rates and voluntary avoidance behaviors intersect. EFSA allergen labeling requirements elevate compliance costs for European producers.
- Protein-Enriched:Incorporates whey isolate, pea protein, or precision fermentation-derived concentrates at 8-15g per serving. Fitness enthusiasts in United States direct-to-consumer channels drive recurring subscription volume. Manufacturing complexity from Maillard reaction control during high-protein baking creates entry barriers.
- Vegan:Eliminates egg and dairy through aquafaba, flax gel, and commercial egg replacer systems. Plant-based positioning captures urban health-conscious consumers in Japanese convenience store channels.
- Sugar-Free:Relies on erythritol, allulose, or stevia blends with bulking agents to maintain crumb structure. Diabetic and weight management segments in United States supermarket aisles generate baseline volume.
By volume, Sugar-Free leads through mainstream retail penetration. By growth pace, Protein-Enriched is climbing the fastest as athletic nutrition blurs into everyday snacking.
Distribution Channel:
Margin structures diverge sharply: online retail captures subscription lifetime value while supermarkets absorb slotting fees and spoilage risk in exchange for impulse visibility.
- Online Retail:Direct-to-consumer logistics with flash-frozen or ambient-stable packaging. United States fitness enthusiasts and German urban consumers drive 30-40% channel shift velocity in low-calorie bakery. Personalized macro-nutrient portals deepen retention economics.
- Supermarkets:Mass-market placement with 14-21 day shelf-life requirements and dedicated health-positioned aisle sections. Japan and Germany lead in low-calorie bakery aisle development.
- Health Food Stores:Premium positioning with USDA organic or EU organic certification requirements. Dual organic-low-calorie SKUs command 15-20 point shelf price premiums.
- Cafés:Fresh-baked or thaw-and-serve formats for immediate consumption. Corporate wellness procurement mandates in United States large employers specify sub-200-calorie options for cafeteria contracts.
Supermarkets still move the most units. Online retail is expanding most quickly as logistics infrastructure matures for perishable bakery.
Target Customer Type:
Customer archetypes determine sweetness intensity, portion sizing, and protein loading with minimal overlap in formulation preferences between diabetics and fitness enthusiasts.
- Fitness Enthusiasts:Prioritizes protein density and glycemic index with macro-tracking compatibility. This cohort is displacing traditional weight watchers segments in volume contribution across United States and Germany.
- Health-Conscious Consumers:Seeks clean-label positioning with recognizable ingredient decks and minimal processing claims. Drives organic certification demand in natural retail channels.
- Diabetics:Requires clinically validated low-glycemic formulations with precise carbohydrate disclosure. FDA nutrition labeling requirements constrain permissible health claims.
- Weight Watchers:Calorie-centric purchasing with portion-controlled packaging preferences. Losing share to fitness enthusiasts as category positioning shifts from restriction to performance.
Fitness Enthusiasts now dominate premium tier spending. Health-Conscious Consumers are gaining share fastest as clean-label expectations mainstream.
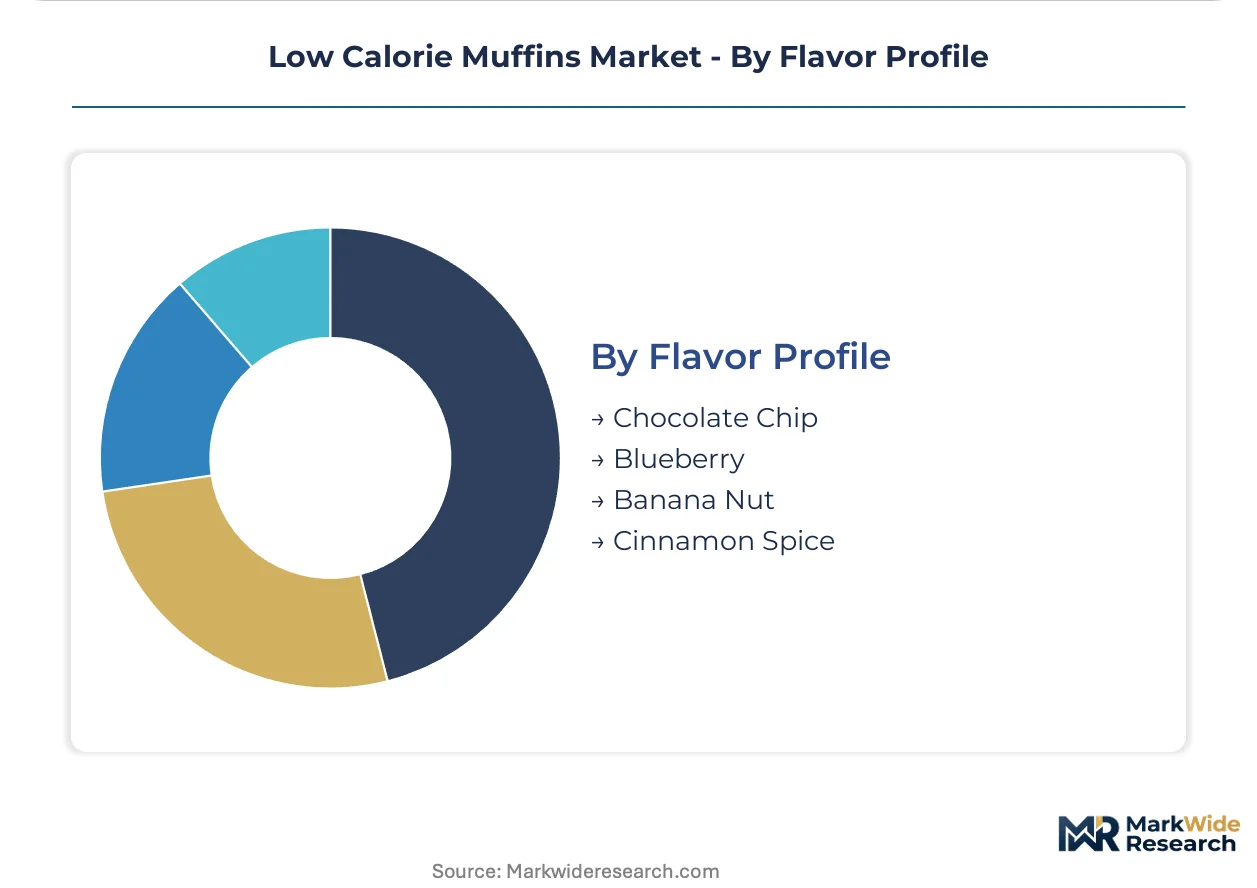
Flavor Profile:
Flavor selection signals category maturity: established profiles secure shelf space while novelty variants test in limited distribution before scale-up.
- Blueberry:Standard-bearer for health-positioned bakery with antioxidant associations and visual differentiation through fruit inclusion. Anchors baseline SKUs across all distribution channels.
- Chocolate Chip:Indulgence-permission positioning bridges diet and treat occasions. United States consumers show highest per-capita consumption.
- Banana Nut:Comfort-food nostalgia with natural sweetness enabling modest sugar reduction. Performs strongly in cafés and convenience channels.
- Cinnamon Spice:Seasonal and year-round variants with warmth perception that masks alternative sweetener aftertaste. Popular in sugar-free formulations.
Blueberry maintains volume leadership. Chocolate Chip is expanding most quickly as permissible indulgence positioning broadens category appeal beyond strict dieters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German bakery exports supply health-positioned retail channels across Northern Europe, while Japanese convenience store networks import formulation expertise from United States direct-to-consumer brands. Trade corridors concentrate premium low-calorie muffin flows between these three manufacturing hubs and their respective buyer geographies.
United States
Corporate wellness procurement mandates at large employers specify sub-200-calorie bakery options, pulling institutional demand through cafeteria contracts. FDA nutrition labeling requirements constrain permissible health claims while creating compliance-based differentiation. Chicago and Minneapolis anchor Midwestern ingredient processing clusters where wheat protein and modified starch production concentrates.
Germany
Celiac diagnosis rates and voluntary gluten avoidance behaviors intersect in natural retail channels, elevating clean-label expectations. EU Green Deal sustainability frameworks reshape ingredient sourcing toward domestic oat and legume fiber suppliers. Bavaria and Baden-Württemberg host specialized bakery operations serving European gluten-free lines.
Japan
Lawson and 7-Eleven Japan expand fresh bakery sections with dedicated health-positioned shelving, creating first-mover positioning opportunities. METI standards govern functional food claims and novel ingredient approvals. Tokyo and Osaka metropolitan areas concentrate urban health-conscious consumers driving vegan and low-glycemic SKU adoption.
United Kingdom
Subscription-based replenishment purchasing displaces impulse-driven supermarket selection among fitness-oriented urban consumers. EFSA health claims regulations constrain formulation choices for exporters serving continental Europe. Greater London anchors direct-to-consumer logistics infrastructure for flash-frozen muffin delivery models.
India
Health-conscious urban consumers in metropolitan centers drive emerging demand for protein-enriched and sugar-free formats. FSSAI labeling requirements govern nutritional claims and alternative sweetener approvals. Maharashtra and Karnataka host expanding modern retail networks developing dedicated health-positioned bakery aisles.
Low Calorie Muffins Market Competitive Landscape
Player mix skews toward multinational CPG conglomerates with dedicated R&D infrastructure and specialized bakery operators serving regional certification requirements. Consolidation pressure concentrates among mid-tier producers lacking regulatory affairs capabilities. Three strategic archetypes dominate: diversified food conglomerates with cross-category innovation pipelines, specialized bakery groups with co-manufacturer networks, and direct-to-consumer brands with subscription retention models. Capacity expansion and clean-label reformulation partnerships constitute the dominant competitive moves.
Within the diversified conglomerate tier, General Mills and Kellogg Company occupy positions exemplifying R&D-driven protein-enriched format development. Grupo Bimbo anchors Latin American production networks while competing in European lines through specialized bakery operations. Among specialized operators, ARYZTA represents the co-manufacturer certification and gluten-free compliance archetype.
| Leading Market Players |
|---|
| General Mills |
| Grupo Bimbo |
| Hostess Brands |
| McKee Foods |
| Flowers Foods |
| ARYZTA |
| Britannia Industries |
| Kellogg Company |
| Otis Spunkmeyer |
| Others |
Value Network & Pricing Analysis
USDA organic certification gates both supplier qualification and shelf-price positioning simultaneously, compressing margin structures for uncertified producers while rewarding dual-certified facilities with 15-20 point premiums in natural retail channels. FDA and EFSA clean-label mandates further bifurcate the supply base, concentrating procurement power among bakeries with dedicated regulatory affairs infrastructure.
Pricing Analysis
Next-generation precision fermentation-derived proteins command premium positioning against conventional whey-isolate and prior-generation pea protein systems. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and protein density, with organic-protein-enriched SKUs at the apex and conventional sugar-free formats occupying mainstream shelves. Cost compression in mid-tier sugar-free formulations is intensifying because erythritol and allulose price volatility tracks corn and sugar beet harvest yields. Fitness enthusiasts in direct-to-consumer channels show least price sensitivity; weight watchers in supermarket aisles show most.
Supply Chain Analysis
Strategic stockpiling of alternative sweeteners and modified starches dominates inventory strategy as harvest volatility and approval pathway delays create input uncertainty. Supply concentrates in the United States Midwest for wheat protein and enzymatic fat-mimetics, Germany for oat and legume fiber systems, and Japan for convenience store distribution infrastructure. Raw material dependencies center on corn-derived erythritol, sugar beet allulose, and lipase-modified starches. Single-source vulnerability runs through Midwestern modified starch production where three states anchor domestic supply. Distribution runs through direct-to-consumer frozen logistics, supermarket slotting-fee networks, and institutional cafeteria contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based replenishment purchasing expands faster than per-unit retail transactions, creating service-attach economics through personalized macro-nutrient portals and recurring revenue algorithms that deepen customer lifetime value beyond single-sale margins.
For Market Incumbents: Compound regulatory affairs capabilities to defend against emerging precision-fermentation entrants and accelerated EFSA novel food approval timelines that threaten protein-enriched positioning. Prioritize backward integration into domestic oat and legume fiber supply to secure EU Green Deal compliance and reduce Midwestern ingredient concentration exposure. Lock in co-manufacturer certification pipelines to preempt 18-24 month organic-allergen-free dual audit delays that stall product launches. For New Entrants and Emerging Players: Differentiate on precision fermentation protein positioning to bypass conventional dairy and legume supply chains entirely. Target Japanese convenience store channels where Lawson and 7-Eleven Japan are expanding health-positioned bakery shelving with limited incumbent penetration. Pursue direct-to-consumer frozen subscription models with macro-customization portals to capture recurring revenue and bypass retail slotting fees. For Investors and Strategic Acquirers: EFSA's 2023 novel food allergenicity guidance reshapes the acquisition landscape toward US FDA GRAS self-determination pathways where faster market entry preserves option value. Five-to-ten year viability favors specialized bakery operators with co-manufacturer certification networks and clean-label formulation expertise scarcity. Watch for FDA sweetener approval pathway acceleration as the inflection signal that unlocks ultra-low-calorie product development beyond current hydrocolloid stability ceilings.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Partnership | ARYZTA's specialized bakery operations demonstrate gluten-free compliance barriers that concentrate R&D budgets among certified producers. |
| Direct-to-Consumer Frozen Subscription Launch | Flash-frozen logistics bypass retail slotting fees while capturing recurring revenue through personalized nutrition algorithms in US and German urban centers. |
| Precision Fermentation Protein Integration | General Mills R&D infrastructure pilots fermentation-derived texture systems that miniaturize premium-conventional price gaps in protein-enriched formats. |
| USDA Organic Certification Investment | Dual organic-low-calorie positioning commands shelf price premiums in natural retail channels where health-conscious consumers cluster. |
| Japanese Convenience Store Channel Expansion | Lawson and 7-Eleven Japan health-positioned shelving creates first-mover positioning for vegan and low-glycemic SKU adoption in Tokyo and Osaka. |
Research Methodology
Initial hypotheses were tested against primary input from bakery R&D directors, regulatory affairs leads at multinational CPG manufacturers, category buyers at health food retailers, and supply chain planners at co-manufacturer networks and refined through secondary validation. FDA nutrition labeling guidance, EFSA novel food submissions, USDA organic certification databases, and Nielsen retail audit data anchored quantitative triangulation. Bottom-up SKU-level volume builds and top-down category spending estimates were reconciled across modeling approaches.
Variance decomposition across the projection horizon isolates drivers by product type, distribution channel, target customer archetype, and regional regulatory cluster. CAGRs derive from segment-level growth rate blending rather than single-point extrapolation. Forecast inputs incorporate enzymatic fat-mimetic technology diffusion curves, alternative sweetener approval pathway timelines, and corporate wellness procurement mandate adoption rates in large US employers.
The analysis sits within stated boundaries; outcomes outside sustained FDA and EFSA clean-label enforcement or accelerated precision fermentation scale-up would require recalibration. Forecasts reflect documented assumptions about regulatory stability and input cost trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Frozen Bakery Market
Bakery Products
Gluten-Free Baking Mixes Market
Bakery Products
Toasted Flour Market
Bakery Products
Cake Base Discs Market
Bakery Products
South America Bakery Products Market
Bakery Products
Bakery Contract Manufacturing Market
Bakery Products
Sourdough Market
Bakery Products
Gluten-Free Bakery Products Market
Bakery Products
Frozen Bakery Additives Market
Bakery Products
Ice Cream Cones Market
Bakery Products
Global Rice Cakes Market
Bakery Products
Baked Foods Market
Bakery Products
Matcha Cookie Market
Bakery Products
Baking Molds and Trays Market
Bakery Products
Organic Frozen Bakery Market
Bakery Products
Low Fat Bread Market