
 Vegan Certified Cake Mixes Market | 2026-2036
Vegan Certified Cake Mixes Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Certified Cake Mixes Market Analytics
North American specialty millers is consolidating production of certified vegan baking bases around allergen-free facilities. Bob's Red Mill leverages its employee-owned structure to sustain long-term ingredient sourcing relationships with regional oat and almond suppliers. King Arthur Baking competes through its baker-education ecosystem, while Simple Mills specializes in grain-free formulations that occupy premium shelf space across natural grocery channels.
Vegan certified cake mixes are dry, pre-measured blends of plant-based flours, leavening agents, and binders that exclude all animal derivatives, typically requiring the addition of water or oil to produce finished cakes. These formulations rely on enzymatic or chemical leavening systems rather than egg proteins, with primary commercial purpose of enabling consistent, scalable dessert production for home bakers and small foodservice operations. The gluten-free ingredient segment anchors volume due to overlapping allergen-sensitive and vegan consumer bases, while organic sub-categories command disproportionate margin pools. Chocolate flavor profiles dominate retail velocity, though lemon variants are gaining fastest among health-conscious consumers seeking reduced-sugar positioning.
The FDA maintains labeling standards for plant-based claims under its food identity regulations, while USDA organic certification intersects with vegan positioning through feed and processing requirements. EFSA and EMA frameworks across Europe govern novel ingredient approvals and clean-label substantiation, directly shaping which hydrocolloid binders and protein isolates gain market access. Stakeholders must monitor evolving definitions of vegan certification integrity as third-party standards from Vegan Action and V-Label proliferate with divergent trace-threshold requirements.
Market Dynamics
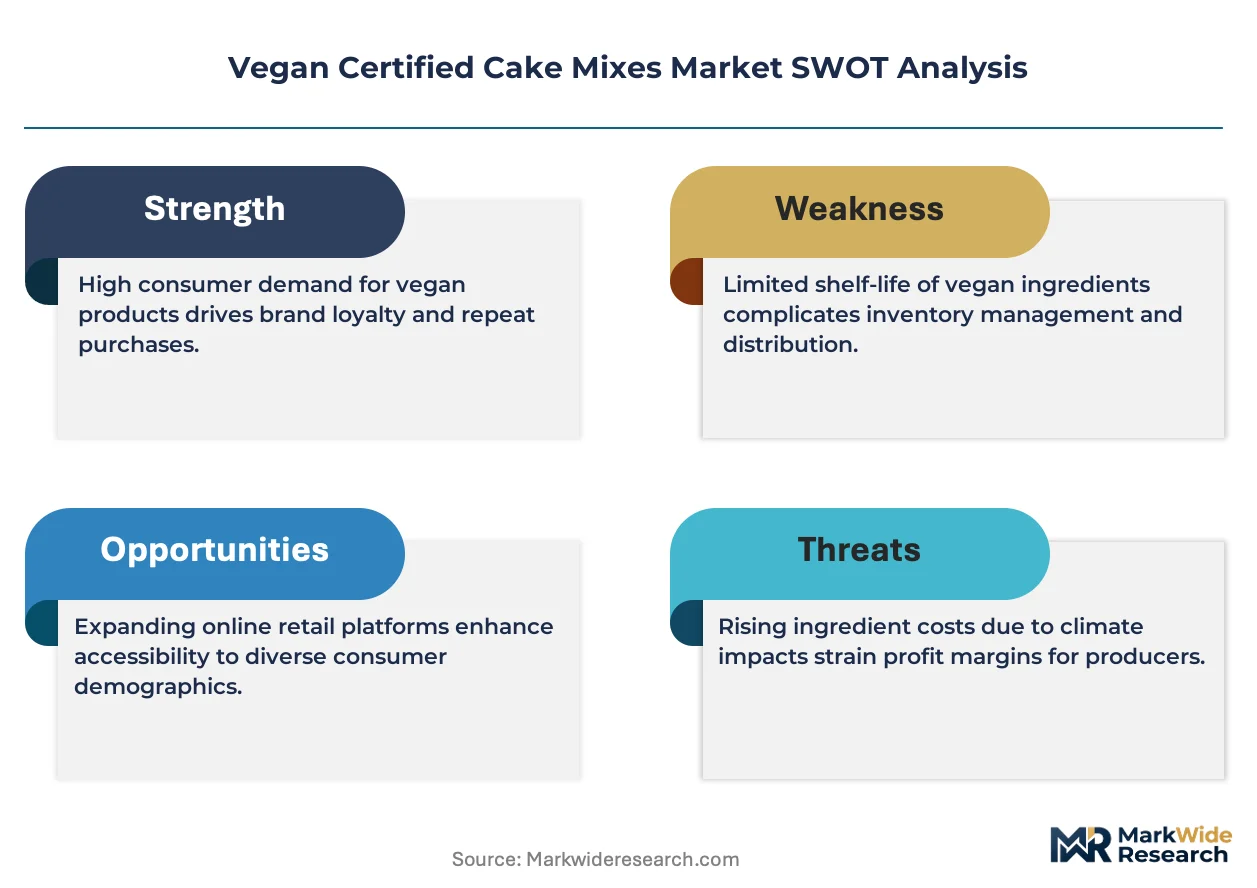
Clean-label ingredient sourcing is compressing formulation cycles across the vegan certified cake mixes sector, forcing manufacturers to requalify hydrocolloid binders and protein isolates under tightening EFSA novel food assessments. This pressure cascades through supply chains as bakeries and retail brands race to maintain certification integrity while scaling production.
Growth Catalysts
- EU Green Deal compliance mandates:Member states are embedding sustainability requirements into food production licensing, accelerating plant-based ingredient substitution in commercial baking operations across Germany and France.
- Home baking segment expansion:Specialty retail channels report surging demand from allergen-sensitive households seeking dual-certified vegan and gluten-free dessert bases for domestic consumption.
- Oat protein extraction advances:Enzymatic processing improvements are reducing off-flavor compounds in plant-based leavening systems, improving sensory parity with conventional egg-based formulations.
Market Restraints
- Almond flour price volatility:California drought cycles and water allocation disputes are destabilizing input costs for grain-free vegan mix formulations.
- EFSA novel food approval timelines:Emerging hydrocolloid binders face month-long safety assessments that delay product launches and compress competitive windows.
- Egg-based conventional mixes:Lower per-unit pricing and established distribution density in mass retail channels create persistent substitution pressure at the price-sensitive consumer tier.
Strategic Opportunities
- United Kingdom foodservice penetration:Underdeveloped vegan dessert programs in contract catering and hospitality chains offer white-space expansion for bulk-format certified mixes.
- F-Gas Regulation refrigeration incentives:Cold-chain efficiency mandates are favoring dry-mix distribution models over frozen alternatives in EU institutional procurement.
- Direct-to-bakery subscription channels:Specialty millers are bypassing distributor markups through recurring shipment models targeting independent retail bakeries.
Industry Challenges
- Food technologist talent scarcity:Formulation expertise spanning plant protein chemistry, enzymatic leavening, and clean-label stability remains concentrated among a narrow specialist cohort.
- V-Label trace-threshold verification:Divergent cross-contamination standards between Vegan Action and European certification bodies complicate multi-market product qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Certified Cake Mixes Market |
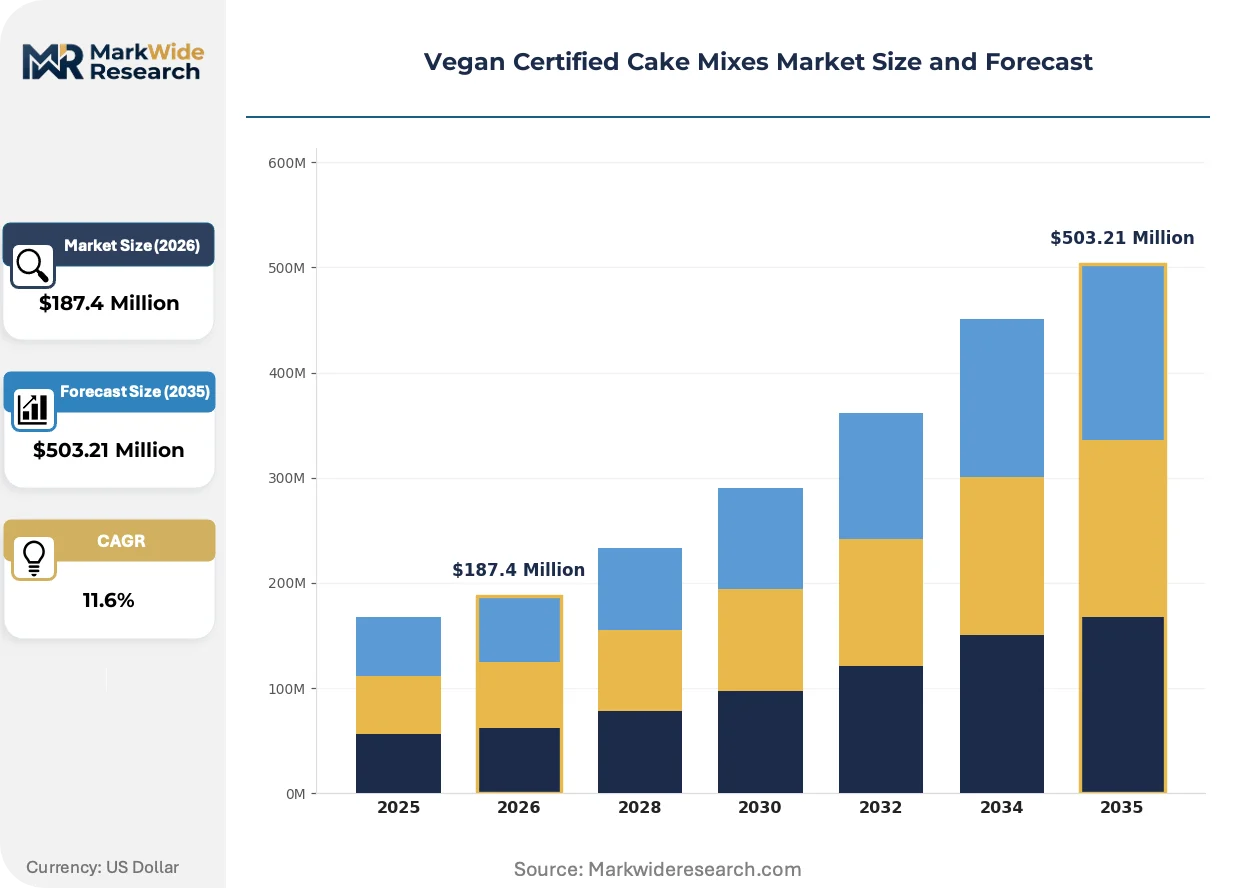
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ingredient Type: Gluten-Free, Organic, Whole Grain, Non-GMO Flavor Profile: Chocolate, Vanilla, Red Velvet, Lemon Target Audience: Health-Conscious Consumers, Vegans, Families, Bakers Packaging Type: Resealable Bags, Boxes, Biodegradable, Single-Serve |
| Companies Covered | Bob's Red Mill, Simple Mills, King Arthur Baking, Namaste Foods, Pamela's Products, Miss Jones Baking, Dawn Foods, Betty Crocker, Duncan Hines, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Certified Cake Mixes Market Evolving Landscape
Precision fermentation and enzymatic processing are converging to reshape ingredient functionality in plant-based baking, compressing the gap between vegan formulations and conventional performance benchmarks. These advances are redefining what clean-label claims can substantiate in commercial dessert production.
Precision fermentation-derived egg white proteins are automating texture replication in vegan sponge cakes and chiffon formulations. Mid-size specialty bakeries in the United Kingdom and Germany are piloting these ingredients at pilot-scale volumes, validating scaled manufacturing protocols. The technology is automating the elimination of lengthy consumer sensory adjustment periods that previously slowed vegan product line conversions.
The EU F-Gas Regulation is tightening hydrofluorocarbon phase-down schedules for industrial refrigeration equipment used in ingredient storage and finished goods distribution. Food manufacturers are retrofitting cold-chain infrastructure or shifting toward ambient-stable dry mix formats to avoid compliance penalties. Chocolate-flavored vegan cake mixes with extended shelf stability are capturing disproportionate attention from reformulation teams responding to this refrigeration cost pressure.
Certification-driven purchasing is consolidating buyer preferences around third-party verified claims rather than manufacturer self-declarations. Natural grocery channels are displacing conventional supermarket placements for uncertified plant-based alternatives, with V-Label and Vegan Action logos becoming mandatory for shelf access. This preference compression is most visible in France and Germany, where retail buyers are conditioning purchase orders on dual organic-vegan certification status.
Vegan Certified Cake Mixes Market Segmentation
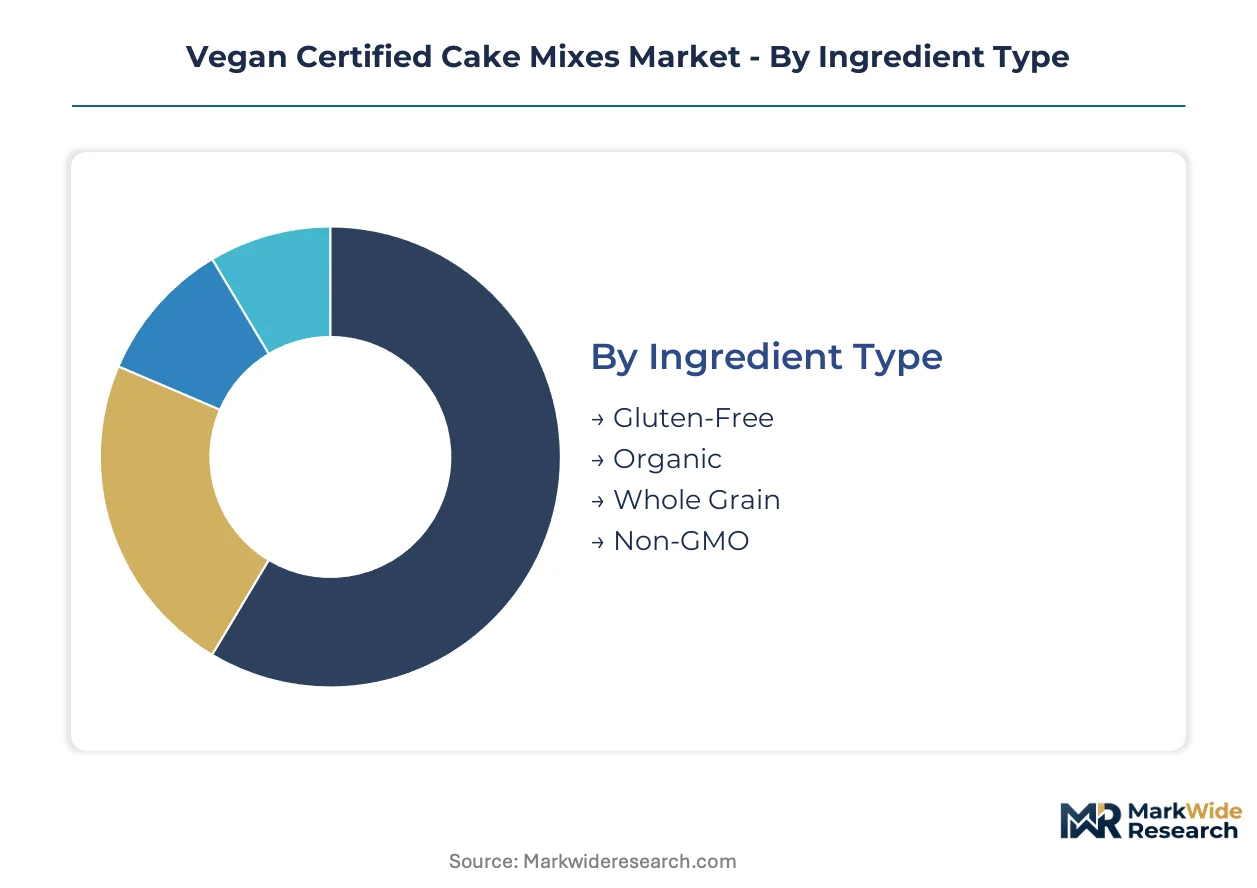
Segmentation in vegan certified cake mixes reveals how certification requirements, sensory preferences, and distribution channels fragment demand across distinct buyer cohorts. Each dimension captures different trade-offs between price tolerance, ingredient scrutiny, and convenience expectations that manufacturers must navigate simultaneously.
Ingredient Type:
Cost tier separates buyers in this category, with premium positioning commanding shelf space through certification stacking while economy formulations compete on accessibility.
- Gluten-Free:Formulations eliminate wheat, barley, and rye proteins through alternative flour systems such as rice, tapioca, and sorghum blends. Demand clusters among allergen-sensitive households in Germany and the United Kingdom where dual vegan-gluten-free certification drives purchase decisions. EFSA novel food assessments for emerging hydrocolloid binders create formulation bottlenecks that favor established suppliers with approved ingredient portfolios.
- Organic:USDA and EU organic certification intersects with vegan claims through feed and processing requirements, commanding disproportionate margin pools in natural grocery channels. French retail buyers increasingly condition purchase orders on dual organic-vegan status, compressing market access for single-certified alternatives.
- Whole Grain:Incorporates minimally processed wheat, spelt, or oat flours retaining bran and germ layers for fiber positioning.
- Non-GMO:Verified through third-party testing protocols excluding genetically modified corn, soy, or beet sugar derivatives.
Volume sits with Gluten-Free; growth tilts toward Organic.
Flavor Profile:
Application context differentiates buyers here, with retail velocity favoring indulgence-positioned varieties while foodservice channels prioritize versatile bases for customization.
- Chocolate:Cocoa-based formulations dominate retail velocity through familiar sensory expectations and masking capabilities for off-notes in plant-based protein systems. Reformulation teams in the United Kingdom and Germany are prioritizing extended shelf-stable chocolate variants to circumvent F-Gas Regulation refrigeration cost pressures in institutional procurement.
- Lemon:Citrus oil and zest formulations are gaining fastest among health-conscious consumers seeking reduced-sugar positioning and perceived digestive benefits. Pilot programs at specialty bakeries in France validate enzymatic processing improvements that reduce bitterness in plant-based leavening systems.
- Vanilla:Bourbon and Tahitian vanilla extracts provide neutral bases for home customization and frosting pairing.
- Red Velvet:Beet juice or anthocyanin-based color systems replicate traditional cocoa-vinegar chemistry without animal-derived buttermilk.
Revenue concentrates in Chocolate; steepest expansion trajectory belongs to Lemon.
Target Audience:
Customer type determines channel strategy, with divergent tolerance for preparation complexity and price premiums across household versus professional contexts.
- Health-Conscious Consumers:Buyers prioritize clean-label ingredient lists, reduced sodium, and functional additions such as adaptogens or protein fortification. German supermarkets report surging demand from this cohort for single-serve formats enabling portion control without waste.
- Vegans:Core buyers requiring third-party certification integrity from Vegan Action or V-Label rather than manufacturer self-declarations. V-Label trace-threshold verification complexity complicates multi-market qualification for brands targeting both European and North American certification standards.
- Families:Multi-serve packaging and kid-friendly flavor profiles drive repeat purchase in conventional grocery channels.
- Bakers:Professional and semi-professional users demand consistent hydration ratios and predictable rise characteristics for commercial production.
Volume concentrates with Families; margin capture favors Bakers.
Packaging Type:
Supply concentration shapes competitive dynamics, with sustainability mandates and logistics efficiency driving divergent format investments across regional markets.
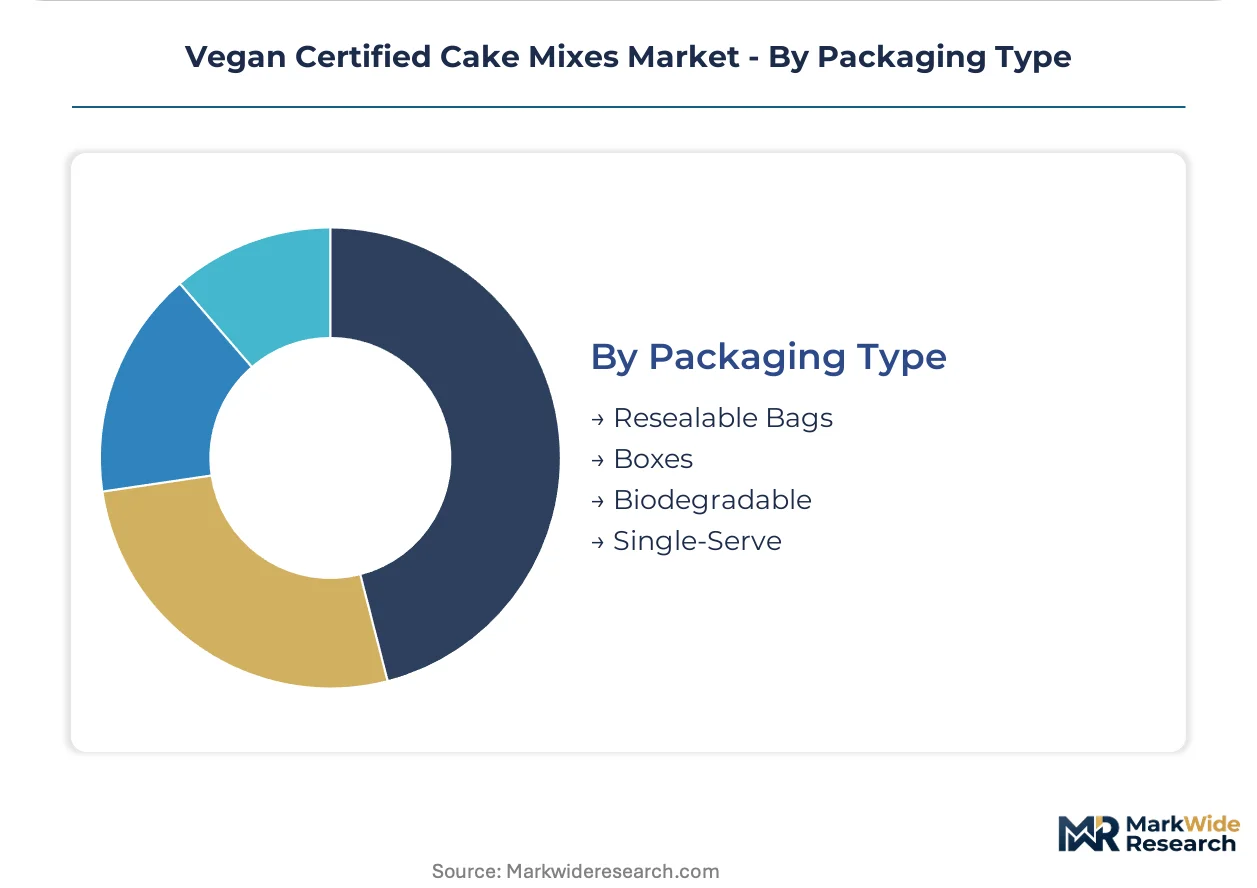
- Resealable Bags:Multi-layer barrier films with zip-lock closures preserve freshness across multiple use occasions, dominating household penetration in France and Germany. EU Green Deal packaging waste directives are accelerating shift from rigid formats to flexible alternatives with reduced material intensity.
- Biodegradable:Cellulose-based or compostable packaging materials command premium positioning in natural grocery channels. King Arthur Baking and Bob's Red Mill compete through sustainability credentials that align with employee-owned and regional sourcing narratives respectively.
- Boxes:Conventional paperboard with polyethylene liners retains cost advantage in mass retail distribution.
- Single-Serve:Individual portion packets target trial conversion and on-the-go preparation occasions.
Volume sits with Boxes; growth tilts toward Biodegradable.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Almond orchards in California's Central Valley supply critical flour inputs for grain-free formulations, while European oat cultivation in Scandinavia underpins leavening system advances. These feedstock localities anchor divergent regional production strategies across the vegan certified cake mixes sector.
United States
Specialty retail channels in California and the Pacific Northwest drive dual-certified vegan-gluten-free demand. FDA food identity regulations govern plant-based labeling claims, intersecting with USDA organic certification requirements. King Arthur Baking operates an employee-owned education ecosystem from Vermont that sustains regional ingredient sourcing relationships.
Germany
Natural grocery penetration in Berlin and Munich clusters around V-Label certified products with extended shelf stability. EU Green Deal compliance mandates embed sustainability requirements into food production licensing across member states. Precision fermentation pilot programs at mid-size specialty bakeries in Hamburg validate scaled manufacturing protocols for egg-white protein alternatives.
United Kingdom
Contract catering and hospitality chains in London and Manchester present underdeveloped vegan dessert program opportunities. F-Gas Regulation refrigeration incentives favor dry-mix distribution models over frozen alternatives in institutional procurement. Direct-to-bakery subscription channels from specialty millers target independent retail bakeries in the Southeast.
France
Retail buyers in Paris and Lyon condition purchase orders on dual organic-vegan certification status. EFSA novel food assessments govern hydrocolloid binder approvals that shape formulation accessibility. Chocolate-flavored reformulation teams prioritize ambient-stable variants to circumvent cold-chain cost pressures.
Vegan Certified Cake Mixes Market Competitive Landscape
Global majors compete with regional champions across certification integrity and distribution density. The vendor base spans employee-owned specialty millers, diversified baking conglomerates, and grain-free formulation specialists. Three archetypes dominate: heritage brands with regional sourcing narratives, education-platform bakers, and allergen-focused premium-positioned players. Capacity expansion and portfolio diversification represent the dominant competitive moves as manufacturers race to maintain certification integrity while scaling production.
Within the heritage miller tier, Bob's Red Mill and King Arthur Baking occupy positions defined by ownership structure and regional supply relationships. Bob's Red Mill leverages its employee-owned structure to sustain long-term ingredient sourcing, while King Arthur Baking competes through baker-education ecosystems. Simple Mills represents the grain-free specialist archetype, occupying premium shelf space across natural grocery channels. These three entities exemplify how divergent organizational models address overlapping consumer bases seeking clean-label, certified-vegan dessert ingredients.
| Leading Market Players |
|---|
| Bob's Red Mill |
| Simple Mills |
| King Arthur Baking |
| Namaste Foods |
| Pamela's Products |
| Miss Jones Baking |
| Dawn Foods |
| Betty Crocker |
| Duncan Hines |
| Others |
Value Network & Pricing Analysis
Precision fermentation-derived egg white proteins are compressing formulation economics while redrawing supplier power dynamics across the vegan certified cake mixes sector. Enzymatic leavening advances simultaneously reduce per-batch input costs and concentrate production capacity among facilities with certified clean-label infrastructure.
Pricing Analysis
Warranty and certification-bundling separates premium positioning from unbundled economy tiers. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification stacking and organic status. Price differentiation hinges on dual vegan-gluten-free certification and regional sourcing narratives. Pricing pressure stems from almond flour cost volatility in California. Home baking enthusiasts exhibit highest price sensitivity; contract catering operations show lowest.
Supply Chain Analysis
Reverse logistics for expired or damaged dry mixes remains underdeveloped, with most channels relying on landfill disposal rather than ingredient recovery flows. Supply concentrates in the United States, Germany, and the United Kingdom for precision fermentation capacity and oat protein processing. Raw material dependencies center on California almonds, Scandinavian oats, and South American tapioca starch. Single-source vulnerability runs through drought-exposed almond orchards. Distribution runs through natural grocery channels and direct-to-bakery subscription models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic processing platforms are displacing legacy chemical leavening systems, compressing the technology transition window for manufacturers still reliant on established binder portfolios.
For Market Incumbents: Hedge against precision fermentation supply concentration by diversifying hydrocolloid binder qualifications across EFSA-approved portfolios. Defensive moves center on backward integration into regional oat protein extraction and certification integrity investments that exceed V-Label trace-threshold standards. Threats include novel entrant bakeries leveraging automated texture replication without consumer adjustment periods.
For New Entrants and Emerging Players: Independent retail bakeries in the United Kingdom Southeast present the most penetrable buyer archetype currently underserved by bulk-format subscription channels. White-space targets include contract catering chains lacking vegan dessert programs and hospitality procurement seeking F-Gas Regulation-compliant ambient-stable formats. Go-to-market angle emphasizes direct recurring shipment models bypassing distributor markups.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified baking conglomerates seeking certified-vegan portfolio expansion. Long-term viability over the mid-term horizon favors targets with dual organic-vegan certification status and established EFSA novel food approvals. Signal to watch is F-Gas Regulation enforcement intensity accelerating dry-mix preference over frozen alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Automates texture parity with conventional egg-based formulations for mid-size bakeries. |
| Dual Certification Investment | Secures shelf access in French and German natural grocery channels conditioning on organic-vegan status. |
| Direct-to-Bakery Subscription Launch | Bypasses distributor markups targeting independent retail bakeries in underpenetrated UK regions. |
| EFSA Novel Food Pre-Approval | Accelerates product launches by front-loading hydrocolloid binder safety assessments. |
| Ambient-Stable Reformulation | Aligns with EU F-Gas Regulation cold-chain efficiency mandates favoring dry-mix distribution. |
Research Methodology
Document review covered EFSA novel food registers, EU Green Deal implementation guidance, and F-Gas Regulation phase-down schedules, complemented by interviews with plant protein chemists, enzymatic processing specialists, natural grocery category buyers, and independent bakery procurement managers. Secondary validation drew from customs trade data for almond and oat flour flows, FDA food identity regulation filings, and V-Label certification databases. Bottom-up demand modeling triangulated against top-down market sizing across ingredient type, flavor profile, and target audience dimensions.
Output tables segmented volume and value projections by gluten-free, organic, whole grain, and non-GMO ingredient categories alongside chocolate, lemon, vanilla, and red velvet flavor profiles. CAGRs were derived from elasticity-adjusted demand curves incorporating oat protein extraction yield improvements and precision fermentation cost decline trajectories. Modeled inputs included EFSA approval timeline distributions and EU member state sustainability mandate adoption rates.
Revisions become necessary when EFSA novel food assessments extend beyond baseline timelines or California drought cycles intensify almond flour supply disruptions. Forecasts reflect assumptions about enzymatic leavening sensory parity achievement and certification body threshold harmonization. Practitioners should monitor F-Gas Regulation enforcement intensity and V-Label trace-threshold divergence for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Specialty Bakery Market
Bakery Products
Ice Cream Cake Market
Bakery Products
Pie Shells Market
Bakery Products
Layer Cake Mixes Market
Bakery Products
Lentil Bread Market
Bakery Products
Biscuit Mixes Market
Bakery Products
Batter and Breader Premixes Market
Bakery Products
Vegan Baking Mix Market
Bakery Products
Low Fat Muffin Market
Bakery Products
Canada Frozen Bakery Market
Bakery Products
Pastry Dough Market
Bakery Products
North America Gluten Free Bakery Mixes Market
Bakery Products
Asia-Pacific Bakery Products Market
Bakery Products
Low Calorie Rice Cake Market
Bakery Products
Ready-To-Finish Bakery Products Market
Bakery Products
Bread Premix Market