
 Ready-To-Finish Bakery Products Market | 2026-2036
Ready-To-Finish Bakery Products Market Size, Share, and Industry Trends Forecast 2026-2036
Ready-To-Finish Bakery Products Market Analytics
A capital-intensity divergence between automated frozen dough lines and artisan par-baked operations is rotating competitive advantage toward scale players. Dawn Food Products leverages its vertically integrated ingredient supply to sustain margin control across North American foodservice channels. Rich Products Corporation anchors its position through proprietary cryogenic freezing technology that extends distribution reach for unbaked formulations. Grupo Bimbo competes on geographic dominance, operating localized production hubs that reduce freight costs for temperature-sensitive par-baked breads.
Ready-to-finish bakery products comprise partially processed flour-based formulations—frozen dough, par-baked breads, cake mixes, and puff pastry—that require final thermal processing before consumption, typically formulated with controlled moisture content between 35% and 55% to ensure consistent proofing or baking performance. These products serve commercial and institutional food preparers seeking to reduce skilled labor hours while maintaining output consistency. Frozen dough commands the largest value pool due to extended shelf life and lower logistics sensitivity, though par-baked breads capture premium positioning in European artisan-channel supply. Cake mixes represent the most mature segment with consolidated brand ownership, while puff pastry differentiates through laminated-fat technology barriers that limit new entrant replication.
The FDA enforces Current Good Manufacturing Practices and preventive controls under FSMA for domestic and imported ready-to-bake formulations, elevating compliance costs for smaller co-manufacturers. The EPA regulates refrigerant emissions from blast-freezing operations, pushing capital investment toward ammonia-based or CO2 cascade systems in production facilities. The EU Green Deal's Farm-to-Fork targets on processed food sustainability are beginning to shape export specifications for par-baked products entering European wholesale channels. Stakeholders must monitor evolving clean-label ingredient standards and freezing-energy benchmarks as procurement criteria harden across contract foodservice accounts.
Market Dynamics
Labor scarcity across foodservice and retail bakery operations is compressing proof-to-sale cycles and forcing automation investment into frozen dough portioning and par-bake finishing systems.
Growth Catalysts
- FSMA Preventive Controls:The FDA's updated requirements for hazard analysis and risk-based preventive controls are accelerating supplier consolidation as smaller co-manufacturers exit rather than absorb compliance infrastructure costs.
- Quick-Service Restaurant Channel Expansion:QSR operators in the United States are standardizing frozen dough programs to reduce in-store labor hours and eliminate variable proofing outcomes.
- Cryogenic Freezing Technology:Advancements in liquid nitrogen and CO2 cascade freezing systems are extending distribution radii for unbaked formulations without quality degradation.
Market Restraints
- Wheat Price Volatility:Input cost swings for hard red winter wheat and specialty flour grades compress margin predictability for frozen dough producers lacking forward-contract coverage.
- Cold Chain Concentration Risk:Third-party refrigerated logistics capacity constraints in the Midwest United States create fulfillment bottlenecks during peak seasonal demand windows.
- Clean-Label Reformulation Barriers:Removal of dough conditioners and extended-shelf-life emulsifiers degrades freeze-thaw stability, forcing trade-offs between ingredient simplicity and operational tolerance.
Strategic Opportunities
- Underpenetrated Southeast Asia:Quick-service bakery chains in Indonesia and Vietnam lack frozen dough supplier infrastructure, creating first-mover openings for cold-chain-capable exporters.
- EU Green Deal Farm-to-Fork Alignment:Sustainability certification for par-baked products entering European wholesale channels commands procurement preference from contract foodservice accounts.
- Direct-to-Operator E-Commerce:Digital platforms connecting artisan bakeries to regional frozen dough suppliers are disintermediating traditional broadline distributors in secondary US markets.
Industry Challenges
- Skilled Maintenance Technician Scarcity:Automated lamination and freezing lines require mechatronics expertise that bakery operations struggle to recruit at prevailing wage levels.
- Legacy ERP Integration Friction:Frozen dough suppliers adopting lot-level traceability systems face data architecture conflicts with customer procurement platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ready-To-Finish Bakery Products Market |
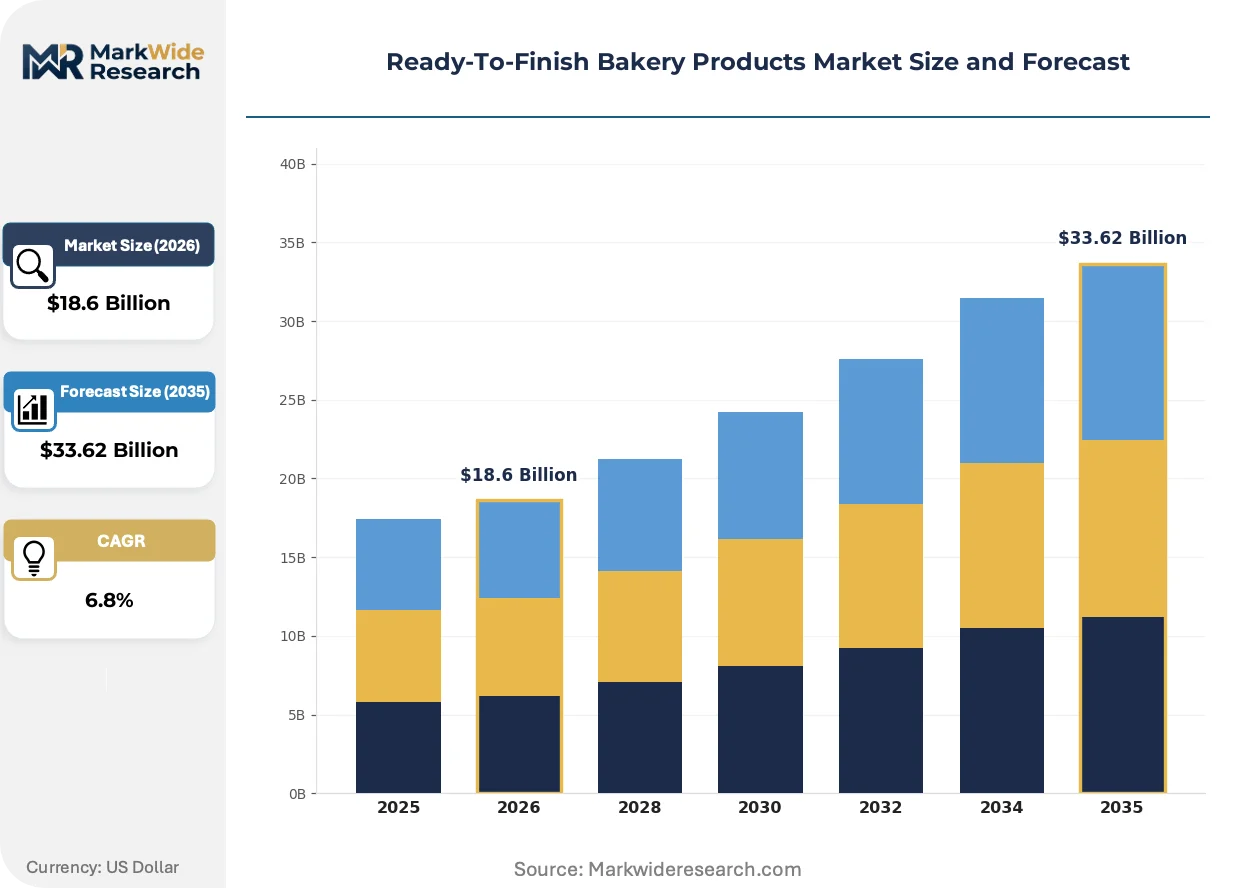
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $33.62 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Dough, Par-baked Breads, Cake Mixes, Puff Pastry End User: Restaurants, Bakeries, Cafeterias, Retail Chains Packaging Type: Bags, Boxes, Trays, Film Wrappings Distribution Channel: Online Stores, Supermarkets, Specialty Stores, Wholesale Distributors |
| Companies Covered | Dawn Food Products, Rich Products Corporation, Grupo Bimbo, Associated British Foods, Aryzta AG, Lantmannen Unibake, Europastry, General Mills, Vandemoortele, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ready-To-Finish Bakery Products Market Evolving Landscape
Active innovation across the ready-to-finish bakery segment centers on equipment footprint reduction, regulatory alignment with clean-label mandates, and procurement model digitization.
Modular proofing-retardation units with embedded IoT sensors are miniaturizing the capital barrier for mid-size bakery operations seeking controlled fermentation without dedicated room infrastructure. Independent retail bakeries in the United States are adopting these units fastest, compressing the addressable market for traditional walk-in proofer installations and enabling flexible production scheduling across multiple SKUs.
The EPA's phasedown of hydrofluorocarbon refrigerants under the American Innovation and Manufacturing Act is forcing blast-freezing retrofit decisions across domestic production facilities. Ammonia-based and transcritical CO2 cascade systems are capturing new build specifications, though retrofit economics delay adoption at legacy plants concentrated in the Great Lakes manufacturing corridor.
Foodservice procurement teams are consolidating supplier rosters and demanding outcome-based specifications for finished product consistency rather than ingredient-level contracts. This behavior shift compresses the viable vendor base for frozen dough programs while elevating technical service capabilities to competitive parity with unit economics in multi-unit restaurant evaluations, with the pattern most visible in US casual dining chain RFP processes.
Ready-To-Finish Bakery Products Market Segmentation
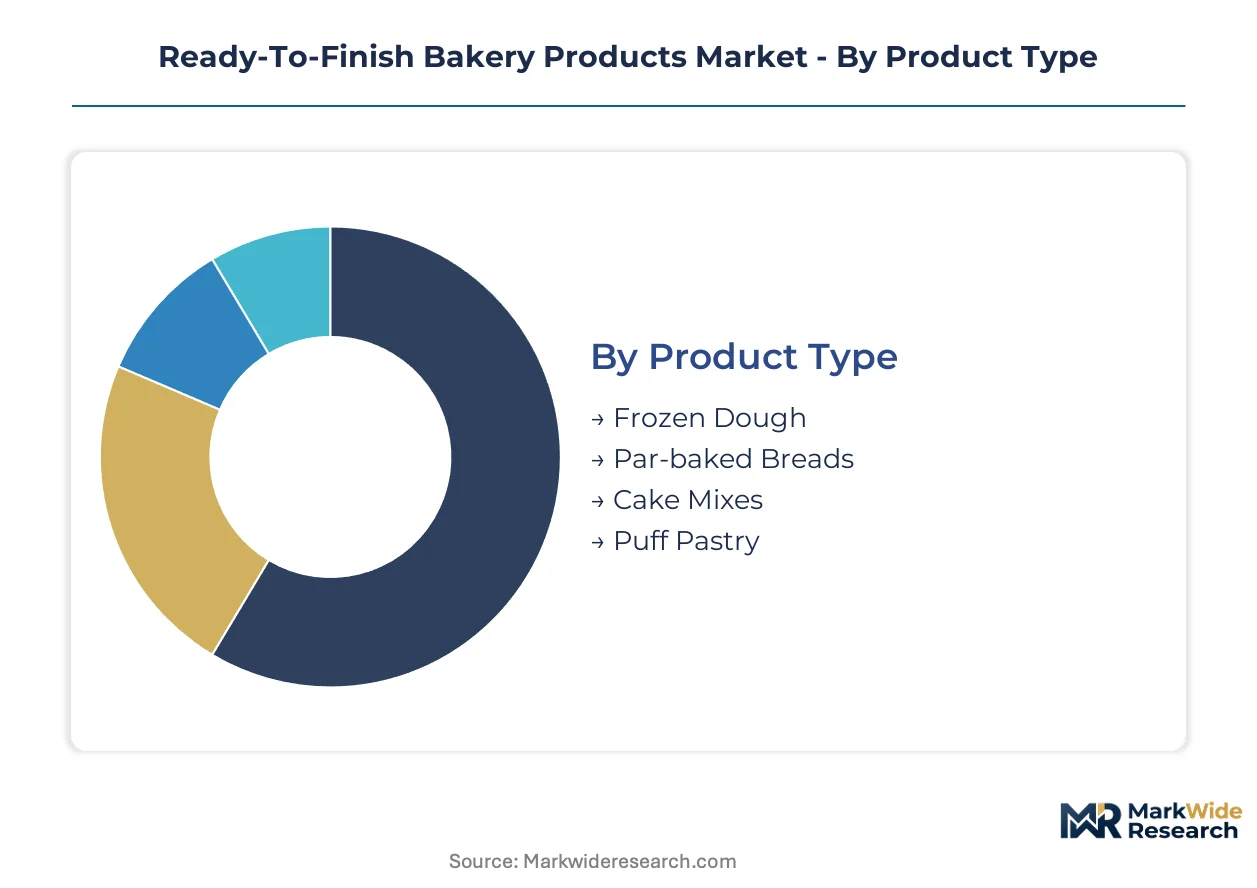
Segmentation in ready-to-finish bakery products reveals how regulatory compliance costs, cold-chain infrastructure, and end-use labor economics concentrate value across distinct product configurations and channel pathways. Understanding these divisions exposes where scale advantages accumulate versus where niche positioning remains viable.
Product Type:
FDA preventive controls under FSMA apply differential compliance burdens across moisture-content thresholds and unbaked versus partially-baked classifications, segmenting the competitive landscape by capital intensity.
- Frozen Dough:Unbaked formulations with controlled moisture between 35% and 55% enable extended distribution radii through cryogenic freezing. Demand concentrates in United States quick-service restaurant chains seeking to eliminate in-store proofing variability and reduce hourly labor dependency.
- Par-baked Breads:Partially thermal-processed loaves requiring finish baking retain artisan texture cues while compressing customer preparation time. European wholesale channels and United States in-store bakery expansions at major retail chains pull volume for premium-positioned formats.
- Cake Mixes:Dehydrated flour-sugar-fat blends with longest shelf stability represent the most mature segment with consolidated brand ownership and limited technology differentiation.
- Puff Pastry:Laminated-fat products with specialized sheeting requirements create formulation barriers that limit replication by new entrants and sustain margin premiums in foodservice accounts.
Established volume favors frozen dough; emerging adoption favors par-baked breads.
End User:
Labor scarcity and proof-to-sale cycle compression drive divergent purchasing criteria across institutional, commercial, and retail preparation environments.
- Restaurants:United States quick-service and casual dining operators standardize frozen dough programs to reduce skilled bakery staffing requirements and guarantee output consistency across locations.
- Bakeries:Independent retail operations adopt modular proofing-retardation units with IoT sensors, enabling flexible SKU scheduling without dedicated room infrastructure and compressing demand for traditional equipment.
- Cafeterias:Institutional food preparers in education and healthcare sectors prioritize portion-controlled formats with extended frozen holding tolerance to manage irregular service windows.
- Retail Chains:United States supermarket in-store bakery expansions drive volume pull-through for par-baked and frozen dough formats that support fresh-baked aroma marketing with minimal on-site labor.
Procurement consolidation favors restaurant chains; technical service intensity favors bakery independents.
Packaging Type:
Cold-chain compatibility and moisture-barrier performance segment packaging selection by distribution distance and freeze-thaw cycling requirements.
- Bags:Flexible polyethylene formats dominate high-velocity frozen dough SKUs for foodservice distributors seeking pallet density and handling efficiency.
- Boxes:Rigid corrugated protection supports par-baked bread formats vulnerable to crush damage during refrigerated transport through third-party logistics networks.
- Trays:Thermoformed containers with lid-sealing preserve laminated layer integrity in puff pastry products through distribution vibration exposure.
- Film Wrappings:High-barrier coextruded films extend shelf life for cake mixes in retail environments with ambient storage conditions.
Operational throughput favors bags; damage reduction favors boxes.
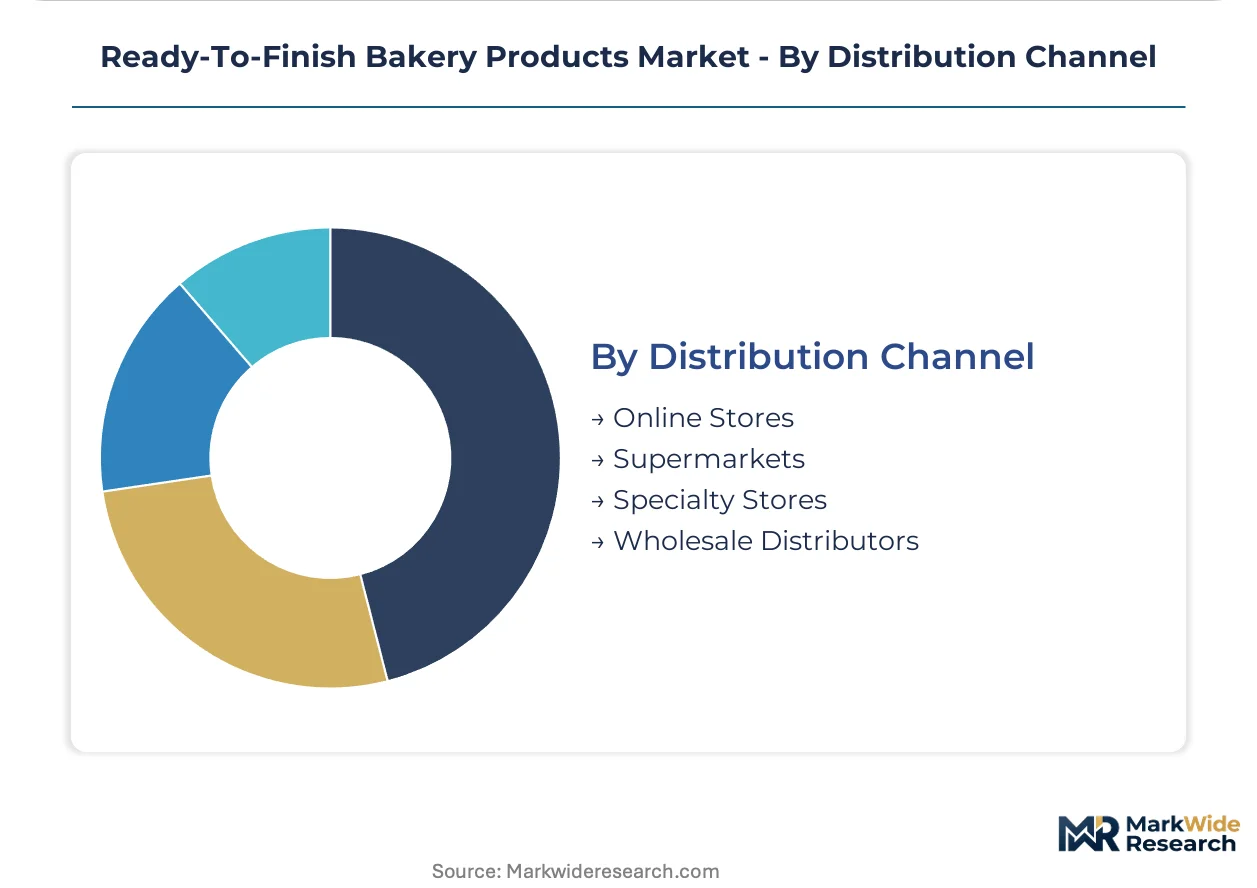
Distribution Channel:
Refrigerated logistics capacity constraints and procurement digitization reshape channel economics for temperature-sensitive formulations.
- Online Stores:Direct-to-operator platforms are disintermediating traditional broadline distributors in secondary United States markets by connecting artisan bakeries to regional frozen dough suppliers.
- Supermarkets:Retail grocery chains with captive cold-chain infrastructure capture frozen dough and par-baked volume through vertical integration into in-store bakery operations.
- Specialty Stores:Independent bakery supply retailers serve small-batch operators with fragmented purchasing patterns and high service-touch requirements.
- Wholesale Distributors:Broadline foodservice distributors with multi-temperature warehousing dominate chain restaurant supply through consolidated delivery economics and inventory pooling.
Scale efficiency favors wholesale distributors; margin capture favors online stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds European markets by roughly fifteen percent due to consolidated quick-service restaurant procurement and captive in-store bakery expansion at major retail chains. Developing Asian markets command freight-adjusted premiums that compress margins for exporters lacking localized freezing infrastructure.
United States
Quick-service restaurant chains drive frozen dough volume through standardized programs that eliminate variable proofing outcomes. The FDA enforces FSMA preventive controls that accelerate supplier consolidation as smaller co-manufacturers absorb compliance costs. Chicago and Minneapolis anchor production gravity for cryogenic freezing operations serving national distribution networks.
Germany
Artisan-channel demand for par-baked breads sustains premium positioning in European wholesale supply. The EU Green Deal's Farm-to-Fork sustainability targets reshape export specifications for processed food entrants. Munich and Stuttgart concentrate laminated-fat technology specialists serving foodservice accounts across Central Europe.
China
Western-style bakery chain expansion in tier-one cities pulls imported frozen dough volumes despite domestic flour milling capacity. The national food safety regulator enforces GB standards for imported bakery formulations that elevate documentation burdens for foreign suppliers. Shanghai and Beijing host cold-chain logistics hubs connecting regional bakery operations to international supply.
Brazil
Quick-service bakery concepts in São Paulo and Rio de Janeiro adopt frozen dough programs to reduce skilled labor dependency. ANVISA regulates imported food formulations with traceability requirements that favor established exporters with compliance infrastructure. The Southeast industrial corridor concentrates par-baked production for foodservice distributors serving institutional accounts.
India
Café chain expansion in Mumbai and Bangalore creates first-mover openings for cold-chain-capable frozen dough exporters. FSSAI mandates food safety licensing for imported bakery products that filters supplier participation to scale players. The National Capital Region and Maharashtra host emerging domestic production attempting to substitute import dependency.
Ready-To-Finish Bakery Products Market Competitive Landscape
Concentration sits with diversified food conglomerates and specialized frozen bakery suppliers. The vendor base separates into three tiers: multinational ingredient-integrated manufacturers, regional cryogenic specialists, and private-label co-manufacturers. Scale advantages accumulate around captive flour milling and proprietary freezing technology. Competitive moves center on backward integration into ingredient supply and geographic hub localization to reduce freight costs for temperature-sensitive formats.
Among North American diversified manufacturers, Dawn Food Products and Rich Products Corporation exemplify the ingredient-integrated archetype with captive supply chain control. Grupo Bimbo represents geographic dominance through localized production hubs. European specialists including Aryzta AG and Europastry occupy positions emphasizing artisan-channel par-baked formats. Associated British Foods and General Mills exemplify conglomerate portfolio diversification into ready-to-finish categories. Lantmannen Unibake and Vandemoortele represent regional European players with laminated-fat technology specialization.
| Leading Market Players |
|---|
| Dawn Food Products |
| Rich Products Corporation |
| Grupo Bimbo |
| Associated British Foods |
| Aryzta AG |
| Lantmannen Unibake |
| Europastry |
| General Mills |
| Vandemoortele |
| Others |
Value Network & Pricing Analysis
FSMA preventive controls certification gates supplier qualification and price differentiation simultaneously, as compliant co-manufacturers command premiums over non-certified competitors while buyers absorb audit costs into landed pricing. Frozen dough and par-baked formats stratify across premium artisan-channel positioning versus economy-scale QSR supply, with certification tier and volume scale as the dominant pricing axes.
Pricing Analysis
Configured-to-order pricing for custom-formulated frozen dough with specific moisture content and proofing parameters commands spreads of twenty to thirty percent above standard SKU pricing. Three-tier pricing structure across premium artisan-certified, standard FSMA-compliant, and economy private-label levels segments buyer access by technical service intensity and lot-level traceability. Pricing pressure stems from wheat futures volatility and compressed margins at co-manufacturers lacking forward-contract coverage. Quick-service restaurant procurement teams exhibit highest price sensitivity due to standardized menu economics, while independent artisan bakeries accept premiums for technical consultation and flexible minimum order quantities.
Supply Chain Analysis
Inventory positioning and lead-time compression favor regional freezing hubs over centralized national production, with frozen dough holding tolerance enabling safety stock reduction. Supply concentrates in the United States, Germany, and China, with Chicago-Stuttgart-Shanghai anchoring cryogenic freezing infrastructure for temperature-sensitive unbaked formulations. Hard red winter wheat and specialty flour grades, laminated-fat inputs, and refrigerant systems constitute critical raw material dependencies. Single-source vulnerability sits with third-party refrigerated logistics capacity in the Midwest United States, where seasonal peak demand creates fulfillment bottlenecks. Distribution runs through broadline foodservice distributors with multi-temperature warehousing for chain restaurant accounts, while direct-to-operator digital platforms disintermediate traditional channels in secondary markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts and preventive maintenance agreements for automated proofing-retardation equipment expand faster than hardware sales, converting capital expenditure into recurring revenue streams for suppliers with field engineering capabilities.
For Market Incumbents: Compound defensive positioning through captive flour milling integration and ammonia-based freezing retrofit investments that lock in compliance advantage as EPA refrigerant phasedown accelerates. Consolidate regional co-manufacturers facing FSMA infrastructure cost absorption to extend geographic hub coverage and compress freight costs for par-baked formats. Threat substitution from modular IoT-enabled proofing units requires technical service bundling to preserve equipment attach rates. For New Entrants and Emerging Players: Differentiate on clean-label formulation capabilities that satisfy EU Green Deal Farm-to-Fork procurement criteria for European wholesale channel entry. Target underpenetrated Southeast Asian quick-service bakery chains in Indonesia and Vietnam lacking localized frozen dough infrastructure. Deploy direct-to-operator e-commerce platforms disintermediating broadline distributors in secondary United States markets as the primary go-to-market angle. For Investors and Strategic Acquirers: FSMA compliance deadline reshapes the acquisition landscape toward distressed co-manufacturers with certified infrastructure but underutilized capacity. Long-term viability favors ingredient-integrated manufacturers with backward integration into flour milling and proprietary cryogenic technology. Watch EPA refrigerant enforcement intensity as the signal indicating accelerated retrofit capital deployment and consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Flour Milling | Dawn Food Products and Rich Products Corporation sustain margin control through captive wheat processing and specialty flour supply. |
| Cryogenic Freezing Technology Licensing | Liquid nitrogen and CO2 cascade systems extend distribution radii for unbaked formulations without quality degradation. |
| FSMA Compliance Certification Investment | Preventive controls infrastructure separates viable suppliers from exiting co-manufacturers unable to absorb audit costs. |
| Direct-to-Operator E-Commerce Platform Launch | Digital procurement disintermediates broadline distributors in secondary markets, capturing margin from fragmented artisan bakery demand. |
| EU Green Deal Sustainability Certification | Farm-to-Fork alignment commands procurement preference from European contract foodservice accounts for par-baked exports. |
Research Methodology
Desk research of FDA FSMA guidance documents, EPA refrigerant phasedown regulations, and EU Green Deal Farm-to-Fork specifications preceded structured interviews with quick-service restaurant procurement directors, frozen dough plant managers, cold-chain logistics operators, and artisan bakery owners. Secondary validation drew from customs trade data for wheat and flour imports, SEC filings of diversified food manufacturers, and industry association production surveys. Bottom-up volume estimates by product type and end-use channel were cross-checked against top-down market sizing from trade flow analysis.
Variance decomposition across product type, end-user segment, packaging format, and distribution channel informed the analytical framework over the projection horizon. CAGRs were derived from regression-based trend extrapolation adjusted for regulatory inflection points and technology adoption curves. Modeled inputs included frozen dough moisture-content specifications, par-baked bread finish-baking parameters, and cryogenic freezing capacity expansion timelines by production hub.
Material uncertainties — wheat price volatility, refrigerated logistics capacity constraints, and clean-label reformulation stability — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement intensity and cold-chain infrastructure investment that may shift with commodity cycles or policy changes. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
APMEA Frozen Bakery Products Market
Bakery Products
Low Calorie Muffins Market
Bakery Products
Qatar Bakery Product Market
Bakery Products
Global Wafer Biscuits Market
Bakery Products
Baking Molds and Trays Market
Bakery Products
Asia-Pacific Bakery Products Market
Bakery Products
No-Fat Cake Market
Bakery Products
GCC Frozen Bakery Products Market
Bakery Products
Low-Calorie Pie Market
Bakery Products
Multigrain Bread Mix Market
Bakery Products
Specialty Bakery Market
Bakery Products
Low-Calorie Toast Market
Bakery Products
Bread Mix Market
Bakery Products
Bakers Yeast Market
Bakery Products
Global Bakery Product Market
Bakery Products
Bread and Baked Food Market