
 Europe Zwieback Market | 2026-2036
Europe Zwieback Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Zwieback Market Foresight
The EU Green Deal is consolidating demand for sustainably sourced zwieback across Europe. Bahlsen GmbH & Co. KG leverages its century-old brand heritage to dominate premium shelf positioning in German retail channels. Dr. Schär AG specializes in gluten-free formulations that anchor its presence in health-conscious segments. Carl Brandt sustains competitive differentiation through its control of traditional baking methods and regional distribution networks.
Zwieback denotes a twice-baked bread product with moisture content below four percent, manufactured through a controlled staling and rebaking process that yields extended shelf stability without preservatives. The product serves commercial and household buyers seeking durable, portable bread alternatives for infant feeding, travel provisions, and digestive-sensitive diets. Whole wheat and gluten-free product types are capturing expanding margin pools as health-positioned variants command price premiums over traditional formulations. Supermarkets and online retail distribution channels are experiencing the fastest volume growth, while specialty stores retain higher per-unit profitability through curated assortments.
EFSA nutritional labeling requirements and the EU Green Deal farm-to-fork strategy are tightening ingredient traceability and clean-label expectations for zwieback producers. REACH chemical safety standards and national food contact material regulations in Germany and France govern packaging compliance across the supply chain. Stakeholders must monitor evolving EU organic certification thresholds and carbon accounting rules to maintain market access and brand positioning.
Market Dynamics
The EU Green Deal's farm-to-fork sustainability targets are forcing zwieback manufacturers to reconfigure ingredient sourcing and carbon accounting practices across European production networks.
Growth Catalysts
- Clean-label infant nutrition demand:Parents in Germany and France prioritize preservative-free, twice-baked bread products for weaning diets, expanding household penetration.
- REACH packaging compliance:Tighter chemical safety standards for food contact materials are accelerating adoption of recyclable paper-based wrapping solutions.
- Gluten-free formulation advances:Rice and buckwheat flour substitutes now achieve comparable shelf stability to wheat-based originals, unlocking allergen-sensitive segments.
Market Restraints
- Wheat price volatility:Ukrainian grain supply disruptions and drought cycles in EU breadbasket regions compress margin predictability for traditional formulations.
- Energy-intensive rebaking:The double-bake process requires sustained oven temperatures above 180°C, exposing producers to natural gas price spikes.
- Fresh bread substitution:Local bakery revival movements in Italy and Spain position crusty loaves as superior sensory alternatives for adult consumers.
Strategic Opportunities
- Eastern European underpenetration:Poland and Romania show nascent zwieback consumption with minimal branded presence, offering first-mover positioning.
- EU organic certification thresholds:Relaxed transition rules for small-scale bakeries enable faster organic zwieback qualification and premium pricing capture.
- Online direct-to-consumer channels:Subscription models for digestive-health product bundles bypass supermarket slotting fee structures.
Industry Challenges
- Traditional baker skill scarcity:Mastery of controlled staling and moisture management below four percent requires apprenticeships exceeding 24 months.
- EFSA nutritional labeling timelines:Novel health claim submissions for gut-friendly positioning face 18-month scientific review backlogs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Zwieback Market |
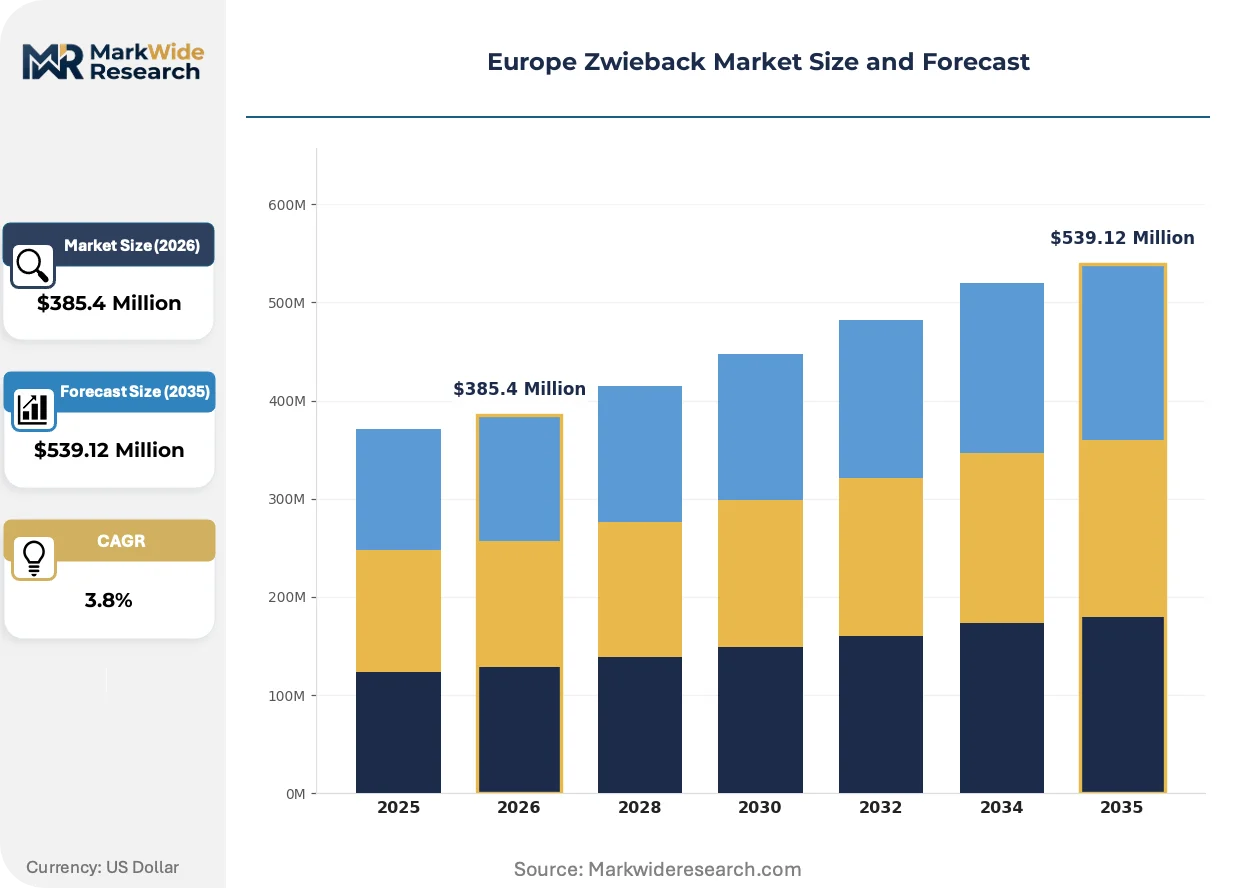
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $539.12 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional, Whole Wheat, Gluten-Free, Flavored Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Wholesale Packaging Type: Bags, Boxes, Tins, Bulk End User: Households, Cafés, Restaurants, Bakeries |
| Companies Covered | Carl Brandt, Lieken AG, Bahlsen GmbH & Co. KG, Dietrich Borggreve Zwieback- & Keksfabrik, Dr. Schär AG, Biback Zwiebackfabrik SOMMER GmbH, Brandt Zwieback-Schokoladen GmbH + Co. KG, ErdmannHAUSER, Roland Murten AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Zwieback Market Shifts & Advancements
Automation and sustainability mandates are converging to reshape zwieback manufacturing economics, with digital process control and regenerative agriculture practices emerging as decisive competitive differentiators.
Precision moisture sensors coupled with AI-driven oven controls are automating the critical second-bake phase that determines shelf stability. Mid-sized German producers are retrofitting legacy lines with these systems to reduce waste rates. The technology is automating quality consistency previously dependent on veteran baker judgment, compressing training cycles and defect rates simultaneously.
EFSA nutritional labeling requirements are tightening substantiation standards for digestive health claims on zwieback packaging. Manufacturers must now provide clinical trial data linking specific fiber content to gut microbiome benefits. The regulation most affects gluten-free specialists seeking premium positioning, forcing reformulation investments or claim abandonment.
Health-conscious German households are consolidating purchases through curated online specialty retailers rather than supermarket center aisles. These platforms bundle zwieback with complementary infant foods and travel provisions, capturing higher basket values. The shift concentrates most visibly in Berlin and Munich urban districts where subscription penetration exceeds rural benchmarks.
Europe Zwieback Market Segmentation
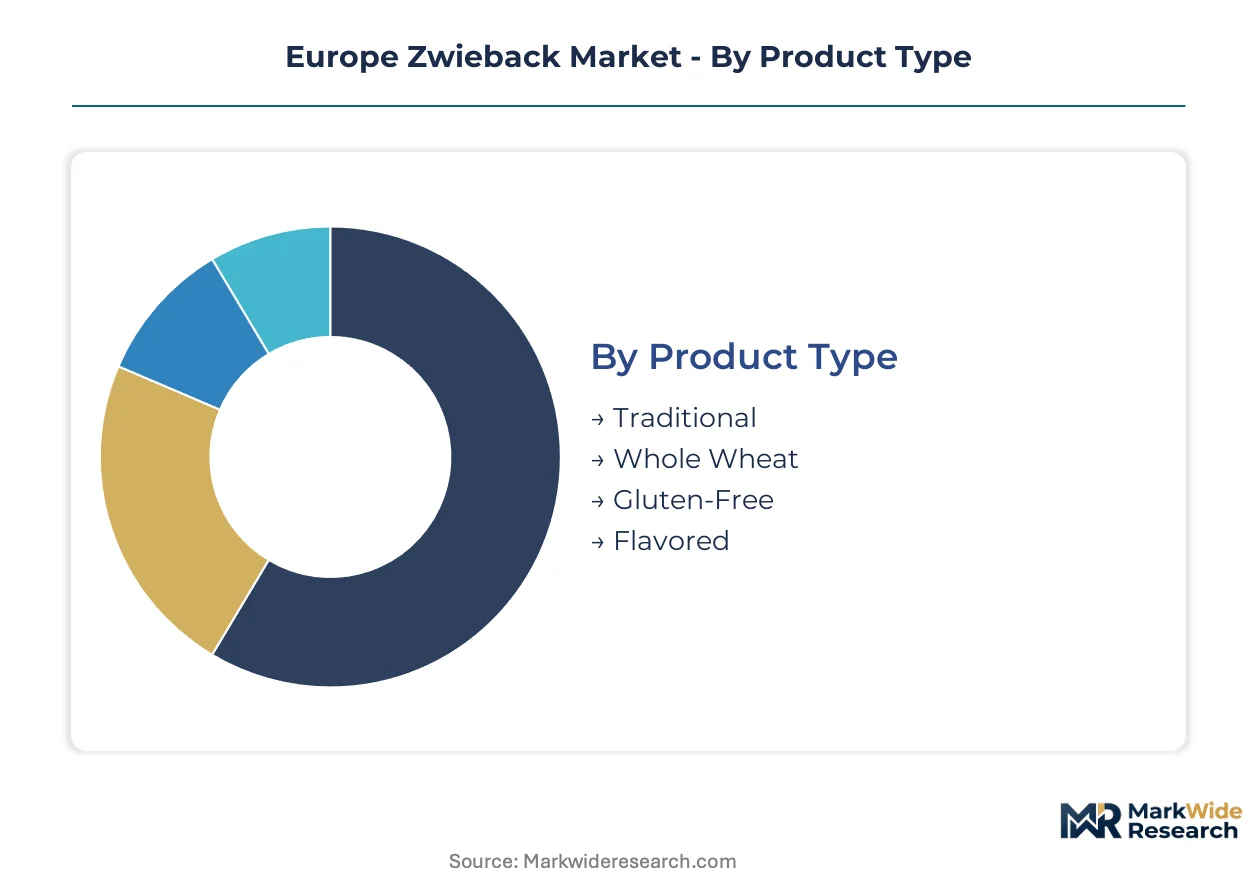
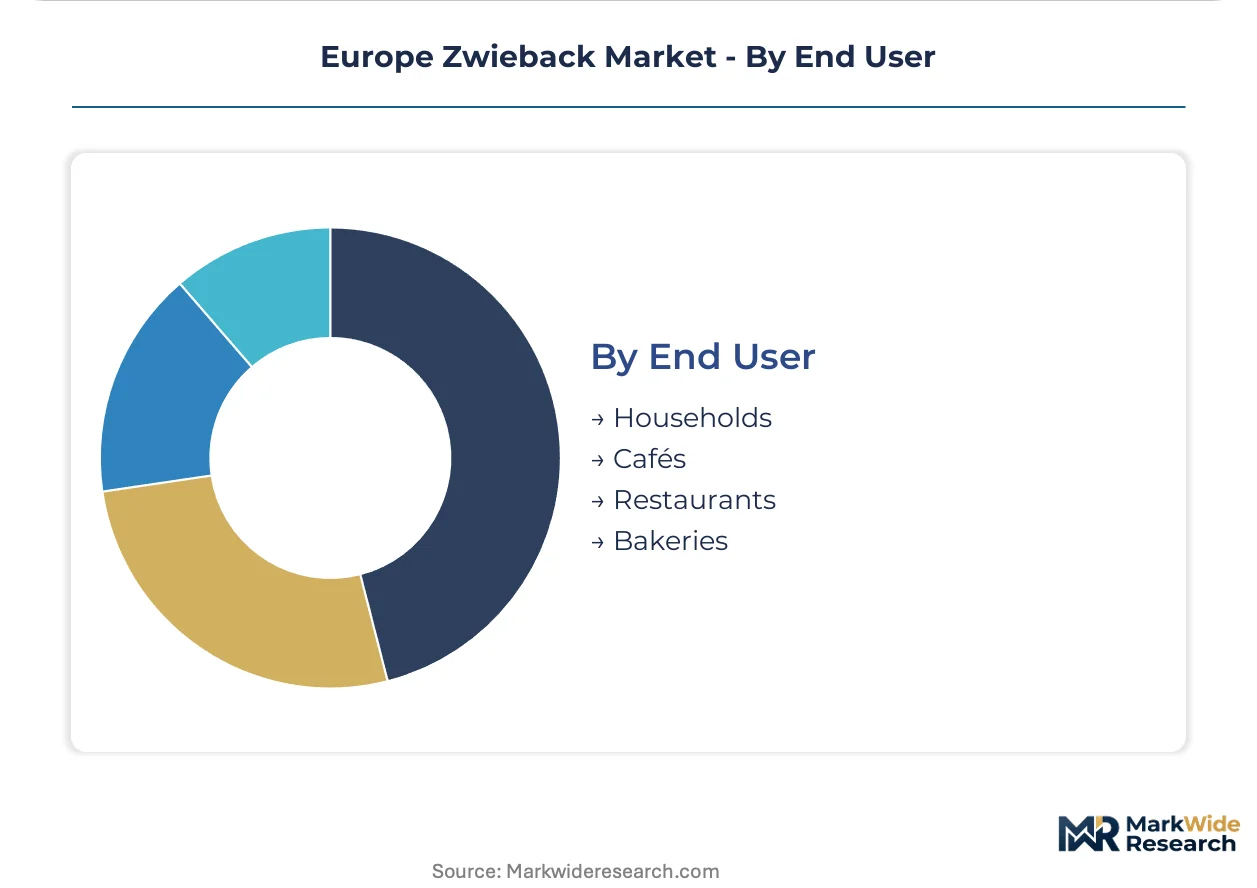
Zwieback demand fragments across four distinct category axes, each revealing divergent margin profiles and channel access requirements. Manufacturers must calibrate portfolio depth against the specific technical and regulatory demands of each segment cluster.
Product Type:
Buyer priorities shift from shelf stability in traditional formats to digestive tolerance in health-positioned variants, with willingness-to-pay escalating accordingly.
- Traditional:Wheat-based formulations with moisture content below four percent deliver maximum shelf life without preservatives. German households anchor volume here, though EFSA clean-label scrutiny is compressing permissible additive lists and reformulation costs.
- Gluten-Free:Rice and buckwheat flour substitutes achieve comparable staling resistance through modified rebaking curves. France and Belgium show concentrated demand from diagnosed celiac populations and preemptive avoiders, commanding substantial price premiums over wheat equivalents.
- Whole Wheat:Fiber-enriched positioning targets health-conscious parents in urban German districts. Bran inclusion complicates moisture management during second-bake phases.
- Flavored:Cinnamon and anise variants occupy seasonal gifting niches, with limited year-round rotation in mainstream retail.
Volume sits with Traditional; growth tilts toward Gluten-Free.
Distribution Channel:
Channel selection determines slotting fee exposure, margin retention, and the depth of consumer education possible at point of purchase.
- Supermarkets:Discounters and full-service chains in Germany and the Netherlands move standard-format zwieback at high velocity, though listing fees and promotional depth requirements erode manufacturer margins. REWE and Edeka centralize purchasing power.
- Online Retail:Direct-to-consumer platforms enable subscription bundling with complementary infant foods, capturing recurring revenue streams without intermediary markups. Berlin and Munich show penetration rates exceeding rural benchmarks.
- Specialty Stores:Organic and allergen-focused retailers in Scandinavia curate premium assortments with extended shelf-facing and staff recommendation protocols.
- Wholesale:Foodservice distributors supply cafés and bakeries seeking ingredient-grade zwieback for dessert bases and crumb coatings.
Supermarkets dominate transaction volume; online channels are expanding most quickly.
Packaging Type:
Material choice reflects the tension between shelf-life engineering and EU Green Deal packaging waste directives, with compliance costs varying by format complexity.
- Bags:Multi-layer laminates with moisture barriers dominate mass-market SKUs, though REACH chemical safety standards are accelerating migration to recyclable paper-based alternatives.
- Boxes:Rigid cartons support premium positioning and gift assortments, with FSC certification increasingly baseline for German retail acceptance.
- Tins:Metal containers retain collectible value for heritage brands, limited to commemorative editions and export markets.
- Bulk:Unpackaged formats serve foodservice and bakery ingredient channels, minimizing per-unit material cost.
Bags capture the highest shipment volumes; box formats are gaining share fastest on sustainability credentials.
End User:
Final consumption context dictates formulation specifications, from infant-safe moisture levels to commercial durability requirements.
- Households:Parents purchasing for weaning diets and travel provisions prioritize single-serve convenience and clean-label ingredient decks. German family demographics concentrate demand.
- Cafés:Coffee-serving establishments in Italy and Austria deploy zwieback as dessert accompaniments and breakfast plate components, favoring individually wrapped portions.
- Restaurants:Fine-dining kitchens utilize zwieback crumbs for texture applications in plated desserts and savory coatings.
- Bakeries:Artisan producers incorporate commercial zwieback into cheesecake bases and layered confections, requiring consistent particle size and moisture specifications.
Households anchor absolute consumption; foodservice channels are climbing the fastest on post-pandemic away-from-home recovery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hanover anchors European zwieback manufacturing heritage, with Lower Saxony's industrial baking corridor concentrating century-old production infrastructure and specialized workforce pools that supply distribution networks across the continent.
Germany
German households purchase the majority of European zwieback volume, driven by infant weaning traditions and travel-provision stocking patterns. EFSA nutritional labeling requirements enforce strict substantiation standards for digestive health claims on packaging. The Hanover-Bielefeld corridor hosts concentrated baking facilities where precision moisture-control technology is displacing manual oven supervision.
France
French demand clusters around gluten-free formulations serving diagnosed celiac populations in Paris and Lyon metropolitan areas. ANSM oversees novel food ingredient approvals for rice and buckwheat flour substitutes entering zwieback recipes. Brittany's organic grain cooperatives are contracting directly with manufacturers to secure regenerative agriculture sourcing credentials.
Italy
Italian consumption concentrates in northern regions where zwieback serves as dessert accompaniment in Milan and Turin café cultures. REACH chemical safety standards govern packaging material compliance for multi-layer laminates used in humid Mediterranean climates. Emilia-Romagna's food machinery builders are exporting automated rebaking lines to German producers seeking energy efficiency upgrades.
Netherlands
Dutch retail channels move high-velocity standard-format zwieback through Rotterdam-centered distribution hubs serving Benelux markets. EU Green Deal farm-to-fork traceability requirements are accelerating blockchain adoption for ingredient provenance documentation. Amsterdam's sustainable packaging startups are piloting recyclable paper barriers that maintain sub-four-percent moisture seals.
Poland
Polish zwieback consumption remains nascent with minimal branded presence, creating first-mover positioning opportunities for heritage manufacturers. The country's national food safety regulator enforces harmonized EU hygiene standards while transitional organic certification rules enable faster qualification timelines. Warsaw's emerging specialty food retailers are testing curated zwieback assortments alongside Scandinavian import lines.
Europe Zwieback Market Competitive Landscape
The competitive structure tilts toward heritage-brand specialists with multi-generational market presence. German and Swiss producers command premium shelf positioning through controlled distribution relationships and regional manufacturing density. Three archetypes dominate: century-old family enterprises leveraging brand equity, gluten-free specialists capturing health-conscious segments, and industrial-scale bakers optimizing commodity formulations. Strategic moves concentrate on automated production retrofits and direct-to-consumer channel development bypassing supermarket slotting structures.
Among German heritage manufacturers, Bahlsen GmbH & Co. KG and Carl Brandt occupy positions exemplifying premium-brand archetypes built on regional loyalty and traditional baking credentials. Dr. Schär AG represents the health-specialist vector, anchoring gluten-free formulation expertise that commands substantial price premiums in French and Belgian markets. These three entities illustrate how competitive positioning fragments across brand-heritage, health-specialization, and scale-efficiency vectors rather than consolidating around unified strategies.
| Leading Market Players |
|---|
| Carl Brandt |
| Lieken AG |
| Bahlsen GmbH & Co. KG |
| Dietrich Borggreve Zwieback- & Keksfabrik |
| Dr. Schär AG |
| Biback Zwiebackfabrik SOMMER GmbH |
| Brandt Zwieback-Schokoladen GmbH + Co. KG |
| ErdmannHAUSER |
| Roland Murten AG |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap baking specialists anchor European zwieback production, their generational capital structures enabling patient investment in precision moisture-control equipment while insulating pricing discipline from quarterly earnings pressure. This ownership pattern concentrates supply-side bargaining power in Lower Saxony's Hanover-Bielefeld corridor, where multi-decade supplier relationships with organic grain cooperatives translate into input cost stability that supports premium price maintenance.
Pricing Analysis
Value-based pricing anchored to infant-safe moisture outcomes dominates premium tiers, with sub-four-percent moisture guarantees commanding substantial premiums over standard shelf-stable formats. Three-tier pricing structure across premium, standard, and economy levels separates heritage-branded organic lines from private-label discounter offerings, with certification tier (EU organic, Demeter, conventional) operating as the primary differentiation driver. Pricing pressure stems from energy-intensive rebaking costs, with natural gas price volatility compressing margins in mid-tier segments. Discounter-channel households exhibit highest price sensitivity, while specialty-retail parents purchasing for weaning diets demonstrate lowest elasticity.
Supply Chain Analysis
EU organic certification thresholds gate upstream access, with regenerative agriculture credentials increasingly mandatory for German retail listing. Supply concentrates in Germany, France, and Italy, with Lower Saxony hosting precision baking equipment clusters and Brittany supplying organic grain contracts. Raw material dependencies center on wheat, rice flour, and buckwheat substitutes, with Ukrainian grain disruptions elevating sourcing risk. Single-source vulnerability characterizes heritage-brand proprietary rebaking curves, where veteran baker expertise remains non-substitutable. Distribution runs through Rotterdam-centered logistics hubs serving Benelux supermarkets, with direct-to-consumer channels bypassing traditional wholesale layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AI-driven oven control systems are displacing manual baker judgment in moisture management, compressing training cycles from 24-month apprenticeships to algorithm-assisted quality protocols. This technology transition rewards producers capable of retrofitting legacy lines while marginalizing traditionalists dependent on craft expertise.
For Market Incumbents: To counter automation-driven margin compression from mid-sized German competitors, heritage manufacturers should deepen backward integration into organic grain milling and secure exclusive distribution slots in curated online specialty retailers. Certification investment in regenerative agriculture sourcing under EU Green Deal farm-to-fork protocols offers defensive positioning against clean-label entrants. For New Entrants and Emerging Players: Enter via Poland's nascent specialty food retail channel, where minimal branded presence and relaxed organic transition rules enable faster qualification timelines than saturated German markets. Direct-to-consumer subscription bundling with complementary infant foods captures recurring revenue without supermarket slotting fee exposure, with Warsaw and Kraków offering test-bed demographics. For Investors and Strategic Acquirers: Distressed-cycle entries favor gluten-free specialists with established rice and buckwheat formulation expertise in French and Belgian markets, where celiac-population demand commands durable price premiums. Long-term viability hinges on automation retrofit completion and direct-to-consumer channel penetration. The signal to watch is EFSA nutritional labeling backlog resolution, which will unlock gut-friendly health claim positioning for prepared acquirers.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Moisture Sensor Deployment | AI-driven oven controls from Emilia-Romagna equipment builders reduce waste rates and compress quality variance. |
| Regenerative Agriculture Sourcing | Brittany organic grain cooperatives supply EU Green Deal-compliant ingredient provenance for German retail access. |
| Direct-to-Consumer Channel Launch | Berlin and Munich subscription models bypass REWE and Edeka slotting fee structures while capturing higher basket values. |
| Gluten-Free Formulation Expansion | Rice and buckwheat substitutes unlock French and Belgian celiac-population segments with substantial price premiums. |
| Recyclable Packaging Transition | Amsterdam sustainable packaging startups pilot paper barriers satisfying REACH chemical safety standards. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, with primary interviews conducted across plant managers at German baking facilities, procurement leads at REWE and Edeka central buying offices, organic grain cooperative agronomists in Brittany, and regulatory affairs specialists navigating EFSA nutritional labeling requirements. Secondary sources included EU Green Deal implementation documents, REACH chemical safety compliance databases, ANSM novel food ingredient approvals, and Hanover industrial baking cluster economic development reports. Bottom-up volume modeling triangulated against top-down category spending estimates from retail audit data.
Data-stream reconciliation across shipment volumes, ingredient input costs, and channel price points informed the analytical framework. Segmentation dimensions spanned product type (traditional, gluten-free, whole wheat, flavored), distribution channel (supermarkets, online retail, specialty stores, wholesale), and end-user context (households, cafés, restaurants, bakeries). CAGRs were derived from trend extrapolation adjusted for technology adoption curves and regulatory implementation timelines. Forecast inputs incorporated energy cost scenarios for natural gas-dependent rebaking processes and organic certification transition pace under EU farm-to-fork protocols.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained Ukrainian grain supply disruption or accelerated EFSA health claim substantiation requirements. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Bahrain Bakery Product Market
Bakery Products
Low Fat Bran Muffins Market
Bakery Products
Healthy Biscuits Market
Bakery Products
Sourdough Market
Bakery Products
South America Ice Cream Market
Bakery Products
Bakery Cases Market
Bakery Products
No-Fat Cake Market
Bakery Products
North America Pizza Oven Market
Bakery Products
Low-Calorie Breakfast Muffins Market
Bakery Products
Fortified Bakery Market
Bakery Products
United States Cookies Market
Bakery Products
Bread Dough Improver Market
Bakery Products
Laminated Dough Market
Bakery Products
Pastry Margarine Market
Bakery Products
Malted Rye Flour Market
Bakery Products
Gluten-Free Baking Mixes Market