
 GCC Bakery Products Market | 2026-2036
GCC Bakery Products Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Bakery Products Market Intelligence
The capital-intensity divergence between automated industrial lines and artisan-scale operations is reorganizing competitive dynamics across the GCC. Agthia Group leverages its integrated flour-to-retail infrastructure to dominate ambient bread supply in the UAE and Saudi Arabia. Americana Group sustains broad foodservice penetration through centralized production hubs serving quick-service restaurant chains. Almarai Company anchors dairy-adjacent bakery growth by controlling chilled distribution networks that extend product shelf life.
GCC bakery products comprise wheat-flour-based, yeast-leavened or chemically raised goods manufactured through continuous mixing, proofing, and thermal processing, with formulations typically specifying protein content between 11-14% for bread applications and fat ratios of 15-25% for laminated pastries. The industrial purpose spans retail nourishment, foodservice accompaniment, and hospitality dessert presentation across temperature-controlled supply chains. Bread commands the largest volume share within product type segmentation, though gluten-free options are expanding fastest as health-positioned SKUs multiply in UAE and Saudi supermarkets. Distribution channel segmentation tilts toward supermarkets for packaged goods, while specialty shops capture margin pools in premium cakes and custom pastries for celebrations.
Saudi Arabia's SFDA and the UAE's Ministry of Climate Change and Environment enforce Gulf Standardization Organization food safety benchmarks that mandate ingredient traceability and limit artificial additive use, compelling manufacturers to reformulate or risk market exclusion. Saudi Arabia's Quality of Life Program and UAE National In-Country Value certification further steer procurement toward domestic production and local workforce development. Stakeholders must monitor how evolving halal certification interoperability across Bahrain, Oman, and Kuwait reshapes cross-border product registration and logistics planning.
Market Dynamics
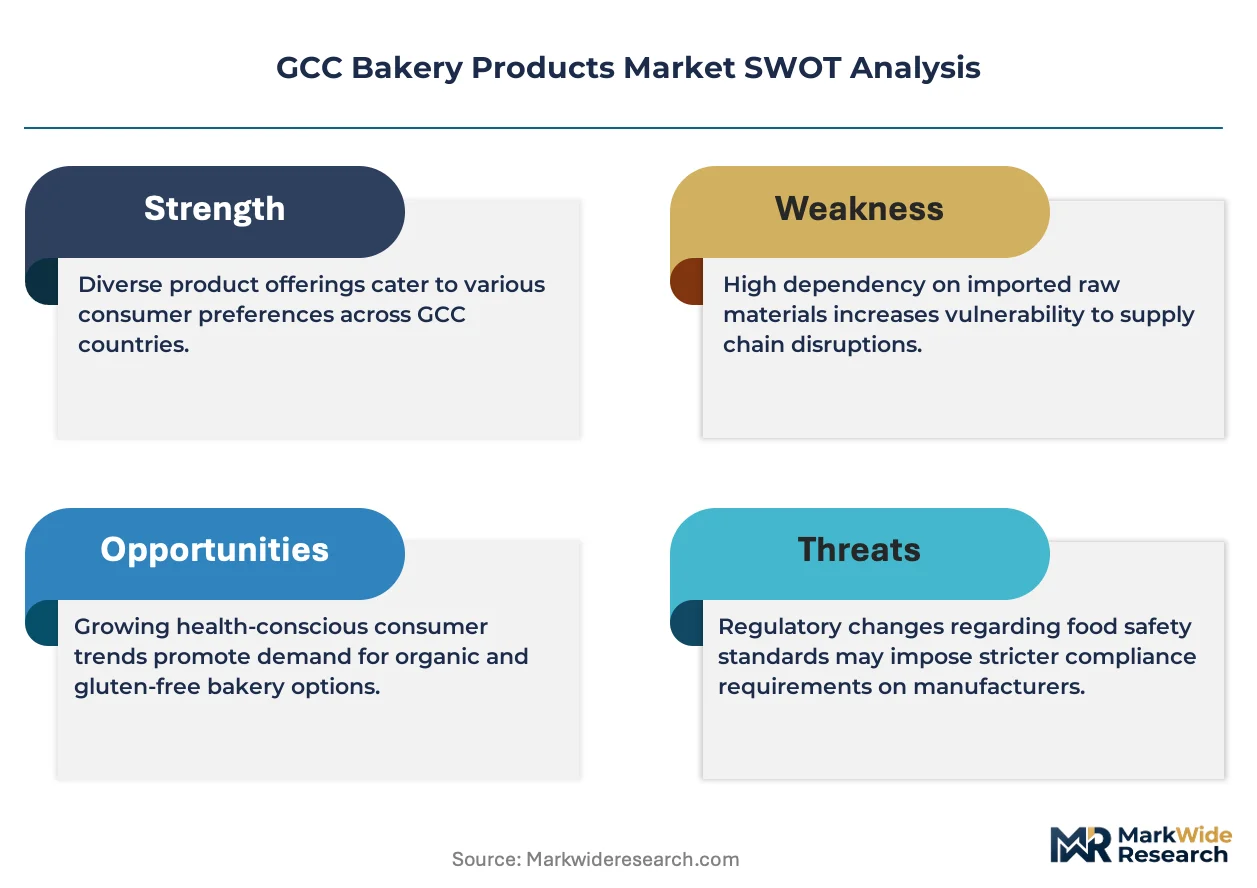
Capital-intensity divergence between automated industrial lines and artisan-scale operations is reorganizing competitive dynamics across the GCC. Foodservice procurement consolidation and hospitality investment waves are compressing margins for mid-tier producers while rewarding integrated flour-to-retail infrastructure.
Growth Catalysts
- Hospitality Investment Waves:Hotel chains in Dubai and Abu Dhabi anchor high-volume artisanal bread and pastry contracts. Foodservice businesses expand premium baked goods procurement as Gulf tourism infrastructure scales.
- SFDA Labeling Enforcement:Saudi Arabia's updated food labeling standards push reformulation toward cleaner ingredient decks. Manufacturers reformulate or risk market exclusion from the kingdom's retail channels.
- Chilled Distribution Networks:Dairy-adjacent bakery growth accelerates through controlled cold chain extension. Product shelf life expansion unlocks new retail placement opportunities in ambient and chilled aisles.
Market Restraints
- Wheat Import Dependency:GCC states source over ninety percent of wheat through international suppliers. Currency fluctuation and shipping disruption transmit directly to input cost volatility.
- Flour Milling Concentration:Integrated agribusiness groups control upstream flour supply in the UAE and Saudi Arabia. Independent bakeries face margin compression from captive raw material pricing.
- Artisan Labor Scarcity:Traditional laminated pastry and sourdough bread production requires skilled craft labor. Visa-dependent workforce structures limit talent pipeline reliability.
Strategic Opportunities
- Gluten-Free SKU Expansion:Health-positioned product lines multiply in UAE and Saudi supermarkets. Dedicated production lines capture premium pricing from diet-specific consumer segments.
- In-Country Value Certification:UAE National In-Country Value certification steers procurement toward domestic production. Local workforce development investments qualify suppliers for preferential contract terms.
- Halal Certification Interoperability:Evolving cross-border recognition standards between Bahrain, Oman, and Kuwait reshape product registration logistics. Unified certification reduces duplicate compliance costs for multi-market distribution.
Industry Challenges
- Reformulation Timeline Compression:Gulf Standardization Organization additive limits force rapid ingredient deck changes. Product stability testing and consumer acceptance trials must accelerate without quality compromise.
- Integrated System Migration:Legacy batch processing equipment lacks connectivity to continuous monitoring platforms. Capital requirements for automated proofing and thermal processing lines strain mid-tier balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Bakery Products Market |
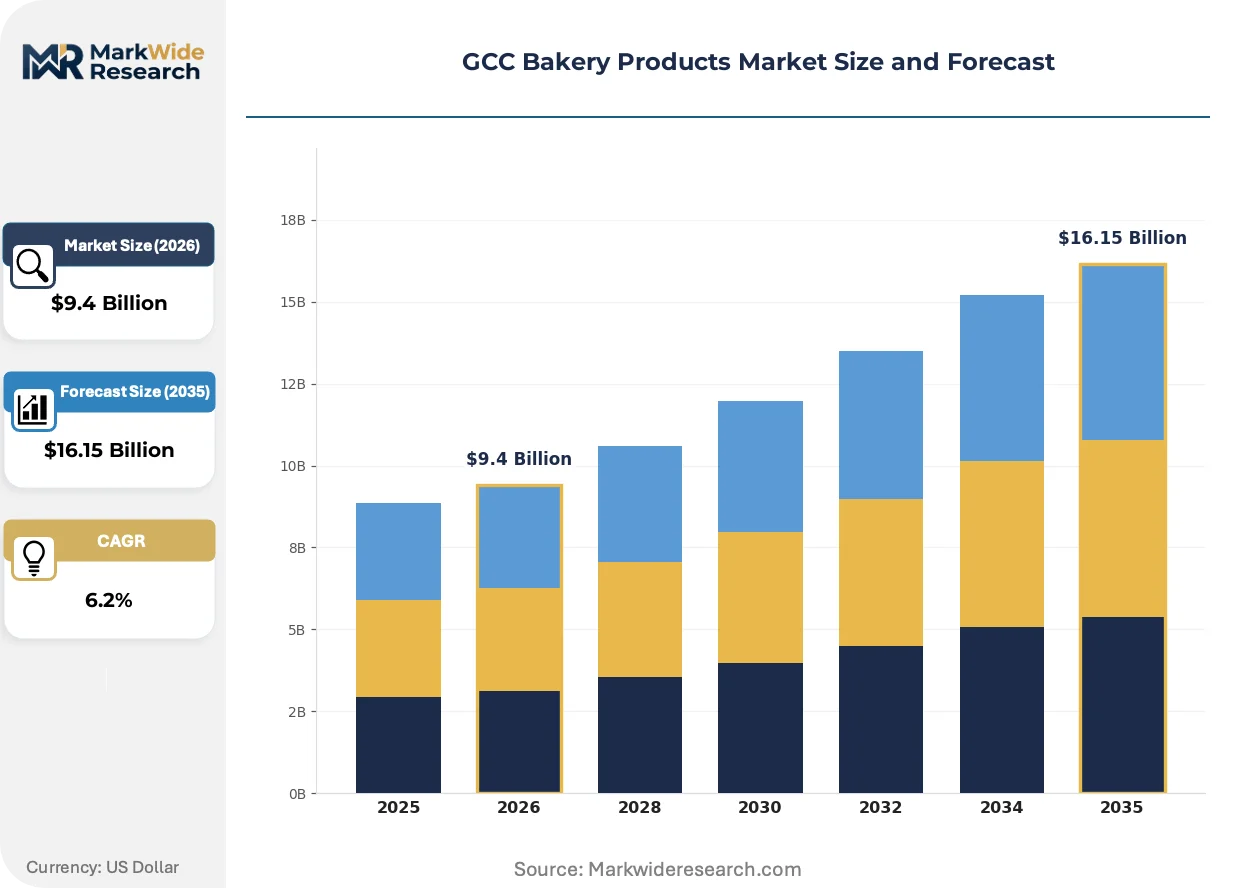
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $16.15 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bread, Pastries, Cakes, Crackers Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Shops Customer Type: Retail Consumers, Foodservice Businesses, Hotels, Bakeries Ingredient Type: Wheat Flour, Sugar, Yeast, Gluten-Free Options |
| Companies Covered | Agthia Group, Dawn Food Products, Americana Group, General Mills, Mondelez International, Sunbulah Group, Aryzta AG, Modern Bakery LLC, Almarai Company, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Bakery Products Market Strategic Shifts & Innovations
Active fermentation monitoring and enzyme-based dough conditioning are reshaping production economics across industrial and artisan GCC bakeries. These technologies compress variability while extending distribution reach.
Continuous mixing systems equipped with real-time hydration sensors are supplanting traditional batch kneading in high-volume bread operations. Saudi industrial bakeries adopt these platforms to reduce labor dependence and standardize protein network development. The technology is compressing unit economics for ambient bread while displacing smaller batch producers from supermarket supply contracts.
SFDA enforcement of ingredient traceability mandates is tightening supply chain documentation requirements. Manufacturers must implement lot-level tracking from flour mill to retail shelf. Saudi Arabia's bread and pastry segments are responding by consolidating supplier bases to reduce audit complexity.
Hotel and airline catering procurement teams now specify frozen par-baked goods over fully finished products. Central commissaries finish baking on-site to ensure aroma and crust texture at service. This pattern concentrates most visibly in Dubai's luxury hospitality cluster where guest experience metrics drive specification tightening.
GCC Bakery Products Market Segmentation
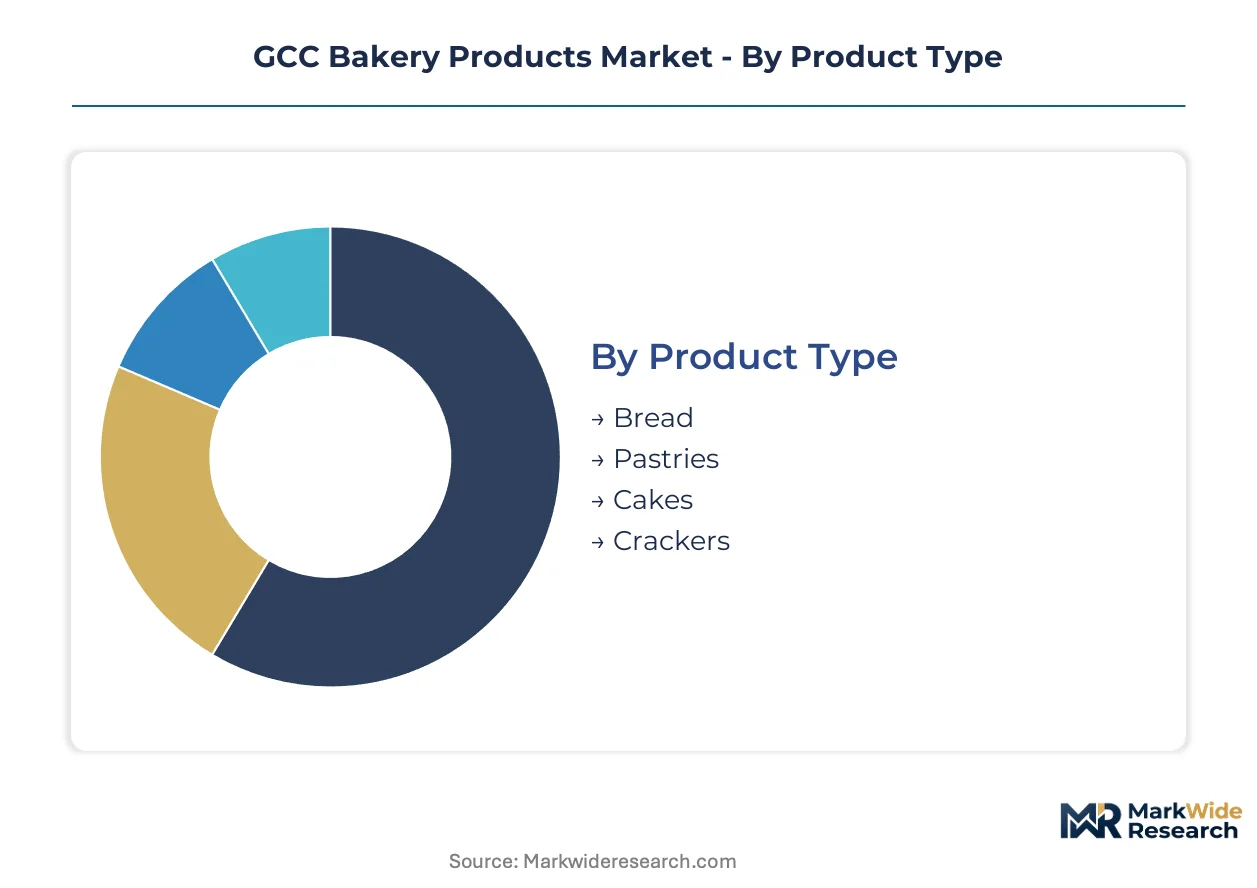
Segmentation in the GCC bakery sector reveals divergent margin structures between commodity bread and premium pastry lines. Distribution channel dynamics and ingredient specification tiers determine competitive positioning for manufacturers serving Saudi Arabia and UAE retail networks.
Product Type:
Domestic production concentrates in ambient bread for retail shelves, while pastries and cakes serve export-oriented hospitality contracts across the Gulf.
- Bread:Wheat-flour-based formulations specify protein content between 11-14% for optimal gluten network development. Saudi Arabia's industrial bakeries anchor volume demand through supermarket supply contracts, though SFDA labeling enforcement is forcing rapid reformulation toward cleaner ingredient decks.
- Pastries:Laminated dough applications require fat ratios of 15-25% and skilled craft labor for layer integrity. Dubai and Abu Dhabi hotel chains drive specification tightening through frozen par-baked procurement models that concentrate finishing at central commissaries.
- Cakes:Celebration-oriented SKUs capture margin pools in premium tiers through custom decoration and portion sizing for hospitality dessert presentation.
- Crackers:Shelf-stable snacking formats extend distribution reach through ambient aisle placement in UAE and Saudi supermarkets.
Bread commands the established base. The steepest expansion runs through gluten-free positioned alternatives.
Distribution Channel:
Cost tier differentiation separates mass-market packaged goods from artisan-scale premium capture points.
- Supermarkets:Temperature-controlled supply chains enable bread and pastry placement across ambient and chilled aisles. Saudi Arabia's retail consolidation favors integrated flour-to-retail suppliers with national distribution coverage.
- Specialty Shops:Custom cake decoration and sourdough bread production require skilled labor and localized production. UAE urban centers support premium pricing through celebration-driven purchase occasions and hospitality contract fulfillment.
- Convenience Stores:Grab-and-go pastry and cracker formats target transit-oriented consumption in Dubai and Riyadh commercial corridors.
- Online Retail:Direct-to-consumer cake and artisan bread delivery is expanding fastest through platform partnerships in Saudi Arabia's major cities.
Supermarket channels anchor volume throughput. Specialty shops capture the widest margin spreads.
Customer Type:
Application intensity varies from daily nourishment to ceremonial presentation across temperature-controlled supply chains.
- Foodservice Businesses:Quick-service restaurant chains procure standardized bread and pastry formats through centralized production hubs. Americana Group's infrastructure exemplifies the scale requirements for multi-outlet supply.
- Hotels:Luxury hospitality procurement in Dubai specifies frozen par-baked goods over fully finished products to ensure aroma and crust texture at service.
- Retail Consumers:Packaged bread purchases concentrate in supermarket weekly shopping patterns across Saudi Arabia and UAE household segments.
- Bakeries:Independent operators face margin compression from captive flour pricing by integrated agribusiness groups controlling upstream supply.
Foodservice businesses generate the highest contract volumes. Hotels drive the most stringent quality specifications.
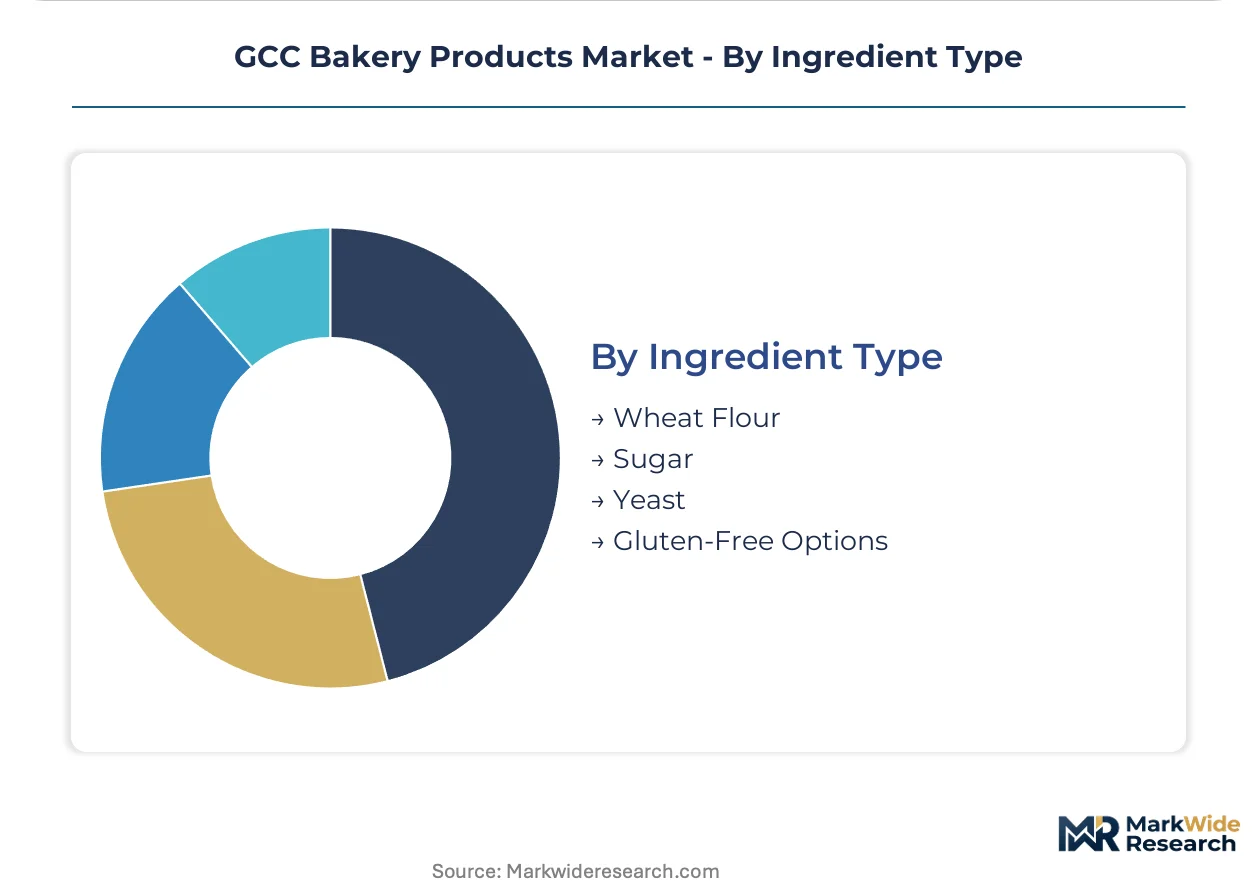
Ingredient Type:
Supply concentration in wheat milling shapes formulation economics, while alternative ingredients unlock premium positioning.
- Wheat Flour:Protein content specifications between 11-14% determine bread application suitability. GCC states source over ninety percent of wheat through international suppliers, transmitting currency fluctuation directly to input cost volatility.
- Gluten-Free Options:Rice, almond, and tapioca flour substitutes command premium pricing from diet-specific consumer segments. UAE and Saudi supermarkets are multiplying health-positioned SKUs fastest through dedicated production line investment.
- Sugar:Sweetness modulation and browning control function across cake and pastry categories with formulation stability requirements.
- Yeast:Active fermentation monitoring technologies are compressing variability in industrial bread operations while reducing labor dependence.
Wheat flour underpins the commodity base. Gluten-free alternatives are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the UAE where hospitality procurement commands premium tiers, while Saudi Arabia's retail consolidation compresses margins for mid-tier suppliers. This asymmetry shapes investment flows and capacity allocation decisions across the Gulf.
Saudi Arabia
Domestic flour milling integration and SFDA labeling enforcement drive supplier consolidation toward cleaner ingredient decks. The Quality of Life Program steers procurement toward domestic production and local workforce development. Riyadh's industrial bakeries anchor volume supply contracts for supermarket chains operating across the kingdom.
United Arab Emirates
Dubai and Abu Dhabi hotel chains anchor high-volume artisanal bread and pastry contracts through frozen par-baked procurement models. MOCCAE enforcement of Gulf Standardization Organization benchmarks mandates ingredient traceability from mill to retail shelf. Dubai's luxury hospitality cluster drives specification tightening for aroma and crust texture at service.
Kuwait
Foodservice procurement consolidation rewards integrated flour-to-retail infrastructure with national distribution coverage. Evolving halal certification interoperability standards reshape cross-border product registration logistics for multi-market suppliers. Kuwait City's retail network concentrates demand for ambient bread placement across temperature-controlled supermarket aisles.
Oman
Hospitality investment waves in Muscat generate contract volumes for premium pastry and celebration cake segments. Cross-border halal certification recognition with neighboring states reduces duplicate compliance costs for distribution network expansion. The capital's commercial corridors support grab-and-go pastry formats targeting transit-oriented consumption patterns.
Qatar
Chilled distribution network extension unlocks dairy-adjacent bakery placement in ambient and chilled retail aisles. Procurement teams specify frozen par-baked goods over fully finished products to ensure freshness metrics at service. Doha's hospitality procurement concentration drives quality specification tightening for bread and pastry supply contracts.
GCC Bakery Products Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the GCC bakery sector. Integrated agribusiness groups dominate upstream flour supply and ambient bread production through captive milling infrastructure. Mid-tier independent bakeries compete on artisan specialization and custom celebration cakes. Dominant competitive moves include backward integration into flour milling and strategic partnerships with hospitality procurement teams.
Within the integrated infrastructure tier, Agthia Group and Almarai Company exemplify players controlling upstream supply and chilled distribution networks. Americana Group occupies a position representing foodservice penetration through centralized production hub architecture. These three anchors illustrate how flour-to-retail integration, dairy-adjacent cold chain extension, and quick-service restaurant chain supply each constitute distinct competitive vectors.
| Leading Market Players |
|---|
| Agthia Group |
| Dawn Food Products |
| Americana Group |
| General Mills |
| Mondelez International |
| Sunbulah Group |
| Aryzta AG |
| Modern Bakery LLC |
| Almarai Company |
| Others |
Cost & Logistics Intelligence
SFDA labeling enforcement and halal certification interoperability gate both supplier qualification and price differentiation simultaneously across GCC bakery markets. Manufacturers must absorb compliance costs to access Saudi retail channels while premium tiers extract value from traceability documentation demanded by UAE hospitality procurement.
Pricing Analysis
Configured-to-order pricing for celebration cakes and artisan sourdough loaves commands spreads of three-to-five times over standard ambient bread SKUs. Three-tier pricing structure across premium, standard, and economy levels reflects gluten-free certification status, protein content grade, and volume commitment scale. Cost compression in mid-tier packaged bread is intensifying because retail consolidation favors integrated flour-to-retail suppliers with national distribution coverage. Quick-service restaurant chains exhibit highest price sensitivity through centralized procurement, while Dubai luxury hotels demonstrate lowest sensitivity due to guest experience metrics.
Supply Chain Analysis
Port congestion at Jebel Ali and container availability fluctuations on Asia-Gulf trade lanes inject lead-time variability into wheat flour and specialty ingredient inbound flows. GCC states draw from Australia, Canada, and Black Sea origins for wheat supply, with malt extracts and industrial yeast anchored in European manufacturing bases. Single-source vulnerability concentrates in integrated agribusiness groups controlling UAE and Saudi flour milling capacity. Distribution runs through temperature-controlled hub-and-spoke networks with final-mile bakery delivery to supermarket chains and hotel commissaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GCC bakery markets sit in early-cycle expansion as hospitality investment waves and health-positioned SKU proliferation extend penetration beyond traditional daily bread consumption into premium occasion-based segments.
For Market Incumbents: Secure backward integration into captive flour milling to neutralize raw material cost volatility from currency fluctuation. Anchor capacity expansion in Riyadh and Dubai to capture Quality of Life Program procurement preference and In-Country Value certification advantages. Defend against artisan-scale entrants by automating proofing and thermal processing lines that compress unit economics for ambient bread. For New Entrants and Emerging Players: Gluten-free production capacity gaps in Saudi secondary cities present white-space targets where supermarket chains under-serve diet-specific consumer segments. Frozen par-baked finishing services for independent hotels outside Dubai's luxury cluster offer penetrable contract entry points. Pursue platform partnerships with Saudi online retail aggregators to establish direct-to-consumer cake and artisan bread delivery presence. For Investors and Strategic Acquirers: SFDA enforcement timeline reshapes the acquisition landscape toward targets with validated clean-label reformulation pipelines and lot-level traceability systems already operational. Five-to-ten year viability favors chilled distribution network owners with dairy-adjacent bakery placement capabilities. Monitor halal certification interoperability negotiations between Bahrain, Oman, and Kuwait as signal for cross-border logistics scalability inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation | SFDA compliance unlocks Saudi supermarket shelf placement and commands premium positioning. |
| Chilled Distribution Extension | Almarai-style dairy network control extends product shelf life and retail aisle access. |
| Frozen Par-Baked Capacity | Dubai hotel procurement specifications concentrate contract volumes toward finish-at-service models. |
| Gluten-Free Line Investment | UAE and Saudi health-positioned SKU multiplication captures diet-specific premium pricing tiers. |
| In-Country Value Certification | UAE National ICV qualification steers government and hospitality procurement toward domestic production. |
Research Approach
A standing panel of bakery operations directors, flour mill procurement leads, hotel F&B executives, and supermarket category buyers provided ongoing calibration against market developments. Primary fieldwork combined structured interviews with supply chain managers at integrated agribusiness groups and artisan bakery owners in Dubai and Riyadh. Secondary validation drew from Gulf Standardization Organization food safety bulletins, Saudi SFDA labeling guidance documents, UAE Ministry of Climate Change and Environment circulars, and customs records of wheat import flows. Bottom-up capacity assessments at industrial bakeries were triangulated against top-down retail audit data from Nielsen and Circana coverage of UAE and Saudi supermarket channels.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including product type, distribution channel, customer application, and ingredient specification tier. CAGRs were derived from elasticity-adjusted demand projections incorporating protein content specification shifts and gluten-free penetration curves. Forecast inputs included hospitality investment pipeline tracking from Dubai Department of Tourism and Commerce Marketing and Saudi Quality of Life Program infrastructure spend disclosures.
Underlying assumptions cover sustained SFDA enforcement intensity, stable wheat import tariff regimes, and halal certification interoperability progression, with deviation risk concentrated in shipping disruption to Jebel Ali and currency fluctuation in GCC dollar-pegged economies. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Marzipan Market
Bakery Products
Bakery Improvers Market
Bakery Products
Europe Bakery Products Market
Bakery Products
Specialty Bakery Market
Bakery Products
Europe Zwieback Market
Bakery Products
Pancake Mixes Market
Bakery Products
Frozen Bakery Market
Bakery Products
Canada Frozen Bakery Market
Bakery Products
Premix Bread Flour Market
Bakery Products
Par-Baked Bread Market
Bakery Products
Global Baked Food and Cereals Market
Bakery Products
Matcha Cookie Market
Bakery Products
Banana Bread Market
Bakery Products
Bread Slicer Blades Market
Bakery Products
Bread Improver Market
Bakery Products
North America Sweet Biscuits Market