
 Gluten-Free Baking Mixes Market | 2026-2036
Gluten-Free Baking Mixes Market Size, Share, and Industry Trends Forecast 2026-2036
Gluten-Free Baking Mixes Market Intelligence
Modular single-serve pouch configurations is broadening buyer choice across pantry staples and impulse categories. King Arthur Baking Company leverages its heritage milling expertise to sustain premium positioning in bread and cake formulations. General Mills competes through mass-channel scale, while Bob's Red Mill Natural Foods anchors the natural-foods channel with heritage grain sourcing.
Gluten-free baking mixes comprise pre-blended dry formulations combining alternative flours, starches, binders, and leavening agents engineered to mimic wheat-based dough rheology and finished product texture without gluten protein networks. Manufacturers typically mill rice, almond, or chickpea flours to sub-150 micron particle size before blending with xanthan gum or psyllium husk to replicate viscoelastic properties. Cake mixes command the largest volume share due to forgiving formulation tolerances and shorter production cycles, while bread mixes carry higher margin pools given technical complexity and repeat purchase loyalty. Almond flour and coconut flour ingredient segments attract premium positioning as paleo and keto diet adherents expand the addressable base beyond celiac consumers.
The FDA enforces its gluten-free labeling rule requiring products to contain less than 20 parts per million gluten, while the USDA oversees organic certification claims frequently paired with gluten-free positioning. The EU's regulation through EFSA and national food safety agencies mandates comparable thresholds under its gluten-free and very low gluten categories, creating dual compliance architecture for exporters. Stakeholders must monitor evolving allergen labeling requirements and emerging novel protein regulations that could reshape binder ingredient sourcing decisions.
Market Dynamics
Home baking participation has doubled since pandemic-era habit formation, creating durable pull for shelf-stable convenience formats that replicate artisan results without technical expertise. This demand surge compresses product development cycles and rewards brands with heritage credibility.
Growth Catalysts
- FDA Gluten-Free Labeling Rule:The sub-20 ppm standard builds consumer trust and reduces trial barriers for newly diagnosed celiac patients entering the category.
- Almond Flour Formulation:Paleo and keto diet adherents expand addressable demand beyond medical necessity, commanding premium price realization.
- Single-Serve Pouch Configurations:Modular packaging broadens distribution into convenience retail and direct-to-consumer subscription channels.
Market Restraints
- Xanthan Gum Supply Concentration:Fermentation-derived binder production clusters in Chinese industrial biotechnology corridors, exposing formulations to input volatility.
- Organic Certification Overlap:USDA organic compliance adds 18-24 month timeline extensions and audit costs to new product introductions.
- Chickpea Flour Substitution:Legume-based alternatives from adjacent gluten-free categories threaten rice-dominant mix formulations on protein positioning.
Strategic Opportunities
- School Nutrition Programs:USDA Child Nutrition Program reform creates institutional procurement pathways for allergen-safe baking SKUs.
- Ancient Grain Convergence:Teff and sorghum flour integration with precision fermentation binders enables clean-label texture replication.
- Direct-to-Consumer Subscription:Replenishment models bypass slotting fee barriers that constrain mass retail distribution for emerging brands.
Industry Challenges
- Food Science Talent Scarcity:Rheology expertise for gluten-free dough systems remains concentrated in cereal science programs at limited land-grant universities.
- Co-Manufacturer Certification Backlogs:Third-party gluten-free facility audits face 6-9 month scheduling delays from accredited bodies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gluten-Free Baking Mixes Market |
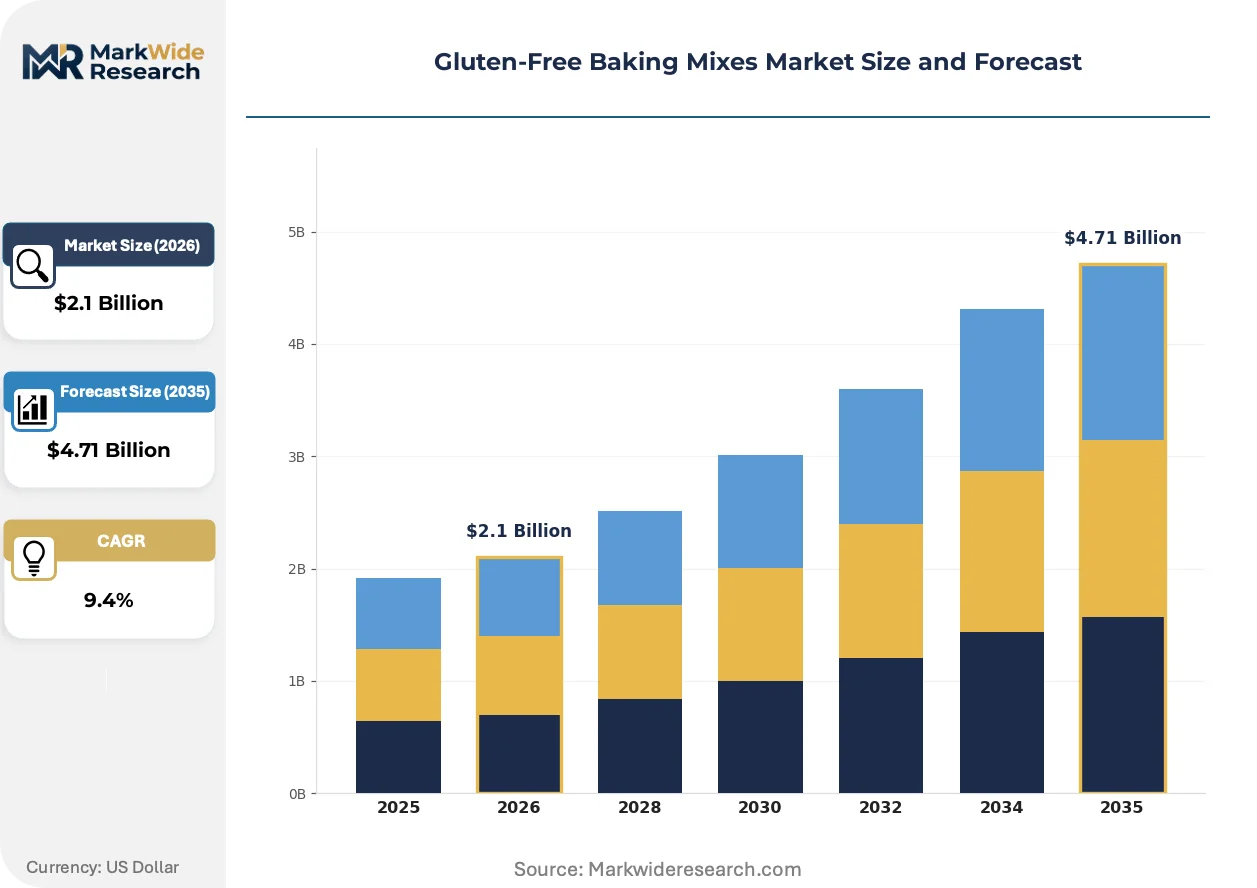
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.71 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pancake Mixes, Cookie Mixes, Cake Mixes, Bread Mixes Ingredient Source: Almond Flour, Coconut Flour, Rice Flour, Chickpea Flour Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Stores Customer Type: Individual Consumers, Restaurants, Bakeries, Food Manufacturers |
| Companies Covered | King Arthur Baking Company, Inc., Pamela's Products, General Mills Inc., Partake Foods, Continental Mills, Inc., Conagra Brands, Inc., Kinnikinnick Foods Inc., Williams-Sonoma Inc., Bob's Red Mill Natural Foods, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gluten-Free Baking Mixes Market Strategic Shifts & Innovations
Formulation science is advancing beyond simple wheat substitution toward functional ingredient systems that replicate extensibility and crumb structure. These developments reshape competitive differentiation from brand heritage to technical performance.
Precision fermentation-derived hydrocolloids are overtaking plant-extracted gums in premium mix formulations. Clean-label buyers at natural foods retailers now reject xanthan gum declarations, forcing reformulation toward microbial cellulose and fermentation starches. This transition compresses margin structures for brands locked into long-term agricultural supply contracts.
The FDA's updated Food Allergen Safety, Treatment, Education, and Research (FASTER) Act implementation expands sesame labeling requirements, creating dual-compliance complexity for facilities handling multiple allergens. Manufacturers must segregate production lines or absorb dedicated facility investments. Bread mix categories face the steepest compliance burden given their higher allergen cross-contact risk profiles.
Pantry loading behavior has fragmented into mission-based purchasing where consumers stock specialized mixes for discrete occasions rather than routine replacement. Club and e-commerce channels capture this shift through curated variety packs. Subscription services in coastal metropolitan markets now represent the fastest-growing volume pathway for cake and brownie mix subcategories.
Gluten-Free Baking Mixes Market Segmentation
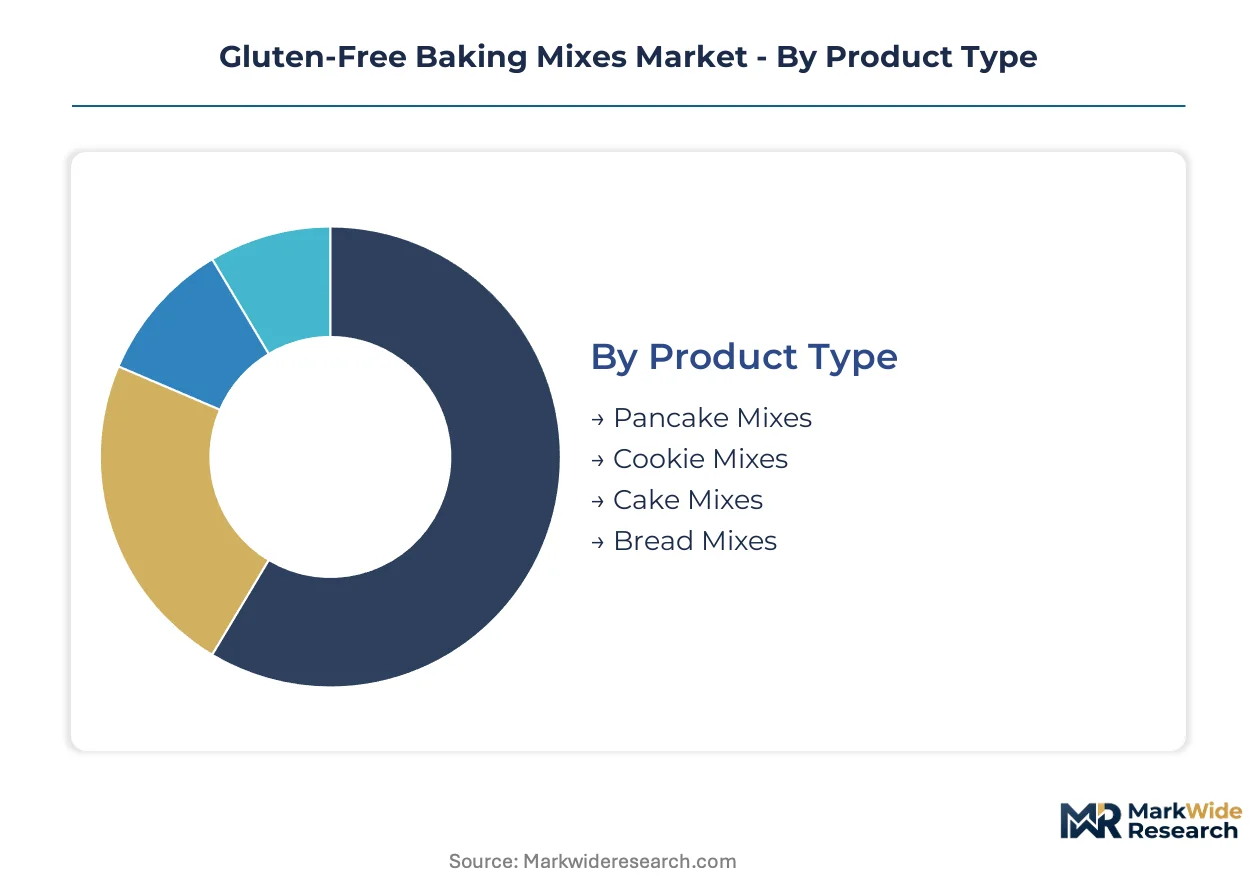
Gluten-free baking mixes fragment across four distinct taxonomies that reshape certification burdens and margin structures. Product type determines FDA gluten-free labeling intensity, while ingredient source dictates organic and non-GMO audit complexity. Distribution channel and customer type further stratify compliance architectures and pricing power.
Product Type:
Cake mixes carry the lightest certification load among formulations, while bread mixes trigger the most intensive third-party gluten-free facility audits given their higher cross-contact risk profiles and extended production cycles.
- Cake Mixes:Pre-blended formulations combining rice flour, starches, and rapid-rise leavening systems engineered for forgiving batter tolerances and short bake cycles. Demand concentrates in US coastal metropolitan markets where subscription replenishment models capture pantry-loading behavior for occasion-based purchasing.
- Bread Mixes:Complex systems integrating precision fermentation binders and extended fermentation protocols to replicate wheat dough extensibility and crumb structure. Technical sophistication commands premium price realization and repeat purchase loyalty among home baking enthusiasts managing celiac dietary requirements.
- Pancake Mixes:Breakfast-oriented formulations optimized for griddle performance with minimal mixing requirements, appealing to convenience-seeking household segments.
- Cookie Mixes:Drop-batter systems with higher fat and sugar matrices that mask alternative flour flavor profiles, targeting impulse and gift-giving purchase occasions.
Cake mixes sit at the top of the volume ranking, with bread mixes climbing the fastest as technical performance becomes the primary purchase criterion.
Ingredient Source:
Cost tier stratification runs deepest in this category, with heritage grain and nut-based flours commanding substantial premiums over commodity rice flour formulations.
- Almond Flour:Blanched and milled to sub-150 micron particle size, delivering protein density and moisture retention that supports paleo and keto dietary positioning. California Central Valley almond processing clusters expose supply to drought-induced harvest volatility and water rights pricing pressure.
- Rice Flour:Milled white and brown rice varieties providing neutral flavor baselines and cost-efficient volume production. Asian milling corridors in Thailand and Vietnam dominate supply, with USDA organic certification adding 18-24 month timeline extensions for clean-label positioning.
- Coconut Flour:Defatted coconut meal with high fiber absorption rates requiring formulaic liquid adjustments, attracting tropical-origin clean-label positioning.
- Chickpea Flour:Legume-based alternative with protein positioning that threatens rice-dominant formulations, sourced primarily from Indian subcontinent processing facilities.
Rice flour anchors volume leadership through cost accessibility, with almond flour expanding most quickly as dietary adherence beyond medical necessity broadens the addressable base.
Distribution Channel:
Channel selection directly determines slotting fee exposure and direct consumer relationship depth, with mass retail imposing the steepest capital barriers for emerging brands.
- Supermarkets:Mass-channel placement requiring substantial trade promotion investment and planogram compliance, rewarding General Mills-scale operators with existing retail relationships and consolidated logistics infrastructure.
- Online Retail:Direct-to-consumer and marketplace platforms bypassing slotting fee barriers while enabling subscription replenishment and curated variety pack configurations. E-commerce penetration concentrates in coastal US metropolitan markets with higher specialty diet adoption rates.
- Health Food Stores:Natural-foods channel prioritizing clean-label ingredient declarations and heritage sourcing narratives, with Bob's Red Mill anchoring shelf presence through grain mill credibility.
- Specialty Stores:Gluten-free dedicated retailers and gourmet kitchen supply outlets serving diagnosed celiac consumers with higher willingness-to-pay for certified safety assurance.
Supermarkets maintain volume dominance, with online retail gaining share fastest as subscription models capture mission-based pantry loading behavior.
Customer Type:
End-use application diverges sharply between household convenience seeking and commercial technical performance requirements, with food manufacturers imposing the most stringent specification standards.
- Individual Consumers:Home baking participants seeking shelf-stable convenience formats that replicate artisan results without technical expertise, with pandemic-era habit formation creating durable category pull.
- Restaurants:Foodservice operators requiring bulk formats and consistent batch performance for menu items serving allergen-sensitive patrons, with liability exposure driving certified supplier relationships.
- Bakeries:Artisan and commercial operations blending base mixes with in-house fermentation protocols and finishing techniques, demanding rheological consistency across production scales.
- Food Manufacturers:Industrial purchasers integrating mixes into co-manufactured finished goods, with co-packer certification backlogs creating 6-9 month supplier qualification delays from accredited audit bodies.
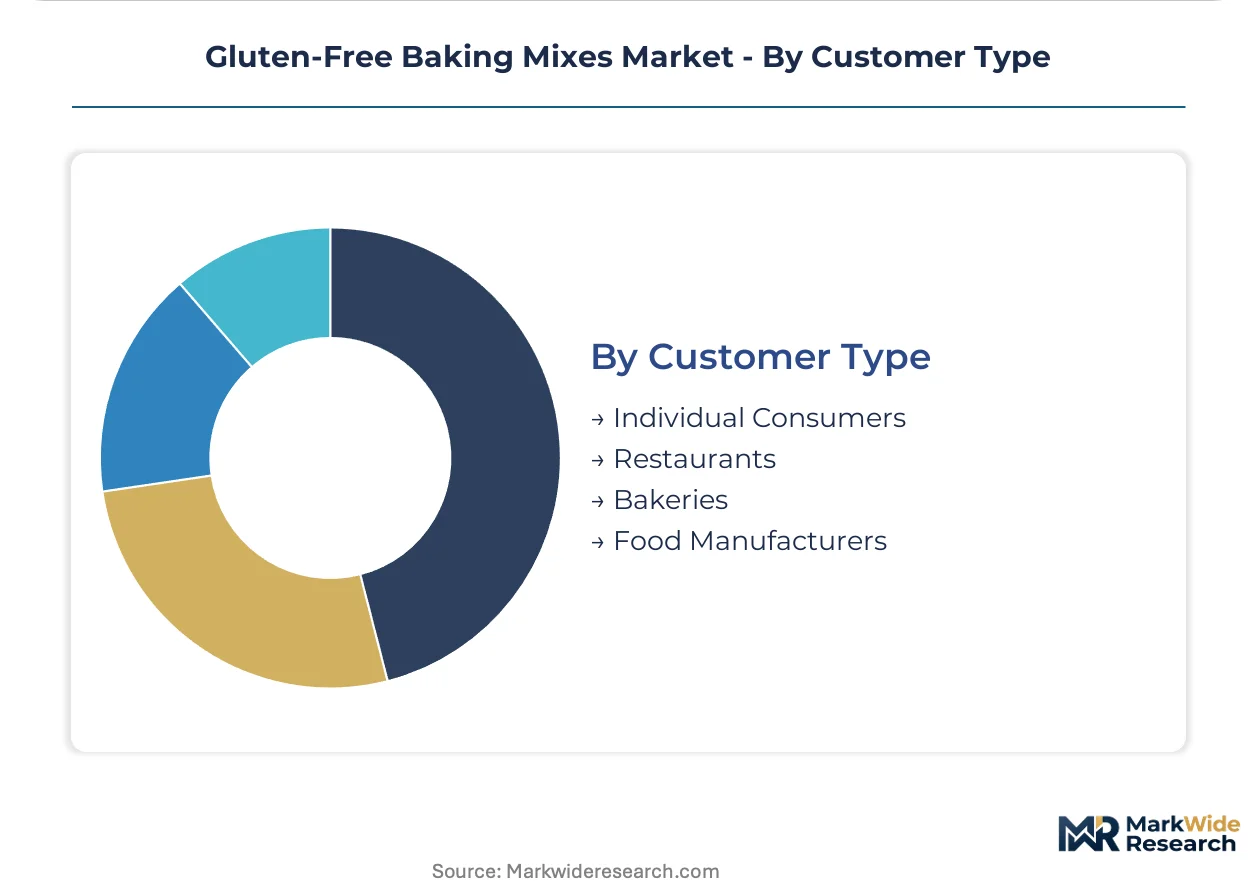
Individual consumers represent the largest volume pool, with food manufacturers showing the steepest expansion trajectory as CPG brands outsource gluten-free product development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gluten-free baking mixes trace their industrial roots to American health-food movements of the 1970s, when Bob's Red Mill began stone-milling alternative grains in Oregon. The category scaled through California-based natural foods distribution networks before achieving mass-market penetration via Midwestern retail consolidation.
United States
Diagnosed celiac prevalence and paleo-diet adherence drive household penetration above comparable markets. The FDA enforces sub-20 ppm gluten thresholds through its Food Safety Modernization Act inspection protocols. California's Central Valley almond processing clusters supply premium flour inputs, while Minneapolis-St. Paul anchors General Mills' R&D and distribution infrastructure.
Germany
EFSA-mandated gluten-free labeling categories create dual-tier product architecture for domestic and export formulations. The country's federal food safety authority enforces strict facility segregation requirements for cross-contamination prevention. Bavaria's organic milling cooperatives around Munich supply heritage grain inputs to Central European private-label manufacturers.
United Kingdom
Free-from aisle expansion at Tesco and Sainsbury's has normalized specialty diet purchasing beyond medical necessity. The Food Standards Agency coordinates with Trading Standards on gluten-free claim enforcement. Greater London's direct-to-consumer subscription startups concentrate fulfillment operations near Heathrow logistics corridors for EU market access.
Australia
Coeliac Australia certification programs build consumer trust through third-party auditing beyond regulatory minima. Food Standards Australia New Zealand maintains harmonized gluten-free standards with mandatory allergen declaration protocols. Melbourne's food manufacturing belt hosts co-manufacturing facilities serving Asia-Pacific export markets.
Canada
Health Canada's gluten-free regulations align with FDA thresholds, easing cross-border product standardization for North American portfolios. The Canadian Food Inspection Agency oversees dual-language labeling compliance for Quebec distribution requirements. Ontario's Golden Horseshoe region concentrates industrial baking and mix manufacturing for both domestic consumption and US export.
Gluten-Free Baking Mixes Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification intensity and ingredient sourcing dimensions. The market structures into three tiers: mass-channel operators with consolidated retail relationships, natural-foods specialists with heritage credibility, and emerging direct-to-consumer brands bypassing slotting fees. Strategic archetypes include legacy millers leveraging grain expertise, CPG conglomerates optimizing portfolio breadth, and allergen-focused pure-plays building community trust. Competitive moves concentrate on co-manufacturer certification partnerships and subscription channel development.
Among heritage milling specialists, King Arthur Baking Company and Bob's Red Mill Natural Foods exemplify the premium-tier archetype through grain sourcing narratives and technical formulation credibility. General Mills occupies the scale-driven position, representing mass-channel operators with consolidated retail infrastructure. These three anchors demonstrate how competitive positioning diverges between technical performance claims and distribution efficiency optimization.
| Leading Market Players |
|---|
| King Arthur Baking Company, Inc. |
| Pamela's Products |
| General Mills Inc. |
| Partake Foods |
| Continental Mills, Inc. |
| Conagra Brands, Inc. |
| Kinnikinnick Foods Inc. |
| Williams-Sonoma Inc. |
| Bob's Red Mill Natural Foods, Inc. |
| Others |
Cost & Logistics Intelligence
Xanthan gum fermentation capacity clusters in Chinese industrial biotechnology corridors, with contract pricing cascading through three distinct formulation tiers before reaching shelf price points. California almond flour milling commands premium realization against commodity rice flour baselines, while organic certification timelines stretch supplier working capital requirements across eighteen to twenty-four month audit cycles.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates heritage grain formulations from commodity rice flour mixes and private-label alternatives. Price differentiation rests on certification intensity and ingredient provenance, with FDA sub-20 ppm compliance and USDA organic seals commanding substantial shelf price premiums. Cost compression in economy tiers is intensifying because chickpea flour substitutes threaten rice-dominant positioning on protein claims. Food manufacturers show the least price sensitivity given liability exposure, while pantry-loading individual consumers in coastal metropolitan markets demonstrate the highest elasticity to promotional depth.
Supply Chain Analysis
Single-source vulnerability sits with Chinese xanthan gum fermentation facilities that anchor binder supply for precision texture replication. Raw material flows draw from Thai and Vietnamese rice milling corridors, California Central Valley almond processing clusters, and Indian subcontinent chickpea flour facilities. Tariff exposure runs through agricultural commodity channels dependent on water rights pricing pressure and drought-induced harvest volatility. Distribution runs through mass retail requiring slotting fee investment, natural foods channels prioritizing clean-label credentials, and direct-to-consumer subscription models bypassing trade promotion barriers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gluten-free baking mixes function as a stable compounder, with pandemic-era home baking habit formation creating durable replenishment demand that transcends economic cyclicality.
For Market Incumbents: Extend formulation expertise into ancient grain convergence opportunities, integrating teff and sorghum flours with precision fermentation binders to defend against clean-label rejection of xanthan gum declarations. Deepen co-manufacturer certification partnerships to compress the six to nine month third-party audit backlogs that constrain capacity expansion. Channel control through direct-to-consumer subscription infrastructure offers the strongest defensive moat against emerging brands bypassing mass retail slotting fees.
For New Entrants and Emerging Players: Begin with USDA Child Nutrition Program procurement pathways, where institutional allergen-safe baking SKU demand remains underserved by heritage millers focused on retail velocity. School nutrition program penetration offers the most penetrable white space, with federal reform creating mandated purchase volumes. A subscription replenishment model anchored in coastal metropolitan markets enables slotting fee avoidance while capturing mission-based pantry loading behavior.
For Investors and Strategic Acquirers: Roll-up economics work for regional co-manufacturing facilities with gluten-free certification infrastructure because third-party audit backlogs create six to nine month supplier qualification delays that constrain CPG outsourcing demand. The category demonstrates long-term viability through dietary adherence expansion beyond medical necessity into paleo and keto lifestyle positioning. The signal to watch is FDA FASTER Act implementation expanding sesame labeling requirements, which will force dedicated facility investments that favor scaled operators with segregated production lines.
| Strategic Initiative | Industry Significance |
|---|---|
| Ancient Grain Formulation Development | Teff and sorghum integration with precision fermentation binders enables clean-label texture replication without xanthan gum declarations. |
| Direct-to-Consumer Subscription Launch | Replenishment models bypass slotting fee barriers that constrain emerging brand distribution through mass retail channels. |
| Co-Manufacturer Certification Investment | Third-party gluten-free facility audits face six to nine month scheduling delays, creating capacity constraints for CPG outsourcing demand. |
| School Nutrition Program Penetration | USDA Child Nutrition Program reform creates institutional procurement pathways with mandated allergen-safe baking SKU volumes. |
| Precision Fermentation Binder Adoption | Microbial cellulose and fermentation starches displace plant-extracted gums as clean-label buyers reject xanthan gum declarations. |
Research Approach
Direct dialogue with brand managers at heritage milling specialists, category buyers at natural foods retailers, supply planners at mass-channel operators, and technical R&D directors at co-manufacturing facilities grounded qualitative assessment. Secondary validation drew from FDA gluten-free labeling guidance documents, USDA organic certification audit protocols, Nielsen retail audit data, and SEC filings from publicly traded CPG conglomerates. Bottom-up demand modeling across consumer segments triangulated against top-down category value estimates.
Segmentation outputs reflect disaggregation by product type, ingredient source, distribution channel, and customer end-use across the analysis window. CAGRs were derived from trend extrapolation adjusted for pandemic-era habit formation durability and regulatory implementation timelines. Forecast inputs incorporated FDA FASTER Act compliance cost modeling, almond harvest volatility scenarios tied to California water rights pricing, and precision fermentation binder adoption curves.
Several conditions sit outside the modeled scope, including unforeseen novel protein regulations reshaping binder ingredient sourcing, extreme climate events disrupting heritage grain harvests, and accelerated chickpea flour substitution rates threatening rice-dominant formulation economics. Forecasts reflect documented assumptions about celiac diagnosis rates and dietary adherence trend persistence. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
North America Gluten Free Bakery Mixes Market
Bakery Products
US Frozen Bakery Market
Bakery Products
Pastries Market
Bakery Products
Frozen Bakery Additives Market
Bakery Products
Asia-Pacific Baked Food and Cereals Market
Bakery Products
Ice Cream Market
Bakery Products
Fondant Market
Bakery Products
Cakes and Pastries Market
Bakery Products
Organic Bakery Products Market
Bakery Products
Middle East and Africa Fortified Bakery Products Market
Bakery Products
Canada Frozen Bakery Market
Bakery Products
Gluten-Free Bakery Market
Bakery Products
North America Pizza Oven Market
Bakery Products
Specialty Frozen Bakery Market
Bakery Products
Low-Calorie Breakfast Muffins Market
Bakery Products
Gluten-Free Bakery Products Market