
 Toasted Flour Market | 2026-2036
Toasted Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Toasted Flour Market Analytics
Sprouted and ancient grain alternatives is recalibrating cost structures across toasted flour portfolios as processors balance enzyme activity control against premium positioning. Cargill Inc. leverages its North American grain origination network to secure consistent hard red wheat supply for thermal processing. Ardent Mills anchors industrial-scale toasted flour capacity through its multi-region milling infrastructure. Bob's Red Mill Natural Foods differentiates via stone-ground heritage varietals that command shelf-space premiums in specialty retail.
Toasted flour denotes grain subjected to controlled dry-heat treatment between 140°C and 180°C, triggering Maillard browning and partial starch gelatinization while reducing microbial load and enzyme activity. This thermal modification imparts nutty flavor notes, extends shelf stability, and improves water-binding capacity for commercial baking and sauce applications. Wheat flour leads product type volume due to established industrial baking demand, though rice flour and coconut flour are gaining fastest as gluten-free and paleo-formulation adoption widens. Within applications, baking captures the largest value pool while nutritional supplement positioning in protein-fortified products is emerging as the highest-margin growth vector.
The FDA's Food Safety Modernization Act preventive controls and USDA organic certification standards govern production protocols, with FSMA's hazard analysis requirements pushing smaller processors toward third-party audited safety plans. The EPA's Clean Air Act permitting for thermal processing equipment adds compliance layers to facility expansion decisions. Stakeholders must monitor evolving state-level clean-label disclosure laws and carbon accounting mandates that will reshape supplier qualification criteria and capital allocation across toasted flour manufacturing networks.
Market Dynamics
The toasted flour market is undergoing structural recalibration as artisan bakeries and clean-label processors demand thermal-modified grains that balance flavor differentiation against microbial safety validation under tightened preventive control mandates.
Growth Catalysts
- FSMA Preventive Controls:The FDA's updated hazard analysis requirements for thermal-treated grain products are accelerating third-party safety plan adoption among commercial bakers seeking supply chain liability protection.
- Heritage Grain Revival:Midwest and Pacific Northwest agricultural programs are expanding hard red wheat and ancient varietal cultivation for specialty thermal processing.
- Maillard Browning Applications:Controlled dry-heat treatment between 140°C and 180°C is enabling nutty flavor profiles that command shelf-space premiums in premium sauce and baking categories.
Market Restraints
- Input Cost Volatility:Hard red wheat futures and natural gas pricing for thermal equipment operation create margin compression for mid-scale processors without origination networks.
- Supply Concentration Risk:North American grain origination and multi-region milling infrastructure dominate industrial-scale capacity, limiting sourcing flexibility for emerging gluten-free formulators.
- Enzyme Activity Trade-offs:Partial starch gelatinization during thermal treatment reduces fermentable sugars, constraining application in certain yeast-leavened product categories.
Strategic Opportunities
- Protein-Fortified Positioning:Nutritional supplement applications in sports nutrition and meal-replacement categories represent the highest-margin expansion vector for thermal-modified flour portfolios.
- Rice and Coconut Flour Segments:Gluten-free and paleo-formulation adoption is widening fastest in these categories, creating white space outside wheat-dominant industrial baking.
- Carbon Accounting Alignment:State-level clean-label disclosure laws and supplier qualification criteria are rewarding processors with verified low-carbon thermal processing infrastructure.
Industry Challenges
- Thermal Process Engineering Talent:Scarcity of specialists capable of optimizing Maillard reaction kinetics against microbial reduction targets is slowing facility commissioning timelines.
- EPA Clean Air Act Permitting:Thermal processing equipment expansion faces multi-layer compliance reviews that extend capital deployment cycles and increase facility siting uncertainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Toasted Flour Market |
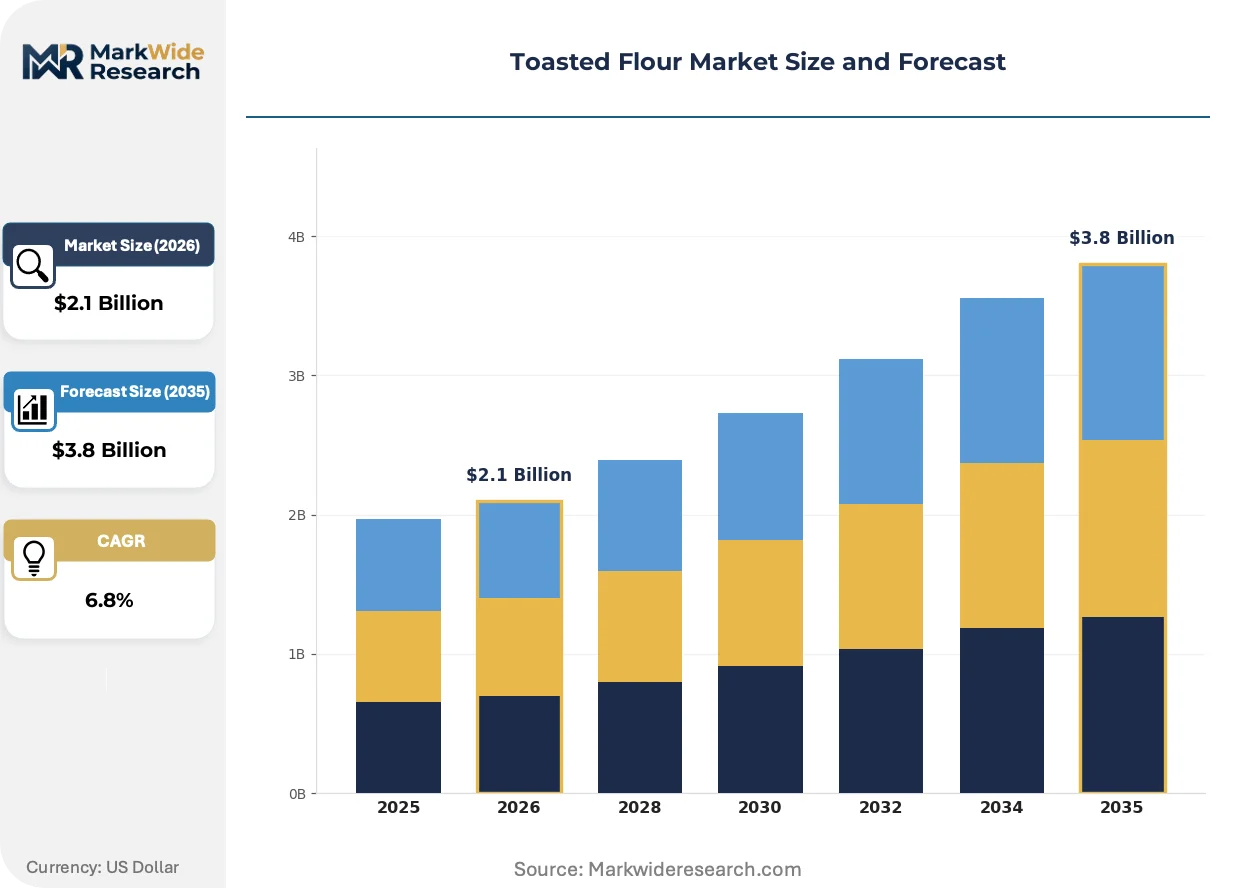
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wheat Flour, Barley Flour, Rice Flour, Coconut Flour End User: Bakeries, Restaurants, Home Cooks, Food Processors Application: Baking, Thickening Agent, Coating, Nutritional Supplement Distribution Channel: Supermarkets, Online Retail, Wholesale, Specialty Stores |
| Companies Covered | Cargill Inc., Archer Daniels Midland Company, Ardent Mills, Bob's Red Mill Natural Foods, King Arthur Flour Company, ITC Limited, Conagra Brands, Bunge Milling, P&H Milling Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Toasted Flour Market Evolving Landscape
Precision thermal control systems and enzyme-modified alternatives are reshaping how processors balance flavor development against functional performance in clean-label formulations.
Continuous belt roasting with real-time moisture feedback is overtaking batch kiln systems in industrial-scale operations. Large commercial bakeries and sauce manufacturers are adopting these systems to reduce thermal variation and improve lot-to-lot consistency. The shift is compressing capital recovery timelines while enabling tighter process validation documentation for FSMA compliance.
REACH chemical safety assessments and emerging EU Green Deal carbon border adjustments are tightening disclosure requirements for imported grain thermal processing. European formulators now demand supply chain emission documentation that North American exporters must retrofit into existing certification frameworks. Wheat flour imports into the EU face heightened scrutiny relative to domestic rice flour processing.
Direct-procurement relationships between artisan bakeries and heritage grain cooperatives are displacing traditional distributor channels in specialty retail. Stone-ground, single-origin toasted flours now move through farm-to-bakery contracts that bypass conventional ingredient wholesalers. The Pacific Northwest and Midwest cooperative networks demonstrate this pattern most visibly, with shelf-space premiums captured by vertically traceable supply chains.
Toasted Flour Market Segmentation
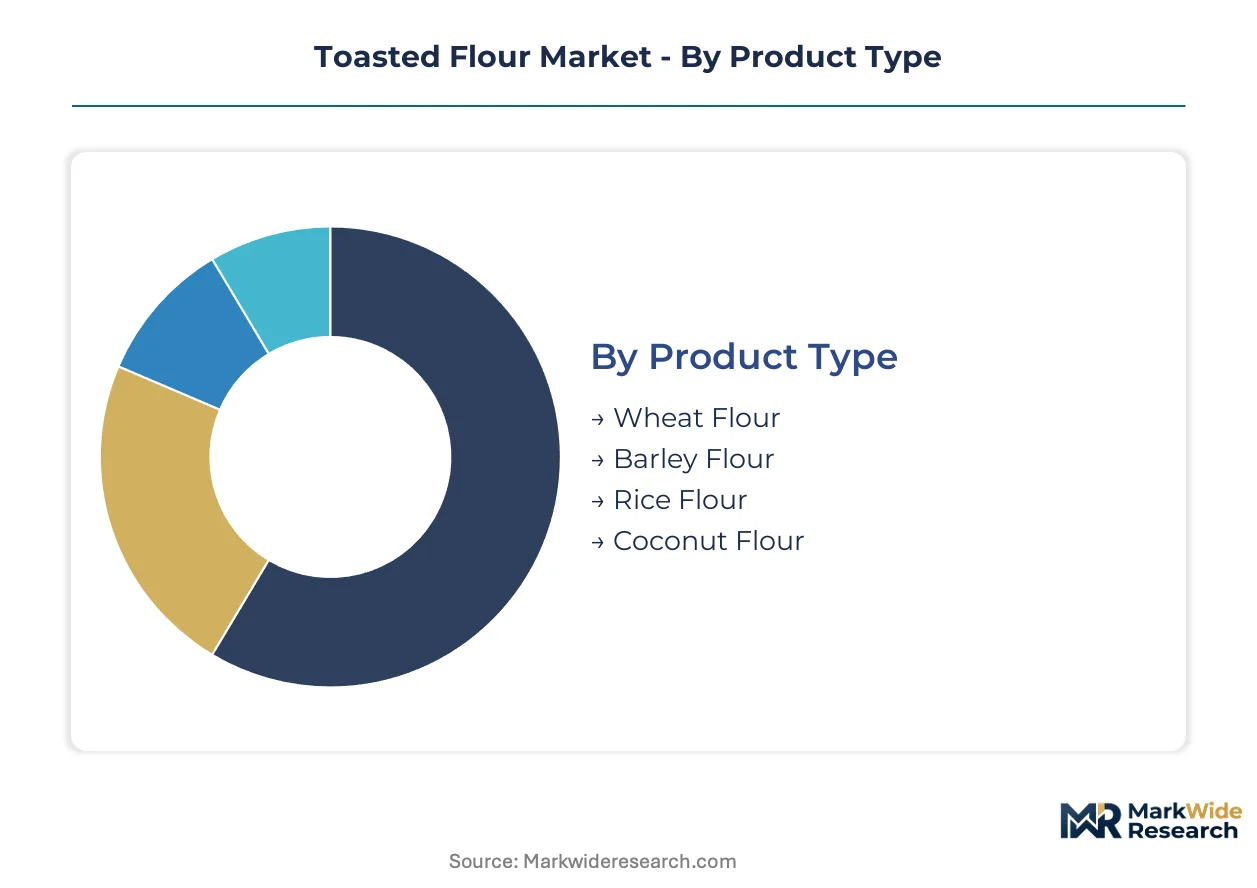
Segmentation in the toasted flour market reveals how thermal processing specifications align with distinct buyer requirements across product formulations and channel access. Understanding these divisions enables processors to calibrate equipment investments and certification priorities against margin profiles.
Product Type:
Upgrade cycles in thermal processing equipment favor wheat-dominant portfolios while creating entry points for gluten-free alternatives as bakeries diversify ingredient sourcing.
- Wheat Flour:Hard red wheat varieties undergo controlled dry-heat treatment between 140°C and 180°C, triggering Maillard browning and partial starch gelatinization. Industrial bakeries in the United States concentrate demand here, driven by established supply chains and FSMA preventive control validation requirements that favor proven thermal protocols.
- Rice Flour:White and brown rice bases require lower moisture thresholds during roasting to prevent scorching while achieving microbial reduction. Gluten-free formulators and paleo-product manufacturers are expanding procurement fastest, though supply concentration in Southeast Asian origination networks constrains North American processor flexibility.
- Barley Flour:Beta-glucan content demands precise temperature modulation to preserve soluble fiber benefits while developing nutty flavor notes. Craft breweries and specialty bakeries represent primary offtake.
- Coconut Flour:High fat content necessitates rapid cooling post-thermal treatment to prevent rancidity. Health-conscious home cooks and paleo-diet adherents drive specialty retail placement.
Wheat flour sits at the top of the volume ranking, with rice flour climbing the fastest.
End User:
Customer scale determines thermal specification stringency, with commercial operators demanding batch documentation that home segments rarely require.
- Bakeries:Artisan and commercial operations specify lot-to-lot consistency for Maillard reaction kinetics, driving adoption of continuous belt roasting systems with real-time moisture feedback. FSMA hazard analysis requirements push these buyers toward third-party audited suppliers with validated preventive controls.
- Restaurants:Sauce kitchens and bakery-café chains utilize toasted flour for roux-based thickeners and flavor-differentiated baked goods. Menu innovation cycles accelerate as chefs seek heritage grain provenance for narrative value.
- Home Cooks:Specialty retail packaging in smaller formats dominates, with stone-ground heritage varietals commanding shelf-space premiums through farm-to-bakery traceability claims.
- Food Processors:Industrial-scale sauce manufacturers and ready-meal formulators prioritize water-binding capacity and extended shelf stability from thermal-modified starches.
Bakeries anchor absolute demand volume, while food processors are gaining share fastest through protein-fortified product expansion.
Application:
Functional performance requirements vary sharply across use cases, with thermal treatment parameters calibrated to end-product texture and safety specifications.
- Baking:Bread, pastry, and cracker applications leverage Maillard-derived flavor compounds and modified starch gelatinization for crumb structure. Yeast-leavened categories face constraints from reduced fermentable sugars post-thermal treatment.
- Thickening Agent:Gravies, soups, and sauces exploit improved water-binding capacity without raw flour taste. Quick-service restaurant chains standardize on pre-toasted bases for consistency.
- Coating:Fried and baked breading applications utilize toasted flour for adhesion and color development. Poultry and seafood processors specify low-moisture variants for crunch retention.
- Nutritional Supplement:Protein-fortified powders and meal replacements represent the highest-margin positioning, with thermal treatment ensuring microbial safety for immunocompromised consumers.
Baking commands the largest value pool, with nutritional supplement applications expanding most quickly on margin-driven portfolio reallocation.
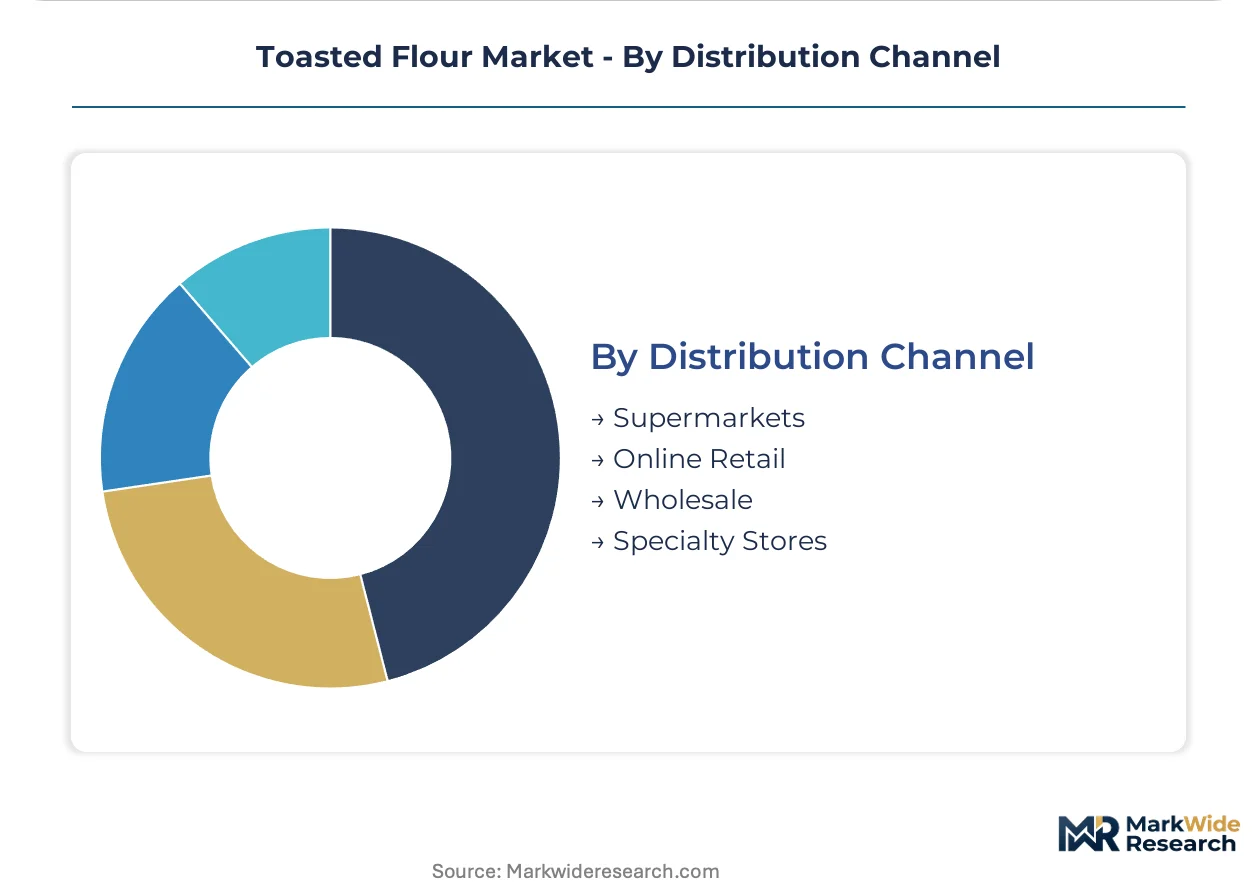
Distribution Channel:
Channel selection shapes packaging formats, certification requirements, and price realization for thermal-modified flour portfolios.
- Supermarkets:Mass-market retail demands shelf-stable packaging and clean-label positioning, with heritage grain claims differentiating premium placements from commodity flour adjacent to baking aisles.
- Online Retail:Direct-to-consumer platforms enable single-origin and small-batch toasted flour discovery, bypassing conventional distributor markups for vertically traceable supply chains.
- Wholesale:Foodservice distributors and ingredient brokers handle bulk shipments to commercial bakeries and processors, with FSMA documentation transfer critical to liability management.
- Specialty Stores:Natural food co-ops and gourmet retailers prioritize stone-ground processing and cooperative sourcing from Pacific Northwest and Midwest heritage grain networks.
Supermarkets dominate volume throughput, with online retail gaining traction fastest among artisan bakery direct-procurement relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States industrial baking clusters anchor toasted flour procurement, with heritage grain cooperatives in the Midwest and Pacific Northwest driving specialty varietal demand alongside tightened FDA preventive control mandates.
United States
Artisan bakeries in Portland and Minneapolis-St. Paul expand direct-procurement contracts for stone-ground heritage wheat, bypassing conventional distributors. The FDA's updated Food Safety Modernization Act preventive controls push commercial bakers toward third-party audited suppliers with validated thermal process documentation. Kansas City and Minneapolis milling corridors concentrate industrial-scale capacity for hard red wheat thermal processing.
Germany
EU Green Deal carbon border adjustments and REACH chemical safety assessments tighten disclosure requirements for imported thermal-treated grain products. German formulators now demand supply chain emission documentation that North American exporters must retrofit into certification frameworks. The Rhine-Ruhr industrial corridor hosts precision thermal equipment engineering specialists serving continental bakery chains.
France
Traditional baguerie and pâtisserie segments experiment with toasted flour for nutty flavor differentiation in premium product lines. ANSM food safety oversight aligns with EU-wide EFSA thermal processing guidance for microbial reduction validation. The Paris Basin and Lyon-Auvergne regions concentrate artisan milling cooperatives pursuing heritage grain revival programs.
Italy
Pasta and specialty bread manufacturers evaluate rice flour thermal processing for gluten-free portfolio expansion. Italian Ministry of Health circulars on novel food ingredients create regulatory pathways for thermal-modified ancient grains. Emilia-Romagna and Lombardy industrial baking clusters pilot continuous belt roasting systems for lot-to-lot consistency.
Canada
Prairie province hard red wheat output supplies North American thermal processing demand, with Alberta and Saskatchewan grain elevators integrating pre-processing quality validation. Health Canada and PMRA coordinated oversight on grain treatment residues aligns with USDA organic equivalency agreements. Winnipeg and Calgary serve as origination hubs for cross-border specialty flour trade.
Toasted Flour Market Competitive Landscape
Global majors compete with regional champions across origination networks and thermal processing infrastructure, creating a tiered structure where scale-driven grain traders, multi-region millers, and heritage-focused specialty operators occupy distinct competitive positions. Consolidation pressures intensify as FSMA compliance costs favor integrated safety plan documentation. Three archetypes dominate: North American grain origination specialists with captive thermal capacity, stone-ground heritage varietal purveyors commanding retail premiums, and diversified food conglomerates leveraging brand portfolios for ingredient channel placement. Capacity expansion and strategic partnerships represent the dominant competitive moves, with processors securing heritage grain supply through cooperative offtake agreements.
Within the diversified agribusiness tier, Cargill Inc. and Archer Daniels Midland Company occupy positions anchored by continental grain origination networks. Ardent Mills exemplifies the multi-region milling archetype with distributed thermal processing infrastructure. Bob's Red Mill Natural Foods represents the heritage-focused specialty operator, leveraging stone-ground processing claims for natural channel differentiation. These three companies illustrate how competitive positioning stratifies across scale, geographic coverage, and brand positioning vectors.
| Leading Market Players |
|---|
| Cargill Inc. |
| Archer Daniels Midland Company |
| Ardent Mills |
| Bob's Red Mill Natural Foods |
| King Arthur Flour Company |
| ITC Limited |
| Conagra Brands |
| Bunge Milling |
| P&H Milling Group |
| Others |
Value Network & Pricing Analysis
Industrial-scale commercial bakeries in the United States concentrate procurement volume, anchoring contract-based long-term offtake pricing that favors processors with validated FSMA preventive controls and multi-region milling infrastructure. This buyer concentration enables volume-tiered negotiations while squeezing margins for mid-scale operators lacking origination networks.
Pricing Analysis
Input-cost pass-through from hard red wheat futures and natural gas pricing for thermal equipment operation shapes margin structures across processor tiers. Three-tier pricing structure across premium, standard, and economy levels separates stone-ground heritage varietals from commodity thermal-treated wheat and bulk industrial grades. Price differentiation hinges on certification grade—USDA organic and third-party FSMA audit status—and volume scale. Cost compression in mid-tier standard grades is intensifying because natural gas volatility and grain origination bottlenecks compress processor margins. Artisan bakeries exhibit least price sensitivity, prioritizing lot-to-lot consistency and provenance documentation, while foodservice distributors and quick-service restaurant chains drive hardest bargain negotiations.
Supply Chain Analysis
Regional distribution centers in Kansas City and Minneapolis-St. Paul anchor hub-and-spoke patterns for North American toasted flour movement. Geographic supply concentrates in the United States, Canada, and Germany, with Prairie province hard red wheat output feeding cross-border thermal processing demand. Raw material dependencies rest on hard red wheat varietals, natural gas for thermal equipment operation, and specialized roasting belt systems. Single-source vulnerability in Southeast Asian rice flour origination networks constrains gluten-free formulator flexibility. Distribution runs through foodservice wholesalers and direct-procurement farm-to-bakery contracts, with specialty retail increasingly bypassing conventional distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EPA Clean Air Act permitting timelines in the United States and streamlined thermal equipment siting in Canadian Prairie provinces, where Health Canada-PMRA coordinated oversight aligns with USDA organic equivalency agreements.
For Market Incumbents: Deepen backward integration into heritage grain origination through cooperative offtake agreements with Midwest and Pacific Northwest agricultural programs. Add continuous belt roasting capacity in Alberta and Saskatchewan to exploit Canadian regulatory alignment while defending against emerging gluten-free formulators. FSMA compliance cost escalation favors integrated safety plan documentation, pushing smaller competitors toward exit or acquisition. For New Entrants and Emerging Players: EU Green Deal carbon border adjustments in Germany open a window for low-carbon thermal processing specialists with verified supply chain emission documentation. Target rice flour and coconut flour segments where gluten-free and paleo-formulation adoption widens fastest, creating white space outside wheat-dominant industrial baking. Pursue direct-procurement relationships with artisan bakeries in Portland and Minneapolis-St. Paul, bypassing conventional distributor channels through farm-to-bakery traceability claims. For Investors and Strategic Acquirers: Diversified food conglomerates seeking clean-label ingredient portfolio expansion are the most active acquirer in this space. Long-term viability rests on processors with captive heritage grain supply and validated low-carbon thermal infrastructure. Acquisition target archetype: mid-scale operators with FSMA-compliant documentation and Pacific Northwest cooperative network access. Watch for state-level carbon accounting mandates as inflection indicator for supplier qualification criteria reshaping capital allocation.| Strategic Initiative | Industry Significance |
|---|---|
| Heritage Grain Cooperative Offtake Agreement | Secures hard red wheat supply from Midwest agricultural programs for thermal processing. |
| Continuous Belt Roasting Capacity Expansion | Reduces thermal variation for FSMA lot-to-lot consistency documentation. |
| Carbon Accounting Certification Program | Aligns with EU Green Deal disclosure requirements for German formulator access. |
| Direct-to-Artisan-Bakery Distribution Launch | Bypasses conventional wholesaler markups through farm-to-bakery traceability. |
| Protein-Fortified Product Line Extension | Captures highest-margin positioning in sports nutrition and meal-replacement categories. |
Research Methodology
Direct dialogue with thermal process engineers, commercial bakery procurement directors, heritage grain cooperative managers, and FSMA compliance consultants grounded qualitative insights. Secondary validation drew from FDA preventive control guidance documents, USDA organic certification standards, EPA Clean Air Act permitting records, and customs data on thermal-treated grain trade flows. Bottom-up and top-down triangulation cross-checked processor capacity estimates against end-use demand segmentation.
Bottom-up modeling built from individual facility throughput assumptions across wheat, rice, barley, and coconut flour categories, while top-down analysis anchored total addressable market sizing against industrial baking and nutritional supplement consumption trends. Segmentation dimensions included product type, end user scale, application functional requirements, and distribution channel access. CAGRs were derived from fitted growth curves against historical thermal processing equipment deployment patterns and heritage grain cultivation expansion rates.
Revisions become necessary when EPA permitting delays, hard red wheat futures volatility, or EU carbon border adjustment implementation timelines materialize outside baseline assumptions. Forecasts reflect documented assumptions about regulatory enforcement intensity and cooperative network expansion rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Shelf-Stable Dough Market
Bakery Products
North America Pizza Oven Market
Bakery Products
Bakery Fillings Market
Bakery Products
Vegan Baking Mix Market
Bakery Products
Cakes and Pastries Market
Bakery Products
South America Bakery Products Market
Bakery Products
Pastries Market
Bakery Products
Low-Calorie Breakfast Muffins Market
Bakery Products
Low Fat Bran Muffins Market
Bakery Products
Packaged Bread Market
Bakery Products
Yeastless Dough Market
Bakery Products
Wedding Cakes Market
Bakery Products
Pizza Crust Market
Bakery Products
Doughnuts Market
Bakery Products
Bahrain Bakery Product Market
Bakery Products
Premix Bread Flour Market