
 Gluten-Free Bakery Market | 2026-2036
Gluten-Free Bakery Market Size, Share, and Industry Trends Forecast 2026-2036
Gluten-Free Bakery Market Outlook
The gap between premium artisan positioning and mass-market commodity pricing is recalibrating competitive strategy across the gluten-free bakery sector. General Mills leverages its CPG scale to secure shelf space in conventional retail, while Bob's Red Mill Natural Foods anchors the premium ingredient-driven segment with heritage brand credibility. Dr. Schar AG dominates European-style formulation expertise, competing on certified medical-grade purity rather than lifestyle appeal.
Gluten-free bakery comprises baked goods formulated without wheat, barley, rye, or their crossbred varieties, typically employing alternative flours such as rice flour with xanthan gum at 0.5-2% inclusion to replicate gluten's viscoelastic binding function. These products serve celiac patients, gluten-intolerant consumers, and elective dietary adherents requiring safe, sensorially acceptable substitutes for conventional wheat-based items. Breads and cookies command the largest volume pools within product type segmentation, though cakes sustain higher per-unit margins through occasion-based premium pricing. Almond flour and coconut flour formulations lead ingredient type growth due to clean-label protein positioning, while tapioca starch occupies the cost-optimized tier in private-label manufacturing.
The FDA enforces its 20 ppm gluten threshold for voluntary gluten-free claims, with USDA overlapping jurisdiction on meat-containing bakery items, while the EU's Regulation 828/2014 mandates equivalent labeling standards for cross-border trade. These frameworks compel manufacturers to maintain segregated production lines and third-party certification, raising capital barriers for new entrants. Stakeholders must monitor evolving allergen threshold science and potential harmonization between FDA and Codex Alimentarius standards to anticipate reformulation requirements and certification investments.
Market Dynamics
Segregated production line requirements under FDA's 20 ppm gluten threshold are compressing margins for mid-scale manufacturers while accelerating capital consolidation among certified operators with dedicated allergen-free facilities.
Growth Catalysts
- Celiac diagnosis protocols:Expanded serological screening in pediatric populations drives first-time household adoption of certified gluten-free staples, converting latent demand into recurring purchase patterns.
- Clean-label protein positioning:Almond flour and coconut flour formulations attract paleo and keto dietary adherents beyond the celiac core, broadening addressable household penetration.
- Retail foodservice channel expansion:Conventional grocers dedicate discrete shelf sections and in-store bakeries to gluten-free SKUs, reducing consumer search friction and trial barriers.
Market Restraints
- Input cost volatility:Tapioca starch and rice flour prices fluctuate with Southeast Asian harvest cycles, squeezing private-label manufacturers on margin stability.
- Supply concentration risk:Xanthan gum production clusters with fermentation specialists in China, creating single-source dependency for binding agent supply security.
- Technical limitation:Gluten's viscoelastic structure remains unmatched by alternative protein networks, limiting crumb elasticity and shelf-life extension in yeast-leavened breads.
Strategic Opportunities
- Underpenetrated foodservice:QSR chains and contract caterers in Germany and France lag Anglo-Saxon markets in gluten-free menu integration, offering first-mover positioning.
- Regulatory tailwind:EU Regulation 828/2014 harmonization with Codex Alimentarius standards may reduce cross-border certification duplication, lowering market entry costs for pan-European brands.
- Distribution innovation:Direct-to-subscription models bypass conventional slotting fee structures, enabling artisan producers to capture full margin on specialty formulations.
Industry Challenges
- Segregated facility capex:Dedicated production lines, air handling systems, and cleaning protocols require capital outlays that exclude sub-scale entrants from certified production.
- Third-party certification timelines:Gluten-Free Certification Organization and Celiac Support Association audit backlogs extend product launch schedules by six to twelve months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gluten-Free Bakery Market |
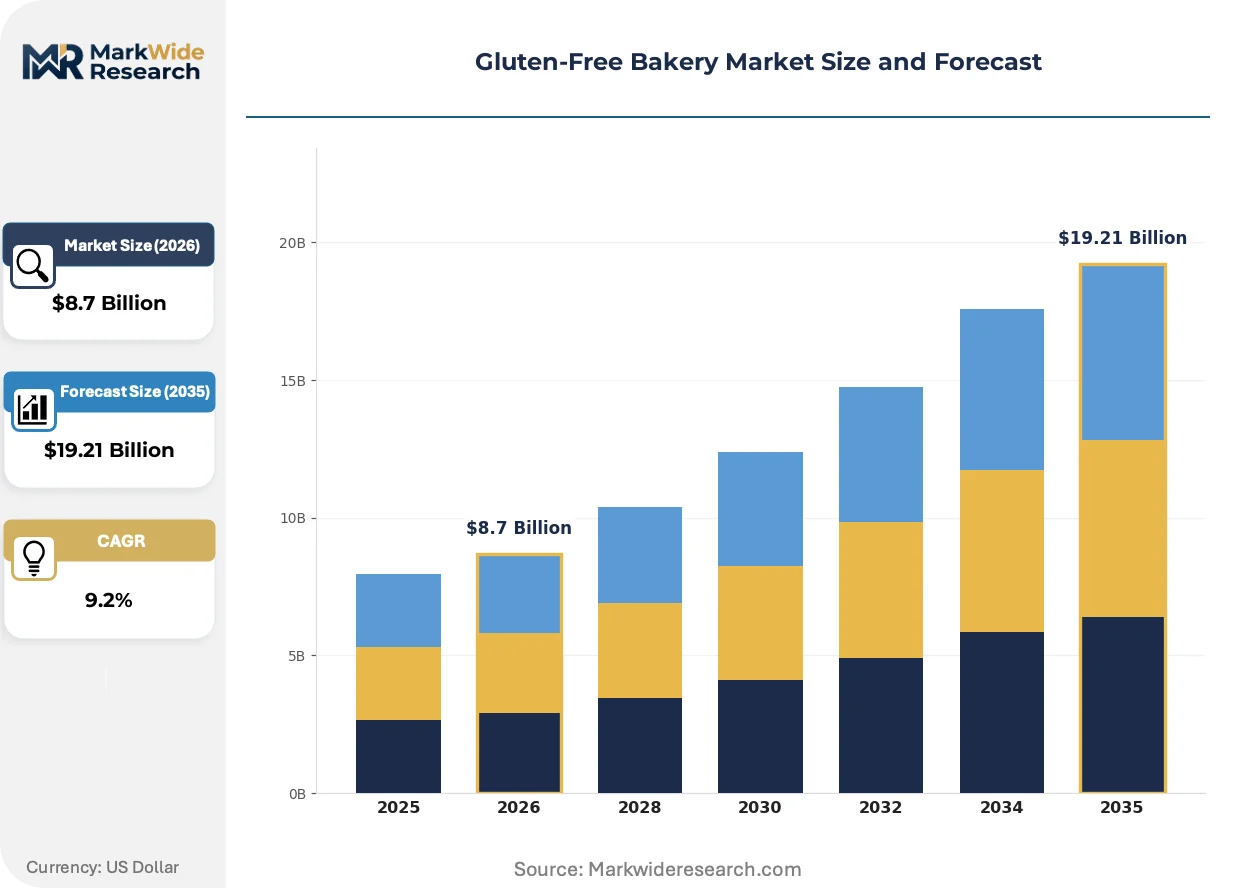
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.21 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Breads, Cookies, Cakes, Muffins Distribution Channel: Online, Supermarkets, Specialty Stores, Foodservice Ingredient Type: Almond Flour, Coconut Flour, Oat Flour, Tapioca Starch Packaging Type: Bags, Boxes, Jars, Pouches |
| Companies Covered | General Mills, Bob's Red Mill Natural Foods, Dr. Schar AG, The Hain Celestial Group, Conagra Brands, Amy's Kitchen, Dawn Food Products, Grupo Bimbo, Europastry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gluten-Free Bakery Market Strategic Shifts
Enzymatic processing and novel hydrocolloid combinations are redefining texture parity benchmarks, while regulatory convergence and channel fragmentation simultaneously compress compliance costs and expand access points.
Hydrocolloid blending systems incorporating psyllium husk and konjac gum are overtaking single-ingredient xanthan gum dependence in premium bread formulations. Artisan bakeries and clean-label specialists adopt these systems fastest, seeking to eliminate E-number additives from ingredient declarations. The shift is overtaking commodity hydrocolloid suppliers in the premium tier while forcing reformulation service providers to expand their gum portfolios.
EU Regulation 828/2014's equivalence provisions with FDA labeling standards are reducing dual-certification burdens for transatlantic exporters. Manufacturers can now leverage single audit cycles for both markets, redirecting compliance budgets toward R&D rather than redundant testing. North American brands with European expansion ambitions capture the greatest efficiency gains from this harmonization.
Subscription-based replenishment models are displacing conventional retail trial for specialty flour blends and frozen dough formats. Health-conscious households in metropolitan Australia and coastal United States markets lead this channel migration, prioritizing convenience and dietary adherence over in-store discovery. Direct relationships enable manufacturers to capture consumption data and optimize flavor rotation schedules.
Gluten-Free Bakery Market Segmentation
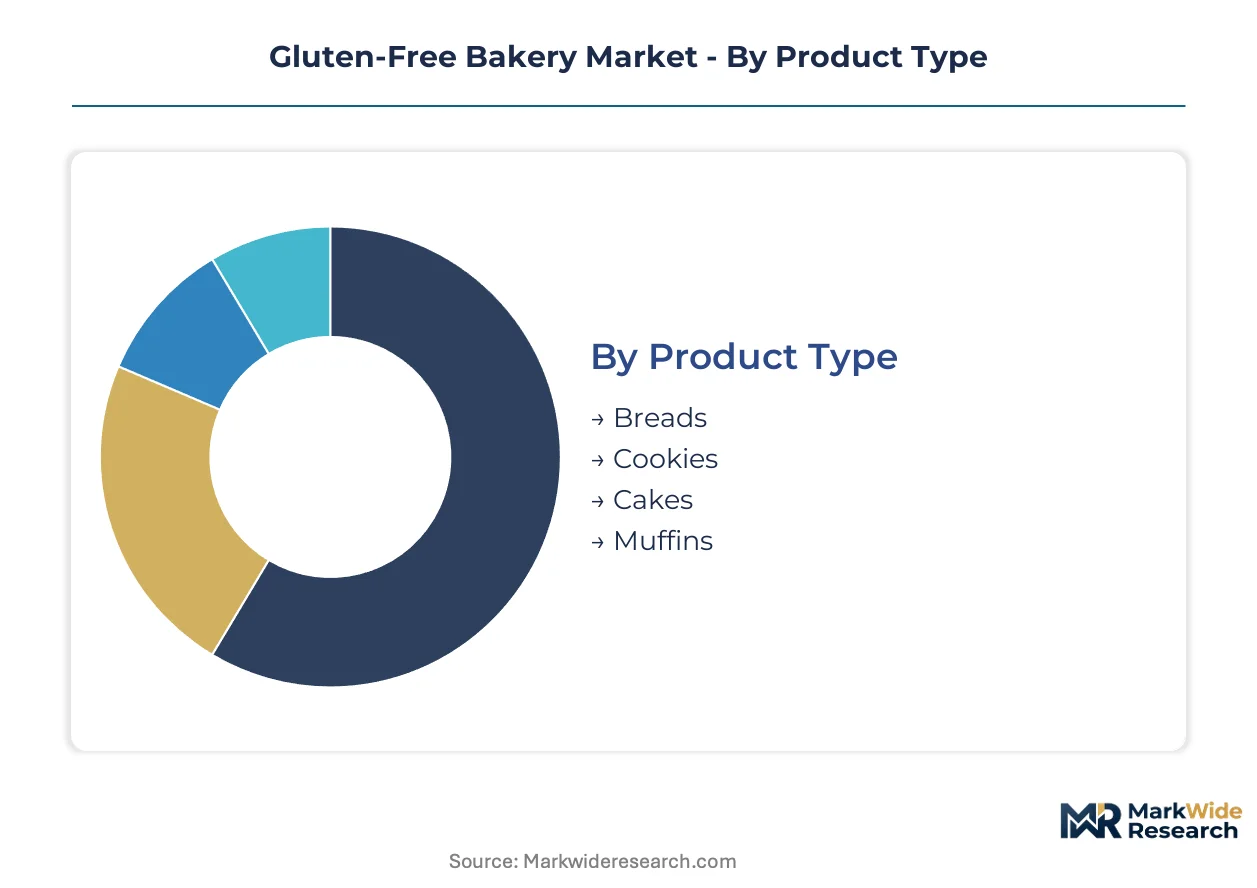
Segmentation in gluten-free bakery reveals divergent capital requirements across production formats, with dedicated allergen-free facilities commanding premium investment thresholds. Manufacturers must align portfolio composition with channel-specific certification burdens and ingredient sourcing complexity.
Product Type:
Capital intensity peaks in yeast-leavened formats requiring controlled fermentation environments and extended production runs to achieve viable unit economics.
- Breads:Formulations rely on hydrocolloid binding systems—xanthan gum, psyllium husk, or konjac gum—to replicate gluten's viscoelastic structure in dough matrices. Demand concentrates in United States metropolitan households with celiac diagnoses, where consumers accept price premiums for certified medical-grade purity and extended shelf stability.
- Cakes:Occasion-based premium pricing sustains higher per-unit margins through specialized ingredient positioning and decorative finishing requirements. United States coastal markets drive volume, with consumers prioritizing clean-label almond and coconut flour bases for celebration events.
- Cookies:Shelf-stable formats suit mass-market private-label manufacturing with lower barrier-to-entry capital requirements.
- Muffins:Single-serve portions align with convenience-oriented retail and foodservice grab-and-go channels.
Most installed capacity flows through Breads. Expansion is steepest in Cakes.
Distribution Channel:
Channel selection dictates compliance architecture, with foodservice and retail each imposing distinct certification and traceability protocols.
- Supermarkets:Conventional grocers dedicate discrete shelf sections and in-store bakeries to gluten-free SKUs, reducing consumer search friction. Slotting fee structures favor scaled CPG operators with certified production networks spanning multiple manufacturing sites.
- Foodservice:QSR chains and contract caterers require segregated preparation protocols and supplier audit documentation. Underpenetrated markets in Germany and France lag Anglo-Saxon adoption curves, offering first-mover positioning for certified manufacturers.
- Online:Direct-to-subscription models bypass conventional slotting fees, enabling artisan producers to capture full margin.
- Specialty Stores:Health-focused retailers prioritize heritage brand credibility and ingredient transparency in curated assortments.
Volume concentrates in Supermarkets. Share gains are most rapid in Foodservice.
Ingredient Type:
Input sourcing geography and harvest volatility create divergent margin stability profiles across alternative flour categories.
- Almond Flour:High-protein, low-carbohydrate positioning attracts paleo and keto dietary adherents beyond the celiac core. California's Central Valley production clusters supply North American manufacturers, with pricing tied to nut commodity cycles and irrigation water allocation.
- Tapioca Starch:Cost-optimized tier serves private-label manufacturing with functional binding properties at lower price points. Southeast Asian harvest cycles—particularly Thailand and Vietnam—introduce supply concentration risk and input cost volatility.
- Coconut Flour:Clean-label protein positioning drives premium tier adoption in artisan and specialty formulations.
- Oat Flour:Avenin protein concerns require certified gluten-free sourcing protocols to meet FDA's 20 ppm threshold.
Manufacturing throughput centers on Tapioca Starch. Premium positioning is expanding most quickly in Almond Flour.
Packaging Type:
Packaging format selection intersects with shelf-life extension requirements and retail channel merchandising constraints.
- Bags:Flexible packaging dominates bread and cookie formats, offering cost efficiency and modified atmosphere compatibility for shelf-life extension in retail environments.
- Boxes:Rigid formats support cake and premium cookie gifting occasions with structural protection and premium unboxing experience.
- Pouches:Resealable flexible formats suit single-serve and on-the-go consumption patterns in convenience channels.
- Jars:Glass and rigid plastic containers serve specialty spreads and wet-format bakery adjuncts with extended ambient stability requirements.
Production volume flows predominantly through Bags. Format innovation is accelerating fastest in Pouches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands the largest certified product volume, while Germany's foodservice channel lags Anglo-Saxon adoption curves by several years. Australia and the United Kingdom show the steepest direct-to-consumer channel migration, with coastal metropolitan households driving subscription model penetration.
United States
FDA's 20 ppm gluten threshold enforcement shapes formulation standards for celiac-diagnosed households in metropolitan markets. The agency's voluntary labeling rule compels segregated production line investments across domestic manufacturing sites. California's Central Valley anchors almond flour supply clusters, with ingredient processors serving premium bakery brands in Los Angeles and San Francisco.
Germany
EU Regulation 828/2014 harmonization reduces dual-certification burdens for domestic exporters targeting transatlantic markets. The country's national food safety regulator enforces equivalent labeling standards to FDA thresholds, streamlining audit cycles. Bavaria's artisan bakery sector concentrates medical-grade purity expertise, competing on certified formulations rather than lifestyle positioning.
United Kingdom
Retail foodservice channel expansion accelerates as conventional grocers dedicate discrete shelf sections to gluten-free SKUs in London and Southeast England. The Food Standards Agency maintains alignment with EU Regulation 828/2014 post-Brexit, preserving cross-border trade certification efficiency. Greater Manchester and Birmingham manufacturing clusters serve private-label contracts for supermarket chains.
Australia
Coastal metropolitan households in Sydney and Melbourne lead subscription-based replenishment model adoption for specialty flour blends. Food Standards Australia New Zealand enforces gluten-free labeling thresholds matching Codex Alimentarius standards. Queensland's coconut flour processing facilities supply clean-label protein positioning for artisan bakery brands.
France
Underpenetrated QSR and contract catering channels offer first-mover positioning for certified manufacturers entering the market. ANSM oversight of food allergen labeling converges with EU-wide harmonization frameworks. Île-de-France's foodservice distribution networks in Paris lag gluten-free menu integration compared to London or New York benchmarks.
Gluten-Free Bakery Market Competitive Environment
Top-tier vendors anchor mass-market shelf space, while mid-scale artisan producers occupy premium ingredient-driven niches. The vendor base stratifies across three tiers: multinational CPG conglomerates with certified production networks, heritage ingredient specialists with regional sourcing credibility, and European medical-grade purity experts. Two dominant competitive moves define current positioning: geographic expansion into underpenetrated foodservice markets and portfolio diversification into clean-label protein formulations.
Among North American CPG conglomerates, General Mills exemplifies scale-driven conventional retail penetration, while Bob's Red Mill Natural Foods occupies the heritage ingredient specialist archetype with regional sourcing credibility. Dr. Schar AG represents the European medical-grade purity tier, anchoring certified formulation expertise rather than lifestyle appeal. These three company structures illustrate the competitive triangle between mass-market access, premium ingredient positioning, and clinical-grade certification standards.
| Leading Market Players |
|---|
| General Mills |
| Bob's Red Mill Natural Foods |
| Dr. Schar AG |
| The Hain Celestial Group |
| Conagra Brands |
| Amy's Kitchen |
| Dawn Food Products |
| Grupo Bimbo |
| Europastry |
| Others |
Value Chain & Pricing Dynamics
Xanthan gum fermentation capacity in China anchors binding-agent cost structures, transmitting upstream commodity pressure through private-label manufacturers while premium artisan tiers absorb volatility via almond flour substitution and subscription pricing models.
Pricing Analysis
Capacity additions in Southeast Asia are reshaping price floors for tapioca-starch-dependent manufacturers, compressing margins in the cost-optimized tier. Three-tier pricing structure across premium, standard, and economy levels separates certified medical-grade formulations from clean-label lifestyle positioning and private-label commodity SKUs. Pricing pressure stems from input cost volatility in rice flour and tapioca starch harvest cycles. Private-label manufacturers exhibit highest price sensitivity, while celiac-diagnosed households in United States metropolitan markets accept sustained premiums for certified purity.
Supply Chain Analysis
Direct-to-subscription channels handle specialty flour blend demand from health-conscious coastal households, bypassing conventional slotting fee structures. Raw material sourcing draws from Thailand and Vietnam for tapioca starch, California's Central Valley for almond flour, and Queensland for coconut flour processing. Single-source vulnerability concentrates in Chinese xanthan gum fermentation specialists. Distribution runs through segregated allergen-free facilities with third-party certification protocols, creating capital barriers for uncertified entrants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA's 20 ppm gluten threshold enforcement and EU Regulation 828/2014 harmonization continuously expand the addressable base of certified-product-dependent households.
For Market Incumbents: Deploy segregated facility networks as the defensive moat against mid-scale artisan challengers. Accelerate certification investments to extend audit backlogs for sub-scale competitors. Channel control through retail foodservice partnerships in underpenetrated German and French QSR markets locks out later entrants. For New Entrants and Emerging Players: Direct-to-subscription routes offer the lowest-friction path around conventional slotting fee barriers. White-space targets cluster in German and French contract catering channels lagging Anglo-Saxon adoption curves. A go-to-market angle anchored on enzymatic processing and psyllium-konjac hydrocolloid systems differentiates against xanthan-dependent incumbents. For Investors and Strategic Acquirers: Consolidation pressure builds where certified production line requirements exclude sub-scale operators from margin-competitive positioning. Acquisition targets with dedicated allergen-free facilities and existing Gluten-Free Certification Organization audit relationships offer durable competitive positioning. Watch EU- Codex Alimentarius harmonization progress as the inflection signal for pan-European brand scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Segregated Facility Certification | Gluten-Free Certification Organization audits create six-to-twelve month launch barriers for uncertified competitors. |
| Direct-to-Consumer Channel Expansion | Subscription models bypass supermarket slotting fees and capture full margin on specialty formulations. |
| Clean-Label Ingredient Repositioning | Psyllium husk and konjac gum systems eliminate E-number additives from premium bread declarations. |
| EU Foodservice Market Entry | German and French QSR underpenetration offers first-mover positioning against Anglo-Saxon incumbents. |
| Backward Integration into Almond Supply | California Central Valley sourcing clusters reduce nut commodity cycle exposure for premium tier producers. |
Study Parameters
Multiple input streams — regulatory filing analysis, trade data reconciliation, and primary fieldwork — were reconciled to construct market estimates. Bakery manufacturing executives, retail category buyers, foodservice procurement managers, and celiac patient advocacy organization representatives provided operational validation. Secondary sources included FDA enforcement actions, EU Regulation 828/2014 implementation guidance, Codex Alimentarius standards documentation, and customs records for alternative flour imports. Bottom-up capacity modeling and top-down demand estimation were cross-checked for convergence.
Data-stream reconciliation across product type, ingredient category, distribution channel, and geographic market dimensions anchored the analytical framework. CAGRs were derived from segmented growth trajectory modeling across the projection horizon. Forecast inputs incorporated celiac diagnosis rate assumptions, retail foodservice channel expansion curves, and hydrocolloid substitution elasticity parameters for binding system transitions.
Regulatory threshold revisions, harvest cycle disruptions in Southeast Asian tapioca production, and xanthan gum supply concentration events are the dominant revision risks. Forecasts reflect documented assumptions regarding certification audit timelines and channel migration velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Packaged Bread Market
Bakery Products
Bakery Mixes Market
Bakery Products
Organic Bakery Products Market
Bakery Products
Organic Frozen Bakery Market
Bakery Products
Flour Mixes Market
Bakery Products
Pancakes Market
Bakery Products
Bread Market
Bakery Products
Vegan Baking Mix Market
Bakery Products
Specialty Frozen Bakery Market
Bakery Products
Europe Sweet Biscuits Market
Bakery Products
GCC Bakery Products Market
Bakery Products
Middle East and Africa Sweet Biscuits Market
Bakery Products
Gluten-Free Baking Mixes Market
Bakery Products
Bread Dough Improver Market
Bakery Products
No-Fat Cake Market
Bakery Products
Oman Frozen Bakery Products Market