
 Frosting, Toppings, and Decorations Market | 2026-2036
Frosting, Toppings, and Decorations Market Size, Share, and Industry Trends Forecast 2026-2036
Frosting, Toppings, and Decorations Market Insights
Buyer concentration among foodservice chains and artisan bakery cooperatives is hardening as procurement scales shift toward fewer, larger accounts with technical specification requirements. Dawn Foods leverages its North American distribution density to anchor supply contracts with regional bakery networks. Dr. Oetker competes through European retail channel control and home-baking kit bundling. Wilton Brands specializes in craft-focused decorating tools and education-driven consumer engagement.
Frosting, toppings, and decorations comprise formulated sugar-based, fat-based, and chocolate-based systems applied to finished baked goods for aesthetic enhancement, flavor layering, and shelf-life extension, with buttercream and fondant formulations requiring precise temperature-controlled preparation between 18°C and 22°C for optimal pliability. The primary commercial purpose spans finished goods differentiation in retail bakery, foodservice plating, and celebratory cake production. Buttercream and fondant categories dominate volume flows in commercial bakeries due to operational familiarity and cost predictability, while ganache and royal icing segments capture disproportionate margin pools in wedding cake and luxury confectionery channels where labor intensity justifies premium positioning.
FDA food additive regulations and EFSA food contact material standards govern ingredient safety and packaging migration limits across the United States and European supply corridors, with FDA color additive batch certification requirements directly shaping formulation timelines and product launch cadences for decorators. The EU Green Deal packaging waste directives are accelerating shifts toward recyclable jar and sachet formats that comply with extended producer responsibility frameworks. Stakeholders must monitor evolving clean-label thresholds and regional packaging compliance deadlines to preempt reformulation costs and secure retail listing continuity.
Market Dynamics
Clean-label ingredient mandates from FDA and EFSA are forcing wholesale portfolio reformulation across the frosting, toppings, and decorations supply base, compressing launch timelines and elevating R&D spend as the central competitive battleground.
Growth Catalysts
- Artisan bakery expansion:Specialty baking cooperatives in the United States and Germany are scaling procurement of premium fondant and buttercream systems, creating dedicated supply contracts with technical specification requirements.
- EU Green Deal packaging directives:Extended producer responsibility frameworks are accelerating shifts toward recyclable jar and sachet formats, opening compliance-driven product refresh cycles.
- Home baking kit bundling:Retail channel partners are consolidating decoration SKUs into integrated baking sets, expanding household penetration of royal icing and ganache components.
Market Restraints
- Cocoa butter price volatility:Chocolate-based decoration formulations face margin compression from commodity input swings, constraining pricing flexibility in ganache segments.
- Temperature-controlled supply chain requirements:Buttercream and fondant demand 18°C to 22°C handling precision, limiting distribution radius and raising logistics costs for regional bakery networks.
- FDA color additive batch certification:Pre-market notification timelines for new pigment approvals extend formulation-to-launch cycles, delaying product pipeline velocity.
Strategic Opportunities
- Japan specialty confectionery channel:Wedding cake and luxury patisserie segments in Tokyo and Osaka show underpenetrated demand for premium ganache and custom fondant applications.
- Edible inkjet printing convergence:Digital decoration technology paired with food-grade pigment systems enables mass customization for celebratory cake production.
- Direct-to-artisan distribution platforms:Bypassing traditional wholesale intermediaries, suppliers can capture margin by serving independent bakery cooperatives through specialized e-procurement portals.
Industry Challenges
- Decorating technician skill scarcity:Commercial bakeries report difficulty recruiting personnel proficient in temperature-controlled fondant handling and precision piping techniques.
- Clean-label reformulation capex:Removing artificial stabilizers and synthetic colorants requires investment in natural alternative sourcing and stability testing infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frosting, Toppings, and Decorations Market |
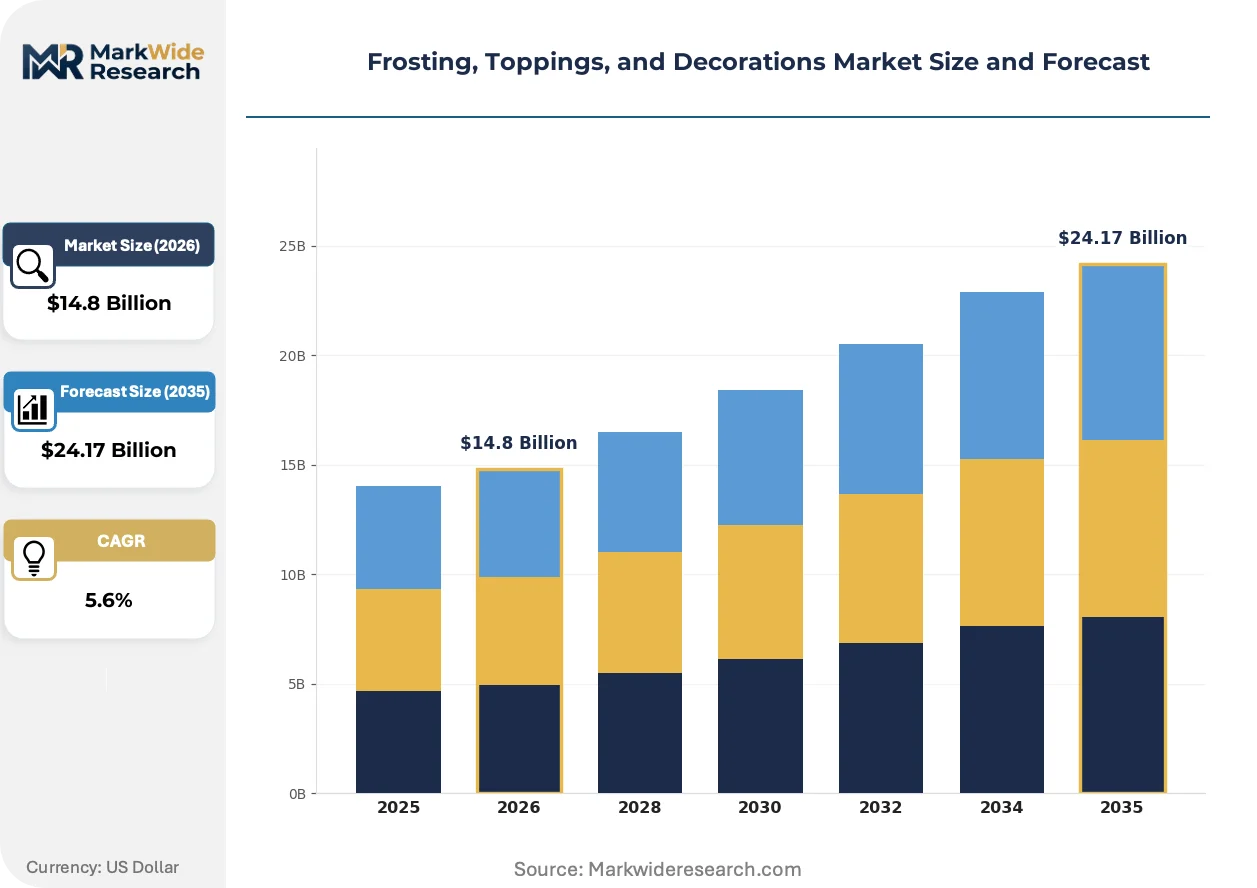
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.17 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Buttercream, Fondant, Ganache, Glaze, Royal Icing, Whipped Cream Application: Birthday Cakes, Wedding Cakes, Pastries, Cupcakes, Donuts, Confectionery Packaging Type: Plastic Tubes, Bottles, Jars, Sachets, Cans, Decorative Boxes End User: Bakers, Pastry Shops, Foodservice, Home Bakers, Confectioners, Caterers |
| Companies Covered | Wilton Brands, Dawn Foods, Dr. Oetker, Puratos, Rich Products, Cargill, Barry Callebaut, Associated British Foods, Bakels, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frosting, Toppings, and Decorations Market Trends and Innovations
Digital decoration technologies and natural ingredient systems are converging to reshape how frosting, toppings, and decorations are formulated, distributed, and applied across commercial and home baking channels.
Edible inkjet printing systems are absorbing market share from traditional hand-piping methods in high-volume celebratory cake production. Regional bakery networks in Germany and the United States are piloting these platforms for custom image reproduction on fondant surfaces. The technology is absorbing labor hours from skilled decorating technicians while compressing order turnaround times for personalized cake orders.
EFSA food contact material standards and FDA packaging migration limits are tightening permissible thresholds for chemical transfer from decoration containers. Suppliers serving European retail channels are accelerating transitions to glass jar and aluminum sachet formats ahead of 2025 extended producer responsibility deadlines. Wedding cake specialists sourcing premium ganache components face the steepest compliance recertification burdens.
Foodservice chains are consolidating decoration procurement through centralized technical specification programs, displacing fragmented spot-buying from multiple regional distributors. This pattern concentrates volume with fewer qualified suppliers capable of meeting batch traceability and allergen documentation requirements. The United States exhibits the most advanced buyer concentration, with national bakery cooperatives standardizing buttercream formulations across member locations.
Frosting, Toppings, and Decorations Market Segmentation
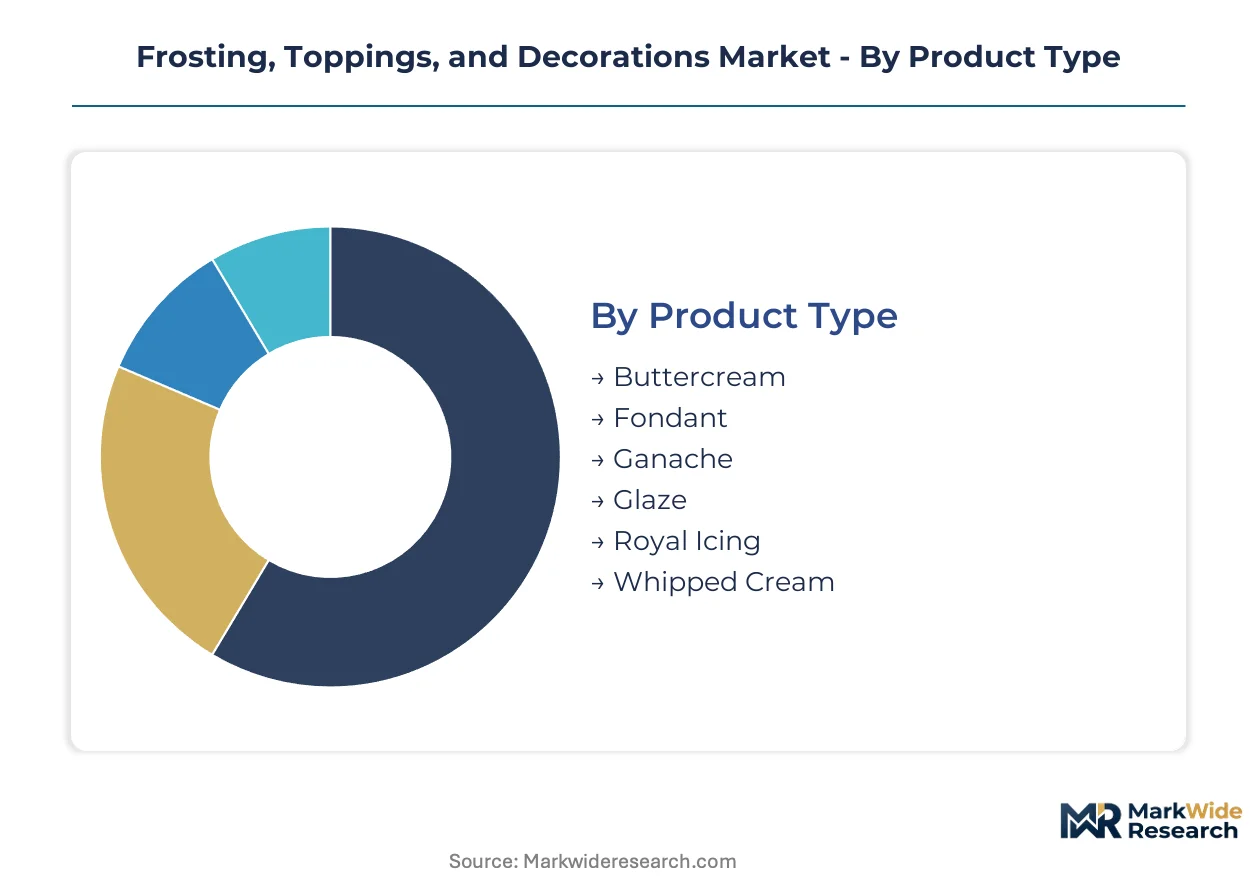
Segmentation in the frosting, toppings, and decorations market reveals how supply-side capabilities align with divergent customer technical requirements. Each dimension exposes distinct margin structures, formulation constraints, and procurement patterns that shape competitive positioning across commercial and household channels.
Product Type:
Supply concentration clusters around temperature-stable formulations that minimize logistics complexity for regional bakery networks.
- Buttercream:Fat-based emulsion systems combining butter or shortening with powdered sugar require precise temperature control between 18°C and 22°C during preparation. Commercial bakeries in the United States standardize buttercream procurement through cooperative buying agreements that lock in formulation specifications across member locations. FDA color additive batch certification requirements extend launch timelines for new buttercream variants.
- Fondant:Sugar dough systems incorporating glucose and glycerin deliver smooth, rollable surfaces for sculptural cake decoration. Wedding cake specialists in Germany and Japan drive premium fondant demand through technical specifications for pliability and finish quality. Temperature-controlled handling requirements limit distribution radius and favor regional production facilities.
- Ganache:Chocolate-cream emulsions capturing disproportionate margins in luxury confectionery channels where labor intensity justifies premium positioning.
- Glaze:Thin, pourable sugar coatings applied to donuts and pastries for sheen and shelf-life extension.
- Royal Icing:Egg white-based systems hardening to rigid finishes for detailed piping work on celebration cakes.
- Whipped Cream:Aerated dairy or non-dairy toppings with shortest shelf life and most restrictive cold chain requirements.
Today's leader: Buttercream. Tomorrow's challenger: Ganache.
Application:
Application-driven demand fragments across occasion-based purchasing cycles with divergent technical specification intensity.
- Wedding Cakes:Multi-tiered celebration structures demanding premium fondant and ganache systems with exacting finish standards. Tokyo and Osaka patisseries show underpenetrated demand for custom fondant applications with intricate decorative elements. EFSA food contact material standards govern packaging for premium components in European wedding cake supply chains.
- Birthday Cakes:High-volume celebratory segment absorbing edible inkjet printing technologies for mass customization. Regional bakery networks in Germany pilot digital decoration platforms for custom image reproduction on fondant surfaces.
- Pastries:French and Viennese-style baked goods requiring precise glaze and cream applications.
- Cupcakes:Individual portion formats driving standardized frosting dispensing and decoration efficiency.
- Donuts:Glaze-dominant segment with high-throughput production requirements.
- Confectionery:Chocolate-based decorations for pralines and bonbons with cocoa butter price volatility exposure.
Wedding cakes command premium pricing power. Birthday cakes scale volume fastest.
Packaging Type:
EU Green Deal directives are restructuring packaging procurement toward recyclable formats ahead of extended producer responsibility deadlines.
- Jars:Glass containers gaining share in European retail channels as suppliers transition from plastic ahead of 2025 compliance deadlines. Wedding cake specialists face steepest recertification burdens for premium ganache packaging.
- Sachets:Aluminum single-serve formats aligning with EFSA food contact material standards for migration limit compliance.
- Plastic Tubes:Squeezable formats for controlled dispensing in high-volume foodservice applications.
- Bottles:Pourable liquid toppings for glaze and syrup applications.
- Cans:Aerosol whipped cream systems with propellant regulatory considerations.
- Decorative Boxes:Gift-oriented presentation packaging for premium home baking kits.
Jars lead compliance-driven transitions. Sachets capture on-the-go convenience growth.
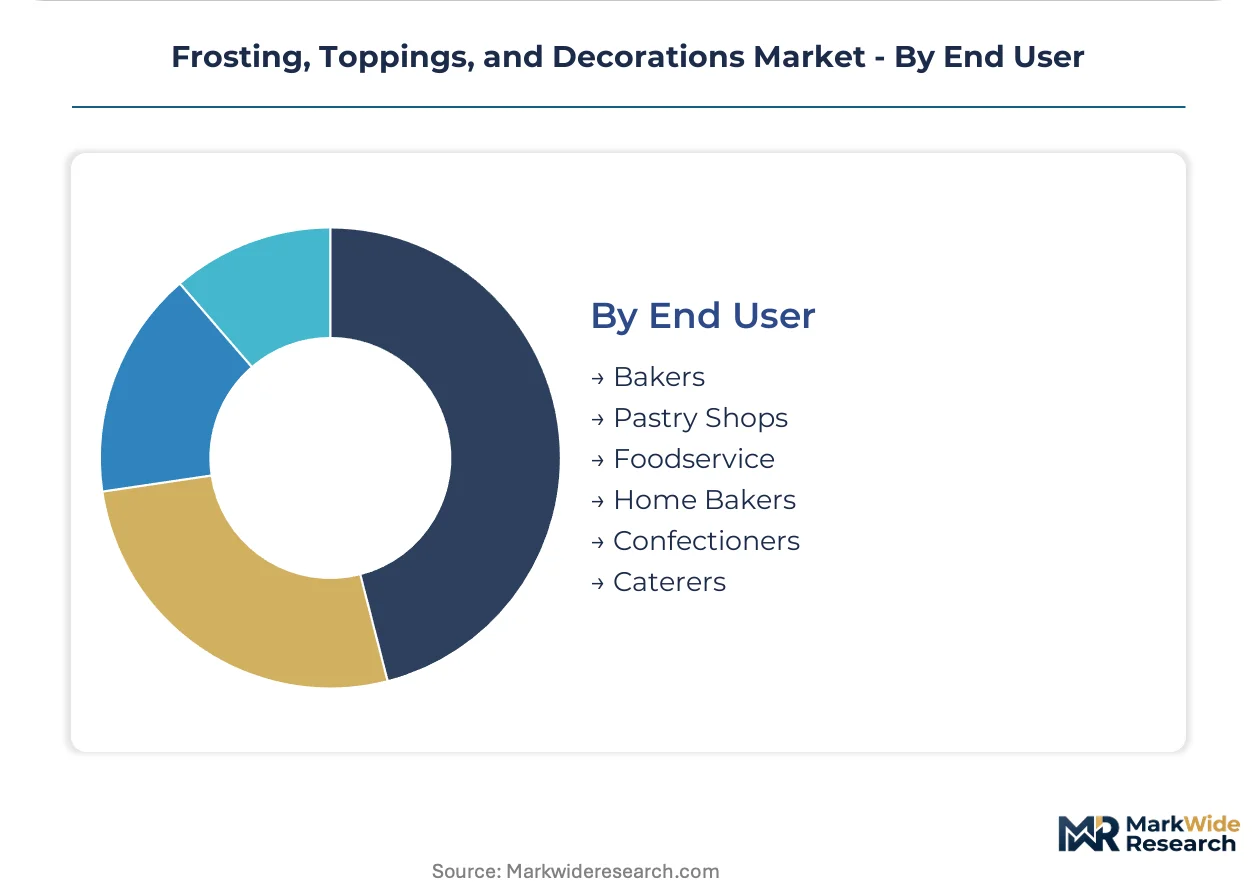
End User:
Buyer concentration hardens as procurement scales shift toward fewer, larger accounts with technical documentation requirements.
- Bakers:Commercial bakery cooperatives in the United States consolidating decoration procurement through centralized technical specification programs. National networks standardize buttercream formulations across member locations with batch traceability mandates.
- Pastry Shops:Artisan operators in Germany scaling premium fondant and ganache procurement with dedicated supply contracts.
- Foodservice:Chain restaurants displacing fragmented spot-buying with qualified supplier concentration.
- Home Bakers:Retail channel bundling of decoration SKUs into integrated baking sets expanding household penetration.
- Confectioners:Chocolate specialists exposed to cocoa butter commodity input swings.
- Caterers:Event-service operators with variable demand patterns and limited cold chain infrastructure.
Bakers anchor commercial volume. Home bakers expand addressable market breadth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States and Germany operate parallel specialty baking ecosystems, yet Japan's wedding cake artisans command premium positioning that outstrips both in per-unit decoration spend. Demand concentrates where cooperative bakery networks and regulatory clarity intersect.
United States
National bakery cooperatives standardize buttercream procurement across member locations with batch traceability mandates. FDA color additive batch certification requirements extend formulation-to-launch timelines for new decoration variants. Regional networks in the Midwest and Southeast pilot centralized technical specification programs that displace fragmented spot-buying.
Germany
Artisan bakery cooperatives scale premium fondant and ganache procurement through dedicated supply contracts with exacting pliability specifications. EFSA food contact material standards govern packaging migration limits for European retail channels. Wedding cake specialists in Munich and Hamburg drive premium segment uptake through custom fondant applications.
Japan
Tokyo and Osaka patisseries exhibit underpenetrated demand for premium ganache and intricate custom fondant applications in luxury wedding cake channels. METI standards for food manufacturing equipment shape facility certification requirements. Specialty confectionery clusters in Kanto and Kansai regions absorb disproportionate margin pools from labor-intensive decoration techniques.
United Kingdom
Retail channel partners consolidate decoration SKUs into integrated home-baking kits, expanding household penetration of royal icing components. REACH compliance obligations govern chemical inputs in formulation processes. London-based artisan bakery networks standardize procurement through cooperative buying agreements with technical documentation requirements.
France
Luxury patisserie channels in Paris and Lyon sustain premium ganache demand through wedding cake and celebration segments. EU Green Deal packaging waste directives accelerate transitions toward recyclable jar formats ahead of extended producer responsibility deadlines. Île-de-France confectionery clusters specialize in chocolate-based decoration systems with cocoa butter price exposure.
Frosting, Toppings, and Decorations Market Competitive Landscape
North American producers anchor one tier; European specialists hold formulation-intensive positions in another. The vendor base organizes around three strategic archetypes: diversified ingredient conglomerates with captive distribution, regional bakery supply specialists with technical service capabilities, and craft-focused tool and education providers. Competitive moves concentrate on portfolio diversification toward clean-label systems and backward integration into natural colorant sourcing.
Within the diversified conglomerate tier, Cargill and Barry Callebaut occupy positions defined by commodity input leverage and industrial-scale formulation infrastructure. Dawn Foods and Dr. Oetker exemplify regional bakery supply specialists with dense distribution networks and cooperative procurement relationships. Wilton Brands represents the craft-focused archetype, anchoring consumer engagement through education-driven positioning rather than ingredient supply relationships.
| Leading Market Players |
|---|
| Wilton Brands |
| Dawn Foods |
| Dr. Oetker |
| Puratos |
| Rich Products |
| Cargill |
| Barry Callebaut |
| Associated British Foods |
| Bakels |
| Others |
Pricing and Supply Chain Analysis
Cocoa butter commodity swings cascade through ganache and chocolate-based decoration tiers, compressing margins for European wedding cake specialists while forcing premium fondant producers toward natural colorant sourcing to defend price positioning against FDA certification delays.
Pricing Analysis
Capacity additions in Germany and the United States are reshaping price floors for buttercream and fondant formulations as regional production facilities reduce cold-chain logistics premiums. Three-tier pricing structure across premium, standard, and economy levels separates wedding cake ganache from foodservice buttercream and mass-market glaze systems. Cost compression in chocolate-based segments is intensifying because cocoa butter volatility constrains pricing flexibility. Foodservice chains exhibit highest price sensitivity due to centralized procurement scale, while Tokyo patisseries show lowest sensitivity for custom fondant applications.
Supply Chain Analysis
EU Green Deal domestic-content mandates for recyclable packaging are reshaping sourcing patterns as European suppliers accelerate glass jar and aluminum sachet transitions ahead of extended producer responsibility deadlines. Manufacturing concentrates in the United States, Germany, and Belgium for temperature-controlled buttercream and fondant systems. Supply chains draw from cocoa butter processors, natural colorant extractors, and glucose syrup refiners. Single-source vulnerability runs through concentrated natural colorant suppliers facing FDA batch certification bottlenecks. Distribution runs through cooperative bakery networks and specialized e-procurement portals serving artisan producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EFSA packaging migration limits and FDA color additive mandates continuously force portfolio reformulation, creating sustained demand for compliance-capable suppliers.
For Market Incumbents: Hedge against cocoa butter price volatility through backward integration into chocolate processing or long-term offtake agreements with West African suppliers. Reinforce technical service capabilities around temperature-controlled handling protocols to lock in cooperative bakery contracts as procurement centralizes. Prioritize natural colorant sourcing infrastructure to preempt FDA certification delays that stall product launches.
For New Entrants and Emerging Players: The price-point gap between premium Japanese wedding cake ganache and economy foodservice glaze creates white-space opportunity for mid-tier fondant systems with clean-label positioning. Target Germany's artisan bakery cooperatives through specialized e-procurement portals bypassing traditional wholesale intermediaries. Pursue edible inkjet printing convergence as the most penetrable technology segment for digital decoration platforms.
For Investors and Strategic Acquirers: Consolidation pressure builds where clean-label reformulation capex burdens exceed standalone R&D capacity for regional specialists. Five-to-ten-year viability favors suppliers with captive natural colorant sourcing and cooperative bakery network density. Target acquisition archetype: regional bakery supply specialists with technical service capabilities and EFSA-compliant packaging infrastructure. Signal to watch: FDA batch certification backlogs triggering forced product delistings at smaller competitors.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Natural Colorant Sourcing | Captures margin from FDA certification delays while securing clean-label supply for reformulation mandates. |
| Cooperative Bakery Network Expansion | Locks in volume concentration as procurement centralizes through technical specification programs in the United States. |
| Edible Inkjet Printing Platform Deployment | Absorbs skilled technician labor hours while compressing turnaround for personalized cake orders in Germany. |
| Glass Jar Packaging Transition | Preempts EU Green Deal extended producer responsibility deadlines for European retail channel continuity. |
| Direct-to-Artisan E-Procurement Portal Launch | Bypasses wholesale intermediaries to capture margin from independent bakery cooperatives scaling premium procurement. |
Research Methodology
Bottom-up bakery and foodservice modeling reconciled against top-down ingredient supplier tracking forms the analytical core. Primary interviews with bakery cooperative procurement directors, pastry shop owners, foodservice chain supply managers, and decoration product R&D heads combined with secondary validation from FDA color additive certification databases, EFSA food contact material standards filings, and EU Green Deal packaging directive implementation timelines. Trade data from customs records and cooperative bakery network procurement disclosures anchored supply-side triangulation.
Input-output matrices mapped formulation inputs through finished decoration outputs across product type, application occasion, packaging format, and end-user channel dimensions throughout the forecast period. CAGRs derived from segment-level volume buildups reconciled against macroeconomic consumption indicators and regulatory implementation schedules. Temperature-controlled logistics cost curves and natural colorant price indices fed industry-specific forecast sensitivity testing.
Caveats apply where FDA batch certification backlogs, cocoa butter commodity spikes, or EU packaging compliance deadline accelerations could materially shift the outlook. Forecasts reflect documented assumptions about regulatory implementation pacing and cooperative bakery network consolidation trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Pastry Dough Market
Bakery Products
Gluten-Free Bakery Market
Bakery Products
Bakery Premixes Market
Bakery Products
Asia-Pacific Baked Food and Cereals Market
Bakery Products
North America Gluten Free Bakery Mixes Market
Bakery Products
Bakery Flavors Market
Bakery Products
Gluten-Free Bread Market
Bakery Products
Pizza Crust Mix Market
Bakery Products
Yeastless Dough Market
Bakery Products
Low-Calorie Breakfast Muffins Market
Bakery Products
Bakery Cases Market
Bakery Products
Pizza Crust Market
Bakery Products
Cakes, Pastries, and Sweet Pies Market
Bakery Products
Dough Whitener Market
Bakery Products
Bakery Emulsions Market
Bakery Products
Qatar Bakery Product Market