
 Dough Whitener Market | 2026-2036
Dough Whitener Market Size, Share, and Industry Trends Forecast 2026-2036
Dough Whitener Market Analytics
Industrial food manufacturers are redrawing procurement patterns for dough whitening solutions, shifting from legacy oxidizing agents toward enzyme-based alternatives. Solvay leverages its peroxide chemistry heritage to sustain supply relationships with commodity bakeries across Western Europe. Evonik Industries AG specializes in biotechnology-derived whitening enzymes that compete on clean-label positioning. BASF SE anchors volume through its broad chemical whitener blends portfolio serving multinational snack producers.
Dough whitener denotes a class of food-grade additives—encompassing benzoyl peroxide, azodicarbonamide, and glucose oxidase formulations—designed to bleach flour proteins and improve crumb color uniformity in finished baked goods. These agents typically function at inclusion rates between 15 and 75 parts per million, depending on flour extraction rate and desired optical brightness. Oxidizing agents retain the largest installed base among product types, though enzymatic whiteeners capture accelerating interest from manufacturers reformulating around regulatory pressures. Chemical whitener blends concentrate margin pools where distributors bundle conditioners with color stabilizers for mid-size bakeries.
The EU's EFSA and REACH frameworks restrict certain peroxide residues in finished bread, while the FDA maintains GRAS status for benzoyl peroxide within specified limits—creating divergent compliance burdens for exporters. India's FSSAI has tightened additive labeling requirements, forcing reformulation decisions for suppliers targeting its organized bakery sector. Stakeholders must monitor regulatory divergence between jurisdictions and calibrate R&D pipelines toward enzyme platforms that satisfy multiple standards simultaneously.
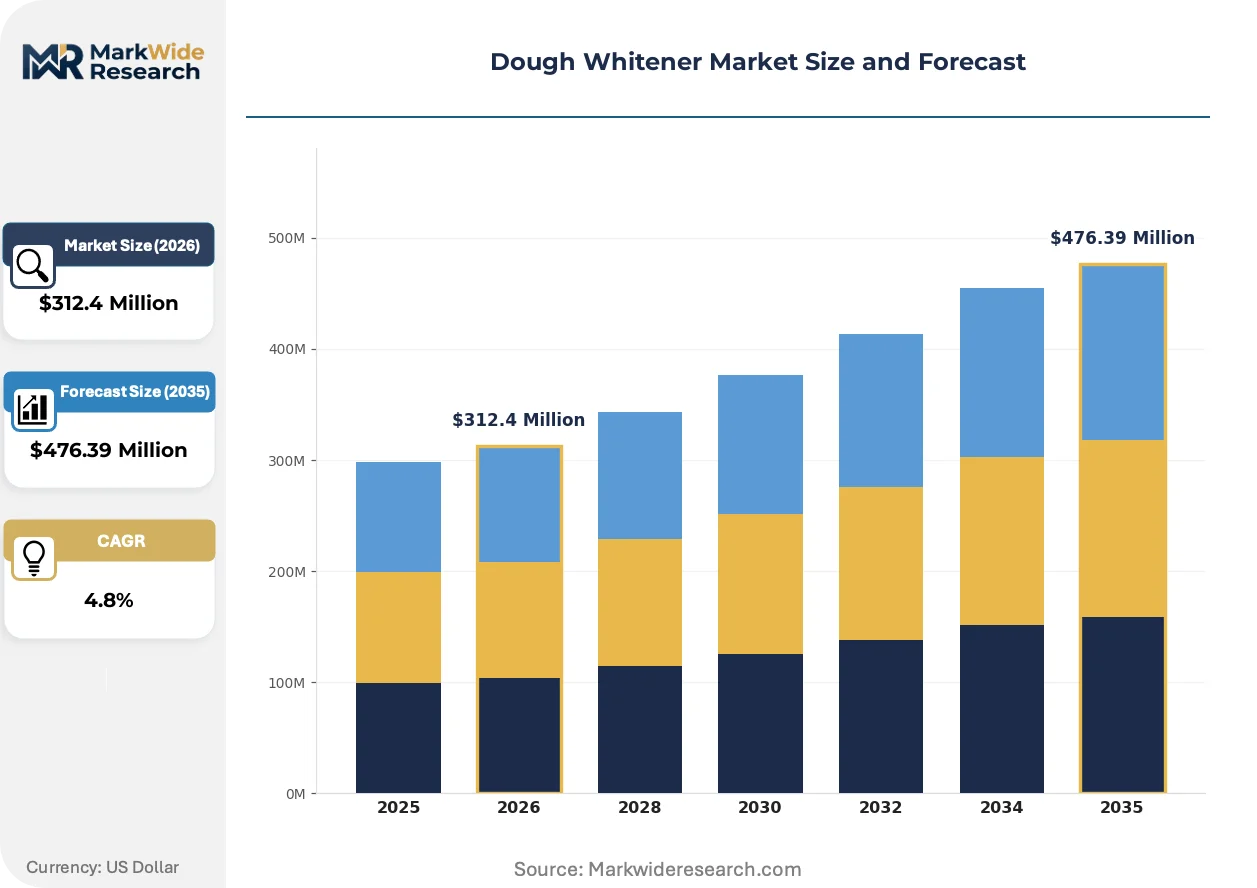
Market Dynamics
Enzymatic whitening platforms are displacing legacy peroxide systems as industrial bakeries face mounting pressure from the EU's F-Gas Regulation and REACH chemical thresholds. This technology pivot is redrawing supplier relationships and R&D allocation across Western European milling corridors.
Growth Catalysts
- REACH chemical restrictions:The EU's tightening peroxide residue limits force industrial bakeries toward enzymatic alternatives that bypass EFSA scrutiny while maintaining crumb brightness specifications.
- Glucose oxidase platforms:Biotechnology-derived whitening enzymes now achieve optical performance parity with benzoyl peroxide at inclusion rates below 50 parts per million.
- German bread production clusters:Large-scale facilities in Baden-Württemberg and Bavaria are upgrading formulation standards ahead of anticipated additive phase-outs.
Market Restraints
- Enzyme input cost volatility:Fermentation-derived glucose oxidase concentrates face price pressure from competing pharmaceutical demand for biocatalysts.
- Technical performance ceiling:Enzymatic whiteners struggle to match the rapid bleaching kinetics of azodicarbonamide in high-extraction flour above 85% ash content.
- Regulatory friction from FDA divergence:The United States maintains GRAS status for benzoyl peroxide, complicating unified formulation strategies for exporters serving both Atlantic markets.
Strategic Opportunities
- India's organized bakery sector:FSSAI labeling mandates are accelerating clean-label reformulation among Mumbai and Bangalore-based industrial producers.
- Enzyme-ascorbic acid convergence:Combined oxidative systems that pair glucose oxidase with vitamin C derivatives offer dual-function conditioning and whitening.
- Direct-to-mill distribution channels:Bypassing traditional chemical distributors allows enzyme suppliers to capture margin pools previously held by commodity bleach traders.
Industry Challenges
- Bioprocess engineering talent scarcity:Industrial enzyme production requires fermentation specialists whose skills concentrate in Basel and Copenhagen biotech clusters.
- Legacy equipment incompatibility:Existing dosing systems calibrated for powder peroxides demand retrofitting for liquid enzyme concentrates.
- Multi-jurisdiction certification timelines:Securing simultaneous approvals under EFSA, FDA, and FSSAI frameworks extends product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dough Whitener Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $476.39 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oxidizing Agents, Enzymatic Whiteeners, Chemical Whitener Blends, Dough Conditioners Application: Baking, Noodles, Snacks, Confectionery Distribution Channel: Online Retailers, Supermarkets, Distributors, Food Service End User: Bakers, Food Manufacturers, Industrial Kitchens, Home Bakers |
| Companies Covered | Solvay, Evonik Industries AG, BASF SE, Arkema S.A., Nouryon, AkzoNobel N.V., Kemira Oyj, Clariant AG, Aditya Birla Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dough Whitener Market Evolving Landscape
Formulation science is converging with bioprocess engineering as suppliers race to deliver enzyme systems that satisfy divergent regulatory regimes without sacrificing process efficiency. Three developments are compressing competitive timelines.
Microencapsulated enzyme delivery systems are miniaturizing active ingredient protection down to sub-micron lipid shells that survive high-shear mixing in industrial dough processing. Mid-size bakeries in the Netherlands and Belgium are piloting these formats to eliminate pre-hydration steps. The technology is compressing equipment capital requirements for enzymatic transitions.
The EU's F-Gas Regulation is accelerating refrigerant-phase chemistry restrictions that indirectly constrain peroxide storage and handling infrastructure. Industrial bakery operators in Germany and France face facility upgrade mandates that favor enzyme platforms requiring no controlled-temperature containment. High-volume bread producers are front-loading enzymatic trials to preempt compliance deadlines.
Ingredient specification sheets now dominate purchasing negotiations as procurement teams consolidate supplier bases around dual-certified enzyme portfolios. Distributors serving French and Italian artisan-industrial hybrids are losing ground to direct manufacturer relationships. This pattern concentrates most visibly in Spain's emerging industrial bakery corridor between Madrid and Valencia.
Dough Whitener Market Segmentation
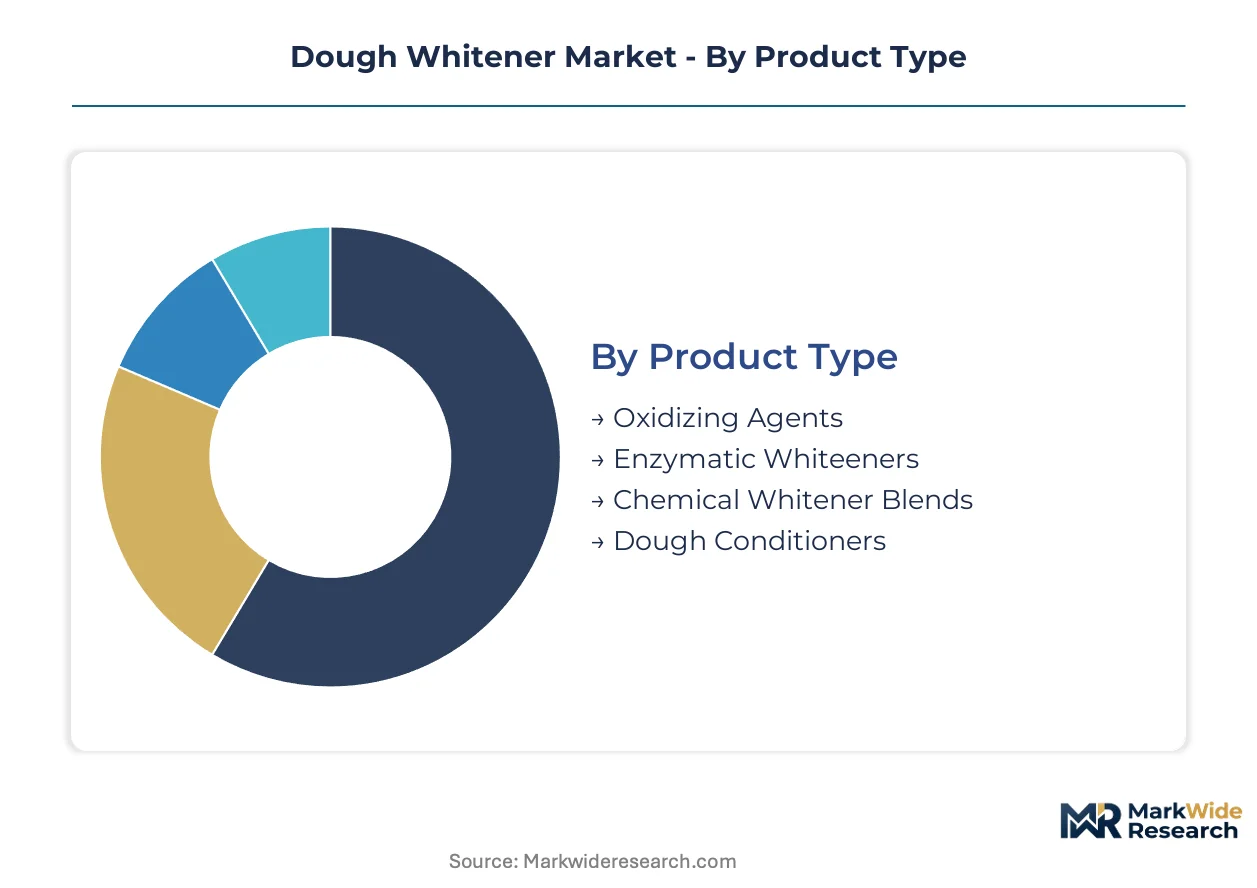
Segmentation in the dough whitener market reveals how regulatory pressure and formulation complexity split procurement behaviors. Industrial buyers prioritize enzymatic platforms for EU compliance, while commodity producers optimize around chemical cost structures. Understanding these divides clarifies where suppliers can defend margin pools.
Product Type:
REACH thresholds and FDA divergence create divergent technology adoption curves across whitening chemistries.
- Oxidizing Agents:Benzoyl peroxide and azodicarbonamide formulations dominate legacy installations in high-volume bread plants. US commodity bakeries in the Midwest and Southeast sustain procurement volumes despite European phase-out trajectories.
- Enzymatic Whiteeners:Glucose oxidase concentrates achieve optical parity at sub-50 ppm inclusion rates. German industrial facilities in Baden-Württemberg and Bavaria are retrofitting dosing systems to capture F-Gas Regulation compliance advantages.
- Chemical Whitener Blends:Powdered peroxide-ascorbate combinations serve mid-tier bakeries seeking single-step conditioning.
- Dough Conditioners:Integrated whitening-strengthening systems reduce ingredient handling steps for artisan-industrial hybrids.
Established volume favors oxidizing agents; emerging adoption favors enzymatic whiteeners.
Application:
Crumb color specifications vary sharply across finished goods categories, reshaping formulation priorities.
- Baking:Pan bread and bun manufacturers face the strictest EFSA residue scrutiny. Large-scale German and French facilities are consolidating supplier relationships around dual-certified enzyme portfolios to preempt multi-jurisdiction audit failures.
- Noodles:Asian wheat noodle producers prioritize rapid bleaching kinetics for high-extraction flour above 85% ash. Azodicarbonamide retains footholds where regulatory enforcement remains fragmented.
- Snacks:Cracker and biscuit makers balance whitening with Maillard control requirements.
- Confectionery:Precision color targets in wafer and sponge applications favor microencapsulated enzyme delivery.
Volume concentrates in baking; steepest expansion trajectory appears in noodles as clean-label reformulation accelerates across Asian organized sectors.
Distribution Channel:
Margin capture depends on bypassing legacy chemical distributor markups.
- Online Retailers:Specialty enzyme concentrates and small-batch conditioners reach artisan bakers through direct-to-kitchen platforms. Netherlands-based pilot programs demonstrate compressed capital requirements for enzymatic transitions.
- Supermarkets:Private-label bread programs drive consolidated procurement of standardized whitener blends. Spanish retail chains between Madrid and Valencia are front-loading supplier consolidation to secure volume pricing.
- Distributors:Traditional chemical traders retain mid-size bakery relationships through bundled conditioner offerings.
- Food Service:Industrial kitchen contracts prioritize shelf-stable powder formats for logistics simplicity.
Direct channels gain share fastest; distributor intermediation faces margin compression.
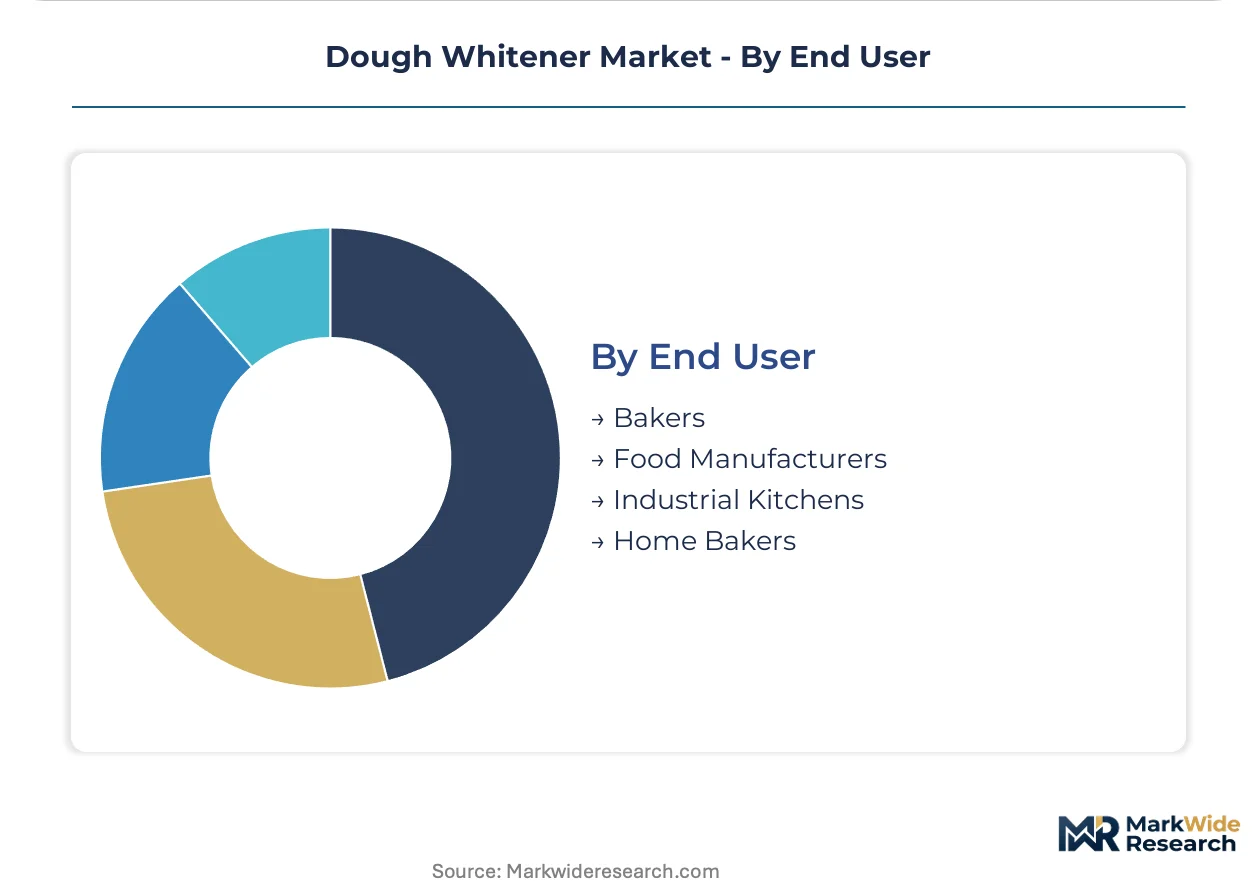
End User:
Scale determines whether enzymatic conversion economics justify equipment retrofit costs.
- Bakers:Independent and chain bakeries represent the most fragmented demand pool. Italian artisan-industrial hybrids in Emilia-Romagna and Lombardy are piloting microencapsulated systems to eliminate pre-hydration steps.
- Food Manufacturers:Multinational snack producers anchor volume through long-term chemical whitener blend contracts. BASF and Solvay sustain relationships here via broad portfolio availability.
- Industrial Kitchens:Centralized production facilities for hospitality chains favor single-source conditioning systems.
- Home Bakers:Consumer-packaged whitening aids remain a marginal segment with limited formulation innovation.
Procurement sophistication clusters with food manufacturers; conversion flexibility concentrates among bakers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical handling infrastructure underwrites Northwestern Europe's dominance in dough whitener trade flows, connecting German milling corridors to Atlantic export routes.
Germany
Baden-Württemberg and Bavaria host Europe's densest concentration of industrial bread production facilities. The F-Gas Regulation's refrigerant-phase chemistry restrictions are forcing facility upgrades that favor enzyme platforms over peroxide storage systems. Stuttgart-based milling clusters are retrofitting dosing equipment to accommodate glucose oxidase concentrates ahead of compliance deadlines.
United States
Midwest commodity bakeries sustain legacy benzoyl peroxide procurement despite European phase-out trajectories. FDA GRAS status for oxidizing agents creates regulatory divergence that complicates unified formulation strategies for exporters. Chicago and Minneapolis production corridors anchor volume demand through long-term chemical whitener blend contracts.
France
Artisan-industrial hybrid bakeries in Île-de-France and Auvergne-Rhône-Alpes are piloting microencapsulated enzyme delivery systems. EFSA residue scrutiny under REACH frameworks drives procurement consolidation around dual-certified portfolios. Parisian distribution networks are losing ground to direct manufacturer relationships as specification sheets dominate purchasing negotiations.
India
Mumbai and Bangalore-based organized bakery producers face FSSAI labeling mandates accelerating clean-label reformulation. The central food regulator's tightened additive disclosure requirements are forcing supplier switching decisions. Western Maharashtra's industrial baking corridor is front-loading enzymatic trials to preempt enforcement timelines.
Netherlands
Antwerp-Rotterdam port chemistry clusters enable enzyme concentrate import and formulation blending for EU distribution. Dutch mid-size bakeries are compressing capital requirements for enzymatic transitions through online retail procurement channels. Eindhoven-region equipment vendors are retrofitting legacy powder dosing systems for liquid enzyme compatibility.
Dough Whitener Market Competitive Landscape
Listed leaders compete with private specialists across formulation technology and regulatory certification breadth. The supplier base concentrates around three tiers: multinational chemical conglomerates with peroxide heritage, biotechnology specialists with enzyme platforms, and regional distributors bundling conditioners for mid-tier bakeries. Strategic moves center on direct-to-mill channel bypassing and dual-jurisdiction certification stacking to compress launch timelines.
Within the multinational chemical tier, Solvay and BASF SE occupy positions anchored by broad portfolio availability and commodity bakery relationships. Evonik Industries AG exemplifies the biotechnology specialist archetype, representing enzyme-based clean-label positioning against legacy oxidizing agents. These three entities collectively illustrate how regulatory divergence between EFSA and FDA frameworks is fragmenting competitive strategy across Atlantic markets.
| Leading Market Players |
|---|
| Solvay |
| Evonik Industries AG |
| BASF SE |
| Arkema S.A. |
| Nouryon |
| AkzoNobel N.V. |
| Kemira Oyj |
| Clariant AG |
| Aditya Birla Chemicals |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day glucose oxidase concentrate lead times from Basel and Copenhagen fermentation clusters concentrate pricing power among biotechnology specialists serving German industrial bakeries. This inventory compression tightens procurement negotiating positions for mid-size facilities retrofitting legacy peroxide dosing equipment.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification breadth and volume commitment. Premium tiers capture dual-certified enzyme portfolios for EFSA-FDA convergence; standard tiers serve single-jurisdiction commodity bakeries; economy tiers supply powder peroxide blends for cost-optimized Midwest US facilities. Price differentiation hinges on REACH compliance documentation depth and after-sales technical support bundling. Pricing pressure stems from pharmaceutical sector competition for biocatalyst fermentation capacity. Commodity bakeries in the US Midwest exhibit highest price sensitivity; multinational snack producers anchored by BASF and Solvay contracts show lowest.
Supply Chain Analysis
Antwerp-Rotterdam port chemistry infrastructure serves as the chokepoint for enzyme concentrate import and EU-wide distribution. Manufacturing concentrates in Germany, Switzerland, and Denmark; fermentation feedstocks draw from agricultural suppliers in France and the Netherlands. Raw material dependencies include glucose syrup, specialized yeast strains, and lipid encapsulation compounds. Single-source vulnerability runs through Copenhagen-region fermentation specialists for high-activity glucose oxidase. Distribution runs through direct-to-mill channels bypassing legacy chemical distributors for large-scale German and French facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dough whitener market sits at a platform-economics inflection where enzyme-as-a-service formulations interoperate across EFSA, FDA, and FSSAI regulatory stacks, collapsing multi-certification timelines into unified specification sheets.
For Market Incumbents: Fortify certification breadth through simultaneous EFSA-FDA submission stacking to compress launch cycles against emerging biotechnology specialists. Prioritize backward integration into fermentation capacity near Basel and Copenhagen clusters to secure biocatalyst supply against pharmaceutical sector competition. Channel control through direct-to-mill relationships in Germany's Baden-Württemberg corridor defends margin pools from distributor disintermediation. For New Entrants and Emerging Players: Lead with microencapsulated enzyme delivery systems targeting Italian artisan-industrial hybrids in Emilia-Romagna seeking pre-hydration elimination. India's Mumbai-Bangalore organized bakery corridor offers most penetrable geography given FSSAI labeling mandate enforcement timelines. Go-to-market angle should emphasize online retail procurement channels compressing capital requirements for enzymatic transitions. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational chemical conglomerates seeking to divest legacy peroxide portfolios amid REACH phase-out trajectories. Long-term viability favors biotechnology platforms with dual-certified enzyme pipelines spanning Atlantic regulatory divergence. Signal to watch is FSSAI enforcement acceleration prompting supplier switching decisions among Western Maharashtra industrial baking clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Copenhagen and Basel biotech clusters anchor biocatalyst supply security against pharmaceutical competition. |
| Dual-Certification Portfolio Development | Simultaneous EFSA-FDA submissions compress product launch timelines for Atlantic market convergence. |
| Direct-to-Mill Channel Establishment | Bypassing chemical distributors captures margin pools in Germany's large-scale bread production corridors. |
| Microencapsulated Delivery System Launch | Sub-micron lipid shells eliminate pre-hydration steps for Italian artisan-industrial hybrid bakeries. |
| Online Retail Procurement Platform | Netherlands-based pilots demonstrate compressed capital requirements for mid-size enzymatic transitions. |
Research Methodology
A spread of perspectives from fermentation plant managers, industrial bakery procurement leads, distribution channel partners, and EFSA regulatory affairs specialists converged on the working assumptions. Primary interviews combined with secondary validation from customs/trade data, Cefic chemical industry reports, SEC 10-K filings, and FSSAI additive disclosure databases. Bottom-up volume modeling triangulated against top-down market sizing across enzymatic and chemical whitening platforms.
Segmentation dimensions modeled include product type tier, application category, distribution channel structure, and end-user scale classification across the analysis window. CAGRs derived from regression analysis against industrial bakery capacity expansion trajectories and regulatory enforcement timeline assumptions. Forecast inputs incorporated F-Gas Regulation compliance deadline clustering and FSSAI labeling mandate acceleration patterns.
The analysis sits within stated boundaries; outcomes outside synchronized EFSA-FDA-FSSAI enforcement trajectories or glucose oxidase fermentation capacity expansion would require recalibration. Forecasts reflect documented assumptions regarding regulatory divergence persistence and biocatalyst input cost volatility. Practitioners should keep alternative scenarios live as REACH threshold tightening and pharmaceutical sector biocatalyst competition evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Global Bakery Product Market
Bakery Products
Frosting, Toppings, and Decorations Market
Bakery Products
Toasted Flour Market
Bakery Products
Specialty Frozen Bakery Market
Bakery Products
Par-Baked Bread Market
Bakery Products
Pastry Margarine Market
Bakery Products
Doughnuts Market
Bakery Products
Qatar Bakery Product Market
Bakery Products
Cakes and Pastries Market
Bakery Products
United States Cookies Market
Bakery Products
Diabetic Bakery Products Market
Bakery Products
Low Fat Muffin Market
Bakery Products
Fortified Bakery Market
Bakery Products
Low Fat Bread Market
Bakery Products
Multigrain Bread Mix Market
Bakery Products
South America Bakery Products Market