
 Almond Flour Market | 2026-2036
Almond Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Almond Flour Market Intelligence
Access to capital for advanced milling and processing equipment is rewriting the competitive landscape for almond flour producers. This shift favors large-scale operators with integrated supply chains. Blue Diamond Growers leverages its vast cooperative structure for consistent almond supply. Borges Agricultural & Industrial Nuts, S.A. competes on its extensive global distribution network, while Bob's Red Mill Natural Foods differentiates through its strong brand within the specialty health food channel.
Almond flour is a grain-free baking ingredient produced from finely ground almonds, typically after a blanching process removes the skins. Its chemical composition, high in protein and healthy fats but low in carbohydrates, makes it a staple for specific dietary formulations like ketogenic plans. Blanched almond flour leads the product type category due to its fine texture preferred in confectionery and baking. The gluten-free baking application segment is expanding rapidly as consumers seek wheat alternatives.
Food allergen labeling mandates from the US Food and Drug Administration (FDA) and parallel regulations in the European Union dictate packaging requirements. Health claims associated with almond-based products are reviewed by authorities like the European Food Safety Authority (EFSA), shaping marketing strategies. To secure premium positioning, producers must navigate evolving international standards for organic and non-GMO certifications.
Market Dynamics
Consumer-led demand for gluten-free and low-carbohydrate baking alternatives is the primary force shaping the almond flour market. This health-driven pull directly influences processing investments, product formulation, and global trade flows for specialized almond products.
Growth Catalysts
- Allergen-Driven Reformulation:Food allergen labeling mandates from the US FDA and parallel rules in the European Union compel food manufacturers to reformulate products, creating a direct pull for wheat flour alternatives.
- Dietary Sector Expansion:The expansion of ketogenic and paleo diet food sectors, especially in prepared foods and baking mixes, provides a dedicated, high-value application segment for almond flour.
- European Health Consciousness:Rising disposable incomes and health awareness in markets such as Germany and the UK create concentrated pockets of demand for premium, health-oriented baking ingredients.
Market Restraints
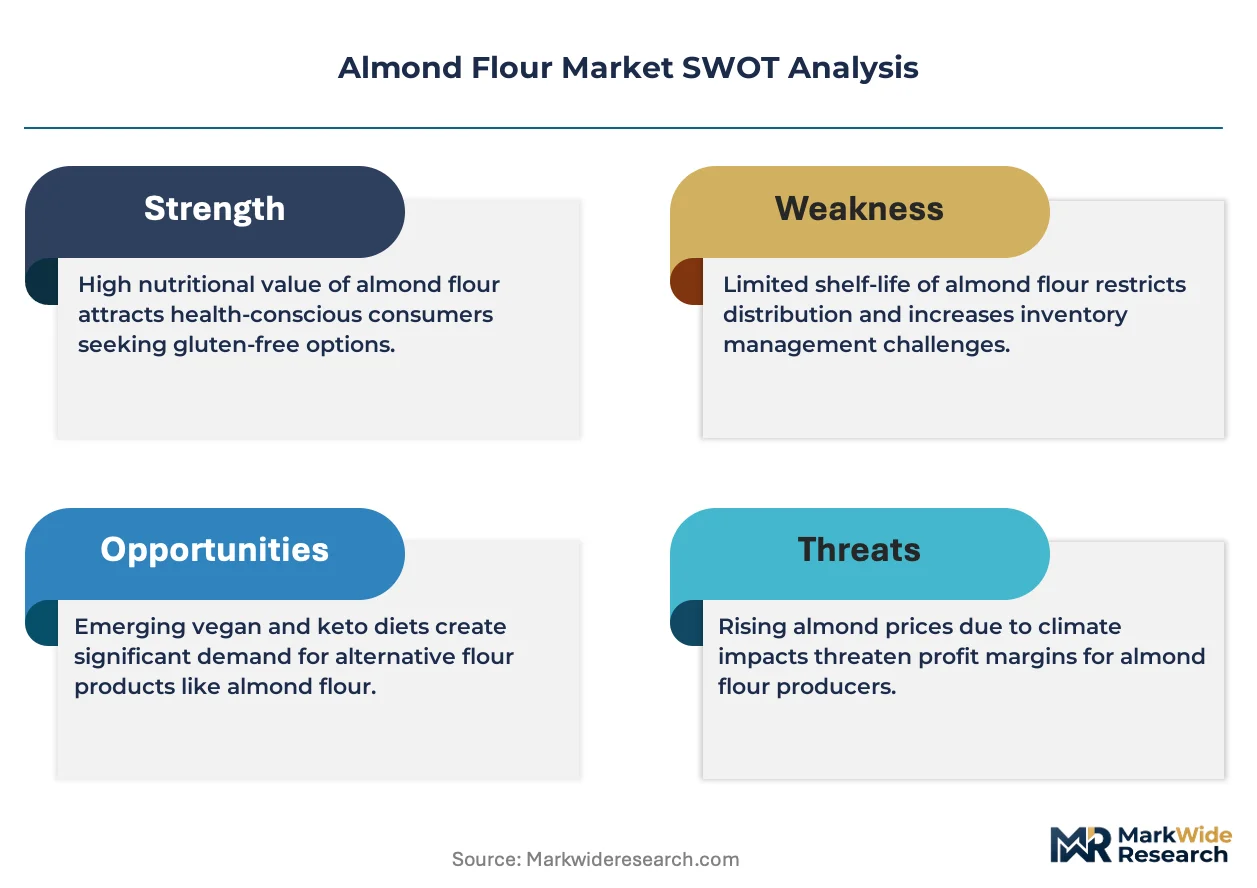
- Input Cost Volatility:Almond price fluctuations, linked to water availability and climatic conditions in primary growing regions like California, create unpredictable input costs for flour producers.
- Substitution from Alternatives:The availability of lower-cost nut flours, particularly coconut flour, and an expanding array of seed flours presents a significant substitution threat in price-sensitive channels.
- Aflatoxin Regulation:Strict regulations on aflatoxin levels in almonds, actively enforced by bodies like the European Food Safety Authority (EFSA), can lead to shipment rejections and supply chain disruptions.
Strategic Opportunities
- Application Beyond Baking:Developing almond flour-based products such as high-protein pastas, savory snacks, and breadings for ready-to-eat meals represents a significant opportunity beyond the core confectionery segment.
- Asia-Pacific Market Entry:Markets in Australia and South Korea show nascent but growing consumer interest in gluten-free and low-carbohydrate lifestyles, offering new geographic growth frontiers for exporters.
- Direct-to-Consumer Channels:Building direct-to-consumer (DTC) subscription models for specialty baking ingredients enables producers to capture higher margins and cultivate brand loyalty among dedicated home bakers.
Industry Challenges
- Capital for Advanced Milling:Securing capital for high-capacity blanching and ultra-fine milling equipment is a major hurdle for smaller producers attempting to scale operations and achieve cost-competitiveness.
- Certification and Compliance Burden:Navigating the complex, country-specific, and often costly processes for organic, non-GMO, and gluten-free certifications creates a significant operational burden for producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Almond Flour Market |
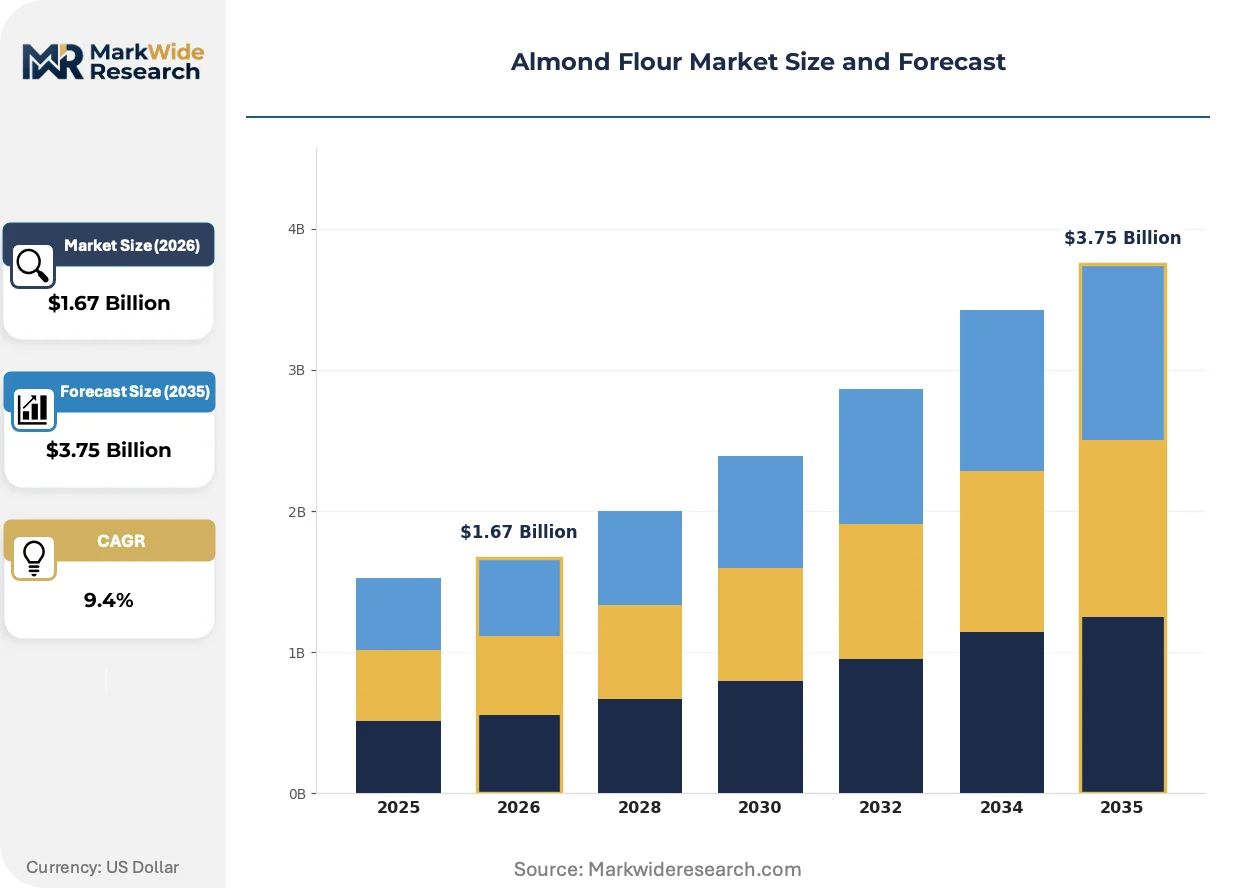
| Market Size in 2026 | $1.67 Billion |
| Market Size in 2035 | $3.75 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blanched Almond Flour, Natural Almond Flour, Raw Almond Flour, Roasted Almond Flour Application: Gluten-Free Baking, Confectionery, Beverage Additives, Nutritional Supplements, Cosmetic Ingredients Packaging Type: Plastic Bags, Paper Bags, Stand-Up Pouches, Bulk Packaging Customer Type: Food Manufacturers, Health Food Stores, Specialty Bakeries, Dietary Clinics |
| Companies Covered | Borges Agricultural & Industrial Nuts, S.A, Treehouse California Almonds LLC, Blue Diamond Growers, Hodgson Mill Inc., Olam International Ltd., Bob's Red Mill Natural Foods, Royal Nut Company, SunOpta, Inc., John B. Sanfilippo and Son Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Almond Flour Market Strategic Shifts & Innovations
Product and process sophistication defines the current innovation cycle in the almond flour market. This shift is driven by a need to enhance texture, comply with nuanced food safety rules, and cater to more specific dietary sub-segments.
Digital twin technology for milling operations allows producers to create detailed simulations of their processing lines. Large-scale producers are adopting this to optimize for particle size, temperature, and oil content without physical trial runs. This approach is virtualizing the historically manual process of quality control and new product development, accelerating time-to-market for custom flour grades.
New front-of-pack nutrition labeling proposals from the FDA and similar initiatives in Europe are influencing product formulation. These regulations pressure manufacturers to improve nutritional profiles, making low-carbohydrate, high-protein ingredients like almond flour more attractive for achieving favorable scores. The gluten-free baking mix segment is most affected, actively reformulating products to highlight these positive attributes on new packaging.
A notable behavioral shift involves consumers seeking specific flour attributes, such as "super-fine" grind for macarons or "natural" almond meal with skins for rustic baking. This specialization disrupts the one-size-fits-all model, favoring brands that offer a portfolio of textures over single-product bulk suppliers. The trend is most visible within the direct-to-consumer and specialty health food channels in North America and Western Europe.
Almond Flour Market Segmentation
Segmentation provides a granular view of the almond flour market, revealing distinct product attributes, application areas, and consumer profiles. This detailed breakdown helps producers and distributors tailor offerings and optimize their strategic positioning. Understanding these segments is crucial for identifying areas of concentrated demand and emerging growth opportunities.
Product Type:
The after-sales service intensity for different almond flour product types varies, reflecting diverse processing requirements and customer expectations for texture and shelf life.
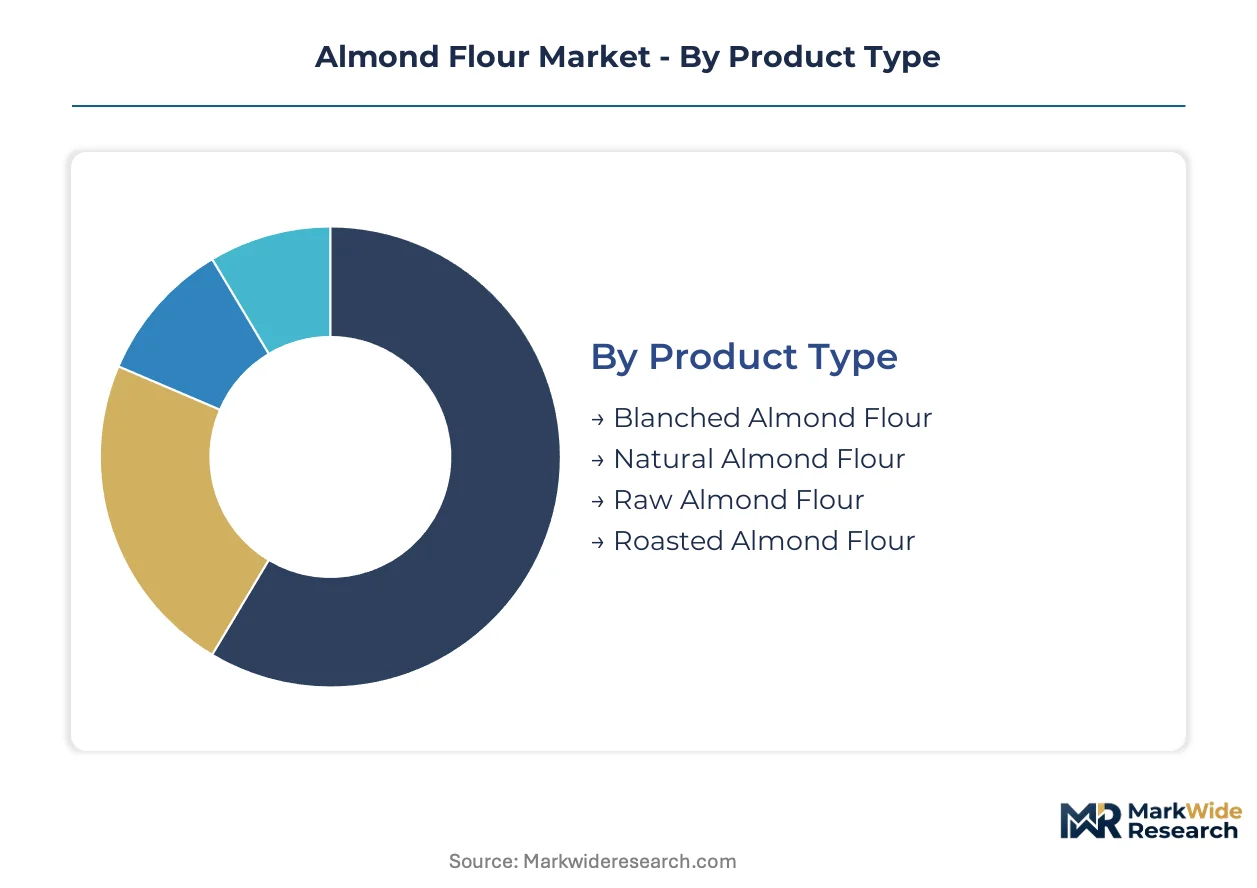
- Blanched Almond Flour:Produced from blanched almonds with skins removed, resulting in a very fine, light-colored flour. Confectionery and gluten-free baking applications drive demand in Western Europe due to its superior texture for delicate pastries and cakes.
- Natural Almond Flour:Made from whole, unblanched almonds with skins intact, offering a slightly coarser texture and richer flavor. Home bakers and specialty health food channels in North America seek this type for rustic breads and baked goods, valuing its nutritional profile.
- Raw Almond Flour:This flour is minimally processed from raw almonds, preserving enzyme activity and a distinct, fresh almond taste.
- Roasted Almond Flour:Roasted almonds are ground into this flour, imparting a deeper, nuttier flavor profile often used in savory dishes and specialized baking.
By volume, Blanched Almond Flour leads. By growth pace, Natural Almond Flour is ahead.
Application:
The application segments for almond flour exhibit distinct cost structures, influenced by the required purity, particle size, and functional properties for each end-use.
- Gluten-Free Baking:Utilized as a primary wheat flour alternative in baked goods for consumers with gluten sensitivities or dietary preferences. This segment experiences concentrated demand in Germany, driven by stringent allergen labeling and a health-conscious consumer base.
- Confectionery:Incorporated into macaroons, marzipan, and other delicate sweets, valued for its fine texture and mild flavor. European markets, particularly France and Italy, show consistent demand for confectionery applications, where traditional recipes rely on almond flour.
- Beverage Additives:Almond flour adds protein and texture to smoothies, shakes, and plant-based milk alternatives, catering to functional beverage trends.
- Nutritional Supplements:Used in protein bars, meal replacements, and powdered supplements for its high protein and healthy fat content.
- Cosmetic Ingredients:Employed in natural skincare products as an exfoliant or emollient, leveraging its fine texture and nourishing properties.
Gluten-Free Baking experiences the steepest expansion trajectory. Confectionery maintains a stable and significant market share.
Packaging Type:
Packaging types for almond flour reflect the volume requirements and specific handling needs of different customer segments, from industrial users to individual consumers.
- Plastic Bags:Lightweight, resealable plastic pouches or bags offer convenience and moisture protection for consumer-sized portions. Retail grocery channels in the US drive significant demand for plastic bags due to their cost-effectiveness and consumer appeal.
- Bulk Packaging:Large sacks, super sacks, or drums designed for industrial-scale transport and storage of high volumes of almond flour. Food manufacturers and large-scale bakeries globally require bulk packaging to optimize their production lines and reduce per-unit costs.
- Paper Bags:Environmentally conscious consumers and specialty stores prefer paper bags for their biodegradability and natural aesthetic.
- Stand-Up Pouches:These innovative pouches offer strong shelf appeal and user-friendly features like reclosable zippers, popular in health food stores.
Bulk Packaging accounts for the largest volume. Stand-Up Pouches are rapidly gaining share in specialty retail.
Customer Type:
Customer type segmentation reveals varying levels of market maturity and specific supply chain requirements across the almond flour ecosystem.
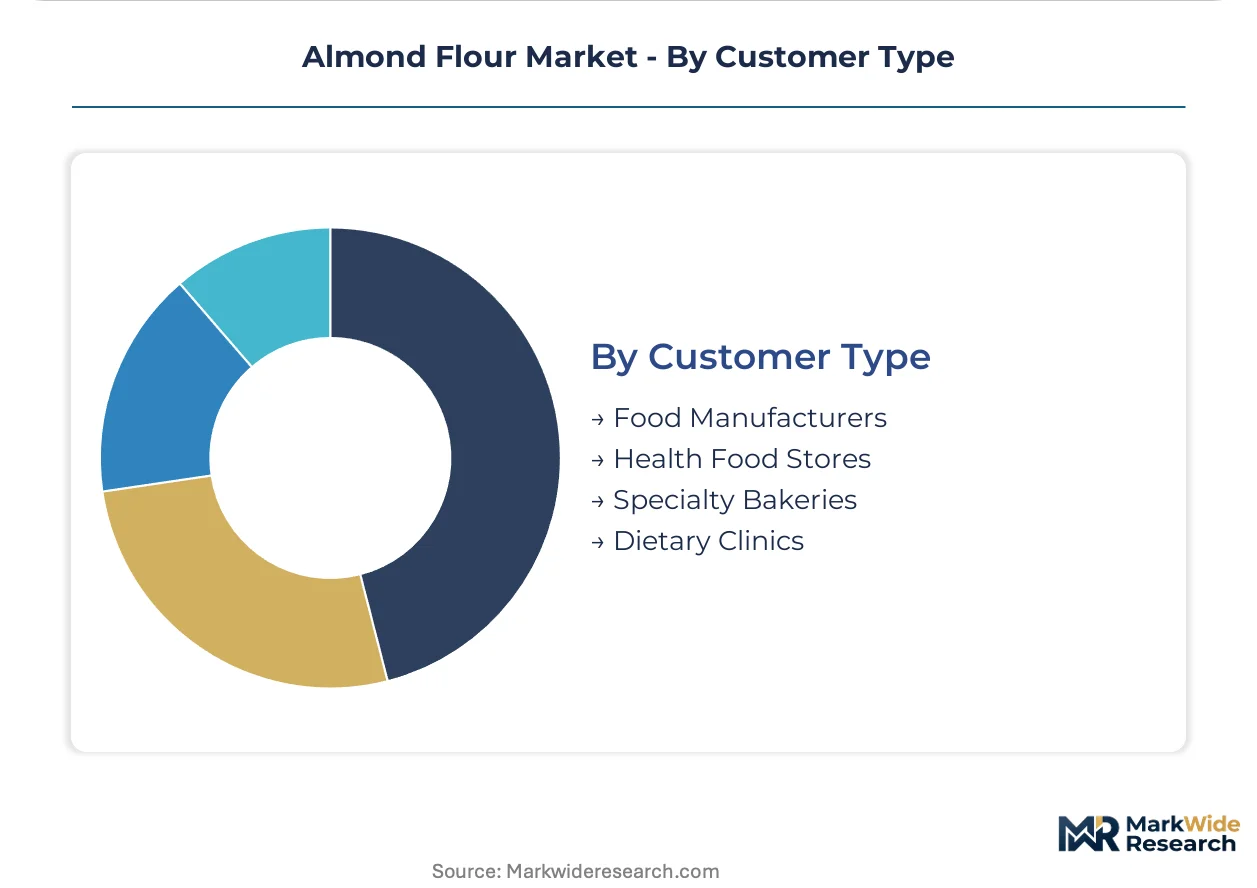
- Food Manufacturers:Industrial purchasers requiring large, consistent volumes of almond flour for diverse product lines, including snacks, cereals, and baked goods. Major food corporations in North America and Europe drive this segment, seeking reliable supply for their extensive product reformulations.
- Specialty Bakeries:Artisanal bakeries focusing on gluten-free or health-conscious products, demanding high-quality, often organic or non-GMO certified, almond flour. Urban centers across the UK and Australia exhibit strong demand from specialty bakeries catering to niche dietary preferences.
- Health Food Stores:These retailers stock various almond flour types for health-conscious consumers, emphasizing organic and non-GMO certifications.
- Dietary Clinics:Clinics and nutritionists recommend almond flour to patients following specific dietary plans like ketogenic or paleo, often purchasing in smaller, specialized quantities.
Food Manufacturers command the largest market share. Specialty Bakeries are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for almond flour exhibits asymmetry, with California's input cost volatility directly impacting global supply. In contrast, health-conscious consumer markets like Germany sustain premium pricing for specialized product formulations. This dynamic shapes investment flows and distribution strategies across regions.
United States
Demand for almond flour in the United States stems from home bakers and a robust specialty health food channel. FDA food allergen labeling mandates compel manufacturers to reformulate products, creating a consistent pull for wheat alternatives. Large-scale food manufacturers in North America drive demand for bulk supply to support extensive product lines.
Germany
Germany's health-conscious consumer base and rising disposable incomes fuel concentrated demand for premium almond flour. EU allergen labeling directives and EFSA reviews for health claims influence product formulation and marketing within the country. Urban centers across Germany exhibit strong demand from specialty bakeries catering to niche dietary preferences.
France
Confectionery applications, particularly macarons and marzipan, drive consistent demand for fine-textured almond flour in France. European food safety regulations, including EFSA guidelines, ensure product quality for traditional recipes. Major European confectionery hubs rely on a stable supply of blanched almond flour for their artisanal and industrial production.
South Korea
South Korea exhibits nascent but growing consumer interest in gluten-free and low-carbohydrate lifestyles. The country's Ministry of Food and Drug Safety (MFDS) oversees food standards and labeling, influencing import requirements. Exporters view South Korea as a new geographic growth frontier, particularly for health-oriented baking ingredients.
Australia
Australian consumers are increasingly adopting gluten-free and low-carbohydrate diets, expanding the market for almond flour. Food Standards Australia New Zealand (FSANZ) sets regulatory guidelines for food composition and labeling. Specialty bakeries in major Australian cities cater to this evolving consumer demand, driving growth in the premium segment.
Almond Flour Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, supplying raw materials and semi-processed ingredients. The market structure favors large-scale operators with integrated supply chains due to the capital intensity of advanced milling equipment. Strategic archetypes include vertically integrated growers, global distributors, and specialized brand manufacturers, all seeking to expand geographic reach or diversify product portfolios.
Vertically integrated growers, such as Blue Diamond Growers, leverage vast cooperative structures for consistent almond supply and processing. Global distributors like Borges Agricultural & Industrial Nuts, S.A. exemplify players focused on extensive international networks to reach diverse markets. Bob's Red Mill Natural Foods represents a specialized brand manufacturer, differentiating through strong presence within the health food channel and a portfolio of texture-specific products.
| Leading Market Players |
|---|
| Borges Agricultural & Industrial Nuts, S.A |
| Treehouse California Almonds LLC |
| Blue Diamond Growers |
| Hodgson Mill Inc. |
| Olam International Ltd. |
| Bob's Red Mill Natural Foods |
| Royal Nut Company |
| SunOpta, Inc. |
| John B. Sanfilippo and Son Inc. |
Cost & Logistics Intelligence
Almond price volatility in California directly impacts flour producers' margins, which then influences pricing strategies for premium baking ingredients. This upstream input cost concentration shapes the downstream profitability for specialty food manufacturers.
Pricing Analysis
Configured-to-order pricing for specialized almond flour grades, such as "super-fine" for macarons, commands a premium over standard commodity spot pricing for bulk blanched flour. Price differentiation occurs based on certification level, like organic or non-GMO, and the volume scale of purchase. Pricing softness reflects the availability of lower-cost nut flour alternatives, particularly coconut flour. Food manufacturers purchasing in bulk exhibit the highest price sensitivity, while specialty bakeries prioritize quality over cost.
Supply Chain Analysis
Export-control regimes, particularly strict aflatoxin regulations enforced by the European Food Safety Authority (EFSA), limit the flow of non-compliant almond shipments into lucrative European markets. The global almond supply chain concentrates heavily in the United States (California), Australia, and Spain, drawing from these primary growing regions. Raw material dependency on almond harvests creates a structural risk of input cost volatility due to water availability and climatic conditions. Distribution runs through a dual model, with bulk packaging for industrial food manufacturers and stand-up pouches for direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The almond flour market requires a robust substitution defense strategy, as incumbents must navigate the persistent threat from lower-cost alternatives like coconut flour and other seed flours. This competitive pressure necessitates continuous product differentiation and market expansion.
For Market Incumbents: Build brand equity through premium certifications, such as organic and non-GMO, to insulate against price erosion from generic alternatives. Invest in advanced milling equipment to achieve superior particle size consistency for delicate baking applications, enhancing product quality. This helps mitigate the margin pressure stemming from input cost volatility and broadens appeal beyond basic gluten-free needs. Control over the supply chain through cooperative structures ensures consistent raw material access.
For New Entrants and Emerging Players: Pursue niche application segments beyond traditional baking, such as high-protein pastas or savory snack breadings, where established players have less focus. The Asia-Pacific market, particularly South Korea and Australia, presents a penetrable geographic white space for health-oriented baking ingredients. Develop direct-to-consumer subscription models for specialty flour attributes, cultivating brand loyalty among dedicated home bakers. This direct channel strategy mitigates reliance on crowded retail shelves.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-sized, specialty health food brands that have established strong consumer loyalty and certification portfolios but lack capital for advanced milling expansion. Long-term viability for almond flour remains strong over the next decade due to sustained dietary trends and allergen-driven reformulation. Target acquisition profiles include companies with robust global distribution networks or unique product formulation expertise. The signal to watch is the increasing market share of non-blanched or roasted almond flours.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Ultra-Fine Milling Technology | Enhances product quality for delicate confectionery, expanding market reach in European patisseries. |
| Diversify into Savory Applications | Captures new revenue streams in high-protein snacks and gluten-free breadings for food manufacturers. |
| Expand Non-GMO/Organic Certification | Secures premium positioning and meets evolving health-conscious consumer demand in Germany. |
| Develop Direct-to-Consumer Channels | Cultivates brand loyalty and captures higher margins from dedicated home bakers in North America. |
| Strengthen Supply Chain Resilience | Mitigates input cost volatility from California's almond harvests, ensuring consistent production. |
Research Approach
A standing panel of food manufacturers' procurement leads, specialty bakery owners, health food store buyers, and almond growers provided ongoing calibration and validation for market trends. This analysis combined extensive primary interviews with secondary validation from agricultural commodity reports, food regulatory body publications (e.g., EFSA, FDA), and industry association data. Bottom-up data aggregation and top-down market sizing approaches were triangulated for accuracy.
Scenario-bracketing established upper and lower bounds for market projections across the analysis window, considering economic and regulatory environments. The analytical framework modeled segmentation across product types, applications, packaging formats, and customer types. Compound Annual Growth Rates were derived from historical data and projected dietary shifts. Key forecast inputs included almond harvest yields and gluten-free product innovation.
Sensitivities concentrate around unforeseen climatic events impacting almond harvests and significant shifts in global trade policies. Forecasts reflect assumptions documented at the time of publication. Material shifts in major agricultural yields or food safety regulations would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Boysenberry Extract Market
Ingredients
Pet Food Premix Market
Ingredients
Global Natural Gum Market
Ingredients
Low Calorie Oil Market
Ingredients
Global Malt Ingredients Market
Ingredients
South America Clean Ingredients Market
Ingredients
Global Tomato Powder Market
Ingredients
North America Dairy Ingredients Market
Ingredients
China Corn Glucose Market
Ingredients
Oyster Peptide Market
Ingredients
Philippines Edible Oils & Fats Market
Ingredients
Bulk Food Ingredients Market
Ingredients
Cold Pressed Oil Market
Ingredients
High Oleic Oil Market
Ingredients
Brazil Corn Syrup Market
Ingredients
Africa Plant Protein Ingredients Market