
 Instant Cake Gel Market | 2026-2036
Instant Cake Gel Market Size, Share, and Industry Trends Forecast 2026-2036
Instant Cake Gel Market Outlook
Aftermarket formulation services is fragmenting as bakeries shift from commodity shortening to performance-optimized gel systems. Puratos Group leverages its global baking science network to sustain technical advisory relationships with mid-size commercial bakeries. AB Mauri anchors European supply through specialized emulsifier manufacturing, while Kerry Group competes on clean-label positioning across Asian markets.
Instant cake gel is a pre-hydrated emulsifier system containing monoglycerides, polyglycerol esters, and hydrocolloids, typically delivered at 60-70% active content to aerate batters and stabilize fat-water interfaces during mechanical mixing. The product enables consistent cake volume, crumb structure, and shelf-life extension in high-speed industrial production. Ready-to-use gel formats command premium positioning among commercial bakeries seeking labor reduction, while powdered variants occupy cost-sensitive segments in emerging markets. Liquid formulations lead in food manufacturer channels where automated dosing systems predominate.
FDA food additive regulations under 21 CFR govern emulsifier safety thresholds in US applications, while EFSA evaluates polyglycerol ester daily intake limits under EU food law. India's FSSAI enforces labeling requirements for bakery improvers that influence gel product positioning. Stakeholders must monitor evolving clean-label definitions across these jurisdictions to align formulation investments with shifting compliance boundaries and purchasing criteria.
Market Dynamics
Commercial bakeries across Southeast Asia are abandoning commodity shortening in favor of performance-optimized emulsifier gel systems, compressing margins for traditional fat suppliers while elevating technical formulation partners.
Growth Catalysts
- Clean-label ingredient mandates:China's SAMR food additive standards are accelerating reformulation investments as manufacturers eliminate synthetic emulsifiers from retail-facing cake products.
- Quick-service bakery expansion:Indonesia's quick-service bakery chains require consistent batter performance across high-throughput production lines, creating pull for pre-hydrated gel systems.
- Labor cost escalation:India's organized bakery sector faces wage inflation that makes ready-to-use gel formats economically compelling versus manual shortening measurement.
Market Restraints
- Palm oil price volatility:Monoglyceride feedstock costs fluctuate with Malaysian palm oil futures, squeezing gel manufacturer margins unpredictably.
- Emulsifier supply concentration:Polyglycerol ester production clusters in select European chemical parks, exposing buyers to single-source risk during logistics disruptions.
- Clean-label technical ceiling:Natural hydrocolloid alternatives fail to match synthetic stabilizer performance in high-ratio cake formulations, limiting premium positioning.
Strategic Opportunities
- Vietnam bakery modernization:Foreign direct investment in Ho Chi Minh City industrial baking facilities outpaces local emulsifier supply capability.
- Plant-based cake applications:Egg replacement formulations in vegan bakery segments demand specialized aeration gels with novel protein-hydrocolloid synergy.
- FSSAI labeling simplification:India's proposed consolidated bakery improver disclosure rules would reduce compliance burden for multi-SKU gel portfolios.
Industry Challenges
- Emulsification chemistry expertise gap:Commercial bakery technicians lack training in gel system troubleshooting versus familiar shortening handling.
- Legacy equipment incompatibility:Automated dosing hardware in older Malaysian production lines requires retrofitting for high-viscosity gel pumping.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Instant Cake Gel Market |
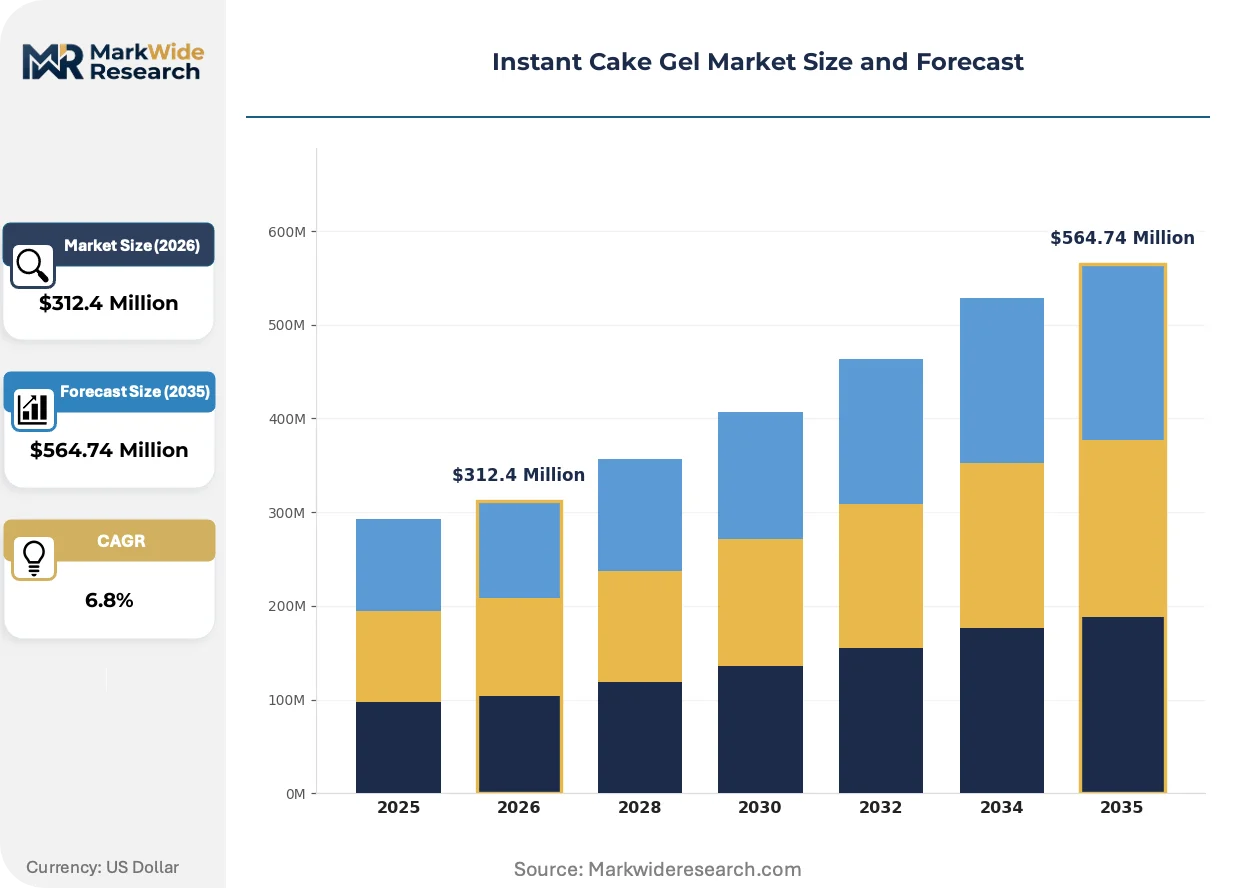
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ready-to-Use, Powdered, Liquid, Gel-based End User: Home Bakers, Commercial Bakeries, Restaurants, Food Manufacturers Flavor Profile: Vanilla, Chocolate, Strawberry, Citrus Packaging Type: Sachets, Bottles, Tubs, Pouches |
| Companies Covered | AB Mauri, Puratos Group, Ingredion, Dawn Foods, Kerry Group, Bakels Group, Corbion, Lasenor Emul, Vintop Products Private Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Instant Cake Gel Market Strategic Shifts
Formulation science and regulatory precision are converging to redefine competitive advantage, with technical service capabilities separating sustainable suppliers from commodity traders.
Enzyme-modified emulsifier gels with targeted lipase treatment are rendering obsolete conventional distilled monoglyceride systems in sponge cake production. Industrial bakeries in Thailand and the Philippines are adopting these enzymatic variants for superior crumb softness retention. The technology is rendering obsolete decade-old emulsifier specifications locked into multinational bakery chain supply agreements.
REACH registration requirements for polyglycerol ester imports are tightening documentation burdens for Asian gel manufacturers serving European food manufacturers. EFSA's ongoing re-evaluation of emulsifier acceptable daily intake limits is forcing proactive toxicology investments. The regulatory pressure is compressing supplier margins most severely for small-batch European artisan bakery channels.
Specification-driven procurement through centralized baking science teams is displacing traditional ingredient purchasing by commodity traders. Large Southeast Asian bakery groups now mandate gel performance guarantees tied to specific cake volume and staling rate metrics. This contractual precision is most advanced in Singapore and Malaysia, where multinational quick-service restaurant supply chains dominate volume allocation.
Instant Cake Gel Market Segmentation
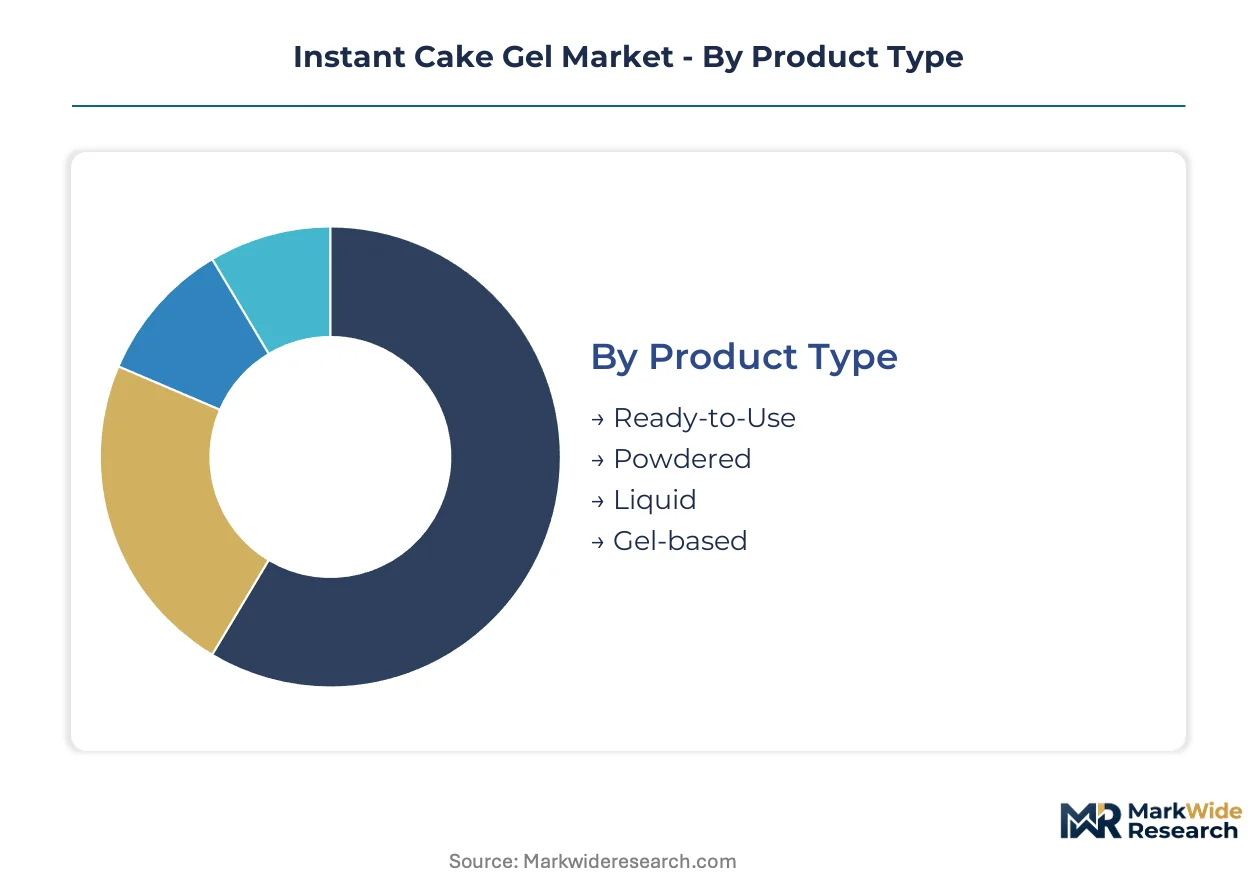
Instant cake gel segmentation reflects divergent technical requirements across production scales, from artisan home baking to automated industrial lines. Product format and packaging choices directly determine emulsifier stability, dosing precision, and labor economics for each end-use channel.
Product Type:
Mature ready-to-use formats dominate commercial throughput while emerging enzymatic variants reshape performance benchmarks in industrial applications.
- Ready-to-Use:Pre-hydrated emulsifier systems at 60-70% active content eliminate manual shortening measurement. Commercial bakeries in Indonesia's quick-service chains specify these gels for consistent aeration across high-throughput sponge cake production.
- Powdered:Dehydrated monoglyceride and hydrocolloid blends require reconstitution but offer extended ambient shelf stability. India's organized bakery sector adopts powdered variants in cost-sensitive tier-2 and tier-3 cities where cold-chain infrastructure remains limited.
- Liquid:Low-viscosity emulsifier concentrates integrate with automated dosing pumps in food manufacturer facilities. Malaysian industrial baking lines specify liquid formats for continuous batter production.
- Gel-based:High-viscosity thixotropic systems target specialty cake applications requiring precise structure control. Artisan producers in Vietnam's emerging bakery clusters experiment with gel-based formats for layered chiffon cakes.
Ready-to-Use handles the majority of throughput; Gel-based is expanding most quickly on share as enzymatic modifications penetrate Southeast Asian industrial channels.
End User:
Volume concentration sits with food manufacturers while margin capture favors technical advisory relationships with mid-size commercial bakeries.
- Home Bakers:Small-format sachet purchases drive retail channel placement. India's urban home baking communities source instant gel through e-commerce platforms for celebration cake preparation.
- Commercial Bakeries:Centralized procurement teams specify performance-guaranteed emulsifier systems. Thailand's industrial bakery groups mandate cake volume and staling rate metrics in gel supply contracts.
- Restaurants:Dessert menu consistency requirements pull pre-hydrated formats for in-house pastry production. Singapore's hotel bakery operations standardize on ready-to-use gels for banquet volume reliability.
- Food Manufacturers:Automated production lines demand liquid or pumpable gel systems with precise viscosity specifications. Philippines-based snack cake producers integrate instant gel into continuous mixing operations.
Food Manufacturers command the largest volume allocation; Commercial Bakeries deliver the steepest margin expansion through formulation service attachments.
Flavor Profile:
Application versatility separates baseline vanilla formulations from premium positioned specialty variants commanding ingredient transparency premiums.
- Vanilla:Neutral base formulations compatible with diverse cake recipes and regional taste preferences. Standard vanilla gels constitute the default specification across Southeast Asian commercial bakery procurement.
- Chocolate:Cocoa-compatible emulsifier systems optimized for fat-rich batter stability. Indonesia's chocolate cake production lines specify these variants for consistent crumb structure in high-cocoa formulations.
- Strawberry:Fruit-acid stabilized gels for cream cake and shortcake applications. Seasonal demand spikes align with strawberry harvest windows in temperate production regions.
- Citrus:Low-pH tolerant emulsifier blends for lemon and orange cake segments. China's SAMR clean-label mandates accelerate natural citrus flavor positioning in retail-facing products.
Vanilla absorbs the bulk of production volume; Citrus is climbing the fastest as acid-stable clean-label formulations gain formulation priority.
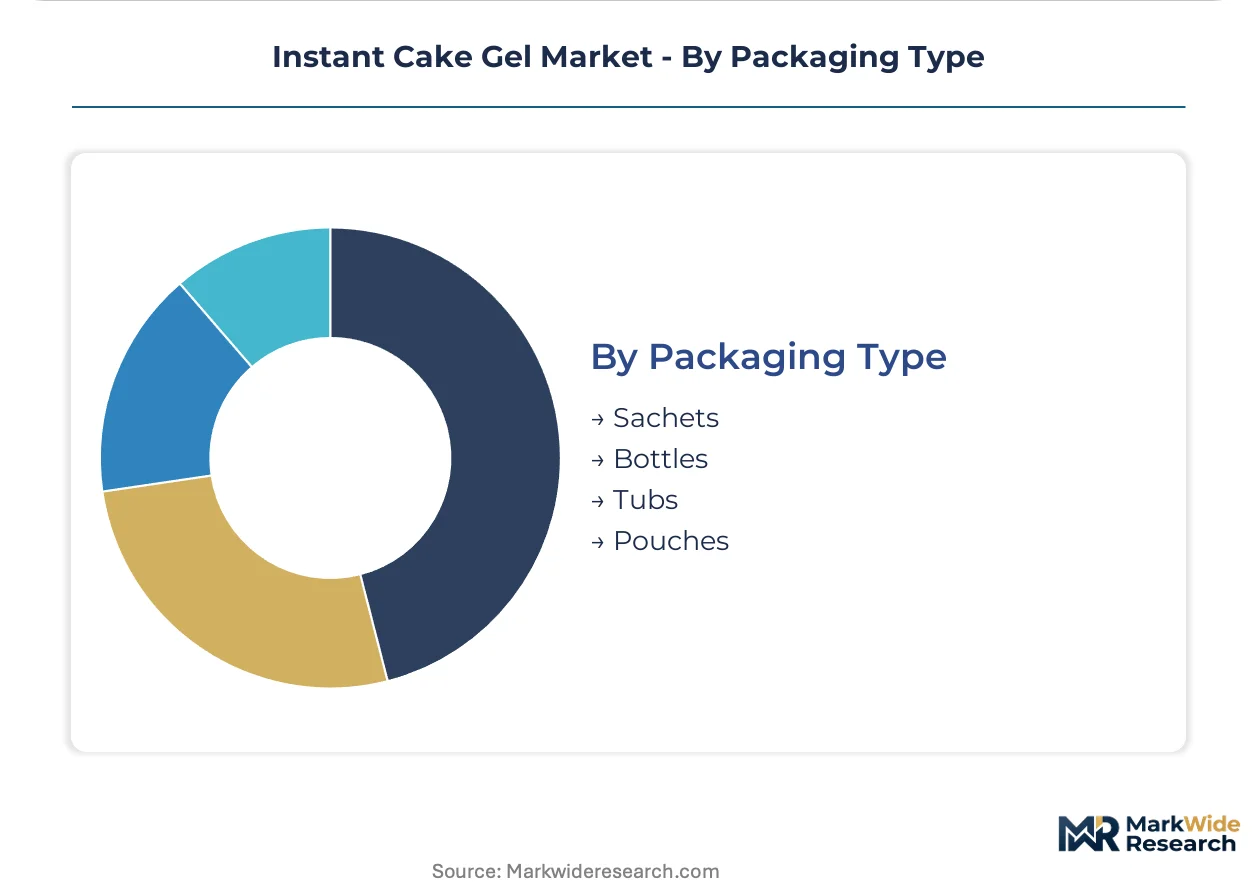
Packaging Type:
Packaging format selection traces directly to dosing automation level and batch size economics across the end-use spectrum.
- Sachets:Single-use portions eliminate measurement error for small-batch production. Home bakers and restaurant pastry stations in India prefer sachet formats for inventory rotation simplicity.
- Bottles:Pump-dispensed liquid concentrates suit semi-automated bakery operations. Mid-size Malaysian commercial bakeries specify bottle packaging for flexible batch scaling.
- Tubs:Bulk scoopable containers serve high-volume manual dosing environments. Traditional bakeries in Vietnam's Mekong Delta region rely on tub packaging for cost-per-gram efficiency.
- Pouches:Flexible film packaging with precision spouts enables controlled dispensing without dedicated pumping equipment. Emerging bakery clusters in the Philippines adopt pouches for intermediate volume production.
Tubs handle the majority of industrial throughput; Pouches are gaining share fastest as flexible packaging investments expand across Southeast Asian co-manufacturing networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesian quick-service bakery chains show the highest demand elasticity to labor-saving formats, while German artisan producers resist gel adoption due to traditional shortening preference. Chinese regulatory pressure accelerates clean-label reformulation faster than cost-sensitive Indian tier-2 markets permit.
China
SAMR food additive standards are eliminating synthetic emulsifiers from retail-facing cake products, forcing manufacturers to reformulate with natural hydrocolloid alternatives. The Yangtze River Delta industrial baking corridor in Shanghai and Suzhou leads enzymatic gel adoption for sponge cake volume consistency.
Indonesia
Quick-service bakery chains in Jakarta and Surabaya mandate pre-hydrated gel systems for standardized batter performance across high-throughput production lines. Domestic palm oil processing clusters in Sumatra create feedstock proximity advantages for monoglyceride-based gel manufacturers.
India
FSSAI labeling requirements for bakery improvers influence gel product positioning in organized retail channels. Maharashtra and Karnataka host concentrated industrial bakery capacity in Mumbai and Bangalore, where wage inflation drives ready-to-use format adoption over manual shortening measurement.
Vietnam
Foreign direct investment in Ho Chi Minh City industrial baking facilities outpaces local emulsifier supply capability, creating import dependency for performance-optimized gel systems. Mekong Delta traditional bakeries in Can Tho and Long An retain tub-packaged scoopable formats for cost-per-gram efficiency.
Thailand
Industrial bakery groups in Bangkok mandate cake volume and staling rate metrics in gel supply contracts, advancing specification-driven procurement. EFSA-aligned export requirements from Thai food manufacturers to European markets tighten REACH documentation burdens for polyglycerol ester imports.
Instant Cake Gel Market Competitive Environment
Capability concentration sits with technical formulation specialists; scale advantage sits with diversified ingredient conglomerates. The market structures around three tiers: global baking science networks, regional emulsifier manufacturers, and local distribution-focused blenders. Consolidation pressures favor acquisition of enzymatic formulation capabilities and backward integration into palm-derived feedstock processing.
Among European-based specialists, AB Mauri and Puratos Group exemplify the technical advisory archetype, anchoring supply relationships through baking science expertise rather than commodity pricing. Kerry Group occupies the diversified conglomerate position, competing across Asian markets on clean-label positioning breadth. These three represent the dominant competitive vectors: formulation science depth, geographic coverage scale, and regulatory compliance agility.
| Leading Market Players |
|---|
| AB Mauri |
| Puratos Group |
| Ingredion |
| Dawn Foods |
| Kerry Group |
| Bakels Group |
| Corbion |
| Lasenor Emul |
| Vintop Products Private Limited |
| Others |
Value Chain & Pricing Dynamics
Sumatra's palm oil processing clusters concentrate monoglyceride feedstock capacity, giving Malaysian and Indonesian gel manufacturers downstream pricing leverage over European and Indian competitors who must import base emulsifiers. This geographic concentration amplifies margin volatility when Malaysian palm oil futures swing, forcing reformulation cost absorption or pass-through negotiations with bakery procurement teams.
Pricing Analysis
Technical advisory and formulation service contracts drive lifetime value capture beyond commodity gel sales. Three-tier pricing structure across premium enzymatic, standard distilled monoglyceride, and economy powdered formats separates performance-guaranteed industrial supply from cost-sensitive artisan channels. Pricing pressure stems from clean-label reformulation investments required for China's SAMR compliance, compressing margins on legacy synthetic emulsifier portfolios. Food manufacturers exhibit lowest price sensitivity due to automated dosing system lock-in, while Vietnam's Mekong Delta traditional bakeries demand maximum cost-per-gram efficiency.
Supply Chain Analysis
Tariff exposure between ASEAN manufacturing hubs and European REACH-registered chemical parks dominates supply chain risk planning for polyglycerol ester procurement. Production gravity centers on Malaysia, Indonesia, and Germany, with enzymatic modification capabilities clustering in the Yangtze River Delta. Raw material dependencies span Malaysian palm oil derivatives, European polyglycerol feedstocks, and Indian hydrocolloid gum supplies. Single-source vulnerability in distilled monoglyceride distillation capacity creates bottleneck exposure during logistics disruptions. Distribution runs through regional baking ingredient distributors with technical service attachments, bypassing commodity traders in specification-driven procurement environments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Instant cake gel markets reward defensive moats built on regulatory entrenchment—EFSA and SAMR compliance investments create switching costs that lock bakery customers into validated supply relationships. Formulation science capabilities compound this advantage through performance-guaranteed supply contracts.
For Market Incumbents: Harden technical advisory relationships by embedding enzymatic formulation specialists within Southeast Asian industrial bakery groups facing EFSA export documentation burdens. Deepen backward integration into Sumatra palm oil fractionation to secure monoglyceride feedstock cost control against Malaysian futures volatility. Expand capacity in Ho Chi Minh City to capture foreign direct investment inflows outpacing local emulsifier supply capability.
For New Entrants and Emerging Players: Vietnam's southern industrial baking corridor offers the most penetrable geography, with import dependency creating white-space for performance-optimized gel systems. Target India's tier-2 organized bakery sector with powdered variants suited to limited cold-chain infrastructure. Pursue plant-based cake application segments where egg replacement formulations demand novel protein-hydrocolloid synergy unavailable from legacy suppliers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors enzymatic formulation specialists with REACH-registered European supply access and SAMR-compliant clean-label portfolios. Long-term viability hinges on regulatory agility across multi-jurisdictional additive standards. Acquisition targets should demonstrate backward integration into palm-derived feedstocks or captive enzymatic modification capabilities. Watch for FSSAI labeling simplification implementation as inflection signal for Indian market expansion acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Formulation Capacity Expansion | REACH-registered enzymatic gel production secures European food manufacturer access against documentation burdens. |
| Backward Integration into Palm Oil Fractionation | Captive monoglyceride feedstock supply insulates margins from Malaysian futures volatility. |
| Clean-Label Certification Investment | SAMR-compliant natural hydrocolloid positioning unlocks China's retail-facing cake product channels. |
| Technical Service Team Embedding | On-site formulation specialists lock in industrial bakery contracts through performance guarantee structures. |
| Ho Chi Minh City Distribution Hub Establishment | Local inventory positions capture Vietnamese FDI inflows outpacing domestic emulsifier supply growth. |
Study Parameters
A spread of perspectives from commercial bakery procurement directors, emulsifier formulation chemists, FSSAI regulatory consultants, and palm oil derivatives traders converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation through customs trade data, FSSAI additive registry filings, EFSA scientific opinions on emulsifier safety, and ASEAN food industry association reports. Bottom-up demand modeling from end-use segment consumption patterns triangulated against top-down supply capacity assessments across Malaysian and Indonesian processing facilities.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon, with segmentation modeling spanning product format, end-use channel, flavor profile, and packaging type dimensions alongside regulatory compliance tier. CAGRs derived from volume trajectory analysis incorporating palm oil price elasticity, bakery labor cost inflation, and clean-label reformulation investment cycles. Industry-specific forecast inputs included enzymatic adoption rates in Thai industrial bakeries and quick-service bakery chain expansion timelines in Indonesia.
Macroeconomic conditions sit as an overlay; deviation in palm oil futures volatility, ASEAN wage inflation trajectories, or EFSA daily intake limit revisions would shift the trajectory. Forecasts reflect documented assumptions about regulatory implementation timing and technology adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Organic Bread Flour Market
Bakery Products
Matcha Cookie Market
Bakery Products
Asia-Pacific Frozen Bakery Market
Bakery Products
Southeast Asia Bakery Products Market
Bakery Products
Low Calorie Bread Market
Bakery Products
Bread Crumbs Market
Bakery Products
Specialty Bakery Market
Bakery Products
Flour Mixes Market
Bakery Products
Cake Base Discs Market
Bakery Products
Baked Foods Market
Bakery Products
Malted Rye Flour Market
Bakery Products
Organic Bakery Products Market
Bakery Products
Pizza Crust Mix Market
Bakery Products
Laminated Dough Market
Bakery Products
Low-Carb Low-Fat Bread Market
Bakery Products
Europe Sweet Biscuits Market