
 On-The-Go Breakfast Products Market | 2026-2036
On-The-Go Breakfast Products Market Size, Share, and Industry Trends Forecast 2026-2036
On-The-Go Breakfast Products Market Analysis
Food scientist and packaging engineer talent scarcity is redrawing competitive boundaries for manufacturers racing to deliver shelf-stable, clean-label formats. General Mills leverages its cereal R&D infrastructure to cross-train teams on bar and biscuit innovation. Kellogg Company anchors North American production capacity through dedicated on-the-go manufacturing lines. Nestlé competes in emerging markets by adapting European formulation expertise to local taste profiles and climate-stability requirements.
On-the-go breakfast products are shelf-stable, individually packaged food and beverage items formulated for single-session consumption without preparation, typically achieving twelve-to-eighteen-month stability through controlled water activity, modified atmosphere packaging, or aseptic processing. These products serve commuters, students, and shift workers who forfeit traditional sit-down meals due to time compression. Protein shakes and breakfast biscuits command the fastest expansion as consumers prioritize macronutrient transparency and glycemic control in portable formats. Single-serve packs dominate margin pools by enabling impulse purchases and trial-sized entry points, while resealable pouches sustain premium positioning in health-conscious channels where portion management drives repeat loyalty.
The FDA governs nutrition labeling and health claim substantiation, compelling reformulation around sodium and added sugar thresholds that directly alter recipe architecture and ingredient sourcing. The USDA's National Organic Program and EPA packaging sustainability guidelines intersect with state-level extended producer responsibility laws in California and New York, multiplying compliance complexity for national distribution strategies. Stakeholders must monitor how front-of-pack scoring systems and emerging state plastic bans recalibrate both material selection and consumer communication priorities.
Market Dynamics
Commute time compression in urban corridors is fragmenting traditional breakfast occasions into micro-consumption windows, forcing manufacturers to engineer products that deliver satiety signals within 90-second consumption periods while maintaining shelf stability across temperature-variable distribution.
Growth Catalysts
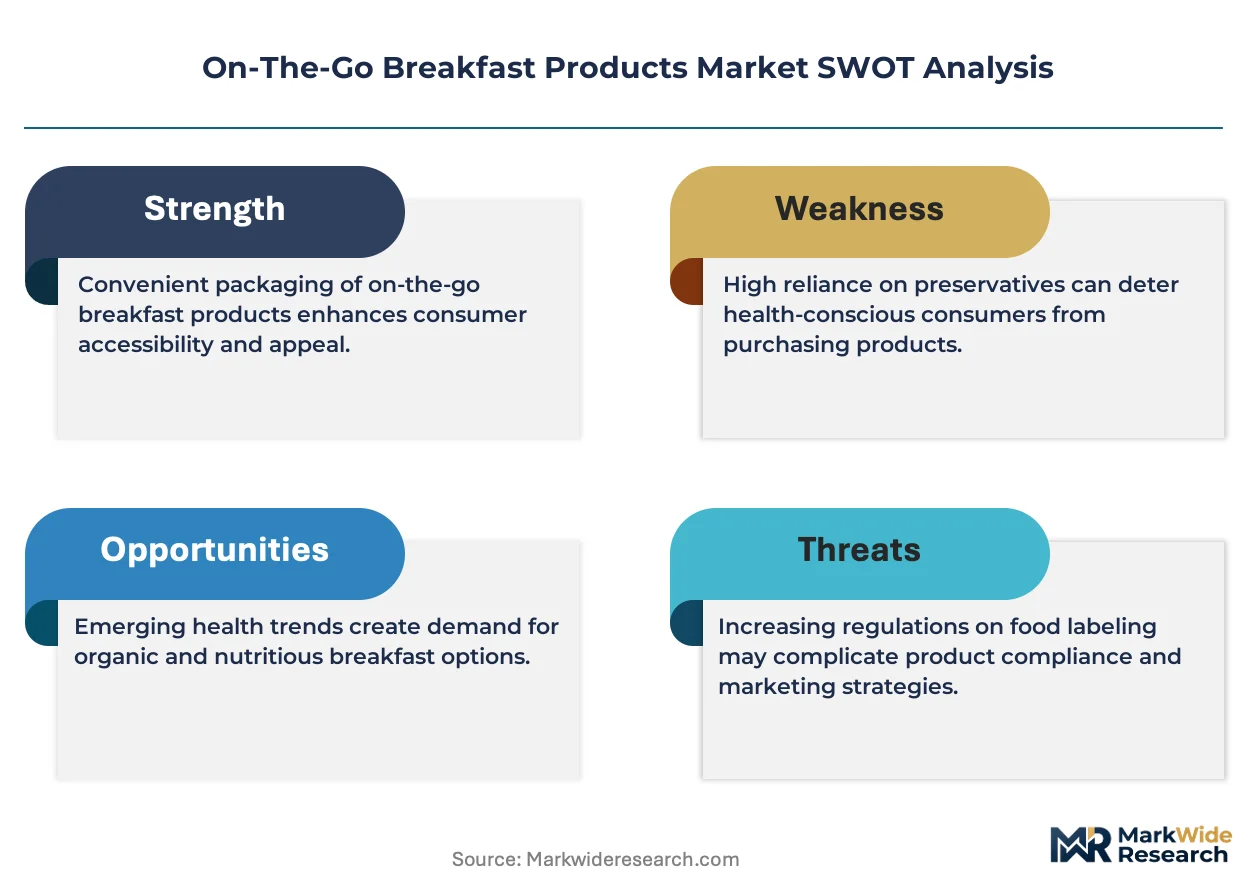
- Front-of-Pack Labeling Mandates:FDA disclosure requirements are accelerating clean-label reformulation investments, pulling capital toward natural preservation systems and away from artificial additive architectures.
- Shift Worker Density:Healthcare and logistics sectors operating 24-hour rotations generate demand for protein-dense, individually packaged items that substitute for missed traditional meal occasions.
- Aseptic Carton Technology:Advanced barrier packaging extends ambient distribution reach into convenience stores lacking refrigeration infrastructure, opening channel access previously blocked by cold-chain requirements.
Market Restraints
- Input Cost Volatility:Whey protein isolate and specialty grain prices fluctuate with dairy futures and climate-impacted harvests, compressing margin predictability for mid-tier producers.
- Supply Concentration Risk:Modified atmosphere packaging films depend on a narrow supplier base concentrated in East Asian manufacturing clusters, exposing brands to logistics disruption.
- Technical Shelf-Life Ceiling:Clean-label formulations sacrifice 3-6 months of stability versus preservative-heavy alternatives, constraining distribution radius for premium-positioned lines.
Strategic Opportunities
- Underpenetrated Secondary Cities:India's tier-2 and tier-3 urban corridors lack breakfast-format retail infrastructure, creating first-mover advantage for brands adapting European formulation expertise to FSSAI compliance frameworks.
- Regulatory Tailwind:California's extended producer responsibility laws incentivize fiber-based packaging innovation, rewarding early movers with preferred retail placement in sustainability-focused channels.
- Technology Convergence:High-pressure processing combined with edible film barriers enables ambient-stable fresh-format positioning previously restricted to refrigerated cases.
Industry Challenges
- Food Science Talent Scarcity:Formulation chemists skilled in water activity manipulation without synthetic preservatives command premium compensation, inflating R&D overhead.
- Certification Timeline Compression:USDA Organic and Non-GMO Project verification cycles extend 8-14 months, delaying product launches behind competitor windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | On-The-Go Breakfast Products Market |
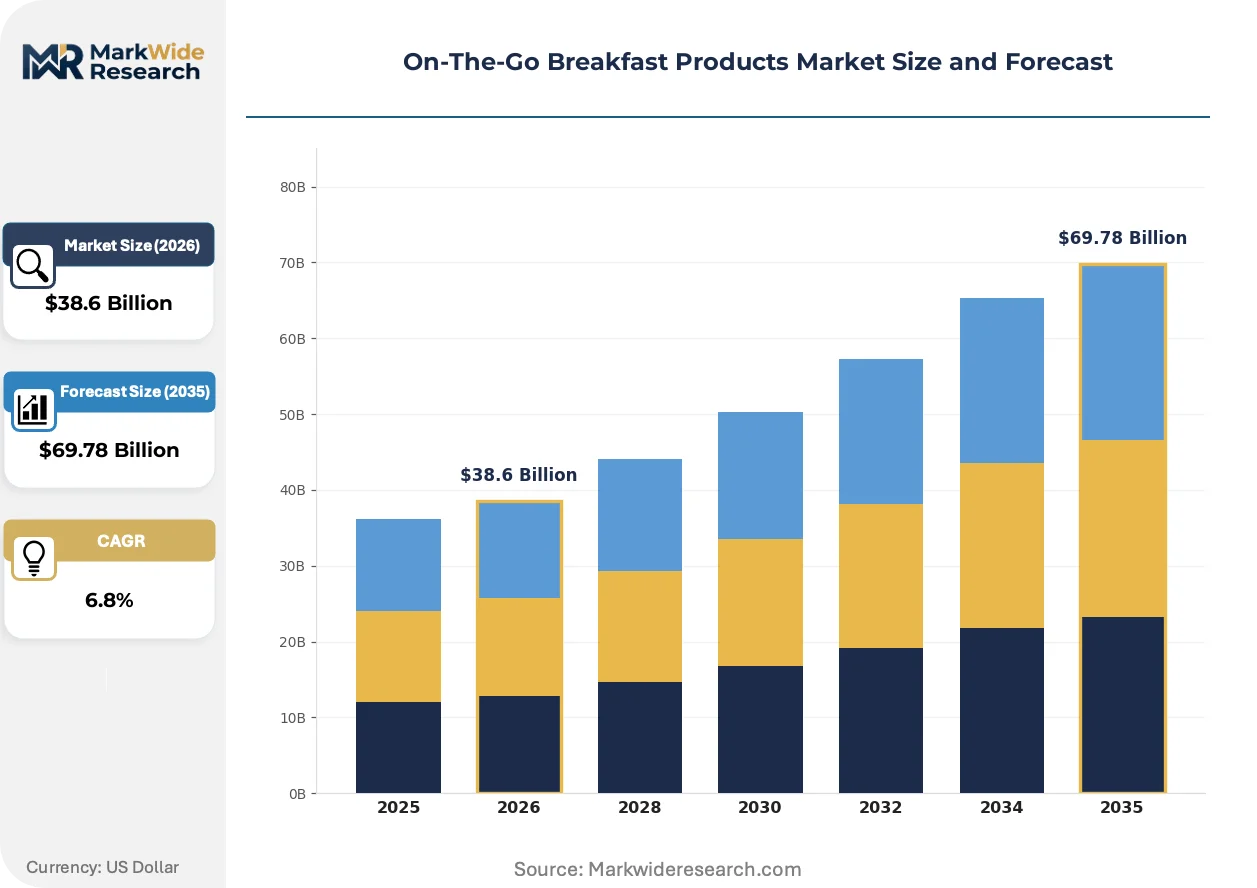
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granola Bars, Protein Shakes, Breakfast Biscuits, Ready-to-Eat Oats Delivery Mode: Online Retail, Supermarkets, Convenience Stores, Vending Machines Customer Type: Students, Working Professionals, Athletes, Health-Conscious Individuals Packaging Type: Single-Serve Packs, Multi-Pack Boxes, Resealable Pouches, Bottles |
| Companies Covered | General Mills, Kellogg Company, Nestlé, PepsiCo, Post Holdings, Mondelez International, Danone, Unilever, Hain Celestial Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
On-The-Go Breakfast Products Market Emerging Trajectories
Packaging material science and regulatory disclosure requirements are converging to redefine what constitutes an acceptable portable breakfast, with shelf-stable formats now expected to deliver nutritional transparency previously associated with fresh perimeter categories.
High-barrier metallized films paired with nitrogen flush systems are displacing conventional polyethylene structures in premium breakfast bar segments. Urban professionals seeking glycemic control now reject packaging that obscures ingredient provenance. This material shift compresses acceptable shelf-life claims from 18 months toward 12-month freshness positioning.
REACH restrictions on per- and polyfluoroalkyl substances are forcing European manufacturers to abandon grease-resistant coatings that enabled paper-based breakfast sandwich wraps. Reformulation around plant-derived barrier layers adds 8-12% to packaging unit costs. Brands serving German and French commuter rail channels are absorbing these costs to maintain single-serve format viability.
Subscription replenishment models are capturing recurring revenue from remote workers who abandoned daily commutes but retained portable consumption habits. Direct-to-consumer channels displace convenience store impulse purchases for this cohort. The United States exhibits the clearest bifurcation, with coastal metropolitan areas showing strongest subscription attachment while interior markets retain grab-and-go dominance.
On-The-Go Breakfast Products Market Segmentation
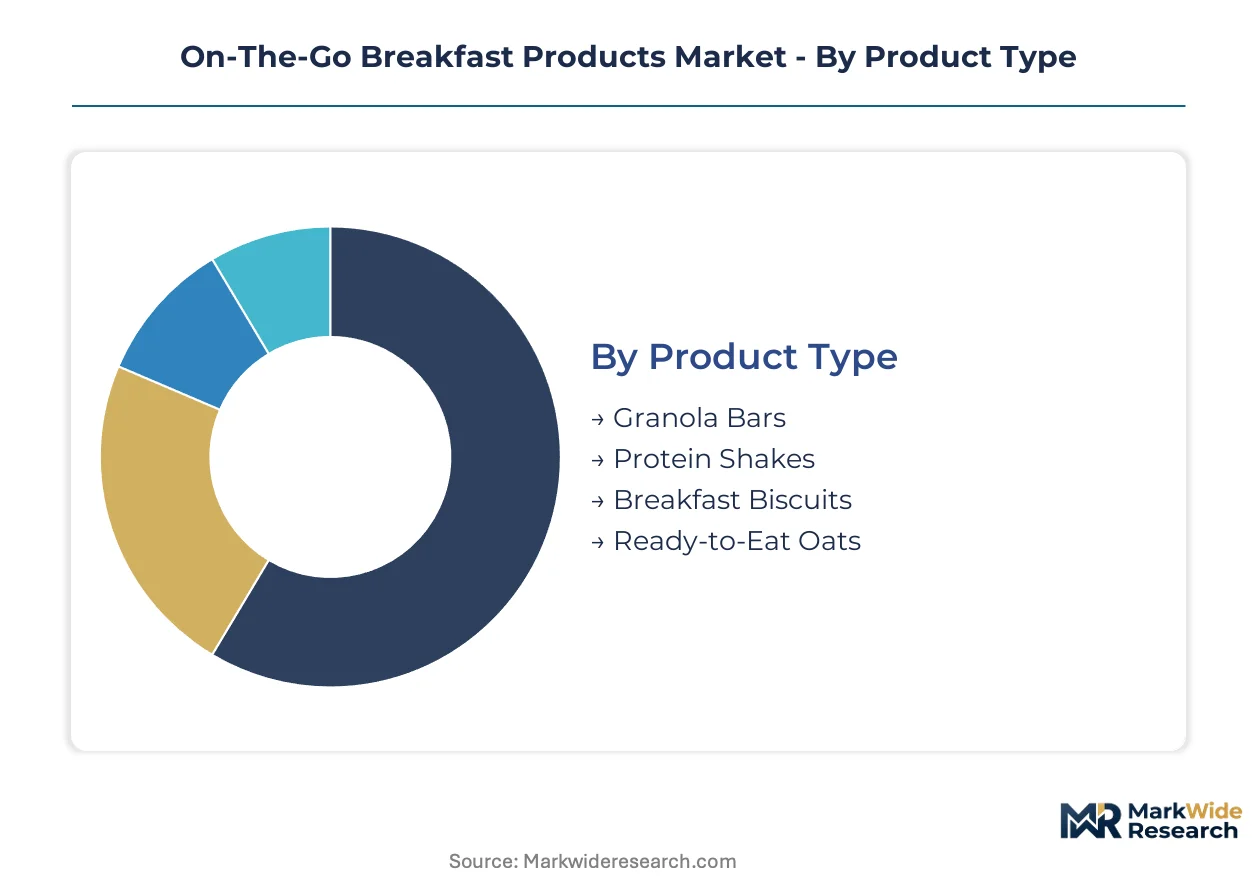
Segmentation in the on-the-go breakfast market reveals how consumption contexts override traditional demographic boundaries. Manufacturers must align formulation, packaging, and channel strategy to specific micro-occasions rather than broad consumer categories.
Product Type:
Domestic production clusters in the United States and Western Europe supply granola bars and protein shakes to export markets, while breakfast biscuits and ready-to-eat oats travel shorter distances due to moisture-sensitivity constraints.
- Granola Bars:Oat and nut-based compressed formats achieving shelf stability through controlled water activity below 0.6. Demand concentrates in United States coastal metropolitan corridors where commuter rail access supports grab-and-go purchase patterns. FDA front-of-pack labeling mandates accelerate clean-label reformulation away from artificial preservatives.
- Protein Shakes:Aseptically processed dairy or plant-based beverages delivering 15-30g protein per 330ml serving. Expansion runs fastest among healthcare shift workers in Germany and France seeking meal replacement during irregular hours. REACH restrictions on packaging coatings add 8-12% to European unit costs.
- Breakfast Biscuits:Shelf-stable baked formats with glycemic control positioning. German commuter rail channels absorb premium pricing for single-serve variants.
- Ready-to-Eat Oats:Pre-cooked grain cups requiring hot water activation. United States college campuses drive trial through vending placement.
Granola bars command the established base. The steepest expansion runs through protein shakes.
Delivery Mode:
Channel economics separate high-frequency impulse formats from planned replenishment, with margin structures dictating which product types dominate each pathway.
- Online Retail:Subscription models capturing recurring revenue from remote workers who retained portable consumption habits after abandoning daily commutes. Direct-to-consumer channels displace convenience store impulse purchases for this cohort in United States coastal metropolitan areas.
- Supermarkets:Multi-pack boxes dominate shelf space, with California and New York stores prioritizing fiber-based packaging compliance under extended producer responsibility laws.
- Convenience Stores:Single-serve packs generate impulse trial through checkout placement. Aseptic carton technology extends ambient distribution into stores lacking refrigeration infrastructure.
- Vending Machines:Temperature-stable formats with 12-month shelf life requirements. United States college campuses and healthcare facilities represent concentrated installation points.
Supermarkets anchor volume throughput. Subscription online retail is climbing the fastest.
Customer Type:
Professional constraints on morning time budgets create sharper segmentation than age or income variables, with shift patterns and commute structures determining format preferences.
- Students:Price-sensitive demand concentrated in United States college towns and urban India tier-2 cities. Vending machine access and multi-pack value positioning drive trial.
- Working Professionals:Fastest-expanding segment as urban commute compression in United States, Germany, and Japan fragments traditional breakfast into 90-second consumption windows. Protein density and glycemic transparency dominate purchase criteria.
- Athletes:Macronutrient precision requirements favor protein shakes with disclosed amino acid profiles. United States specialty retail and direct-to-consumer channels capture this premium positioning.
- Health-Conscious Individuals:Clean-label and organic certification requirements. USDA Organic and Non-GMO Project verification cycles extend 8-14 months, delaying product launches.
Working professionals represent the fastest-expanding buyer segment. Students provide the volume foundation.
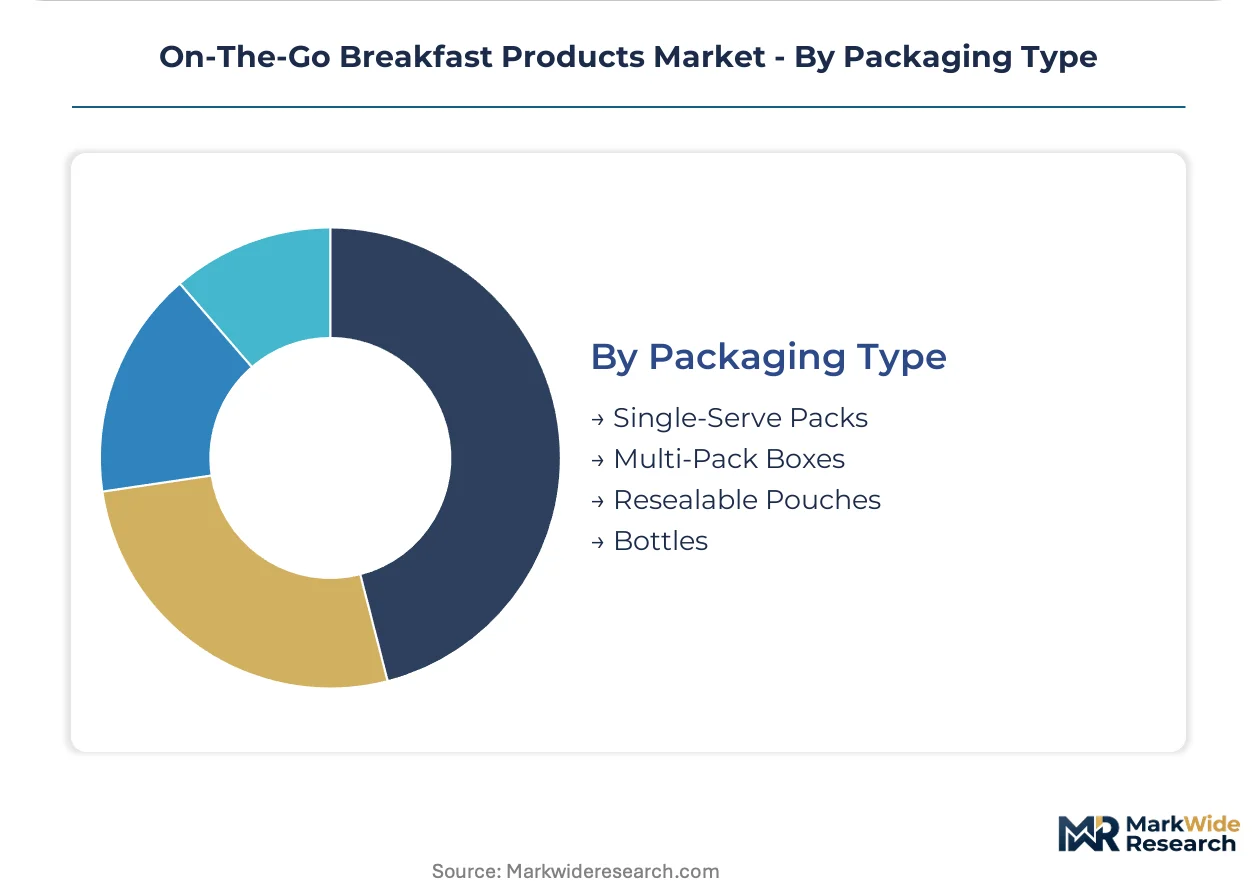
Packaging Type:
Material science investments separate premium positioning from economy tiers, with barrier properties and sustainability credentials determining channel access.
- Single-Serve Packs:Individual portion control enabling impulse purchase and trial-sized entry points. Nitrogen flush systems and high-barrier metallized films displace conventional polyethylene in premium United States and European markets.
- Multi-Pack Boxes:Economy positioning for pantry stock-up occasions. California extended producer responsibility laws incentivize fiber-based substrate innovation.
- Resealable Pouches:Premium health-channel positioning where portion management drives repeat loyalty. REACH restrictions on per- and polyfluoroalkyl substances force European manufacturers toward plant-derived barrier layers.
- Bottles:Aseptic carton and PET formats for beverage categories. Hot-fill and retort capabilities determine shelf-life extension without refrigeration.
Single-serve packs dominate margin pools. Resealable pouches are gaining share fastest in sustainability-focused channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. United States buyers prioritize protein density and glycemic transparency for compressed commute windows. German and French markets emphasize clean-label certification and sustainable packaging under REACH mandates. Indian demand clusters in tier-2 urban corridors where breakfast-format retail infrastructure remains underdeveloped.
United States
Coastal metropolitan corridors drive grab-and-go purchase density through commuter rail access and convenience store penetration. FDA front-of-pack labeling mandates accelerate reformulation investments toward natural preservation systems. Chicago and New York manufacturing clusters host dedicated on-the-go production lines serving national distribution networks.
Germany
Commuter rail channels absorb premium pricing for single-serve breakfast biscuits with glycemic control positioning. REACH restrictions on per- and polyfluoroalkyl substances force migration toward plant-derived barrier layers, adding 8-12% to packaging unit costs. Bavaria-based formulation facilities adapt European expertise to export markets requiring climate-stability engineering.
France
Healthcare and logistics shift workers generate demand for protein-dense meal replacement during irregular hours. EFSA disclosure requirements intersect with national nutrition scoring systems to recalibrate consumer communication priorities. Paris basin production capacity focuses on aseptic carton technology for ambient distribution into convenience channels lacking refrigeration.
India
Tier-2 and tier-3 urban corridors present first-mover opportunity for brands adapting European formulation expertise to FSSAI compliance frameworks. Price-sensitive student demand concentrates in college towns where vending machine access drives trial. Maharashtra and Karnataka industrial zones develop domestic manufacturing to reduce import dependency for shelf-stable formats.
Japan
Urban commute compression fragments traditional breakfast into 90-second consumption windows favoring portion-controlled formats. METI packaging sustainability guidelines incentivize fiber-based substrate innovation for premium health channels. Tokyo-Osaka manufacturing corridors specialize in high-barrier metallized films paired with nitrogen flush systems.
On-The-Go Breakfast Products Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with multinational food conglomerates leveraging cereal R&D infrastructure and beverage processing capabilities against mid-tier clean-label challengers. The competitive structure rewards backward integration into specialty grain sourcing and captive aseptic processing capacity. Three archetypes dominate: diversified packaged food giants with cross-category breakfast platforms, dairy and nutrition specialists with protein formulation depth, and emerging clean-label insurgents competing on certification velocity. Capacity expansion and portfolio diversification represent the dominant competitive moves, as incumbents acquire regional brands to fill geographic or format gaps.
Within the diversified packaged food tier, General Mills, Kellogg Company, and Nestlé occupy positions that exemplify scale-driven competitive dynamics. General Mills leverages established cereal R&D infrastructure to cross-train technical teams on bar and biscuit innovation. Kellogg Company anchors North American production capacity through manufacturing lines dedicated exclusively to on-the-go formats. Nestlé competes in emerging markets by adapting European formulation expertise to local taste profiles and climate-stability requirements, representing the geographic diversification archetype.
| Leading Market Players |
|---|
| General Mills |
| Kellogg Company |
| Nestlé |
| PepsiCo |
| Post Holdings |
| Mondelez International |
| Danone |
| Unilever |
| Hain Celestial Group |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts for whey protein isolate and specialty grain supply lock in both raw material access and margin visibility for North American manufacturers navigating dairy futures volatility and climate-impacted harvest cycles. These arrangements insulate tier-one producers from spot-market spikes while constraining pricing flexibility for mid-tier competitors lacking backward integration into ingredient sourcing.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement for protein inputs and specialty grains, with price differentiation resting on certification grade and volume scale. Three-tier pricing structure across premium, standard, and economy levels separates USDA Organic-positioned lines from conventional formulations and private-label economy tiers. Cost compression in the standard tier is intensifying because clean-label reformulation sacrifices 3-6 months of shelf stability, forcing shorter distribution radii and higher logistics overhead. Students in United States college towns and urban India tier-2 cities exhibit highest price sensitivity, while German commuter rail channels absorb premium pricing for glycemic-control-positioned breakfast biscuits with minimal volume elasticity.
Supply Chain Analysis
Strategic stockpile preferences for modified atmosphere packaging films and nitrogen flush system components predominate over just-in-time approaches, given the narrow supplier base concentrated in East Asian manufacturing clusters. Geographic supply concentration centers on China, South Korea, and Japan for high-barrier metallized films, while domestic production clusters in the United States and Western Europe handle final formulation and packaging assembly. Raw material dependencies include whey protein isolate, oat and nut inputs, and plant-derived barrier layers forced by REACH restrictions. Single-source vulnerability in packaging film supply exposes brands to logistics disruption from regional port congestion. Distribution runs through national retail networks anchored by Chicago and New York manufacturing corridors, with direct-to-consumer channels displacing convenience store volumes in coastal metropolitan areas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: FDA front-of-pack labeling mandates and extended producer responsibility laws in California and New York create compliance barriers that favor incumbents with established verification cycles and reformulation infrastructure.
For Market Incumbents: Shield market position by deepening captive supply of specialty grains through backward integration into agricultural sourcing partnerships in the United States Midwest. Accelerate USDA Organic and Non-GMO Project certification velocity to outpace clean-label insurgents, as verification cycles extending 8-14 months currently delay competitive product launches. Prioritize channel control in convenience store networks through aseptic carton technology deployment that extends ambient distribution reach into refrigeration-constrained locations.
For New Entrants and Emerging Players: Anchor in India's tier-2 and tier-3 urban corridors where breakfast-format retail infrastructure remains underdeveloped and first-mover advantage awaits brands adapting European formulation expertise to FSSAI compliance frameworks. Target price-sensitive student demand through vending machine placement in Maharashtra and Karnataka college towns, leveraging domestic manufacturing zones to reduce import dependency. Pursue a direct-to-consumer subscription go-to-market angle for remote workers in United States coastal metropolitan areas who retained portable consumption habits post-commute.
For Investors and Strategic Acquirers: Formulation-technology specialists with water activity manipulation capabilities and clean-label preservation expertise represent the most defensible acquisition target archetype, given food science talent scarcity that commands premium compensation and inflates R&D overhead. Frame long-term viability around five-to-ten-year windows where regulatory disclosure requirements and packaging sustainability mandates continue concentrating market share among compliant scale players. Monitor California extended producer responsibility law enforcement intensity as the critical inflection signal for fiber-based packaging innovation returns and preferred retail placement access.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Investment | Natural preservation systems displace artificial additives under FDA front-of-pack mandates. |
| Fiber-Based Packaging Innovation | California extended producer responsibility laws reward early movers with preferred channel placement. |
| Aseptic Processing Capacity Expansion | Ambient distribution reach extends into convenience stores lacking refrigeration infrastructure. |
| Direct-to-Consumer Subscription Launch | Recurring revenue capture from remote workers displaces convenience store impulse purchases. |
| Backward Integration into Specialty Grain Sourcing | Captive supply insulates margin predictability from climate-impacted harvest volatility. |
Methodological Framework
Operator-level perspectives from brand managers, category buyers at retailers, channel sales heads, and supply planners anchored the qualitative base for this analysis. Primary interviews with food scientists and packaging engineers at diversified packaged food manufacturers, dairy and nutrition specialists, and emerging clean-label insurgents combined with secondary validation from FDA filing databases, USDA National Organic Program records, Nielsen retail audit data, and SEC 10-K disclosures. Bottom-up volume triangulation across product type, delivery mode, customer type, and packaging type segmentation dimensions converged with top-down market sizing checks.
Sensitivity analysis around input cost volatility scenarios and regulatory timeline compression informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, delivery mode, customer type, packaging type, and regional regulatory cluster. CAGRs were derived from trend extrapolation adjusted for structural shift impacts. Forecast inputs incorporated shift worker density patterns in healthcare and logistics sectors, aseptic carton technology penetration rates, and front-of-pack labeling compliance investment cycles.
Material uncertainties — whey protein isolate price spikes, modified atmosphere packaging film supply disruptions, and certification timeline extensions — sit outside the modeled envelope. Forecasts reflect assumptions about urban commute compression persistence, clean-label preference durability, and regulatory enforcement intensity that could revise trajectory materially. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Healthy Biscuits Market
Bakery Products
United States Bread Market
Bakery Products
Global Cakes Market
Bakery Products
Specialty Frozen Bakery Market
Bakery Products
Bakery Flavors Market
Bakery Products
Baked Foods Market
Bakery Products
Bakery Improvers Market
Bakery Products
Cake Concentrate Market
Bakery Products
Matcha Cookie Market
Bakery Products
Shelf-Stable Dough Market
Bakery Products
Cookies Market
Bakery Products
Ice Cream Cake Market
Bakery Products
Bakery Emulsions Market
Bakery Products
Pastry Premixes Market
Bakery Products
Bakery Premixes Market
Bakery Products
Frozen Bakery Products Market