
 Flip Lip Bags Market | 2026-2036
Flip Lip Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Flip Lip Bags Market Foresight
Small-format food brands is bifurcating from bulk industrial buyers as the dominant growth archetype in flip lip bag procurement. Emerald Packaging leverages its West Coast manufacturing footprint to supply artisan food producers with custom-printed resealable formats. Mondi Group anchors European demand through its kraft-paper hybrid laminates that target bakery and snack applications. Rutan Poly Industries competes on short-run flexibility, serving regional co-packers with polyethylene-based stock and semi-custom options.
Flip lip bags are flexible pouches featuring a hinged closure lip that enables repeated opening and resealing without auxiliary fasteners, typically constructed from multi-layer polyethylene or polypropylene laminates ranging from 2 to 6 mils in thickness, with oxygen transmission rates below 0.5 cc per square meter per day for barrier-grade specifications. Their primary commercial purpose centers on extending shelf stability for moisture-sensitive or aromatic products while delivering consumer convenience in single-hand operation. Polyethylene formulations dominate volume production due to cost efficiency and heat-seal compatibility, though biodegradable films represent the fastest-expanding material category as brand owners respond to retailer sustainability scorecards. Stand-up pouches capture the largest margin pool among packaging styles because of premium shelf presence and higher barrier complexity, while flat bags remain the mature, high-volume workhorse for frozen and dried goods.
FDA food-contact regulations govern material migration limits for U.S.-destined flip lip bags, while EU REACH and the Packaging and Packaging Waste Regulation enforce recyclability targets and restricted substance lists across European supply chains. These frameworks compel converters to validate laminate layer separability or shift to mono-material constructions to maintain market access. Stakeholders must monitor evolving extended producer responsibility schemes and decide whether to absorb compliance costs or pass them through premium positioning before certification requirements harden.
Market Dynamics
Food & Beverage processors are expanding flip lip bag adoption for portion-controlled packaging. The EU Packaging and Packaging Waste Regulation is tightening recyclability mandates across member states. Demand concentrates in Germany, where bakery and confectionery brands prioritize resealable flexible formats.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Tightening recyclability mandates across member states compel converters to validate laminate layer separability or shift to mono-material constructions. This regulatory pressure accelerates innovation in separable barrier films.
- Portion-controlled packaging demand:Food & Beverage processors are expanding flip lip bag adoption for single-serve and controlled-portion applications. Bakery and snack brands drive volume in resealable flexible formats.
- Biodegradable films:Brand owners respond to retailer sustainability scorecards by sourcing compostable alternatives to polyethylene laminates. This material shift opens new supplier relationships and certification pathways.
Market Restraints
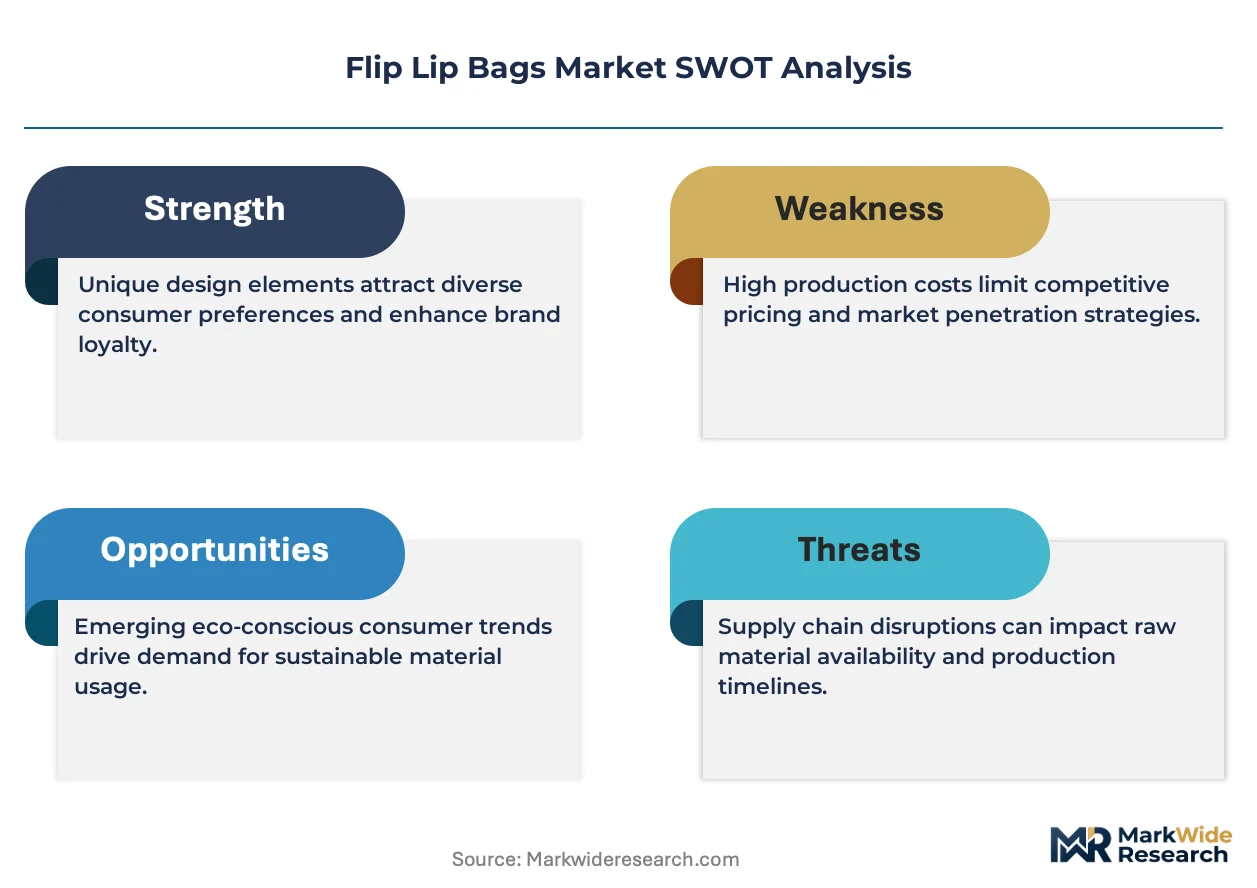
- Resin cost volatility:Polyethylene and polypropylene input prices fluctuate with crude oil derivatives and regional petrochemical capacity. Converters face margin compression when pass-through clauses lag spot market moves.
- Mono-material technical limitations:Oxygen transmission rates in single-substrate films struggle to match multi-layer barrier performance. High-moisture or aromatic applications remain captive to complex laminates.
- Extended producer responsibility schemes:Emerging EPR frameworks in EU member states impose downstream cost recovery obligations. Small converters lack capital to fund collection infrastructure or compliance systems.
Strategic Opportunities
- Kraft-paper hybrid laminates:Bakery and snack applications in Germany and France show strong pull for fiber-based resealable formats. Mondi Group anchors this demand through scalable production.
- Short-run flexibility services:Regional co-packers and artisan food producers require semi-custom polyethylene-based stock with rapid turnaround. Rutan Poly Industries competes in this whitespace.
- FDA food-contact compliance positioning:U.S.-destined flip lip bags require validated migration limits. Converters with pre-certified material libraries capture cross-border supply contracts.
Industry Challenges
- Barrier-grade certification timelines:Validating oxygen transmission rates below 0.5 cc per square meter per day requires extended laboratory testing. Product development cycles stretch when reformulating for mono-material compliance.
- Laminate layer separability validation:EU recyclability mandates demand proof of mechanical or chemical separation. Converters must rebuild quality systems around separability testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flip Lip Bags Market |
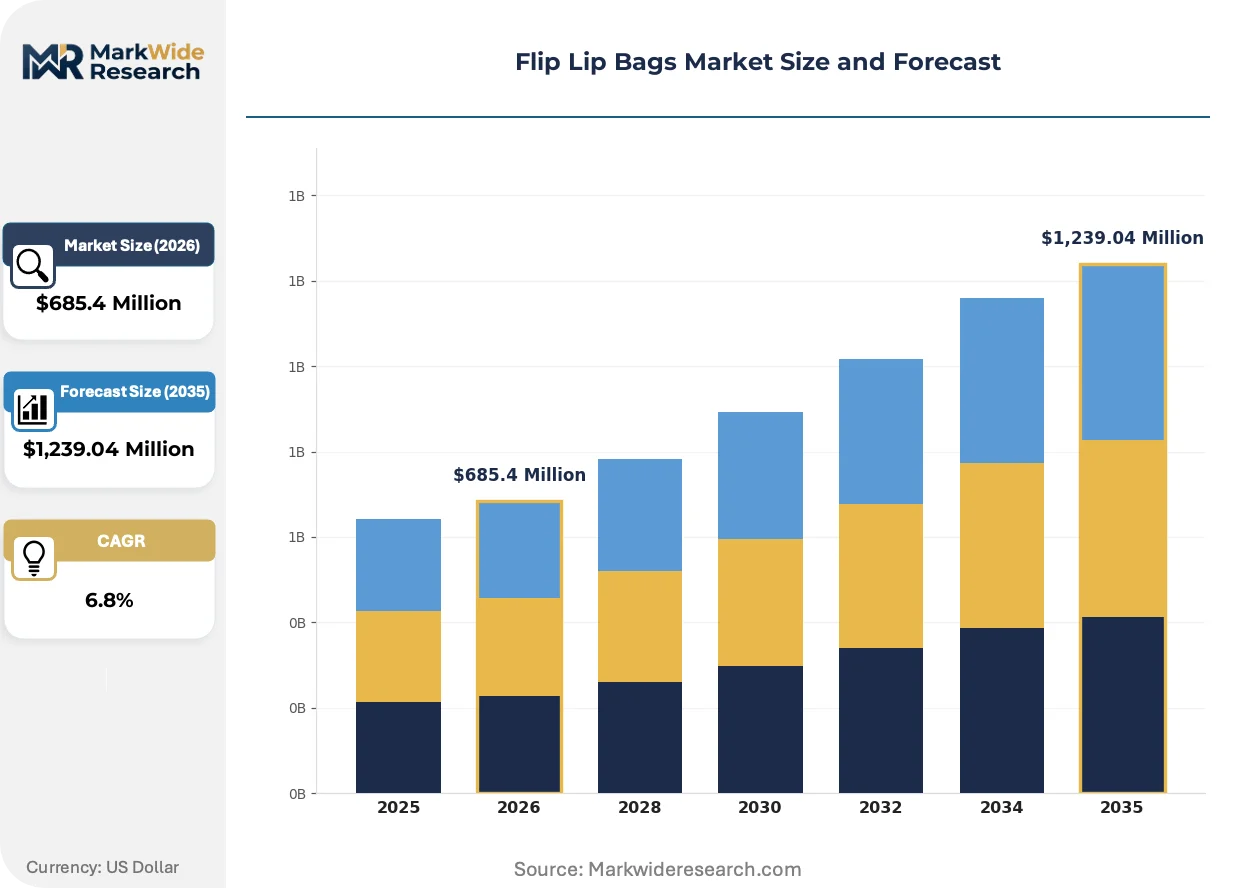
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyethylene, Polypropylene, Kraft Paper, Foil, Laminates, Biodegradable Films End Use Industry: Food & Beverage, Personal Care, Household Products, Agriculture, Pharmaceuticals, Pet Care Closure Type: Zip Lock, Press Seal, Heat Seal, Tin Tie, Slide Lock, Spout Packaging Style: Stand-Up Pouches, Flat Bags, Gusseted Bags, Side Seal Bags, Quad Seal Bags, Doypack |
| Companies Covered | Emerald Packaging, Rutan Poly Industries, Ampac Holdings, Mondi Group, EZ Products, International Plastics, North Coast Plastics, Dana Poly, Confidential Data, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flip Lip Bags Market Shifts & Advancements
Material science and regulatory compliance are actively reshaping competitive positioning in flip lip bag manufacturing. Converters must now engineer for simultaneous barrier performance and end-of-life separability.
Mono-material polyethylene formulations are bifurcating from traditional multi-layer laminates as the dominant technical pathway. Bakery and snack brands in Germany and France are adopting these separable films at accelerated pace to preempt EU Packaging and Packaging Waste Regulation enforcement. This shift is compressing demand for legacy aluminum-oxide barrier layers while elevating converter investment in co-extrusion equipment.
REACH restricted substance lists and EU Green Deal circularity targets are tightening material specifications across European supply chains. Industrial consequence includes mandatory recyclability validation and layer separability documentation for market access. High-barrier applications in frozen and dried goods face the steepest compliance burden, with converters reformulating around ethylene-vinyl alcohol alternatives.
Small-format food brands are consolidating procurement around regional co-packers with custom-printing capabilities. Artisan producers displace bulk industrial buyers as the fastest-expanding customer segment for resealable flexible formats. This pattern concentrates in California and Pacific Northwest clusters where West Coast manufacturing footprints enable rapid sample-to-production cycles.
Flip Lip Bags Market Segmentation
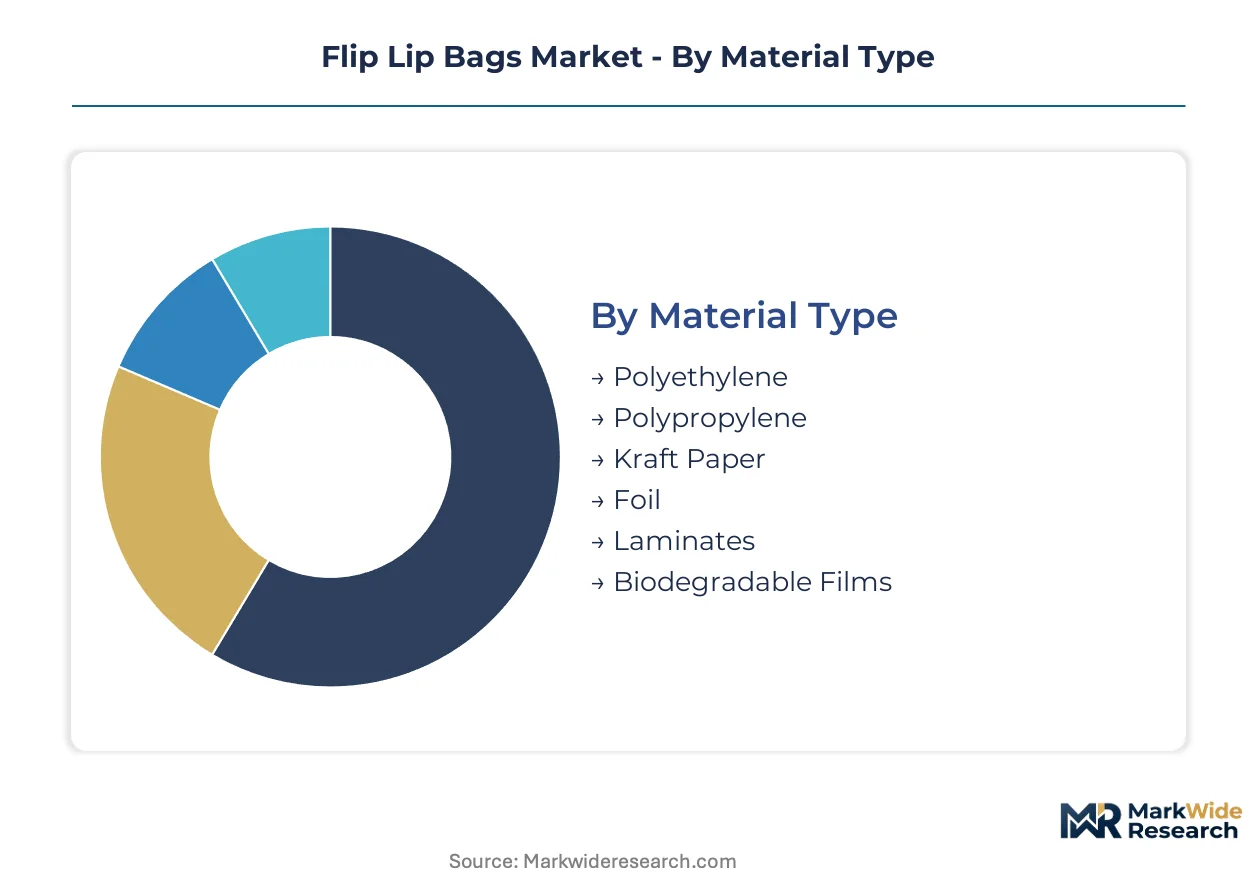
Flip lip bag procurement patterns diverge sharply across material grades and closure mechanisms, with sustainability mandates and shelf-life requirements driving distinct specification clusters. Converters must align production capabilities with the technical demands of each segment to capture margin in a tightening regulatory environment.
Material Type:
Polyethylene formulations dominate domestic production volumes across North American and European converter networks, while biodegradable films and kraft-paper hybrids increasingly anchor export-led demand from sustainability-focused brand owners.
- Polyethylene:Multi-layer low-density and linear low-density formulations deliver oxygen transmission rates below 0.5 cc per square meter per day through co-extrusion. Bakery and frozen food processors in Germany specify these for cost-efficient barrier performance under EU Packaging and Packaging Waste Regulation timelines.
- Biodegradable Films:Polylactic acid and cellulose-based compostable substrates address retailer sustainability scorecards in France and California. These materials command premium positioning but face technical constraints in high-moisture applications where barrier performance degrades.
- Polypropylene:Oriented and cast films offer superior clarity and stiffness for retail display applications.
- Kraft Paper:Fiber-based substrates with polymer windows target bakery and snack segments seeking plastic reduction narratives.
- Foil:Aluminum-laminated structures provide maximum barrier for aromatic or oxygen-sensitive contents.
- Laminates:Complex multi-substrate constructions remain standard for frozen and dried goods requiring extended shelf stability.
Polyethylene holds the largest share; momentum sits with biodegradable films.
End Use Industry:
Application concentration varies by margin profile, with pharmaceutical and personal care segments demanding validated migration compliance while food processors drive absolute volume scale.
- Food & Beverage:Portion-controlled packaging for snacks, confectionery, and frozen goods generates the highest procurement frequency. German bakery brands and U.S. artisan producers specify resealable formats for repeat-purchase convenience.
- Personal Care:Wipes, cotton pads, and travel-size toiletries require moisture retention and single-hand operability. European Union REACH compliance elevates material certification costs for this segment.
- Household Products:Cleaning wipes and laundry pods utilize stand-up formats with robust closure integrity.
- Agriculture:Seed and fertilizer packaging prioritizes UV resistance and extended outdoor durability.
- Pharmaceuticals:FDA food-contact validation governs U.S. market entry for medical device and supplement packaging.
- Pet Care:Treats and kibble applications mirror food-grade specifications with odor-containment requirements.
Food & Beverage generates the dominant revenue base; personal care climbs the fastest on premium positioning.
Closure Type:
Mechanism selection tracks price tier and reseal frequency requirements, with press seal and zip lock variants commanding distinct tooling investments at converter level.
- Zip Lock:Interlocking plastic tracks enable hundreds of open-close cycles without degradation. Snack brands in the Pacific Northwest cluster specify these for premium positioning.
- Press Seal:Finger-pressure adhesion suits lower-frequency reseal applications at reduced material cost. European private-label producers favor this mechanism for economy-tier positioning.
- Heat Seal:Permanent closure for single-use or tamper-evident requirements.
- Tin Tie:Metal wire closure for coffee and bakery segments seeking heritage aesthetic.
- Slide Lock:Plastic slider mechanism for enhanced consumer convenience in large-format bags.
- Spout:Dispensing closure for liquids and pourable solids in food and household applications.
Press seal captures the highest unit volumes; zip lock gains share fastest on convenience premiums.
Packaging Style:
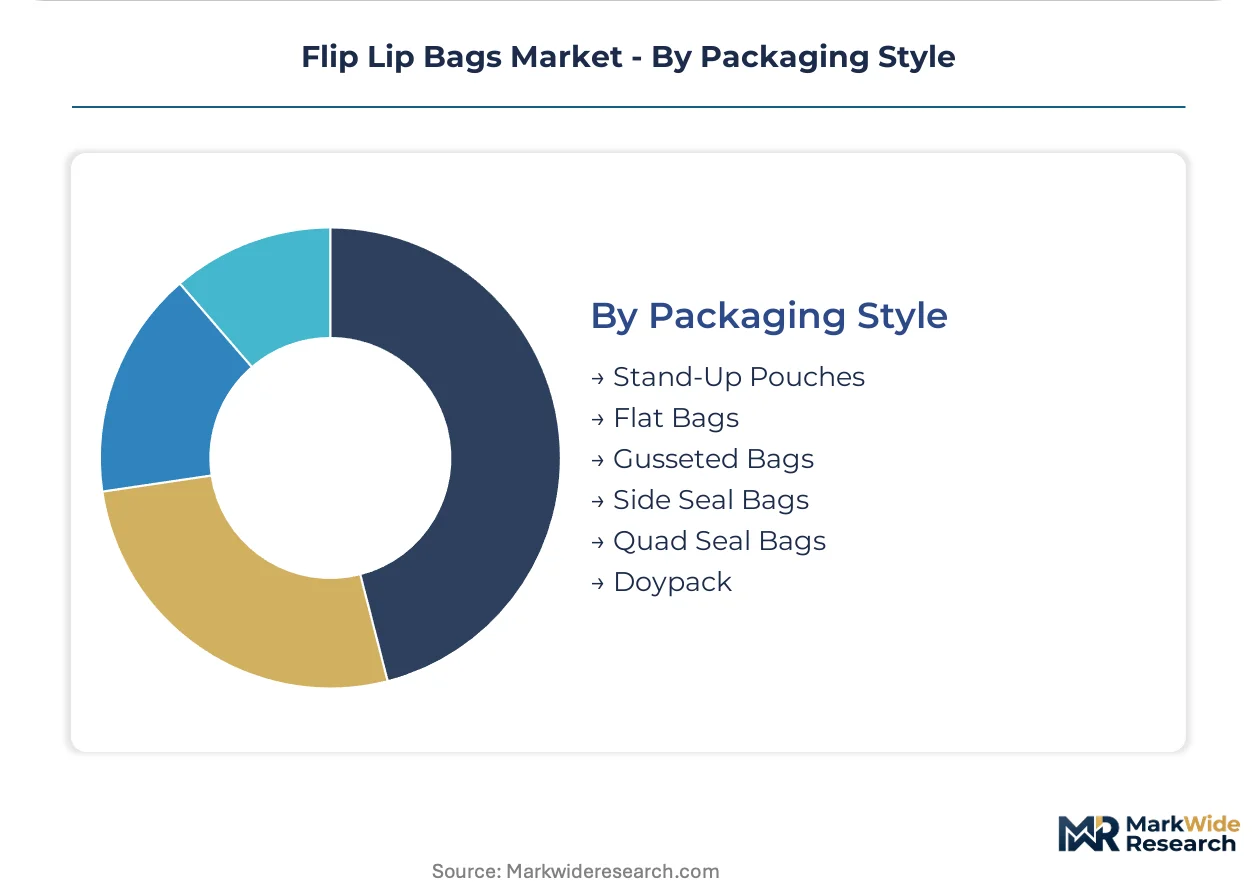
Structural format determines shelf presence and filling-line compatibility, with stand-up configurations requiring specialized forming equipment that constrains supplier selection.
- Stand-Up Pouches:Gusseted bottom construction enables vertical display and maximizes retail facings. Mondi Group and West Coast converters scale production for bakery and snack brands prioritizing premium shelf impact.
- Flat Bags:Two-seal construction dominates frozen and dried goods for cost efficiency and high-speed filling compatibility. Bulk industrial buyers in Germany specify these for commodity-scale procurement.
- Gusseted Bags:Side or bottom expansion panels increase volume capacity for bulk contents.
- Side Seal Bags:Vertical seal configuration for single-serve and sample applications.
- Quad Seal Bags:Four-corner seal structure for heavy or dense products requiring reinforced stability.
- Doypack:Pre-formed stand-up format with integrated closure for liquid and semi-liquid contents.
Flat bags retain the largest installed base; stand-up pouches show the steepest expansion trajectory on retail differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converter capacity clusters in Germany, the United States, and France, with regulatory pressure from EU REACH and FDA food-contact standards dictating material certification investments. Artisan food producers in California and bakery brands in Bavaria drive specification divergence between premium custom formats and commodity-scale procurement.
Germany
Bakery and confectionery brands in Bavaria and North Rhine-Westphalia specify resealable flexible formats for portion-controlled packaging. The EU Packaging and Packaging Waste Regulation mandates laminate layer separability validation for market access. Industrial converters in the Munich-Stuttgart corridor scale mono-material polyethylene production to preempt compliance deadlines.
United States
Artisan food producers in California and the Pacific Northwest cluster procurement around West Coast manufacturing footprints for rapid sample-to-production cycles. FDA food-contact regulations govern material migration limits for domestic and export-bound flip lip bags. Emerald Packaging leverages its regional presence to supply custom-printed resealable formats to small-format brands.
France
Retailer sustainability scorecards in Île-de-France and Auvergne-Rhône-Alpes accelerate demand for biodegradable films and kraft-paper hybrid laminates. EU REACH restricted substance lists tighten material specifications across national supply chains. Mondi Group anchors European demand through scalable production of fiber-based resealable formats targeting bakery applications.
China
Export-oriented converters in the Yangtze River Delta and Pearl River Delta supply polyethylene-based stock to North American and European brand owners. GB standards and MIIT directives shape domestic material specifications, though international compliance drives laminate reformulation. Regional co-packers source semi-custom options for frozen and dried goods requiring extended shelf stability.
Canada
Health Canada and PMRA regulations align with FDA frameworks for food-contact packaging serving cross-border supply chains. Ontario and Quebec-based processors prioritize resealable formats for snack and confectionery applications. Short-run flexibility services from regional suppliers address procurement patterns of mid-tier food brands seeking rapid turnaround.
Flip Lip Bags Market Competitive Landscape
Concentration sits with diversified packaging conglomerates and specialized flexible film converters serving distinct tier requirements. The vendor base spans multinational material science groups with integrated laminate production and regional fabricators competing on customization velocity. Strategic archetypes include: scale-driven mono-material specialists, short-run custom-printing operators, and kraft-paper hybrid laminate innovators. Competitive moves center on co-extrusion equipment investment for separable barrier films and geographic footprint expansion to capture artisan food brand procurement.
Among North American flexible packaging specialists, Emerald Packaging and Rutan Poly Industries occupy distinct positioning archetypes. Emerald Packaging represents the West Coast manufacturing footprint model serving artisan food producers with custom-printed capabilities. Rutan Poly Industries exemplifies the short-run flexibility operator targeting regional co-packers with polyethylene-based stock and rapid turnaround. Mondi Group anchors the European tier as the kraft-paper hybrid laminate scale player. These three entities collectively illustrate the geographic and capability segmentation defining competitive dynamics.
| Leading Market Players |
|---|
| Emerald Packaging |
| Rutan Poly Industries |
| Ampac Holdings |
| Mondi Group |
| EZ Products |
| International Plastics |
| North Coast Plastics |
| Dana Poly |
| Confidential Data |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between German bakery brands and polyethylene converters lock in resin supply visibility while capping price volatility exposure under EU Packaging and Packaging Waste Regulation timelines. These arrangements tether procurement costs to indexed petrochemical benchmarks, forcing converters to absorb margin compression when pass-through clauses lag spot polyethylene movements.
Pricing Analysis
EU Packaging and Packaging Waste Regulation dictates the pricing tier structure across European flip lip bag procurement, separating certified mono-material formats from legacy multi-layer laminates facing recyclability penalties. Three-tier pricing structure across premium, standard, and economy levels reflects barrier-grade certification status, with FDA-validated migration tiers commanding additional positioning. Cost compression in standard-grade polyethylene is intensifying because resin volatility outpaces contract renegotiation cycles. Artisan food producers in California exhibit lowest price sensitivity due to premium positioning requirements, while European private-label producers drive hardest bargain on volume-scale commodity procurement.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for Chinese converters supplying North American brand owners with polyethylene-based stock. Manufacturing gravity centers on Germany, China, and the United States, with raw material feeds drawing from Saudi Arabian and U.S. Gulf Coast petrochemical complexes. Supply chain risk concentrates in single-source vulnerability for ethylene-vinyl alcohol barrier resins. Distribution runs through regional co-packer networks and direct-to-brand converter relationships, with West Coast manufacturing footprints enabling rapid turnaround for California artisan clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flip lip bag procurement fragmentation creates multiple entry points as small-format food brands displace bulk industrial buyers, splintering volume concentration across regional co-packers and custom-printing specialists.
For Market Incumbents: Consolidate production scale around mono-material polyethylene capabilities to preempt EU Packaging and Packaging Waste Regulation enforcement deadlines. Acquire short-run flexibility operators in California and Pacific Northwest clusters to capture artisan food brand procurement shifting from bulk buyers. Vertical integration into co-extrusion equipment manufacturing reduces capital expenditure exposure on separable barrier film R&D cycles. For New Entrants and Emerging Players: FDA food-contact certification fast-track positions converters for cross-border supply contracts serving U.S.-destined pharmaceutical and supplement packaging. Target biodegradable film segments in France and California where retailer sustainability scorecards create pull ahead of technical maturity. White-space sits with kraft-paper hybrid laminates for German bakery applications, with go-to-market angle anchored through Mondi Group's established fiber-based production partnerships. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap converters with pre-certified material libraries and regional co-packer relationships, avoiding pure commodity polyethylene players facing margin compression. Long-term viability over a multi-year horizon rests on separable barrier film capabilities and EPR compliance infrastructure rather than legacy multi-layer laminate scale. Signal to monitor is EU member state extended producer responsibility scheme implementation pace, which will determine compliance cost absorption versus pass-through feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Production Scale-Up | EU Packaging and Packaging Waste Regulation compliance secures German bakery brand procurement. |
| Backward Integration into Resin Compounding | Captive polyethylene supply hedges against Gulf Coast petrochemical price volatility. |
| FDA Certification Fast-Track Investment | Pre-validated migration libraries capture U.S. pharmaceutical packaging cross-border contracts. |
| Kraft-Paper Hybrid Laminate Development | Fiber-based formats address French retailer sustainability scorecards ahead of biodegradable film maturity. |
| Short-Run Flexibility Service Launch | Rapid sample-to-production cycles align with California artisan food brand procurement patterns. |
Research Methodology
Cross-validation between converter production data and brand owner procurement disclosures anchors the qualitative findings on specification divergence across material grades. Primary interviews with flexible packaging plant managers, bakery procurement leads, retail category buyers, regulatory compliance officers, and co-packer operations directors combined with secondary validation from EU regulatory filings, FDA food-contact substance databases, customs trade records, and petrochemical pricing benchmarks. Bottom-up capacity assessments and top-down demand segmentation triangulate volume estimates.
Sensitivity analysis on resin price assumptions and regulatory enforcement timelines shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include material type, closure mechanism, packaging style, end-use industry, and regional regulatory cluster. CAGRs derive from trend extrapolation against historical adoption curves, with industry-specific inputs incorporating oxygen transmission rate certification timelines and extended producer responsibility scheme rollout schedules.
Underlying assumptions cover EU Packaging and Packaging Waste Regulation enforcement adherence, polyethylene resin supply continuity, and artisan food brand procurement growth persistence, with deviation risk concentrated in mono-material barrier performance shortfalls and EPR cost recovery mechanism design. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Handle Gusseted Bags Market
Bags and Containers
Cross Corner Industrial Bags Market
Bags and Containers
Freezer Bags Market
Bags and Containers
Padding Bags Market
Bags and Containers
Bag-In-Tube Market
Bags and Containers
Americas Plastic Bags and Sacks Market
Bags and Containers
Twin Seal Bags Market
Bags and Containers
Slider Bags Market
Bags and Containers
4-Loop FIBC Market
Bags and Containers
Bagster Bag Market
Bags and Containers
Laminated Woven PP Bags Market
Bags and Containers
Breather Bags Market
Bags and Containers
Wicketed Bags Market
Bags and Containers
Crates Market
Bags and Containers
Ventilated FIBC Market
Bags and Containers
Frosted Bag Market