
 Hanging Bags Market | 2026-2036
Hanging Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Hanging Bags Market Foresight
Skilled textile and flexible packaging labor availability is collapsing across traditional manufacturing bases, forcing producers to automate or relocate conversion operations. Novolex Holdings leverages its North American film extrusion network to sustain supply continuity for retail-facing hanging bag programs. Mondi Group anchors European demand through integrated kraft paper and barrier film operations that serve supermarket private-label contracts. International Paper Company competes via containerboard-adjacent converting expertise that extends into corrugated-display-compatible hanging formats.
Hanging bags are suspended flexible containers engineered with integrated hooks, grommets, or adhesive strips, typically fabricated from polyethylene films, woven polypropylene, or laminated nonwovens with load-bearing seams rated between five and twenty-five kilograms, designed for vertical storage in closets, retail displays, or transit environments. Fabric and plastic material segments dominate current volume, with synthetic formulations representing the fastest-expanding margin pool as brands seek tear-resistant, washable alternatives to single-use films. Travel bags and organizer bags lead product-type demand, while storage bags occupy the mature mass-retail channel where price compression limits producer returns.
FDA food-contact regulations govern hanging bags deployed in pantry and kitchen applications within the United States, while REACH and EU Green Deal packaging directives restrict substance migration and mandate recycled content thresholds across European markets. China's GB standards and SAMR labeling requirements shape product compliance for domestic distribution and export manufacturing. Stakeholders must monitor evolving extended producer responsibility frameworks and material certification schemes to secure channel access and avoid compliance-driven margin erosion.
Market Dynamics
Flexible packaging labor shortages across traditional manufacturing bases are forcing producers toward automation and geographic relocation of conversion operations, fundamentally restructuring supply continuity and cost structures for hanging bag programs.
Growth Catalysts
- E-commerce category expansion:Digital retail platforms are broadening home organization and travel accessories assortments, creating dedicated shelf space for hanging storage solutions. Amazon and Alibaba's private-label pushes amplify visibility.
- REACH recycled content mandates:The EU Green Deal's packaging directives are pulling virgin material substitution, accelerating demand for post-consumer recycled polyethylene formulations in European retail-facing programs.
- Urban apartment living concentration:China's tier-one cities are amplifying need for vertical storage as square footage compresses, with Shanghai and Beijing households prioritizing closet optimization products.
Market Restraints
- Polyethylene resin price volatility:Feedstock cost swings tied to naphtha and natural gas liquid markets compress converter margins unpredictably, especially for non-indexed retail contracts.
- Skilled seam-welding labor scarcity:Traditional textile manufacturing regions in Bangladesh and Vietnam face collapsing availability of technicians capable of load-rated ultrasonic bonding operations.
- Corrugated display substitution:Retailers are testing shelf-ready corrugated alternatives with integrated hooks, threatening flexible hanging bag placement in supermarket planograms.
Strategic Opportunities
- India organized retail penetration:Reliance Retail and D-Mart expansion into tier-two cities creates first-mover advantage for hanging bag suppliers establishing local converting partnerships.
- SAMR labeling compliance services:China's evolving GB standards for flexible packaging present revenue streams for testing and certification providers serving export manufacturers.
- RFID-integrated inventory tracking:Convergence of flexible packaging with passive tag embedding enables smart closet and luggage applications for premium consumer segments.
Industry Challenges
- Automation capex recovery timelines:Robot-assisted bag-making equipment requires five-to-seven-year payback periods that strain mid-cap converters' balance sheets amid interest rate pressure.
- Extended producer responsibility registration:Germany's VerpackG and France's Citeo compliance timelines demand dedicated regulatory staff that smaller producers struggle to hire.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hanging Bags Market |
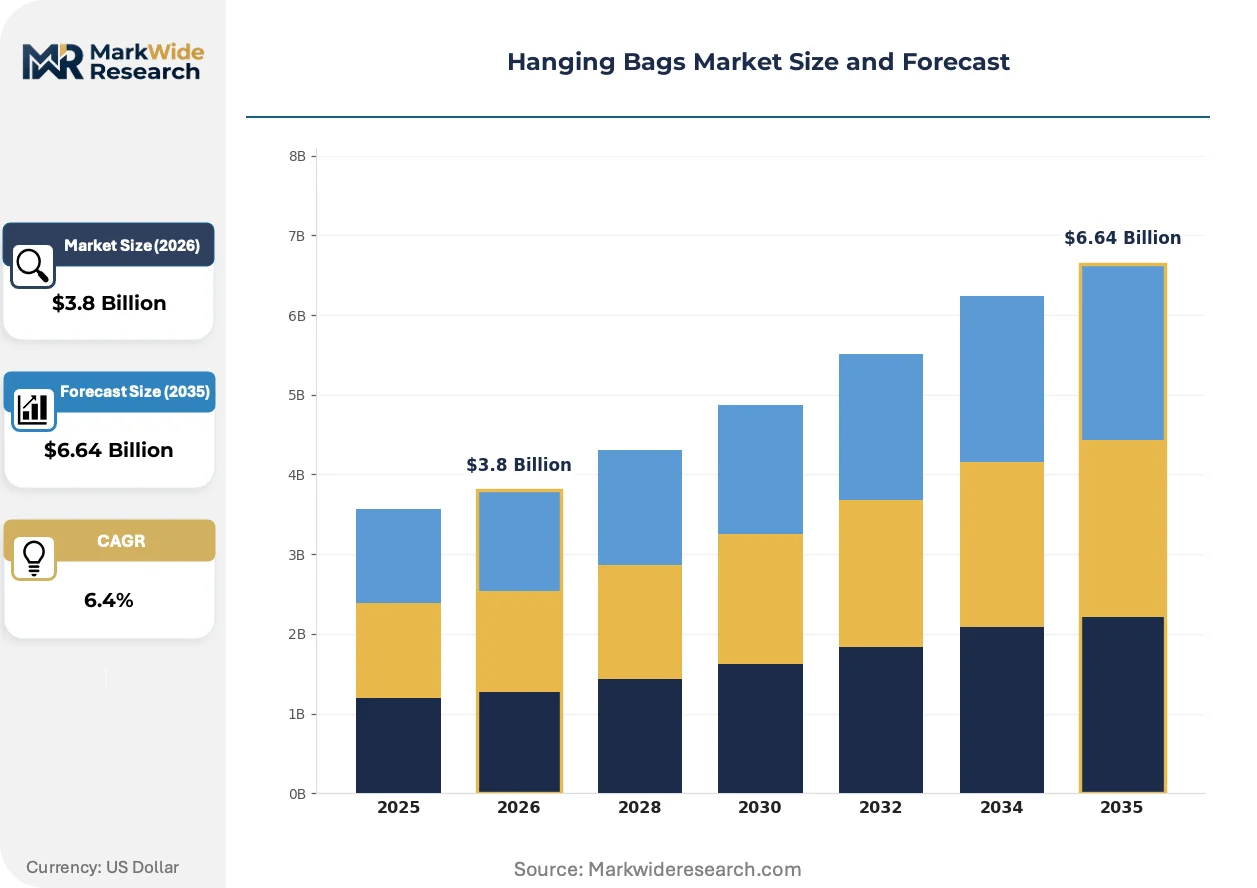
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Travel Bags, Storage Bags, Cosmetic Bags, Organizer Bags Material: Fabric, Plastic, Synthetic, Leather End User: Retail Consumers, E-commerce Shoppers, Fashion Enthusiasts, Outdoor Adventurers Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Novolex Holdings, Mondi Group, International Paper Company, Amcor plc, Inteplast Group, Global-Pak Inc., Smurfit Kappa Group, Coveris, ProAmpac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hanging Bags Market Shifts & Advancements
Material science advances and regulatory pressure on single-use plastics are actively restructuring competitive differentiation in hanging bag manufacturing, with performance and sustainability claims now inseparable from product development roadmaps.
Monomaterial polyethylene constructions are decomposing multi-layer barrier films in travel and organizer bag applications. Luggage brands and direct-to-consumer closet system suppliers are adopting these recyclable alternatives at accelerating pace. The technology is decomposing incumbent converters' laminated film expertise advantages and compressing R&D differentiation cycles.
The EU's Packaging and Packaging Waste Regulation is tightening material recovery targets and harmonizing extended producer responsibility fees across member states. Flexible packaging converters serving supermarket private-label programs face mandatory recycled content thresholds and substance migration testing expansion. German and French retail chains are responding by consolidating supplier bases toward vertically integrated film producers with in-house recycling capabilities.
Subscription-based closet organization services are displacing one-time retail purchases among affluent urban consumers in the United States and United Kingdom. Companies like California Closets and British startups are bundling hanging storage into whole-system redesigns, shifting procurement from individual consumers to interior design firms. This channel rotation is most visible in London, New York, and Los Angeles metropolitan markets where space optimization commands premium pricing.
Hanging Bags Market Segmentation
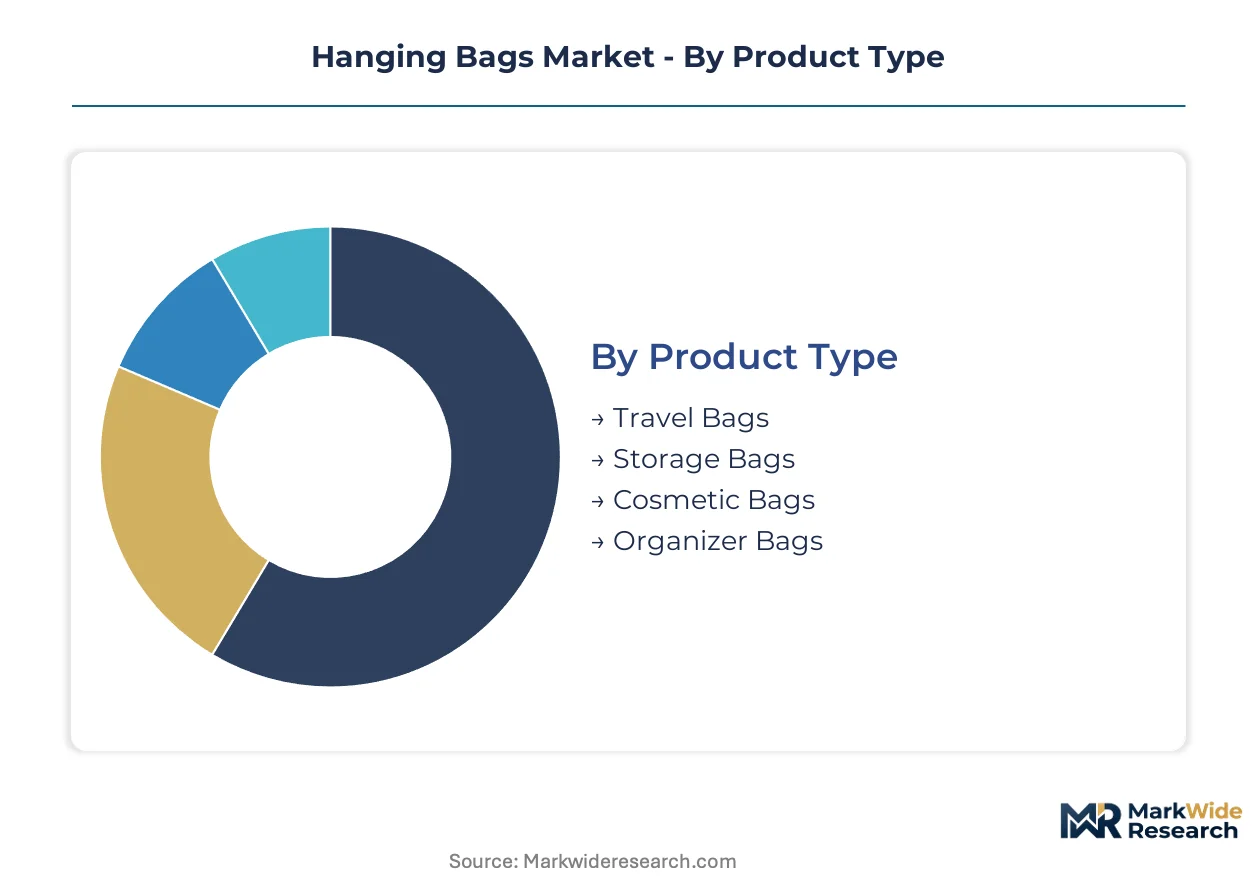
Hanging bag producers navigate divergent margin profiles across product architectures, with material composition and channel placement determining exposure to regulatory pressure and substitution risk. Segmentation discipline separates defensible premium positions from commoditized volume exposed to corrugated display alternatives.
Product Type:
Corrugated shelf-ready displays with integrated hooks threaten flexible hanging bag placement in supermarket planograms, intensifying substitution pressure on mass-market storage formats while travel and organizer segments retain structural differentiation through portability requirements.
- Travel Bags:Engineered with reinforced grommets and tear-resistant seams rated for transit loads, these formats concentrate demand among China's frequent domestic travelers and international e-commerce shoppers on Alibaba and Amazon. The segment benefits from airline baggage restrictions that favor collapsible vertical storage over rigid alternatives.
- Organizer Bags:Modular compartment designs with integrated hooks target closet optimization in Shanghai and Beijing's compressed urban apartments. Subscription-based closet services in New York and London bundle these into whole-system redesigns, shifting procurement toward interior design firms.
- Storage Bags:Basic polyethylene constructions dominate mass retail channels where price compression limits producer returns and corrugated alternatives gain trial placement.
- Cosmetic Bags:Smaller-format hanging designs with clear vinyl windows serve bathroom and vanity organization, typically purchased through specialty beauty retailers.
Storage bags anchor the volume base while organizer bags gain share at the steepest rate.
Material:
Cost tier stratification separates virgin polymer formulations from recycled-content and natural fiber alternatives, with regulatory thresholds in Europe and China pulling material substitution toward certified sustainable inputs.
- Synthetic:Laminated nonwoven and woven polypropylene constructions deliver tear resistance and washability that single-use films cannot match. Luggage brands and direct-to-consumer closet system suppliers adopt these recyclable alternatives at accelerating pace, displacing incumbent converters' multi-layer film expertise.
- Plastic:Monomaterial polyethylene constructions decompose multi-layer barrier films in travel applications, with EU Packaging and Packaging Waste Regulation mandates accelerating virgin material substitution toward post-consumer recycled formulations.
- Fabric:Cotton canvas and natural fiber weaves serve premium closet organization segments in London and Los Angeles metropolitan markets where space optimization commands premium pricing.
- Leather:Full-grain and bonded leather constructions occupy luxury accessory channels with limited volume but intact margin structures.
Plastic formulations dominate current volume while synthetic alternatives expand most quickly as brands seek durable, washable substitutes for disposable films.
End User:
Customer type segmentation tracks the channel migration from individual retail purchase toward institutional procurement through subscription services and professional organizers.
- E-commerce Shoppers:Digital-native buyers on Amazon and Alibaba private-label programs drive visibility for hanging storage solutions, with platform algorithms amplifying home organization category expansion.
- Retail Consumers:Traditional mass-market purchasers remain exposed to corrugated display substitution in supermarket environments.
- Fashion Enthusiasts:Aesthetic-conscious buyers prioritize material finish and brand alignment over pure functionality.
- Outdoor Adventurers:Durability-focused users demand load-rated seams and weather-resistant constructions for camping and expedition applications.
Retail consumers provide the established revenue base while e-commerce shoppers climb the fastest as digital platforms broaden their home organization assortments.
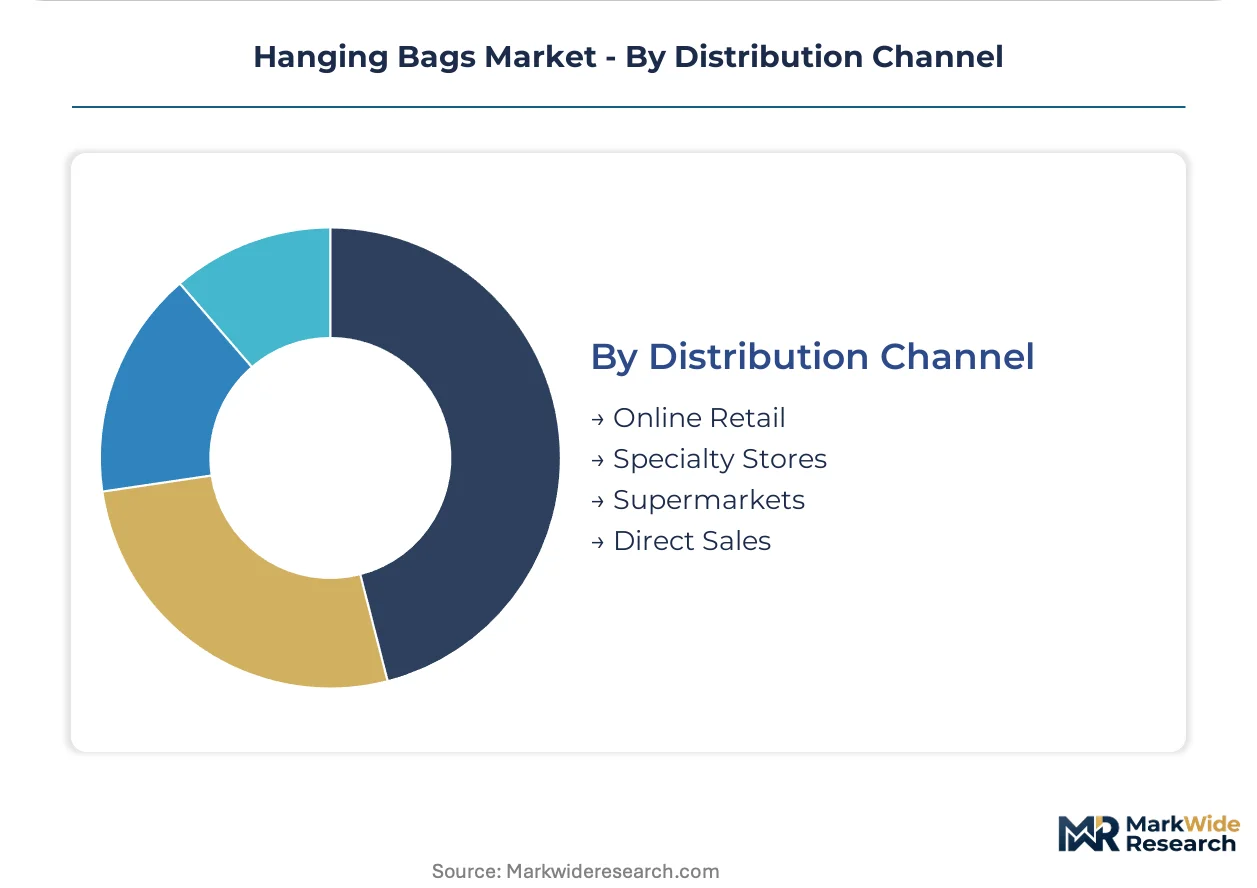
Distribution Channel:
Channel concentration determines compliance burden and working capital intensity, with direct and online formats reducing regulatory complexity compared to multi-jurisdiction retail placements.
- Online Retail:Amazon and Alibaba's category expansion creates dedicated digital shelf space with reduced physical packaging compliance overhead compared to European supermarket placements.
- Specialty Stores:Curated home organization retailers in tier-one Chinese cities and US coastal metros command premium positioning for performance-tier products.
- Supermarkets:German and French retail chains consolidate supplier bases toward vertically integrated film producers with in-house recycling capabilities to meet extended producer responsibility mandates.
- Direct Sales:California Closets and British subscription services bundle hanging storage into whole-system redesigns, capturing affluent urban consumers in space-constrained markets.
Supermarkets anchor volume throughput while online retail captures the steepest expansion trajectory as digital platforms displace physical shelf dependency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR labeling requirements in China anchor the dominant geography for hanging bag compliance, with GB standards shaping both domestic distribution and export manufacturing protocols across Asia-Pacific supply chains.
United States
California Closets and subscription-based closet services in New York and Los Angeles bundle hanging storage into whole-system redesigns, shifting procurement toward interior design firms. FDA food-contact regulations govern pantry and kitchen applications, mandating specific migration thresholds for polyethylene films. Dallas and Chicago retail corridors sustain mass-market volume through big-box home organization categories.
Germany
VerpackG extended producer responsibility mandates force supermarket chains toward consolidated supplier bases with in-house recycling capabilities. REACH recycled content thresholds accelerate virgin material substitution in private-label flexible packaging programs. The Ruhr industrial corridor hosts film extrusion and converting operations serving Central European retail networks.
China
Shanghai and Beijing households prioritize closet optimization as urban apartment square footage compresses, amplifying demand for vertical storage solutions. SAMR labeling requirements and evolving GB standards create compliance complexity for export manufacturers. The Yangtze River Delta concentration of textile and flexible packaging converters supplies both domestic e-commerce platforms and international brands.
India
Reliance Retail and D-Mart expansion into tier-two cities creates first-mover opportunity for suppliers establishing local converting partnerships. BIS certification requirements for flexible packaging materials shape product compliance for organized retail penetration. Maharashtra and Gujarat industrial clusters host emerging domestic manufacturing capacity for home organization products.
United Kingdom
London metropolitan subscription services displace one-time retail purchases among affluent urban consumers seeking space optimization. EU Green Deal packaging directives, still influential in post-Brexit alignment discussions, pull material substitution toward certified sustainable inputs. Midlands converting operations serve European supermarket private-label contracts with corrugated-display-compatible hanging formats.
Hanging Bags Market Competitive Landscape
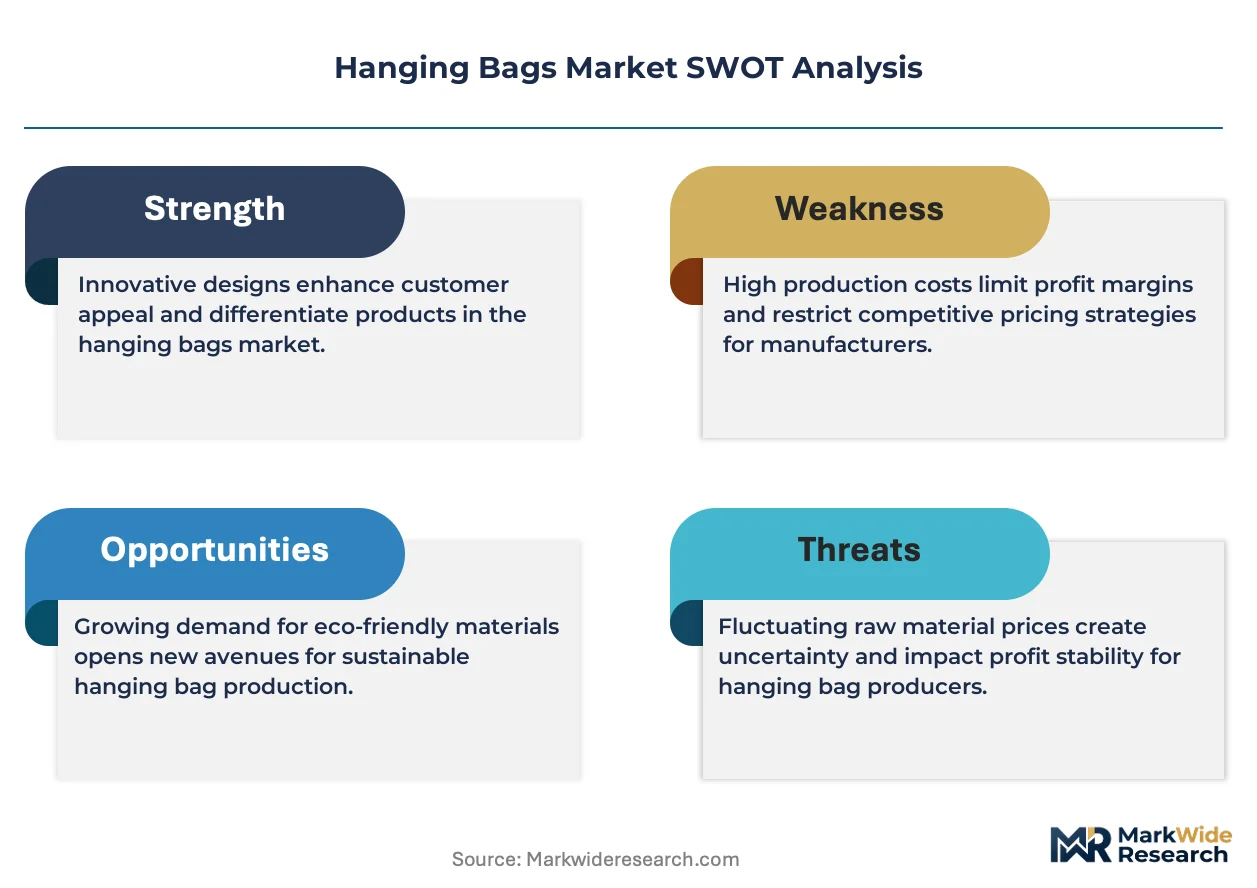
A small set of integrated leaders sits above a broader specialist tier, with film extrusion and kraft paper operations commanding supply continuity advantages over pure-play converters. The structure fragments across geographic regulatory zones, with European EPR compliance and Chinese labeling requirements sorting players by compliance capability depth. Three archetypes dominate: vertically integrated film producers with captive recycling streams, containerboard-adjacent converters leveraging corrugated expertise, and regional specialists anchored in single-jurisdiction regulatory mastery. Capacity expansion and strategic partnerships represent the dominant competitive vectors, with automation investments and local joint ventures displacing traditional labor-dependent models.
Among North American integrated players, Novolex Holdings represents the film extrusion archetype with supply network breadth, while International Paper Company exemplifies containerboard-adjacent converting expertise extending into display-compatible formats. Mondi Group anchors European positioning through integrated kraft paper and barrier film operations serving supermarket private-label contracts.
| Leading Market Players |
|---|
| Novolex Holdings |
| Mondi Group |
| International Paper Company |
| Amcor plc |
| Inteplast Group |
| Global-Pak Inc. |
| Smurfit Kappa Group |
| Coveris |
| ProAmpac |
| Others |
Supply & Pricing Matrix
Monomaterial polyethylene substitution for multi-layer barrier films is simultaneously pulling production toward German and Chinese extrusion hubs with in-house recycling capabilities and compressing margin pools for laminated-film specialists locked into virgin resin contracts. This input transition rewards converters with backward integration into post-consumer recycled feedstock streams while penalizing pure-play assemblers exposed to spot resin volatility.
Pricing Analysis
Price spreads between European and Asian supply bases widen during polyethylene resin volatility cycles, with German converters commanding premiums for REACH-compliant recycled content formulations. Three-tier pricing structure across premium synthetic, standard plastic, and economy polyethylene levels separates luggage brands seeking tear-resistant washability from mass retail storage bags. Pricing pressure stems from corrugated display substitution trials in French and German supermarket planograms. Mass retail consumers exhibit highest price sensitivity, while subscription-based closet service procurement in London and New York shows lowest elasticity.
Supply Chain Analysis
Inventory cycles for ultrasonic welding equipment and monomaterial film stocks have lengthened to twelve-to-eighteen weeks as automation capex surges across Bangladeshi and Vietnamese converting operations. Supply concentrates in China, Germany, and Vietnam, with Yangtze River Delta extruders feeding both domestic e-commerce platforms and export manufacturers. Raw material dependencies center on polyethylene resin, woven polypropylene feedstock, and ultrasonic bonding consumables. Single-source vulnerability sits with European film producers lacking captive recycling streams. Distribution runs through Alibaba and Amazon fulfillment networks for direct-to-consumer segments, while supermarket private-label programs flow through consolidated German and French retail chain procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hanging bags occupy an early-cycle expansion phase justified by subscription-based closet services displacing one-time retail purchases among affluent urban consumers in space-constrained metropolitan markets.
For Market Incumbents: Compound film extrusion expertise into captive post-consumer recycled polyethylene streams before EU Packaging and Packaging Waste Regulation thresholds harden. Defend supermarket private-label positioning against corrugated display substitution by embedding RFID inventory tracking for smart closet applications. Prioritize automation investments in Bangladeshi and Vietnamese converting operations to offset skilled seam-welding labor scarcity.
For New Entrants and Emerging Players: SAMR labeling fast-tracks for Chinese domestic distribution create regulatory moats against export-dependent competitors. Target India's tier-two city organized retail expansion through Reliance Retail and D-Mart partnership structures. Penetrate the cosmetic bag segment with clear vinyl window designs for specialty beauty retail channels.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated film producers with in-house recycling capabilities over pure-play converters. Long-term viability hinges on exposure to e-commerce platform growth and subscription service procurement channels. Monitor German VerpackG and French Citeo compliance timelines as inflection indicators for regulatory-driven supplier consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Monomaterial Film Conversion | REACH mandates accelerate virgin material substitution toward recyclable polyethylene formulations. |
| RFID Tag Embedding | Premium luggage brands adopt passive inventory tracking for smart closet and luggage applications. |
| Automation Capex Deployment | Robot-assisted bag-making equipment offsets skilled seam-welding labor scarcity in Vietnam. |
| India Local Converting Partnership | Reliance Retail expansion into tier-two cities creates first-mover manufacturing footprint. |
| SAMR Compliance Service Launch | Testing and certification revenue streams serve export manufacturers navigating Chinese labeling requirements. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with flexible packaging procurement managers at supermarket chains, e-commerce platform category directors, ultrasonic welding equipment technicians, and regulatory compliance officers at film extrusion facilities. Secondary validation drew from EU Packaging and Packaging Waste Regulation filings, SAMR labeling guidance documents, Alibaba and Amazon category expansion announcements, and customs trade data for polyethylene film imports. Bottom-up segment sizing triangulated against top-down market boundary estimates.
Across the analysis window, the forecasting framework modeled volume and value trajectories by material composition, product architecture, distribution channel concentration, and end-user procurement pattern. CAGRs were derived from segment-level growth rate blending anchored to e-commerce platform category expansion rates and urban apartment living concentration indices. Industry-specific inputs included airline baggage restriction evolution and subscription service penetration rates in metropolitan closet optimization markets.
Decision-makers should treat outputs as directional under assumptions of sustained EU regulatory tightening and Chinese domestic consumption growth; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Breathable Bags Market
Bags and Containers
Loose-Fill Peanuts Market
Bags and Containers
Heat Sealing Bags Market
Bags and Containers
Vacuum Shrink Bags Market
Bags and Containers
Grip Seal Bags Market
Bags and Containers
Vacuum Sealer Bags Market
Bags and Containers
Mesh Bags Market
Bags and Containers
Aluminum Beverage Bags Market
Bags and Containers
Laminated Woven PP Bags Market
Bags and Containers
Trash Bags Market
Bags and Containers
Baggage Packaging Service Market
Bags and Containers
Cassava Bags Market
Bags and Containers
Refuse Bags Market
Bags and Containers
Bag on Valve Technology Market
Bags and Containers
Garbage Bag Market
Bags and Containers
Commodity Liners Market