
 Vacuum Sealer Bags Market | 2026-2036
Vacuum Sealer Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Vacuum Sealer Bags Market Analytics
A shift from single-source resin procurement to multi-source co-extruded film supply is realigning cost structures across the Vacuum Sealer Bags Market. IMPAK Corporation leverages captive manufacturing of high-barrier laminates to sustain margin control in premium segments. Vollrath anchors North American commercial kitchen demand through institutional-grade roll bag formats. YLTPACK competes on scale economics in Asian export channels for polyethylene-based quart and gallon configurations.
Vacuum sealer bags are multi-layer flexible packaging structures, typically comprising polyethylene tie layers with nylon or ethylene vinyl alcohol barrier films, manufactured through blown film co-extrusion and subsequently embossed to enable air evacuation via channel patterns. Their primary purpose is to extend shelf life by removing oxygen from food or industrial contents, thereby inhibiting aerobic microbial growth and oxidative degradation. Co-extruded films command the widest specification range across sous vide and industrial packaging applications where thermal stability and puncture resistance converge. Roll bags lead in commercial settings where operators cut custom lengths to reduce material waste, while heavy-duty bags occupy the highest unit-value tier in protein processing and long-term freezer storage.
Food contact compliance under FDA 21 CFR 177.1520 and EU Regulation 10/2011 governs monomer migration limits and additive permissibility for polyethylene and nylon layers in vacuum sealer bags sold across the United States and European Economic Area. China's SAMR enforces GB 4806.7 standards for domestic food-grade plastic packaging, creating a fragmented certification burden for exporters serving multiple jurisdictions. Stakeholders must monitor evolving extended producer responsibility frameworks and chemical disclosure requirements to preempt reformulation costs and market access barriers.
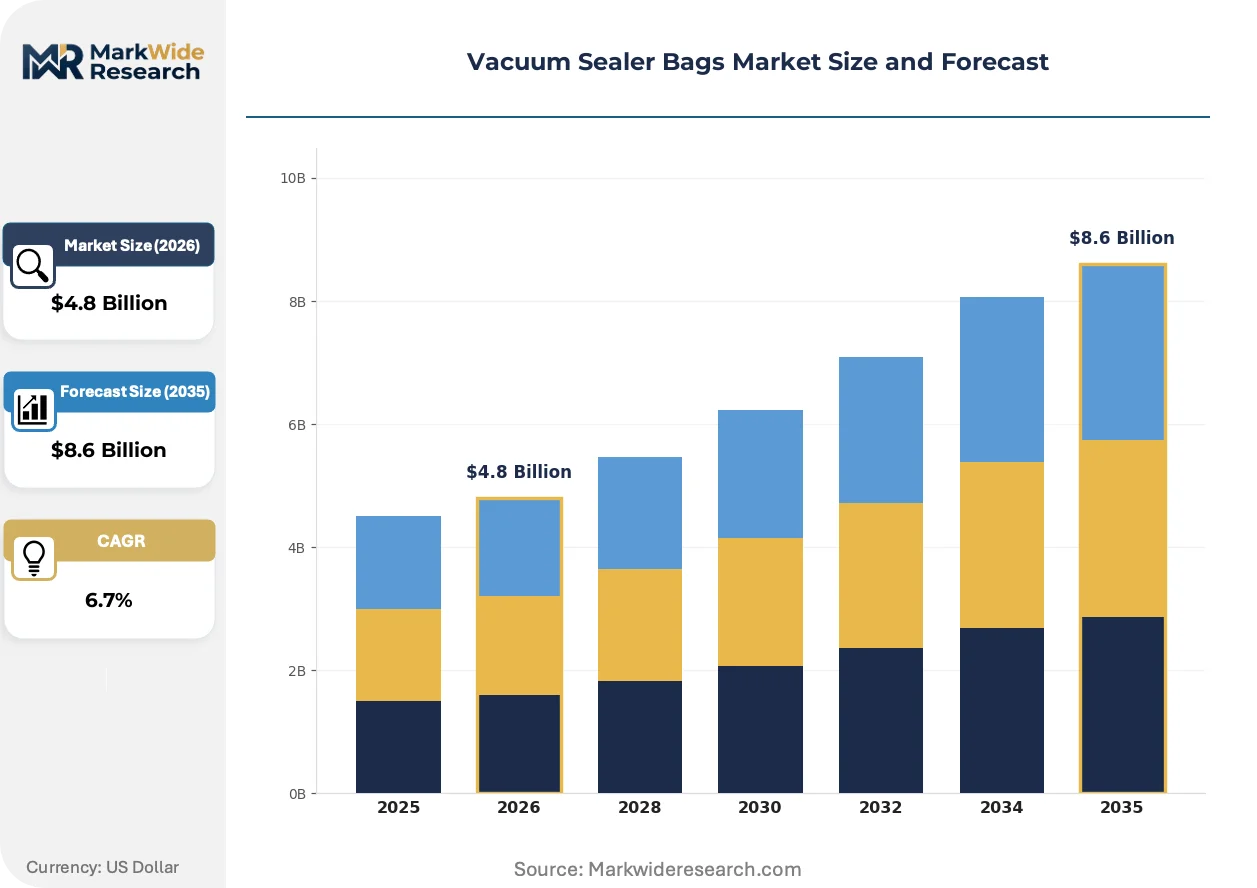
Market Dynamics
Co-extrusion technology maturation is compressing specification margins across the Vacuum Sealer Bags Market as multi-layer barrier films replace simpler mono-material constructions in premium foodservice and industrial applications.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Extended producer responsibility mandates are accelerating replacement of conventional single-use plastics with recyclable multi-layer alternatives in German and French commercial kitchens.
- Sous vide cooking expansion:Foodservice operators in institutional catering and hospitality are specifying thermal-stable vacuum sealer bags for precision temperature protocols.
- Ethylene vinyl alcohol barrier films:Oxygen transmission rates below 0.5 cc/m²/day are enabling protein processors to extend cold-chain distribution windows without modified atmosphere packaging.
Market Restraints
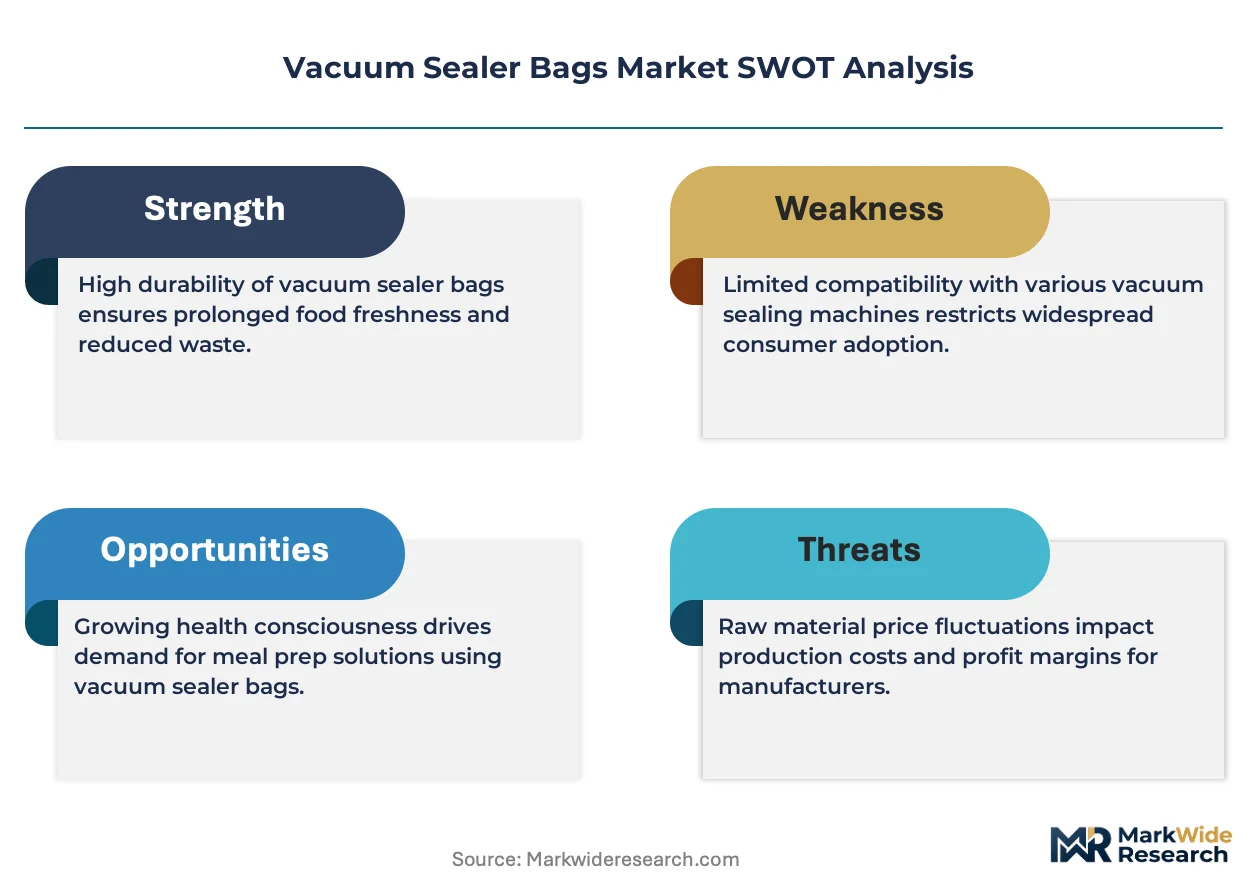
- Nylon resin price volatility:Caprolactam feedstock costs tied to benzene derivatives create margin compression for co-extruded film manufacturers.
- China SAMR certification backlog:GB 4806.7 testing queue delays are extending time-to-market for Western exporters by 4-8 months.
- Silicone bag substitution:Reusable platinum-cured silicone pouches are capturing meal-prep consumer segments previously served by disposable polyethylene channels.
Strategic Opportunities
- India FSSAI compliance pathway:Domestic food-grade plastic packaging standardization is opening import substitution opportunities for local co-extrusion capacity.
- Pharmaceutical cold-chain:Vaccine distribution integrity requirements are creating specification pull for ultra-high-barrier vacuum sealer bags in temperature-controlled logistics.
- Japan METI carbon accounting:Corporate supply chain disclosure rules are incentivizing lightweighting and bio-based content in flexible packaging procurement.
Industry Challenges
- Migration testing capacity:FDA 21 CFR 177.1520 and EU 10/2011 dual certification requires specialized analytical chemistry expertise that contract laboratories struggle to staff.
- Legacy embossing equipment retrofit:Channel pattern standardization for air evacuation compatibility demands capital expenditure on blown film line modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vacuum Sealer Bags Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heavy-Duty Bags, Quart Bags, Gallon Bags, Roll Bags Material: Polyethylene, Nylon, Polyvinyl Chloride, Co-Extruded Films Application: Food Storage, Sous Vide Cooking, Marinating, Industrial Packaging Size: Small, Medium, Large, Custom Sizes |
| Companies Covered | IMPAK Corporation, Vollrath, YLTPACK, Weston Brands, Zoro, GreenPak, JVR Industries, FoodSaver, Boya Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vacuum Sealer Bags Market Evolving Landscape
Material science convergence with regulatory disclosure requirements is redefining competitive advantage in vacuum sealer bag specification. Manufacturers are racing to demonstrate compliance transparency while maintaining barrier performance.
High-barrier co-extruded laminates are consolidating technical specifications across sous vide and industrial packaging segments. Foodservice distributors are specifying these structures for dual-use thermal and freezer applications. The technology is consolidating what were previously separate product lines into unified SKUs, reducing inventory carrying costs for procurement teams.
EU REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing reformulation of grease-resistant additives in nylon barrier layers. Manufacturers serving the European Economic Area are accelerating fluorine-free alternatives through ECHA notification pathways. Protein processing applications in Germany and the Netherlands are experiencing the steepest specification transition curves.
Direct procurement from co-extrusion specialists is displacing distributor intermediaries in North American commercial kitchen supply. Institutional buyers with volume scale are establishing specification control through mill-direct relationships. This pattern is most visible in US regional restaurant chains consolidating bag procurement across 50-plus location footprints.
Vacuum Sealer Bags Market Segmentation
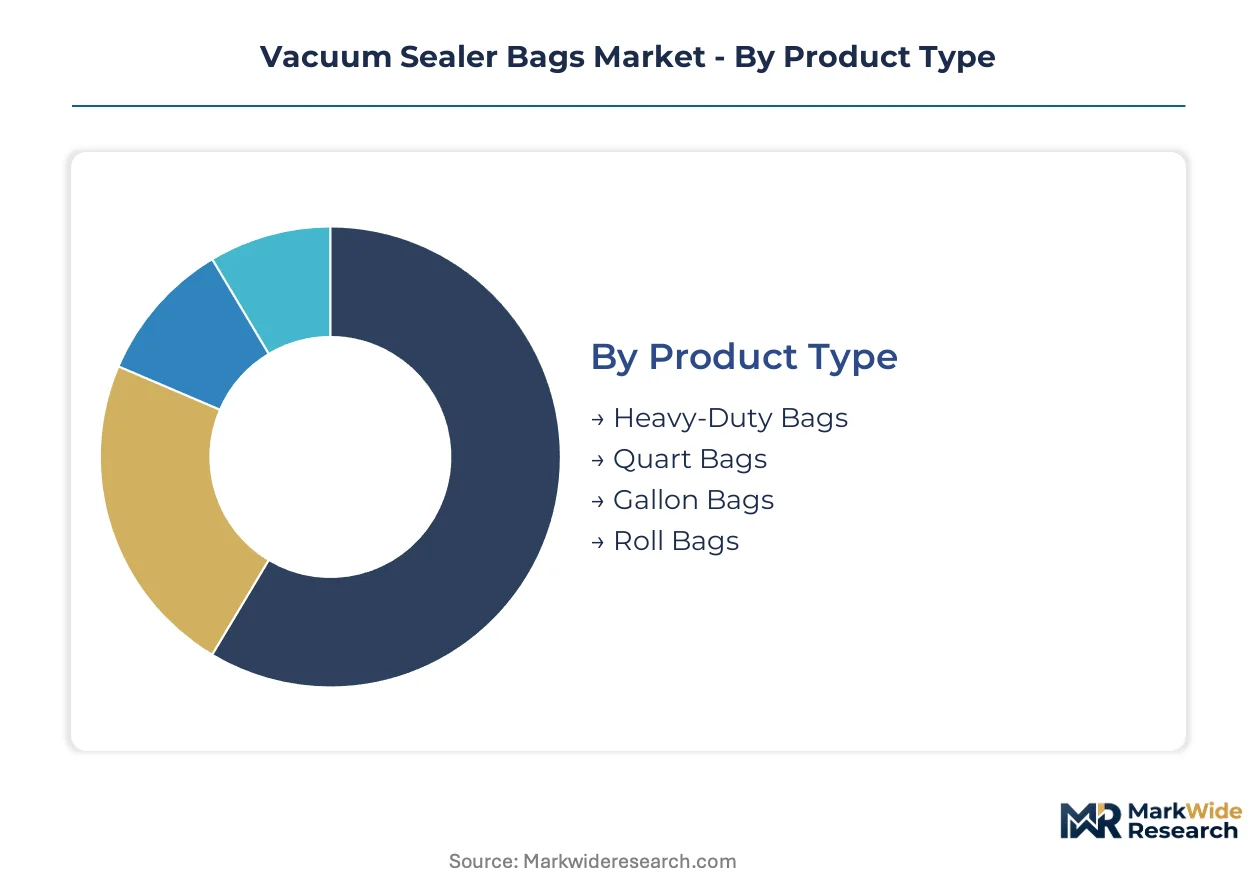
Specification differentiation across vacuum sealer bags determines barrier performance, thermal stability, and regulatory compliance trajectories. Procurement teams segment requirements by operational intensity, material science capabilities, and end-use thermal protocols rather than commoditized price points alone.
Product Type:
Capital intensity concentrates in roll bag manufacturing where continuous extrusion lines and embossing equipment demand seven-figure installation costs, while pre-cut formats require lower tooling thresholds.
- Heavy-Duty Bags:Multi-layer co-extruded structures with enhanced puncture resistance and nylon barrier content exceeding 15% by weight. Protein processors in Germany specify these for bone-in meat applications where failure rates must stay below 0.3%.
- Roll Bags:Continuous embossed film supplied on cardboard cores, enabling operators to cut custom lengths. Institutional kitchens across the United States favor this format for waste reduction protocols where standard sizes generate 12-18% trim scrap.
- Quart Bags:Pre-cut polyethylene-nylon laminates optimized for single-meal portioning.
- Gallon Bags:Larger format pre-cuts serving family-size meal prep and bulk protein storage.
Roll bags absorb the bulk of installed capacity; heavy-duty bags are expanding most quickly.
Material:
Barrier performance and migration compliance costs stratify raw material selection, with EVOH and nylon commanding premium positions over commodity polyethylene.
- Co-Extruded Films:Multi-layer blown film structures combining polyethylene tie layers with nylon or EVOH barriers in five to seven layer configurations. Sous vide applications in France and the Netherlands mandate these for thermal stability above 85°C.
- Polyethylene:Homopolymer and linear low-density grades forming base layers and economy-tier pre-cuts.
- Nylon:Polyamide 6 and 6/6 resins supplying oxygen barrier and puncture resistance.
- Polyvinyl Chloride:Legacy formulation in declining use due to plasticizer migration concerns and ECHA scrutiny.
Co-extruded films dominate specification conversations; polyethylene maintains volume leadership through cost position.
Application:
End-use thermal protocols and regulatory exposure determine material specification stringency and certification burden.
- Food Storage:General-purpose oxygen exclusion for refrigerated and frozen goods, spanning residential and commercial contexts.
- Sous Vide Cooking:Precision temperature water bath applications requiring thermal stability above 90°C and FDA 21 CFR 177.1520 compliance for prolonged food contact.
- Marinating:Short-duration liquid contact with acidic or enzymatic content, demanding seal integrity under pressure.
- Industrial Packaging:Non-food applications including electronics, pharmaceuticals, and chemical components where ESD protection or moisture exclusion takes priority.
Food storage commands absolute volume; sous vide cooking climbs the fastest as hospitality operators expand precision temperature programs.
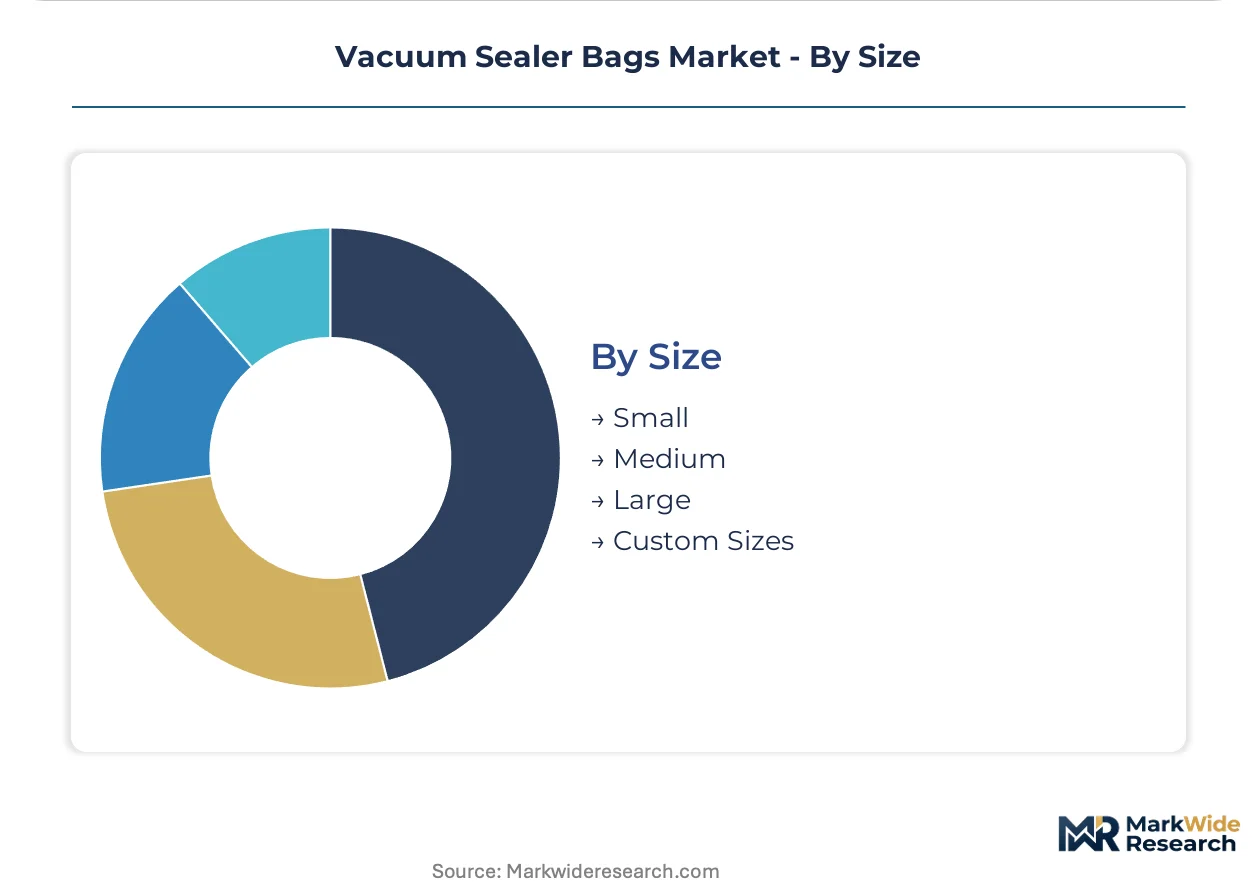
Size:
SKU proliferation versus standardization trade-offs shape inventory economics and manufacturing changeover efficiency.
- Small:Single-portion formats under 20cm width for snack portions and individual protein cuts.
- Medium:Standard quart and gallon equivalents serving household meal prep.
- Large:Bulk formats exceeding 30cm width for primal cuts and institutional quantities.
- Custom Sizes:Specification-driven dimensions for OEM equipment integration or proprietary processing lines.
Medium sizes anchor production planning; custom sizes gain share fastest among regional restaurant chains consolidating procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial kitchen procurement concentrates in Germany, where sustainability mandates and extended producer responsibility frameworks are accelerating replacement cycles for multi-layer barrier packaging. Foodservice operators across Western Europe and North America are expanding specifications for thermal-stable formats that serve dual sous vide and freezer applications.
United States
Regional restaurant chains with 50-plus location footprints are establishing mill-direct procurement relationships with co-extrusion specialists to reduce distributor markups. FDA 21 CFR 177.1520 compliance requirements govern migration limits for polyethylene and nylon layers in food contact applications. Institutional kitchens in the Chicago and Dallas metropolitan areas favor roll bag formats to cut material waste from standard size mismatches.
Germany
Protein processors in the Ruhr industrial corridor specify heavy-duty bags with nylon barrier content exceeding 15% by weight for bone-in meat applications demanding sub-0.3% failure rates. The EU Packaging and Packaging Waste Regulation tightens material compliance timelines for single-use food contact plastics through 2025. Bavarian commercial kitchen modernization programs are driving fastest replacement cycle velocities across the European Economic Area.
China
Export-oriented manufacturers serving Western foodservice channels face GB 4806.7 certification queues extending time-to-market by 4-8 months. SAMR enforcement of domestic food-grade plastic packaging standards creates fragmented compliance burdens for multinational suppliers. Yangtze River Delta co-extrusion capacity is expanding to capture Asian export demand for polyethylene-based quart and gallon configurations.
France
Sous vide cooking adoption in institutional catering and hospitality is specifying thermal stability above 85°C for precision temperature protocols. ECHA notification pathways for fluorine-free grease-resistant additives are accelerating reformulation of nylon barrier layers under REACH Annex XVII restrictions. Paris and Lyon foodservice distributors are consolidating SKUs around high-barrier co-extruded laminates for dual-use thermal and freezer applications.
Japan
Corporate supply chain disclosure rules under METI carbon accounting are incentivizing lightweighting and bio-based content in flexible packaging procurement. Precision meal-prep culture drives specification for ultra-high-barrier formats in temperature-controlled logistics. Osaka and Nagoya industrial clusters are piloting channel pattern standardization for air evacuation compatibility across legacy embossing equipment retrofits.
Vacuum Sealer Bags Market Competitive Landscape
Capacity expansion dominates the current landscape as co-extrusion specialists add blown film lines to capture institutional procurement consolidation. The vendor base stratifies between captive laminate manufacturers, commercial kitchen equipment integrators, and scale-driven Asian exporters. Three archetypes define competitive positioning: high-barrier technology specialists, roll format institutional suppliers, and polyethylene volume exporters. Geographic expansion and strategic partnerships constitute the dominant competitive moves, with technology licensing emerging in barrier film formulations.
Among North American fabricators, IMPAK Corporation and Vollrath exemplify divergent archetypes within the premium tier. IMPAK Corporation represents the captive manufacturing model for high-barrier laminate margin control. Vollrath occupies a position anchoring institutional-grade roll bag demand through equipment-integrated supply relationships. At the scale-driven end, YLTPACK sits within the Asian export archetype competing on polyethylene-based volume economics for standard quart and gallon configurations.
| Leading Market Players |
|---|
| IMPAK Corporation |
| Vollrath |
| YLTPACK |
| Weston Brands |
| Zoro |
| GreenPak |
| JVR Industries |
| FoodSaver |
| Boya Packaging |
| Others |
Value Network & Pricing Analysis
Blown film co-extrusion line upgrades across German and Chinese manufacturing clusters are simultaneously compressing unit economics and concentrating supply relationships among capitalized multi-layer barrier specialists. This technology transition rewards operators with seven-figure installation capacity while squeezing mono-material competitors out of premium foodservice specifications.
Pricing Analysis
Warranty-backed FDA 21 CFR 177.1520 and EU 10/2011 dual certification bundles separate premium co-extruded film suppliers from unvalidated commodity exporters. Three-tier pricing structure across premium, standard, and economy levels tracks barrier performance tiers and migration testing documentation depth. Cost compression in standard polyethylene channels is intensifying because Yangtze River Delta capacity expansion floods Asian export markets. Meal-prep consumers exhibit highest price sensitivity; protein processors in Germany's Ruhr corridor demonstrate lowest sensitivity due to failure-rate penalties.
Supply Chain Analysis
Single-source vulnerability sits with caprolactam feedstock suppliers tied to benzene derivative markets in Germany, Belgium, and South Korea. Nylon resin, EVOH barrier films, and polyethylene tie layers constitute critical raw material inputs. Tariff exposure on Chinese-manufactured co-extruded films shipped to North American foodservice channels threatens margin stability. Distribution runs through mill-direct relationships with institutional buyers and foodservice equipment integrators, bypassing traditional distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Vacuum Sealer Bags Market functions as a cost-of-compliance story where EU REACH Annex XVII and extended producer responsibility mandates erect capital barriers that protect certified incumbents from price-only competition.
For Market Incumbents: Lock in backward integration into captive EVOH and nylon laminate production to defend margins against resin price volatility. Prioritize GB 4806.7 pre-certification investments to circumvent SAMR testing queue delays that strand Western competitors. Channel control through equipment-integrated supply relationships with Vollrath-class institutional distributors creates switching-cost moats.
For New Entrants and Emerging Players: Direct-to-commercial-kitchen digital platforms offer lowest customer-acquisition costs for penetrating fragmented US regional restaurant chains. India's FSSAI compliance pathway presents the most penetrable geography given import substitution tailwinds and nascent local co-extrusion capacity. Target pharmaceutical cold-chain specifications where ultra-high-barrier requirements command premium positioning absent entrenched competition.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to flexible packaging conglomerates seeking barrier technology capabilities. Five-to-ten year viability hinges on fluorine-free additive reformulation completion and carbon accounting disclosure readiness. The signal to watch is Japan METI supply chain disclosure adoption rates, which will force procurement preference shifts toward lightweighted and bio-based content suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Barrier Film Production | IMPAK Corporation's laminate manufacturing model demonstrates margin control against resin volatility. |
| Dual Jurisdiction Certification Pre-Investment | FDA and EU 10/2011 parallel testing reduces SAMR queue delays for Western exporters. |
| Mill-Direct Procurement Relationship Development | US regional chains with 50-plus locations bypass distributor markups through specification control. |
| Fluorine-Free Additive Reformulation | ECHA REACH Annex XVII compliance protects European Economic Area market access. |
| Pharmaceutical Cold-Chain Specification Entry | Vaccine distribution integrity requirements create ultra-high-barrier demand outside foodservice saturation. |
Research Methodology
Independent corroboration across co-extrusion plant managers, foodservice procurement directors, and regulatory affairs specialists underwrites the qualitative findings. Technical R&D directors at barrier film manufacturers, distribution channel partners in German and North American commercial kitchen supply, and customs trade data specialists provided primary perspective. Secondary validation drew from ECHA notification databases, FDA 21 CFR guidance documents, SAMR GB standard filings, and SEC 10-K disclosures from listed packaging conglomerates. Bottom-up capacity modeling and top-down demand segmentation triangulate volume estimates.
Rate-of-change decomposition across the analysis window isolates volume drivers from price-mix effects in co-extruded film adoption. Segmentation dimensions span product type, material configuration, application thermal protocol, and regional regulatory cluster. CAGRs derive from installed capacity expansion schedules, replacement cycle velocities in commercial kitchen modernization programs, and sous vide cooking penetration curves. Industry-specific forecast inputs include caprolactam price elasticity coefficients and EVOH oxygen transmission rate improvement trajectories.
Inputs from primary stakeholder interviews and regulatory filing databases were available through the study window; gaps in real-time SAMR certification queue duration data introduce uncertainty bands around China market entry timing assumptions. Forecasts reflect documented assumptions regarding EU Packaging and Packaging Waste Regulation enforcement timelines and fluorine-free additive substitution rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Zipper Bags Market
Bags and Containers
Inner Bulk Liners Market
Bags and Containers
Flip-Up Vacuum Pack Market
Bags and Containers
Mattress and Furniture Bags Market
Bags and Containers
Disposable Garbage Bags Market
Bags and Containers
Ventilated Bulk Bags Market
Bags and Containers
Liner Bags Market
Bags and Containers
Non-Barrier Bag Market
Bags and Containers
Bag-In-Box Market
Bags and Containers
Breather Bags Market
Bags and Containers
Ziplock Food Bags Market
Bags and Containers
Drink Carrier Poly Bags Market
Bags and Containers
Baggage Packaging Service Market
Bags and Containers
Shrink Bags Market
Bags and Containers
Freezing Bags Market
Bags and Containers
Lay Flat Bags Market