
 Ziplock Food Bags Market | 2026-2036
Ziplock Food Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Ziplock Food Bags Market Insights
Asset-light leasing models for extrusion equipment are tilting competitive dynamics toward mid-sized converters that previously faced capital barriers. Berry Global Inc. leverages its North American film manufacturing footprint to sustain cost advantages in polyethylene supply. Novolex anchors its position through vertical integration into resin compounding and recycling operations. SC Johnson & Son, Inc. differentiates via brand equity and retail shelf presence that controls premium household channels.
Ziplock food bags are reclosable storage pouches manufactured from low-density polyethylene or biodegradable films, typically featuring interlocking zipper tracks or slider mechanisms that create repeatable airtight seals for moisture and oxygen barrier protection. The primary commercial purpose centers on extending food freshness duration while enabling portioned storage across residential and food service environments. Gallon bags and freezer bags occupy the highest margin pools due to thicker gauge requirements and performance specifications that command price premiums over standard sandwich formats. Biodegradable materials represent the fastest-growing segment as food service operators navigate tightening waste regulations and corporate sustainability mandates.
The FDA regulates food-contact substances under 21 CFR, while the EPA oversees resin manufacturing emissions and emerging chemical restrictions that shape material selection across domestic supply chains. State-level extended producer responsibility frameworks in California and New York are forcing converters to redesign products for recyclability or compostability certification. Stakeholders must monitor how rapidly advancing mechanical recycling infrastructure and chemical recycling scale will alter virgin resin cost spreads and sustainable material viability.
Market Dynamics
The EU's Single-Use Plastics Directive is forcing converters to abandon conventional polyethylene formulations and rebuild supply chains around certified compostable resins before 2030 deadlines.
Growth Catalysts
- Meal-kit delivery expansion:Portion-controlled packaging specifications from HelloFresh and Blue Apron are standardizing ziplock bag formats across North American fulfillment networks.
- California's SB 54 EPR framework:Extended producer responsibility mandates are accelerating design-for-recyclability investments among domestic converters seeking compliance advantages.
- Commercial kitchen automation:Robotic prep line integration at Chipotle and Sweetgreen locations is specifying standardized bag sizes for ingredient staging and waste reduction.
Market Restraints
- Resin cost volatility:Ethane feedstock price swings tied to Permian Basin natural gas liquids output are compressing margin visibility for polyethylene-dependent converters.
- Biodegradable certification bottlenecks:ASTM D6400 and EN 13432 testing timelines stretching 18-24 months are delaying product launches for compostable film innovators.
- Mechanical recycling contamination:Mixed-material slider mechanisms and multi-layer barrier films are rendering post-consumer ziplock bags non-recyclable through existing municipal streams.
Strategic Opportunities
- India food service modernization:Quick-service restaurant chains expanding in Mumbai and Bangalore are adopting portion-control packaging protocols previously standardized in Western markets.
- Reusable bag subscription models:Loop and similar circular economy platforms are piloting durable silicone ziplock alternatives with deposit-return logistics.
- USDA BioPreferred procurement:Federal cafeteria and military commissary purchasing mandates are creating guaranteed offtake channels for biobased film suppliers meeting minimum renewable content thresholds.
Industry Challenges
- Composting infrastructure gaps:Industrial composting facility coverage remains sparse outside California, Oregon, and Washington, limiting biodegradable bag value realization.
- Extrusion equipment retooling costs:Transitioning from polyethylene to polylactic acid or polyhydroxyalkanoate processing requires screw and die modifications exceeding mid-sized converter capital reserves.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ziplock Food Bags Market |
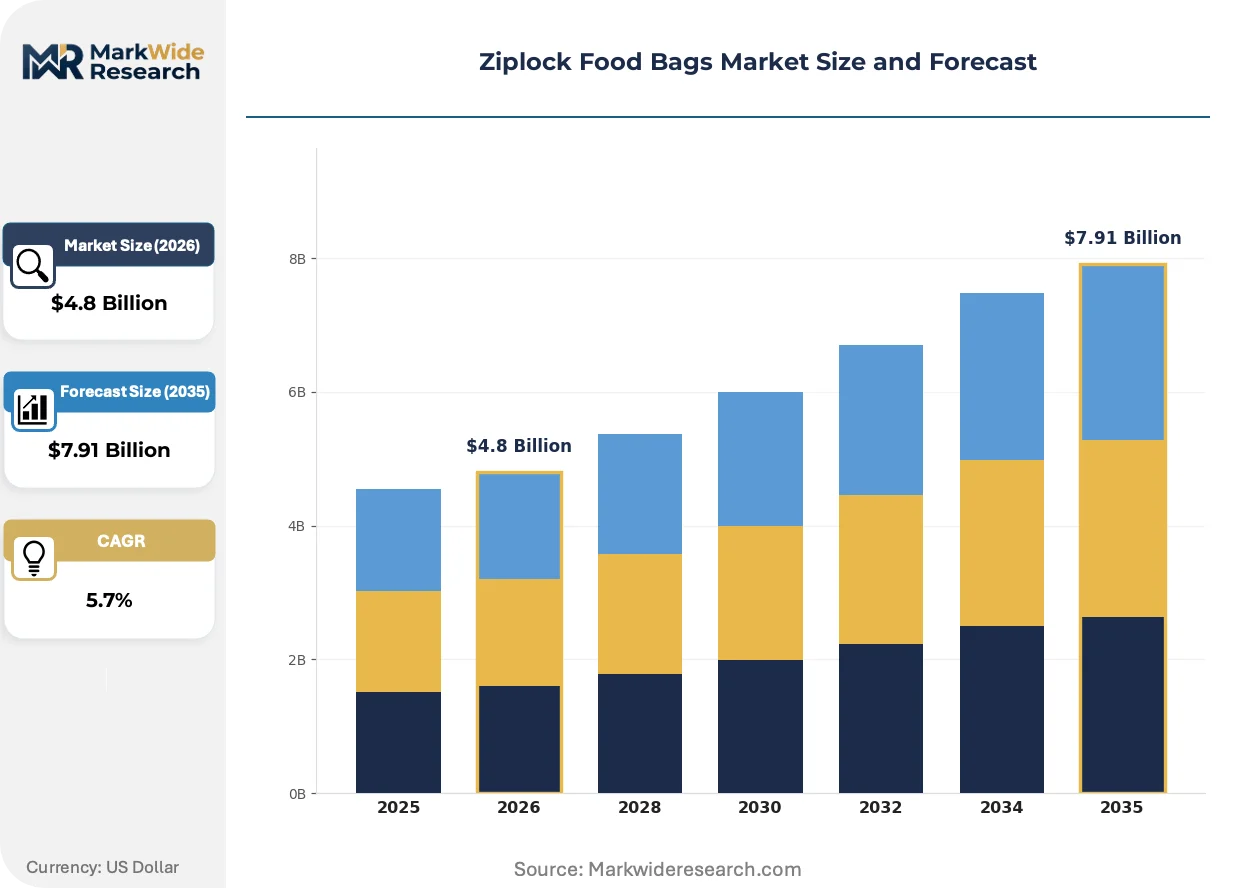
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sandwich Bags, Freezer Bags, Gallon Bags, Snack Bags Material: Plastic, Biodegradable, Polyethylene, PVC Closure Type: Zip Seal, Slider Seal, Press Seal, Adhesive Seal End User: Household, Food Service, Retail, Catering |
| Companies Covered | Berry Global Inc., Novolex, SC Johnson & Son, Inc., Minigrip LLC, Poly-America, L.P., The Glad Products Company, Inteplast Group, Ltd., Sealed Air Corporation, Reynolds Consumer Products LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ziplock Food Bags Market Trends and Innovations
Material science breakthroughs and regulatory compliance pressures are converging to reshape product architecture and manufacturing economics across the ziplock food bag sector.
Monolayer polylactic acid formulations with oxygen scavenger additives are collapsing the performance gap between biodegradable and conventional polyethylene films. Food service operators in the Pacific Northwest are piloting these materials for refrigerated protein storage. The technology is collapsing virgin resin demand among sustainability-mandated corporate accounts.
REACH restrictions on intentionally added microplastics are compelling European converters to eliminate slip agents and anti-block compounds from film formulations. The industrial consequence is slower line speeds and elevated defect rates during the transition period. Freezer bag categories face the steepest reformulation costs due to low-temperature flexibility requirements.
Direct-to-restaurant e-procurement platforms are consolidating purchasing power previously fragmented across independent distributors. WebstaurantStore and similar digital wholesalers are private-labeling ziplock bags and capturing margin from traditional broadline distributors. This channel shift concentrates most visibly in Texas and Florida metropolitan markets where restaurant density supports same-day delivery logistics.
Ziplock Food Bags Market Segmentation
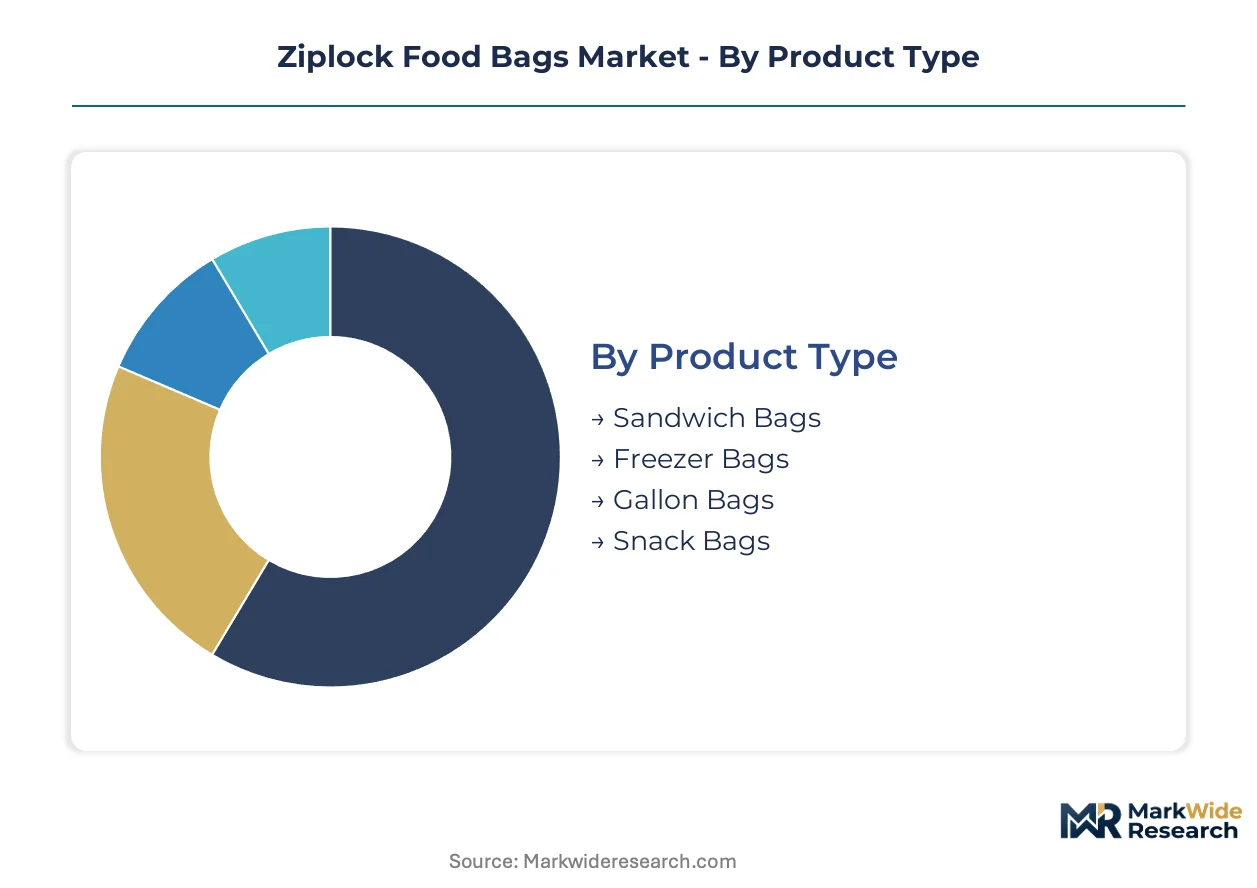
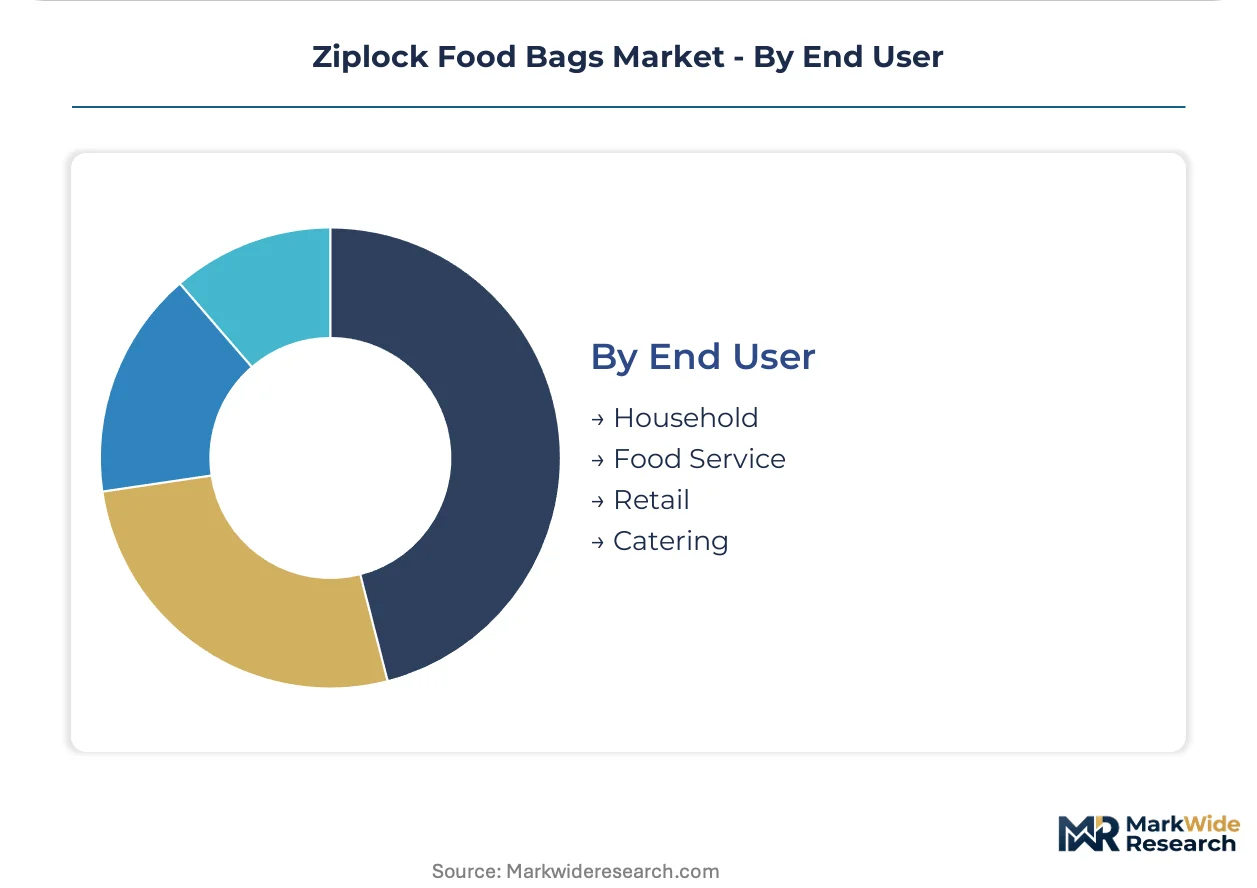
Ziplock food bags serve divergent performance requirements across temperature extremes, regulatory jurisdictions, and automation compatibility. Segmentation reveals where material investments concentrate and which specifications command procurement priority in contract negotiations.
Product Type:
After-sales service intensity varies sharply by product type, with freezer bag failures triggering immediate supply chain disruption for food service operators while sandwich bag defects permit substitution.
- Freezer Bags:Multi-layer polyethylene constructions incorporate ethylene-vinyl acetate for low-temperature flexibility down to negative twenty degrees Fahrenheit. Quick-service chains in Minnesota and Wisconsin specify these for protein inventory staging where bag failure causes direct spoilage losses.
- Gallon Bags:Thicker gauge specifications—typically three to four mil—support marinades and brined poultry processing in commercial kitchens. Texas and Florida restaurant clusters drive volume through bulk ingredient prep standardization.
- Sandwich Bags:Single-ply low-density polyethylene dominates household consumption with minimal barrier requirements. Retail shelf placement in California and New York mass merchandisers determines brand visibility.
- Snack Bags:Smaller format dimensions target portion-controlled retail packaging and school lunch programs. USDA school nutrition guidelines in Illinois and Pennsylvania shape specifications.
By volume, sandwich bags lead. By growth pace, freezer bags are climbing the fastest.
Material:
Cost tier stratification separates virgin resin formulations from certified compostable alternatives, with price spreads determining accessibility for budget-constrained food service accounts.
- Biodegradable:Polylactic acid and polyhydroxyalkanoate formulations achieve ASTM D6400 certification for industrial composting. Oregon and Washington food service operators face procurement mandates under state extended producer responsibility frameworks.
- Polyethylene:Linear low-density and low-density variants provide moisture barrier performance at lowest unit cost. Permian Basin ethane feedstock proximity advantages concentrate converter capacity in Texas and Louisiana.
- Plastic:General-purpose petroleum-based films without specialized barrier additives serve price-sensitive retail channels. Dollar store distribution networks in Ohio and Georgia absorb significant volume.
- PVC:Chlorinated formulations persist in specific medical and industrial food packaging applications despite environmental pressure. FDA 21 CFR compliance requirements limit expansion into general food contact uses.
By volume, polyethylene dominates. By margin expansion, biodegradable materials are gaining share fastest.
Closure Type:
Application environment dictates closure selection, with automated processing lines imposing dimensional tolerances that manual sealing applications ignore.
- Slider Seal:Polypropylene track mechanisms enable one-handed operation in food service environments where glove protocols complicate pinch-seal alternatives. Chipotle and Sweetgreen prep line robotics specify slider formats for consistent handling geometry.
- Zip Seal:Interlocking polyethylene ridges provide repeatable airtight performance across temperature cycling. Residential freezer storage in Michigan and Colorado households sustains baseline demand.
- Press Seal:Adhesive-free cohesive films target single-use applications where reclosability is unnecessary. Meal-kit fulfillment centers in New Jersey and California utilize these for non-refrigerated dry ingredient pouches.
- Adhesive Seal:Pressure-sensitive strips enable tamper-evident packaging for retail sale environments. Convenience store distributors in Arizona and Nevada specify these for grab-and-go food merchandise.
By volume, zip seal leads. By automation compatibility, slider seal is expanding most quickly.
End User:
Customer type determines specification complexity, with food service accounts demanding lot traceability and household buyers prioritizing shelf price.
- Food Service:National restaurant chains impose uniform specifications across franchise networks, requiring converters to maintain multi-state distribution capability. Sysco and US Foods private-label programs concentrate purchasing power.
- Household:Brand loyalty and retail placement drive selection in supermarket and mass merchandiser channels. SC Johnson's Ziploc brand controls premium shelf positioning in Walmart and Target stores.
- Retail:Private-label programs at Kroger, Albertsons, and Ahold Delhaize capture price-sensitive consumers through promotional pricing cycles. Store brand penetration runs highest in Indiana and Missouri markets.
- Catering:Event-based demand fluctuates seasonally, with wedding and corporate event planners in California and Florida specifying premium formats for presentation value.
By volume, household leads. By contract value concentration, food service is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains a substantial export surplus in polyethylene film formulations while importing specialized biodegradable resins from European and Asian suppliers. Germany and China balance net-neutral trade positions through integrated resin-to-converter operations. India and Brazil remain net importers of high-performance barrier films for food service applications.
United States
Meal-kit fulfillment networks in New Jersey and California drive standardized ziplock bag procurement at scale. The EPA oversees resin manufacturing emissions while state-level extended producer responsibility frameworks in California and New York force design-for-recyclability investments. Texas and Louisiana host the densest converter clusters due to Permian Basin ethane feedstock proximity.
Germany
Industrial food processing automation in Bavaria and Baden-Württemberg specifies precision-seal formats for ingredient staging. REACH restrictions on intentionally added microplastics compel reformulation of slip agents and anti-block compounds. The North Rhine-Westphalia chemical corridor anchors European bioplastic resin development for certified compostable alternatives.
China
Quick-service restaurant expansion in Shanghai and Shenzhen adopts portion-control packaging protocols from Western franchise operators. The Ministry of Ecology and Environment enforces dual carbon goals that accelerate polylactic acid film investments. The Yangtze River Delta concentrates extrusion equipment manufacturing and biodegradable resin pilot production.
India
Food service modernization in Mumbai and Bangalore creates demand for standardized ziplock formats previously uncommon in domestic markets. The Food Safety and Standards Authority of India regulates food-contact materials under evolving compliance timelines. Gujarat's petrochemical corridor supplies virgin polyethylene while Maharashtra converters experiment with imported biodegradable formulations.
Brazil
Supermarket private-label expansion in São Paulo and Rio de Janeiro absorbs volume from price-sensitive household segments. The National Health Surveillance Agency enforces food-contact substance regulations that lag European stringency. The São Paulo state industrial belt hosts South America's largest flexible packaging converter concentration.
Ziplock Food Bags Market Competitive Landscape
On the supply side, the industry is consolidating around resin-integrated conglomerates and brand-differentiated consumer goods specialists. Mid-sized regional converters face capital barriers to biodegradable material transitions while asset-light leasing models for extrusion equipment tilt competitive dynamics toward flexible entrants. Three strategic archetypes dominate: vertically integrated resin-to-film operators, retail brand equity holders, and private-label contract manufacturers. Capacity expansion in biodegradable resin compounding and strategic partnerships with meal-kit fulfillment networks represent the dominant competitive moves.
Within the integrated-resin tier, Berry Global Inc. and Novolex exemplify supply chain control through captive polyethylene production and recycling operations. SC Johnson & Son, Inc. anchors the brand-differentiated segment through retail shelf presence that commands premium positioning in household channels. These three companies illustrate how scale, integration depth, and consumer recognition create defensible positioning against commodity converter competition.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Novolex |
| SC Johnson & Son, Inc. |
| Minigrip LLC |
| Poly-America, L.P. |
| The Glad Products Company |
| Inteplast Group, Ltd. |
| Sealed Air Corporation |
| Reynolds Consumer Products LLC |
| Others |
Pricing and Supply Chain Analysis
Permian Basin ethane feedstock concentration anchors polyethylene cost curves and compresses margin visibility for converters outside Texas and Louisiana. Biodegradable resin premiums of three to five times virgin polyethylene spreads concentrate margin pools among certified compostable suppliers with ASTM D6400 validation.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures with volume-tiered discounts. Three-tier pricing structure across premium, standard, and economy levels separates certified compostable films from virgin polyethylene and generic plastic alternatives. Cost compression in standard polyethylene tiers is intensifying because Permian Basin supply proximity advantages disadvantage distant converters. Food service procurement teams at Sysco and US Foods exhibit highest price sensitivity, while sustainability-mandated corporate accounts absorb biodegradable premiums with minimal negotiation.
Supply Chain Analysis
Tariff exposure between China and the United States dominates raw material sourcing risk for polylactic acid resin imports. Supply concentrates in the United States for polyethylene extrusion, China for biodegradable resin pilot production, and Germany for compostable film innovation. Raw material dependencies center on ethane feedstock from Permian Basin natural gas liquids, imported polylactic acid from Yangtze River Delta producers, and oxygen scavenger additives from specialty chemical suppliers. Single-source vulnerability in certified compostable resin channels threatens converters facing California SB 54 compliance deadlines. Distribution runs through direct-to-restaurant e-procurement platforms and traditional broadline distributors serving multi-state franchise networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
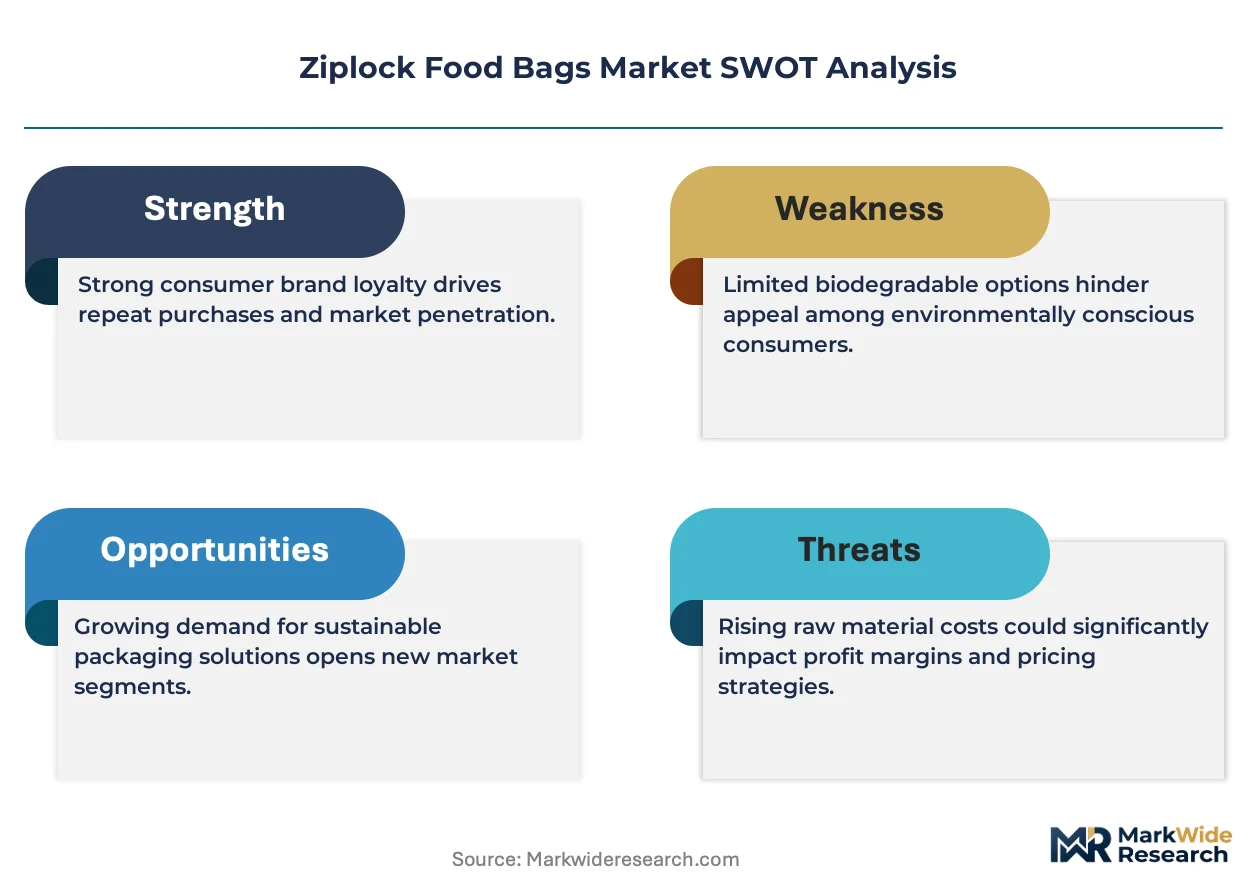
This market functions as a defensive-moat story where regulatory entrenchment creates durable positioning. Extended producer responsibility frameworks in California and New York impose switching costs that lock converters into compliance-validated supply relationships.
For Market Incumbents: Insulate market position through captive resin compounding capacity in Texas and Louisiana to offset Permian Basin proximity advantages held by Berry Global and Novolex. Deepen backward integration into mechanical recycling operations to secure post-consumer feedstock for circular product lines. The threat of asset-light leasing models for extrusion equipment enabling mid-sized converter entry demands preemptive capacity discipline. For New Entrants and Emerging Players: Build out biodegradable film production targeting Oregon and Washington food service procurement mandates under state extended producer responsibility frameworks. The most penetrable white space sits in certified compostable gallon bags for quick-service restaurant protein staging, where incumbent capacity constraints delay product launches. A direct-to-restaurant e-procurement partnership with WebstaurantStore or similar digital wholesalers offers channel access without broadline distributor margin capture. For Investors and Strategic Acquirers: Capital is best deployed toward converters with validated ASTM D6400 certification and established meal-kit fulfillment network relationships. Long-term viability across the next decade rests on regulatory compliance entrenchment rather than commodity scale. The signal to watch is California SB 54 enforcement velocity and industrial composting facility buildout rates in Pacific Northwest markets.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Resin Capacity Expansion | ASTM D6400 certification delays 18-24 months reward early movers with compliance advantages. |
| Backward Integration into Recycling | Post-consumer polyethylene feedstock secures circular product lines for California EPR mandates. |
| Meal-Kit Fulfillment Partnership | HelloFresh and Blue Apron standardization locks in volume across North American distribution networks. |
| Direct-to-Restaurant E-Procurement Launch | WebstaurantStore private-label capture displaces traditional broadline distributor margin pools. |
| Sustainability Repositioning | USDA BioPreferred procurement mandates create guaranteed offtake for federal cafeteria and military commissary channels. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with food service procurement directors at national restaurant chains, extrusion equipment operators at mid-sized converters, resin compounding technical leads, and retail category buyers at mass merchandisers. Secondary validation drew from FDA 21 CFR food-contact substance filings, EPA resin manufacturing emissions disclosures, California SB 54 implementation guidance, and trade data on polyethylene film imports. Bottom-up volume estimates from converter capacity utilization and top-down demand segmentation from food service operator procurement patterns were triangulated to reconcile output figures.
Calibration against historical pricing spreads between virgin and biodegradable resins anchored growth rate derivation across the analysis window. Segmentation dimensions modeled include product type, material certification tier, closure mechanism, and end-user procurement channel, with additional granularity on state-level regulatory compliance clusters. CAGRs were computed from year-over-year progression of volume and value estimates. Industry-specific forecast inputs incorporated meal-kit fulfillment network expansion rates and industrial composting facility coverage maps.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by polylactic acid resin producers or accelerated California enforcement timelines would shift outcomes materially. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Bulk Bag Conditioners Market
Bags and Containers
Tamper Evident Bag Sealers Market
Bags and Containers
Waterproof Bags Market
Bags and Containers
Crates Market
Bags and Containers
Cassava Bags Market
Bags and Containers
Multiwall Bags Market
Bags and Containers
Bag in Drum Market
Bags and Containers
Global Bag Filling Machines Market
Bags and Containers
Padding Bags Market
Bags and Containers
Lawn and Leaf Bags Market
Bags and Containers
Frosted Bag Market
Bags and Containers
Anti-Corrosion Bags Market
Bags and Containers
Refuse Bags Market
Bags and Containers
Side Gusset/Quad Seal Bag Market
Bags and Containers
Wicketless Bags Market
Bags and Containers
Drum Liners Market