
 Global Plastic Surgery and Integumentary System Procedures Market | 2026-2036
Global Plastic Surgery and Integumentary System Procedures Market Size, Share, and Industry Trends Forecast 2026-2036
Global Plastic Surgery and Integumentary System Procedures Market Foresight
Procedure bundling into all-inclusive aesthetic packages is consolidating buyer choice across the value chain. AbbVie Inc. leverages its integrated portfolio spanning injectables and surgical devices to anchor premium positioning. Johnson & Johnson sustains broad channel access through its established hospital and ambulatory surgical center relationships. Galderma competes on dermatology-specialized injectable formulations that differentiate beyond commodity fillers.
Plastic surgery and integumentary system procedures encompass surgical and non-surgical interventions that modify, restore, or enhance skin, subcutaneous tissue, and associated structures through mechanical, thermal, or pharmacological means, typically employing energy-based devices with wavelength-specific parameters or biocompatible implantable materials. These interventions serve reconstructive purposes following trauma or congenital conditions, alongside elective cosmetic applications where patient-reported aesthetic outcomes drive commercial value. Injectable fillers and laser therapy command disproportionate margin pools due to recurring treatment cycles and lower capital requirements compared to surgical alternatives. Breast augmentation and liposuction retain mature volume positions but face slower growth as non-invasive modalities capture patient preference shifts. Radiofrequency and cryolipolysis represent the fastest-expanding technology categories, fueled by minimal downtime protocols and expanding dermatology clinic adoption.
FDA premarket notification pathways and EU MDR conformity assessment frameworks govern device safety and clinical evidence requirements, while HIPAA and GDPR provisions constrain patient data utilization for marketing and outcome tracking. These regulatory layers elevate compliance costs for manufacturers but simultaneously create barriers that favor established players with dedicated regulatory affairs infrastructure. Stakeholders must monitor evolving reimbursement classifications for reconstructive versus cosmetic indications, as payor policy decisions will reshape addressable patient populations and procedure mix across delivery settings.
Market Dynamics
Minimally invasive modalities are compressing surgical procedure volumes as energy-based devices and biologic injectables capture patient preference shifts toward reduced downtime and lower complication profiles.
Growth Catalysts
- EU MDR Conformity Assessment:Tighter clinical evidence requirements for implantable devices elevate quality standards that favor manufacturers with robust regulatory infrastructure, filtering out marginal competitors.
- Radiofrequency Technology:Non-ablative skin tightening protocols expand addressable patient populations beyond traditional surgical candidates into preventive aesthetic maintenance segments.
- South Korea:Concentrated medical tourism flows and government-supported K-beauty export initiatives position Seoul as a procedure innovation hub attracting cross-border patient demand.
Market Restraints
- Hyaluronic Acid Feedstock Volatility:Pharmaceutical-grade raw material sourcing concentrates among limited European and Japanese suppliers, exposing filler manufacturers to input cost instability.
- FDA Premarket Notification Friction:510(k) pathway documentation requirements for novel energy-based devices extend clearance timelines, compressing first-mover advantage windows.
- Non-Invasive Substitution:Cryolipolysis and high-intensity focused ultrasound modalities capture body contouring volumes previously directed toward liposuction surgical suites.
Strategic Opportunities
- Brazil:Underpenetrated secondary cities outside São Paulo and Rio de Janeiro present whitespace for ambulatory clinic network expansion targeting middle-income aesthetic consumers.
- Telemedicine Pre-Consultation:Digital patient screening workflows reduce in-person evaluation burden while expanding geographic reach for specialized reconstructive surgeons.
- AI-Assisted Surgical Planning:Machine learning algorithms for outcome prediction and implant sizing converge with 3D imaging to differentiate premium service tiers.
Industry Challenges
- Interventional Radiology Skill Migration:Energy-based device operation requires cross-training between dermatology and surgical disciplines, creating credentialing bottlenecks.
- Biocompatibility Certification Lag:Novel synthetic fillers face extended ISO 10993 testing timelines that delay commercialization against established hyaluronic acid formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Plastic Surgery and Integumentary System Procedures Market |
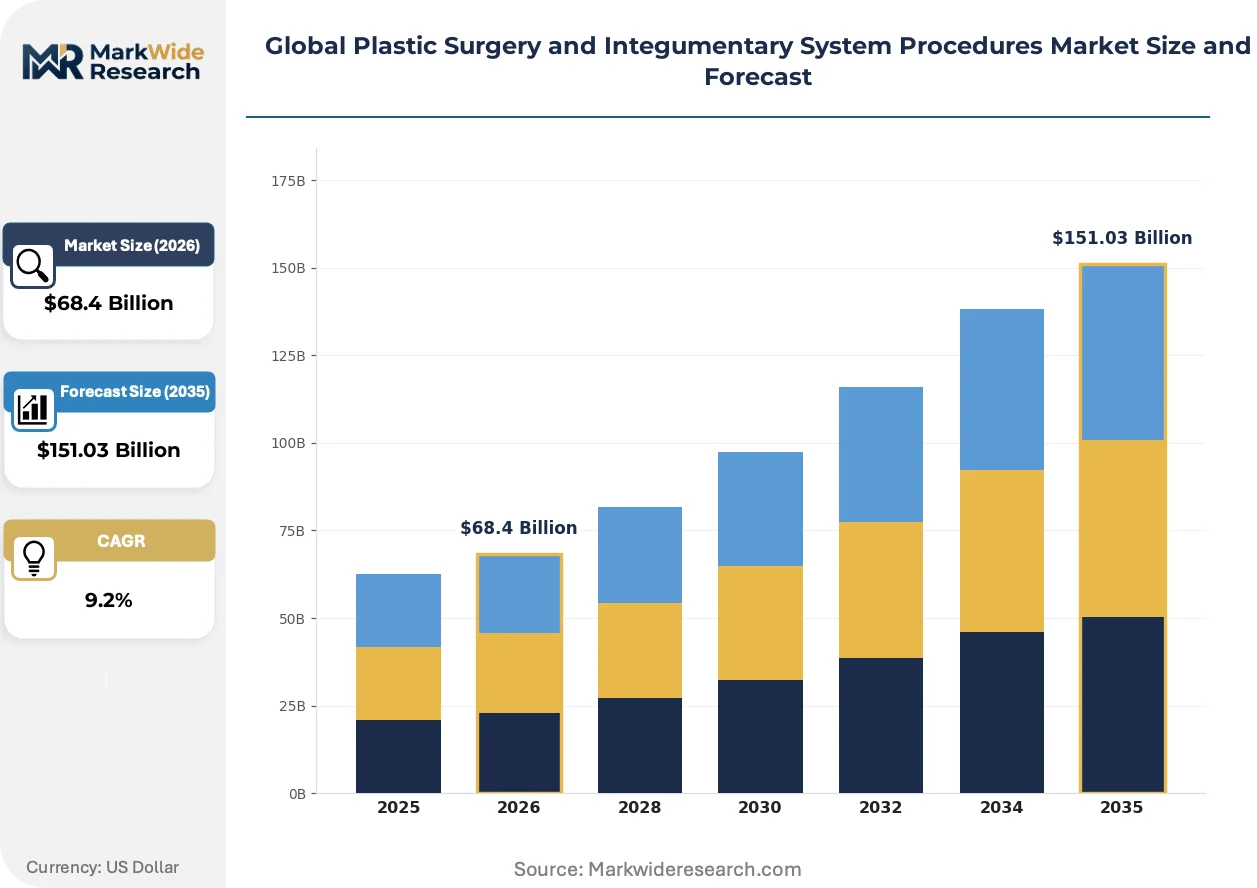
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $151.03 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Rhinoplasty, Liposuction, Hair Transplant, Breast Augmentation, Abdominoplasty, Facelift Technology: Laser Therapy, Ultrasound-Assisted Surgery, Radiofrequency, Cryolipolysis, Injectable Fillers, Platelet-Rich Plasma Application: Scar Revision, Skin Tightening, Burn Treatment, Cellulite Reduction, Wrinkle Removal, Tattoo Removal End User: Private Clinics, Specialty Hospitals, Cosmetic Centers, Ambulatory Surgical Centers, Dermatology Clinics, Aesthetic Institutes |
| Companies Covered | AbbVie Inc., Johnson & Johnson, Galderma, Merz Pharma, Bausch Health Companies Inc., Sientra Inc., Lumenis Ltd, Hologic Inc., Alma Lasers Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Plastic Surgery and Integumentary System Procedures Market Shifts & Advancements
Device miniaturization and algorithmic treatment personalization are collapsing the boundary between clinical-grade and consumer-accessible aesthetic interventions.
Microfocused ultrasound with visualization is electrifying non-surgical lifting protocols by enabling precise depth-targeted energy delivery without epidermal damage. High-volume dermatology chains in the United States deploy these systems at weekly utilization rates exceeding traditional laser platforms. The technology is electrifying margin structures by reducing consumable costs per procedure while commanding premium pricing against older radiofrequency modalities.
GDPR Article 9 restrictions on special category health data constrain European providers from deploying predictive analytics for patient outcome marketing. This regulatory friction redirects investment toward anonymized aggregate benchmarking platforms rather than individualized retention algorithms. German and French clinic networks respond by consolidating into larger entities capable of sustaining dedicated data protection officer functions.
Subscription-based maintenance programs displace episodic procedure purchasing among millennial and Generation Z aesthetic consumers. United States med-spa chains unbundle traditional consultation fees into monthly access tiers that include preventive toxin and filler touch-ups. This behavioral pivot concentrates patient lifetime value capture while compressing competitor switching opportunities.
Global Plastic Surgery and Integumentary System Procedures Market Segmentation
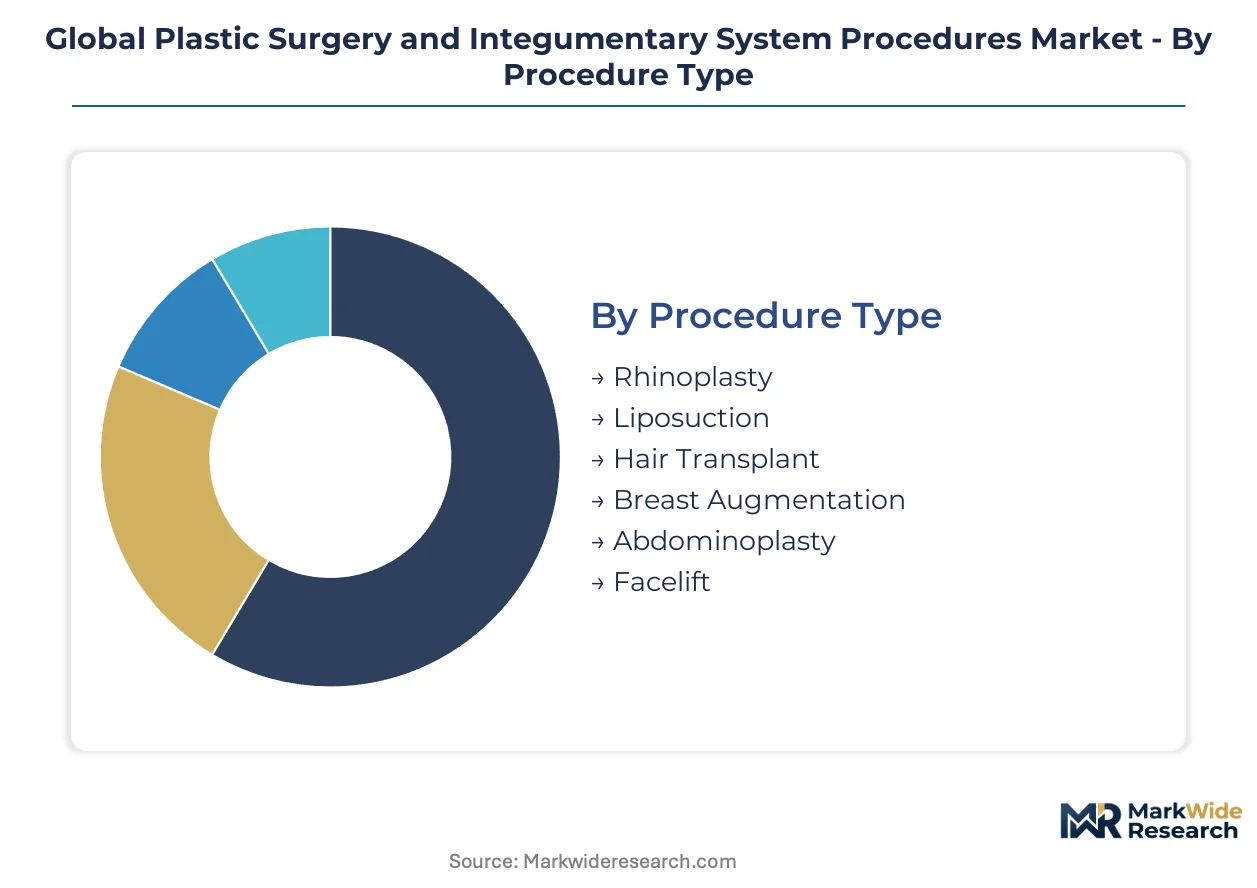
Segmentation in plastic surgery and integumentary procedures reveals divergent margin structures between capital-intensive surgical suites and consumable-driven non-invasive modalities. Procedure mix directly determines equipment depreciation schedules, staff credentialing requirements, and patient recurrence patterns across delivery settings.
Procedure Type:
Volume concentration clusters in mature surgical interventions, while premium expansion concentrates in minimally invasive alternatives that compress recovery windows.
- Liposuction:Suction-assisted lipectomy with tumescent anesthesia protocols remains the reference standard for adipose tissue reduction. Demand concentrates in Brazil and the United States, where high-volume ambulatory centers achieve economies of scale through standardized cannula sets and compression garment bundling.
- Breast Augmentation:Silicone and saline implant placement procedures require specialized operative facilities with overnight observation capabilities. South Korea's cosmetic surgery district in Seoul Gangnam anchors premium pricing through concierge recovery services and implant customization workflows.
- Rhinoplasty:Nasal structural modification combining osseocartilaginous sculpting with functional airway preservation.
- Hair Transplant:Follicular unit extraction and direct hair implantation techniques for androgenetic alopecia correction.
- Abdominoplasty:Panniculectomy with rectus plication for post-bariatric body contouring.
- Facelift:Superficial musculoaponeurotic system suspension procedures targeting gravitational tissue descent.
Mature deployment sits with Liposuction. Newer deployment is concentrated in Hair Transplant techniques leveraging automated extraction devices.
Technology:
Capital equipment intensity varies dramatically between laser platforms requiring six-figure investments and consumable-heavy injectable modalities with minimal fixed asset requirements.
- Injectable Fillers:Cross-linked hyaluronic acid and calcium hydroxylapatite formulations delivered via microneedle injection for volume restoration and wrinkle effacement. United States med-spa chains deploy these at weekly volumes exceeding surgical scheduling capacity, with hyaluronic acid variants commanding recurring maintenance cycles.
- Radiofrequency:Monopolar and bipolar energy delivery systems generate dermal collagen remodeling through controlled thermal injury. Adoption concentrates in German dermatology networks seeking non-ablative alternatives to fractional laser resurfacing under stricter EU MDR device classification requirements.
- Laser Therapy:Ablative and non-ablative wavelength-specific platforms for epidermal resurfacing and chromophore targeting.
- Ultrasound-Assisted Surgery:Microfocused and high-intensity focused ultrasound for non-invasive lifting and fat reduction.
- Cryolipolysis:Controlled adipocyte cooling for non-surgical fat reduction through apoptotic clearance mechanisms.
- Platelet-Rich Plasma:Autologous growth factor concentrates for hair restoration and tissue regeneration protocols.
Established infrastructure dominates Laser Therapy installations. Steepest expansion trajectory belongs to Cryolipolysis as clinic chains deploy compact tabletop units.
Application:
Reconstructive indications carry reimbursement eligibility that cosmetic applications lack, creating divergent patient access and pricing elasticity across indication categories.
- Skin Tightening:Collagen induction and neocollagenesis protocols addressing dermal laxity through thermal or mechanical stimulation. Demand concentrates in Japan's aging demographic segments, where preventive aesthetic maintenance displaces delayed surgical intervention.
- Wrinkle Removal:Neuromodulator and filler combinations targeting dynamic and static rhytides. United States cosmetic centers achieve highest patient throughput through toxin injection protocols with 15-minute chair times.
- Scar Revision:Surgical and laser modalities for traumatic or postsurgical scar texture and color improvement.
- Burn Treatment:Acute and reconstructive interventions for thermal injury sequela including contracture release.
- Cellulite Reduction:Subcision and energy-based approaches to fibrous septae disruption.
- Tattoo Removal:Q-switched and picosecond laser platforms for exogenous pigment fragmentation.
Reimbursement-supported volume concentrates in Burn Treatment. Purely cosmetic demand is climbing fastest in Cellulite Reduction as device manufacturers target previously underserved patient complaints.
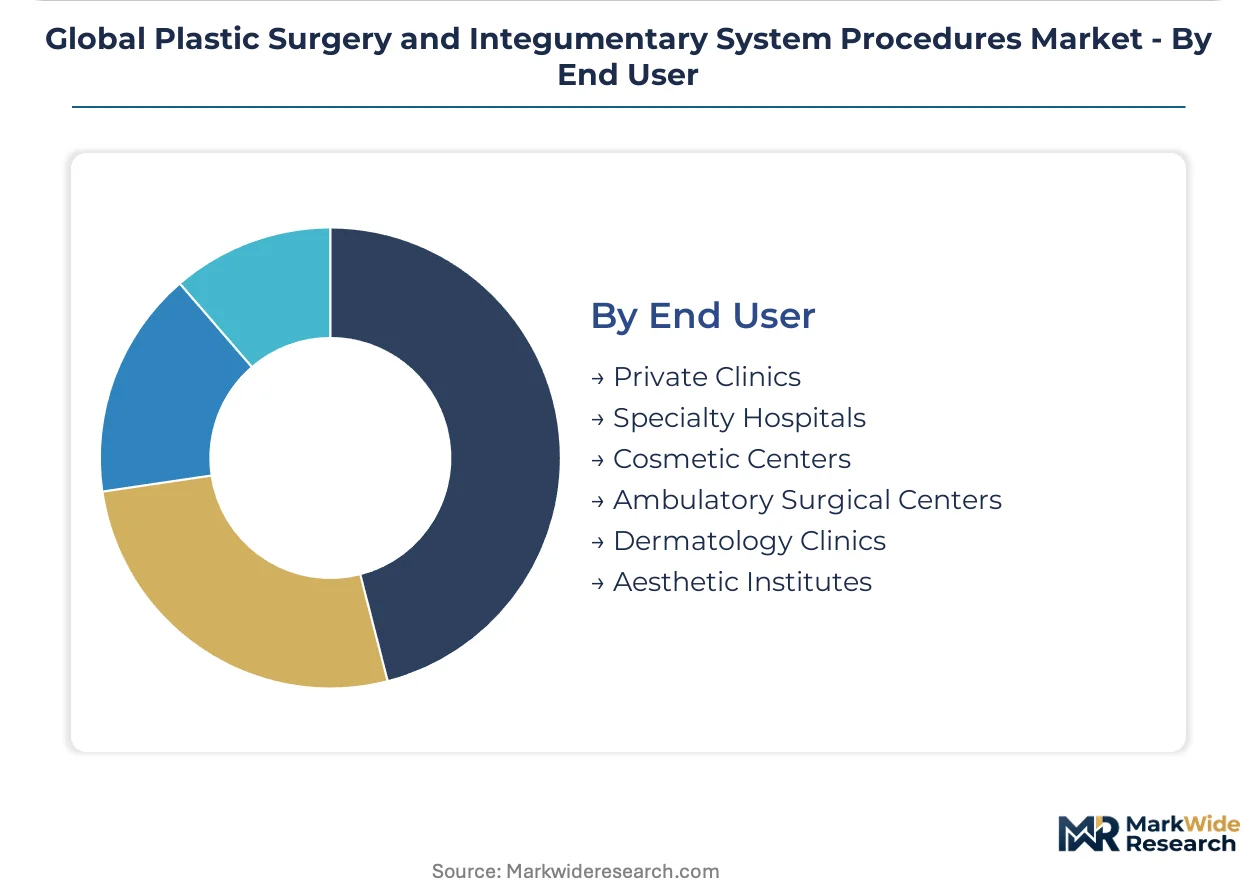
End User:
Facility type determines regulatory oversight intensity, with hospital-based settings facing Joint Commission or national equivalent scrutiny absent from standalone cosmetic centers.
- Cosmetic Centers:Dedicated aesthetic medicine facilities combining surgical and non-surgical service lines under unified brand positioning. South Korea's concentration of multi-story cosmetic surgery complexes in Seoul achieves patient volume density unmatched in Western markets.
- Private Clinics:Physician-owned practices with direct control over procedure mix and pricing architecture. Brazil's São Paulo and Rio de Janeiro house established networks now expanding into secondary cities.
- Specialty Hospitals:Acute care institutions with plastic surgery departments handling complex reconstructive caseloads.
- Ambulatory Surgical Centers:Medicare-certified facilities optimized for same-day discharge surgical protocols.
- Dermatology Clinics:Skin-specialty practices emphasizing non-invasive energy-based and injectable modalities.
- Aesthetic Institutes:Training-affiliated centers combining patient care with resident and fellow education missions.
Institutional maturity clusters in Specialty Hospitals. Capacity expansion is concentrating in Dermatology Clinics as equipment miniaturization enables office-based deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device manufacturing concentrates in Germany, Israel, and the United States, while procedure demand clusters in South Korea, Brazil, and the United States. This geographic split creates distinct regulatory exposure profiles across the value chain.
United States
FDA 510(k) clearance pathways govern energy-based device commercialization timelines. Cosmetic centers in Los Angeles and Miami achieve patient volume density through bundled aesthetic packages combining surgical and non-surgical modalities. The concentration of ambulatory surgical centers in Florida and California compresses pricing for mature procedures like liposuction.
South Korea
MFDS device registration requirements align with international standards while maintaining shorter review windows than FDA pathways. Seoul's Gangnam district anchors global medical tourism flows through multi-story cosmetic surgery complexes offering concierge recovery services. Government-backed K-beauty export initiatives extend domestic procedure innovations into cross-border patient markets.
Brazil
ANVISA medical device regulations require in-country testing for implantable materials, extending market entry timelines for foreign manufacturers. São Paulo and Rio de Janeiro house established private clinic networks now expanding into underpenetrated secondary cities. Middle-income aesthetic consumers in Belo Horizonte and Curitiba drive ambulatory clinic network formation.
Germany
EU MDR conformity assessment frameworks impose stricter clinical evidence requirements for implantable devices than predecessor directives. Dermatology networks in Munich and Hamburg deploy radiofrequency platforms as non-ablative alternatives under tighter device classification rules. Data protection officer mandates under GDPR Article 9 redirect clinic investment toward anonymized benchmarking platforms.
Israel
Ministry of Health medical device regulations facilitate rapid prototype-to-clinical validation cycles for energy-based technologies. Tel Aviv's medical technology cluster specializes in ultrasound-assisted and laser platform development. Startups in this ecosystem supply OEM components to larger multinational device manufacturers.
Global Plastic Surgery and Integumentary System Procedures Market Competitive Landscape
The competitive structure tilts toward diversified pharmaceutical conglomerates with aesthetic medicine divisions. Market concentration remains moderate, with established players leveraging regulatory infrastructure as a moat against emerging competitors. Three archetypes dominate: integrated pharmaceutical-aesthetic portfolios, pure-play dermatology specialists, and energy-based device manufacturers. Portfolio diversification and strategic geographic expansion constitute the primary competitive moves, as players seek to capture recurring revenue from injectable maintenance cycles.
Among integrated pharmaceutical conglomerates, AbbVie Inc. and Johnson & Johnson occupy positions spanning injectables and surgical devices. Galderma represents the dermatology-specialized archetype with concentrated expertise in biocompatible formulations. These three companies exemplify distinct strategic postures: AbbVie leverages cross-portfolio bundling, Johnson & Johnson exploits hospital channel relationships, and Galderma competes through formulation differentiation beyond commodity fillers.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Johnson & Johnson |
| Galderma |
| Merz Pharma |
| Bausch Health Companies Inc. |
| Sientra Inc. |
| Lumenis Ltd |
| Hologic Inc. |
| Alma Lasers Ltd |
| Others |
Supply & Pricing Matrix
Pharmaceutical-grade hyaluronic acid feedstock indices cascade through three-tier pricing structures separating Seoul Gangnam concierge centers from São Paulo ambulatory clinics and Belo Horizonte economy-tier providers, with raw material volatility compressing margins most acutely at consumable-heavy injectable formulations.
Pricing Analysis
Margin tightening in premium surgical tiers reflects EU MDR certification costs and extended implant approval timelines, while cost-down pressure accelerates across standard dermatology clinic tiers as cryolipolysis device commoditization intensifies. Three-tier pricing stratifies across premium concierge recovery bundles, standard ambulatory surgical center packages, and economy-tier standalone toxin injection protocols. Brand premium and MFDS/FDA certification tier differentiation separate AbbVie and Galderma positioning from regional filler manufacturers. Middle-income Brazilian consumers in secondary cities exhibit highest price sensitivity; Seoul medical tourism patients demonstrate lowest elasticity due to bundled K-beauty export packaging.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Miami anchor hub-and-spoke patterns for temperature-sensitive biologic shipments. Manufacturing concentrates in Germany for laser platforms, Israel for ultrasound-assisted devices, and Switzerland for pharmaceutical-grade hyaluronic acid fermentation. Raw material dependencies center on Japanese and European suppliers for cross-linked filler feedstocks, German optical components for fractional laser systems, and Israeli semiconductor substrates for energy-delivery controllers. Single-source vulnerability concentrates in pharmaceutical-grade sodium hyaluronate purification capacity. Distribution runs through specialized medical device logistics networks with cold-chain requirements for autologous biologic products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around regulatory infrastructure moats, with EU MDR conformity assessment costs and FDA 510(k) documentation burdens forcing marginal device manufacturers toward exit or acquisition.
For Market Incumbents: Lock in cross-portfolio bundling advantages by anchoring injectable maintenance subscriptions to surgical device placements, while deepening backward integration into hyaluronic acid feedstock through captive supply agreements with European fermentation specialists. Channel control through hospital GPO contracts and ambulatory surgical center preferred vendor status defends against emerging energy-based device entrants from Tel Aviv clusters. For New Entrants and Emerging Players: The premium-to-economy price gap in Brazilian secondary cities opens whitespace for compact cryolipolysis tabletop units targeting Belo Horizonte and Curitiba middle-income consumers. Telemedicine pre-consultation workflows and AI-assisted surgical planning software companions offer the most penetrable entry vectors against established Seoul and Los Angeles cosmetic center networks. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap dermatology clinic networks in Germany facing GDPR Article 9 compliance cost burdens, with consolidation plays targeting entities with established data protection officer functions. Long-term viability hinges on recurring revenue capture from millennial and Generation Z subscription-based maintenance programs. Watch MFDS regulatory pathway acceleration as inflection signal for Korean medical tourism recovery velocity.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Conformity Assessment Acceleration | Streamlined CE marking pathways compress time-to-revenue for German laser platform manufacturers against FDA timelines. |
| Backward Integration into Hyaluronic Acid Feedstock | Captive fermentation capacity insulates AbbVie and Galderma from Japanese supplier price volatility and allocation constraints. |
| Subscription-Based Maintenance Program Launch | Monthly toxin and filler access tiers concentrate patient lifetime value capture among United States millennial med-spa consumers. |
| AI-Assisted Surgical Planning Software Development | Machine learning outcome prediction differentiates premium service tiers for Seoul Gangnam cosmetic surgery complexes. |
| Telemedicine Pre-Consultation Platform Deployment | Digital screening workflows expand geographic reach for specialized reconstructive surgeons beyond traditional catchment areas. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with cosmetic center operations directors, hospital purchasing committee members, biomedical engineers at energy-based device manufacturers, and GPO contracts managers. FDA 510(k) premarket notification databases, MFDS medical device registration filings, ANVISA implantable material approval records, and EU MDR notified body certificates provided segmentation validation. Bottom-up procedure volume estimates from ambulatory surgical center utilization data reconciled with top-down pharmaceutical company aesthetic division revenue disclosures.
Data-stream reconciliation across implant unit shipments, energy-based device installation records, and injectable filler volume reports calibrated analytical frameworks across the projection horizon. Segmentation dimensions modeled encompassed procedure type, technology platform, application indication, and end-user facility category. CAGRs derived from weighted average of historical growth trajectories and technology substitution elasticity parameters, with specific inputs from radiofrequency device adoption curves and cryolipolysis clinic chain expansion rates.
Inputs from MFDS, FDA, and ANVISA regulatory databases were available through the study window; gaps in real-time ambulatory surgical center pricing transparency introduce uncertainty bands around volume forecasts. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Surgery
Asia-Pacific Cosmetic Surgery Market
Cosmetic Surgery
Global Mastopexy Market
Cosmetic Surgery
Rhytidectomy Market
Cosmetic Surgery
Japan Cosmetic Surgery Market
Cosmetic Surgery
Global Blepharoplasty Market
Cosmetic Surgery
Cosmetic Surgery Market
Cosmetic Surgery
Rhinoplasty Market
Cosmetic Surgery
Dimpleplasty Market
Cosmetic Surgery
Germany Cosmetic Surgery Market
Cosmetic Surgery
Saudi Arabia Cosmetic Surgery Market
Cosmetic Surgery
France Cosmetic Surgery Market
Cosmetic Surgery
Reconstructive Surgery Market
Cosmetic Surgery
Minimally Invasive Cosmetic Procedures Market
Cosmetic Surgery
India Cosmetic Surgery Market
Cosmetic Surgery
Cosmetic Surgery and Services Market
Cosmetic Surgery
Liposuction Market