
 Incontinence Skin Care Products Market | 2026-2036
Incontinence Skin Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Incontinence Skin Care Products Market Outlook
Aftermarket service revenue is reconfiguring competitive economics in incontinence skin care as recurring replenishment models displace one-time transactions. Coloplast A/S anchors its position through deep clinical channel relationships across European home care networks. Essity leverages its tissue and hygiene scale to sustain manufacturing cost advantages in barrier creams and cleansing wipes. Kimberly-Clark competes through brand strength in North American retail pharmacy and institutional procurement channels.
Incontinence skin care products encompass topical formulations and absorbent accessories engineered to prevent moisture-associated skin damage, typically incorporating petrolatum-based barriers, pH-balanced cleansers, and zinc oxide composites manufactured under cosmetic or medical device quality systems. Their primary commercial purpose centers on reducing dermatitis incidence among patients with urinary or fecal incontinence, thereby lowering wound care burdens and antimicrobial exposure in care settings. Barrier creams capture concentrated margin pools due to prescription-adjacent positioning and clinical endorsement requirements, while skin cleansing wipes represent the fastest-growing product type as protocol standardization spreads across nursing homes and rehabilitation centers. The end user base tilts toward institutional channels where bundled procurement contracts dominate, though home care direct-to-consumer sales are expanding through online retail subscription mechanics.
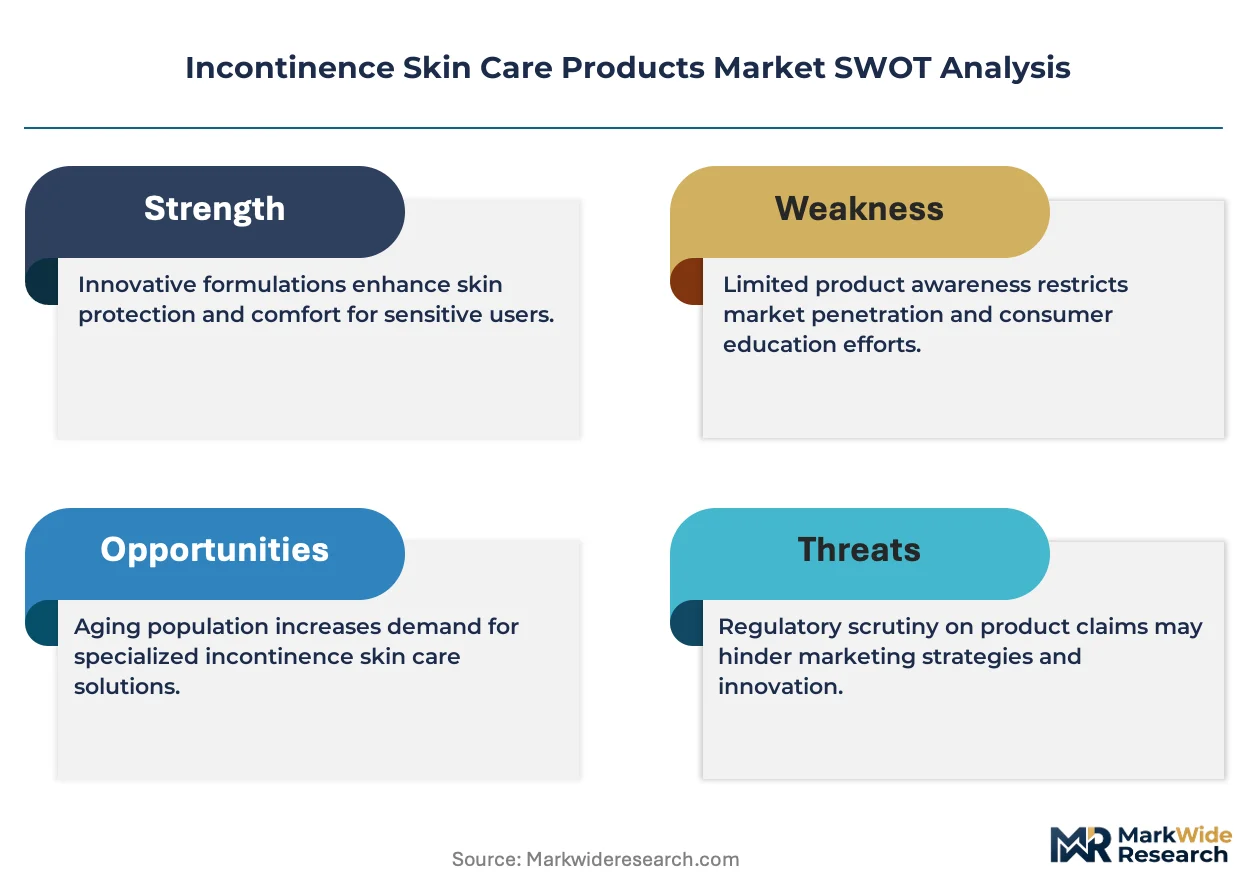
The U.S. FDA oversees medical device classifications for certain barrier and protective products, while the EPA regulates antimicrobial claims in cleansing formulations, and the EU MDR and REACH frameworks govern market access for European manufacturers. These regulatory layers elevate compliance costs but simultaneously create defensible positions for firms with established quality management systems and dossier histories. Stakeholders must monitor evolving dermatological evidence standards and reimbursement coding shifts that could recategorize products between cosmetic and medical benefit tiers.
Market Dynamics
Recurring replenishment mechanics are compressing transaction economics across the incontinence skin care value chain, forcing manufacturers to rebuild revenue models around subscription fulfillment and institutional contract renewals rather than discrete product sales.
Growth Catalysts
- EU MDR compliance timelines:Medical device reclassification of barrier creams in Europe is accelerating dossier investments by established manufacturers, raising barriers to entry for cosmetic-grade competitors.
- Long-term care acuity escalation:Rising resident complexity in nursing facilities across Germany and Japan is expanding protocol-driven skin care regimens beyond basic hygiene into clinical prevention.
- Zinc oxide nanoformulation:Advanced particle engineering is improving barrier film durability while reducing application frequency, lowering labor burden for understaffed care settings.
Market Restraints
- Petrolatum price volatility:Refinery output fluctuations for white petroleum jelly feedstocks are compressing margin stability for barrier cream manufacturers.
- Single-source API concentration:Zinc oxide active pharmaceutical ingredient supply clusters in Chinese industrial zones create geographic vulnerability for European formulators.
- EPA antimicrobial claim restrictions:Cleansing wipe formulations face re-registration burdens that delay new product introductions by 18-24 months.
Strategic Opportunities
- Indian home care penetration:Urban middle-class aging and informal caregiver networks create whitespace for direct-to-consumer subscription models outside institutional channels.
- Brazilian reimbursement expansion:ANVISA's alignment with geriatric care protocols is opening public procurement pathways previously restricted to acute medical devices.
- Telehealth-integrated skin monitoring:Remote dermatological assessment platforms are converging with replenishment algorithms to enable predictive product delivery.
Industry Challenges
- ISO 13485 certification backlog:Medical device quality management system audit queues are extending time-to-market for barrier products seeking clinical channel access.
- Legacy ERP integration:Subscription billing mechanics require reconfiguration of manufacturing resource planning systems originally architected for batch production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Incontinence Skin Care Products Market |
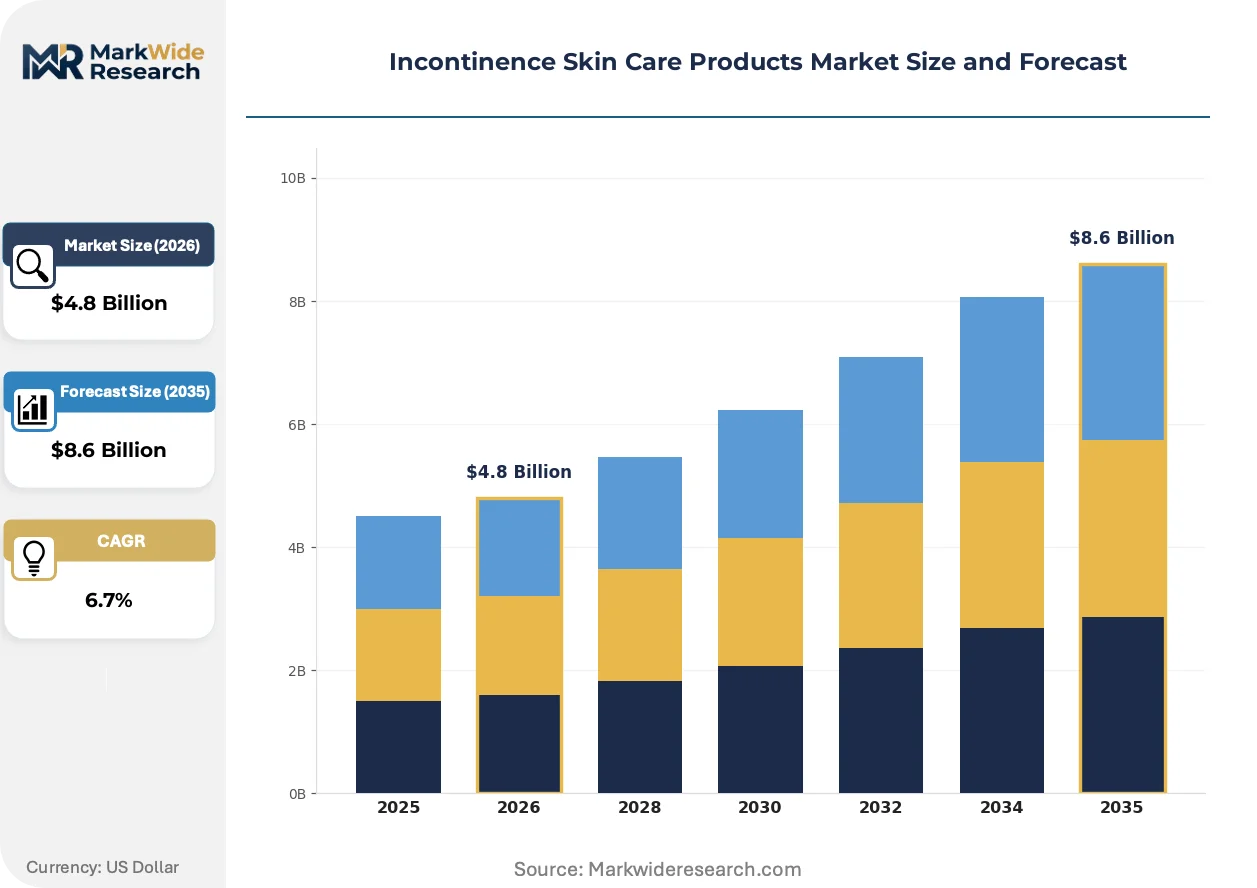
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Barrier Creams, Skin Cleansing Wipes, Moisturizers, Protective Pads End User: Home Care, Hospitals, Nursing Homes, Rehabilitation Centers Distribution Channel: Online Retail, Pharmacies, Supermarkets, Specialty Stores Packaging Type: Tubes, Bottles, Sachets, Pouches |
| Companies Covered | Coloplast A/S, Essity, Kimberly-Clark, ConvaTec Group, Abena Group, Svenska Cellulosa AB, Medline Industries, Attends Ltd, PAUL HARTMANN AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Incontinence Skin Care Products Market Strategic Shifts
Sensor-enabled skin condition monitoring is digitizing care protocols, while regulatory reclassification and procurement model fragmentation are simultaneously reshaping competitive access and customer relationship economics.
pH-buffered hydrogel formulations with real-time moisture indicators are digitizing preventive care workflows. Skilled nursing facilities in the Netherlands and Sweden are piloting these systems at scale. The technology is digitizing labor allocation by triggering automated replenishment orders before barrier breakdown occurs.
REACH Annex XVII restrictions on microplastic-containing leave-on products are forcing reformulation of conventional barrier cream bases. Manufacturers serving the European market are accelerating petrolatum-alternative development programs. Wipe and cream categories face divergent compliance timelines, with rinse-off products receiving temporary derogations that barrier formulations do not.
Direct contracting between long-term care chains and specialized manufacturers is disintermediating traditional distribution. Group purchasing organizations are losing leverage as procurement departments build in-house category expertise. This pattern is most visible in Germany's consolidated nursing home sector, where three operators control access to over forty percent of resident beds.
Incontinence Skin Care Products Market Segmentation
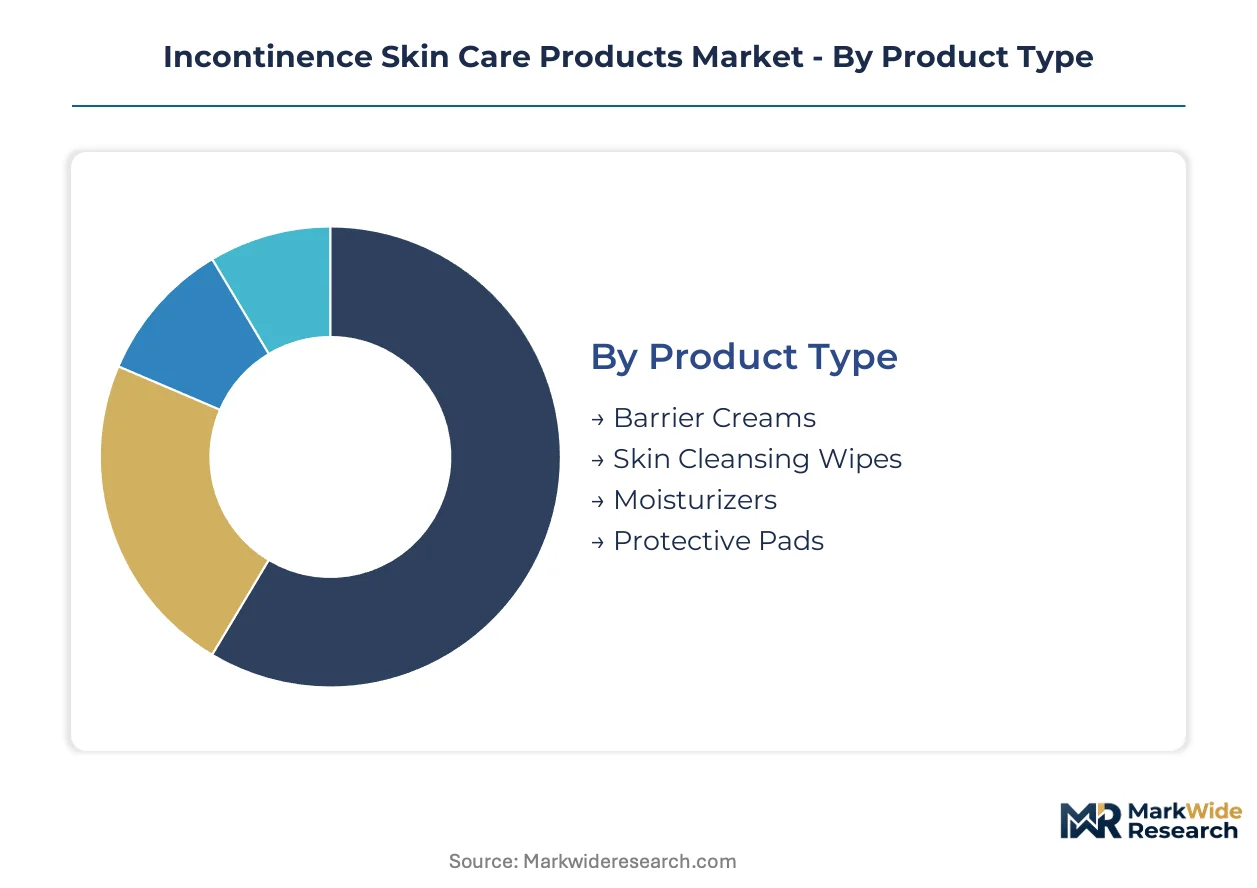
Segmentation in incontinence skin care reveals how formulation chemistry, care setting acuity, and procurement channel economics fragment demand across distinct margin pools. Understanding these divisions exposes where subscription mechanics and regulatory positioning create sustainable competitive advantage.
Product Type:
Cost tier stratification separates prescription-adjacent clinical formulations from commodity hygiene products, with active ingredient concentration and dossier investment determining pricing power.
- Barrier Creams:Petrolatum-based and zinc oxide composite formulations create occlusive films to prevent moisture-associated dermatitis. Demand concentrates in German and Japanese nursing homes where protocol standardization mandates clinical-grade prevention regimens. EU MDR reclassification is raising compliance barriers that favor established manufacturers with quality management system certifications.
- Skin Cleansing Wipes:pH-balanced, fragrance-free disposable cloths engineered for perineal hygiene without barrier disruption. Rehabilitation centers in the Netherlands are adopting these at scale as labor-saving alternatives to basin bathing, though EPA antimicrobial claim re-registration timelines delay new product introductions.
- Moisturizers:Emollient formulations for compromised skin barrier maintenance.
- Protective Pads:Absorbent accessories that complement topical skin protection protocols.
Barrier creams hold installed capacity. Skin cleansing wipes are rotating up the share rankings.
End User:
Application context determines whether procurement flows through retail pharmacy, institutional contract, or direct-to-consumer subscription mechanics.
- Nursing Homes:Long-term care facilities with the highest resident acuity and protocol-driven skin care regimens. Germany's consolidated operator landscape—where three chains control over forty percent of beds—enables direct manufacturer contracting that disintermediates traditional distribution.
- Home Care:Informal caregiver networks and aging-in-place consumers purchasing through online retail subscription models. Indian urban middle-class expansion and Brazilian reimbursement alignment with geriatric protocols are opening whitespace outside institutional channels.
- Hospitals:Acute care settings with wound care prevention mandates.
- Rehabilitation Centers:Transitional care facilities with standardized hygiene protocols.
Nursing homes hold installed capacity. Home care is rotating up the share rankings.
Distribution Channel:
Customer type and purchase frequency reshape channel economics as replenishment models displace one-time transactions.
- Online Retail:Direct-to-consumer platforms enabling subscription fulfillment and predictive replenishment algorithms. Skilled nursing facilities in Sweden pilot sensor-integrated monitoring systems that trigger automated orders before barrier breakdown occurs.
- Pharmacies:Retail pharmacy chains and institutional procurement departments with bundled contract leverage. North American retail pharmacy channels compete on brand strength, while European home care networks reward deep clinical relationships.
- Supermarkets:Mass-market retail for economy-tier consumer products.
- Specialty Stores:Medical supply and durable medical equipment channels.
Pharmacies hold installed capacity. Online retail is rotating up the share rankings.
Packaging Type:
Volume and application setting dictate format selection, with single-use and bulk configurations serving divergent care workflows.
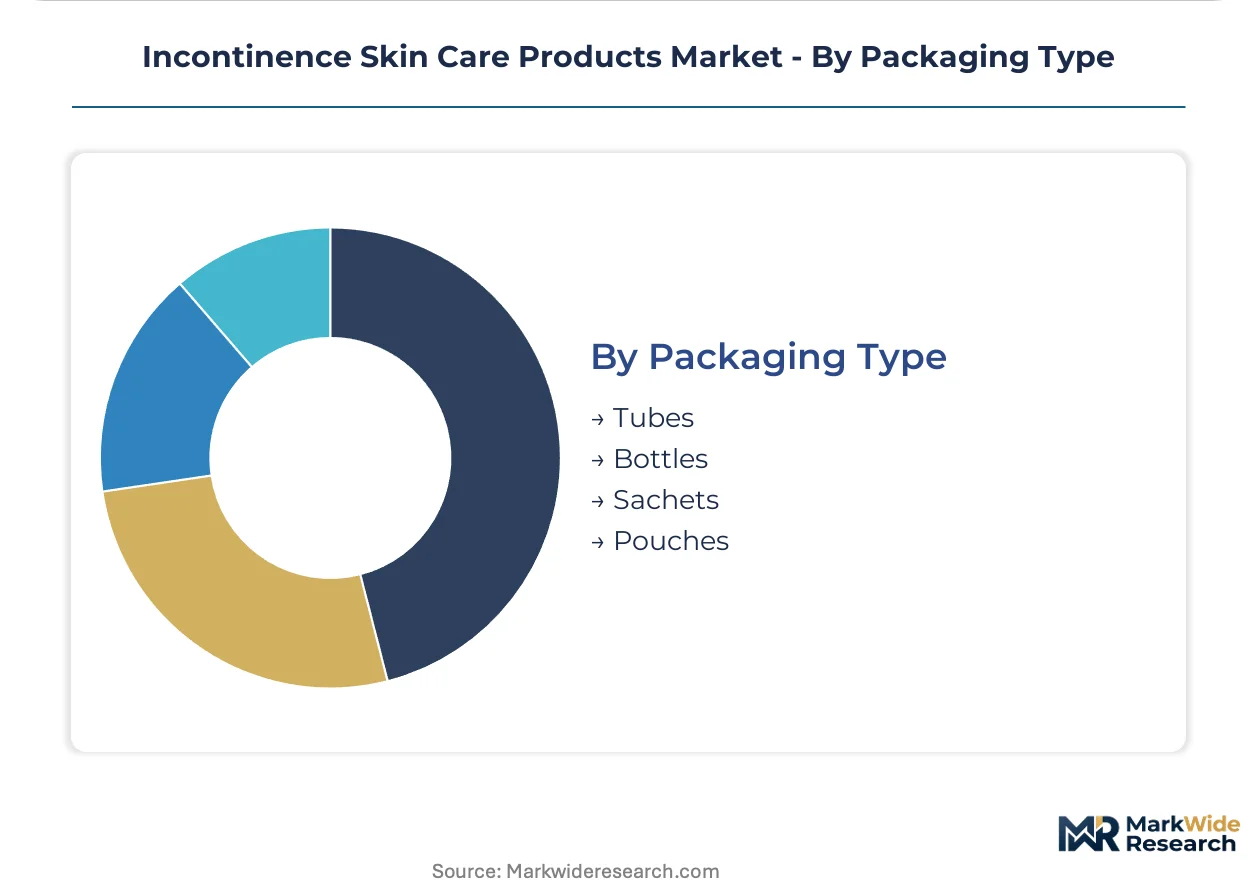
- Sachets:Single-dose barrier cream packets for infection control compliance in acute care. REACH Annex XVII microplastic restrictions force petrolatum-alternative development for leave-on products, accelerating reformulation investments.
- Tubes:Collapsible barrier cream containers for home care and outpatient use. Zinc oxide nanoformulation advances improve film durability while reducing application frequency, lowering labor burden in understaffed settings.
- Bottles:Bulk cleanser and moisturizer containers for institutional refill systems.
- Pouches:Flexible wipe packaging for high-volume dispensing units.
Tubes hold installed capacity. Sachets are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany demonstrate the lowest price elasticity due to established reimbursement infrastructure, while Indian consumers remain highly sensitive to out-of-pocket costs despite expanding middle-class demand. Japan occupies an intermediate position where clinical protocol adherence moderates pure price competition.
Germany
Three nursing home chains control over forty percent of resident beds, enabling direct manufacturer contracting that bypasses traditional distribution markups. The EU MDR reclassification of barrier creams accelerates dossier investments by established quality management system holders. Production clusters concentrate in North Rhine-Westphalia where contract manufacturers serve pan-European home care networks.
United States
Long-term care acuity escalation drives protocol-driven skin care regimens across skilled nursing facilities and rehabilitation centers. The FDA maintains medical device classifications for barrier products while the EPA regulates antimicrobial claims in cleansing formulations, creating dual compliance pathways. Manufacturing activity clusters in the Midwest corridor serving institutional procurement departments with bundled contract structures.
Japan
Aging demographics and formal caregiver shortage expand demand for labor-saving application formats in nursing homes and home care settings. The PMDA oversees quality standards for products positioned adjacent to medical device categories. Industrial concentration in the Kansai region supports formulation expertise for zinc oxide nanoengineering and pH-buffered hydrogel development.
India
Urban middle-class aging and informal caregiver networks create whitespace for direct-to-consumer subscription models outside institutional channels. The CDSCO regulates cosmetic-grade products while medical device pathway clarity remains under development. Mumbai and Bangalore host emerging e-commerce fulfillment infrastructure targeting home care penetration.
Brazil
ANVISA's alignment with geriatric care protocols opens public procurement pathways previously restricted to acute medical devices. Reimbursement expansion for preventive skin care products reduces out-of-pocket burden for aging consumers. São Paulo anchors distribution networks serving the consolidated southeast corridor where nursing home chains are standardizing procurement.
Incontinence Skin Care Products Market Competitive Environment
Clinical-channel specialists and tissue-hygiene conglomerates split the market between prescription-adjacent positioning and manufacturing scale advantages. The vendor base concentrates around three strategic archetypes: European quality-system holders with deep home care relationships, North American retail pharmacy brands with institutional procurement access, and diversified hygiene conglomerates leveraging captive raw material supply. Competitive moves center on EU MDR dossier completion and direct-to-consumer subscription infrastructure buildout.
Within the clinical-channel tier, Coloplast A/S and Essity occupy positions exemplifying divergent strategic paths. Coloplast A/S represents the European specialist model anchored in quality management system certifications and deep nursing home network relationships. Essity exemplifies scale-driven diversification across tissue and hygiene categories with manufacturing cost advantages in barrier creams and cleansing wipes. Kimberly-Clark sits within the North American retail pharmacy archetype, competing through brand strength in institutional procurement channels and consumer-facing subscription mechanics.
| Leading Market Players |
|---|
| Coloplast A/S |
| Essity |
| Kimberly-Clark |
| ConvaTec Group |
| Abena Group |
| Svenska Cellulosa AB |
| Medline Industries |
| Attends Ltd |
| PAUL HARTMANN AG |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in white petroleum jelly refining across North American refineries is compressing margin stability for barrier cream manufacturers while simultaneously elevating pricing power for zinc oxide API holders in Chinese industrial zones. This utilization asymmetry between feedstock and active ingredient supply tiers forces formulators to absorb cost volatility or reformulate toward petrolatum alternatives.
Pricing Analysis
Recurring replenishment service revenue drives lifetime value in incontinence skin care as subscription mechanics displace one-time transactions. Three-tier pricing structure across clinical-grade, institutional-standard, and retail-economy levels segments buyers by certification tier and protocol adherence requirements. Cost compression in retail-economy tiers intensifies because Essity and Kimberly-Clark leverage tissue-hygiene manufacturing scale. Home care direct-to-consumer segments demonstrate highest price sensitivity due to out-of-pocket burden, while German nursing home chains show lowest elasticity through established reimbursement infrastructure.
Supply Chain Analysis
Single-source concentration of zinc oxide API production in Chinese industrial zones creates geographic vulnerability for European and North American formulators. White petroleum jelly feedstocks draw from North American and European refinery clusters, while pH-buffered hydrogel polymers rest on Japanese and German specialty chemical production. Regulatory restriction through REACH Annex XVII microplastic bans forces petrolatum-alternative development timelines that lag behind compliance deadlines. Distribution runs through direct manufacturer contracting with consolidated nursing home operators, disintermediating traditional group purchasing organization leverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR reclassification of barrier creams constitutes a regulatory inflection that will reshape competitive access and consolidate market share among quality-system holders within the forecast window.
For Market Incumbents: Build regulatory dossier moats through accelerated EU MDR compliance investments before cosmetic-grade competitors achieve medical device pathway access. Defensive consolidation moves center on acquiring contract manufacturers with ISO 13485 certifications in North Rhine-Westphalia and Midwest corridor clusters. Capacity addition in Indian e-commerce fulfillment infrastructure addresses emerging home care subscription demand before local players establish channel control. For New Entrants and Emerging Players: Build out direct-to-consumer subscription infrastructure targeting Indian urban middle-class aging and Brazilian reimbursement expansion whitespace outside institutional procurement channels. Most penetrable segment lies in sensor-enabled skin monitoring integration with predictive replenishment algorithms for Swedish and Dutch skilled nursing facility pilots. Go-to-market angle emphasizes telehealth-integrated dermatological assessment platforms that trigger automated product delivery before barrier breakdown occurs. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across clinical-grade formulation segments as EU MDR dossier investments and REACH-compliant petrolatum-alternative R&D programs escalate fixed cost structures. Long-term viability across the analysis window favors acquisition targets with established quality management system certifications and deep nursing home network relationships rather than commodity hygiene manufacturers. Signal to watch involves ISO 13485 certification backlog resolution timelines that determine time-to-market for barrier products seeking clinical channel access.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Dossier Completion | Quality-system certification unlocks clinical channel access ahead of cosmetic-grade competitors in German nursing networks. |
| Direct-to-Consumer Subscription Launch | Predictive replenishment algorithms capture home care demand in Indian and Brazilian markets outside institutional procurement. |
| Petrolatum-Alternative Formulation Investment | REACH Annex XVII compliance for leave-on products avoids microplastic restriction penalties in European barrier cream sales. |
| Sensor-Enabled Skin Monitoring Integration | Real-time moisture indicators trigger automated orders before barrier breakdown in Dutch and Swedish facility pilots. |
| Contract Manufacturer Acquisition | ISO 13485-certified production capacity in North Rhine-Westphalia accelerates medical device pathway access for barrier products. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with industry stakeholders and systematic secondary validation across regulatory and commercial databases. Primary fieldwork engaged clinical procurement directors at German nursing home chains, biomedical engineers specializing in wound care prevention, GPO contracts managers in North American long-term care, and R&D directors at zinc oxide nanoformulation specialists. Secondary sources encompassed FDA medical device classification filings, EMA MDR submission databases, EPA antimicrobial claim registrations, REACH Annex XVII restriction updates, and hospital procurement contract disclosures. Bottom-up demand modeling triangulated against top-down manufacturer capacity assessments.
Forecast inputs considered product type segmentation across barrier creams, skin cleansing wipes, moisturizers, and protective pads; end user categories spanning nursing homes, home care, hospitals, and rehabilitation centers; and distribution channel dynamics including online retail, pharmacies, supermarkets, and specialty stores. CAGRs derived from volume-demand elasticity modeling against reimbursement pathway expansion and protocol standardization trends. Industry-specific inputs incorporated EU MDR compliance timeline acceleration and petrolatum price volatility indices from refinery output data.
The forecast holds incumbent behavior within observed patterns; aggressive dossier investment acceleration by Coloplast A/S or Essity would shift competitive access timelines and market share distributions. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
United Kingdom Skincare Market
Skincare
Tinted Sunscreen Market
Skincare
US Acne Treatment Market
Skincare
Vitamin C Serum Market
Skincare
Facial Skincare Market
Skincare
Bangladesh Skin Care Products Market
Skincare
Skin Care Emulsion Market
Skincare
Skin Grafting System Market
Skincare
Encapsulated Retinol Market
Skincare
Hand Care Market
Skincare
Skin Resurfacing Market
Skincare
Skin Barrier Market
Skincare
Global Cosmetic Skin Care Market
Skincare
Rice Water Skincare Market
Skincare
Skin Toner Market
Skincare
Global Anti-Aging Market