
 Europe Wound Care Market | 2026-2036
Europe Wound Care Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Wound Care Market Insights
The EU Green Deal's sustainable healthcare procurement guidelines is restructuring purchasing criteria across national health systems, compelling suppliers to demonstrate biodegradability and reduced packaging footprints. Paul Hartmann AG leverages its German manufacturing base to supply zero-waste dressing lines directly into hospital central purchasing. Mölnlycke Health Care AB anchors Nordic procurement contracts through silicone foam technology leadership. Smith & Nephew competes across the United Kingdom and Ireland with negative pressure wound therapy integration into standard surgical pathways.
Wound care encompasses absorbent, antimicrobial, and moisture-retentive products applied to acute or chronic tissue defects, typically manufactured from hydrocolloid polymers, polyurethane foams, calcium alginate fibers, or hydrogel matrices with specified exudate handling capacities measured in grams per square centimeter. These products serve to maintain moist healing environments, prevent infection, and accelerate re-epithelialization in clinical and home settings. Dressings dominate volume flows across European hospital tenders, while chronic wounds command premium pricing due to extended treatment durations and specialized alginate requirements. Homecare channels are expanding fastest as post-acute discharge protocols shorten inpatient stays and shift monitoring burden to district nurses.
EMA coordinates post-market surveillance for wound care devices through the EUDAMED database, while CE marking under the EU Medical Device Regulation mandates clinical evaluation reports for novel absorbent materials. REACH restricts certain phthalates and latex proteins in patient-contact layers, pushing manufacturers toward synthetic elastomer alternatives. France's ANSM and Germany's BfArM enforce national vigilance reporting that shapes product liability exposure. Stakeholders must monitor how the EU AI Act classifies diagnostic wound imaging tools, as algorithmic tissue assessment could redraw competitive boundaries between device and software suppliers.
Market Dynamics
Hospital procurement consortia across Germany, France, and the United Kingdom are consolidating supplier panels around full-line wound care vendors, compressing margins for single-product specialists while rewarding integrated portfolios with multi-year framework agreements.
Growth Catalysts
- German geriatric clinic demand:Chronic wound management in aging care facilities is absorbing advanced foam and hydrocolloid dressings at accelerating volumes.
- EU Green Deal procurement guidelines:Sustainable healthcare purchasing criteria now mandate biodegradability demonstrations, creating preference for zero-waste dressing lines.
- Silicone foam technology:Moisture-retentive polymer advances enable extended wear times and reduced dressing change frequency in post-acute protocols.
Market Restraints
- MDR clinical evidence escalation:CE marking under the EU Medical Device Regulation now demands clinical evaluation reports for novel absorbent materials, extending time-to-market for innovative dressings.
- Calcium alginate fiber supply:Seaweed-derived raw material sourcing concentrates in coastal harvesting regions, exposing manufacturers to seasonal yield variability.
- Phthalate substitution costs:REACH restrictions on patient-contact layer chemistries force reformulation investments without immediate reimbursement recapture.
Strategic Opportunities
- Homecare channel expansion:Post-acute discharge protocols shortening inpatient stays shift monitoring burden to district nurses, creating demand for simplified application systems.
- EUDAMED data integration:EMA's post-market surveillance database offers real-world evidence pathways for differentiated claims on infection prevention performance.
- AI Act diagnostic classification:Algorithmic tissue assessment tools face pending regulatory clarity, creating first-mover advantage for software-device convergence plays.
Industry Challenges
- Specialized wound care nursing shortages:District nurse capacity constraints in the United Kingdom and France limit effective homecare protocol execution despite product availability.
- Legacy hospital inventory systems:ERP integration complexity with existing supply chain platforms delays real-time consumption tracking and automated replenishment.
- Multi-site certification timelines:Parallel BfArM and ANSM vigilance reporting requirements fragment compliance resources for pan-European product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Wound Care Market |
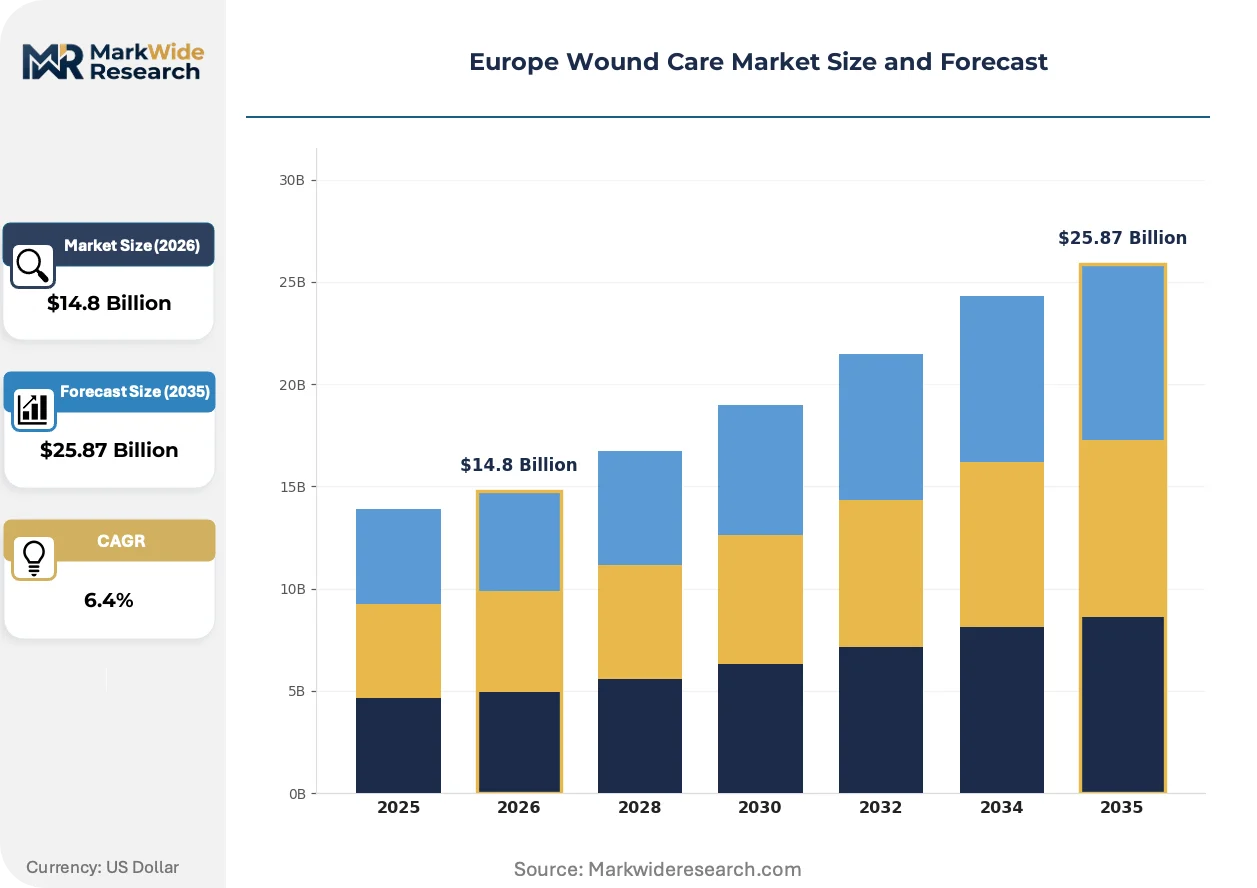
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dressings, Gels, Ointments, Solutions End User: Hospitals, Homecare, Clinics, Long-term Care Facilities Application: Burns, Surgical Wounds, Chronic Wounds, Ulcers Material: Hydrocolloid, Foam, Alginate, Others |
| Companies Covered | Paul Hartmann AG, Solventum, Smith & Nephew, B. Braun SE, Integra LifeSciences Corporation, Mölnlycke Health Care AB, Coloplast, Cardinal Health, ConvaTec Group PLC, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Wound Care Market Trends and Innovations
Digital wound assessment capabilities and sustainable material chemistry are converging to redefine product differentiation, while procurement centralization forces vendors to restructure service delivery models around consolidated buyer power.
Negative pressure wound therapy systems integrated with disposable foam dressings are rewriting surgical pathway economics in United Kingdom hospitals. Acute care units adopting these combined modalities report reduced length-of-stay metrics. The technology is compressing standalone dressing markets by bundling mechanical drainage with absorbent layers in single procedure codes.
REACH enforcement on latex protein content in patient-contact layers is accelerating synthetic elastomer adoption across French and German manufacturing bases. ECHA substance restriction timelines force reformulation commitments two years ahead of compliance deadlines. Hydrogel matrix suppliers are responding with polyurethane alternatives that maintain moisture vapor transmission rates.
Hospital procurement consortia in Germany and France now bundle wound care into broader surgical supplies frameworks, displacing standalone tender participation. District nurse services in the United Kingdom face equivalent pressure as integrated care boards consolidate purchasing across community and acute settings. This buyer concentration demands vendor investment in logistics infrastructure capable of direct-to-ward delivery at scale.
Europe Wound Care Market Segmentation
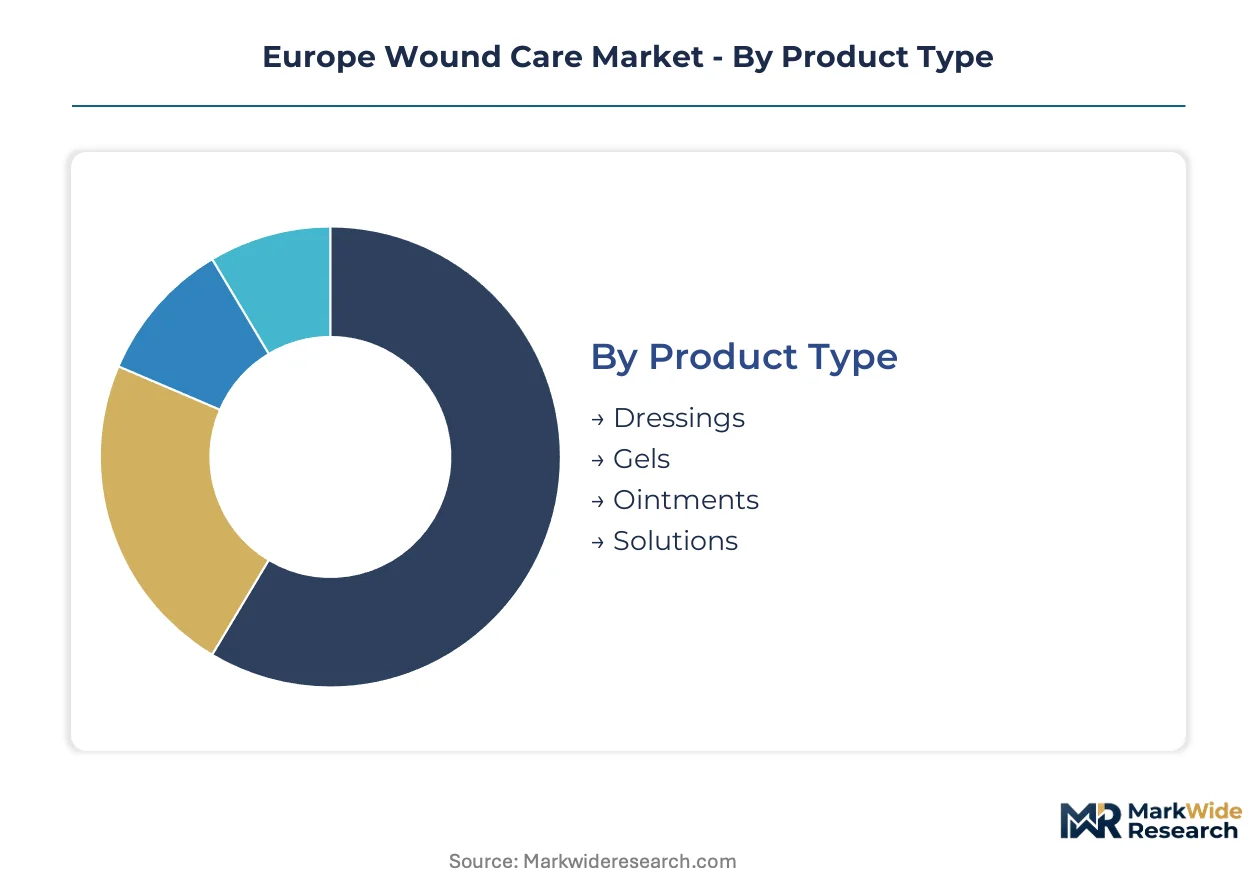
European wound care procurement increasingly segments by care setting and material performance, as hospital consortia bundle absorbent technologies across acute and post-acute pathways. Material chemistry and end-user logistics now determine vendor selection more than unit economics alone.
Product Type:
Dressings function as standalone surface applications, while gels and ointments embed into multi-step protocols requiring nursing training.
- Dressings:Polyurethane foam and hydrocolloid layers dominate hospital tenders through specified exudate absorption rates measured in grams per square centimeter. German geriatric clinics absorb advanced foam variants at accelerating volumes as chronic wound protocols extend wear times.
- Gels:Hydrogel matrices maintain moisture vapor transmission for partial-thickness burns and donor sites. United Kingdom district nurse services prioritize single-use sachet packaging for homecare compliance.
- Ointments:Petroleum-based and antimicrobial formulations serve surgical incision margins in French hospital outpatient departments.
- Solutions:Irrigation and cleansing formulations support debridement procedures in Nordic acute care units.
Dressings lead volumes today; gels are gaining share fastest through homecare channel expansion.
End User:
Procurement concentration varies sharply between centralized hospital frameworks and fragmented community purchasing.
- Hospitals:German, French, and United Kingdom procurement consortia consolidate supplier panels around full-line vendors capable of direct-to-ward logistics. Multi-year framework agreements compress margins for single-product specialists.
- Homecare:Post-acute discharge protocols shift monitoring burden to district nurses, demanding simplified application systems with extended wear intervals. United Kingdom integrated care boards now bundle community wound care into acute procurement frameworks.
- Clinics:Outpatient surgical centers in France and Germany prioritize negative pressure wound therapy integration for reduced length-of-stay metrics.
- Long-term Care Facilities:Pressure ulcer prevention protocols in German geriatric clinics absorb silicone foam technology for repositioning schedules.
Hospitals retain the largest procurement value; homecare channels are expanding most quickly as inpatient stays shorten.
Application:
Acute surgical pathways favor bundled mechanical-absorbent systems, while chronic conditions require specialized alginate chemistry.
- Surgical Wounds:Negative pressure wound therapy systems integrated with disposable foam dressings rewrite pathway economics in United Kingdom acute care units. Bundled procedure codes compress standalone dressing markets.
- Chronic Wounds:Diabetic foot and venous leg ulcers command premium pricing due to extended treatment durations and specialized calcium alginate requirements. EUDAMED post-market surveillance offers real-world evidence pathways for infection prevention claims.
- Burns:Hydrogel and silver-impregnated dressings serve partial-thickness thermal injuries in French burn centers.
- Ulcers:Pressure and arterial ulcer management concentrates in German long-term care facilities with zero-waste dressing procurement mandates.
Surgical applications anchor current revenue; chronic wound management shows the steepest expansion trajectory as population aging accelerates.
Material:
REACH restrictions on phthalates and latex proteins force reformulation investments across patient-contact layers.
- Foam:Silicone-adherent polyurethane foam enables extended wear times and reduced dressing change frequency. Mölnlycke Health Care AB anchors Nordic procurement contracts through technology leadership in moisture-retentive polymer advances.
- Hydrocolloid:Carboxymethylcellulose and gelatin matrices form gel upon exudate contact, maintaining moist healing environments for partial-thickness wounds. Paul Hartmann AG supplies zero-waste dressing lines from German manufacturing bases into hospital central purchasing.
- Alginate:Seaweed-derived calcium alginate fibers gel on contact with wound fluid, serving heavily exuding chronic wounds. Coastal harvesting concentration exposes manufacturers to seasonal yield variability.
- Others:Hydrogel matrices and collagen dressings respond to REACH enforcement with polyurethane alternatives maintaining moisture vapor transmission rates.
Foam leads volumes today; hydrocolloid variants are climbing the fastest through sustainable chemistry procurement preferences.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wound care manufacturing first achieved industrial scale in Germany during the 1960s, when textile and chemical processing capabilities converged to produce standardized gauze and adhesive dressings for post-war hospital systems. This German foundation established quality benchmarks and regulatory frameworks that subsequently spread across Western Europe.
Germany
German geriatric clinics absorb advanced foam and hydrocolloid dressings at accelerating volumes as chronic wound protocols extend wear times. BfArM enforces national vigilance reporting that shapes product liability exposure for absorbent material suppliers. Paul Hartmann AG leverages its Heidenheim manufacturing base to supply zero-waste dressing lines directly into hospital central purchasing consortia across Baden-Württemberg and North Rhine-Westphalia.
United Kingdom
United Kingdom acute care units adopt negative pressure wound therapy systems integrated with disposable foam dressings to reduce length-of-stay metrics. Integrated care boards consolidate purchasing across community and acute settings, bundling wound care into broader surgical supplies frameworks. Smith & Nephew competes across England and Ireland with therapy integration into standard surgical pathways.
France
French hospital outpatient departments prioritize petroleum-based and antimicrobial ointment formulations for surgical incision margins. ANSM enforces vigilance reporting requirements that fragment compliance resources for pan-European product launches. Manufacturing clusters in the Île-de-France region reformulate hydrogel matrices with polyurethane alternatives to maintain moisture vapor transmission rates under REACH enforcement timelines.
Sweden
Nordic procurement contracts anchor around silicone foam technology leadership as moisture-retentive polymer advances enable extended wear times. Mölnlycke Health Care AB supplies Gothenburg-manufactured dressings through regional tender frameworks. District nurse services across Stockholm and Skåne prioritize simplified application systems for homecare compliance.
Italy
Italian long-term care facilities absorb pressure ulcer prevention protocols with specialized alginate requirements for heavily exuding chronic wounds. CE marking under the EU Medical Device Regulation demands clinical evaluation reports for novel absorbent materials entering Lombardy and Emilia-Romagna hospital systems. Coastal harvesting concentration for seaweed-derived raw materials exposes regional manufacturers to seasonal yield variability.
Europe Wound Care Market Competitive Landscape
Capital-heavy producers with integrated manufacturing compete with asset-light distributors sourcing from contract converters across Eastern Europe and Asia. The vendor base concentrates around full-line wound care portfolios capable of satisfying multi-year framework agreements from consolidated hospital procurement consortia. Three archetypes dominate: German-based manufacturers with zero-waste chemistry capabilities, Nordic silicone foam technology specialists, and diversified medical device conglomerates with negative pressure therapy integration. Competitive moves center on logistics infrastructure investment for direct-to-ward delivery and sustainable material certification to satisfy EU Green Deal procurement guidelines.
Within the integrated manufacturing tier, Paul Hartmann AG and Mölnlycke Health Care AB exemplify regional anchor positions through German and Swedish production bases respectively. Smith & Nephew occupies a position bridging device and dressing categories through therapy system integration. These three entities represent the archetype of vendors capable of spanning acute, post-acute, and homecare channels under consolidated tender structures.
| Leading Market Players |
|---|
| Paul Hartmann AG |
| Solventum |
| Smith & Nephew |
| B. Braun SE |
| Integra LifeSciences Corporation |
| Mölnlycke Health Care AB |
| Coloplast |
| Cardinal Health |
| ConvaTec Group PLC |
| Others |
Pricing and Supply Chain Analysis
Hospital procurement consortia across Germany, France, and the United Kingdom command contract-based long-term offtake frameworks that compress supplier margins while rewarding full-line vendors with multi-year purchasing commitments. This buyer concentration forces pricing discipline through volume bundling and direct-to-ward logistics requirements.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates silicone foam technology from hydrocolloid variants and commodity gauze products. Price differentiation rests on CE marking tier under MDR and volume scale within framework agreements. Cost compression in standard-tier foam dressings is intensifying because German central purchasing consortia consolidate supplier panels. District nurse services in the United Kingdom exhibit highest price sensitivity due to fixed per-patient budgets, while acute surgical units in France demonstrate lowest sensitivity for negative pressure wound therapy bundles.
Supply Chain Analysis
Workforce availability constraints in coastal seaweed harvesting regions of France and Italy expose calcium alginate fiber suppliers to seasonal production volatility. Manufacturing concentrates in Germany, Sweden, and France, with raw material dependencies spanning seaweed-derived alginate, polyurethane precursors, and synthetic elastomer alternatives to REACH-restricted latex. Single-source vulnerability concentrates in coastal alginate harvesting regions. Distribution runs through hospital central purchasing consortia and integrated care boards with direct-to-ward delivery mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Wound Care Market represents a late-cycle quality story as chronic wound protocols in German geriatric clinics shift demand toward extended-wear silicone foam specifications with premium pricing durability.
For Market Incumbents: Cement framework agreement dominance by securing zero-waste dressing certification under EU Green Deal procurement guidelines before competitor reformulation cycles complete. Deepen backward integration into polyurethane foam precursor production to defend margin position against calcium alginate supply volatility. MDR clinical evidence escalation threatens single-product specialists with extended time-to-market delays. For New Entrants and Emerging Players: EU AI Act diagnostic classification in France and Germany opens a window for algorithmic tissue assessment tools that bridge software-device regulatory boundaries. Target homecare channel expansion in the United Kingdom where integrated care boards consolidate purchasing and simplified application systems face district nurse capacity constraints. Pursue silicone foam technology licensing from Nordic manufacturing bases as fastest route to hospital tender qualification. For Investors and Strategic Acquirers: Diversified medical device conglomerates with negative pressure wound therapy integration are the most active acquirer in this space, seeking dressing portfolio fill-ins to complete surgical pathway bundles. Long-term viability favors targets with sustainable chemistry certification and direct-to-ward logistics infrastructure already operational. Monitor EUDAMED post-market surveillance data publication as signal for differentiated infection prevention claims that redraw competitive boundaries.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR clinical evaluation reports for novel absorbent materials extend time-to-market for innovative dressings entering German hospital systems. |
| Hospital System Partnership | Multi-year framework agreements with French procurement consortia lock in volume commitments and displace standalone tender competitors. |
| Sustainability Repositioning | Zero-waste dressing lines from Paul Hartmann AG capture EU Green Deal procurement preference in Baden-Württemberg central purchasing. |
| Software Companion Development | Algorithmic tissue assessment tools pending EU AI Act classification create first-mover advantage for diagnostic wound imaging convergence. |
| Backward Integration | In-house production of polyurethane foam precursors insulates Mölnlycke Health Care AB from synthetic elastomer supply volatility under REACH timelines. |
Research Methodology
Multiple input streams — hospital procurement database analysis, clinician interviews, and regulatory filing review — were reconciled to construct segment-level demand estimates. Primary interviews with wound care nurses, hospital purchasing committee members, biomedical engineers, and GPO contracts managers informed application-level adoption patterns. Secondary validation drew from EUDAMED vigilance reports, ANSM and BfArM national databases, EU Medical Device Regulation guidance documents, and REACH substance restriction timelines. Bottom-up product-level volume estimates and top-down healthcare expenditure allocations were cross-referenced for convergence.
Historical tender award patterns were cross-referenced against panel input from procurement directors to anchor growth assumptions across the analysis window. Segmentation dimensions modeled include product type, end-user setting, application category, material chemistry, and country-specific regulatory cluster. CAGRs were derived from trend extrapolation of hospital discharge protocol shifts and homecare channel expansion rates. Forecast inputs incorporated district nurse capacity constraints in the United Kingdom and German geriatric clinic admission trajectories.
Revisions become necessary when MDR implementation timelines shift, EU AI Act diagnostic classification criteria materialize, or alginate harvesting yields deviate from seasonal baselines. Forecasts reflect documented assumptions on procurement consolidation velocity and sustainable chemistry adoption curves. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Dental Wound Dressings Market
Wound Care
Wound Contact Layer Dressing Market
Wound Care
Global Digital Wound Measurement Devices Market
Wound Care
Hemostats for Wound Closure Market
Wound Care
Global Burn Care Market
Wound Care
Enzymatic Wound Debridement Market
Wound Care
Wound Healing Market
Wound Care
Wound Care Sealants Market
Wound Care
Foam Dressing Market
Wound Care
Wound Skin Care Market
Wound Care
Advanced Wound Dressings Market
Wound Care
Pressure Bandages Market
Wound Care
Non-Invasive Surgical Wound Closure Market
Wound Care
US Wound Irrigation System Market
Wound Care
Moist Wound Dressings Market
Wound Care
Smart Bandages and Smart Wound Dressings Market