
 Workstation Desktops Market | 2026-2036
Workstation Desktops Market Size, Share, and Industry Trends Forecast 2026-2036
Workstation Desktops Market Insights
The EU Energy-related Products Directive is broadening design requirements for workstation desktops sold across member states, compelling manufacturers to re-engineer power supply architectures and thermal management systems. Dell leverages its direct enterprise sales channel to sustain premium positioning among professional engineering accounts. HP anchors its portfolio through ISV certification density across media and entertainment verticals. Lenovo competes aggressively on price-performance configurations for small and medium design studios.
Workstation desktops are engineered computing systems built with enterprise-grade processors, discrete professional graphics cards, error-correcting memory, and redundant storage arrays to sustain continuous operation under intensive computational workloads. These systems typically incorporate Xeon or Threadripper-class CPUs with 128GB to 2TB of ECC RAM, supporting CAD, simulation, and real-time rendering pipelines. Tower workstations retain the dominant volume position due to thermal headroom and expansion slot availability, while rack-mounted configurations capture share in data center and render farm deployments. GPU technology segments command premium pricing as generative AI and real-time ray tracing workloads intensify memory and compute demands. Content creator end users represent the fastest-growing buyer category as independent creators and boutique studios scale production capabilities.
The EPA Energy Star program, the EU Ecodesign for Energy-related Products framework, and the EU RoHS directive collectively shape material composition, standby power thresholds, and market access requirements for workstation desktop manufacturers. EPEAT registration requirements in North American public sector procurement further filter vendor eligibility for educational and government contracts. Stakeholders must monitor evolving semiconductor export controls and carbon border adjustment mechanisms that threaten to fragment supply chain configurations and regional product availability.
Market Dynamics
GPU-intensive computational workloads are forcing workstation architecture toward liquid-cooled chassis designs and high-wattage power delivery systems. Thermal management constraints now dictate form factor selection across professional visualization and simulation applications.
Growth Catalysts
- Generative AI pipelines:Media studios deploy GPU-dense tower configurations for real-time inference and training workloads. NVIDIA H100 and AMD Instinct accelerators drive refresh cycles in Los Angeles and London post-production clusters.
- EU Ecodesign Directive:Standby power thresholds below 0.5 watts compel power supply redesigns. German engineering consultancies upgrade fleets to meet Bavarian energy efficiency procurement mandates.
- Industrial automation corridors:CAD-CAM integration in Stuttgart and Wolfsburg manufacturing hubs sustains demand for ISV-certified workstations with ECC memory and redundant storage.
Market Restraints
- DRAM supply concentration:Three Korean and Taiwanese suppliers control high-capacity ECC module output. Price volatility in server-grade memory ripples through workstation bill-of-materials.
- Export control fragmentation:US Bureau of Industry and Security licensing requirements restrict AI accelerator shipments to Chinese research institutions. Vendors maintain separate SKU configurations complicating inventory planning.
- Silicon carbide power component shortages:High-efficiency PSU designs depend on SiC MOSFETs with 26-week lead times. Thermal design power ceilings limit CPU choices when discrete GPU power draw peaks.
Strategic Opportunities
- India PLI scheme for IT hardware:Local assembly incentives attract Dell, HP, and Lenovo to Chennai and Sri City manufacturing zones. Domestic content requirements favor tower workstation production for government and educational tenders.
- Edge AI inference nodes:Rack-mounted workstation configurations displace traditional servers in factory-floor quality inspection. Vision processing pipelines in automotive paint shops require NVIDIA RTX-class compute at the edge.
- Subscription-based hardware provisioning:Boutique architecture studios in Copenhagen and Amsterdam adopt monthly workstation-as-a-service contracts. ISV license bundling with hardware refresh cycles reduces upfront capital barriers.
Industry Challenges
- Electrical-mechanical thermal co-design:600-watt GPU packages demand chassis airflow engineering expertise scarce in regional system integrator channels. Simulation-validated designs require ANSYS or SolidWorks thermal analysis competency.
- Multi-vendor ISV certification synchronization:Autodesk, Dassault Systèmes, and Siemens release quarterly driver validation schedules. Certification lag between GPU driver updates and professional application releases disrupts production timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Workstation Desktops Market |
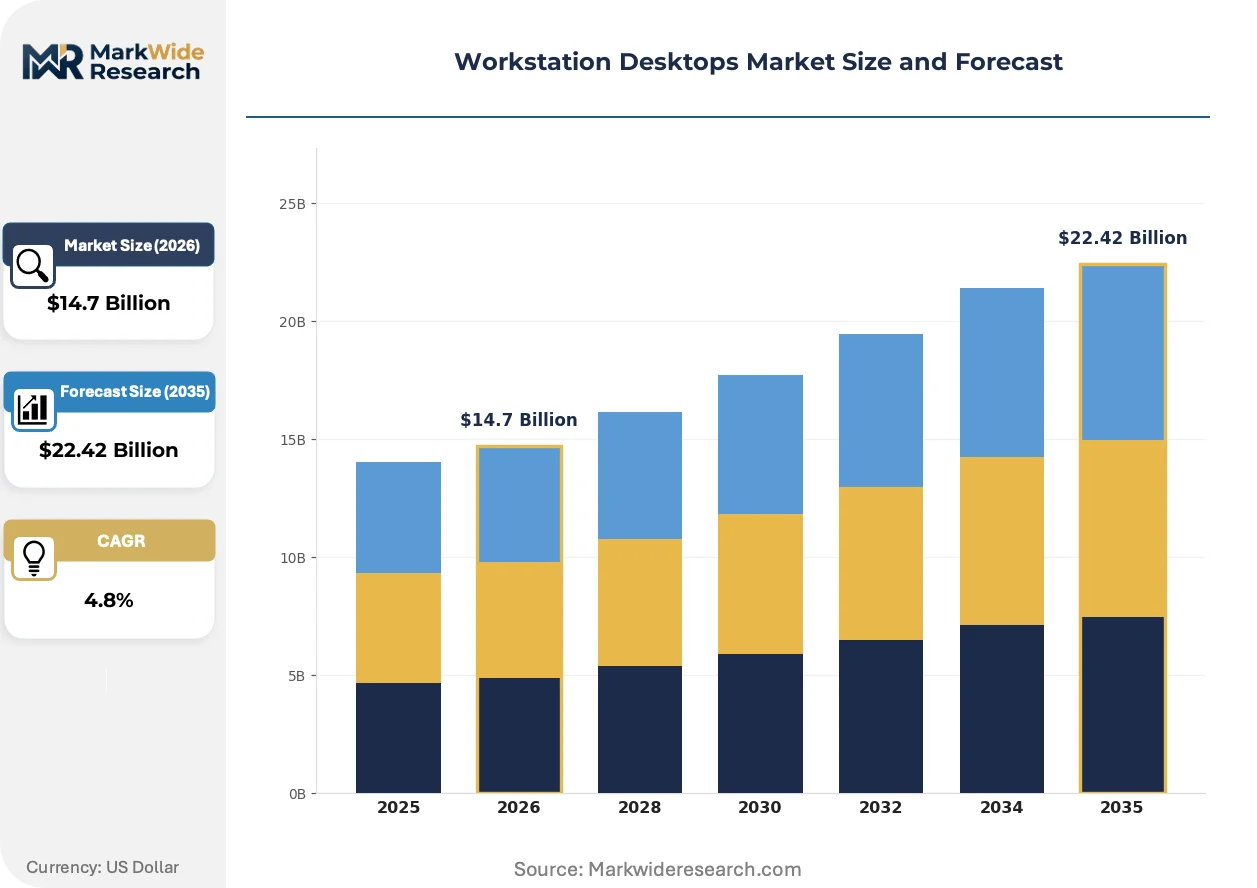
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: All-in-One, Tower Workstations, Rack-mounted Workstations, Blade Workstations End User: Professional Designers, Engineers, Gamers, Content Creators Technology: CPU, GPU, RAM, Storage Distribution Channel: Online Retail, Direct Sales, Distributors, VARs |
| Companies Covered | Dell, HP, Lenovo, Intel, Acer, Gigabyte, Puget Systems, Velocity Micro, Supermicro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Workstation Desktops Market Trends and Innovations
Computational intensity thresholds are redefining workstation form factor boundaries. Thermal design power budgets now exceed what traditional air-cooled towers can dissipate, forcing architectural innovation across hardware and facility layers.
Liquid cooling infrastructure is modularizing across enterprise workstation deployments. Cold-plate designs for CPU-GPU packages enable 1000-watt thermal envelopes in compact tower footprints. Engineering consultancies in Munich and Austin adopt standardized quick-disconnect cooling loops. This approach is modularizing facility-level HVAC requirements, allowing compute density expansion without dedicated server room construction.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants in precision cooling systems. Data center and render farm operators face retrofit deadlines for chiller infrastructure using HFO alternatives or water-based systems. Rack-mounted workstation clusters in Amsterdam and Frankfurt switch to adiabatic cooling designs, compressing facility energy use intensity metrics ahead of CSRD disclosure requirements.
Enterprise buyers now specify outcome-based hardware refresh cycles tied to project pipeline visibility. Architecture and VFX studios in Toronto and Sydney negotiate 18-month replacement guarantees with lessors rather than capital purchases. Channel partners in North America unbundle after-sales support from hardware margin, selling remote diagnostic and predictive failure monitoring as separate subscription lines.
Workstation Desktops Market Segmentation
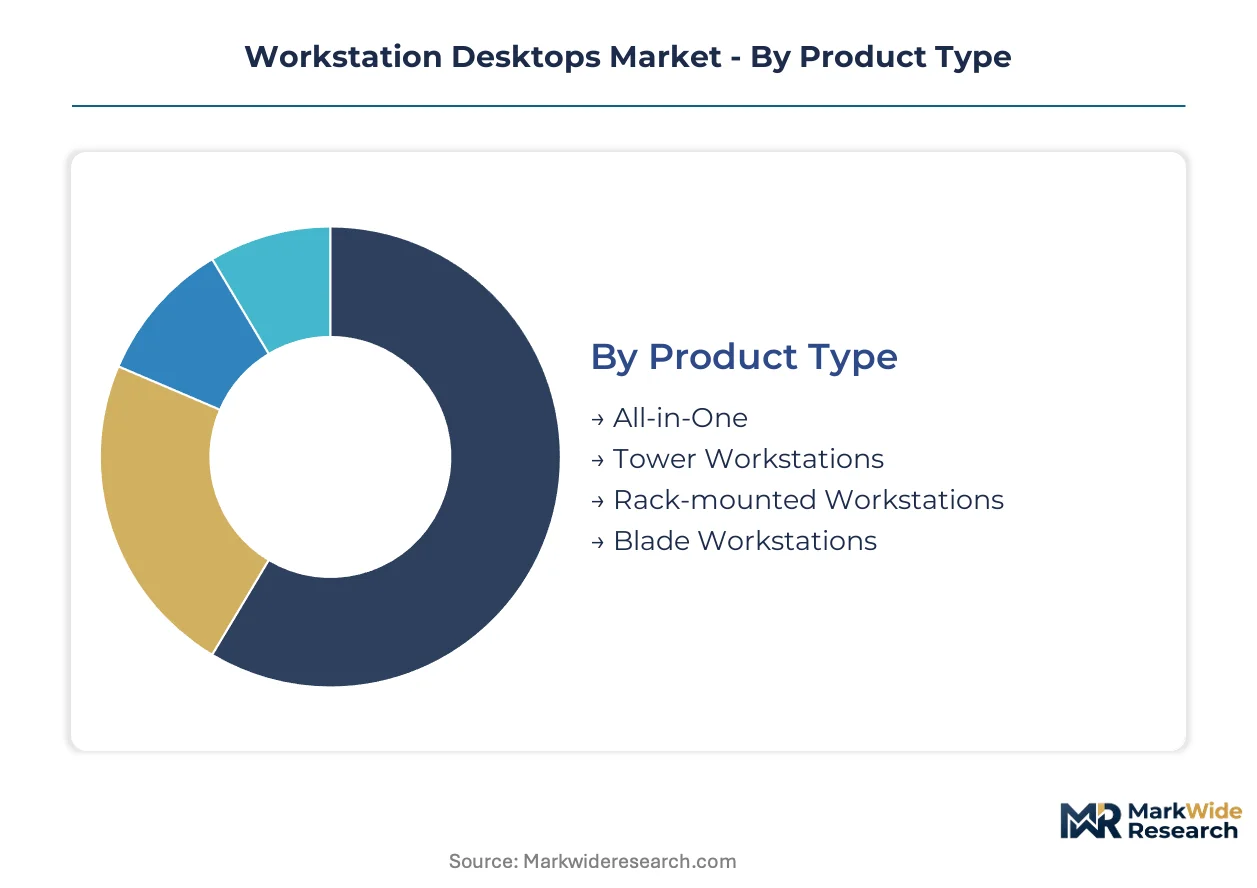
Workstation desktop segmentation reveals divergent thermal, certification, and procurement requirements across professional computing environments. Product form factor selection directly constrains GPU density and cooling architecture possibilities. Distribution channel preferences vary sharply between enterprise fleet buyers and independent content creators.
Product Type:
Buyers differentiate primarily by thermal envelope requirements and facility infrastructure constraints.
- Tower Workstations:Vertical chassis configurations accommodate dual-GPU layouts and 360mm liquid cooling radiators within standard office footprints. German automotive engineering clusters in Stuttgart and Wolfsburg favor these for CAD-CAM workstations requiring ISV certification and local ECC memory expansion.
- Rack-mounted Workstations:1U to 4U server-form-factor designs integrate into data center cooling loops and redundant power distribution. Amsterdam and Frankfurt render farms deploy these for centralized GPU pooling under EU F-Gas Regulation compliance deadlines.
- All-in-One:Integrated display-compute units sacrifice expansion slots for desk-space efficiency. Medical imaging review stations and trading floor deployments prioritize cable reduction over upgrade paths.
- Blade Workstations:Shared chassis architectures consolidate power and cooling across multiple compute nodes. Broadcast production trucks and mobile VFX suites adopt these for density in constrained physical environments.
Tower configurations lead volumes today; rack-mounted designs are gaining share fastest in centralized rendering operations.
End User:
Professional workload intensity and software certification requirements separate buyer categories.
- Engineers:Finite element analysis and computational fluid dynamics workloads demand Xeon or Threadripper processors with 512GB to 2TB ECC RAM. Bavarian industrial automation consultancies specify these for Siemens NX and Dassault Systèmes CATIA certification.
- Content Creators:Video editing, 3D animation, and generative AI pipelines drive GPU memory capacity requirements. Los Angeles and London post-production boutiques scale NVIDIA RTX 6000 Ada configurations for real-time ray tracing and neural rendering.
- Professional Designers:Architecture and product visualization studios balance CPU frequency with single-GPU performance. Copenhagen and Amsterdam practices adopt workstation-as-a-service models to align hardware refresh with project pipelines.
- Gamers:Enthusiast-grade configurations overlap consumer and professional GPU tiers. Overclocking headroom and RGB aesthetics differentiate this segment from ISV-certified professional deployments.
Engineering accounts dominate procurement volumes; content creator segments are expanding most quickly as independent studios proliferate.
Technology:
Component specification tiers determine system validation cycles and thermal design boundaries.
- GPU:Professional graphics accelerators from NVIDIA and AMD carry ISV certification and ECC memory for compute accuracy. Generative AI training and inference workloads concentrate demand in media clusters.
- CPU:Intel Xeon W and AMD Ryzen Threadripper PRO processors scale to 64 cores with AVX-512 or AVX2 vector instructions. Simulation workloads in German manufacturing hubs exploit these parallel capabilities.
- RAM:DDR5 ECC modules from Korean and Taiwanese suppliers range from 128GB entry configurations to 2TB maximums. Supply concentration creates bill-of-materials volatility for system integrators.
- Storage:NVMe RAID arrays and redundant SATA configurations address project file sizes exceeding 10TB in 8K video production. Hot-swap capabilities sustain uptime in broadcast environments.
GPU specifications anchor purchasing decisions; CPU core counts are climbing fastest as simulation parallelism intensifies.
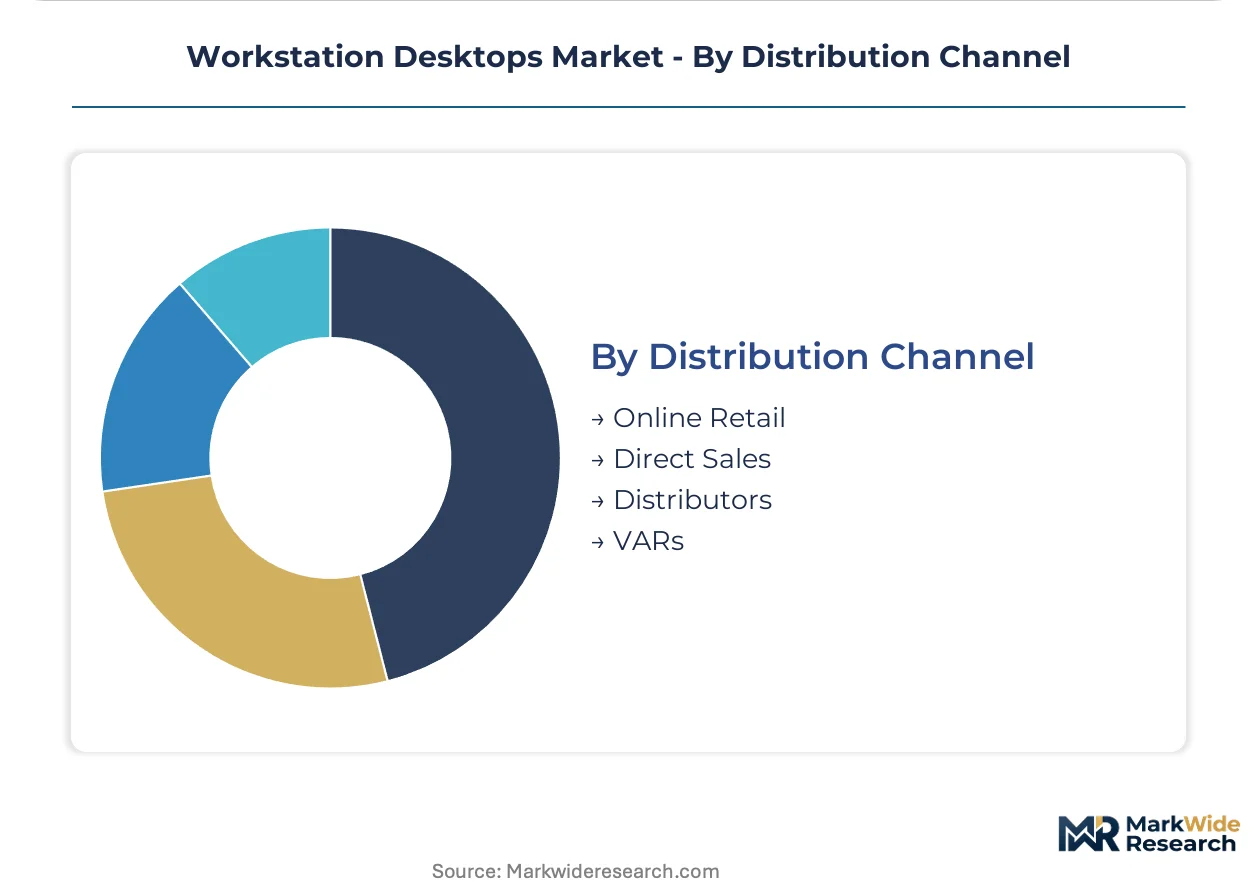
Distribution Channel:
Procurement scale and support integration requirements shape channel selection patterns.
- Direct Sales:Enterprise account teams configure fleet deployments with customized imaging and three-year on-site service. Public sector tenders in Germany and France mandate direct manufacturer relationships for EPEAT compliance documentation.
- VARs:Value-added resellers bundle ISV licensing, deployment services, and tier-one support for boutique studios. Toronto and Sydney architecture practices rely on these relationships for 18-month refresh guarantees.
- Distributors:Broadline wholesalers stock standard SKUs for regional system integrator channels. Inventory fragmentation complicates multi-country rollout coordination.
- Online Retail:E-commerce platforms serve individual creators and small studios with credit-card purchasing and rapid delivery. Configuration limitations restrict this channel to non-certified consumer-prosumer overlap segments.
Direct sales capture the largest contract values; VAR relationships are deepening fastest among mid-size creative enterprises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The workstation desktop industry traces its commercial origins to Silicon Valley engineering labs and German automotive design centers, where early CAD systems demanded dedicated computational hardware. Today procurement concentrates in industrial automation corridors and media production clusters across five major economies.
United States
Los Angeles post-production studios and Austin engineering consultancies drive GPU-dense tower configurations for real-time rendering pipelines. The EPA Energy Star program mandates standby power thresholds below 0.5 watts for federal procurement eligibility. Seattle-area cloud infrastructure providers deploy rack-mounted workstations for edge AI inference in manufacturing quality control.
Germany
Stuttgart and Wolfsburg automotive engineering clusters sustain demand for ISV-certified systems with ECC memory and redundant storage arrays. The EU Ecodesign Directive compels power supply redesigns to meet standby consumption limits. Bavarian industrial automation consultancies upgrade fleets ahead of regional energy efficiency procurement mandates.
China
Shenzhen and Beijing media technology parks scale generative AI training infrastructure using domestically assembled GPU accelerators. The MIIT establishes power efficiency standards for high-performance computing equipment sold to state research institutions. Yangtze River Delta manufacturing hubs integrate workstation-class edge nodes for factory-floor computer vision inspection.
United Kingdom
London VFX boutiques and Manchester architectural visualization studios adopt workstation-as-a-service contracts to align hardware refresh with project pipelines. The UK implements EU-derived Ecodesign requirements through the Office for Product Safety and Standards. Cambridge engineering consultancies specify liquid-cooled tower configurations for computational fluid dynamics workloads.
India
Chennai and Sri City assembly zones attract Dell, HP, and Lenovo under the PLI scheme for IT hardware manufacturing. The BIS enforces standby power standards for imported computing equipment. Bangalore design studios and Hyderabad animation clusters expand procurement of mid-tier tower workstations for independent content production.
Workstation Desktops Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the workstation desktop supply chain, with branded OEMs maintaining in-house assembly while component specialists focus on chip and board design. The vendor base separates into three tiers: multinational enterprise fleet suppliers, regional system integrators, and boutique performance builders. Consolidation pressures intensify as GPU supply concentration and ISV certification costs raise barriers to scale. Dominant competitive moves include geographic manufacturing relocation under trade incentive programs and strategic partnerships with professional software vendors for synchronized driver validation.
Within the multinational tier, Dell Inc., HP Inc., and Lenovo Group Limited exemplify divergent channel strategies. Dell anchors enterprise positioning through direct sales relationships with engineering accounts. HP maintains density of ISV certifications across media and entertainment verticals. Lenovo occupies the price-performance vector for small and medium design studios. These three collectively represent the scale-driven end of procurement, though regional specialists like Puget Systems and Velocity Micro occupy positions in the custom performance segment.
| Leading Market Players |
|---|
| Dell |
| HP |
| Lenovo |
| Intel |
| Acer |
| Gigabyte |
| Puget Systems |
| Velocity Micro |
| Supermicro |
| Others |
Pricing and Supply Chain Analysis
Captive production of high-wattage power supply units anchors both supply resilience and margin control for tier-one workstation OEMs. Dell, HP, and Lenovo maintain in-house chassis and thermal assembly while sourcing discrete GPUs and ECC memory from concentrated Asian supplier bases.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ISV-certified enterprise fleets from prosumer configurations. Price differentiation rests on certification density and thermal envelope capacity. Cost compression in mid-tier tower configurations is intensifying because Lenovo's aggressive price-performance positioning squeezes regional system integrators. Boutique content creators exhibit highest price sensitivity; engineering consultancies purchasing through direct enterprise channels show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Korean and Taiwanese suppliers controlling high-capacity ECC DRAM module output. Component sourcing draws from Taiwan for advanced GPUs, South Korea for memory modules, and China for chassis and power supply assemblies. Silicon carbide MOSFET shortages create procurement bottlenecks for 1000-watt thermal envelope designs. Distribution runs through direct sales for enterprise fleets, VARs for mid-size creative studios, and broadline distributors for regional system integrator channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The workstation desktop market functions as a regulatory compounder where EU Ecodesign Directive standby power mandates accelerate hardware refresh cycles across German engineering clusters.
For Market Incumbents: To counter GPU supply concentration and ISV certification cost inflation, Dell and HP should deepen captive supply of liquid-cooled chassis architectures while expanding direct enterprise channel control in Stuttgart and Wolfsburg automotive engineering corridors. For New Entrants and Emerging Players: Capture white-space in workstation-as-a-service subscription models for Copenhagen and Amsterdam architecture practices, and in edge AI inference rack configurations for Yangtze River Delta factory-floor deployments. Partner with NVIDIA for RTX-class GPU allocation guarantees. For Investors and Strategic Acquirers: Roll-up economics work for regional system integrators with ANSYS thermal simulation competency because 600-watt GPU packages demand scarce chassis airflow engineering expertise. Monitor BIS export control expansion as inflection signal for SKU fragmentation costs.| Strategic Initiative | Industry Significance |
|---|---|
| ISV Certification Density Expansion | Autodesk and Dassault Systèmes validation locks in engineering account retention. |
| Liquid Cooling Infrastructure Partnership | Quick-disconnect loop standardization reduces facility HVAC retrofit costs for Munich consultancies. |
| India PLI Manufacturing Relocation | Chennai and Sri City assembly satisfies domestic content rules for government tenders. |
| Subscription Hardware Provisioning Launch | Monthly workstation-as-a-service contracts reduce capital barriers for Toronto architecture studios. |
| Edge AI Inference Node Development | Rack-mounted configurations displace servers in automotive paint shop quality inspection. |
Research Methodology
Coverage spans the United States, Germany, China, the United Kingdom, and India, with primary inputs from each. The research combines interviews with workstation procurement managers at engineering consultancies, ISV certification directors, thermal design engineers, and channel sales executives at VARs with secondary validation from EPA Energy Star documentation, EU Ecodesign Directive regulatory filings, SEC 10-K disclosures from tier-one OEMs, and BIS export control licensing records. Bottom-up unit shipment estimates triangulate against top-down value projections.
Rate-of-change decomposition separates volume growth from average selling price movements across the analysis window. The analytical framework models segmentation across form factor, end user vertical, GPU technology tier, and distribution channel. CAGRs derive from weighted regression of historical refresh cycles against projected generative AI infrastructure buildouts and EU regulatory compliance deadlines. Industry-specific inputs include NVIDIA H100 allocation patterns and German automotive engineering cluster procurement timelines.
Semiconductor export control expansion, DRAM supply volatility, and F-Gas Regulation compliance cost escalation are the dominant revision risks. Forecasts reflect assumptions about GPU availability and ISV certification synchronization timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Underwater Communication System Market
Others
Singapore Retail Market
Others
Thermal Insulation Solution for LNG and LPG Market
Others
High Frequency Vibrator Market
Others
Pickup Truck Market
Others
Double Card Mobile Phone Market
Others
Europe Digital Experience Platform Market
Others
Smart Card Contactless Ticketing Market
Others
Military Sensors Market
Others
United States Cigarette Market
Others
Exosome Technologies Market
Others
Australia Content Services Platform Market
Others
Japan Automotive LED Lighting Market
Others
Wearable Brain Devices Market
Others
Pediatric Measuring Devices Market
Others
Augmented Reality (AR) in Warehousing and Logistics Market