
 Pediatric Measuring Devices Market | 2026-2036
Pediatric Measuring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Pediatric Measuring Devices Market Outlook
Home care providers is redrawing procurement patterns in the Pediatric Measuring Devices Market as parents seek clinical-grade monitoring outside traditional settings. Seca GmbH & Co. KG anchors European manufacturing scale with precision mechanical and electronic systems for pediatricians. Natus Medical Incorporated specializes in neonatal measurement technologies for hospital NICU environments. Philips Healthcare extends its digital health ecosystem into connected growth-monitoring platforms for integrated care networks.
Pediatric measuring devices encompass calibrated instruments designed to capture anthropometric parameters in infants and children, typically resolving to 0.1 centimeter precision for length and 10-gram resolution for weight to track developmental trajectories against WHO growth standards. These instruments serve primary care, subspecialty clinics, and research institutions requiring reproducible longitudinal data for early intervention decisions. Digital measuring devices command premium positioning as healthcare systems replace legacy mechanical tools with Bluetooth-enabled, EMR-integrated platforms that reduce transcription errors. Ultrasonic measurement technology is gaining fastest in neonatal applications where contactless acquisition minimizes handling stress. Growth monitoring applications generate the deepest margin pools due to recurring calibration contracts and software subscription attach rates.
FDA 510(k) clearance requirements and EU MDR technical documentation obligations shape product development cycles and market access timelines for device manufacturers seeking dual-territory placement. ISO 13485 quality management certification and IEC 60601 electrical safety standards further constrain supplier qualification, favoring established players with dedicated regulatory affairs infrastructure. Stakeholders must monitor evolving cybersecurity guidance from FDA and notified bodies as connected pediatric devices proliferate in home and ambulatory settings.
Market Dynamics
EU MDR compliance deadlines are compressing procurement cycles for digital pediatric measurement platforms, forcing Western European hospitals to accelerate replacement of mechanical legacy systems with sensor-integrated devices that automate WHO growth standard documentation.
Growth Catalysts
- EU MDR technical documentation mandates:German and French pediatric clinics must complete conformity assessments for legacy mechanical devices by 2027-2028, creating replacement demand for certified digital stadiometers and infant scales.
- Bluetooth-enabled EMR integration:Hospital systems are prioritizing wireless data transmission to eliminate transcription errors in longitudinal growth tracking, accelerating sensor-based platform procurement.
- Neonatal contactless measurement:Ultrasonic length acquisition without physical handling stress is gaining preference in NICU environments where minimizing infant disturbance supports clinical outcomes.
Market Restraints
- ISO 13485 certification barriers:Quality management infrastructure requirements favor established manufacturers with dedicated regulatory affairs teams, constraining new market entrants.
- IEC 60601 electrical safety compliance:Testing protocols for connected pediatric devices add 12-18 month development cycles before commercial placement.
- Precision sensor supply concentration:High-resolution load cells and ultrasonic transducers source primarily from German and Japanese component specialists, creating input bottlenecks.
Strategic Opportunities
- Home care channel expansion:Parental demand for clinical-grade growth monitoring outside hospital settings is opening direct-to-consumer distribution for Bluetooth-connected scales.
- Software subscription attach rates:Calibration contracts and growth analytics platforms generate recurring revenue streams beyond hardware margins.
- REACH substance restriction alignment:Lead-free sensor manufacturing compliance positions suppliers for preferential procurement in EU public health tenders.
Industry Challenges
- Cybersecurity validation timelines:FDA and notified body guidance for connected pediatric devices remains evolving, creating uncertainty in premarket submission requirements.
- Biomedical engineering talent scarcity:Specialized expertise in pediatric anthropometric measurement design concentrates in Seca GmbH's Hamburg facility and select Swiss precision instrument clusters.
- Legacy mechanical system integration:Hospital IT departments face complexity bridging decades-old measurement workflows with cloud-based EMR architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pediatric Measuring Devices Market |
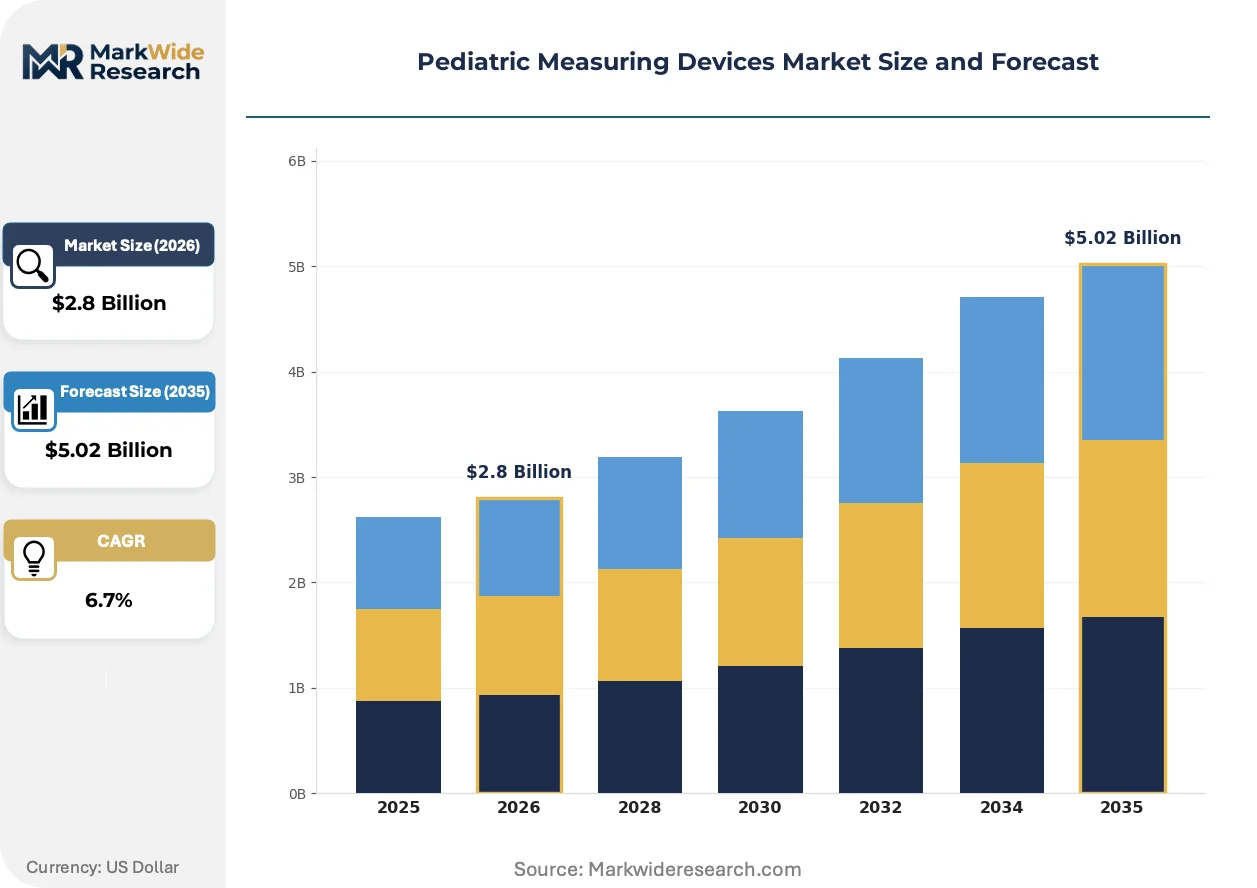
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Height Measuring Tools, Weight Scales, Head Circumference Tapes, Digital Measuring Devices Technology: Ultrasonic Measurement, Electronic Sensors, Optical Sensors, Mechanical Systems End User: Pediatric Clinics, Hospitals, Home Care Providers, Rehabilitation Centers Application: Growth Monitoring, Nutritional Assessment, Clinical Research, Daily Check-Ups |
| Companies Covered | Seca GmbH & Co. KG, Natus Medical Incorporated, Hill-Rom Holdings, Inc., Medtronic plc, GE Healthcare, Philips Healthcare, Welch Allyn, Inc., Masimo Corporation, Drägerwerk AG & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pediatric Measuring Devices Market Strategic Shifts
Digital health convergence is redefining pediatric measurement from isolated clinical instruments to networked data nodes within integrated care ecosystems, compressing hardware replacement cycles while elevating software and service revenue components.
Ultrasonic length measurement technology is miniaturizing from cart-based hospital systems to handheld devices suitable for ambulatory and home settings. Community health programs in Nordic countries are piloting portable units for rural infant screening. This miniaturization is collapsing the traditional boundary between clinical-grade and consumer-accessible measurement precision.
EU MDR's Unique Device Identification requirements are mandating serialized traceability for all Class I pediatric measuring devices by 2026. Manufacturers must reconfigure production lines for automated labeling and database registration. German notified bodies are experiencing 40% application backlogs, delaying market access for updated product portfolios.
Parents are demanding ownership of longitudinal growth data, disrupting traditional hospital-controlled record architectures. Direct-to-consumer platforms with smartphone-connected scales are capturing measurement sessions previously confined to pediatrician offices. This behavioral shift is most pronounced in Netherlands and UK metropolitan markets where digital health literacy runs highest among millennial caregivers.
Pediatric Measuring Devices Market Segmentation
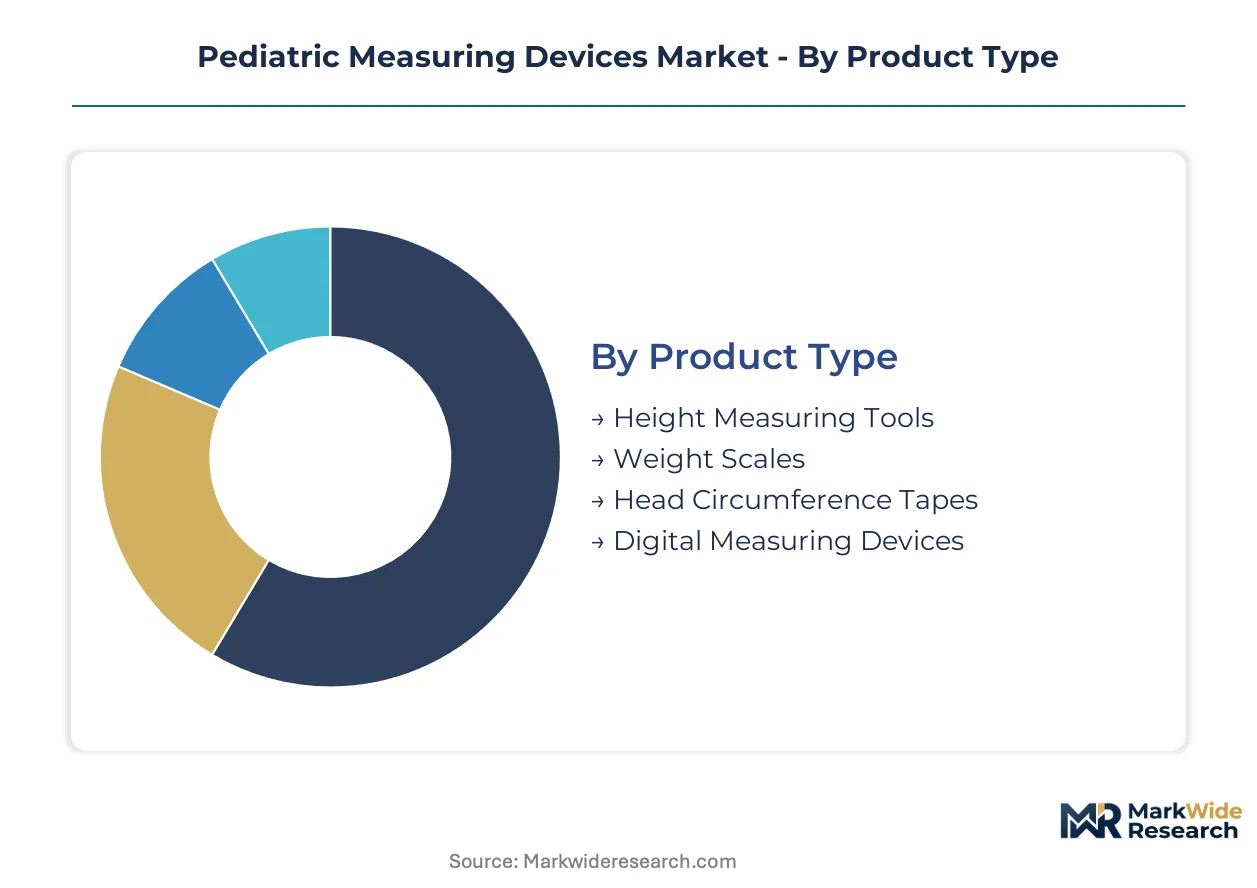
Pediatric measuring devices fragment across four distinct dimensions that determine channel strategy and margin architecture. Product type and technology choices govern manufacturing complexity, while end-user and application segments dictate pricing power and service attach rates.
Product Type:
Distribution channels diverge sharply between institutional procurement and direct-to-consumer pathways, with hospital systems favoring bundled platform purchases while parents buy single-function devices through retail.
- Height Measuring Tools:Stadiometers and length boards resolve to 0.1 centimeter precision for WHO growth standard compliance. Demand concentrates in German and French pediatric clinics replacing mechanical legacy systems under EU MDR deadlines.
- Weight Scales:Infant scales with 10-gram resolution and toddler platforms with 50-gram precision serve distinct age cohorts. Bluetooth-enabled models for home care providers are expanding fastest as millennial caregivers seek clinical-grade monitoring outside hospital settings.
- Head Circumference Tapes:Non-stretch fiberglass tapes with 0.1 centimeter graduations remain the standard for cranial assessment in neonatal units.
- Digital Measuring Devices:Integrated platforms combining length, weight, and BMI calculation with EMR connectivity command premium positioning in hospital procurement tenders.
Height measuring tools dominate installed base. Digital measuring devices are where expansion concentrates.
Technology:
Cost tier stratification separates premium sensor platforms from economy mechanical alternatives, with mid-tier electronic systems capturing volume in community health programs.
- Ultrasonic Measurement:Contactless length acquisition via high-frequency transducers eliminates physical handling stress for neonates. Nordic community health pilots are deploying portable units for rural infant screening.
- Electronic Sensors:Strain gauge load cells and capacitive position sensors enable Bluetooth data transmission to EMR systems. Western European hospital systems prioritize these for transcription error elimination.
- Optical Sensors:Structured light and time-of-flight cameras capture 3D anthropometric data for research applications.
- Mechanical Systems:Spring scales and sliding calipers persist in resource-constrained settings but face EU MDR phase-out pressures.
Mechanical systems retain volume in emerging markets. Ultrasonic measurement is climbing the fastest.
End User:
Customer type determines service intensity, with hospitals demanding calibration contracts and home users prioritizing smartphone app integration over technical support.
- Pediatric Clinics:Primary care settings require compact, multi-function devices for high-throughput well-child visits. German clinic chains are consolidating procurement through group purchasing organizations.
- Hospitals:Tertiary centers demand NICU-grade precision with serialized traceability for EU MDR Unique Device Identification mandates.
- Home Care Providers:Parental self-monitoring creates direct-to-consumer demand for Bluetooth-connected scales with growth tracking apps. Netherlands and UK metropolitan markets show highest digital health literacy adoption.
- Rehabilitation Centers:Specialized seating and positioning clinics need anthropometric data for custom orthotic fabrication.
Hospitals command the deepest margin pools. Home care providers are gaining share fastest.
Application:
Volume concentration sits in routine clinical workflows, while margin expansion follows research and premium home monitoring use cases.
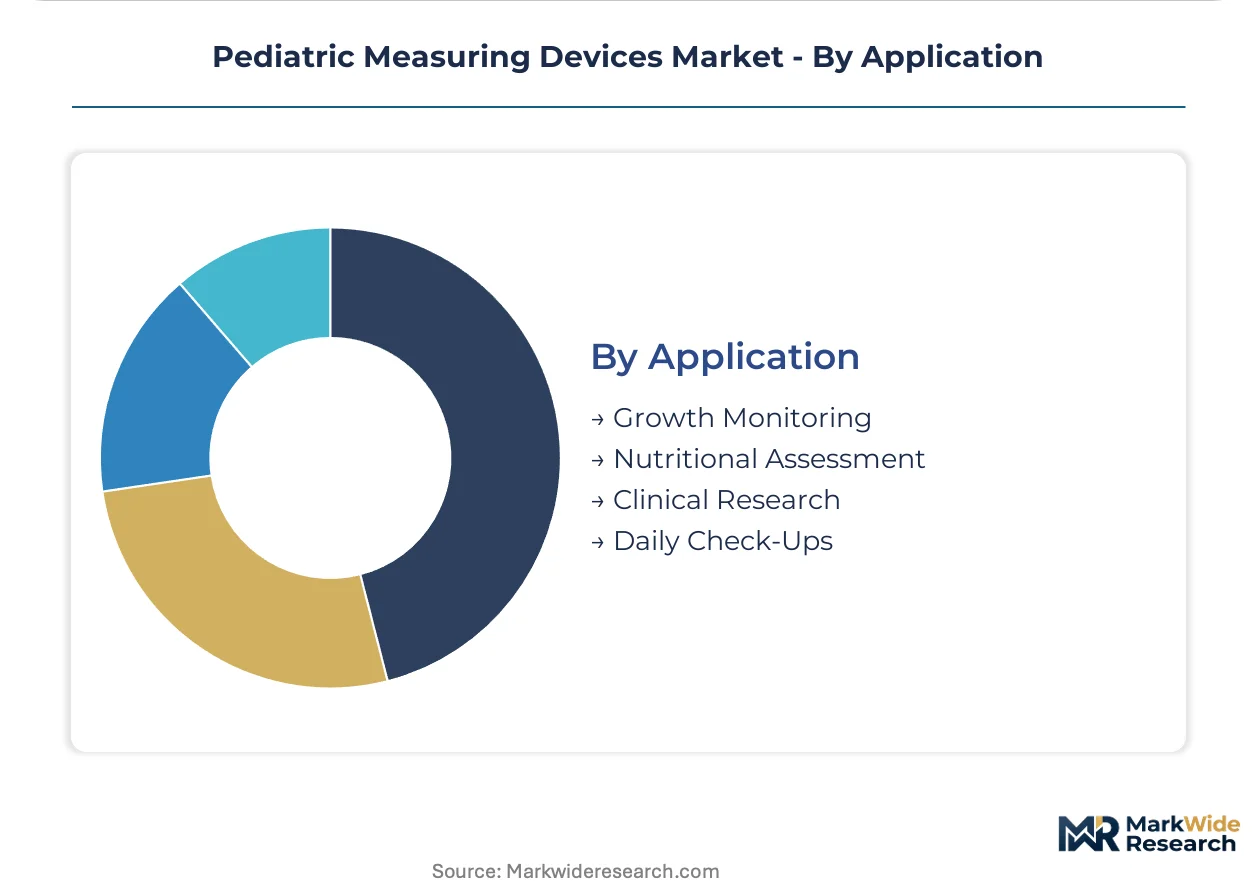
- Growth Monitoring:Longitudinal tracking against WHO standards requires calibrated instruments with documented measurement uncertainty. Recurring calibration contracts generate service revenue beyond hardware sales.
- Nutritional Assessment:Weight-for-height indices support feeding intervention decisions in malnutrition protocols.
- Clinical Research:Multi-site studies demand inter-device reproducibility within 0.3 centimeters for length and 20 grams for weight.
- Daily Check-Ups:Routine screening in busy pediatric practices prioritizes speed and workflow integration over absolute precision.
Growth monitoring anchors recurring revenue. Nutritional assessment shows steepest expansion trajectory in low-resource health programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's medical device logistics corridor underwrites German distribution dominance for precision pediatric instruments across continental Europe. Rail links from Hamburg connect manufacturing clusters in Lower Saxony and Bavaria to French hospital networks within 24 hours. This infrastructure backbone shapes procurement patterns for EU MDR-compliant measurement platforms.
Germany
Hamburg and Lower Saxony host concentrated manufacturing of digital stadiometers and infant scales serving pediatric clinic chains. EU MDR technical documentation mandates force replacement of mechanical legacy systems by 2027. Bavarian precision engineering clusters in Nuremberg and Munich supply high-resolution load cells to domestic device assemblers.
France
Parisian hospital systems drive demand for EMR-integrated measurement platforms with Bluetooth connectivity. ANSM notified body backlogs delay market access for updated portfolios. The Lyon-Grenoble medical technology corridor specializes in optical sensor development for research-grade anthropometric applications.
United States
Massachusetts and California pediatric research institutions require inter-device reproducibility within 0.3 centimeters for multi-site clinical trials. FDA 510(k) clearance timelines shape product development cycles for connected devices. The Minneapolis medical device cluster anchors Midwestern distribution for hospital procurement networks.
Netherlands
Amsterdam and Rotterdam metropolitan markets show highest digital health literacy adoption among millennial caregivers seeking home monitoring solutions. Dutch community health programs pilot portable ultrasonic units for rural infant screening. Eindhoven's sensor technology ecosystem supplies capacitive position sensors to European device manufacturers.
United Kingdom
London and Manchester pediatric clinics consolidate procurement through National Health Service framework agreements. Post-Brexit regulatory divergence from EU MDR creates dual compliance burdens for suppliers. Oxford-Cambridge research corridors demand clinical-grade precision for longitudinal growth studies.
Pediatric Measuring Devices Market Competitive Environment
Listed leaders compete with private specialists across regulatory certification infrastructure, creating tiered market access barriers. The vendor base concentrates around established players with dedicated ISO 13485 quality management systems and IEC 60601 electrical safety validation capabilities. Three archetypes dominate: diversified health technology conglomerates with broad portfolio coverage, precision instrument specialists with deep pediatric anthropometric expertise, and neonatal-focused device developers serving NICU environments. Competitive moves center on M&A for regulatory infrastructure acquisition and strategic partnerships for EMR integration capabilities.
Among German-based precision instrument fabricators, Seca GmbH & Co. KG anchors European manufacturing scale for mechanical and electronic pediatric systems. Natus Medical Incorporated exemplifies the neonatal specialization archetype with concentrated presence in hospital NICU procurement channels. Philips Healthcare occupies a position within the diversified health technology tier, extending digital health ecosystems into connected growth-monitoring platforms for integrated care networks.
| Leading Market Players |
|---|
| Seca GmbH & Co. KG |
| Natus Medical Incorporated |
| Hill-Rom Holdings, Inc. |
| Medtronic plc |
| GE Healthcare |
| Philips Healthcare |
| Welch Allyn, Inc. |
| Masimo Corporation |
| Drägerwerk AG & Co. KGaA |
| Others |
Value Chain & Pricing Dynamics
EU MDR technical documentation mandates gate both supplier qualification and price differentiation simultaneously, forcing manufacturers to absorb certification costs that stratify offerings across calibration-grade precision tiers while hospital procurement committees weigh total cost of ownership against legacy mechanical replacement timelines.
Pricing Analysis
Volume-discount tiering structures dominate hospital procurement, with German and French pediatric clinic chains extracting 15-25% unit cost reductions through group purchasing organization consolidation. Pricing stratifies across premium sensor-integrated platforms with EMR connectivity, mid-tier electronic systems for community health programs, and residual mechanical alternatives facing EU MDR phase-out. Cost compression in the mid-tier is intensifying as Asian component suppliers enter the load cell market. Home care providers show highest price sensitivity, while tertiary hospital NICU units prioritize precision certification over unit cost.
Supply Chain Analysis
Inventory lead times for high-resolution load cells and ultrasonic transducers have extended to 16-22 weeks, constraining device assembly schedules for Western European hospital tenders. Manufacturing concentrates in Germany, Japan, and Switzerland for precision sensor components, with final assembly clustering in Hamburg and Lower Saxony for EU market access. Component sourcing draws from Bavarian precision engineering clusters for strain gauge elements and Eindhoven for capacitive position sensors. Single-source vulnerability concentrates in German-Japanese transducer supply partnerships. Distribution runs through the Port of Hamburg's medical device logistics corridor to French and Benelux hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bluetooth-enabled EMR interoperability is transforming pediatric measurement from discrete hardware transactions into platform-economics ecosystems, where software subscription attach rates and calibration contract recurrence determine long-term vendor viability more than initial device placement.
For Market Incumbents: Secure ISO 13485 certification infrastructure as a competitive moat against emerging Asian sensor suppliers attempting rapid EU MDR compliance. Defensive consolidation should prioritize backward integration into precision load cell manufacturing to reduce transducer supply bottlenecks. Channel control through exclusive GPO contracts with German clinic chains protects installed base against portable ultrasonic disruptors.
For New Entrants and Emerging Players: FDA 510(k) fast-track pathways offer lower regulatory friction than EU MDR notified body queues for initial market traction. The home care segment presents the most penetrable white-space, with Netherlands and UK metropolitan markets showing highest digital health literacy for direct-to-consumer Bluetooth scale launches. A software-first go-to-market angle—lead with growth tracking app adoption, follow with hardware bundling—sidesteps incumbent hospital procurement lock-in.
For Investors and Strategic Acquirers: EU MDR's 2027-2028 legacy device phase-out deadlines reshape the acquisition landscape toward regulatory-ready portfolios with completed technical documentation. Five-to-ten year viability favors targets with established notified body relationships and serialized traceability production lines already configured. The signal to watch is German notified body application backlog clearance rates as an inflection indicator for market access velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Completion | Notified body approval unlocks German and French pediatric clinic replacement procurement cycles. |
| Bluetooth EMR Integration Partnership | Epic and Cerner connectivity agreements differentiate sensor platforms in hospital tenders. |
| Ultrasonic Transducer Supply Agreement | Japanese component partnerships secure resolution specifications for NICU-grade contactless measurement. |
| Home Care Direct-to-Consumer Launch | Netherlands millennial caregiver adoption builds recurring software subscription revenue streams. |
| Calibration Service Network Expansion | On-site ISO 17025 traceability contracts deepen margin pools beyond hardware replacement cycles. |
Study Parameters
The analysis maps digital stadiometers, infant scales, ultrasonic length systems, and mechanical legacy alternatives, each validated through pediatric clinic procurement managers, hospital biomedical engineers, GPO contracts specialists, and notified body regulatory consultants. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement tender records, and ISO 13485 certification registries. Bottom-up device shipment estimates triangulated against top-down healthcare capital expenditure patterns across German, French, and Benelux hospital systems.
Consistency checks validated volume and value outputs against external benchmarks including WHO growth standard implementation timelines, EU medical device trade flows, and pediatric clinic infrastructure investment disclosures. The analytical framework models product type, technology tier, end-user segment, and application use case dimensions across the projection horizon. CAGRs derive from segment-level demand elasticity analysis calibrated to replacement cycle compression under EU MDR deadlines and home care channel expansion trajectories. Forecast inputs include notified body capacity constraints, precision sensor lead time trends, and EMR interoperability adoption curves.
Decision-makers should treat outputs as directional under assumptions of sustained EU MDR enforcement timelines and stable Bluetooth connectivity standards adoption; material deviation in regulatory delay or sensor supply disruption would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Mainframe Market
Others
Global Mobile Video Optimization Market
Others
North America Astrology Market
Others
Cat Food Market
Others
IoT Testing Market
Others
Global Enterprise Mobility in Healthcare Market
Others
Inflight Entertainment Solutions Market
Others
Thailand Travel Retail Market
Others
Underwater Communication System Market
Others
Mexico Retail Market
Others
Dried Egg Market
Others
Running Apparel Market
Others
UK Automotive LED Lighting Market
Others
Middle East and Africa Halal Food & Beverage Market
Others
Italy Feed Additives Market
Others
China Packaging Primers Market