
 Smart Card Contactless Ticketing Market | 2026-2036
Smart Card Contactless Ticketing Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Card Contactless Ticketing Market Analytics
Polycarbonate is displacing PVC as the substrate of choice for durable contactless transit cards, which is realigning unit economics across the card manufacturing tier. NXP Semiconductors leverages its secure-element portfolio to anchor supply relationships with tier-one transit system integrators. Thales Group competes through vertically integrated personalization and digital-ticketing platforms that span physical and mobile issuance. Giesecke & Devrient GmbH specializes in high-volume EMV-compliant card production for European transport authorities demanding interoperability.
Smart card contactless ticketing denotes a credential-based fare collection system wherein a microprocessor-embedded card communicates wirelessly with transit validators via 13.56 MHz radio frequency, typically storing value or trip entitlements in EAL-certified secure elements. The technology serves to reduce dwell time at gates, eliminate cash handling, and enable account-based back-office reconciliation for complex multimodal networks. Single Journey products dominate transaction volume in emerging systems yet carry thin margins, while Monthly Pass categories concentrate recurring revenue and customer lock-in for mature operators. Cloud-Based deployment is expanding fastest as agencies seek to offload infrastructure capital and enable real-time fare policy adjustments, though On-Premise architectures persist where data sovereignty requirements or legacy integration constraints apply.
The European Commission's F-Gas Regulation and GDPR framework shape product design by restricting fluorinated greenhouse gases in card lamination and mandating strict passenger data governance for account-based systems. In the United States, the Federal Transit Administration and PCI Security Standards Council jointly influence procurement specifications by tying capital grants to open-payment readiness and tokenized transaction security. India's BIS certification and CDSCO-equivalent transit standards under the Ministry of Housing and Urban Affairs enforce domestic manufacturing quotas and electromagnetic compatibility testing for metro procurement tenders. Stakeholders must weigh the capital efficiency of cloud migration against the operational autonomy that on-premise architectures preserve as regulatory fragmentation around data localization intensifies.
Market Dynamics
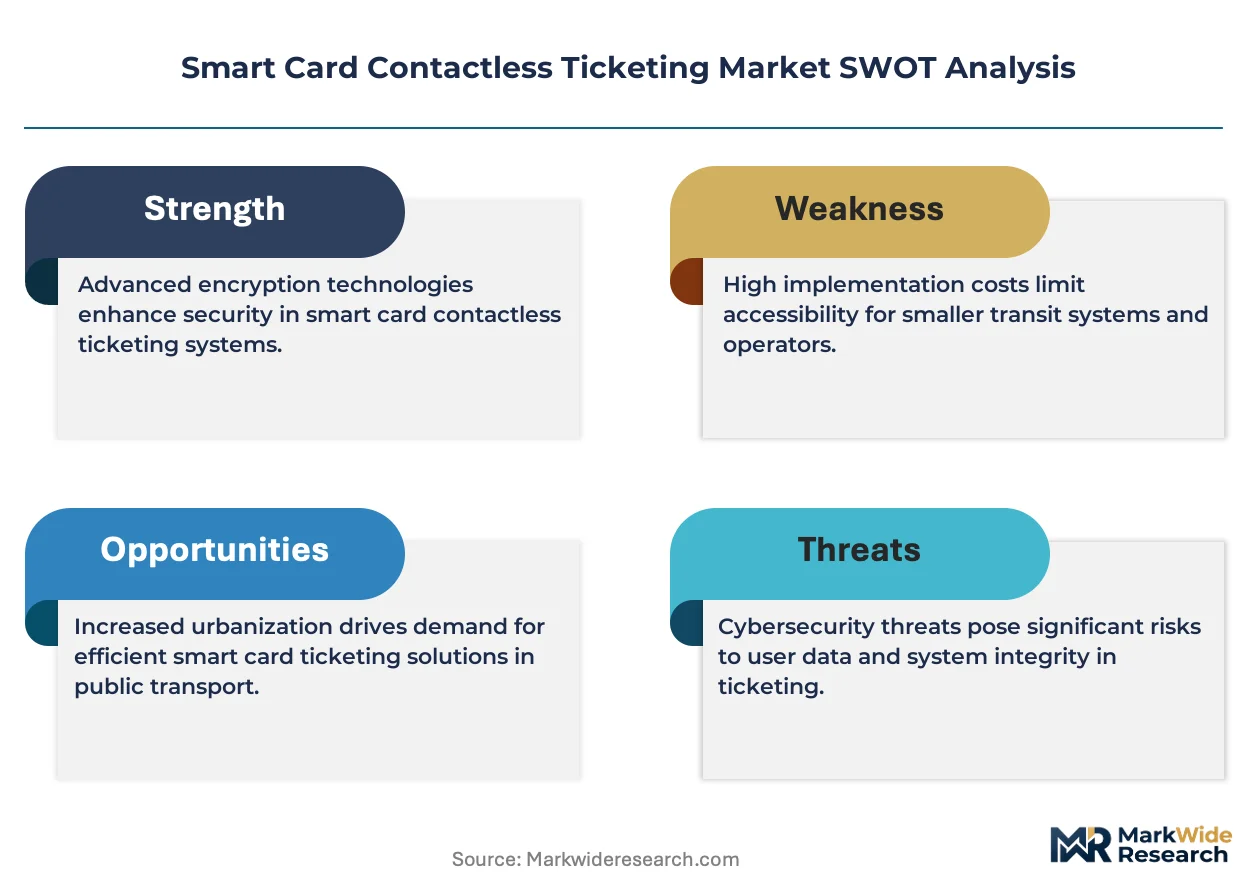
Open-loop payment mandates from financial regulators across multiple continents are forcing transit operators to retool fare collection infrastructure. This regulatory pressure is compressing procurement cycles and reshaping vendor relationships throughout the smart card ecosystem.
Growth Catalysts
- EMV Compliance Mandates:Transit operators in Europe and North America face binding requirements from financial regulators to accept contactless bank cards, accelerating validator hardware replacement cycles.
- Polycarbonate Substrate Migration:Card manufacturers are shifting from PVC to polycarbonate materials, extending product lifespans and reducing replacement frequency for high-volume transit agencies.
- India's Metro Expansion:The National Common Mobility Card program is driving interoperable contactless standards across urban transit networks, creating standardized demand for EMV-compliant secure elements.
Market Restraints
- Secure Element Supply Concentration:Production of EAL-certified chips concentrates among a limited set of semiconductor foundries, exposing transit operators to allocation risk during demand surges.
- GDPR Data Governance Costs:Account-based ticketing systems in Europe face strict passenger data localization requirements, increasing cloud architecture complexity and compliance overhead.
- Mobile Wallet Substitution:Smartphone-based transit credentials are displacing physical card issuance in mature markets, compressing unit volumes for card manufacturers.
Strategic Opportunities
- Cloud Migration Tailwinds:Transit agencies in Germany and France are offloading infrastructure capital to cloud-based fare management platforms, enabling real-time policy adjustments without on-premise hardware.
- Multimodal Integration:Convergence of transit cards with bike-share and parking systems is creating bundled mobility-as-a-service platforms in Scandinavian urban clusters.
- India's Tier-2 City Penetration:Bus rapid transit systems in Surat, Kochi, and Ahmedabad remain underpenetrated by contactless systems, offering greenfield deployment potential.
Industry Challenges
- Legacy Validator Integration:Retrofitting decades-old turnstile infrastructure with NFC readers requires custom mechanical engineering and extended station closure windows.
- Electromagnetic Compatibility Certification:India's BIS testing protocols for metro procurement tenders impose lengthy approval timelines that delay project commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Card Contactless Ticketing Market |
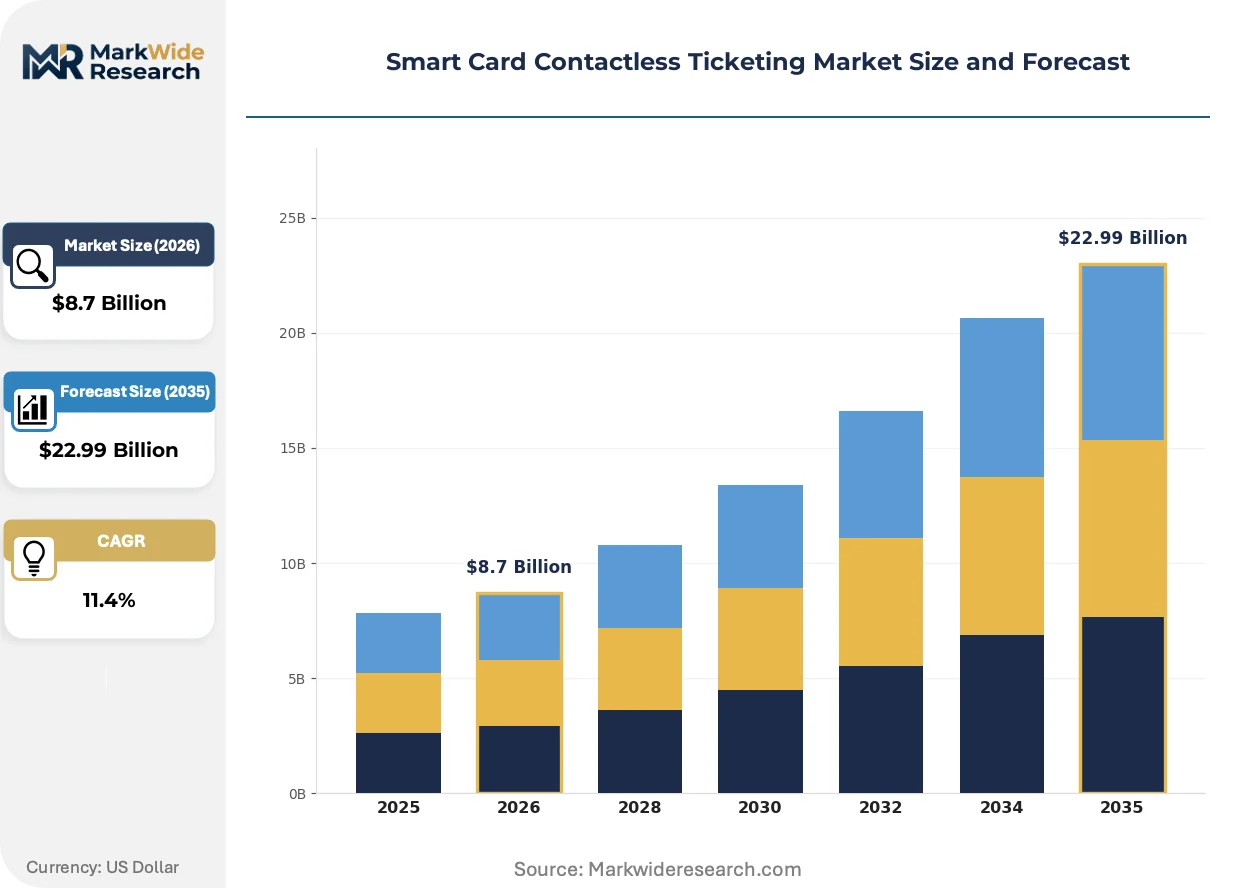
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Journey, Multi Journey, Day Pass, Monthly Pass Deployment: On-Premise, Cloud-Based, Hybrid, Mobile End User: Transportation Authorities, Transit Operators, Event Organizers, Retailers Technology: RFID, NFC, Barcode, Magnetic Stripe |
| Companies Covered | Cubic Corporation, Thales Group, NXP Semiconductors, IDEMIA, Giesecke & Devrient GmbH, CPI Card Group Inc., Infineon Technologies AG, HID Global Corporation, Scheidt & Bachmann GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Card Contactless Ticketing Market Evolving Landscape
Credential technology is bifurcating between physical card durability improvements and digital-native issuance models. This divergence is fragmenting R&D investment across substrate science and tokenized security architectures.
Polycarbonate substrate technology is expanding into high-frequency transit corridors where card replacement costs dominate lifecycle economics. Operators in London, Singapore, and Tokyo are specifying 10-year durability ratings for new procurements. This material shift is compressing PVC demand while elevating lamination equipment requirements for card manufacturers.
The European Commission's F-Gas Regulation is restricting fluorinated greenhouse gases in card lamination processes, forcing substrate suppliers to reformulate adhesive chemistries. Transit card printers must now certify alternative bonding agents that maintain ISO/IEC 14443 electromagnetic performance. German transport authorities are tightening procurement specifications to exclude non-compliant laminates from tender eligibility.
Account-based ticketing architectures are displacing card-centric stored value systems in North American transit agencies. Chicago's CTA and New York's MTA are migrating trip entitlement to back-office servers, reducing gate transaction latency. This behavioral shift is reallocating capital from card personalization equipment toward API development and token vault infrastructure.
Smart Card Contactless Ticketing Market Segmentation
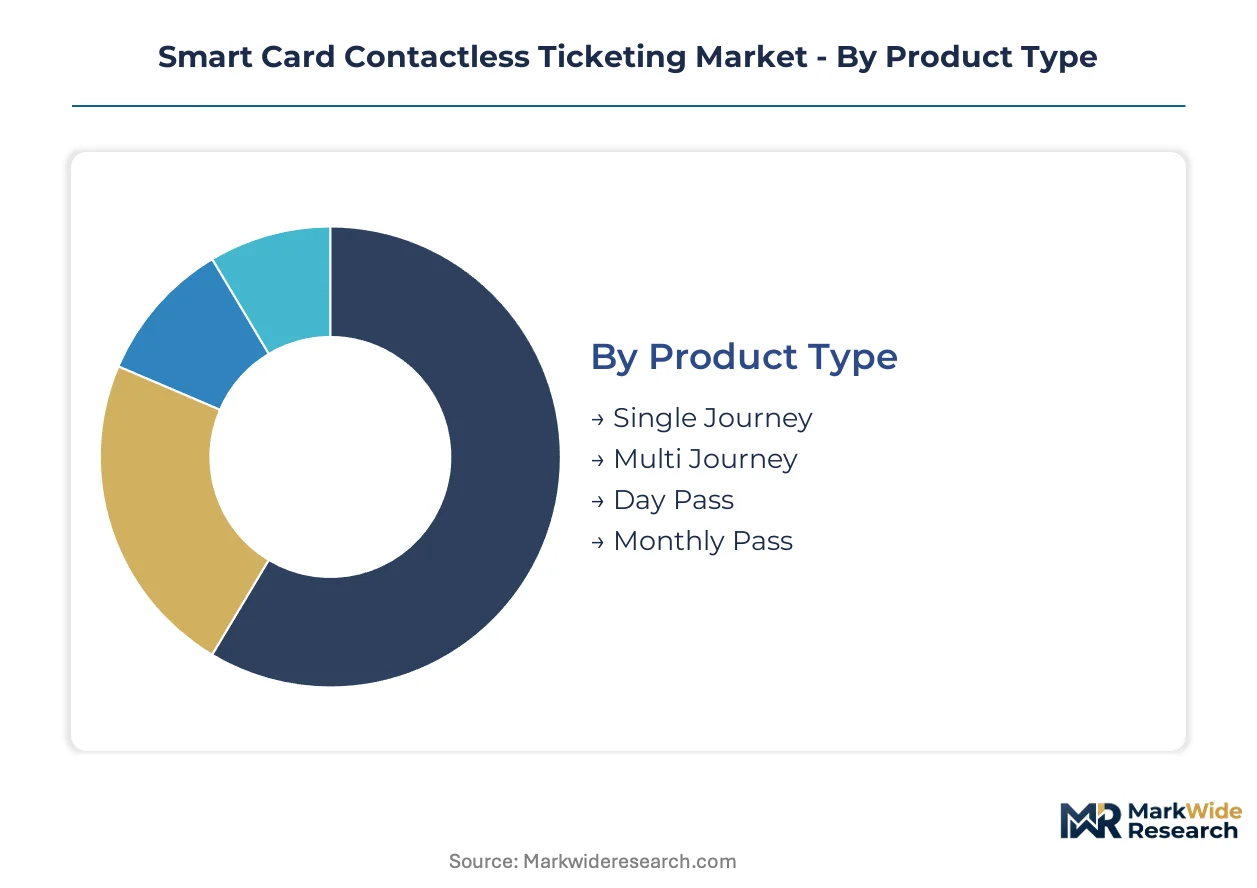
Transit agencies structure procurement around journey patterns, infrastructure maturity, and rider frequency. Each segmentation dimension reveals distinct upgrade cycles and vendor specialization opportunities across the smart card ecosystem.
Product Type:
Replacement cycles vary sharply by journey commitment length, with durable substrates mattering most for recurring-revenue products.
- Single Journey:Disposable paper-based tickets with embedded RFID inlays serve occasional riders and tourist corridors. Demand concentrates in India's expanding metro networks where first-time contactless adoption outpaces carded membership programs.
- Multi Journey:Stored-value credentials with polycarbonate bodies withstand high-frequency gate interactions across London's Underground and Tokyo's JR lines. Operators specify 10-year durability ratings to minimize replacement logistics.
- Day Pass:Time-bound entitlements suit event-driven demand spikes and leisure travel patterns in European city centers.
- Monthly Pass:Subscription-locked credentials generate predictable revenue streams for mature operators in Singapore and Seoul.
Volume placements concentrate in Single Journey products; the faster expansion belongs to Monthly Pass categories as account-based systems displace pay-per-ride models.
Deployment:
Capital efficiency pressures are rebalancing infrastructure ownership between agency balance sheets and vendor-hosted platforms.
- On-Premise:Agencies in Germany and France retain physical server farms to satisfy GDPR data localization mandates. Procurement specifications exclude cloud-native validators from critical path infrastructure.
- Cloud-Based:Real-time fare policy adjustments and API-driven multimodal integration attract North American operators seeking to offload depreciation burdens. Chicago's CTA exemplifies this migration trajectory.
- Hybrid:Split architectures preserve sensitive passenger data on-premise while pushing transaction processing to vendor clouds.
- Mobile:Smartphone-native credentials eliminate card personalization entirely, compressing hardware revenue for traditional manufacturers.
Cloud-Based deployment is climbing the fastest; On-Premise architectures defend position where sovereignty requirements harden.
End User:
Procurement sophistication diverges between public agencies with grant compliance obligations and private operators optimizing for throughput economics.
- Transportation Authorities:Metropolitan planning organizations in India and the United States bundle multimodal specifications into single tender packages. BIS certification and FTA capital grant requirements shape vendor eligibility.
- Transit Operators:Private concessionaires in Brazil and Mexico prioritize validator uptime guarantees over customization depth.
- Event Organizers:Temporary credential issuance for stadiums and festivals demands rapid personalization turnaround.
- Retailers:Closed-loop gift card programs leverage transit-grade security for loyalty applications.
Transportation Authorities dominate absolute spend; Transit Operators are expanding most quickly as concession contracts proliferate.
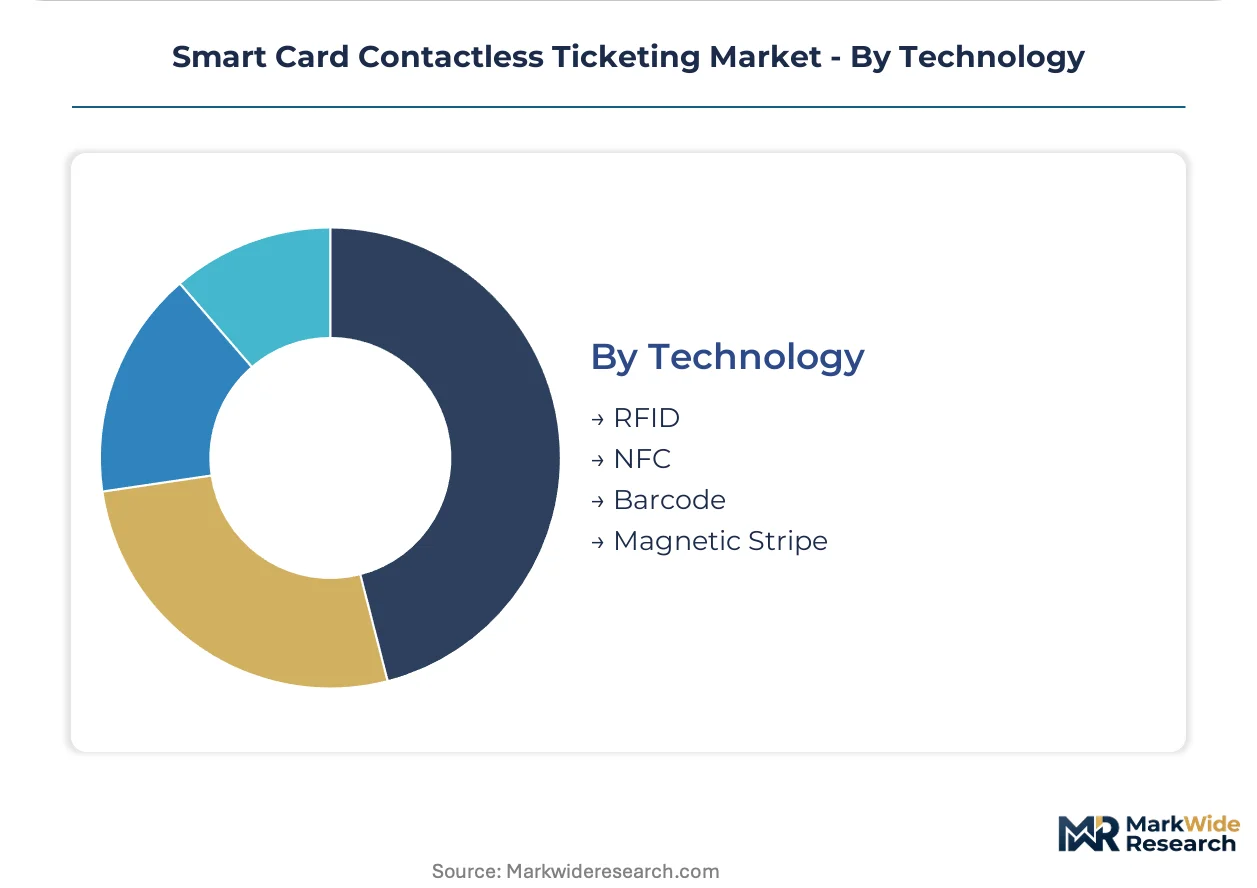
Technology:
Validator hardware refresh cycles are compressing as open-loop mandates force multi-protocol acceptance.
- RFID:Legacy 13.56 MHz implementations persist in closed-loop campus and corporate shuttle systems. Replacement demand concentrates where proprietary protocols face interoperability pressures.
- NFC:EMV-compliant contactless readers anchor new procurements across Europe and North America. India's National Common Mobility Card standardizes on NFC for metro-bus interoperability.
- Barcode:Visual scan credentials serve backup acceptance and low-cost backup channels.
- Magnetic Stripe:Sunset technology persists only where validator replacement capital remains constrained.
NFC commands the steepest expansion trajectory; Magnetic Stripe installations are contracting fastest as agencies retire legacy infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates the most visible near-term demand as metro rail expansion accelerates across tier-1 and tier-2 urban corridors. The National Common Mobility Card program is standardizing interoperable contactless standards that reshape procurement specifications for validator hardware and secure element supply.
United States
Chicago's CTA and New York's MTA are migrating trip entitlement to back-office servers under account-based architectures. The Federal Transit Administration ties capital grants to open-payment readiness, compressing validator replacement cycles. Validator hardware procurement concentrates in legacy corridor retrofits across the Northeast Corridor.
Germany
Transport authorities in Berlin and Munich specify 10-year durability ratings for polycarbonate transit credentials. The F-Gas Regulation restricts fluorinated greenhouse gases in card lamination, forcing adhesive chemistry reformulation. German card printers now certify alternative bonding agents to maintain ISO/IEC 14443 electromagnetic performance.
India
Metro rail expansion in Delhi, Mumbai, Bangalore, and Kochi drives standardized EMV-compliant secure element demand. BIS certification and Ministry of Housing and Urban Affairs standards enforce domestic manufacturing quotas and electromagnetic compatibility testing. Bus rapid transit systems in Surat and Ahmedabad remain underpenetrated by contactless systems.
United Kingdom
Transport for London's Oyster system exemplifies mature closed-loop infrastructure facing mobile wallet substitution pressure. GDPR data localization requirements increase cloud architecture complexity for account-based ticketing pilots. The Greater London Authority bundles multimodal specifications into single tender packages for bike-share and parking convergence.
Japan
JR East's Suica and PASMO systems represent high-frequency polycarbonate credential deployments with 10-year replacement cycles. METI standards shape secure element procurement for transit-bus interoperability. Tokyo's validator infrastructure concentrates manufacturer relationships around NFC-reader supply.
Smart Card Contactless Ticketing Market Competitive Landscape
Strategic partnerships dominate the current landscape as transit operators seek end-to-end credential-to-cloud integration. The vendor base organizes around three tiers: semiconductor secure-element suppliers, card manufacturing specialists, and system integrators with validator hardware portfolios. Two strategic archetypes anchor positioning: substrate-science specialists optimizing polycarbonate durability, and platform-integrators spanning physical issuance to mobile tokenization. M&A activity concentrates in personalization equipment and API development capabilities, while geographic expansion targets India's metro procurement windows.
Within the secure-element tier, NXP Semiconductors and Infineon Technologies AG occupy positions anchored by EAL-certified chip portfolios. Thales Group exemplifies the vertically integrated archetype spanning personalization and digital-ticketing platforms. Giesecke & Devrient GmbH represents high-volume EMV-compliant production specialization for European transport authorities.
| Leading Market Players |
|---|
| Cubic Corporation |
| Thales Group |
| NXP Semiconductors |
| IDEMIA |
| Giesecke & Devrient GmbH |
| CPI Card Group Inc. |
| Infineon Technologies AG |
| HID Global Corporation |
| Scheidt & Bachmann GmbH |
| Others |
Value Network & Pricing Analysis
Polycarbonate resin price indices from Northeast Asia cascade through lamination equipment tiers into validator hardware procurement brackets, with European transport authorities absorbing premium substrate costs under F-Gas Regulation compliance mandates while Indian metro agencies optimize for domestic manufacturing quotas.
Pricing Analysis
Volume placements in Single Journey disposable tickets generate thin unit margins that subsidize recurring-revenue Monthly Pass premiums. Price differentiation rests on EAL certification tier and polycarbonate durability rating, with German authorities specifying 10-year lifespan credentials. Cost compression in card manufacturing is intensifying because mobile wallet substitution erodes physical issuance volumes. Municipal transit agencies in emerging systems exhibit highest price sensitivity; mature operators in London and Tokyo prioritize validator uptime guarantees over per-unit procurement costs.
Supply Chain Analysis
Dual-sourcing requirements from India's BIS certification protocols and European GDPR data localization mandates force transit agencies to qualify multiple secure element foundries across Taiwan, Germany, and South Korea. Semiconductor wafer production draws from fluorinated gas-dependent lamination chemistries and EMV-compliant chip architectures. Single-source vulnerability concentrates in EAL-certified secure element supply during metro expansion surges. Distribution runs through system integrators with captive personalization facilities rather than direct card manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart card contactless ticketing market functions as a cost-of-compliance story where the European Commission's F-Gas Regulation creates a barrier-to-entry moat for substrate suppliers with certified alternative bonding agents.
For Market Incumbents: Hedge polycarbonate supply exposure by anchoring relationships with secondary foundries qualified under India's BIS protocols. Secure validator hardware retrofit contracts in the Northeast Corridor before Federal Transit Administration grant windows close. Mobile wallet substitution threatens physical card volumes; prioritize API development for account-based token vault infrastructure. For New Entrants and Emerging Players: Begin with bus rapid transit systems in Surat, Ahmedabad, and Kochi where contactless penetration remains underdeveloped. Target cloud-based fare management platforms for mid-sized French and German agencies seeking GDPR-compliant hybrid architectures. Position through EMV certification consulting bundled with validator hardware procurement. For Investors and Strategic Acquirers: Distressed-cycle entries favor personalization equipment specialists with BIS-qualified manufacturing footprints in India over pure-play secure element traders. Long-term viability hinges on multimodal integration capabilities spanning transit, bike-share, and parking convergence. Watch for India's National Common Mobility Card procurement windows as inflection indicators for validator hardware demand.| Strategic Initiative | Industry Significance |
|---|---|
| EMV Certification Investment | Unlocks transit operator procurement eligibility under European and North American open-loop mandates. |
| Polycarbonate Substrate Scale-Up | Captures 10-year durability specifications from London, Singapore, and Tokyo metropolitan authorities. |
| Cloud Platform Integration | Enables real-time fare policy adjustments for Chicago CTA and New York MTA account-based migrations. |
| Multimodal API Development | Supports Scandinavian mobility-as-a-service bundling across transit, bike-share, and parking systems. |
| India Manufacturing Localization | Satisfies Ministry of Housing and Urban Affairs domestic content requirements for metro tenders. |
Research Methodology
Document review covered transit authority procurement specifications, BIS certification protocols, and F-Gas Regulation compliance filings, complemented by interviews with fare collection system integrators, secure element procurement managers at semiconductor foundries, transit agency CTOs, and validator hardware engineering directors. Secondary validation drew from Federal Transit Administration capital grant disclosures, European Commission transport funding databases, and metro rail expansion tender documents. Bottom-up unit volume estimates triangulated against top-down market sizing from secure element shipment data.
Historical validator replacement cycles were cross-referenced against panel input from transit agency procurement committees to model deployment trajectories across the projection horizon. Segmentation dimensions included product type, deployment architecture, end-user category, and technology protocol. CAGRs were derived from polynomial trend fitting to metro rail expansion pipelines and polycarbonate substrate adoption curves. Industry-specific inputs incorporated National Common Mobility Card procurement schedules and EMV compliance deadline clustering.
Underlying measurement precision varies by segment; cloud-based deployment and NFC technology categories carry tighter precision than magnetic stripe sunset projections. Forecasts reflect assumptions around regulatory deadline adherence and secure element foundry capacity allocation. Deviation in India's metro expansion funding or European F-Gas Regulation enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Channel-In-A-Box (Ciab) Market
Others
Global Recruitment and Staffing Market
Others
Asia-Pacific Battery E-Commerce Market
Others
Corn Fiber Market
Others
Digital Transformation of Maritime Freight Market
Others
Powder Coating Equipment Market
Others
Global Process Equipment Market
Others
Coriolis Meters Market
Others
North America Luxury Car Market
Others
Cloud-Based Streaming Services Market
Others
Latin America Contract Packaging Market
Others
North America Smart Homes Market
Others
Global B2B Enterprise and Industrial Wearables Market
Others
Flexible PVC Films and Sheets Market
Others
Global Smartphone ODM Market
Others
Asia-Pacific Legal Services Market