
 Australia Content Services Platform Market | 2026-2036
Australia Content Services Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Content Services Platform Market Insights
Market Context with Strategic Players
The Australian government's Digital Transformation Agency mandates are expanding requirements for secure, interoperable content management across federal departments. Telstra Corporation Ltd leverages its national telecommunications infrastructure to dominate cloud-hosted content services for public sector clients. Accenture Australia Pty Ltd sustains consulting-led implementations that integrate legacy systems with modern platform architectures. Elcom Technology specializes in intranet and portal solutions that anchor enterprise knowledge management deployments across healthcare and education sectors.
Technical Definition and Structural Segments
Australia Content Services Platform denotes an integrated software environment that captures, manages, stores, preserves, and delivers content and documents related to organizational processes, typically incorporating metadata indexing, version control, and API-based interoperability with enterprise applications. These platforms serve the primary commercial purpose of replacing fragmented file systems with governed, searchable repositories that support compliance audit trails and cross-departmental workflow automation. Cloud-Based deployment models are capturing the fastest expansion as organizations exit capital-intensive on-premises data center commitments, while Workflow Automation applications concentrate margin pools through recurring subscription structures and professional services attach rates. The Healthcare vertical leads contract value due to stringent patient record retention requirements under the My Health Record system, though Financial Services generates higher platform customization revenue.
Regulatory Frame and Forward-Looking Close
The Office of the Australian Information Commissioner enforces the Privacy Act and Notifiable Data Breaches scheme, compelling platform vendors to embed encryption, access logging, and data sovereignty controls. TGA requirements for healthcare record integrity and APRA prudential standards for financial services data retention further segment product compliance roadmaps. Stakeholders must monitor whether proposed reforms to the Privacy Act introduce direct statutory torts for data mishandling, as this would recalibrate liability structures and procurement criteria across all buyer segments.
Market Dynamics
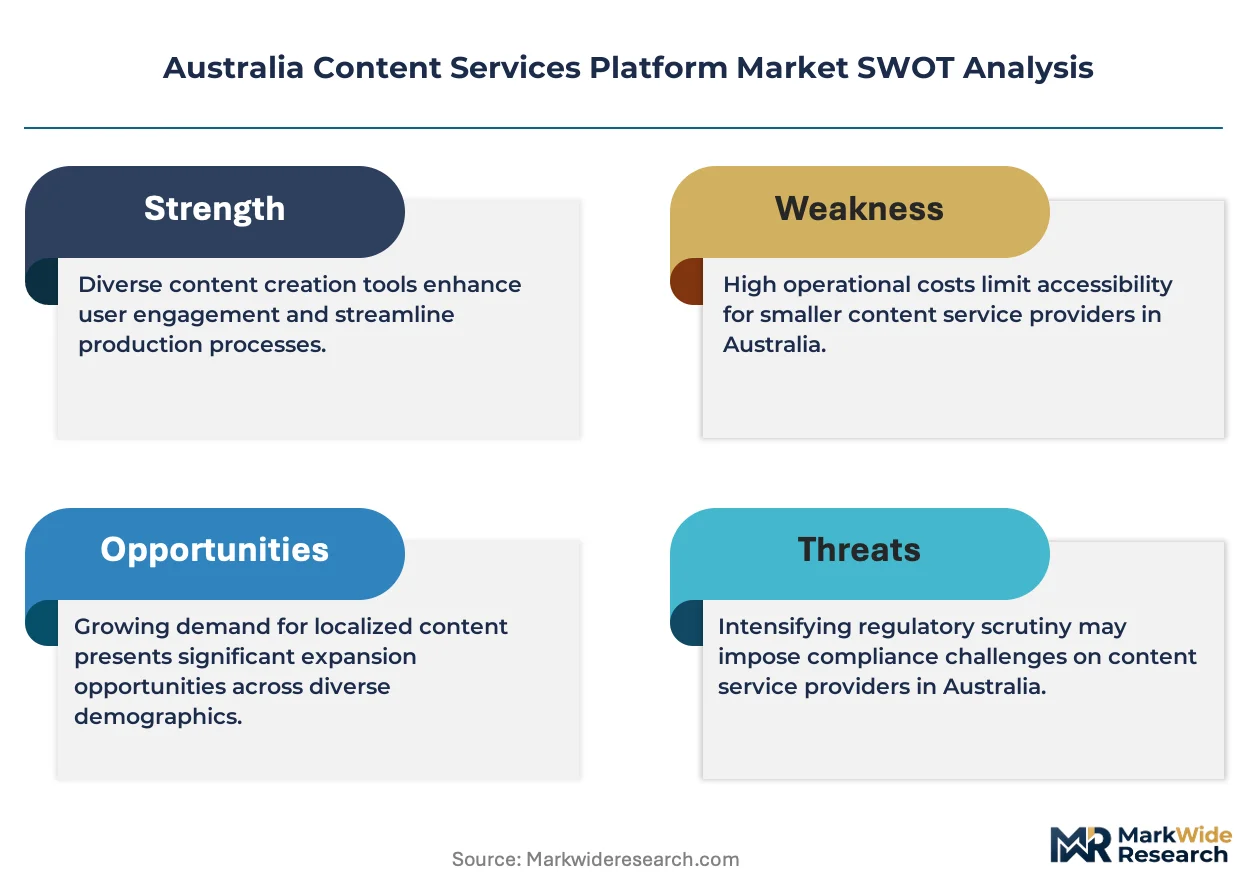
Federal digitization mandates from the Digital Transformation Agency are compressing procurement cycles for secure content platforms, forcing vendors to pre-certify against Privacy Act and Notifiable Data Breaches requirements before contract eligibility.
Growth Catalysts
- My Health Record system:Patient data retention mandates under TGA guidelines are driving healthcare providers toward compliant repository platforms with automated audit trails.
- Privacy Act reforms:Proposed statutory torts for data mishandling are elevating procurement scrutiny, favoring vendors with embedded encryption and sovereignty controls.
- Cloud migration:Sydney and Melbourne enterprise clusters are accelerating exit from capital-intensive on-premises data centers toward subscription-hosted models.
Market Restraints
- Skills concentration:Certified platform architects and compliance specialists cluster disproportionately in Sydney and Melbourne, inflating implementation costs for regional deployments.
- Data sovereignty requirements:APRA prudential standards and OAIC guidance mandate domestic hosting, limiting vendor flexibility to leverage offshore infrastructure arbitrage.
- Legacy system entanglement:Federal and state agencies maintain decades-old record formats that resist API-based interoperability without costly middleware layers.
Strategic Opportunities
- Regional healthcare networks:Queensland and Western Australia public hospital systems remain underpenetrated for integrated clinical content management relative to southeastern saturation.
- AI-augmented metadata extraction:Convergence of natural language processing with robotic process automation is opening automated classification contracts in financial services compliance.
- Subscription unbundling:Vendors are piloting consumption-based pricing for infrequent-access archival tiers, capturing price-sensitive local government segments.
Industry Challenges
- Integration complexity:Enterprise buyers demand seamless connectivity with SAP, Salesforce, and ServiceNow instances, stretching professional services capacity and delaying revenue recognition.
- Certification latency:IRAP assessment timelines for federal cloud security accreditation average 8-14 months, freezing vendor eligibility for high-value agency contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Content Services Platform Market |
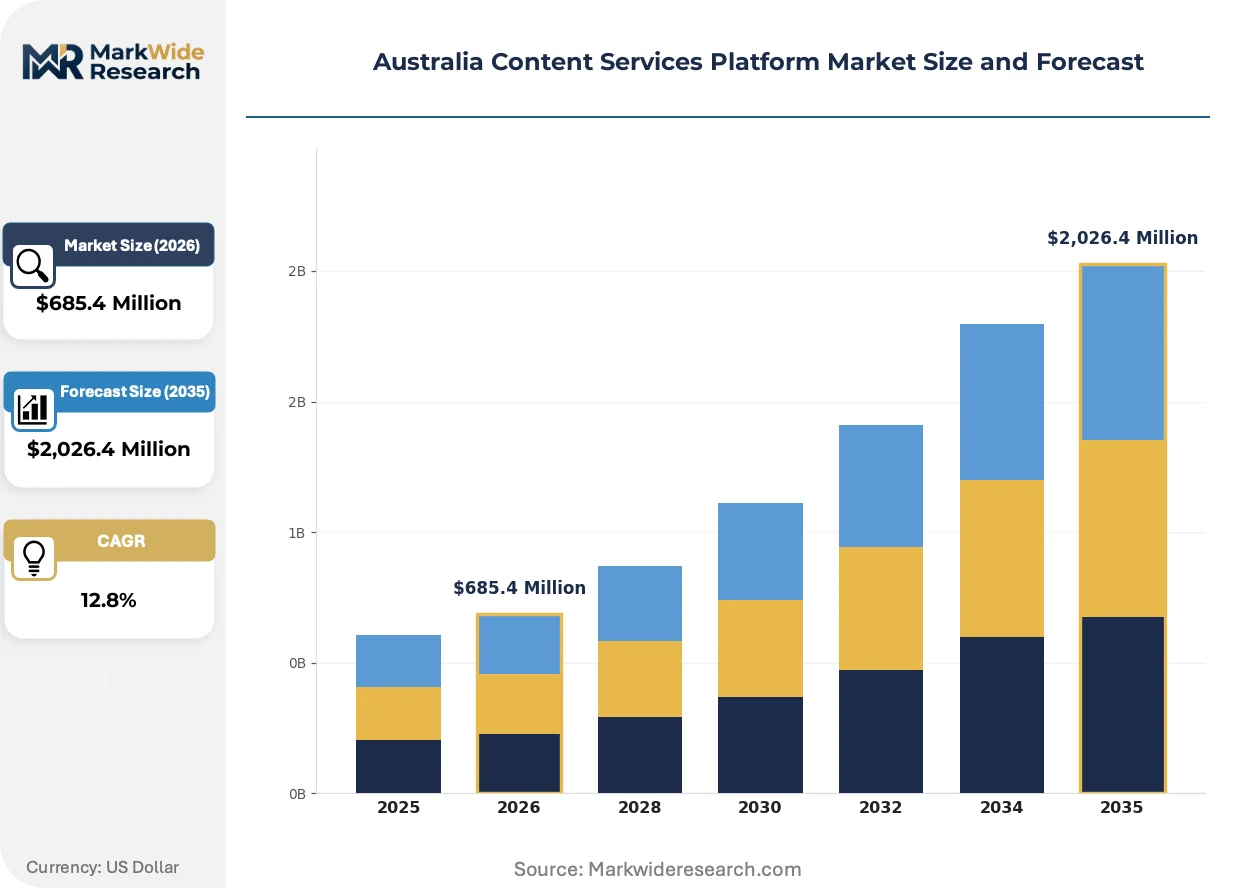
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $2,026.4 Million |
| CAGR (2026 – 2036) | 12.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Services End User: Enterprises, SMBs, Government, Non-Profit Organizations Application: Document Management, Workflow Automation, Digital Asset Management, Records Management Industry Vertical: Healthcare, Education, Financial Services, Manufacturing |
| Companies Covered | UNITH, Trideca, Elcom Technology, Telstra Corporation Ltd, Alley Group, Resolution Digital, Great Minds Consulting, Accenture Australia Pty Ltd, Zeroseven, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Content Services Platform Market Trends and Innovations
Platform architectures are converging around API-first designs that embed compliance automation directly into content ingestion pipelines, reducing post-hoc governance overhead for regulated buyers.
Headless content management architectures are absorbing the separation of presentation layers from repository cores, enabling developers to deploy omnichannel experiences without platform lock-in. Financial services institutions in Sydney are adopting these decoupled systems fastest, compressing traditional vendor switching costs and fragmenting incumbent maintenance revenue pools.
The OAIC is intensifying enforcement of the Notifiable Data Breaches scheme, compelling vendors to engineer real-time breach detection and automated reporting workflows into platform foundations. Healthcare providers face the steepest compliance burden, as My Health Record integration requirements intersect with Privacy Act obligations to create dual-audit trail specifications.
Buyers are consolidating vendor relationships around integrated suites rather than point solutions, displacing standalone document management contracts. State government procurement panels in Victoria and New South Wales now favor multi-year enterprise agreements with single-platform mandates, squeezing niche specialists from approved supplier lists.
Australia Content Services Platform Market Segmentation
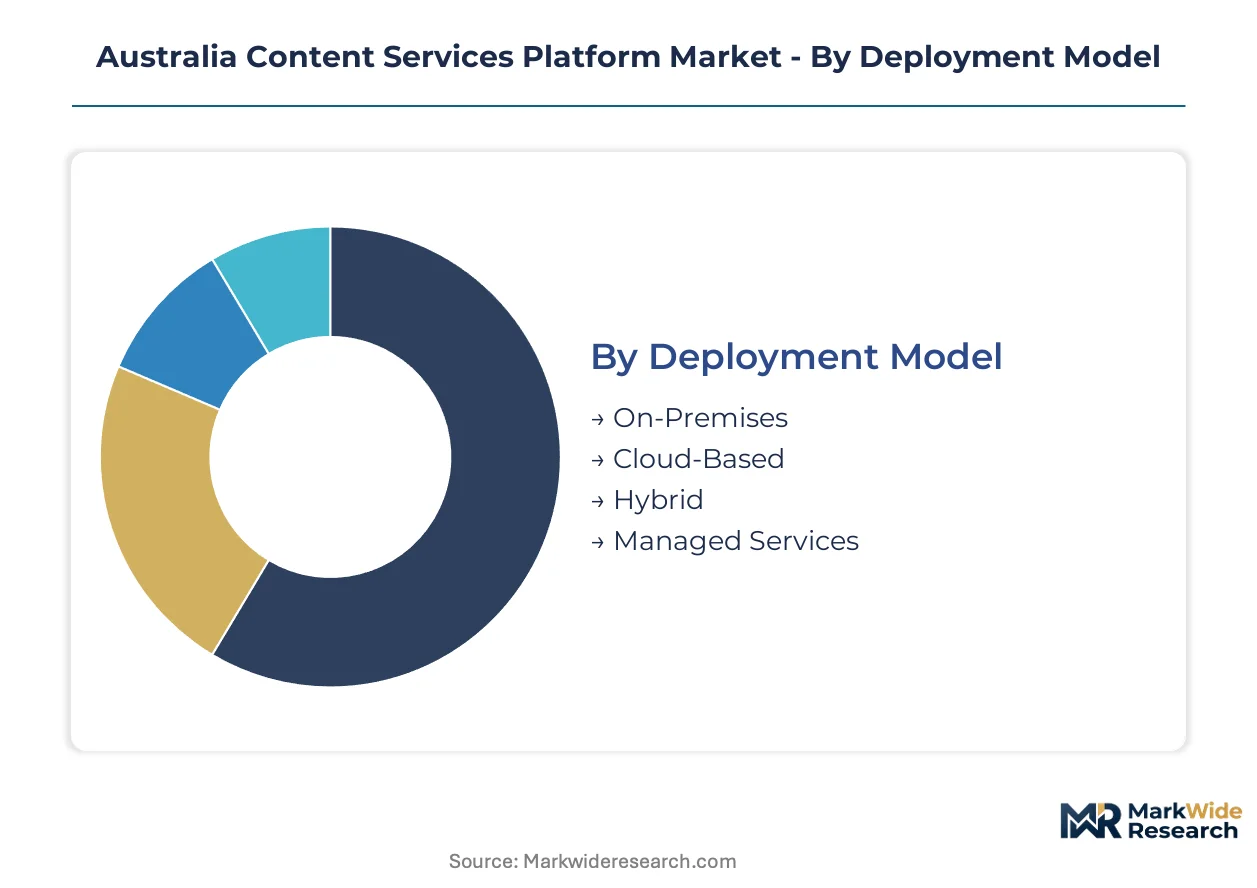
Segmentation of the Australia Content Services Platform Market reveals how procurement priorities diverge across infrastructure commitments, organizational scale, and compliance intensity. Buyers select deployment architectures and application modules based on legacy system burdens, regulatory exposure, and internal technical capacity.
Deployment Model:
Cost tier separates buyers in this category, with capital availability and risk tolerance determining infrastructure strategy.
- Cloud-Based:Multi-tenant architectures with subscription pricing dominate Sydney and Melbourne enterprise procurement. Organizations exit owned data centers to convert fixed infrastructure costs into operational expenditure while meeting OAIC data sovereignty guidance through domestic availability zones.
- Hybrid:Split deployments retain sensitive records on-premises while pushing collaborative content to cloud tiers. Federal agencies favor this architecture to satisfy IRAP certification requirements for classified workflows without sacrificing departmental agility.
- On-Premises:Perpetual license models persist in defense and critical infrastructure operators with air-gapped security mandates.
- Managed Services:Third-party operation of dedicated instances appeals to regional healthcare networks lacking internal platform administration expertise.
Volume sits with Cloud-Based deployments; growth tilts toward Hybrid configurations as federal security accreditation timelines compress.
End User:
Application complexity and procurement authority distinguish organizational buyers in this dimension.
- Government:Federal and state departments mandate IRAP-certified platforms with embedded Privacy Act compliance automation. The Digital Transformation Agency's interoperability standards favor vendors offering API-first architectures that integrate with legacy departmental systems.
- Enterprises:ASX-listed corporations in Sydney's financial district demand workflow automation modules with SAP and Salesforce connectors. Procurement panels emphasize professional services capacity for change management during platform migration.
- SMBs:Price-sensitive adopters select standardized SaaS tiers with minimal customization requirements.
- Non-Profit Organizations:Grant-funded operators prioritize donor management integration and volunteer portal functionality over advanced governance features.
Revenue concentrates with Government contracts; expansion accelerates fastest among Enterprises consolidating fragmented point solutions.
Application:
Functional maturity and integration depth segment buyers by operational pain point severity.
- Workflow Automation:Business process orchestration engines with robotic task allocation command premium pricing in financial services compliance. Sydney institutional banks deploy these modules to automate loan documentation pipelines and regulatory reporting workflows.
- Document Management:Centralized repositories with version control and metadata indexing anchor healthcare digitization under My Health Record system requirements. Victorian public hospitals represent concentrated demand for patient record lifecycle management.
- Records Management:Retention schedule enforcement with legal hold capabilities serves ASIC and APRA audit preparation in listed corporations.
- Digital Asset Management:Media library organization with rights management supports marketing operations in consumer brands and education publishers.
Adoption depth peaks with Document Management; margin expansion favors Workflow Automation through recurring professional services engagement.
Industry Vertical:
Regulatory exposure and record retention mandates create divergent platform specification requirements.
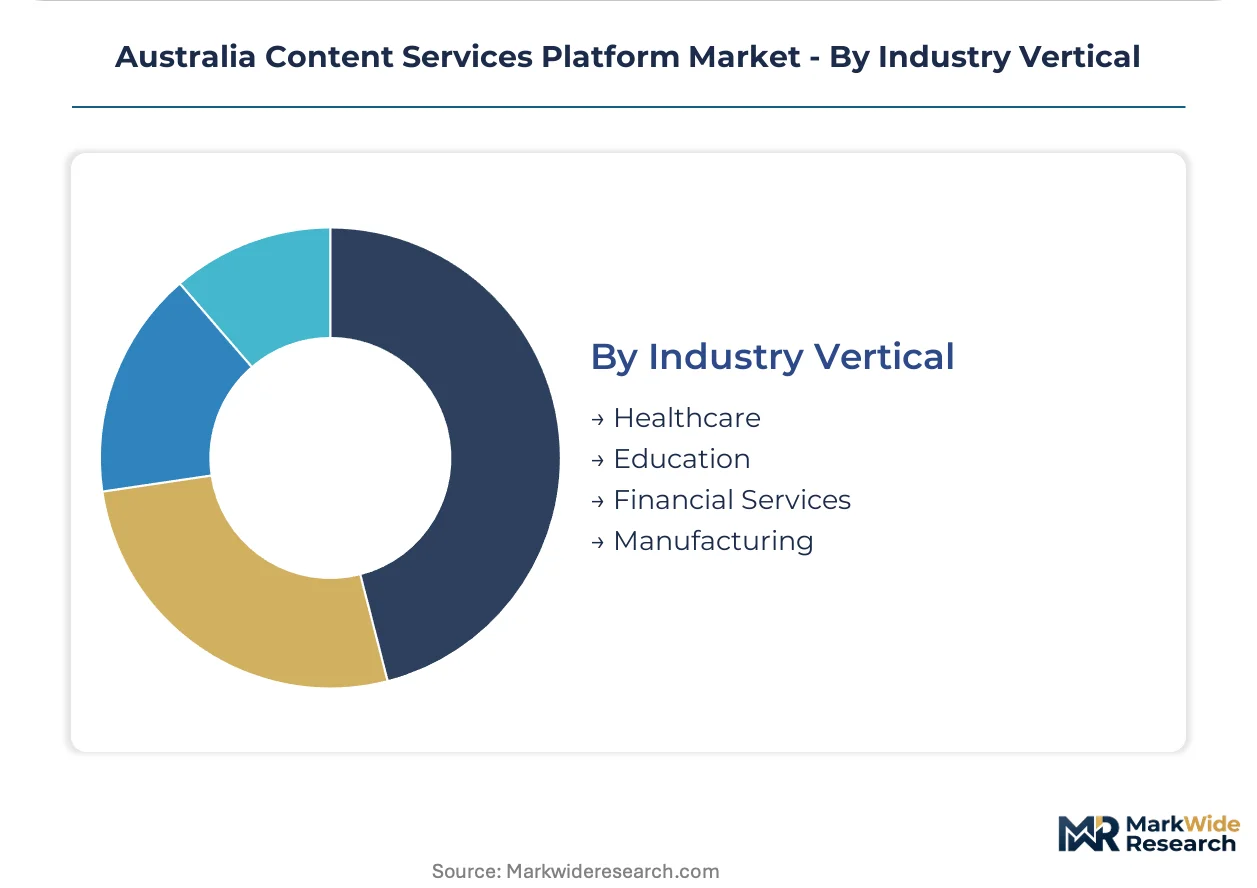
- Healthcare:TGA-aligned systems with patient data encryption and audit trail automation dominate procurement under My Health Record integration mandates. Queensland and Western Australia public hospital networks represent underpenetrated expansion territory relative to southeastern saturation.
- Financial Services:APRA prudential standard compliance drives demand for immutable record retention and granular access logging. Sydney-based institutional banks generate highest customization revenue through specialized risk workflow configurations.
- Education:Student information system integration and research data management shape university and TAFE procurement priorities.
- Manufacturing:Supply chain document traceability and quality management system connectivity define platform selection in export-oriented producers.
Contract value concentrates in Healthcare; platform customization revenue peaks in Financial Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sydney and Melbourne anchor Australian demand for content services platforms, hosting the headquarters of ASX-listed enterprises and federal government departments that drive procurement volume.
New South Wales
Sydney's financial services corridor generates concentrated demand for APRA-compliant workflow automation platforms. The state's Digital Restart Fund accelerates agency digitization timelines. Macquarie Park technology precinct houses implementation specialists serving federal departments.
Victoria
Melbourne's healthcare network drives My Health Record integration contracts across public hospital systems. The Victorian Government's Digital Strategy mandates interoperability standards for departmental content platforms. Docklands enterprise zone attracts cloud service delivery centers.
Queensland
Brisbane's regional healthcare administration creates underpenetrated demand for clinical content management. The state's Hospital and Health Services reform program expands digitization procurement panels. Fortitude Valley emerging technology hub hosts platform implementation partners.
Western Australia
Perth's mining and resources sector generates specialized document management requirements for supply chain traceability. The WA Government's Digital Strategy prioritizes citizen service digitization. Perth CBD enterprise clusters lag southeastern adoption curves by 18-24 months.
South Australia
Adelaide's defense industry presence sustains air-gapped security requirements for classified content repositories. The state's Lot Fourteen innovation precinct incubates sovereign cloud capability. Government procurement panels favor IRAP-certified vendors for agency contracts.
Australia Content Services Platform Market Competitive Landscape
Premium-margin players sit above commodity-margin players across compliance certification depth and professional services attach rates. The vendor base stratifies between telecommunications-backed cloud hosts, consulting-led integrators, and specialized platform developers. Three archetypes dominate: infrastructure-leveraged incumbents, advisory-driven systems integrators, and vertical-focused software specialists. Competitive moves concentrate on IRAP certification acceleration and multi-year enterprise agreement consolidation.
Within the infrastructure-leveraged tier, Telstra Corporation Ltd and Accenture Australia Pty Ltd exemplify divergent approaches to public sector capture. Telstra's national telecommunications footprint anchors cloud-hosted delivery models for federal agencies. Accenture's advisory structure occupies a position bridging legacy system migration with modern platform architectures. Elcom Technology represents the vertical specialist archetype, with its naming convention indicating technology-centric positioning in intranet and knowledge management deployments.
| Leading Market Players |
|---|
| UNITH |
| Trideca |
| Elcom Technology |
| Telstra Corporation Ltd |
| Alley Group |
| Resolution Digital |
| Great Minds Consulting |
| Accenture Australia Pty Ltd |
| Zeroseven |
| Others |
Pricing and Supply Chain Analysis
Federal and state government procurement panels concentrate contract volume for content services platforms, anchoring pricing power in vendors holding IRAP certification and domestic data sovereignty compliance. Subscription-based SaaS tiers dominate commercial terms, with multi-year enterprise agreements compressing spot purchasing and locking in professional services attach rates.
Pricing Analysis
Outcome-based pricing tied to workflow automation throughput anchors premium tiers in financial services contracts. Three-tier pricing structure across premium, standard, and economy levels separates IRAP-certified federal deployments from mid-market SaaS and stripped-down SMB tiers. Cost compression in standard-tier subscriptions is intensifying because hyperscaler infrastructure commoditizes base storage and compute. Regional healthcare networks exhibit highest price sensitivity due to grant-funded capital constraints, while federal agencies prioritize compliance over unit cost.
Supply Chain Analysis
Freight costs for hardware appliances and edge infrastructure concentrate supply chain leverage in Sydney and Melbourne distribution hubs. Platform development draws from software engineering talent pools in Australia, India, and the United States. Cloud infrastructure dependencies hinge on hyperscaler domestic availability zones and sovereign cloud partnerships. Single-source vulnerability sits with IRAP assessment body capacity, which bottlenecks vendor certification timelines. Distribution runs through direct enterprise sales teams and systems integrator channels serving public sector procurement panels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into compliance automation tooling and professional services capacity is reshaping competitive positioning across the Australia Content Services Platform Market. Players are racing to capture upstream certification expertise and downstream implementation labor to defend margin pools.
For Market Incumbents: Acquire specialized IRAP consulting practices to compress accreditation timelines for federal contracts. Consolidate around multi-year enterprise agreements with embedded professional services to lock out niche competitors. The Digital Transformation Agency's interoperability mandates threaten point-solution vendors lacking API-first architectures. For New Entrants and Emerging Players: AI-augmented metadata extraction offers a technology-first wedge into financial services compliance automation. Queensland and Western Australia public hospital systems represent the most penetrable geography given southeastern saturation. Lead with consumption-based pricing for archival tiers to capture price-sensitive local government segments. For Investors and Strategic Acquirers: The window for entry favors vertical specialists with embedded healthcare or financial services compliance expertise. Long-term viability rests on platforms demonstrating sustained federal certification renewal and expanding professional services margins. Watch OAIC enforcement intensity on the Notifiable Data Breaches scheme as the inflection signal for compliance-spending acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| IRAP Certification Acceleration | Compresses 8-14 month assessment timelines to capture federal agency procurement cycles. |
| AI-Native Metadata Platform Launch | Automates TGA-aligned patient record classification for My Health Record integration mandates. |
| Strategic Partnership with Hyperscaler | Secures domestic availability zone capacity for APRA-compliant financial services hosting. |
| Acquisition of Regional Implementation Firm | Extends professional services reach into Queensland and Western Australia hospital networks. |
| Consumption-Based Pricing Pilot | Captures local government archival demand through unbundled storage tiers. |
Research Methodology
Multi-period observation of federal procurement panel awards, IRAP certification timelines, and cloud migration contract values anchored the trend analysis, supplemented by interviews with platform engineering directors, government IT procurement officers, healthcare CIOs, and systems integrator partners. Secondary validation drew from Digital Transformation Agency mandate documents, OAIC enforcement disclosures, APRA prudential standard updates, and hyperscaler domestic infrastructure investment announcements. Bottom-up contract aggregation and top-down market sizing were triangulated to constrain variance.
The input-output matrix framed deployment model penetration, vertical adoption intensity, and geographic concentration as segmentation dimensions across the projection horizon. CAGRs were derived from fitted growth curves against historical contract velocity. Workflow automation module attach rates and professional services revenue mix served as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including potential Privacy Act statutory tort reforms and unannounced hyperscaler data center investments. Forecasts reflect documented assumptions about regulatory enforcement continuity and federal digitization funding levels. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Middle East and Africa Halal Food & Beverage Market
Others
PCB Laminate Market
Others
Asia-Pacific Telecom Transformers Market
Others
High Voltage Measuring Equipment Market
Others
Security Bottles Market
Others
Mobile Computer Cart Market
Others
Latin America Travel Retail Market
Others
Storm Surge Barriers Market
Others
Global Hardware As a Service (Haas) Market
Others
Global Computer Graphics Market
Others
Plastic Films and Sheets Market
Others
Electric Chainsaw Market
Others
Europe Travel Retail Market
Others
Global Automotive LED Lighting Market
Others
Safety Instrumented System (SIS) Market
Others
India Foundry Market