
 United States Cigarette Market | 2026-2036
United States Cigarette Market Size, Share, and Industry Trends Forecast 2026-2036
United States Cigarette Market Intelligence
Asset-light leasing arrangements for retail shelf space and display fixtures are rewriting competitive economics for smaller tobacco manufacturers. Altria Group leverages its scale to secure prime placement in convenience stores nationwide. Vector Group anchors its position through focused discount brand portfolios in price-sensitive Southern markets. British American Tobacco competes via R&D intensity in reduced-risk product pipelines alongside conventional cigarette lines.
A cigarette consists of cured and cut tobacco leaf wrapped in paper, typically containing additives for flavor, burn rate, and moisture retention, with a standard rod length of 70 to 100 millimeters and tar yields measured under ISO smoking protocols. Its primary commercial purpose is to deliver nicotine through combustion for adult consumer use. Menthol variants maintain structural dominance in volume terms, though regulatory pressure from FDA and state-level prohibitions is shifting margin pools toward non-menthol full-flavor segments. Soft pack formats face secular decline as hard pack and box configurations capture preference for product protection and premium positioning across gas station and supermarket channels.
FDA Center for Tobacco Products enforces premarket authorization requirements and flavor standards that determine which products remain legally saleable. State attorneys general and municipal health departments in California and Massachusetts have implemented menthol prohibitions that reshape regional product availability. The Federal Trade Commission monitors advertising and promotional practices under consent decrees dating from historic litigation settlements. Stakeholders must monitor state legislative calendars and FDA deeming rulemakings to anticipate portfolio rebalancing requirements and channel redistribution needs.
Market Dynamics
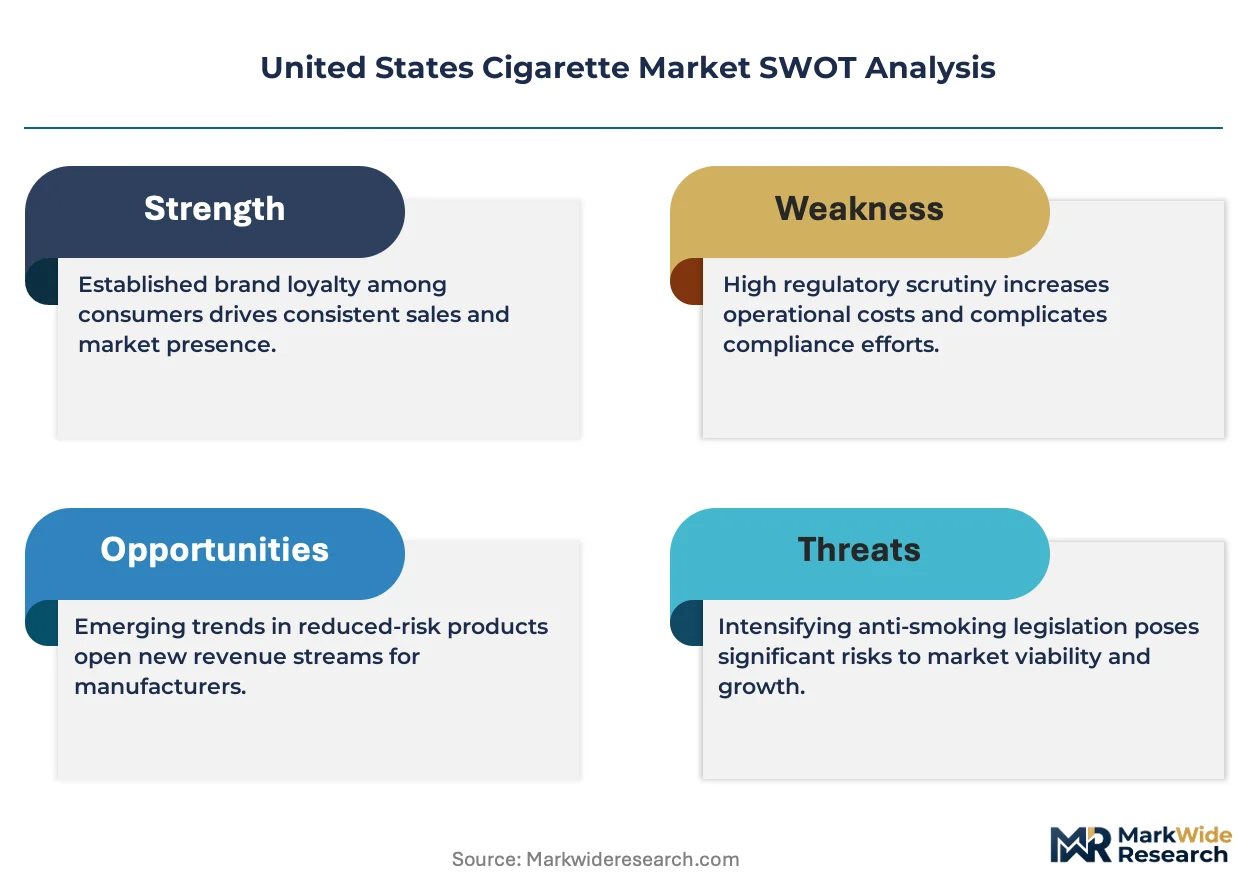
Flavor restrictions and menthol prohibitions are compressing product portfolios and concentrating margin pools in non-menthol full-flavor segments across the United States.
Growth Catalysts
- Adult smoker concentration in convenience channels:Gas stations and c-stores sustain volume throughput despite falling national prevalence rates.
- Reduced-risk product pipelines:Heated tobacco and oral nicotine formats attract switching demand from combustible categories.
- Southeast retail density:Tobacco outlet concentration in Georgia, North Carolina, and Texas supports stable shipment volumes.
Market Restraints
- FDA premarket authorization requirements:The Center for Tobacco Products approval timelines delay new product introductions and freeze portfolio innovation.
- State-level menthol prohibitions:California and Massachusetts bans eliminate high-margin variants from legal retail channels.
- Leaf tobacco input cost volatility:Flue-cured and burley price swings compress manufacturing margins.
Strategic Opportunities
- Modern oral nicotine expansion:Pouch formats bypass combustible restrictions and open shelf space in pharmacy and mass retail channels.
- Heat-not-burn technology convergence:Device and consumable pairing models replicate cigarette economics with reduced regulatory exposure.
- Direct-to-consumer nicotine alternatives:E-commerce and subscription models circumvent traditional wholesale markups.
Industry Challenges
- Flavor chemist talent scarcity:Regulatory pressure on additives reduces the pool of qualified formulation specialists.
- Retail fixture capex intensity:Age-verification technology and display compliance requirements demand ongoing capital deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Cigarette Market |
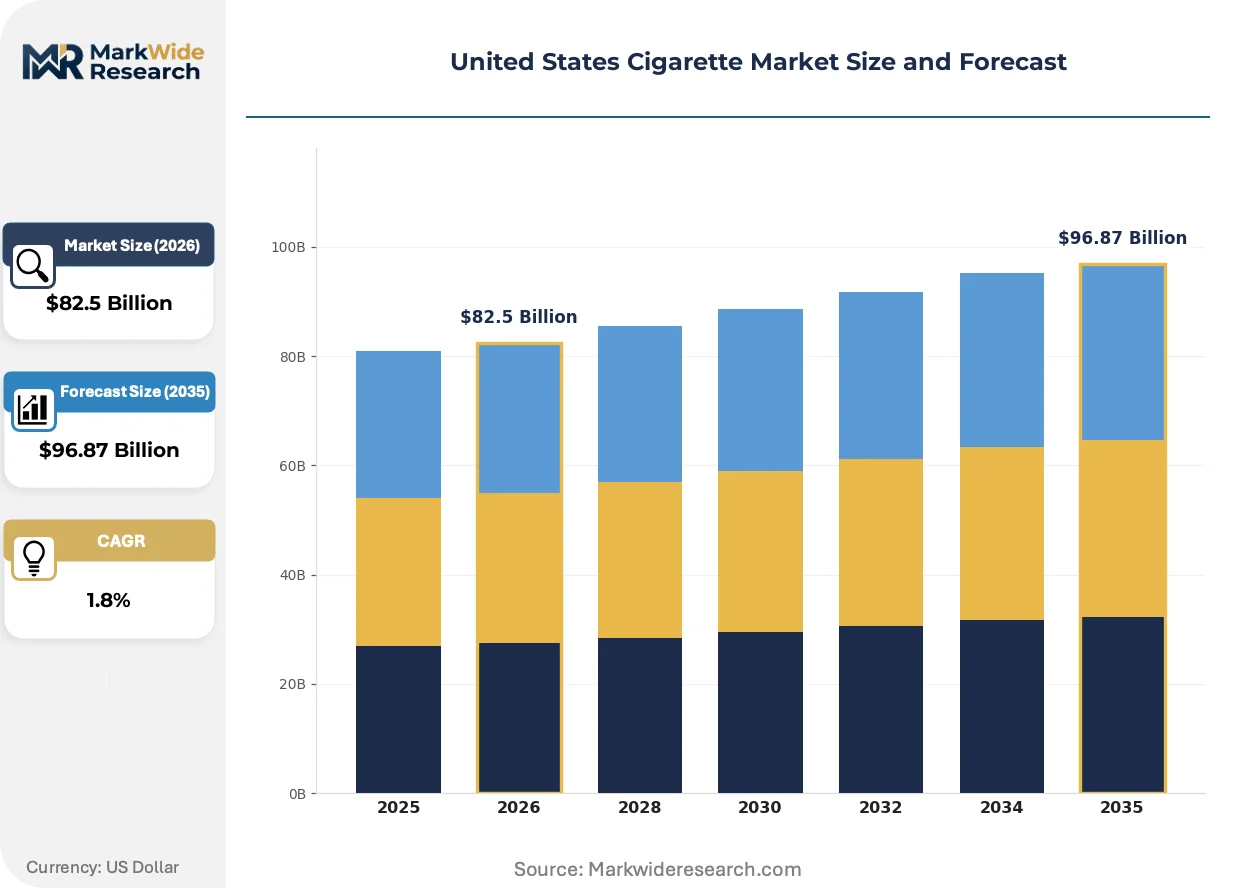
| Market Size in 2026 | $82.5 Billion |
| Market Size in 2035 | $96.87 Billion |
| CAGR (2026 – 2036) | 1.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full Flavor, Light, Menthol, Non-Menthol Packaging Type: Soft Pack, Hard Pack, Box, Carton Distribution Channel: Convenience Stores, Supermarkets, Online Retail, Gas Stations Customer Type: Regular Consumers, Social Smokers, Occasional Smokers, New Smokers |
| Companies Covered | ITG Brands, Turning Point Brands, Altria Group, Universal Corporation, Vector Group, British American Tobacco, Japan Tobacco International, Swedish Match, Philip Morris International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Cigarette Market Strategic Shifts & Innovations
Combustible and non-combustible nicotine delivery systems are converging as manufacturers diversify beyond traditional cigarette formats under regulatory compression.
Heat-not-burn technology is hybridizing conventional tobacco leaf processing with electronic temperature control. Adult smokers in metropolitan markets are adopting these devices at measurable rates. The technology is compressing combustible volume share while opening margin pools previously captured by premium cigarette tiers.
FDA deeming rules and state attorney general enforcement actions are reshaping product availability. Manufacturers must secure premarket authorization for any modified risk claim or new flavor variant. Non-menthol full-flavor segments in the Southeast and Texas absorb displaced demand from prohibited markets.
Channel consolidation among convenience store operators is altering wholesale purchasing patterns. Independent retailers are losing shelf negotiation leverage to national chains with centralized procurement. This concentration is most visible in Florida and Ohio, where regional c-store rollups have accelerated.
United States Cigarette Market Segmentation
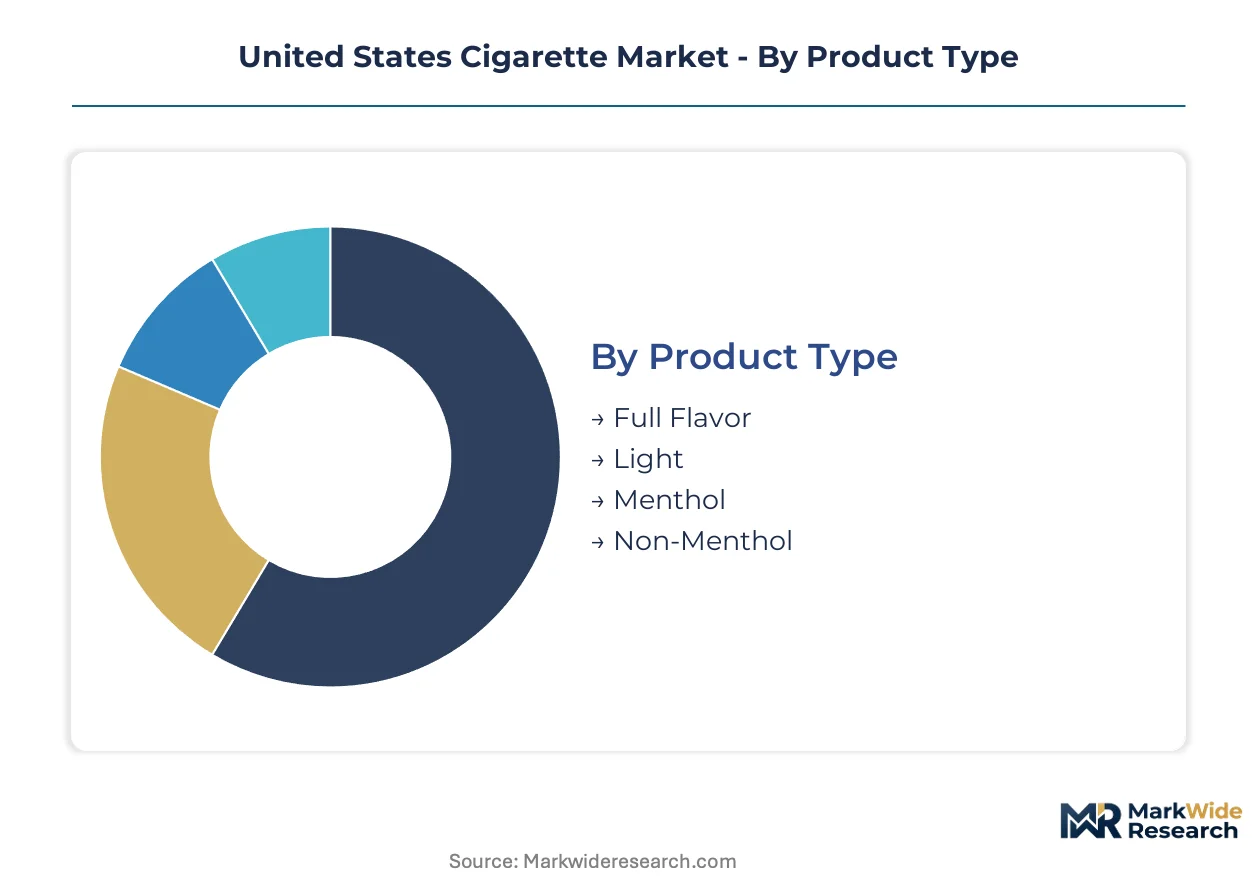
Segmentation in the United States cigarette market determines shelf allocation, margin capture, and regulatory exposure across distinct consumer behaviors and channel economics. Understanding how product formats, packaging preferences, and purchase occasions fragment the market enables manufacturers to optimize portfolio weighting against FDA restrictions and state-level prohibitions.
Product Type:
Full-flavor variants turn inventory fastest in the Southeast and Texas, while menthol SKUs face extended holding periods in banned jurisdictions where gray-market sourcing delays replenishment cycles.
- Full Flavor:Higher tar and nicotine content delivered through burley and flue-cured tobacco blends without flavor masking. Demand concentrates in Georgia, North Carolina, and Texas convenience channels where adult smokers displaced from menthol-ban states absorb volume. FDA flavor restrictions compress alternatives, reinforcing this segment's margin pool expansion.
- Menthol:Characterizing flavor derived from mint oils or synthetic analogs that masks tobacco harshness and delivers cooling sensation. California and Massachusetts prohibitions eliminate legal retail availability, shifting volume to Southeast markets and informal distribution networks. Inventory velocity collapses in banned states while black-market premiums distort pricing.
- Light:Reduced tar and nicotine yields achieved through filter ventilation and expanded tobacco sheet inclusion. Smokers in metropolitan markets seeking perceived risk reduction drive residual demand despite FDA prohibition of "light" descriptor claims.
- Non-Menthol:Unflavored tobacco profile encompassing both full-flavor and reduced-yield variants outside menthol classification. Texas and Florida gas station channels sustain volume as the default option where menthol is restricted.
Full Flavor anchors the volume base while Non-Menthol gains share at the steepest rate as smokers migrate from prohibited menthol variants.
Packaging Type:
Cost tier stratification separates premium box formats from economy soft packs, with hard packs occupying the intermediate position where durability meets price accessibility.
- Hard Pack:Rigid paperboard construction with flip-top lid that protects cigarettes from crushing and moisture. Gas stations and c-stores in Florida and Ohio favor this format for premium positioning and theft deterrence. Altria and Vector Group allocate prime shelf fixtures to hard pack SKUs given higher per-unit margins.
- Box:Thicker paperboard with hinged lid and foil inner seal providing maximum product protection. Supermarket channels in metropolitan markets stock box formats for brand-conscious consumers seeking tactile quality signals. Age-verification technology integration is easiest with standardized box dimensions.
- Soft Pack:Flexible paper wrapper without rigid structure, historically the lowest-cost format. Price-sensitive rural markets in Kentucky and West Virginia sustain residual demand, though volume share erodes as hard pack economics improve.
- Carton:Ten-pack aggregation for bulk purchase, dominant in tribal lands and duty-advantaged channels where per-pack taxes are minimized. Wholesale redistribution patterns concentrate carton volume in Nevada and New Mexico border zones.
Hard Pack generates the highest margin per square foot of shelf space while Box configurations expand most quickly in consolidated retail chains.
Distribution Channel:
Geographic concentration of adult smokers aligns with channel density, as tobacco outlet maps in the Southeast overlay directly with convenience and gas station footprints.
- Convenience Stores:24-hour accessibility and high-frequency purchase occasions sustain volume despite declining national prevalence. Georgia and North Carolina c-store operators command slotting fees that smaller manufacturers struggle to meet.
- Gas Stations:Impulse purchase environment with captive audience during fuel transactions. Texas interstate corridors generate measurable volume concentration through travel-dependent consumption patterns.
- Supermarkets:Planned purchase setting with broader demographic reach but lower tobacco-specific foot traffic. Massachusetts and California menthol bans apply here, eliminating SKU variety.
- Online Retail:Age-verification complexity and PACT Act shipping restrictions limit scale. Direct-to-consumer nicotine alternatives capture switching demand that cigarettes cannot legally pursue.
Convenience Stores anchor the volume base while Gas Stations gain share at the steepest rate through interstate corridor expansion.
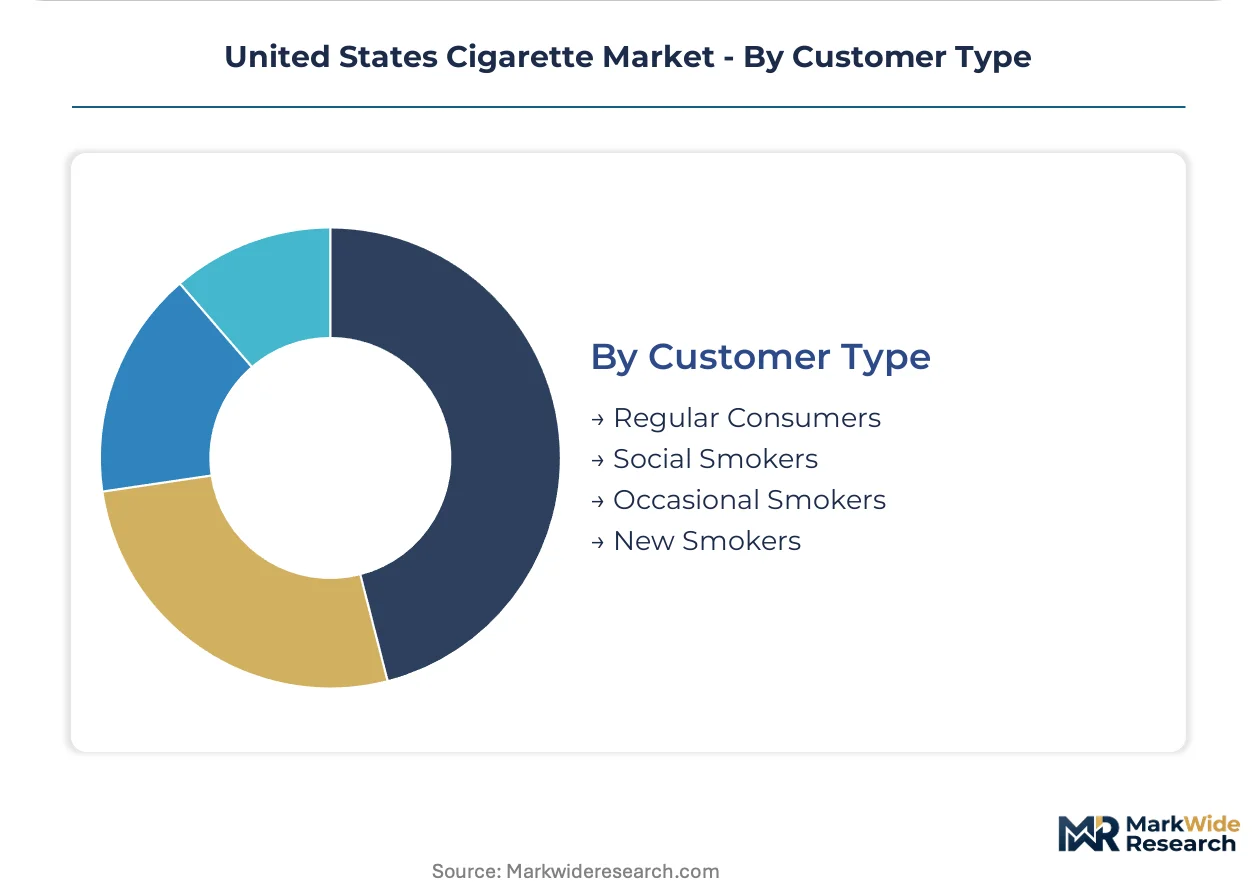
Customer Type:
Maturity gradients separate entrenched consumption patterns from experimental behaviors, with regulatory pressure targeting acquisition of new users while tolerating existing adult smokers.
- Regular Consumers:Daily smokers with established brand loyalty and price-inelastic demand in the short term. Southeast markets concentrate this cohort, sustaining shipment stability despite national decline.
- Occasional Smokers:Intermittent consumption tied to social contexts or stress events, exhibiting higher price sensitivity and brand switching. Metropolitan markets show elevated prevalence of this pattern.
- Social Smokers:Context-dependent consumption in bars, casinos, and entertainment venues where tobacco use remains culturally normalized. Nevada and Louisiana hospitality channels serve this segment.
- New Smokers:Initiation cohort targeted by FDA prevention campaigns and state tobacco-21 laws. Flavor restrictions specifically aim to reduce appeal to this group, compressing manufacturer acquisition strategies.
Regular Consumers anchor the volume base while Occasional Smokers gain share at the steepest rate as daily prevalence contracts toward intermittent patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Adult smokers in convenience-dependent buyer segments concentrate in Southeast and Southwest corridors where tobacco retail density sustains volume throughput despite declining national prevalence rates.
Southeast
Georgia and North Carolina anchor combustible volume through gas station and c-store channel density. State attorneys general in this region have resisted menthol prohibitions seen elsewhere, preserving SKU variety. The Atlanta metropolitan corridor hosts wholesale redistribution hubs serving Florida and Alabama markets.
Texas
Interstate highway corridors generate travel-dependent consumption patterns with elevated carton velocity through border-adjacent counties. Texas maintains permissive tobacco retail licensing relative to coastal states. Dallas-Fort Worth and Houston metropolitan clusters concentrate independent convenience store operators with strong slotting fee negotiation leverage.
California
Menthol prohibitions eliminate legal retail availability of characterizing flavor variants, compressing product portfolios to non-menthol full-flavor segments. FDA deeming rules apply alongside state-level restrictions. Los Angeles and San Francisco Bay Area markets show accelerated migration toward modern oral nicotine alternatives as combustible options narrow.
Midwest
Ohio and Michigan c-store consolidation has shifted wholesale purchasing power toward centralized procurement desks of national chains. State tobacco-21 laws align with federal standards. Chicago metropolitan retail fixtures demand ongoing age-verification technology capex that independent operators struggle to fund.
Northeast
Massachusetts menthol bans mirror California restrictions, eliminating high-margin variants from legal channels. New York and Pennsylvania tobacco tax differentials drive cross-border purchasing into lower-tax jurisdictions. Boston and Philadelphia urban markets exhibit the steepest declines in daily smoking prevalence among adult consumers.
United States Cigarette Market Key Industry Players
Channel-controlling players compete with product-specialist players across tiered shelf-space allocation systems. Market structure consolidates around three to four dominant manufacturers with national convenience store penetration, while mid-tier operators concentrate in price-sensitive regional pockets. Strategic archetypes separate scale-driven portfolio diversifiers from discount-focused brand aggregators and reduced-risk product specialists. Competitive moves center on slotting fee escalation for prime fixture placement and accelerated R&D pipelines for heat-not-burn convergence.
Among scale-driven manufacturers with diversified nicotine portfolios, Altria Group and British American Tobacco occupy positions exemplifying the channel-control archetype through nationwide retail penetration. Vector Group sits within the discount-tier specialization segment, anchoring price-competitive positioning in Southern markets. ITG Brands represents the mid-tier brand aggregation model with focused combustible lineups. These three players illustrate how competitive positioning stratifies across premium fixture access, price-point targeting, and regulatory adaptation capacity.
| Leading Market Players |
|---|
| ITG Brands |
| Turning Point Brands |
| Altria Group |
| Universal Corporation |
| Vector Group |
| British American Tobacco |
| Japan Tobacco International |
| Swedish Match |
| Philip Morris International |
| Others |
Cost & Logistics Intelligence
Interstate freight corridors through Georgia and North Carolina transmit flue-cured tobacco leaf cost volatility directly into manufacturer margin structures, while downstream price differentiation stratifies across convenience store slotting tiers and gas station impulse channels.
Pricing Analysis
Cost-plus contracts indexed to USDA leaf tobacco price reports dominate procurement between manufacturers and leaf dealers. Pricing stratifies across premium, standard, and economy tiers anchored by brand heritage, retail fixture placement, and geographic delivery density. Cost compression in discount segments is intensifying because Vector Group and ITG Brands escalate slotting fee competition for Southern c-store shelf space. Price-sensitive smokers in rural Kentucky and West Virginia exhibit highest elasticity, while brand-loyal regular consumers in Texas metropolitan clusters show lowest sensitivity.
Supply Chain Analysis
Contract manufacturing concentration rests with Altria Group's Richmond production complex and Reynolds American's Winston-Salem operations, supplemented by regional blending facilities in North Carolina. Raw material dependencies center on domestic flue-cured and burley tobacco from Virginia and Kentucky, plus filter tow and paper from specialized converters. Supply chain risk hinges on FDA premarket authorization delays that freeze new SKU introductions and strand inventory investments. Distribution runs through wholesale redistribution hubs in Atlanta and Dallas-Fort Worth serving c-store and gas station networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Modern oral nicotine adoption signals early-cycle expansion as adult smokers displaced from menthol-ban states accelerate switching toward pouch formats and heat-not-burn devices.
For Market Incumbents: Insulate combustible margin pools by deepening backward integration into domestic leaf procurement and accelerating FDA premarket authorization submissions for non-menthol full-flavor variants. Secure exclusive fixture placement agreements with consolidating c-store chains in Florida and Ohio before slotting fee escalation erodes returns. Prioritize heat-not-burn R&D convergence to capture switching demand from prohibited menthol markets. For New Entrants and Emerging Players: Establish a beachhead in modern oral nicotine through pharmacy and mass retail channels where combustible restrictions do not apply. Target price-sensitive occasional smokers in metropolitan markets with direct-to-consumer subscription models that bypass traditional wholesale markups. Pursue white-label manufacturing partnerships with existing leaf processors to minimize capital intensity. For Investors and Strategic Acquirers: Carve-out targets emerge from mid-tier brand aggregators with concentrated Southern market exposure and underutilized FDA regulatory affairs capabilities. Long-term viability hinges on portfolio diversification velocity toward reduced-risk products and geographic optionality in menthol-permissive jurisdictions. Monitor FDA deeming rulemaking calendars as the critical inflection signal for portfolio rebalancing requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Premarket Authorization Investment | FDA Center for Tobacco Products submissions determine which SKUs remain legally saleable across state jurisdictions. |
| Heat-Not-Burn Technology Convergence | Device and consumable pairing models replicate cigarette economics while reducing combustible regulatory exposure. |
| Modern Oral Nicotine Expansion | Pouch formats bypass flavor restrictions and open shelf space in CVS and Walgreens pharmacy channels. |
| Convenience Store Fixture Control | Prime placement agreements with 7-Eleven and Circle K chains determine volume throughput in high-frequency purchase environments. |
| Leaf Tobacco Backward Integration | Captive supply of Virginia flue-cured and Kentucky burley reduces input cost volatility and FDA supply chain scrutiny. |
Research Approach
A standing panel of convenience store category managers, tobacco wholesale distributors, FDA regulatory affairs consultants, and state attorney general policy staff provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from FDA deeming rule dockets, USDA leaf tobacco price reports, and state legislative tracking databases. Bottom-up shipment data triangulated against top-down retail audit estimates from Nielsen and Circana.
Scenario-bracketing framed projections across the analysis window, modeling baseline, accelerated decline, and regulatory compression trajectories. Segmentation dimensions included product type, packaging format, distribution channel, and customer maturity gradient. CAGRs derived from trend extrapolation of historical shipment volumes adjusted for FDA authorization timelines and state-level prohibition implementation schedules. Forecast inputs incorporated convenience store consolidation rates and modern oral nicotine adoption curves.
Stress conditions across FDA authorization delays, menthol prohibition expansion, and leaf tobacco price spikes were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and smoker switching elasticity. Quarterly review of FDA deeming rulemakings, state legislative calendars, and convenience store M&A activity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Video Conferencing Hardware Market
Others
Saudi Arabia Cat Food Market
Others
Global Molded Plastics Market
Others
Ultra Mobile Devices (UMD) Market
Others
Europe Street Lighting Market
Others
Latin America Video Conferencing Hardware Market
Others
Dry-Cleaning and Laundry Services Market
Others
Singapore Retail Market
Others
Czech Republic Market
Others
Spain Automotive LED Lighting Market
Others
Linseed Oil Market
Others
Global Learning Analytics Market
Others
Air Separation Plant Market
Others
Spend Analytics Market
Others
Global Process Equipment Market
Others
DNA Data Storage Market