
 Wearable Brain Devices Market | 2026-2036
Wearable Brain Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Wearable Brain Devices Market Intelligence
The gap between clinical-grade EEG headsets and consumer-facing fitness trackers is realigning product development roadmaps across the industry. Neuralink anchors its position through invasive implant R&D intensity, while Emotiv competes in non-invasive BCI hardware with established channel control in research institutions. Muse (InteraXon) differentiates through meditation-focused consumer software integration, sustaining brand strength in the wellness segment.
Wearable brain devices combine dry or wet electrode arrays, signal amplification circuits, and embedded processors to capture electroencephalographic or neurostimulation data for real-time neural monitoring or modulation. EEG headsets lead unit volume due to established manufacturing scale and lower regulatory barriers, while neurostimulation devices capture concentrated margin pools through prescription-grade indications. Cognitive enhancement wearables represent the fastest-growing application segment as employers and educational institutions pilot attention-training programs.
FDA breakthrough device designation and EU MDR Class IIa/IIb pathways shape market access timelines, with ISO 13485 quality management serving as a baseline procurement filter for hospital systems. Japan's PMDA neurotechnology review standards and South Korea's MFDS digital therapeutics frameworks add further compliance layers for cross-border entrants. Stakeholders must monitor reimbursement code creation for remote neuro-monitoring as the decisive inflection point for clinical segment scalability.
Market Dynamics
Remote patient monitoring protocols are collapsing the traditional clinical-site bottleneck for EEG diagnostics, forcing hardware manufacturers to optimize for home-use signal fidelity rather than hospital-grade laboratory conditions.
Growth Catalysts
- FDA breakthrough device designation:Accelerated review pathways compress commercialization timelines for neurotechnology developers seeking prescription-grade indications.
- Employer wellness programs:Fortune 500 companies pilot attention-training initiatives using cognitive enhancement wearables for workforce productivity optimization.
- Germany's DiGA framework:Digital health applications reimbursement creates precedent for wearable brain device prescription coverage across EU member states.
Market Restraints
- Dry electrode material costs:Silver-silver chloride sensor substrates face price volatility from precious metals supply concentration in South African mining operations.
- Signal artifact interference:Motion artifacts and ambient electrical noise degrade data quality in non-laboratory environments, limiting clinical validity.
- EU MDR Class IIb technical documentation:Extended conformity assessment timelines for neurostimulation devices delay market entry by 18-24 months versus predecessor directives.
Strategic Opportunities
- Pediatric epilepsy monitoring:Underpenetrated home-use segment for seizure detection wearables with caregiver alert integration.
- ISO 13485-certified contract manufacturers:Specialized EMS providers in South Korea offer turnkey quality management for neurotechnology startups.
- EEG-fNIRS convergence:Hybrid optical-electrical sensing architectures enable hemodynamic-neural correlation mapping for research institutions.
Industry Challenges
- Biomedical signal processing expertise:Scarcity of engineers with combined neuroscience and embedded systems competencies constrains R&D velocity.
- Legacy hospital IT integration:HL7 FHIR interoperability requirements demand middleware development for EMR connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wearable Brain Devices Market |
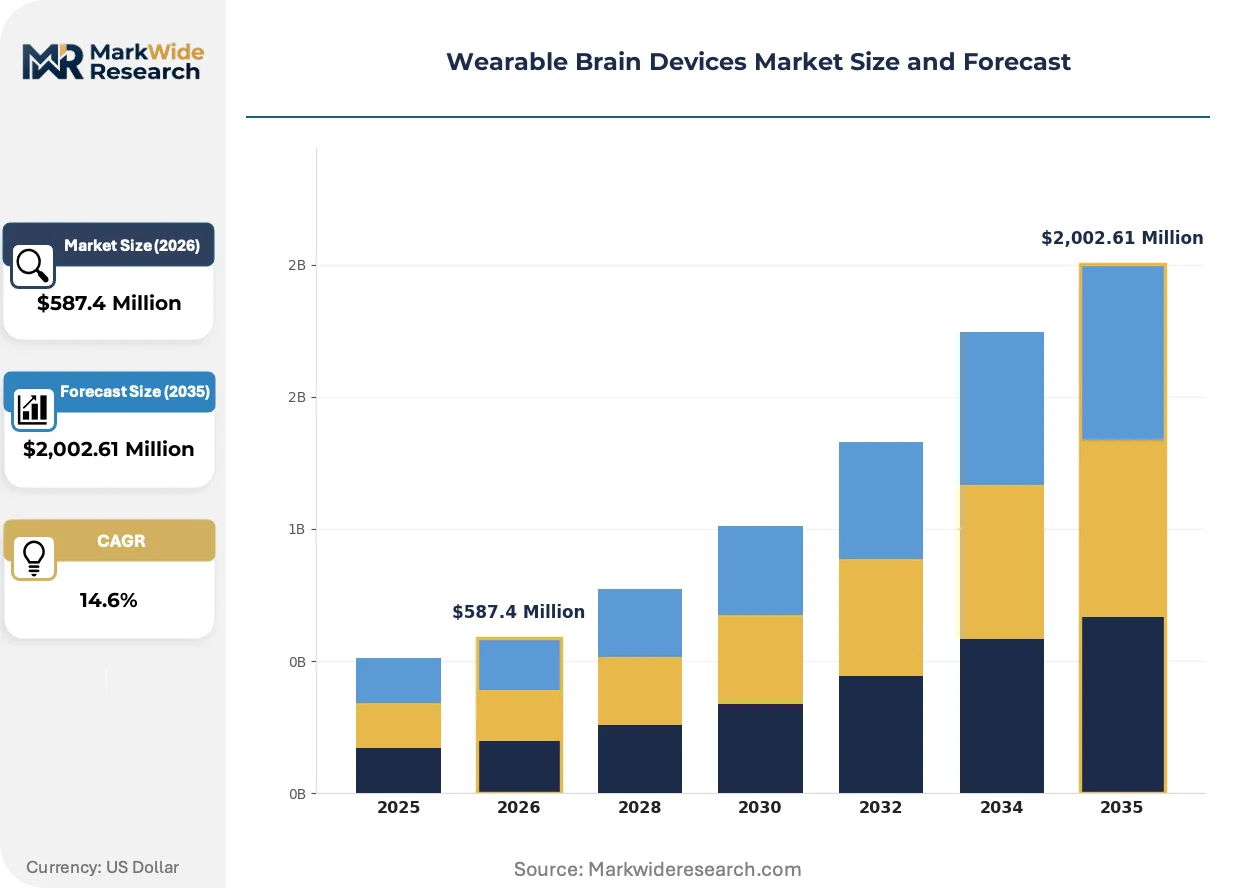
| Market Size in 2026 | $587.4 Million |
| Market Size in 2035 | $2,002.61 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: EEG Headsets, Neurostimulation Devices, Cognitive Enhancement Wearables, Fitness Trackers Technology: Wireless, Bluetooth, EEG, Neurofeedback End User: Healthcare Professionals, Fitness Enthusiasts, Researchers, Consumers Application: Mental Health, Cognitive Training, Sleep Monitoring, Fitness |
| Companies Covered | Neurable, Mendi Innovations, Neuralink, Narbis, Epitel, Emotiv, IDUN Technologies, Neurosity, Muse (InteraXon), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wearable Brain Devices Market Strategic Shifts & Innovations
Machine learning inference at the edge is compressing the latency between neural signal capture and actionable feedback, enabling closed-loop neurostimulation systems that were previously confined to implantable devices.
Dry polymer electrode arrays with micro-needle geometries are rewriting the usability-versus-fidelity tradeoff that has constrained consumer EEG adoption for two decades. Sleep technology companies integrate these sensors into overnight monitoring headbands, eliminating conductive gel application barriers. The structural consequence is market expansion into wellness applications previously served by accelerometer-only sleep trackers.
EU MDR Class IIa/IIb neurotechnology pathways are forcing device developers to front-load clinical evidence generation before CE marking submission. Manufacturers now embed post-market surveillance infrastructure during initial design phases rather than retrofitting compliance. Neurostimulation devices with prescription indications face the steepest documentation burden, while wellness-focused EEG headsets exploit lower-risk classification routes.
Enterprise procurement of cognitive enhancement wearables is displacing individual consumer purchases as the dominant volume channel. Human resources departments negotiate fleet pricing for attention-monitoring programs, unbundling hardware from software subscriptions. This concentration is most visible in United States technology sector employers piloting productivity optimization initiatives.
Wearable Brain Devices Market Segmentation
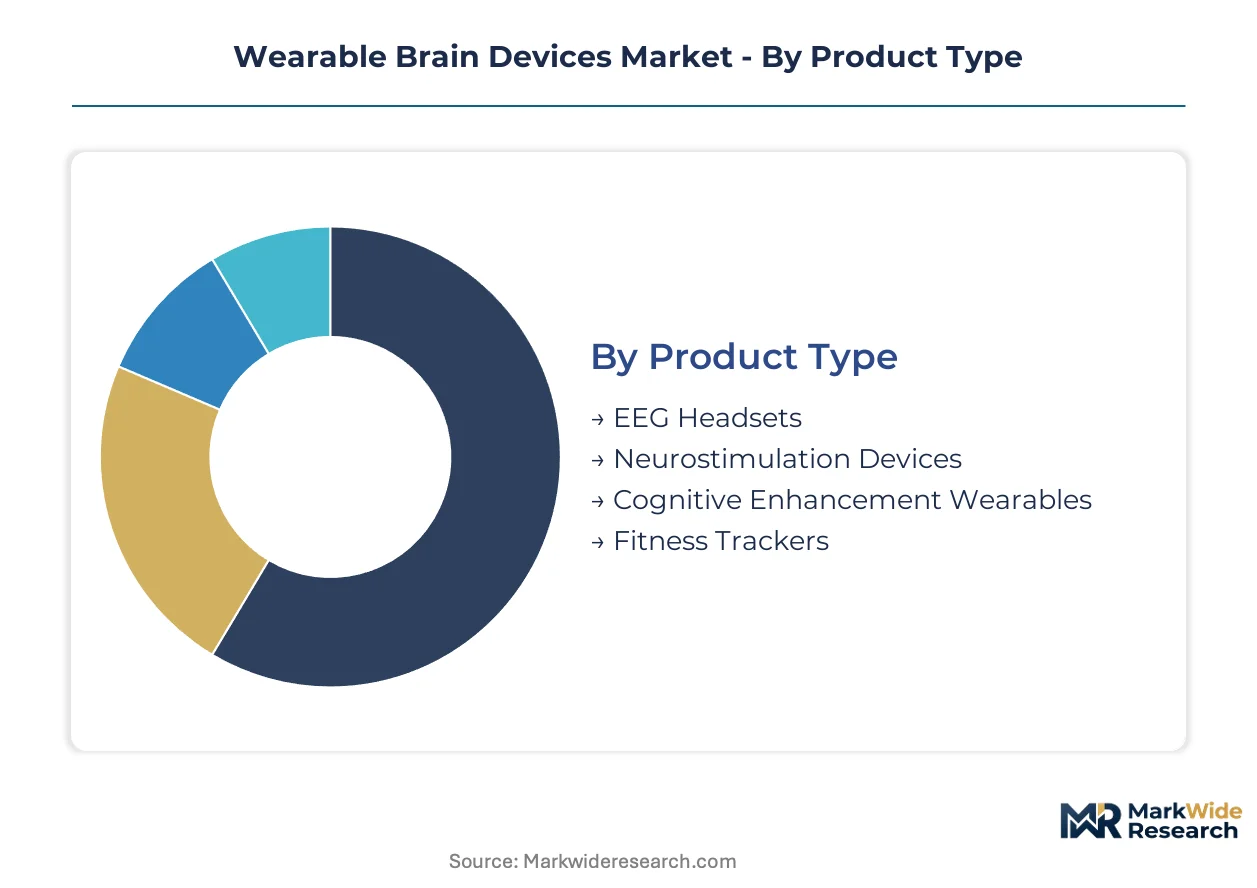
Wearable brain devices fragment across four distinct category axes, each reflecting divergent regulatory pathways and customer procurement behaviors. Product type and application segmentation reveal the deepest strategic fault lines between clinical prescription models and direct-to-consumer wellness positioning.
Product Type:
Customization intensity spans from FDA-regulated neurostimulation implants to mass-market fitness bands with neural-adjacent sensors, creating tiered margin architectures across the hardware spectrum.
- EEG Headsets:Dry and wet electrode arrays capture electroencephalographic signals through scalp-mounted sensors with embedded amplification circuits. Demand concentrates among research institutions in the United States and Germany, driven by remote patient monitoring protocols that collapse clinical-site bottlenecks for diagnostic workflows.
- Neurostimulation Devices:Transcranial direct current stimulation and alternating current systems deliver targeted electrical modulation through wearable form factors. Prescription-grade indications in Japan and South Korea attract concentrated margin pools, though EU MDR Class IIb documentation burdens extend market entry timelines substantially.
- Cognitive Enhancement Wearables:Attention-training hardware with real-time neurofeedback loops targets workforce productivity optimization. Enterprise procurement from Fortune 500 human resources departments displaces individual consumer purchases as the dominant volume channel.
- Fitness Trackers:Accelerometer-integrated headbands with basic sleep staging algorithms compete in the wellness segment. Meditation-focused software integration from Canadian developers sustains brand differentiation against generic sensor hardware.
Most installed capacity flows through EEG Headsets. Expansion is steepest in Cognitive Enhancement Wearables.
Technology:
Signal transmission architectures separate clinical-grade fidelity requirements from consumer convenience priorities, with wireless protocols dominating non-invasive applications.
- Wireless:Proprietary radio frequency protocols enable low-latency data streaming without tethered connections. Hospital systems in the United States prioritize wireless implementations for patient mobility during extended monitoring protocols.
- Bluetooth:Standardized short-range connectivity reduces hardware BOM costs for consumer-facing manufacturers. Fitness Enthusiasts and direct-to-consumer segments drive volume through smartphone app ecosystem integration.
- EEG:Analog front-end designs with active noise cancellation and high-impedance buffering extract microvolt-scale neural signals. Researchers in German university medical centers demand laboratory-grade specifications for publication-quality data acquisition.
- Neurofeedback:Closed-loop algorithms process real-time spectral power to deliver immediate sensory feedback. Mental health applications in clinical settings require IEC 60601-1-2 electromagnetic compatibility certification for therapeutic claims.
Bluetooth-enabled devices command the largest shipment volumes. Neurofeedback systems are climbing the fastest as closed-loop therapeutic indications expand.
End User:
Procurement authority separates institutional buyers with ISO 13485 vendor requirements from individual purchasers prioritizing aesthetic design and subscription pricing.
- Healthcare Professionals:Neurologists and psychiatrists prescribe FDA-designated breakthrough devices for epilepsy monitoring and depression protocols. Reimbursement code creation for remote neuro-monitoring remains the decisive inflection point for segment scalability.
- Fitness Enthusiasts:Wellness-motivated consumers purchase sleep headbands and meditation trainers through direct-to-consumer channels. German DiGA framework precedents create potential prescription coverage pathways for hardware-software bundles.
- Researchers:Academic neuroscience laboratories and pharmaceutical clinical trial operators source calibrated equipment with published validation studies. EEG-fNIRS hybrid architectures from South Korean contract manufacturers address hemodynamic-neural correlation mapping demand.
- Consumers:Price-sensitive purchasers respond to brand marketing and app store ratings rather than technical specifications. Intermittent usage patterns and high device abandonment rates constrain lifetime value metrics for hardware-only vendors.
Healthcare Professionals generate the highest per-unit margins. Researchers are gaining share fastest as pharmaceutical neurotechnology trials multiply.
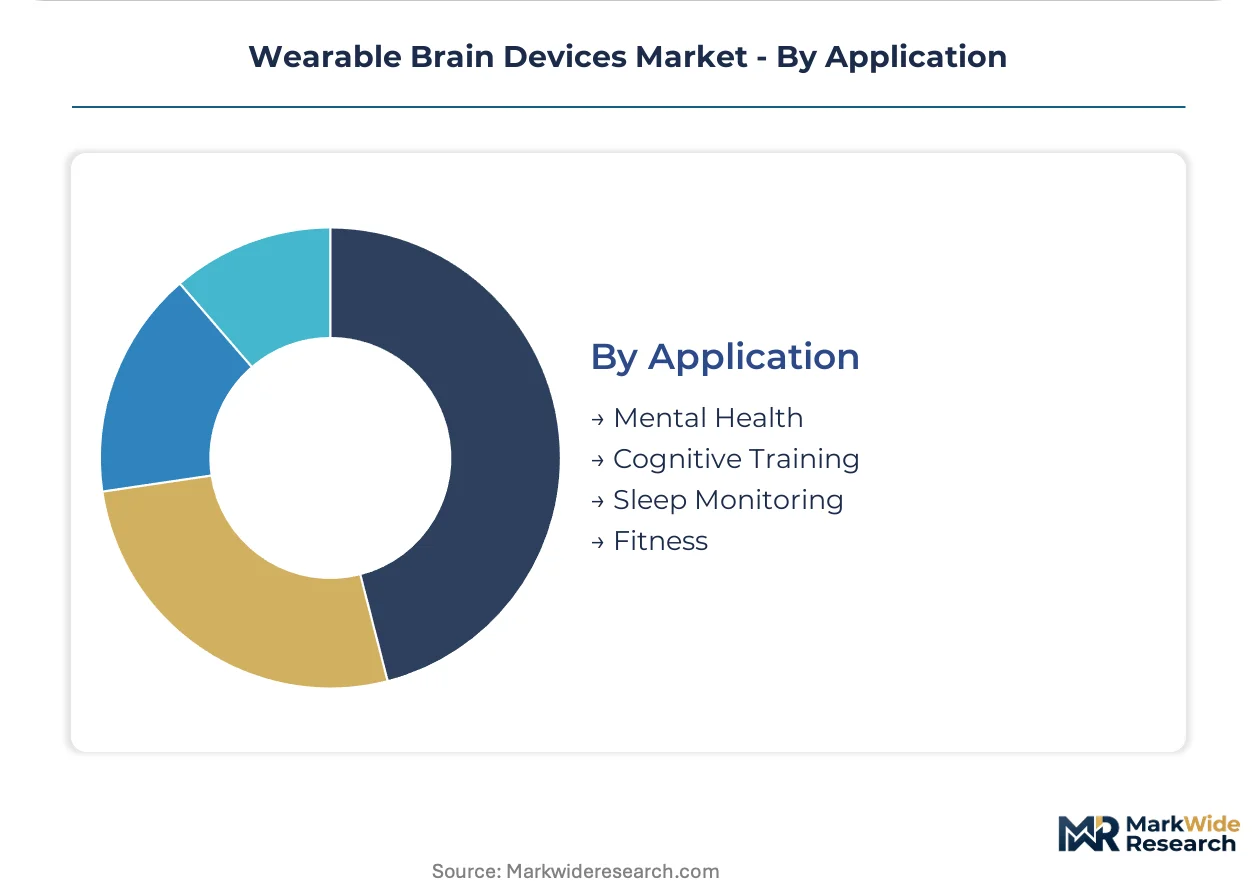
Application:
Clinical indication depth determines regulatory classification and pricing power, with prescription mental health applications commanding premium positioning against wellness-adjacent fitness use cases.
- Mental Health:Depression, anxiety, and PTSD treatment protocols leverage neurostimulation and neurofeedback for therapeutic endpoints. FDA breakthrough device designations accelerate review timelines for developers seeking prescription-grade positioning in the United States.
- Cognitive Training:Attention and working memory enhancement programs target pediatric ADHD populations and aging adult cognitive decline. Employers in the United States technology sector pilot fleet pricing for workforce productivity optimization initiatives.
- Sleep Monitoring:Overnight EEG and accelerometer fusion enables sleep staging and disorder screening without polysomnography laboratory visits. Dry polymer electrode arrays with micro-needle geometries eliminate conductive gel barriers for home-use adoption.
- Fitness:General wellness positioning with stress detection and recovery metrics competes against accelerometer-only wearable incumbents. Lower-risk classification routes under EU MDR enable faster commercialization for non-therapeutic claims.
Mental Health applications capture the steepest pricing premiums. Sleep Monitoring is expanding most quickly as overnight home-use protocols displace laboratory polysomnography.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neurotechnology talent clusters in Boston, Seoul, and Zurich anchor regional development pipelines. Research institutions with established EEG laboratories attract venture funding and spin-out activity. Regulatory sandbox programs in select jurisdictions compress commercialization timelines for breakthrough device developers.
United States
FDA breakthrough device designations accelerate review timelines for neurostimulation developers seeking prescription-grade indications. Reimbursement frameworks for remote neuro-monitoring mature fastest in Massachusetts and California, where hospital systems pilot home-use EEG protocols. The Greater Boston cluster concentrates venture-backed BCI startups alongside MIT and Harvard Medical School research hospitals.
Germany
The DiGA framework creates precedent for wearable brain device prescription coverage across EU member states. TÜV SÜD and other notified bodies under EU MDR Class IIa/IIb pathways extend conformity assessment timelines for neurostimulation entrants. Berlin and Munich host ISO 13485-certified contract manufacturers serving neurotechnology hardware developers.
Japan
PMDA neurotechnology review standards add compliance layers for cross-border entrants seeking prescription indications. METI funding programs support domestic EEG-fNIRS hybrid architecture development. The Kanto region around Tokyo concentrates pharmaceutical clinical trial operators sourcing calibrated neuro-monitoring equipment.
South Korea
MFDS digital therapeutics frameworks shape market access for software-integrated hardware bundles. Specialized EMS providers in Seoul and Busan offer turnkey quality management systems for neurotechnology startups. Samsung Medical Center and affiliated research institutions drive demand for laboratory-grade EEG validation studies.
Switzerland
Swissmedic maintains alignment with EU MDR while offering streamlined pathways for breakthrough neurotechnology. ETH Zurich and University Hospital Zurich anchor a precision engineering cluster serving microelectrode array manufacturers. The Basel-Zurich corridor attracts neurostimulation device developers seeking proximity to pharmaceutical clinical research organizations.
Wearable Brain Devices Market Key Industry Players
Top-tier vendors anchor the invasive implant segment, while mid-tier specialists populate non-invasive BCI hardware and consumer wellness applications. The vendor base stratifies across three tiers: prescription-grade neurostimulation developers with FDA designations, research-calibrated EEG headset manufacturers with institutional channel control, and direct-to-consumer wellness brands with software-integrated meditation platforms. Strategic moves concentrate on M&A for regulatory asset acquisition and strategic partnerships with ISO 13485-certified contract manufacturers.
Within the invasive neurotechnology tier, Neuralink exemplifies capital-intensive R&D positioning. Among non-invasive BCI specialists, Emotiv and Muse (InteraXon) occupy distinct archetypes—Emotiv represents research-institution channel dominance, while Muse anchors consumer wellness software integration. These three companies collectively illustrate the segmentation fault lines between clinical prescription models and direct-to-consumer positioning.
| Leading Market Players |
|---|
| Neurable |
| Mendi Innovations |
| Neuralink |
| Narbis |
| Epitel |
| Emotiv |
| IDUN Technologies |
| Neurosity |
| Muse (InteraXon) |
| Others |
Cost & Logistics Intelligence
Dry polymer electrode manufacturing scale-up in South Korean contract manufacturing zones simultaneously compresses per-unit sensor costs and concentrates procurement leverage among ISO 13485-certified EMS providers serving neurotechnology developers.
Pricing Analysis
Hardware-software unbundling separates device margins from recurring SaaS revenue streams across cognitive enhancement and wellness segments. Three-tier pricing structure across premium prescription-grade, standard clinical-research, and economy consumer-meditation levels reflects FDA breakthrough designation tiering and electrode fidelity specifications. Cost compression in consumer EEG headsets intensifies as Bluetooth-integrated fitness bands from Asian OEMs flood direct-to-consumer channels. Enterprise fleet buyers in United States technology sectors exhibit lowest price sensitivity, while individual wellness consumers abandon devices at threshold price points above meditation app subscription costs.
Supply Chain Analysis
Biomedical signal processing engineer scarcity in German precision manufacturing clusters and Massachusetts medical device corridors constrains R&D velocity for neurotechnology hardware developers. Silver-silver chloride sensor substrate supply draws from South African precious metals mining operations, while dry polymer electrode arrays source from South Korean and Chinese materials science specialists. Single-source vulnerability in conductive gel precursor chemicals creates disruption exposure for wet-electrode EEG headset manufacturers. Distribution runs through hospital GPO contracts for prescription-grade neurostimulation, direct-to-consumer e-commerce for wellness devices, and institutional procurement portals for research-calibrated equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wearable brain devices market compounds steadily as FDA breakthrough designations and Germany's DiGA framework institutionalize reimbursement pathways for prescription-grade neurotechnology.
For Market Incumbents: Anchor defensive positioning through backward integration into dry electrode substrate manufacturing, capturing margin pools threatened by silver price volatility. Fortify ISO 13485-certified contract manufacturing relationships in South Korea against emerging Chinese EMS competitors seeking neurotechnology entry. Prioritize HL7 FHIR interoperability middleware development to lock hospital EMR integration channels against software-native entrants. For New Entrants and Emerging Players: Closed-loop neurofeedback algorithm differentiation offers entry into pediatric epilepsy home-monitoring, a segment where caregiver alert integration remains underdeveloped by established vendors. Exploit EU MDR Class IIa lower-risk classification pathways for wellness-positioned sleep headbands, avoiding neurostimulation documentation burdens. Pursue German DiGA prescription coverage as the beachhead for hardware-software bundle reimbursement across EU member states. For Investors and Strategic Acquirers: Valuations sit cheapest among research-calibrated EEG headset manufacturers with institutional channel control but limited consumer brand recognition. Five-to-ten year viability hinges on reimbursement code creation for remote neuro-monitoring as the decisive scalability inflection. Monitor FDA breakthrough device designation velocity as the signal indicating which development pipelines warrant capital deployment priority.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerates review timelines for neurostimulation developers seeking prescription-grade United States market access. |
| CE Marking Pathway under EU MDR | Class IIa/IIb conformity assessments force clinical evidence front-loading for European neurotechnology commercialization. |
| Hospital System Partnership | Massachusetts General and affiliated research hospitals pilot home-use EEG protocols for remote patient monitoring scalability. |
| Software Companion Development | Meditation-integrated platforms from Canadian developers sustain brand differentiation against generic sensor hardware vendors. |
| Reimbursement Strategy | Germany's DiGA framework creates precedent for wearable brain device prescription coverage across EU member states. |
Research Approach
Bottom-up healthcare provider and research institution demand modeling reconciled against top-down neurotechnology hardware manufacturing capacity tracking forms the analytical core. Primary interviews with neurologists, hospital biomedical engineers, GPO contracts managers, and neurotechnology startup executives combine with secondary validation against FDA 510(k) and breakthrough device designation filings, EU MDR notified body registration databases, and German BfArM DiGA directory listings. Triangulation across these sources yields segment-level volume and value estimates.
Historical trendline analysis of EEG headset shipment patterns and neurostimulation device approval timelines informs projection frameworks across the analysis window. Segmentation dimensions modeled include product type tier, regulatory classification pathway, end-user procurement authority, and geographic reimbursement maturity. CAGR derivation incorporates electrode manufacturing cost curves, software subscription attach rates, and institutional procurement cycle timing. Forecast inputs include silver price volatility scenarios and FDA review queue velocity assumptions.
The model holds under stable precious metals supply and continued FDA breakthrough designation throughput; deviation in EU MDR notified body capacity constraints or reimbursement code creation delays would shift commercialization timeline assumptions. Forecasts reflect these documented assumptions with explicit sensitivity ranges. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Process Spectroscopy Market
Others
Inorganic Tin Chemicals Market
Others
South Korea Smart Home Market
Others
Allogeneic Human Chondrocyte Market
Others
Rugged Devices Market
Others
Connected TV Market
Others
Magnesite Market
Others
Legal Services Market
Others
UK 3D Printing Construction Market
Others
Asia-Pacific Agricultural Enzymes Market
Others
Global Cryogenic Tanks Market
Others
Corn Fiber Market
Others
Server Market
Others
Fabric Based Computing Market
Others
Quadrant Scale Market
Others
Australia Content Services Platform Market