
 Singapore Retail Market | 2026-2036
Singapore Retail Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Retail Market Outlook
The capital-intensity gap between neighborhood grocers and flagship department stores is collapsing as digital infrastructure costs equalize across formats. NTUC FairPrice leverages its cooperative scale to anchor supply chain control across heartland locations. Dairy Farm International Holdings sustains multi-banner coverage across convenience and health segments. Takashimaya differentiates through curated Japanese imports and experiential floor layouts.
Singapore retail encompasses the sale of finished consumer goods through fixed stores, pop-up formats, and digital platforms, with inventory turnover cycles typically spanning four to twelve weeks depending on perishability and fashion seasonality. The sector functions as a demand-aggregation layer connecting ASEAN manufacturing bases to domestic and tourist consumption. Apparel and electronics segments lead transaction volumes, though beauty products registers the fastest channel shift toward online fulfillment. Mid-range price tiers occupy the broadest customer base, while luxury captures disproportionate margin pools along Orchard Road and Marina Bay.
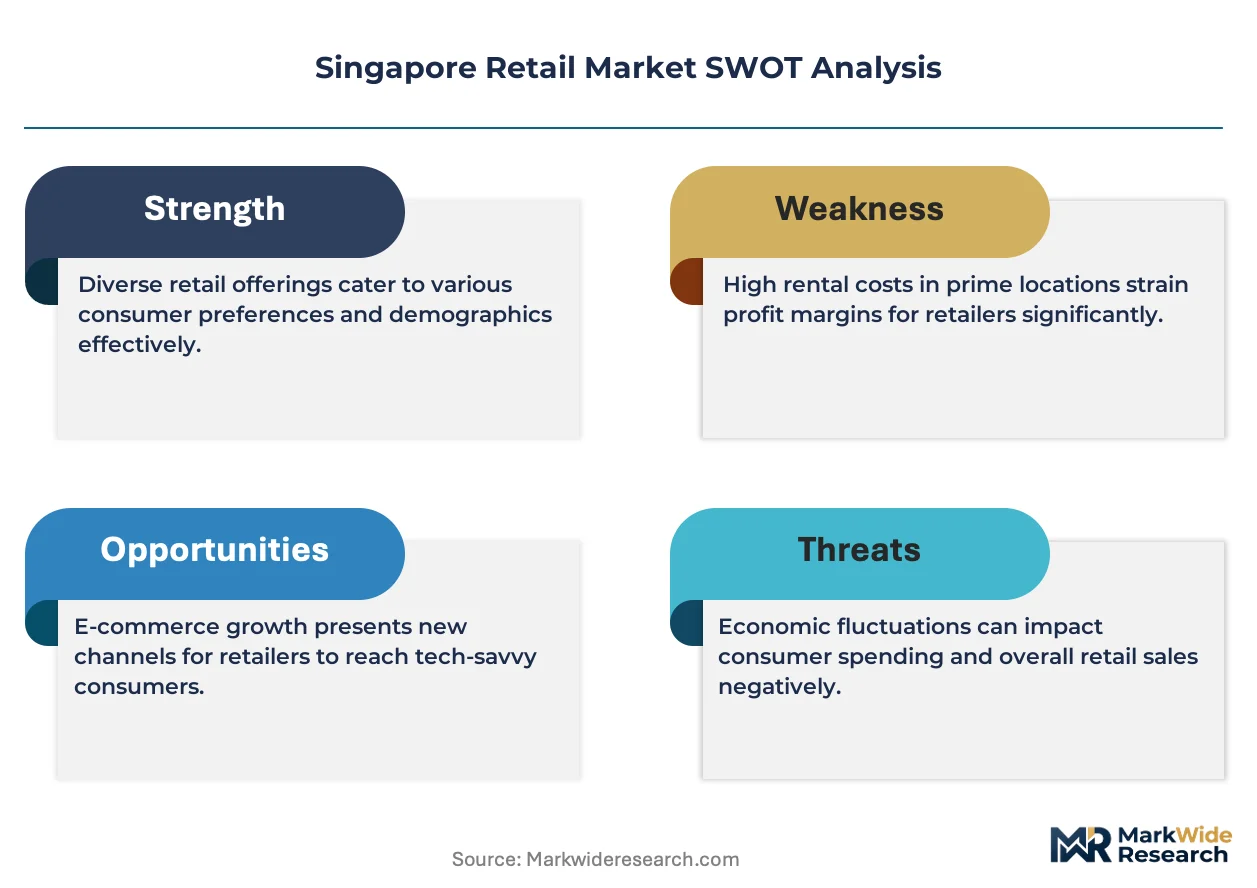
Singapore's Competition and Consumer Commission enforces fair trading practices, while the Personal Data Protection Commission governs customer data use in loyalty programs and e-commerce personalization. These frameworks elevate compliance costs for cross-border digital sellers while creating barriers against unregulated marketplace entrants. Retailers must monitor evolving GST treatment for low-value imports and the Urban Redevelopment Authority's zoning decisions that reshape foot traffic patterns across precincts.
Market Dynamics
Singapore's Personal Data Protection Commission enforcement is compressing digital commerce margins while equalizing compliance burdens between neighborhood grocers and flagship department stores, flattening the capital-intensity gap across retail formats.
Growth Catalysts
- Tourist return flows:Orchard Road luxury corridors capture concentrated demand from returning international visitors, with experiential floor layouts driving transaction density in premium segments.
- Omnichannel infrastructure:Digital platform integration accelerates as inventory management systems synchronize four-to-twelve-week turnover cycles across fixed stores and pop-up formats.
- ASEAN manufacturing connectivity:Singapore functions as a demand-aggregation layer linking regional production bases to domestic consumption, reducing import latency for apparel and electronics segments.
Market Restraints
- Compliance cost escalation:The Personal Data Protection Commission's tightening frameworks elevate operational expenditures for cross-border digital sellers, particularly affecting loyalty program personalization.
- Supply chain concentration:Reliance on ASEAN manufacturing bases creates vulnerability to regional logistics disruptions, with beauty products showing the fastest channel shift toward online fulfillment.
- GST treatment uncertainty:Evolving tax frameworks for low-value imports create pricing friction against unregulated marketplace entrants, compressing mid-range tier margins.
Strategic Opportunities
- Heartland precinct densification:Urban Redevelopment Authority zoning decisions are reshaping foot traffic patterns across suburban locations, opening capture zones for cooperative-format grocers.
- Experiential retail integration:Curated import formats and Japanese product specialization create differentiation wedges against standardized department store offerings.
- Health segment convergence:Multi-banner coverage across convenience and pharmacy channels enables cross-selling of perishables with wellness products in aging demographic catchments.
Industry Challenges
- Talent scarcity in data governance:The Competition and Consumer Commission's fair trading enforcement requires specialized compliance personnel that smaller format retailers struggle to retain.
- Legacy system integration friction:Digital infrastructure equalization demands capital deployment into inventory synchronization platforms that neighborhood operators lack technical capacity to deploy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Retail Market |
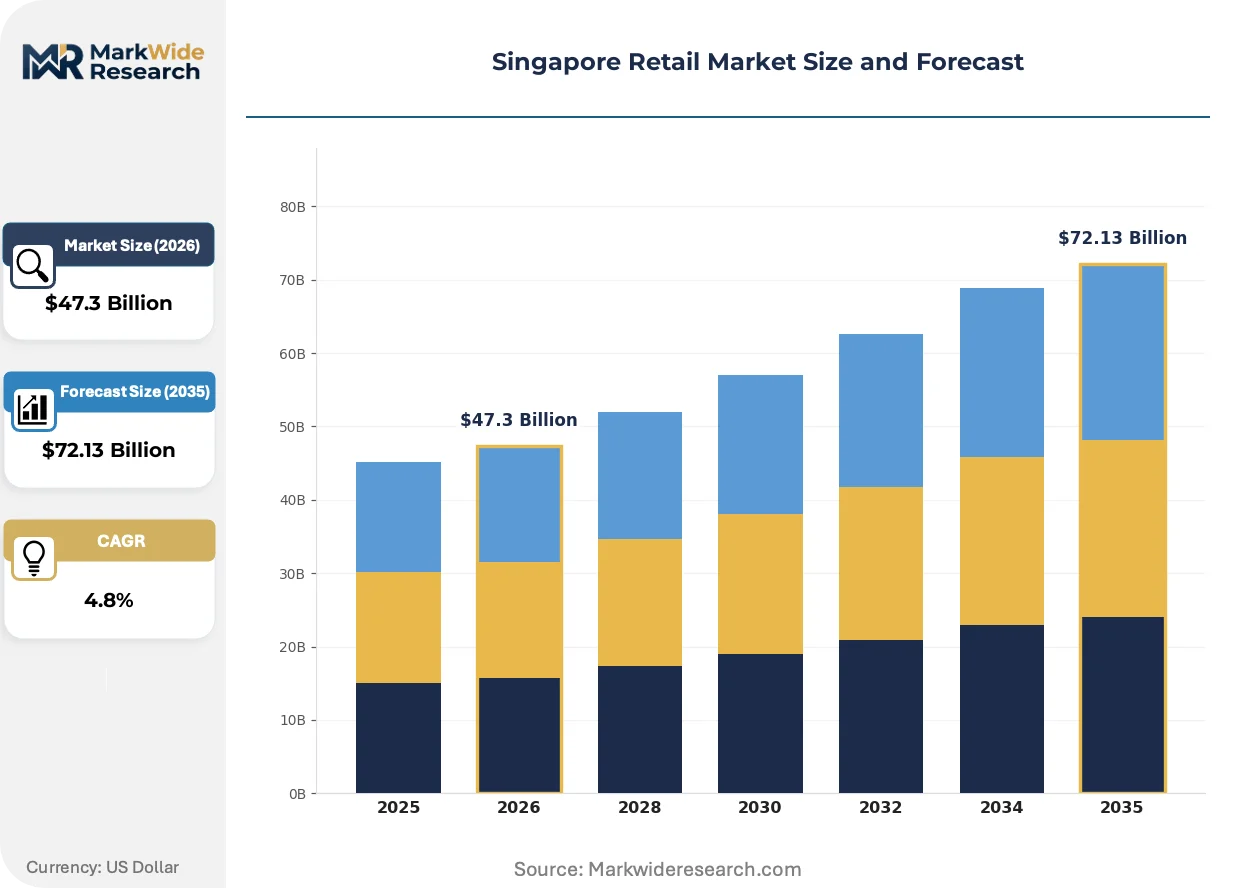
| Market Size in 2026 | $47.3 Billion |
| Market Size in 2035 | $72.13 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Apparel, Electronics, Home Goods, Beauty Products Price Tier: Luxury, Mid-range, Discount, Value Distribution Channel: Online, Brick-and-mortar, Wholesalers, Franchise Customer Type: Local Residents, Tourists, Corporate Clients, Families |
| Companies Covered | NTUC FairPrice, Dairy Farm International Holdings, Sheng Siong Group, Mustafa Centre, Courts Singapore, Watsons, Takashimaya, Giosis Group, Metro Holdings, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Retail Market Strategic Shifts
Retail technology deployment in Singapore is compressing the operational gap between format scales, with regulatory pressure on data use accelerating platform consolidation across digital and physical channels.
Artificial intelligence-driven demand forecasting is displacing traditional merchandise planning in apparel and electronics segments. Mid-range department stores deploy machine learning models to compress buying cycle decisions from seasonal to continuous replenishment. This capability is displacing the buyer intuition that previously differentiated flagship formats from mass-market competitors.
Singapore's Personal Data Protection Commission consent requirements for loyalty program data collection are tightening personalization scope. Retailers must now obtain explicit opt-in for behavioral tracking used in targeted promotions, elevating compliance architecture costs. Beauty products and online fulfillment channels face the steepest adaptation curves as they rely most heavily on granular customer profiling.
Consumer preference is rotating toward unified fulfillment options that blend immediate pickup with scheduled delivery. Heartland grocers and Orchard Road flagships alike are reconfiguring back-of-house space to accommodate click-and-collect volume. This shift is most visible in the mid-range price tier, where customers trade brand loyalty for convenience density in their residential precincts.
Singapore Retail Market Segmentation
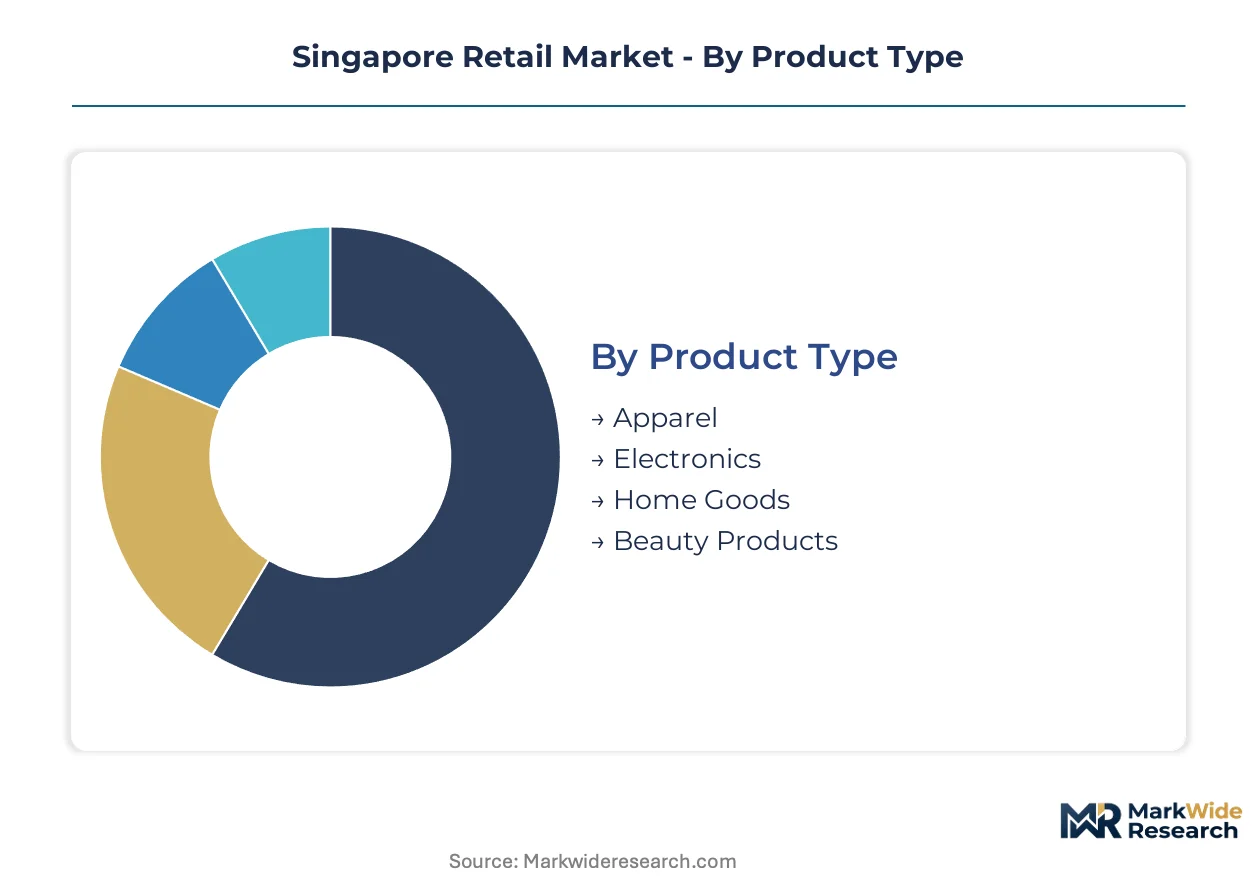
Retail segmentation in Singapore operates under distinct regulatory pressures that reshape competitive boundaries across formats. The Personal Data Protection Commission's consent frameworks and the Urban Redevelopment Authority's zoning decisions create divergent compliance burdens that stratify market positioning.
Product Type:
Personal Data Protection Commission enforcement intensity varies by product category, with perishability and data sensitivity determining personalization scope.
- Apparel:Inventory cycles spanning four-to-twelve weeks demand continuous replenishment systems. Orchard Road flagships capture tourist transaction density while heartland locations serve resident convenience needs.
- Electronics:ASEAN manufacturing connectivity reduces import latency for smartphones and computing devices. Machine learning models now displace traditional buyer intuition in merchandise planning decisions.
- Home Goods:Larger format footprints concentrate in suburban precincts where Urban Redevelopment Authority zoning permits showroom-scale retail.
- Beauty Products:Channel shift toward online fulfillment accelerates as explicit opt-in requirements tighten under data protection frameworks.
Electronics handles the majority of throughput; beauty products is the fastest mover on share.
Price Tier:
Capital deployment requirements scale inversely with margin compression, creating distinct operational architectures across tiers.
- Luxury:Experiential floor layouts along Orchard Road and Marina Bay capture disproportionate margin pools from returning international visitors. Curated Japanese imports and personalized service justify premium positioning.
- Mid-range:Cooperative-format grocers and standardized department stores occupy the broadest customer base. Click-and-collect reconfiguration of back-of-house space drives convenience density in residential precincts.
- Discount:Supply chain control through cooperative scale anchors price competitiveness across heartland locations.
- Value:GST treatment uncertainty for low-value imports creates pricing friction against unregulated marketplace entrants.
Mid-range handles the majority of throughput; luxury is gaining share fastest through experiential differentiation.
Distribution Channel:
Digital infrastructure costs have equalized across formats, collapsing the capital-intensity gap between neighborhood operators and flagship formats.
- Online:Beauty products and electronics lead transaction volumes through platform integration. Compliance architecture costs escalate under explicit consent requirements for behavioral tracking.
- Brick-and-mortar:Fixed stores and pop-up formats synchronize inventory management systems across four-to-twelve-week turnover cycles. Back-of-house reconfiguration accommodates unified fulfillment options.
- Wholesalers:ASEAN manufacturing bases connect to domestic consumption through demand-aggregation layers that reduce logistics latency.
- Franchise:Multi-banner coverage across convenience and health segments enables cross-selling in aging demographic catchments.
Brick-and-mortar handles the majority of throughput; online is expanding most quickly as channel shift accelerates.
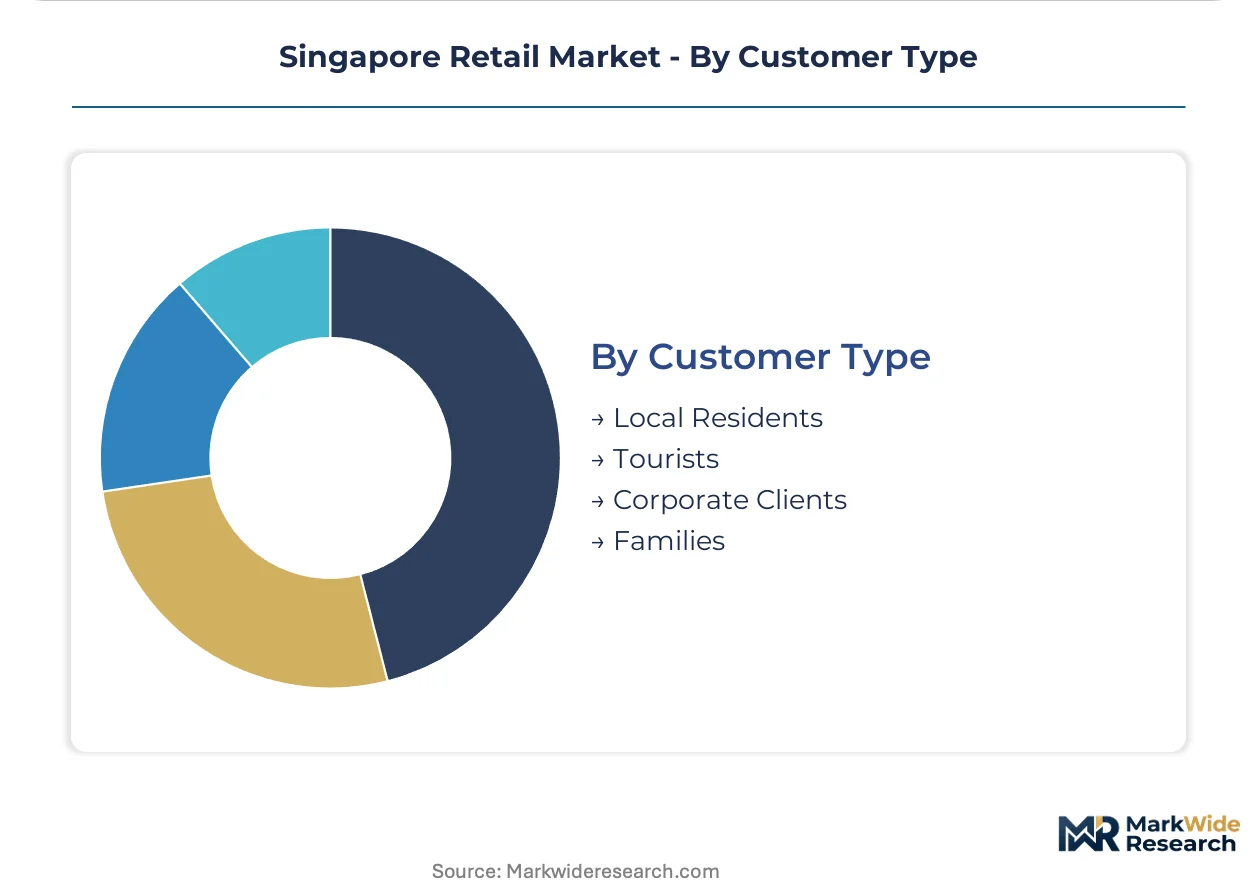
Customer Type:
Urban Redevelopment Authority zoning decisions reshape foot traffic patterns that concentrate demand by customer segment.
- Local Residents:Heartland precinct densification opens capture zones for cooperative-format grocers. Omnichannel adoption accelerates as residents trade brand loyalty for convenience density.
- Tourists:Returning international visitors drive transaction density in Orchard Road luxury corridors. Experiential floor layouts differentiate against standardized department store offerings.
- Corporate Clients:Bulk procurement patterns concentrate in wholesale and franchise channels with dedicated account management.
- Families:Health segment convergence targets aging demographic catchments with wellness product cross-selling alongside perishables.
Local residents handle the majority of throughput; tourists are climbing the fastest as international return flows strengthen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Orchard Road and Marina Bay precincts, while heartland suburban zones compete on convenience density rather than margin extraction. This asymmetry shapes capital deployment patterns across Singapore's retail geography.
Orchard Road Corridor
Luxury flagships capture disproportionate tourist transaction density through experiential floor layouts. The Urban Redevelopment Authority's conservation guidelines preserve heritage façades while permitting back-of-house reconfiguration for unified fulfillment. Takashimaya anchors the Japanese-import specialization cluster with curated merchandise planning.
Marina Bay Financial District
Corporate clientele and high-net-worth residents drive premium convenience retail in integrated developments. The Personal Data Protection Commission's consent frameworks elevate compliance architecture costs for loyalty program operators. Dairy Farm International Holdings sustains multi-banner coverage across pharmacy and convenience formats in this zone.
Heartland Town Centres
NTUC FairPrice leverages cooperative scale to anchor supply chain control across Tampines, Jurong West, and Woodlands. The Housing Development Board's precinct densification creates capture zones for grocers with click-and-collect infrastructure. Sheng Siong Group competes on price positioning in these suburban catchments.
Chinatown and Heritage Districts
Mustafa Centre operates a 24-hour emporium format targeting value-conscious segments and regional visitors. The Singapore Tourism Board's heritage trail investments sustain foot traffic independent of luxury retail cycles. Traditional shophouse operators face zoning constraints on floor area expansion.
Industrial Fringe Zones
Last-mile fulfillment centres concentrate in Jurong and Tampines logistics corridors where Urban Redevelopment Authority zoning permits warehouse-scale retail. Giosis Group exemplifies platform-based sellers utilizing these locations for inventory staging. GST treatment uncertainty for low-value imports creates pricing friction in this channel.
Singapore Retail Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across Singapore retail. Cooperative-format grocers anchor supply chain control through scale aggregation, while luxury flagships differentiate through experiential merchandising. The market structure stratifies into three archetypes: scale-driven cooperatives, multi-banner conglomerates, and curated specialists. Competitive moves concentrate on omnichannel infrastructure deployment and heartland precinct densification rather than horizontal consolidation.
Among Singapore-based operators, NTUC FairPrice and Sheng Siong Group represent the cooperative and listed-grocer archetypes respectively, while Dairy Farm International Holdings anchors the multi-banner conglomerate position with coverage across convenience, health, and premium supermarket segments. These three entities exemplify how scale, format diversification, and price positioning create distinct competitive territories within a geographically constrained market.
| Leading Market Players |
|---|
| NTUC FairPrice |
| Dairy Farm International Holdings |
| Sheng Siong Group |
| Mustafa Centre |
| Courts Singapore |
| Watsons |
| Takashimaya |
| Giosis Group |
| Metro Holdings |
| Others |
Value Chain & Pricing Dynamics
Four-to-twelve-week inventory turnover cycles compress pricing power toward operators with synchronized replenishment systems, flattening margin extraction capability across Orchard Road flagships and heartland grocers alike. The Personal Data Protection Commission's compliance cost escalation feeds directly into operational expenditure structures that reshape competitive positioning between digital-native entrants and legacy format incumbents.
Pricing Analysis
Configured-to-order pricing through curated Japanese import formats commands substantial premiums over standardized department store offerings, with experiential floor layouts and personalized service anchoring the spread. Three-tier pricing structure across premium, standard, and economy levels stratifies by convenience density and brand heritage, while GST treatment uncertainty for low-value imports intensifies cost compression in value-tier segments. Tourist-facing luxury corridors exhibit lowest price sensitivity; heartland residents trade brand loyalty for click-and-collect accessibility.
Supply Chain Analysis
Port congestion along the Singapore-Johor Bahru trade lane elevates inbound logistics costs for ASEAN-manufactured apparel and electronics, with container availability fluctuations rippling through four-to-twelve-week replenishment schedules. Manufacturing concentration in Vietnam, Bangladesh, and China feeds finished goods through demand-aggregation layers, with single-source vulnerability in beauty product components creating exposure to regional logistics disruptions. Distribution runs through cooperative-format scale operators and multi-banner conglomerates with captive warehouse networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Singapore retail sits at a high-growth inflection as Personal Data Protection Commission enforcement accelerates platform consolidation, compressing digital commerce margins while equalizing compliance burdens across format scales.
For Market Incumbents: Consolidate omnichannel infrastructure investments to anchor supply chain control against emerging platform-based sellers, leveraging cooperative scale for procurement leverage. Deploy capital into inventory synchronization systems that compress turnover cycles below competitor benchmarks. Prioritize heartland precinct densification as Urban Redevelopment Authority zoning reshapes foot traffic capture zones. For New Entrants and Emerging Players: Certification fast-track through Personal Data Protection Commission compliance architecture creates differentiation wedge against unregulated marketplace entrants. Target beauty product online fulfillment as the fastest channel shift segment with lowest incumbent personalization adaptation. Pursue experiential retail integration in heritage districts where Singapore Tourism Board investments sustain foot traffic independent of luxury cycles. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because cooperative-format grocers and multi-banner conglomerates possess irreplaceable scale advantages in a geographically constrained market. Acquisition target archetype: mid-format operators with underutilized back-of-house space reconfigurable for unified fulfillment. Signal to watch: Urban Redevelopment Authority zoning decisions accelerating heartland densification timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Omnichannel Infrastructure Deployment | Inventory synchronization platforms compress turnover cycles across fixed stores and pop-up formats. |
| Heartland Precinct Densification | Cooperative-format grocers capture Housing Development Board precinct expansion zones. |
| Experiential Floor Layout Investment | Curated import formats differentiate against standardized department store offerings. |
| Compliance Architecture Buildout | Explicit consent systems satisfy Personal Data Protection Commission behavioral tracking requirements. |
| Unified Fulfillment Reconfiguration | Back-of-house space adaptation enables click-and-collect volume in residential catchments. |
Study Parameters
Initial hypotheses were tested against primary input from retail operations executives, category buyers at cooperative and listed grocers, loyalty program managers, and Urban Redevelopment Authority planning officers and refined through secondary validation against Singapore Department of Statistics retail sales data, Personal Data Protection Commission enforcement notices, and company filings. Bottom-up store-level modeling triangulated against top-down sector aggregation.
Variance decomposition across product type, price tier, distribution channel, and customer type segmentation dimensions shaped analytical framework construction over the projection horizon. CAGRs were derived from trend extrapolation calibrated to historical turnover cycle compression and tourist return flow trajectories. Forecast inputs incorporated ASEAN manufacturing connectivity latency and GST treatment policy evolution.
Decision-makers should treat outputs as directional under base assumptions of sustained tourist recovery and stable regulatory enforcement intensity; material deviation would warrant model refresh. Specific risk factors include supply chain concentration in regional logistics corridors and evolving low-value import tax frameworks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Asia-Pacific Medium-Density Fiberboard Market
Others
Ambient Assisted Living and Smart Home Market
Others
Crystal Growth Equipment Market
Others
Bio-Based Leather Market
Others
Defense Optronics Market
Others
Durian Market
Others
Managed Testing Services Market
Others
Indoor LBS Market
Others
Toy Packaging Market
Others
Europe Tablet PC Market
Others
Medium-Voltage Switchgear Market
Others
Depth Gauge Market
Others
North America Cashew Market
Others
Space Power Supply Market
Others
Surgical Simulation Market
Others
Digital Audio Decoders Market