
 High Frequency Vibrator Market | 2026-2036
High Frequency Vibrator Market Size, Share, and Industry Trends Forecast 2026-2036
High Frequency Vibrator Market Foresight
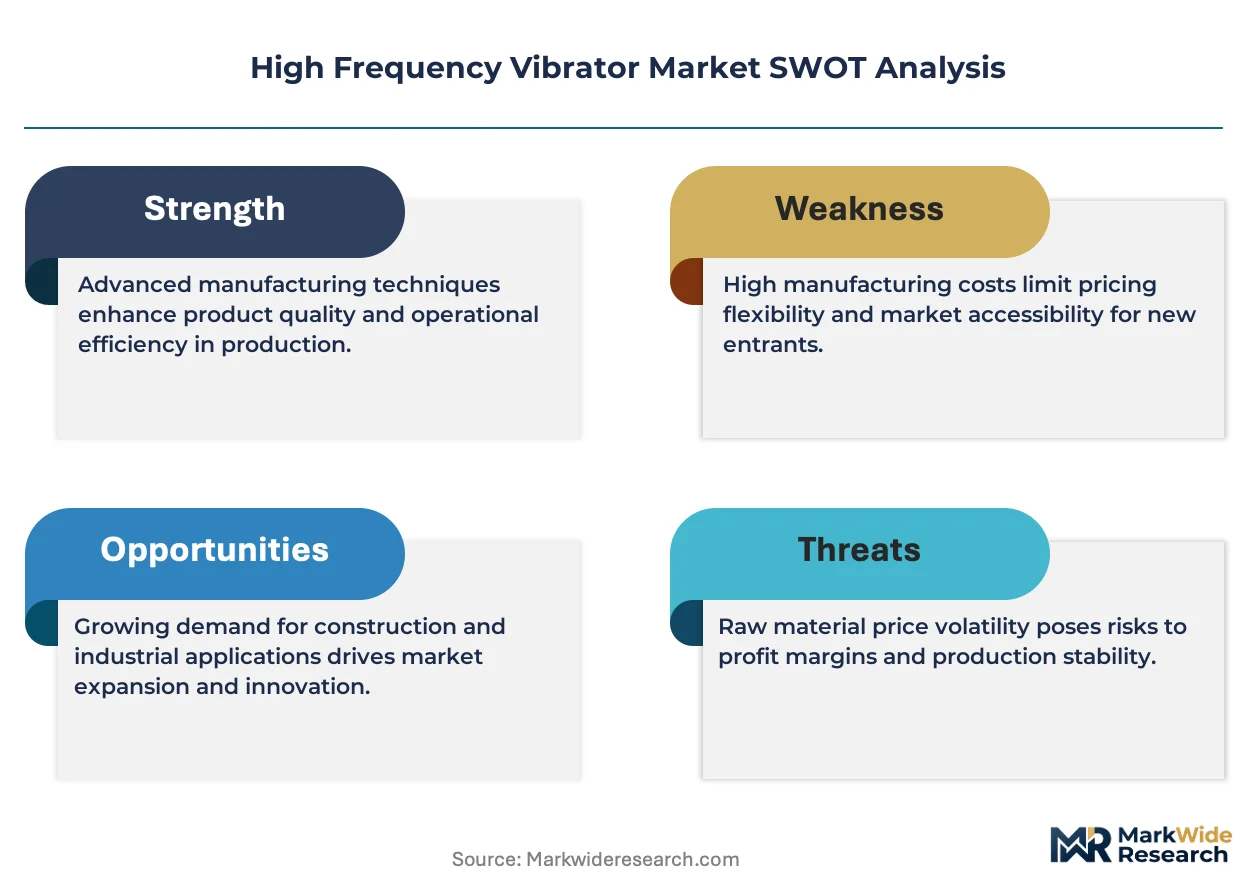
Skilled technician availability for electrodynamic and piezoelectric system calibration is rotating toward scarcity in mature manufacturing economies. Atlas Copco AB leverages its compressor and vibration technology heritage to sustain integrated product ecosystems across European and Asian job sites. Wacker Neuson SE anchors its position through dense rental and distribution networks that place high-frequency units within same-day reach of concrete contractors. BRECON Vibrationstechnik GmbH specializes in custom-engineered solutions for pharmaceutical and food-grade applications where surface finish and contamination control command premium positioning.
High frequency vibrators are electromechanical or electrodynamic devices generating oscillatory forces typically above 3,000 cycles per minute for material consolidation, flow promotion, or compaction in industrial processes. These units employ eccentric weights, electromagnetic coils, or piezoelectric crystals to translate rotational or electrical energy into directed mechanical vibration with amplitude precision measured in millimeters. Electric vibrators dominate volume in construction batch plants and precast yards where grid power availability eliminates compressor dependency, while piezoelectric variants capture margin in pharmaceutical tablet handling and semiconductor wafer positioning where frequency stability below 0.1% drift is mandatory. Pneumatic vibrators retain share in mining and bulk material chutes where explosive atmospheres prohibit spark-generating motor architectures.
The EU Machinery Directive and OSHA workplace vibration standards constrain allowable hand-arm and whole-body exposure thresholds, forcing manufacturers to redesign isolation mounts and reduce emitted accelerations. FDA cGMP guidelines and EMA Annex 15 requirements for pharmaceutical manufacturing equipment further narrow acceptable surface roughness and cleanability profiles for vibratory contact surfaces. Stakeholders must monitor evolving carbon-border adjustment mechanisms and regional machinery efficiency standards that will reshape sourcing decisions for motor windings, cast housings, and electronic drive components.
Market Dynamics
EU Machinery Directive vibration exposure limits and OSHA hand-arm threshold mandates are forcing redesign cycles across pneumatic and electromelectric product lines, compressing replacement timelines for construction contractors while elevating specification complexity for pharmaceutical and food-grade applications.
Growth Catalysts
- OSHA vibration exposure standards:Workplace safety mandates in the United States are accelerating retirement of legacy pneumatic units with higher emitted accelerations, pulling demand toward isolated electromelectric architectures with compliant isolation mounts.
- Concrete compaction intensity:Infrastructure corridors in China are sustaining batch plant procurement of electric vibrators where grid reliability eliminates compressor dependency and reduces operational friction for contractors.
- Pharmaceutical surface finish requirements:FDA cGMP guidelines for tablet handling and powder flow applications are mandating piezoelectric precision below 0.1% frequency drift, expanding premium positioning for contamination-controlled systems.
Market Restraints
- Copper and rare-earth magnet volatility:Motor winding materials and neodymium supply concentration in processing geographies create input cost instability for electromelectric unit manufacturers.
- Calibration technician scarcity:Electrodynamic and piezoelectric system maintenance requires specialized skill sets that are rotating toward shortage in mature manufacturing economies, constraining service network expansion.
- Pneumatic retention in explosive atmospheres:Mining and bulk material chute applications where spark prohibition applies limit electric unit penetration, preserving compressor-dependent architectures in safety-critical zones.
Strategic Opportunities
- India industrial corridor expansion:PLI scheme incentives for domestic manufacturing infrastructure are creating white space for rental network density and same-day distribution models around concrete precast yards.
- Semiconductor wafer positioning:Nanometer-scale vibration control requirements in cleanroom environments are opening piezoelectric applications beyond pharmaceutical into wafer handling and microassembly tooling.
- EU carbon-border adjustment mechanisms:Embodied carbon tracking for cast housings and electronic drive components is creating preference for regional motor winding suppliers with documented supply chain transparency.
Industry Challenges
- EMA Annex 15 cleanability certification:Pharmaceutical equipment validation timelines for surface roughness and material traceability extend sales cycles and require dedicated regulatory affairs capacity.
- Legacy pneumatic integration:Construction contractors with sunk compressor infrastructure face capital friction when migrating to electromelectric units despite operational efficiency gains.
- Electromagnetic compatibility testing:Variable frequency drive architectures for piezoelectric control require IEC 61000 compliance validation that strains smaller manufacturer R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Frequency Vibrator Market |
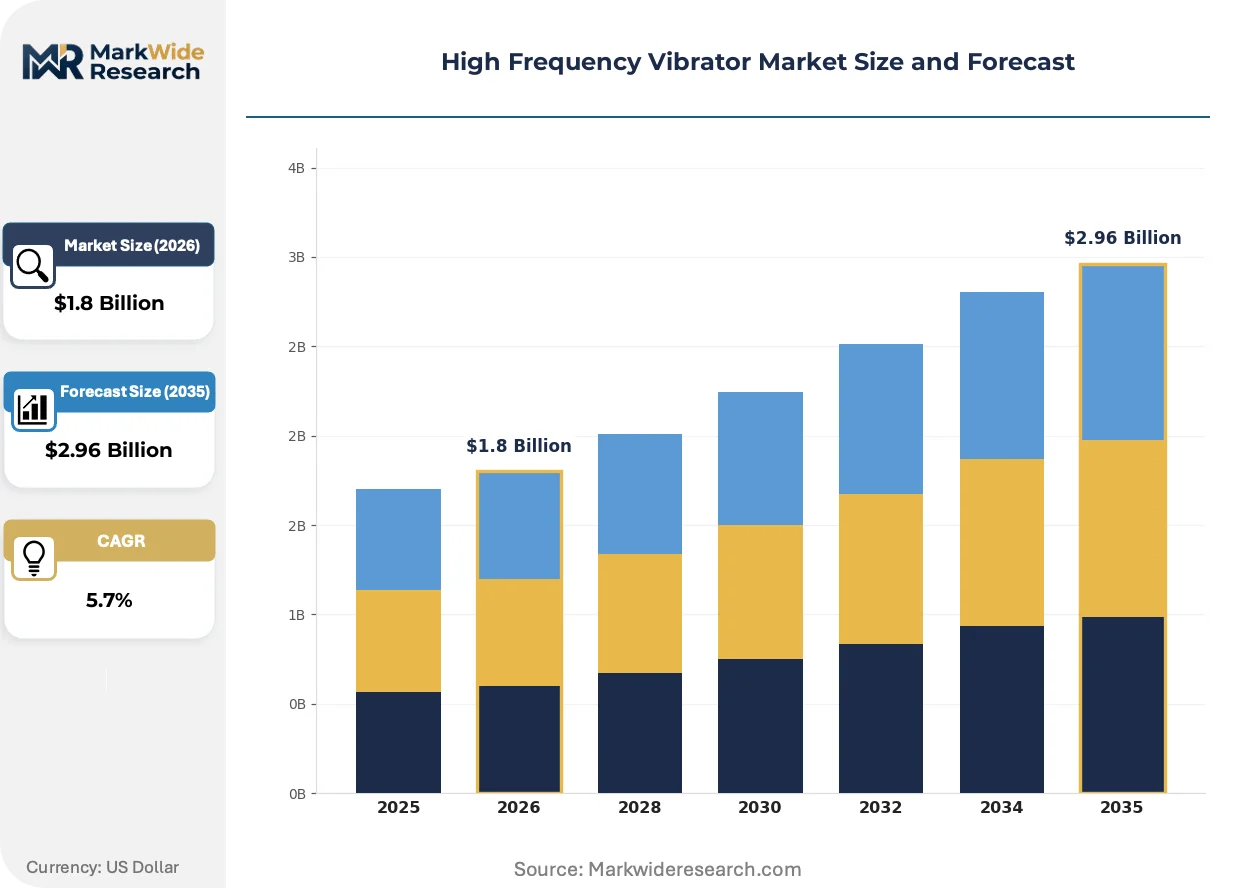
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pneumatic Vibrators, Electric Vibrators, Hydraulic Vibrators, Mechanical Vibrators Application: Construction, Mining, Food Processing, Pharmaceutical End User: Manufacturers, Contractors, Distributors, Service Providers Technology: Electromechanical, Electrodynamic, Ultrasonic, Piezoelectric |
| Companies Covered | Wacker Neuson SE, Atlas Copco AB, Oztec Industries Inc, ENARCO SA, BRECON Vibrationstechnik GmbH, VEGA Srl, Lievers Holland BV, Multiquip Inc, Wyco Tool Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Frequency Vibrator Market Shifts & Advancements
Active material substitution and regulatory tightening are compressing product lifecycles while fragmenting procurement authority between central engineering specifications and distributed job-site rental decisions.
Variable frequency drive control with real-time amplitude feedback is supplanting fixed-frequency electromechanical architectures in pharmaceutical tablet coating and concrete consolidation applications. Precast yard operators in Germany and Japan are specifying these units for batch-to-batch consistency. The technology is supplanting pneumatic dominance in medium-duty compaction by eliminating compressor capital and maintenance overhead while meeting tightening EU Machinery Directive emission thresholds.
REACH substance restrictions on perfluorinated compounds and RoHS recast directives are constraining coating and insulation material choices for vibrator housings and windings. Manufacturers are reformulating surface treatments and seal materials to maintain corrosion resistance without restricted chemistries. Electromelectric product lines destined for European pharmaceutical and food processing installations are experiencing the most intensive material requalification cycles.
Equipment-as-a-service contracting is displacing capital purchase models among mid-size concrete contractors facing balance sheet pressure from material cost inflation. Rental networks with integrated maintenance and calibration services are capturing specification influence previously held by distributor sales engineers. This pattern concentrates in Japan's urban construction markets where contractor fragmentation and skilled technician scarcity coincide.
High Frequency Vibrator Market Segmentation
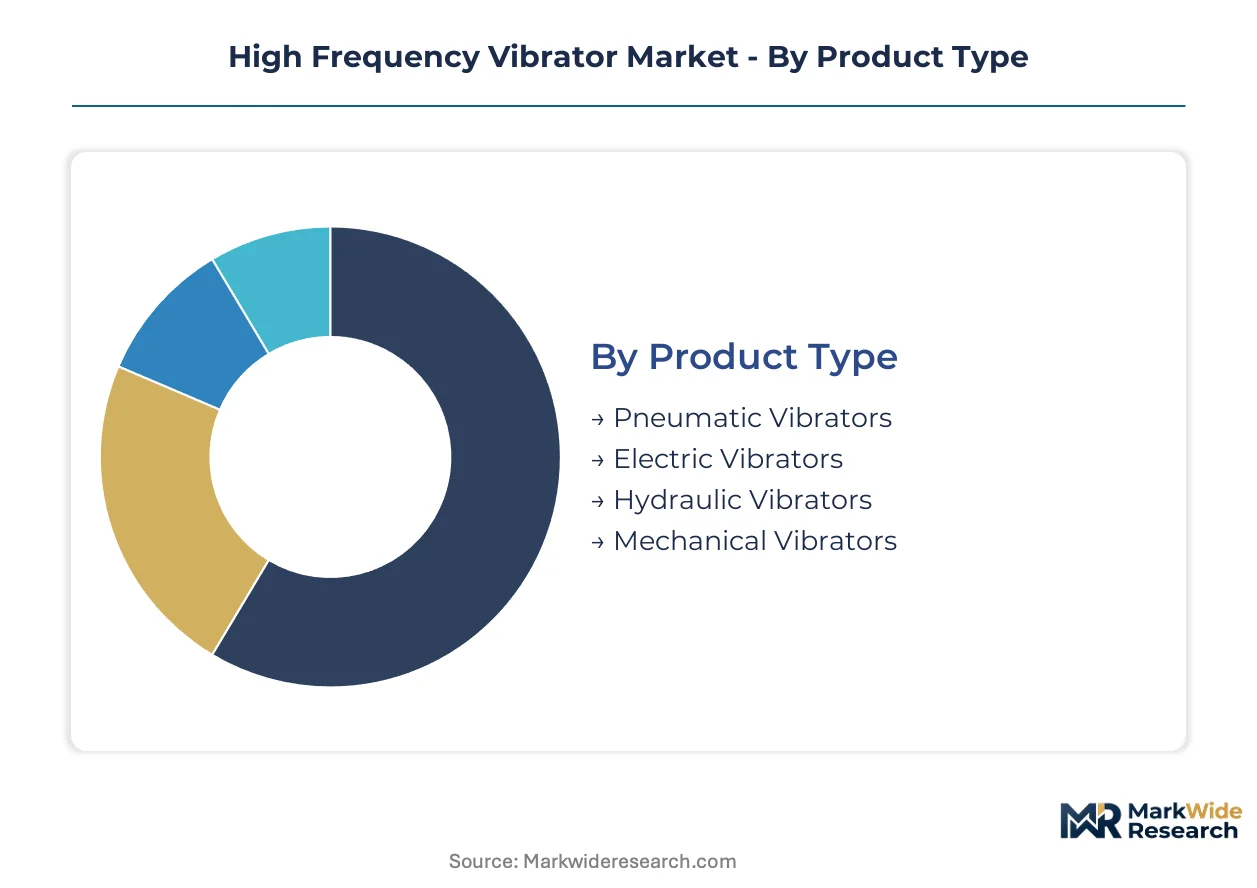
High frequency vibrator procurement fractures across multiple decision axes. Contractors prioritize portability and power source availability, while pharmaceutical and food processors demand frequency stability and surface finish compliance that command fundamentally different engineering investments.
Product Type:
Pneumatic architectures face the most intense substitution pressure from electromelectric alternatives as compressor dependency becomes economically and operationally burdensome in grid-reliable environments.
- Electric Vibrators:Grid-powered units with eccentric weight or electromagnetic drive systems deliver consistent amplitude without compressor infrastructure. Demand concentrates in China's industrial corridor cities where infrastructure investment sustains batch plant procurement and grid reliability eliminates operational friction. OSHA hand-arm vibration thresholds accelerate replacement of legacy pneumatic units toward isolated electromelectric architectures.
- Pneumatic Vibrators:Compressed-air-driven piston or turbine mechanisms generate oscillatory force through pneumatic energy conversion. Mining and bulk material chute applications in explosive atmospheres where spark prohibition applies preserve compressor-dependent architectures as safety-critical necessities despite operational overhead.
- Hydraulic Vibrators:Fluid-power systems leveraging existing hydraulic infrastructure on heavy equipment for material consolidation.
- Mechanical Vibrators:Direct-drive rotational units with fixed-frequency output for basic compaction tasks.
Electric vibrators retain volume leadership; pneumatic vibrators hold the steepest contraction curve outside safety-critical zones.
Application:
Cost tier stratification separates commodity construction procurement from premium pharmaceutical validation cycles.
- Construction:Concrete compaction and precast yard operations dominate unit volume. Germany and Japan contractors specify variable frequency drive units for batch-to-batch consistency. Equipment-as-a-service contracting displaces capital purchases among mid-size contractors facing balance sheet pressure.
- Pharmaceutical:Tablet handling, powder flow promotion, and coating applications mandate piezoelectric precision below 0.1% frequency drift. FDA cGMP guidelines and EMA Annex 15 requirements narrow acceptable surface roughness and extend validation timelines.
- Mining:Bulk material chute flow promotion in spark-prohibited environments.
- Food Processing:Contamination-controlled material handling with cleanability certification requirements.
Construction commands absolute unit volume; pharmaceutical applications climb the fastest on value per unit.
End User:
Customer type determines whether procurement authority sits with central engineering specifications or distributed job-site rental decisions.
- Contractors:Concrete and material handling operators with fragmented procurement authority across project sites. Japan's urban construction markets exhibit concentrated rental network influence where contractor fragmentation and skilled technician scarcity coincide.
- Manufacturers:Integrated production facilities with central capital budgeting and specification control. Pharmaceutical and food-grade OEMs drive piezoelectric and electrodynamic system requirements through engineering-driven procurement.
- Distributors:Channel intermediaries with specification influence in fragmented contractor markets.
- Service Providers:Calibration and maintenance specialists addressing technician scarcity in mature manufacturing economies.
Contractors drive absolute unit demand; manufacturers capture the steepest value concentration.
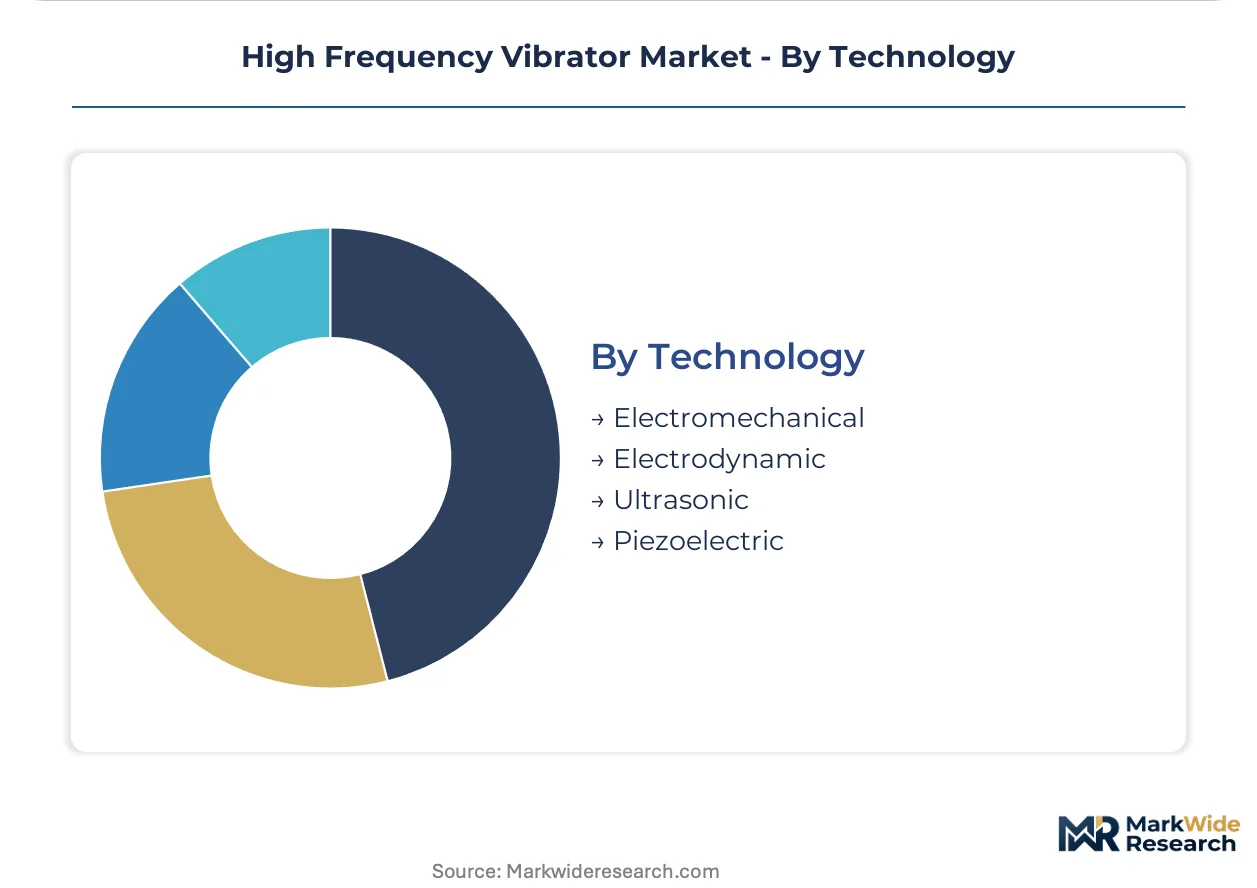
Technology:
Margin structure separates precision-controlled piezoelectric architectures from commodity electromechanical volume production.
- Piezoelectric:Crystal-based oscillation generation with frequency stability below 0.1% drift for nanometer-scale control. Semiconductor wafer positioning in cleanroom environments extends applications beyond pharmaceutical into microassembly tooling. REACH substance restrictions and RoHS recast directives constrain coating and insulation material choices.
- Electromechanical:Eccentric weight or electromagnetic coil systems dominating construction batch plants where amplitude precision requirements permit broader tolerances. Variable frequency drive control with real-time feedback supplants fixed-frequency architectures.
- Electrodynamic:Linear motor-based force generation requiring specialized calibration expertise.
- Ultrasonic:High-frequency acoustic vibration for precision material processing and cleaning applications.
Electromechanical systems retain volume leadership; piezoelectric platforms gain share fastest on precision requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and Japan favor electromelectric precision for concrete compaction, while China absorbs volume through infrastructure corridors and the United States drives replacement cycles through OSHA-mandated safety upgrades.
Germany
Precast yard operators in Bavaria and Baden-Württemberg specify variable frequency drive units for batch-to-batch consistency in concrete consolidation. The EU Machinery Directive enforces stringent vibration exposure limits that compress replacement timelines for legacy pneumatic equipment. Stuttgart's industrial cluster anchors demand for contamination-controlled systems serving pharmaceutical and food-grade applications.
China
Industrial corridor cities sustain procurement of electric vibrators where grid reliability eliminates compressor dependency for construction contractors. The MIIT and GB standards frameworks shape equipment efficiency and safety certifications for domestic manufacturing. Yangtze River Delta infrastructure investment outpaces other manufacturing hubs, concentrating demand in Shanghai and Jiangsu province batch plants.
United States
OSHA hand-arm vibration thresholds accelerate retirement of higher-emission pneumatic units toward isolated electromelectric architectures. The EPA and Department of Labor coordinate enforcement of workplace safety mandates across construction and manufacturing sectors. Texas and California construction markets exhibit concentrated rental network influence where contractor fragmentation meets skilled technician scarcity.
Japan
Urban construction markets in Tokyo and Osaka demonstrate equipment-as-a-service contracting displacement of capital purchases among mid-size concrete contractors. METI industrial standards and JIS certification requirements elevate specification complexity for imported equipment. Kanto region precast yards anchor procurement of precision-controlled systems for infrastructure projects.
India
PLI scheme incentives for domestic manufacturing infrastructure create white space for rental network density around concrete precast yards in Maharashtra and Gujarat. The BIS framework governs equipment safety and performance standards for industrial machinery deployment. Delhi-Mumbai Industrial Corridor investment sustains demand for material consolidation equipment in bulk material handling applications.
High Frequency Vibrator Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper stratum controlling compressor and vibration technology ecosystems while mid-scale players compete on rental network density and same-day distribution reach. The middle tier fragments across electromechanical volume producers and piezoelectric precision specialists serving divergent end-use requirements. Two dominant competitive moves are reshaping positioning: backward integration into motor winding and cast housing supply chains to manage carbon-border exposure, and geographic expansion of rental-service footprints to capture specification influence from distributor sales engineers.
Among European-anchored integrated industrials, Atlas Copco AB and Wacker Neuson SE exemplify divergent archetypes—one leveraging compressor heritage for technology ecosystem control, the other anchoring position through dense rental infrastructure placing units within same-day contractor reach. BRECON Vibrationstechnik GmbH occupies a specialist position, representing the custom-engineering tier where pharmaceutical and food-grade surface finish requirements command premium positioning and extended validation timelines.
| Leading Market Players |
|---|
| Wacker Neuson SE |
| Atlas Copco AB |
| Oztec Industries Inc |
| ENARCO SA |
| BRECON Vibrationstechnik GmbH |
| VEGA Srl |
| Lievers Holland BV |
| Multiquip Inc |
| Wyco Tool Company |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day lead times for neodymium magnet and copper winding procurement concentrate pricing power with motor suppliers in China and Germany, forcing electromelectric vibrator manufacturers to absorb input volatility or push cost escalation downstream to construction contractors and pharmaceutical OEMs.
Pricing Analysis
Long-term offtake contracts dominate procurement between tier-one manufacturers and mining operators, while spot purchasing prevails among mid-size concrete contractors sourcing replacement pneumatic units. Three-tier pricing structure across premium piezoelectric, standard electromelectric, and economy pneumatic levels separates FDA-validated pharmaceutical systems from commodity construction equipment. Cost compression in the electromechanical tier is intensifying because copper and rare-earth magnet volatility strains motor winding economics. Contractors exhibit the highest price sensitivity, while pharmaceutical manufacturers prioritize frequency stability and contamination control over unit cost.
Supply Chain Analysis
Strategic stockpiling of neodymium and copper concentrates among tier-one motor manufacturers contrasts with just-in-time inventory practices at pneumatic vibrator assemblers dependent on aluminum and steel castings. China, Germany, and Japan anchor global supply for precision electromagnetic components and piezoelectric crystals. Motor winding materials and electronic drive components feed from concentrated rare-earth processing geographies. Single-source vulnerability in neodymium supply chains exposes electromelectric producers to export restriction risk. Distribution runs through dense rental networks in Japan and Germany alongside direct OEM sales for pharmaceutical applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Variable frequency drive adoption and OSHA vibration exposure mandates are compressing replacement cycles and fragmenting procurement authority between rental networks and central engineering specifications.
For Market Incumbents: Secure backward integration into cast housing and motor winding supply chains to manage carbon-border adjustment exposure from EU regulatory frameworks. Anchor channel control through expanded calibration and maintenance service networks addressing technician scarcity in mature manufacturing economies. Defend against pneumatic-to-electric substitution by bundling equipment-as-a-service contracts with same-day distribution guarantees. For New Entrants and Emerging Players: Differentiate on piezoelectric precision for semiconductor wafer positioning applications beyond established pharmaceutical markets. Target India's PLI-subsidized industrial corridors for rental network density around Maharashtra and Gujarat precast yards. Pursue joint venture structures with domestic distributors to bypass established compressor-technology ecosystems. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because tightening EU Machinery Directive and OSHA enforcement creates durable replacement demand independent of construction cyclicality. Acquisition candidates include electrodynamic calibration specialists with captive technician training infrastructure. Watch for carbon-border adjustment mechanism implementation thresholds as the signal triggering accelerated regional supply chain restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motor Windings | Captive neodymium and copper supply reduces exposure to carbon-border adjustment mechanisms in EU markets. |
| Rental Network Expansion | Same-day distribution density captures specification influence from distributor sales engineers in fragmented contractor markets. |
| Piezoelectric Precision Investment | Frequency stability below 0.1% drift opens semiconductor wafer handling beyond pharmaceutical tablet applications. |
| Equipment-as-a-Service Contracting | Recurring revenue models displace capital purchases among balance-sheet-constrained mid-size concrete contractors. |
| Calibration Technician Training Programs | Addressed scarcity in electrodynamic and piezoelectric system maintenance constrains competitor service network expansion. |
Research Methodology
The analysis maps electromechanical, piezoelectric, pneumatic, and hydraulic vibrator sub-sectors, each validated through plant engineers, OEM procurement teams, aftermarket service heads, and rental network operators. Primary interviews with construction contractors in Germany, Japan, and China combined with secondary validation from MIIT efficiency filings, OSHA enforcement databases, and EU Machinery Directive implementation records. Bottom-up unit demand modeling and top-down value triangulation cross-checked against trade flow data and capital expenditure disclosures from integrated industrial manufacturers.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include drive technology, application severity, end-user procurement authority, and regional regulatory cluster. CAGRs derived from historical replacement cycle analysis, infrastructure investment trajectories, and safety mandate implementation timelines. Industry-specific forecast inputs encompass concrete batch plant utilization rates and pharmaceutical cleanroom capital deployment patterns.
Material uncertainties — rare-earth export restrictions, REACH substance restriction expansions, and carbon-border adjustment mechanism scope revisions — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement continuity and infrastructure investment sustainability. Revision becomes warranted when OSHA vibration threshold enforcement intensity or EU carbon-border adjustment coverage crosses thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Europe Air Separation Unit Market
Others
ASEAN Smart Homes Market
Others
Germany Smart Home Market
Others
Cat Food and Snacks Market
Others
IT Device Market
Others
Asia-Pacific Battery E-Commerce Market
Others
Cat Food Market
Others
Wearable Translator Market
Others
Connected Homes Market
Others
Fresh Pears Market
Others
Smart-Connected Power Plug Socket Market
Others
Magnesite Market
Others
Smart Home Gateways Market
Others
LED Packaging Market
Others
Fluorite Market
Others
Infant Positioning Aids Market