
 Europe Digital Experience Platform Market | 2026-2036
Europe Digital Experience Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Digital Experience Platform Market Intelligence
The capital-intensity divergence between hyperscaler-backed platforms and independent software vendors is bifurcating competitive dynamics across the European DXP landscape. Salesforce.com, Inc. leverages its Einstein AI layer and Commerce Cloud integration to anchor enterprise retail deployments in Northern Europe. SAP SE sustains deep ERP-DXP convergence that dominates manufacturing and BFSI verticals seeking unified customer and operational data. Adobe specializes in creative-to-experience workflows that control premium positioning among French luxury and German automotive brands.
A Digital Experience Platform constitutes an integrated software architecture that orchestrates content creation, customer data management, personalization engines, and analytics through API-first microservices and headless content delivery networks. Its primary commercial purpose is to enable organizations to compose, deploy, and optimize consistent digital interactions across web, mobile, and emerging touchpoints without re-platforming core infrastructure. Cloud-based and SaaS technology segments are capturing the fastest expansion as European enterprises retire on-premises legacy stacks to meet scalability and remote-work requirements. Content Management and Personalization application segments concentrate margin pools where real-time decisioning and AI-driven content variation command premium pricing from BFSI and retail end users.
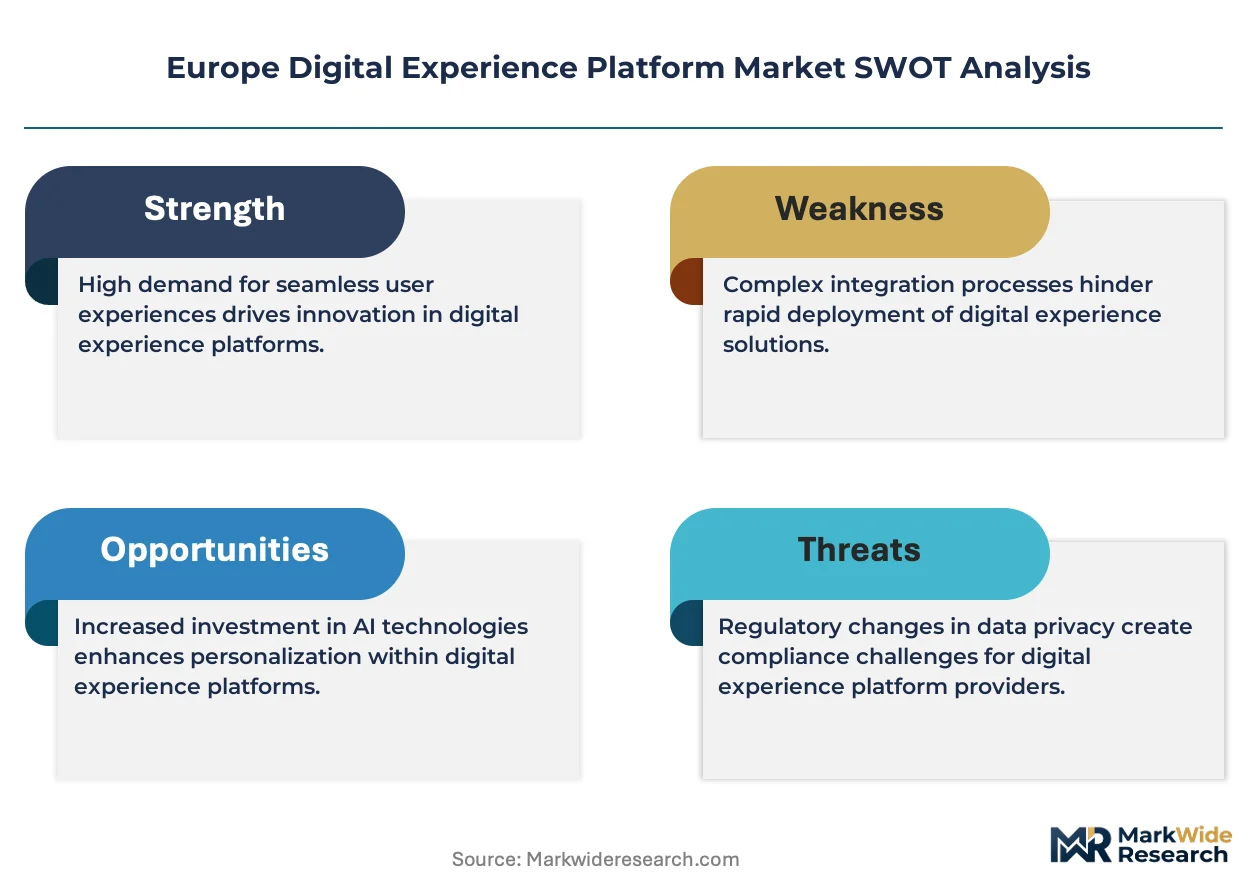
The EU AI Act, GDPR, and EMA guidelines for pharmaceutical digital engagement are shaping product roadmaps by mandating algorithmic transparency, explicit consent mechanisms, and audit-ready data lineage across DXP deployments. France's CNIL and Germany's BfDI are enforcing stricter cross-border data localization interpretations that complicate multi-tenant SaaS architectures and favor regionally hosted instances. Stakeholders must monitor how forthcoming EU Digital Identity framework specifications will force authentication and customer profile unification capabilities into core platform requirements.
Market Dynamics
The EU AI Act's algorithmic transparency mandates are forcing DXP vendors to rebuild personalization engines around explainable AI architectures, fundamentally altering R&D priorities and competitive differentiation across the European market.
Growth Catalysts
- GDPR consent-first architectures:Retail chains in Germany and France are replatforming customer data layers to capture granular opt-ins, creating replacement demand for compliant DXP stacks.
- Composable microservices convergence:Banking groups are unbundling monolithic suites into API-first components that enable real-time journey orchestration without vendor lock-in.
- Luxury vertical expansion:French haute couture houses are deploying headless content delivery networks to synchronize digital flagship stores with physical atelier experiences.
Market Restraints
- Cross-border data localization friction:France's CNIL and Germany's BfDI are enforcing stricter territorial interpretations that complicate multi-tenant SaaS architectures.
- Specialized talent scarcity:The shortage of engineers fluent in both MACH architecture and EU regulatory compliance is inflating implementation timelines.
- Legacy ERP integration costs:Manufacturing verticals face prohibitive capex to bridge SAP SE core systems with modern experience layers.
Strategic Opportunities
- Pharmaceutical digital engagement:EMA guidelines for audit-ready data lineage are creating demand for compliant DXP deployments in drug marketing and patient portals.
- EU Digital Identity framework pre-positioning:Vendors that embed authentication and profile unification capabilities will capture first-mover advantage when specifications finalize.
- Edge computing convergence:Retailers are piloting CDNs that process personalization at the network edge to reduce latency for in-store mobile experiences.
Industry Challenges
- Algorithmic bias audit complexity:BFSI deployers must demonstrate non-discrimination in credit and insurance recommendation engines under overlapping GDPR and EU AI Act requirements.
- Interoperability standardization gaps:The absence of unified API specifications between content management, customer data platforms, and analytics modules forces costly custom integration work.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Digital Experience Platform Market |
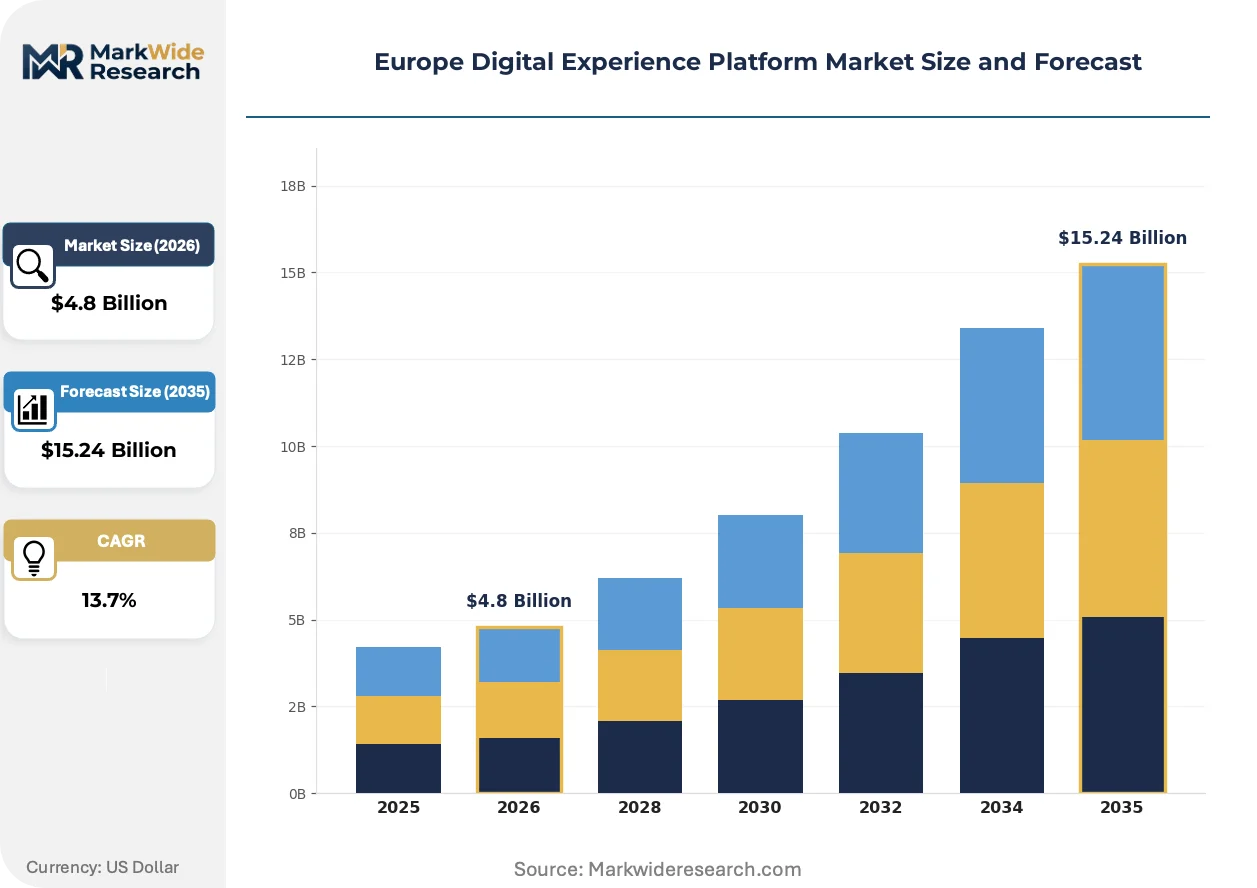
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Content Management, Customer Engagement, Personalization, Analytics Technology: Cloud-based, On-premises, SaaS, API Integration End User: Retail, BFSI, Healthcare, Education Service Type: Consulting, Managed Services, Support, Training |
| Companies Covered | Salesforce.com, Inc., IBM Corporation, SAP SE, Open Text Corporation, Acquia Inc., Microsoft Corporation, Adobe, Sitecore, Oracle Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Digital Experience Platform Market Strategic Shifts & Innovations
Headless architecture is dismantling traditional suite-based procurement patterns across European enterprises, with buyers prioritizing API modularity over bundled functionality. This structural shift is compressing vendor consolidation timelines and elevating specialist component providers.
Headless content management systems are supplanting coupled CMS-DXP suites by decoupling content repositories from presentation layers. German automotive brands and French luxury houses are adopting these architectures fastest, typically completing migrations within 18-month windows. The technology is supplanting legacy template-driven workflows and enabling channel-agnostic content deployment that compresses time-to-market for omnichannel campaigns.
The EU AI Act's risk-based classification system is mandating human oversight interfaces for high-stakes personalization algorithms. BFSI and healthcare deployers must now maintain audit trails for automated decisioning that affects credit, insurance, or patient outcomes. French banking groups are responding by embedding consent management platforms directly into customer journey orchestration layers.
Enterprise procurement patterns are fragmenting as IT and marketing stakeholders diverge on vendor selection criteria. Marketing teams prioritize creative workflow integration and real-time personalization speed, while IT demands API governance and security certification. This tension is most visible in the Nordics, where centralized procurement functions are losing authority to line-of-business budget holders.
Europe Digital Experience Platform Market Segmentation
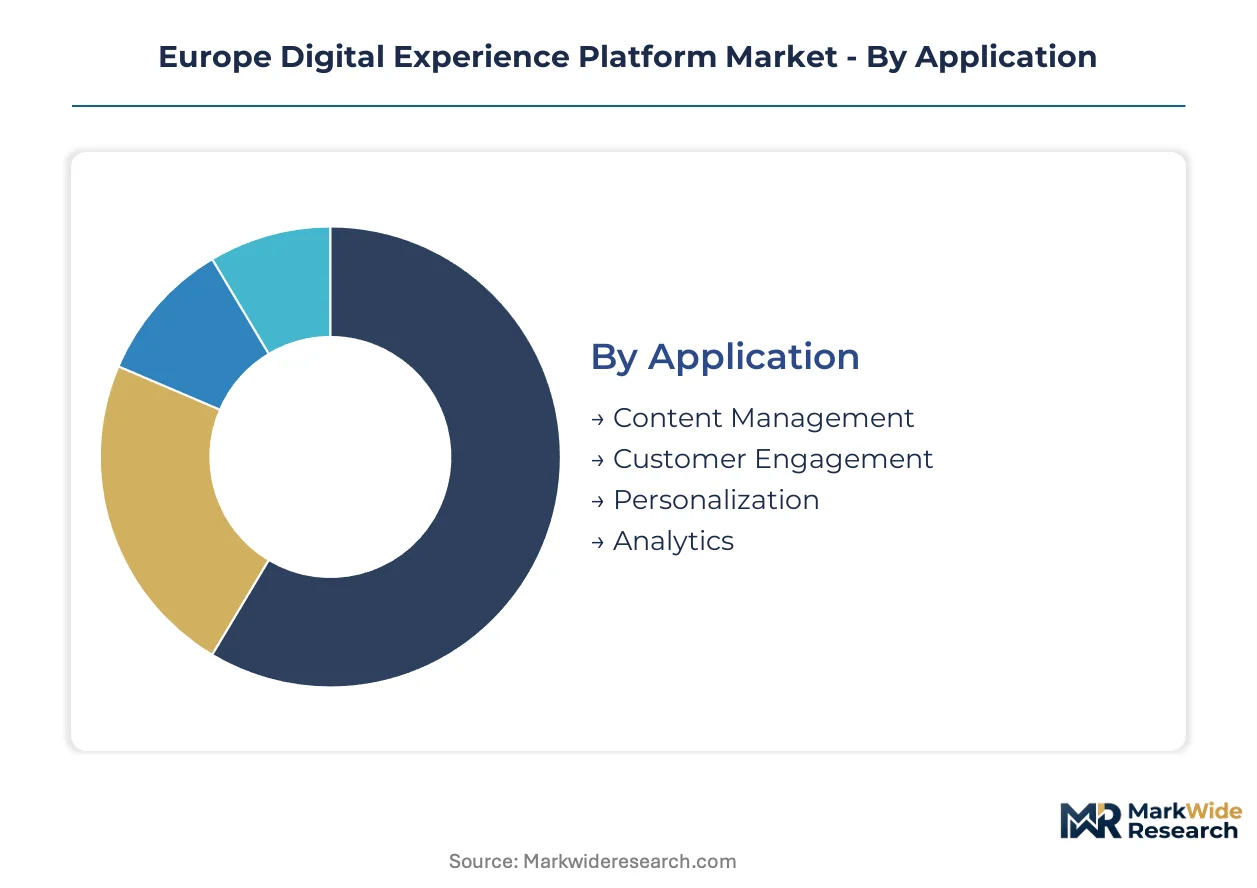
European DXP procurement patterns fragment sharply across deployment models and vertical compliance requirements. Understanding where margin pools concentrate within each dimension enables vendors to prioritize R&D and channel investments against regulatory and customer-type complexity.
Application:
Personalization and real-time decisioning engines command premium pricing multiples across French banking and German retail deployments.
- Personalization:AI-driven content variation engines that dynamically assemble customer-facing experiences based on behavioral signals and consent-managed profile data. French luxury houses and German automotive brands are concentrating procurement here to synchronize digital flagship stores with physical showrooms, though EU AI Act transparency mandates are forcing architectural rebuilds around explainable algorithms.
- Content Management:Headless repositories decoupled from presentation layers, enabling channel-agnostic deployment through API-first architectures. German retail chains are migrating fastest, typically completing 18-month transitions from legacy template-driven systems to compress omnichannel campaign time-to-market.
- Customer Engagement:Journey orchestration tools unifying touchpoint interactions across web, mobile, and in-store experiences.
- Analytics:Audit-ready data lineage modules supporting GDPR and EU AI Act compliance documentation.
Content Management holds installed capacity. Personalization is rotating up the share rankings.
Technology:
Cloud-native architectures are displacing on-premises estates as European enterprises prioritize scalability and remote-work enablement.
- Cloud-based:Scalable infrastructure delivering elastic compute and storage for variable traffic patterns without capital-intensive hardware procurement. French banking groups and German retail chains are concentrating demand here to meet CNIL and BfDI data localization requirements through regionally hosted instances.
- SaaS:Subscription-delivered platforms with embedded maintenance and automatic feature updates. Nordic enterprises are adopting fastest, driven by line-of-business budget holders prioritizing speed-to-deployment over IT-controlled on-premises governance.
- API Integration:Microservices connectivity enabling composable DXP assembly from best-of-breed components.
- On-premises:Legacy estates retained by manufacturing verticals facing prohibitive ERP bridge costs.
SaaS is climbing the fastest. On-premises retains defensive positions in regulated manufacturing.
End User:
BFSI and retail verticals are driving replacement demand as GDPR consent-first architectures force customer data layer replatforming.
- BFSI:Banking, financial services, and insurance deployers requiring audit trails for automated credit and insurance recommendation engines. French banking groups are embedding consent management platforms directly into journey orchestration layers to satisfy overlapping GDPR and EU AI Act non-discrimination requirements.
- Retail:Omnichannel merchants unifying web, mobile, and in-store experiences through headless content delivery. German and French retail chains are expanding personalization engine adoption to synchronize inventory visibility across touchpoints.
- Healthcare:Pharmaceutical and provider organizations navigating EMA guidelines for patient portal and drug marketing engagement.
- Education:Universities and corporate learning platforms deploying modular experience stacks.
BFSI holds installed capacity. Retail is rotating up the share rankings.
Service Type:
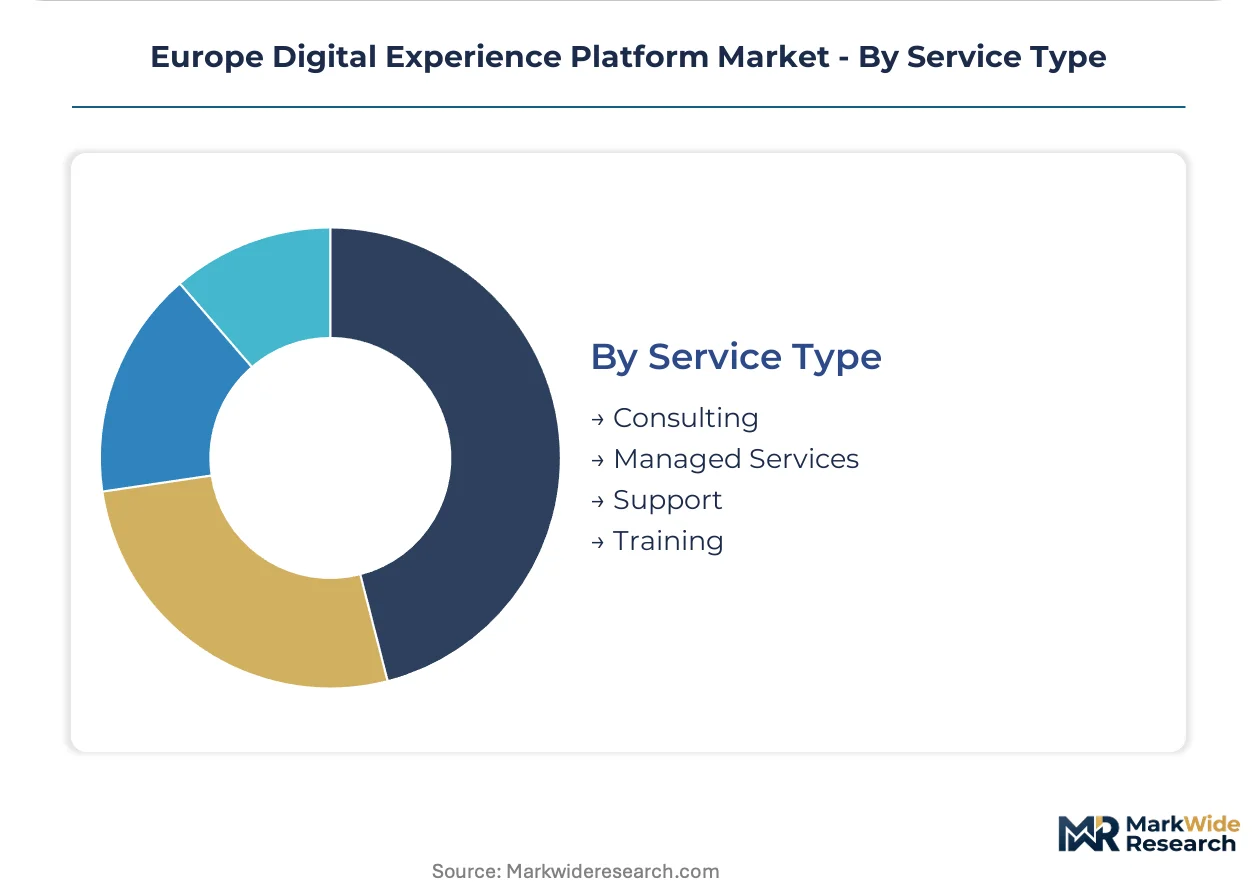
Managed services and specialized consulting are capturing expanding attach rates as MACH architecture and EU regulatory fluency scarcity inflates implementation complexity.
- Managed Services:Ongoing platform operation, security patching, and compliance monitoring outsourced to specialist providers. Demand concentrates among mid-market European enterprises lacking internal MACH architecture expertise.
- Consulting:Strategy and implementation advisory for composable DXP transformation and legacy ERP integration.
- Support:Technical issue resolution and platform health monitoring.
- Training:Capability building for marketing and IT stakeholders on API governance and consent management workflows.
Consulting holds installed capacity. Managed Services is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in French luxury and banking verticals where real-time personalization commands premium multiples, while German manufacturing adopters face legacy ERP integration costs that compress margins.
Germany
Automotive brands and retail chains drive headless CMS migrations to unify digital flagship stores with physical showrooms. BfDI data localization rulings complicate multi-tenant SaaS deployments and favor regionally hosted instances. Munich and Stuttgart clusters concentrate DXP engineering talent scarce in MACH architecture.
France
Luxury houses and banking groups deploy composable stacks for real-time customer journey orchestration. CNIL enforces stricter cross-border data interpretations than peer regulators. Paris anchors demand for consent-first personalization engines that embed explainable AI under EU AI Act mandates.
United Kingdom
BFSI verticals replatform customer data layers to capture granular opt-ins and satisfy post-Brexit regulatory divergence. Financial Conduct Authority guidelines on algorithmic transparency overlap with retained GDPR provisions. London's fintech corridor concentrates procurement for audit-ready analytics modules.
Netherlands
E-commerce platforms and logistics operators prioritize API-first microservices for omnichannel inventory visibility. Dutch Data Protection Authority interpretations on automated decisioning shape vendor selection criteria. Amsterdam's digital commerce cluster pilots edge-computing CDNs for in-store mobile personalization.
Sweden
Nordic enterprises accelerate SaaS adoption as line-of-business budget holders override centralized IT procurement. Swedish Authority for Privacy Protection rulings on consent granularity influence regional product roadmaps. Stockholm's enterprise software cluster concentrates demand for subscription-delivered platforms with embedded compliance monitoring.
Europe Digital Experience Platform Market Key Industry Players
Concentration sits with hyperscaler-backed platforms that leverage AI layers and cloud infrastructure to anchor enterprise retail deployments. The vendor base stratifies across three tiers: integrated suite providers with ERP convergence, creative-to-experience specialists, and API-first component vendors. Dominant competitive moves include M&A to acquire consent management capabilities and strategic partnerships to bridge legacy SAP estates with modern experience layers.
Within the integrated suite tier, Salesforce.com, Inc. and SAP SE exemplify divergent positioning strategies. Salesforce anchors Northern European retail through Einstein AI integration, while SAP sustains manufacturing and BFSI dominance through ERP-DXP convergence. Adobe occupies a premium positioning among French luxury and German automotive brands where creative workflow integration commands pricing multiples.
| Leading Market Players |
|---|
| Salesforce.com, Inc. |
| IBM Corporation |
| SAP SE |
| Open Text Corporation |
| Acquia Inc. |
| Microsoft Corporation |
| Adobe |
| Sitecore |
| Oracle Corporation |
| Others |
Cost & Logistics Intelligence
Eighteen-month implementation cycles for headless CMS migrations concentrate pricing power with vendors possessing MACH-certified engineering benches in Germany and France, while compressing margins for system integrators facing talent scarcity. This lead-time asymmetry rewards pre-built compliance modules that accelerate GDPR and EU AI Act certification timelines.
Pricing Analysis
Configured-to-order pricing for composable DXP stacks commands multiples over standardized SaaS tiers, with French luxury houses and German automotive brands absorbing premiums for real-time personalization engines. Subscription-based SaaS tiers dominate mid-market procurement, while project-based professional services attach rates inflate total contract values for ERP-DXP convergence in manufacturing verticals. Price differentiation hinges on explainable AI certification status and vertical-specific consent-management pre-configuration. Pricing pressure stems from hyperscaler-backed platforms bundling infrastructure credits with experience layer licenses. Mid-market retailers exhibit highest price sensitivity, while BFSI deployers prioritize audit-ready lineage over cost optimization.
Supply Chain Analysis
Inventory concentration among MACH-certified implementation partners in Munich, Paris, and Amsterdam creates lead-time vulnerability for enterprise deployments requiring EU AI Act-compliant architectures. Cloud infrastructure supply concentrates in Ireland, Germany, and the Netherlands, with hyperscaler regions anchoring elastic compute provisioning. Component dependencies span API gateway technologies, identity verification modules, and edge-computing nodes. Single-source vulnerability sits with specialized consent-management platforms certified for CNIL and BfDI interpretations. Distribution runs through systems integrator networks and direct hyperscaler marketplaces, with regional VARs capturing implementation attach rates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across deployment models and vertical compliance requirements creates niche opportunities for specialists unbundling monolithic suites. GDPR consent-first replatforming concentrates demand for modular components that legacy vendors cannot rapidly re-architect.
For Market Incumbents: Secure MACH-certified talent pools in Stuttgart and Paris engineering clusters to defend implementation timelines against boutique competitors. Acquire consent-management specialists with pre-built CNIL and BfDI compliance modules to neutralize regulatory differentiation. Vertical integration into edge-computing CDN infrastructure addresses latency requirements for in-store personalization pilots. For New Entrants and Emerging Players: Managed services gaps in mid-market manufacturing verticals offer white-space entry where SAP-DXP bridge costs deter hyperscaler incumbents. Target pharmaceutical deployers navigating EMA audit-ready lineage requirements with pre-validated data lineage modules. Pursue channel partnerships with Nordic line-of-business budget holders bypassing centralized IT procurement. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because composable architecture mandates will compress vendor counts as buyers prioritize API governance over point solutions. Acquisition targets include explainable AI layer specialists with EU AI Act risk-classification tooling. Watch for CNIL enforcement actions on cross-border data flows as inflection signal for regional hosting demand.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Firm | Consent-management vendors with CNIL pre-certification capture GDPR replacement cycles in French banking. |
| Strategic Partnership | Hyperscaler alliances with SAP integrators bridge manufacturing ERP estates to modern experience layers. |
| Product Launch | Human-in-the-loop interfaces for high-stakes personalization satisfy EU AI Act oversight mandates in BFSI. |
| Platform Integration | Embedded identity verification pre-positions vendors for EU Digital Identity framework specifications. |
| Geographic Expansion | Regionally hosted instances in Frankfurt and Paris address BfDI and CNIL data localization rulings. |
Research Approach
A standing panel of CTOs, IT procurement officers, platform engineers, and integration specialists provided ongoing calibration across primary interview programs. Secondary validation drew from SEC filings, hyperscaler capex disclosures, App Annie enterprise mobility data, and EU regulatory implementation notices. Bottom-up deployment sizing across cloud regions and top-down vendor revenue triangulation anchored value estimates.
Consistency checks against external benchmarks validated projections across the analysis window. Segmentation dimensions modeled include deployment model, organization size, vertical compliance complexity, integration architecture, and regional adoption pattern. CAGRs were derived from fitted growth curves incorporating GDPR replacement demand, EU AI Act implementation timelines, and composable procurement momentum.
Forecasts assume regulatory continuity in GDPR enforcement and EU AI Act risk-classification implementation; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Fluorite Market
Others
Mobile Computing Devices Market
Others
Palatants Market
Others
Global Application Testing Services Market
Others
Aluminium Clad Printed Circuit Board Market
Others
Global Hardware Acceleration Market
Others
Middle East and Africa Home Care Packaging Market
Others
Storm Surge Barriers Market
Others
Magnesite Market
Others
Photo Booth/Kiosk Market
Others
Global Digital Caliper Market
Others
Middle East Paper Making Machine Market
Others
Global Laser Defense Eyewear Market
Others
Industrial Computers Market
Others
Workbench Tanks Market
Others
8K Technology Market