
 Wood Recycling Market | 2026-2036
Wood Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
Wood Recycling Market Intelligence
Aftermarket service revenue from wood waste collection and sorting is fragmenting across regional operators and integrated waste platforms. Waste Management Inc. leverages its national hauling network to control inbound feedstock flows. REMONDIS SE & Co. KG anchors European collection density through municipally contracted sorting facilities. Republic Services Inc. competes on scale, operating transfer stations that consolidate urban construction debris for downstream processors.
Wood recycling encompasses the collection, processing, and reprocessing of post-consumer and post-industrial wood waste into reusable fiber, panel furnish, or energy feedstock, typically requiring moisture content below 20 percent and contaminant removal through magnetic separation and screening. Its primary commercial purpose is to displace virgin timber extraction while supplying raw material to panelboard manufacturers and biomass combustors. Reclaimed timber commands premium positioning in furniture and architectural applications where aesthetic grain patterns justify higher recovery costs. Wood chips dominate volume flows into particleboard and medium-density fiberboard production, where EGGER sustains manufacturing scale across Central European mill networks. Mechanical recycling leads technology adoption due to lower capital intensity versus chemical or thermal routes, though biological treatment is gaining traction for contaminated fractions.
The EPA regulates wood waste under solid waste and hazardous waste frameworks, particularly for treated lumber containing chromated copper arsenate, while the EU Green Deal and F-Gas Regulation indirectly shape demand by penalizing carbon-intensive virgin material use. China's MEE enforces import restrictions on contaminated wood waste, redirecting regional supply chains toward domestic collection infrastructure. Stakeholders must monitor regulatory divergence between jurisdictions to align certification protocols and avoid market access friction.
Market Dynamics
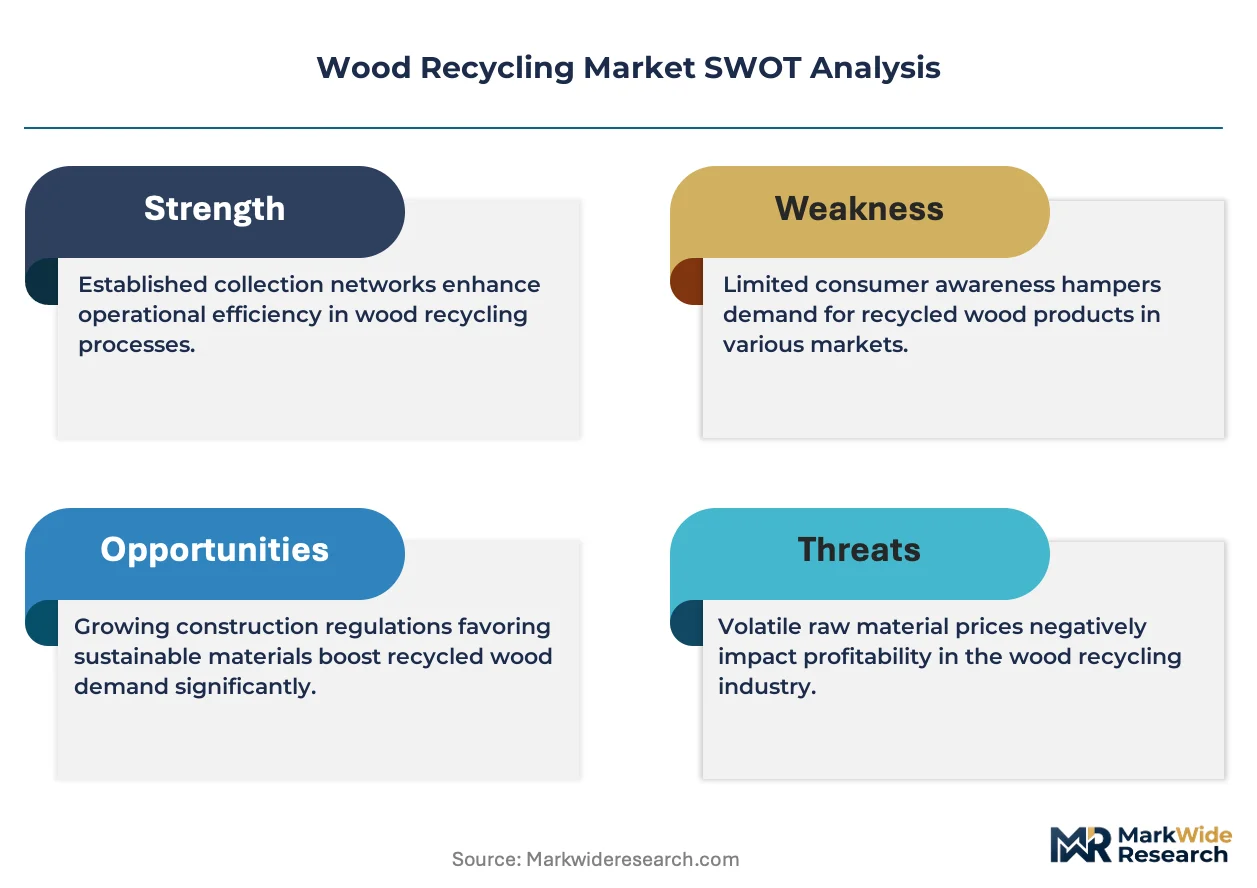
The EU Green Deal's circular economy mandates are compressing virgin timber demand while redirecting procurement toward certified recycled feedstock, forcing processors to reconfigure sorting infrastructure and contaminant detection protocols.
Growth Catalysts
- EU Green Deal mandates:Binding targets for recycled content in construction materials are pulling particleboard manufacturers toward reclaimed fiber sourcing.
- Biomass energy expansion:German power producers are scaling feedstock contracts for recycled wood to meet renewable energy quotas.
- China's green building codes:Reclaimed timber specifications in LEED-equivalent certifications are displacing virgin lumber in high-rise residential projects.
Market Restraints
- Chromated copper arsenate contamination:Treated lumber disposal under EPA hazardous waste rules fragments feedstock pools and elevates sorting costs.
- Regional supply concentration:Urban construction debris flows cluster in coastal Chinese provinces, leaving interior processors starved of volume.
- Moisture content thresholds:Sub-20 percent drying requirements for panelboard furnish demand capital-intensive kiln infrastructure that small operators cannot finance.
Strategic Opportunities
- India's informal sector formalization:The country's PLI scheme for waste-to-energy projects is opening collection infrastructure gaps that integrated platforms can fill.
- Architectural reclaimed timber:Premium furniture makers are contracting directly with demolition contractors for aesthetic-grade salvage, bypassing commodity processors.
- Cross-laminated timber adoption:Japanese construction codes now permit recycled fiber in CLT cores, creating a new high-value outlet for chipped waste.
Industry Challenges
- Magnetic separation technician scarcity:Operators struggle to hire personnel capable of calibrating contaminant removal systems for mixed C&D streams.
- Multi-jurisdiction certification timelines:Divergent EPA and EU Green Deal documentation requirements delay market access for exported panelboard.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wood Recycling Market |
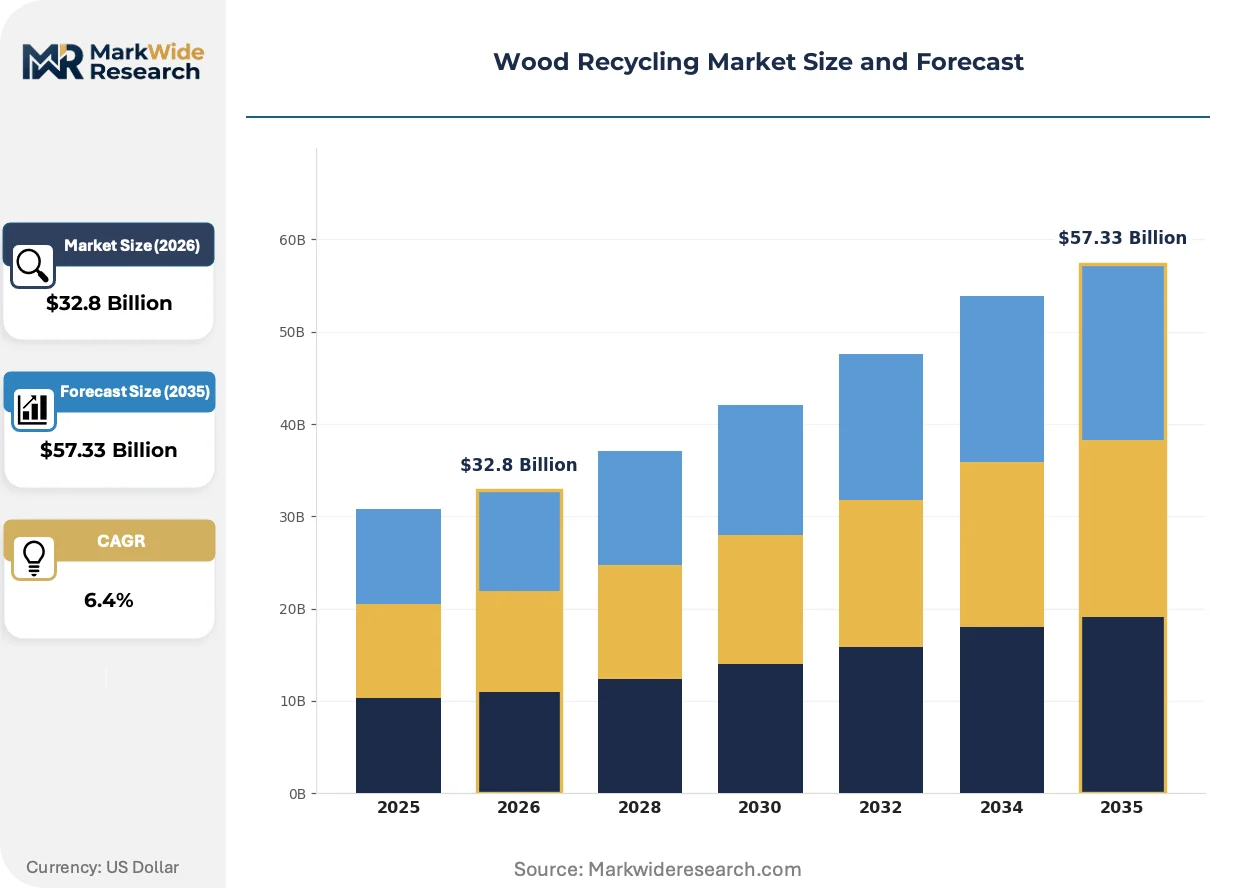
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $57.33 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reclaimed Timber, Wood Chips, Sawdust, Pulp End User: Furniture Manufacturers, Construction Companies, Paper Industry, Biomass Energy Producers Technology: Mechanical Recycling, Chemical Recycling, Thermal Recycling, Biological Treatment Application: Building Material, Wood Composite, Energy Production, Landscaping |
| Companies Covered | American Paper Recycling Corp., A W Jenkinson Woodwaste Ltd, Enva, Republic Services Inc., Waste Management Inc., REMONDIS SE & Co. KG, Rainier Wood Recyclers Inc., EGGER, Global Waste Recyclers Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wood Recycling Market Strategic Shifts & Innovations
Digital sorting infrastructure and policy-driven material substitution are compressing traditional recovery economics while opening premium positioning for traceable reclaimed supply chains.
Near-infrared spectroscopy paired with AI-driven contaminant detection is virtualizing manual sorting labor in high-volume C&D facilities. EGGER and similar panelboard producers are deploying these systems at intake gates to reduce downstream quality failures. The technology is virtualizing grade-based pricing by enabling real-time fiber characterization that separates architectural salvage from boiler fuel.
REACH chemical registration requirements are tightening restrictions on preservative-treated wood cross-border movement. EU member states are diverting former export volumes toward domestic energy recovery. German biomass combustors are absorbing displaced Baltic feedstock that previously flowed to Asian panel mills.
Building developers are embedding reclaimed content specifications directly into design-phase contracts rather than treating recycled fiber as a commodity substitute. Architecture firms in Copenhagen and Vancouver are requiring chain-of-custody documentation for timber salvage. This specification-led procurement is concentrating volume with certified demolition contractors who can guarantee provenance.
Wood Recycling Market Segmentation
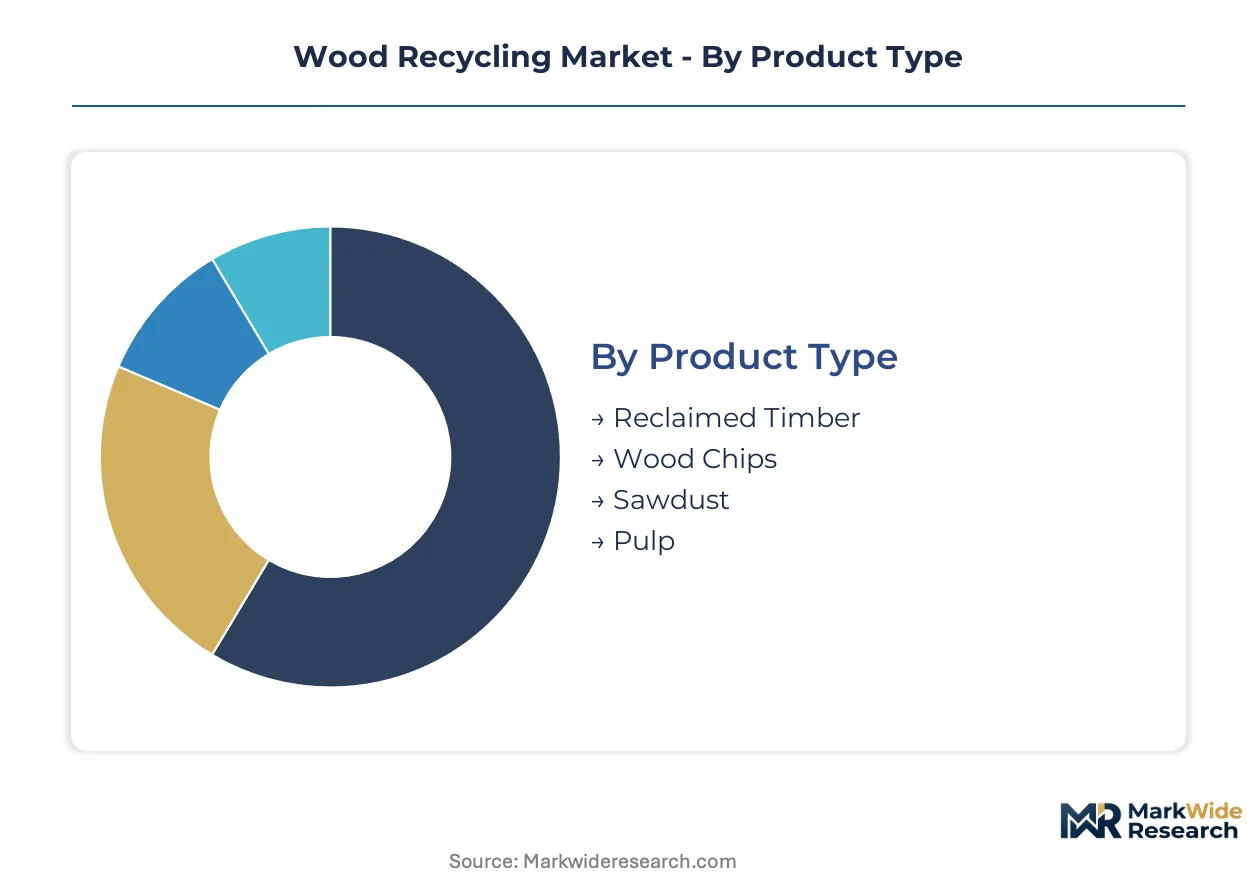
Segmentation in wood recycling separates commodity-grade flows from premium salvage streams, determining which recovery economics justify capital deployment. Each dimension—product form, end-use destination, processing technology, and final application—carries distinct margin profiles and regulatory exposure that reshape procurement priorities across the value chain.
Product Type:
Mature commodity grades dominate volume throughput while emerging specialty categories command price premiums through scarcity and certification requirements.
- Reclaimed Timber:Structural dimensional lumber and architectural-grade boards salvaged from demolition sites, typically graded for visual character and load-bearing integrity. Copenhagen and Vancouver developers now mandate chain-of-custody documentation for high-rise residential projects, compressing supply access to certified demolition contractors.
- Wood Chips:Mechanically reduced fiber from post-industrial and post-consumer sources, screened to uniform size for panelboard furnish. EGGER's Central European mill networks absorb the majority of available volume, though moisture content thresholds below 20 percent strain small operator economics.
- Sawdust:Fine particulate waste from primary milling and secondary manufacturing, often contaminated with adhesives or finishes. Paper industry pulping operations and biomass combustors compete for limited supply in Germany's industrial clusters.
- Pulp:Chemically or mechanically defibered material suitable for paper manufacturing and specialized composite feedstock. Chinese import restrictions under MEE enforcement redirect former export volumes toward domestic tissue and packaging producers.
Wood chips handle the majority of throughput; reclaimed timber is the fastest mover on share.
End User:
Customer concentration varies sharply by contract structure, with municipal energy off-takers offering volume certainty and furniture makers providing margin expansion through specification-led procurement.
- Furniture Manufacturers:Premium seating and casegoods producers sourcing aesthetic-grade reclaimed timber directly from demolition contractors. Danish and Canadian design houses now bypass commodity processors to secure provenance-guaranteed salvage with documented chain-of-custody.
- Construction Companies:General contractors and developers embedding recycled content specifications into design-phase contracts under EU Green Deal mandates. Cross-laminated timber adoption in Japanese building codes opens new structural applications for chipped waste.
- Paper Industry:Tissue and packaging mills consuming mechanically pulped fiber and sawdust residues. Domestic Chinese producers absorb redirected volumes previously exported under now-restricted trade flows.
- Biomass Energy Producers:German power generators scaling feedstock contracts to meet renewable energy quotas, absorbing Baltic-sourced material displaced from Asian panel mills by REACH chemical registration constraints.
Biomass energy producers anchor volume demand; furniture manufacturers deliver the steepest expansion trajectory through premium positioning.
Technology:
Capital intensity and contamination tolerance divide the technology landscape, with mechanical routes achieving scale and biological methods gaining traction for hazardous fractions.
- Mechanical Recycling:Chipping, shredding, and screening operations that reduce wood waste to specified particle sizes without chemical transformation. Near-infrared spectroscopy paired with AI-driven detection is virtualizing manual sorting labor in high-volume C&D facilities across Germany.
- Chemical Recycling:Solvent-based or hydrolytic processes that extract cellulose from contaminated or composite materials. Higher capital requirements and regulatory complexity limit deployment to integrated chemical processors.
- Thermal Recycling:Pyrolysis and gasification converting wood waste to syngas, biochar, or liquid fuels. Energy recovery applications dominate where material quality fails panelboard specifications.
- Biological Treatment:Composting and anaerobic digestion for contaminated fractions, particularly preservative-treated lumber restricted from conventional recycling streams. Gaining regulatory support for hazardous waste diversion in EU member states.
Mechanical recycling commands installed capacity; biological treatment is gaining share fastest through regulatory pressure on treated wood disposal.
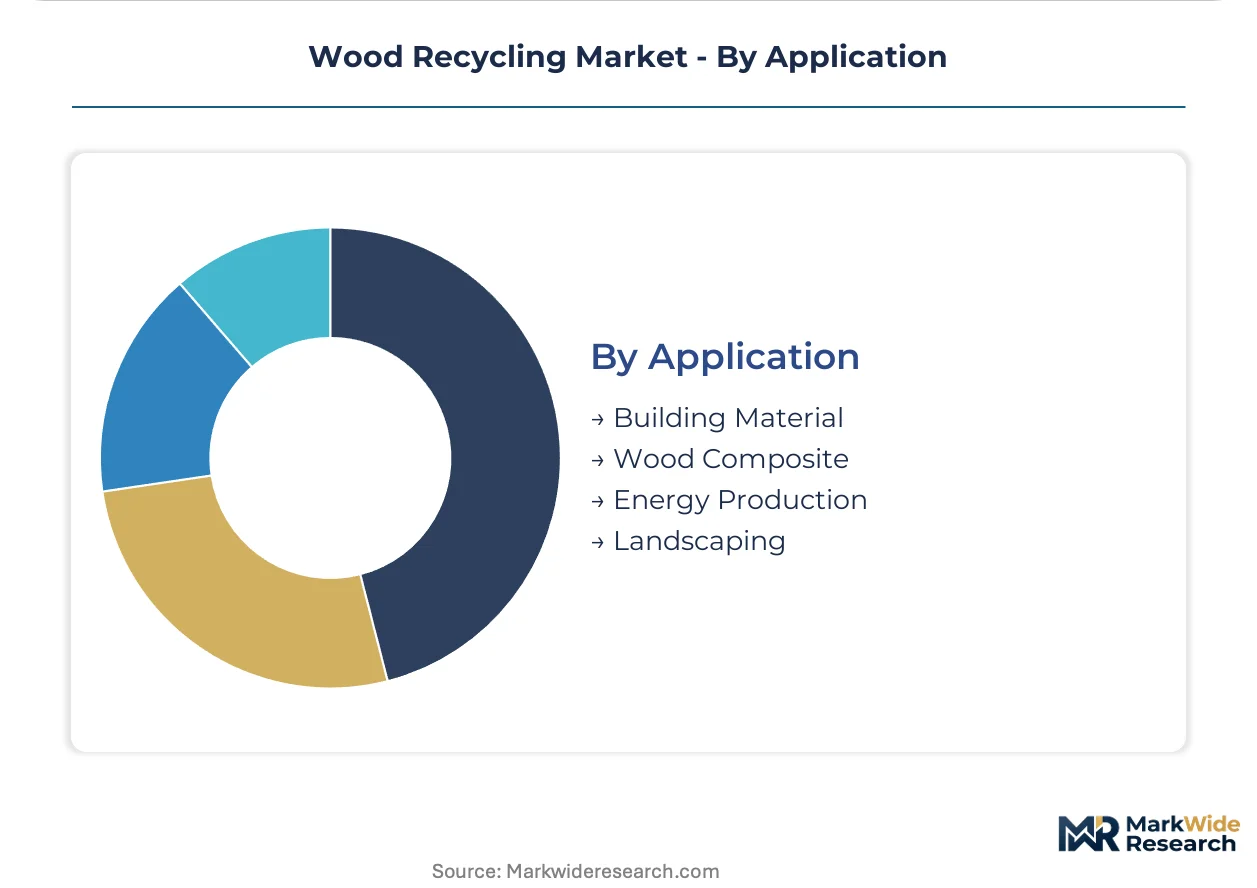
Application:
End-market pricing stratifies by performance requirements, with structural building materials and engineered composites outperforming bulk energy applications on margin.
- Building Material:Direct reuse of dimensional lumber and structural panels in construction, subject to grading standards and code compliance. Japanese CLT core specifications now permit recycled fiber, creating high-value outlet demand.
- Wood Composite:Particleboard, MDF, and engineered lumber incorporating recycled fiber as primary furnish. EGGER and similar producers deploy real-time fiber characterization to separate architectural salvage from boiler fuel at intake gates.
- Energy Production:Combustion and gasification for heat and power generation, typically absorbing lower-grade material rejected by panel manufacturers. German biomass plants absorb displaced Baltic feedstock following REACH restrictions.
- Landscaping:Mulch, erosion control, and soil amendment applications utilizing coarse chips and bark residues. Municipal procurement favors local supply to minimize hauling costs and carbon footprint.
Wood composite manufacturing processes the greatest tonnage; building material applications are climbing the fastest on specification-led premium capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across regions. German biomass operators absorb recycled wood at regulated premiums under renewable energy quotas. Chinese panelboard mills drive the hardest bargain on moisture-content penalties, squeezing small collector margins.
Germany
Biomass energy producers dominate procurement under the EU Green Deal's renewable energy mandates. The country's national environmental regulator enforces strict contaminant thresholds for treated lumber disposal. Industrial clusters around Hamburg and the Ruhr concentrate sorting infrastructure serving EGGER's Central European mill networks.
China
Construction sector demand for reclaimed timber in green building projects absorbs premium salvage grades. The Ministry of Ecology and Environment restricts contaminated wood waste imports, redirecting supply chains toward domestic collection. Coastal provinces Jiangsu and Zhejiang cluster particleboard manufacturing capacity that competes aggressively on fiber pricing.
United States
Integrated waste platforms leverage national hauling networks to control inbound construction debris flows. The EPA regulates chromated copper arsenate-treated lumber under hazardous waste frameworks, fragmenting feedstock pools. Urban corridors in Texas and the Southeast concentrate transfer station capacity consolidating material for downstream processors.
India
The PLI scheme for waste-to-energy projects is opening collection infrastructure gaps that integrated platforms can fill. The Bureau of Indian Standards is developing certification protocols for recycled construction materials. Maharashtra and Gujarat industrial belts concentrate emerging particleboard manufacturing seeking formalized fiber supply.
Japan
Cross-laminated timber adoption in revised construction codes creates structural demand for recycled fiber cores. METI guidelines promote material circularity in building sector procurement. The Kansai region around Osaka anchors demolition salvage networks supplying architectural reclaimed timber to furniture makers.
Wood Recycling Market Key Industry Players
Integrated waste management conglomerates and specialized wood fiber processors split the market along capital intensity lines. National hauling networks confer feedstock control advantages that regional sorting specialists cannot replicate. Three archetypes dominate: vertically integrated waste platforms with municipal contracts, panelboard manufacturers with captive recycling operations, and independent demolition salvage brokers serving premium architectural markets. Competitive moves concentrate on geographic expansion through municipal contract bidding and technology licensing for automated contaminant detection.
Among North American integrated waste platforms, Waste Management Inc. and Republic Services Inc. exemplify the scale-driven archetype controlling urban construction debris flows through transfer station networks. REMONDIS SE & Co. KG anchors the European municipal-contract tier with density advantages in German-speaking sorting infrastructure. These three occupy positions that smaller regional operators cannot challenge on collection radius or capital deployment.
| Leading Market Players |
|---|
| American Paper Recycling Corp. |
| A W Jenkinson Woodwaste Ltd |
| Enva |
| Republic Services Inc. |
| Waste Management Inc. |
| REMONDIS SE & Co. KG |
| Rainier Wood Recyclers Inc. |
| EGGER |
| Global Waste Recyclers Ltd |
| Others |
Cost & Logistics Intelligence
Overcapacity in China's coastal particleboard mills is compressing fiber procurement budgets while elevating quality premiums for certified reclaimed timber in Copenhagen and Vancouver green building projects. This utilization gap between commodity oversupply and premium scarcity is reshaping supplier investment priorities across the value chain.
Pricing Analysis
Aftermarket service revenue from collection logistics and contaminant removal contracts drives lifetime value more than raw material sales. Three-tier pricing structure across premium architectural salvage, standard panelboard furnish, and economy biomass feedstock segments the market. Price differentiation centers on chain-of-custody certification and moisture content guarantees. Cost compression in standard-grade chips is intensifying because Chinese mills enforce sub-20 percent moisture penalties that small collectors cannot absorb. Biomass energy producers exhibit lowest price sensitivity due to regulated renewable energy quota premiums.
Supply Chain Analysis
REACH chemical registration restrictions on preservative-treated wood cross-border movement are fragmenting Baltic-to-Asian feedstock flows. Supply concentrates in Germany, China, and the United States as primary collection and processing hubs. Raw material flows draw from urban construction debris, post-industrial milling residues, and demolition salvage. Single-source vulnerability runs through municipally contracted sorting facilities in Hamburg and Ruhr industrial clusters. Distribution runs through integrated waste platforms with national hauling networks consolidating material for downstream panelboard and energy recovery processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Collection and sorting service contracts are expanding faster than commodity fiber sales, creating attach-rate opportunities for operators who control inbound logistics infrastructure.
For Market Incumbents: Insulate feedstock access by deepening municipal contract density in German-speaking industrial clusters and investing in AI-driven contaminant detection to defend against regional sorting specialists. Secure backward integration into demolition contractor networks to lock architectural-grade salvage flows before competitors reach job sites. For New Entrants and Emerging Players: Pursue India's PLI scheme waste-to-energy corridors where formalized collection infrastructure remains underdeveloped. Target Maharashtra and Gujarat industrial belts seeking certified fiber supply for emerging particleboard capacity. Lead with technology licensing partnerships for near-infrared spectroscopy sorting rather than capital-heavy mill construction. For Investors and Strategic Acquirers: Capital is best deployed toward demolition salvage brokers with documented chain-of-custody capabilities and direct relationships with Copenhagen and Vancouver architecture firms. Long-term viability rests on specification-led procurement becoming standard in green building codes. Watch Japanese cross-laminated timber adoption rates as the inflection signal for structural-grade recycled fiber demand expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Contaminant Detection Deployment | Near-infrared spectroscopy paired with AI virtualizes manual sorting labor in high-volume C&D facilities across Germany. |
| Demolition Contractor Network Integration | Direct salvage procurement bypasses commodity processors to secure provenance-guaranteed architectural timber for premium furniture. |
| Municipal Contract Density Expansion | REMONDIS-style sorting facility anchoring controls inbound construction debris flows before competitors reach urban material. |
| Cross-Laminated Timber Certification Investment | METI-compliant recycled fiber cores open structural applications in Japanese building codes previously restricted to virgin lumber. |
| Biomass Energy Offtake Agreement Structuring | Long-term feedstock contracts with German power generators under EU Green Deal renewable energy quotas stabilize volume. |
Research Approach
The analysis maps reclaimed timber, wood chips, sawdust, and pulp sub-sectors, each validated through demolition contractors, panelboard procurement directors, biomass plant fuel managers, and municipal waste officers. Primary interviews with these stakeholders combined with secondary validation from EPA hazardous waste filings, EU Green Deal implementation reports, China MEE import restriction notices, and customs trade data. Bottom-up fiber flow modeling and top-down market sizing triangulate volume estimates across the projection horizon.
Assumptions held fixed include EU Green Deal binding targets and China MEE enforcement continuity, while biomass energy quota expansion rates and CLT code adoption timelines varied across scenarios. Segmentation dimensions modeled encompass product form, end-use destination, processing technology, and application category. CAGRs derive from fiber demand elasticity against virgin timber pricing and regulatory substitution mandates. Forecast inputs incorporate kiln drying capacity deployment and magnetic separation technician availability constraints.
Sensitivities concentrate around REACH chemical registration enforcement intensity and chromated copper arsenate disposal rule revisions. Forecasts reflect these documented assumptions while acknowledging that regulatory divergence between EPA and EU jurisdictions could accelerate or delay certification protocol alignment. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Construction Waste Management Market
Waste Management & Pollution Control
US Medical Waste Management Market
Waste Management & Pollution Control
Asia-Pacific Municipal Solid Waste Management Market
Waste Management & Pollution Control
India E-Waste Management Market
Waste Management & Pollution Control
Radioactive Waste Management System Market
Waste Management & Pollution Control
GCC Pneumatic Waste Management System Market
Waste Management & Pollution Control
China Waste Management Market
Waste Management & Pollution Control
Europe Industrial Waste Management Market
Waste Management & Pollution Control
Incinerator Market
Waste Management & Pollution Control
United States Trash Bags Market
Waste Management & Pollution Control
North America Solid Waste Management Market
Waste Management & Pollution Control
India Waste-To-Energy Market
Waste Management & Pollution Control
Europe Waste Management Market
Waste Management & Pollution Control
Global Smart Trash Bin Market
Waste Management & Pollution Control
India Recycling Market
Waste Management & Pollution Control
North America Municipal Solid Waste Management Market