
 Europe Biochar Market | 2026-2036
Europe Biochar Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Biochar Market Foresight
Agricultural soil amendment is repositioning as the dominant end-use vertical, pulling investment away from legacy bioenergy applications. PYREG GmbH leverages its continuous pyrolysis technology leadership to anchor premium supply contracts with German vineyard cooperatives. NOVOCARBO GmbH competes through integrated carbon removal services that bundle biochar production with CO2 credit verification. Carbofex Ltd specializes in Nordic wood waste feedstock processing, occupying a defensible niche in Scandinavia's circular biomass economy.
Biochar is a carbon-rich solid produced by heating organic feedstock in oxygen-limited conditions, typically achieving fixed carbon content above 70 percent and surface areas between 200 and 500 square meters per gram. Its primary commercial purpose centers on soil amendment for nutrient retention, pH buffering, and long-term carbon sequestration in agricultural systems. Pyrolysis-based production dominates European manufacturing due to mature reactor engineering and favorable energy coproduct economics. Agricultural residues as feedstock are gaining fastest among input categories, driven by straw and manure availability near arable zones. Environmental remediation applications for soil decontamination represent a concentrated margin pool where certified biochar commands price premiums over commodity grades.
The EU Green Deal, the Carbon Border Adjustment Mechanism, and ECHA's REACH framework collectively mandate emissions disclosure and restrict contaminant thresholds in soil inputs, directly shaping product certification requirements and market access conditions for biochar suppliers. Germany's Federal Environment Agency and France's ANSM enforce national implementation rules that exceed baseline EU standards, creating a two-tier compliance landscape. Stakeholders must monitor evolving carbon credit methodologies under the EU Emissions Trading System and national soil protection laws to anticipate which certification protocols will govern premium market segments.
Market Dynamics
Agricultural soil amendment adoption is accelerating across European farms as the EU Green Deal and Carbon Border Adjustment Mechanism tighten emissions accountability for land-use sectors. Pyrolysis facility buildouts in Germany and expanding biochar certification schemes are redrawing competitive boundaries between commodity and premium supply tiers.
Growth Catalysts
- EU Green Deal carbon accounting mandates:Land-use sector disclosure requirements under the EU Green Deal are forcing agricultural cooperatives to document soil carbon sequestration, creating procurement pull for certified biochar.
- Pyrolysis reactor engineering maturation:Continuous pyrolysis systems now achieve thermal efficiency above 75 percent, cutting unit production costs and enabling scale-up near straw and manure collection points.
- German vineyard cooperative demand concentration:Vineyard soil amendment contracts in Germany's Rhineland-Palatinate and Baden-Württemberg regions are anchoring premium pricing for EBC-certified biochar.
Market Restraints
- Feedstock cost volatility:Agricultural residue prices fluctuate with grain harvest cycles and competing biogas plant demand, compressing margins for pyrolysis operators without captive supply.
- Scandinavian supply concentration:Nordic wood waste processors dominate high-grade feedstock access, limiting continental European producers to lower-carbon-content agricultural residues.
- ECHA REACH contaminant thresholds:Polycyclic aromatic hydrocarbon limits under REACH create compliance friction for producers using mixed municipal waste streams.
Strategic Opportunities
- France ANSM soil protection enforcement:France's national implementation of EU soil protection laws exceeds baseline standards, creating a premium certification tier that commands price separation from commodity grades.
- Environmental remediation application expansion:Soil decontamination projects for heavy metal and hydrocarbon remediation represent a concentrated margin pool where certified biochar achieves significant price premiums.
- Carbon credit methodology convergence:Integration between EU Emissions Trading System carbon removal verification and national soil amendment subsidies is bundling revenue streams for integrated producers.
Industry Challenges
- EBC certification timeline compression:European Biochar Certificate auditing cycles stretch 8-14 months, delaying market access for new production facilities and tying up working capital.
- Pyrolysis engineering talent scarcity:Reactor design and thermal process optimization expertise concentrates among German and Austrian engineering consultancies, limiting facility replication speed.
- Legacy soil amendment distributor integration:Fertilizer and lime distribution networks resist biochar inclusion due to incompatible handling equipment and lower commission structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Biochar Market |
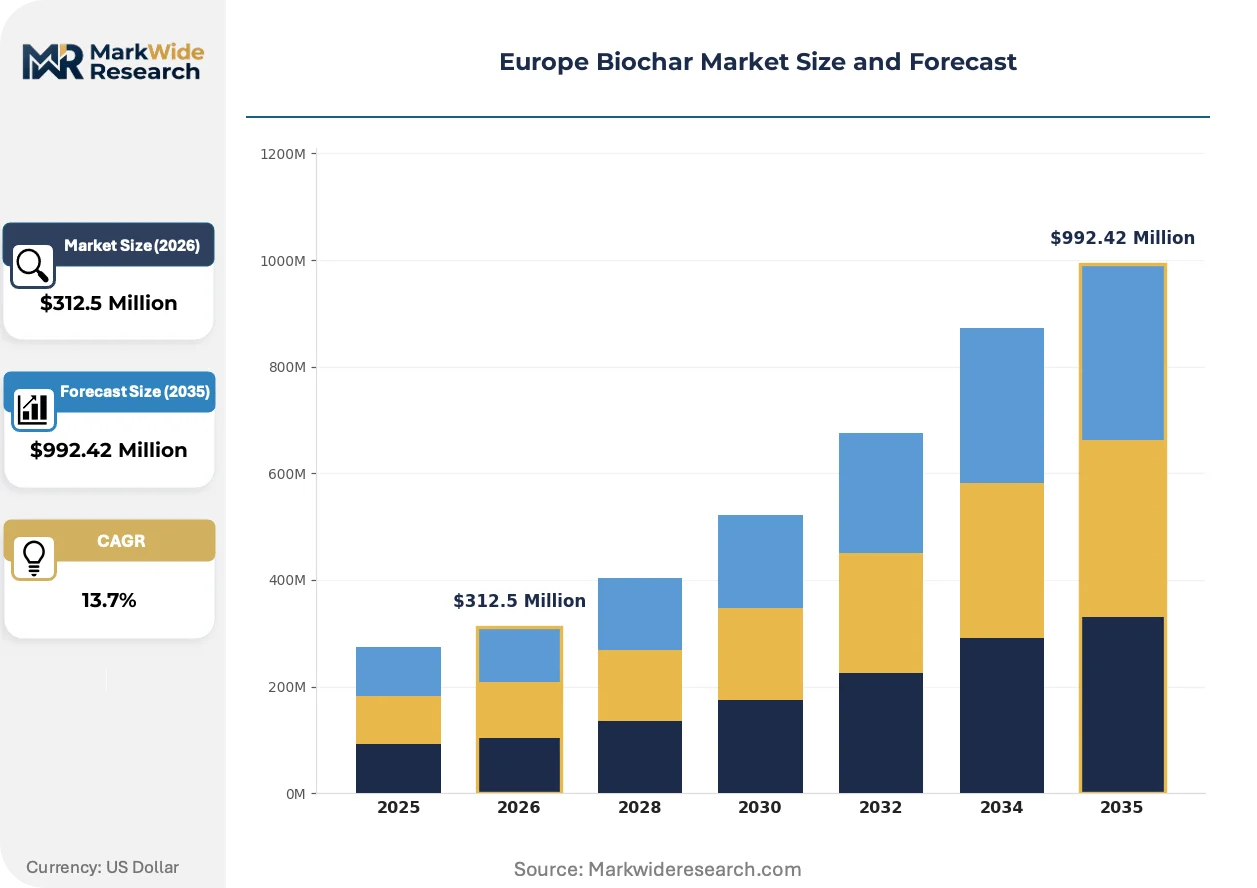
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $992.42 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biochar for Agriculture, Bioenergy Applications, Environmental Remediation, Construction Materials Feedstock Type: Wood Waste, Agricultural Residues, Municipal Solid Waste, Energy Crops Technology: Pirolysis, Gasification, Hydrothermal Carbonization, Torrefaction End Use: Soil Amendment, Carbon Sequestration, Fertilizer Substitute, Water Treatment |
| Companies Covered | PYREG GmbH, NOVOCARBO GmbH, Carbofex Ltd, Sonnenerde GmbH, Airex Energy, Carbonis GmbH & Co KG, Circular Carbon GmbH, Carbon Gold Ltd, Envigas AB, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Biochar Market Shifts & Advancements
Continuous pyrolysis reactor technology is consolidating market share as energy coproduct economics improve. Regulatory frameworks under the EU Green Deal and national soil protection laws are reshaping certification requirements. Buyer procurement patterns are pivoting toward integrated carbon removal service contracts rather than commodity biochar transactions.
Continuous pyrolysis reactor systems are consolidating competitive positioning in European manufacturing. These systems achieve steady-state thermal conversion with syngas energy recovery, cutting parasitic energy losses below 15 percent. German vineyard cooperatives and Dutch greenhouse operators are adopting continuous systems exclusively for premium soil amendment contracts. The technology is consolidating supply tiers by compressing batch reactor economics and forcing intermittent producers into feedstock supply roles.
France's ANSM soil protection enforcement is tightening contaminant thresholds for soil inputs beyond ECHA REACH baselines. Industrial consequence includes mandatory third-party testing for polycyclic aromatic hydrocarbons and heavy metals in all commercial biochar. German Federal Environment Agency implementation rules are following this pattern, creating a two-tier compliance landscape where premium market access requires dual certification.
Carbon credit verification is bundling with biochar procurement in Dutch and German agricultural cooperatives. Buyers now contract for tonnes of CO2 removal verified under EU Emissions Trading System methodologies, with biochar delivery as the fulfillment mechanism. This displacement of commodity spot purchasing concentrates contract volumes with integrated producers possessing in-house verification capabilities. The shift is most visible in Germany's Rhine-Ruhr greenhouse cluster and the Netherlands' Venlo horticulture zone.
Europe Biochar Market Segmentation
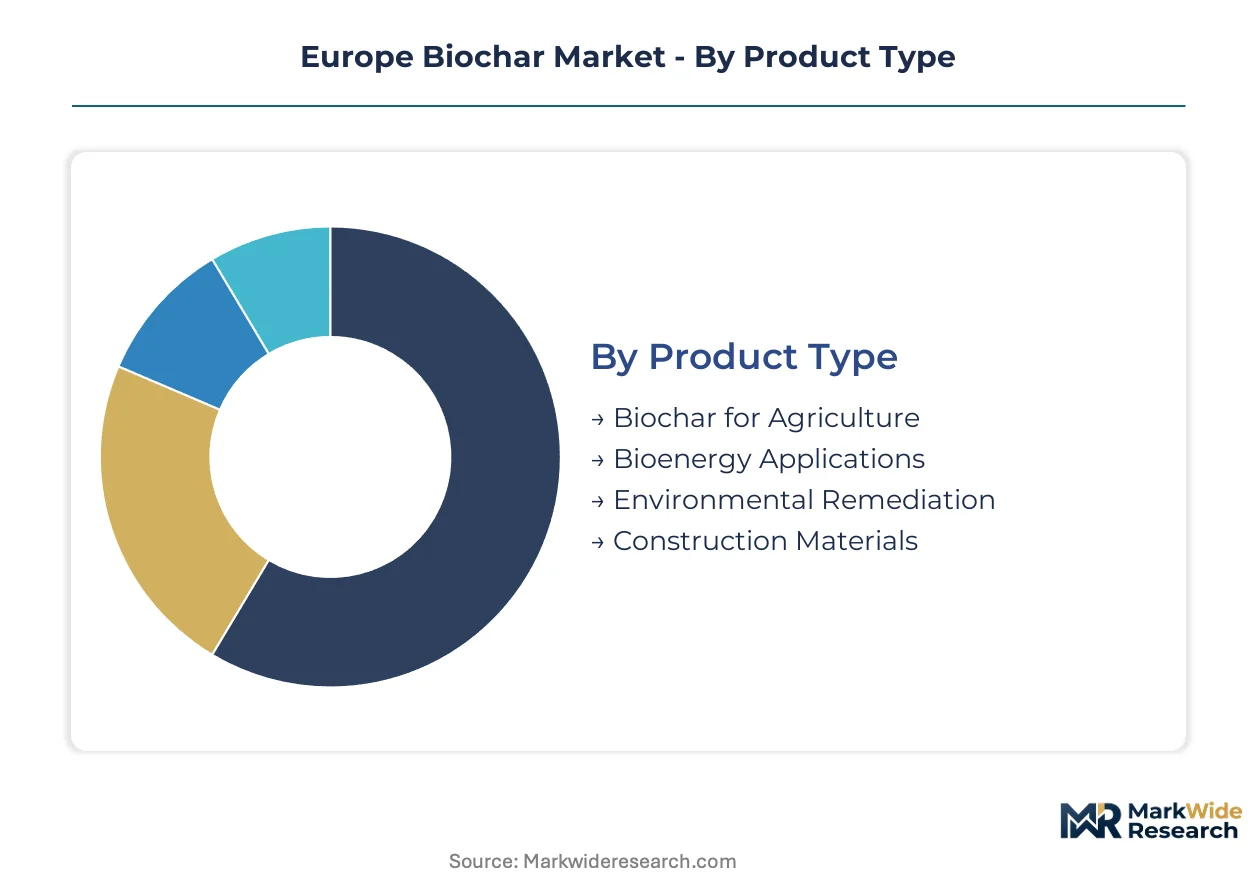
Segmentation in the Europe Biochar Market reveals how production technology choices and feedstock sourcing strategies determine competitive positioning. Buyers select product grades based on carbon content thresholds, contaminant compliance, and bundled carbon credit verification services.
Product Type:
Upgrade cycles in European biochar procurement favor certified grades over commodity alternatives, with EBC certification becoming a baseline requirement for premium contracts.
- Biochar for Agriculture:Fixed carbon content above 70 percent and surface areas between 200 and 500 square meters per gram define specification compliance. Vineyard cooperatives in Germany's Rhineland-Palatinate region anchor demand for EBC-certified agricultural grades under EU Green Deal carbon accounting mandates.
- Environmental Remediation:Heavy metal and hydrocarbon binding capacity drives specification requirements for decontamination projects. Soil remediation contractors in France pay significant premiums for certified biochar exceeding ANSM contaminant thresholds.
- Bioenergy Applications:Syngas coproduct recovery dominates value capture in combined heat and power installations.
- Construction Materials:Lightweight aggregate substitutes in concrete formulations represent an emerging specification tier.
Biochar for Agriculture sits at the top of the volume ranking, with Environmental Remediation climbing the fastest.
Feedstock Type:
Cost tier differentiation separates producers with captive residue supply from those exposed to spot market volatility.
- Agricultural Residues:Straw and manure availability near arable zones enables distributed pyrolysis deployment. German and French farm cooperatives secure long-term residue supply contracts to hedge against competing biogas plant demand.
- Wood Waste:Nordic processors dominate high-grade feedstock access with superior carbon content. Scandinavian circular biomass economies limit continental European producers to lower-carbon-content alternatives.
- Municipal Solid Waste:ECHA REACH polycyclic aromatic hydrocarbon limits create compliance friction for mixed waste stream processors.
- Energy Crops:Dedicated cultivation for pyrolysis feedstock remains marginal due to land-use competition with food production.
Agricultural Residues command the greatest production volume, while Wood Waste delivers the steepest margin expansion trajectory.
Technology:
Application requirements dictate reactor selection, with continuous systems displacing batch configurations in premium supply tiers.
- Pirolysis:Continuous reactor systems achieve thermal efficiency above 75 percent with syngas energy recovery below 15 percent parasitic losses. Dutch greenhouse operators in the Venlo horticulture zone specify continuous pyrolysis exclusively for carbon removal service contracts.
- Gasification:Higher temperature operation produces syngas-dominant output with limited biochar yield. Industrial cogeneration facilities in Germany's Rhine-Ruhr cluster favor gasification for energy coproduct maximization.
- Hydrothermal Carbonization:Wet feedstock processing enables manure and sewage sludge conversion without predrying.
- Torrefaction:Mild thermal treatment produces biocarbon for combustion applications rather than soil amendment grades.
Pirolysis holds the dominant installed base, with Gasification gaining share fastest in combined energy-carbon service configurations.
End Use:
Customer type stratification separates agricultural cooperatives procuring commodity volumes from industrial buyers purchasing verified carbon removal.
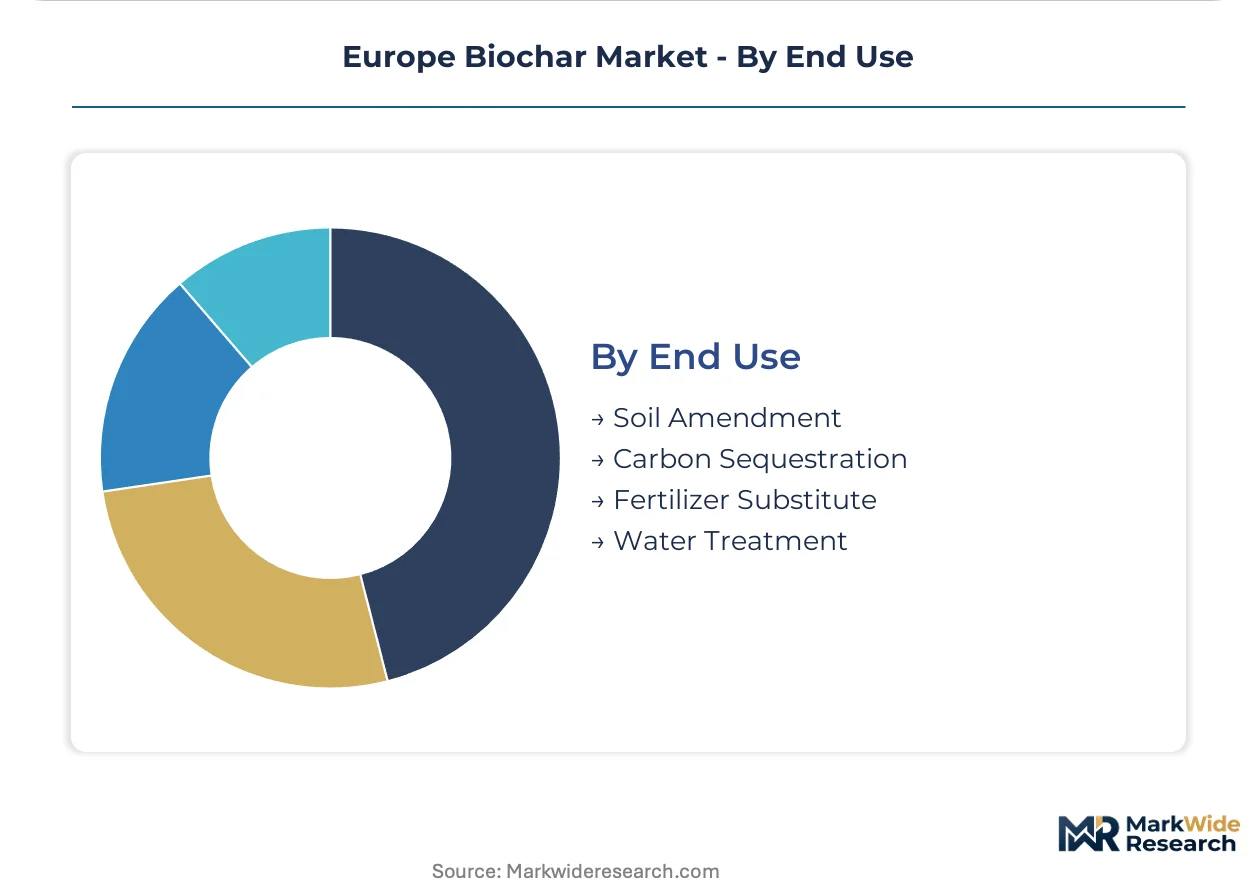
- Soil Amendment:Nutrient retention and pH buffering properties drive specification requirements for permanent grassland and arable applications. German Federal Environment Agency implementation rules exceed baseline EU standards, creating dual certification requirements for market access.
- Carbon Sequestration:EU Emissions Trading System methodology integration bundles biochar delivery with CO2 credit verification. Dutch and German agricultural cooperatives now contract for tonnes of verified removal rather than commodity spot purchasing.
- Fertilizer Substitute:Partial replacement of synthetic nitrogen inputs aligns with Farm to Fork strategy targets.
- Water Treatment:Activated biochar filtration media compete with conventional activated carbon in municipal and industrial wastewater applications.
Soil Amendment generates the highest absolute demand, with Carbon Sequestration expanding most quickly as procurement shifts toward outcome-based contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Rhine-Ruhr greenhouse cluster anchors European biochar procurement volume as Dutch Venlo horticulture operators and French vineyard cooperatives scale carbon removal contracting. National regulatory divergence under EU Green Deal implementation is fragmenting certification requirements across member states.
Germany
Vineyard cooperatives in Rhineland-Palatinate and Baden-Württemberg drive premium demand for EBC-certified agricultural grades. The Federal Environment Agency enforces soil protection rules exceeding baseline EU standards, creating dual certification requirements. PYREG GmbH anchors continuous pyrolysis supply contracts from its German engineering base near arable zones.
Netherlands
Venlo horticulture cluster operators specify continuous pyrolysis systems exclusively for carbon removal service contracts. National integration of EU Emissions Trading System methodologies with soil amendment subsidies bundles revenue streams. Greenhouse operators now contract for tonnes of verified CO2 removal rather than commodity biochar spot purchasing.
France
ANSM soil protection enforcement tightens contaminant thresholds for polycyclic aromatic hydrocarbons and heavy metals beyond ECHA REACH baselines. Soil decontamination contractors in industrial zones pay significant premiums for certified biochar exceeding national thresholds. French farm cooperatives secure long-term agricultural residue supply contracts to hedge against competing biogas plant demand.
Sweden
Nordic wood waste processors dominate high-grade feedstock access with superior carbon content. Envigas AB occupies position within Scandinavia's circular biomass economy. National implementation of EU Green Deal carbon accounting mandates forces agricultural cooperatives to document soil carbon sequestration, creating procurement pull for certified grades.
Italy
Po Valley arable zones accelerate agricultural soil amendment adoption under tightening emissions accountability. Farm cooperatives secure straw supply contracts near pyrolysis deployment points to manage feedstock cost volatility. Italian vineyard operators follow German Rhineland patterns in specifying EBC-certified grades for premium soil amendment contracts.
Europe Biochar Market Competitive Landscape
Capacity expansion dominates the current landscape as pyrolysis facility buildouts redraw competitive boundaries between commodity and premium supply tiers. The vendor base separates into continuous reactor specialists, integrated carbon removal service providers, and regional feedstock processors. Three archetypes define positioning: engineering-led technology licensors, bundled carbon credit verification platforms, and captive feedstock operators. M&A activity and certification scheme pre-qualification constitute the dominant competitive moves.
Among German-based engineering specialists, PYREG GmbH exemplifies the continuous pyrolysis technology archetype, while NOVOCARBO GmbH represents the integrated carbon removal service model. Carbofex Ltd occupies position within the Nordic wood waste feedstock specialist tier. These three entities anchor the competitive structure without exhaustively mapping the field.
| Leading Market Players |
|---|
| PYREG GmbH |
| NOVOCARBO GmbH |
| Carbofex Ltd |
| Sonnenerde GmbH |
| Airex Energy |
| Carbonis GmbH & Co KG |
| Circular Carbon GmbH |
| Carbon Gold Ltd |
| Envigas AB |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between EBC-certified premium tiers and commodity agricultural grades manifests in both price spreads and supply chain configurations across European biochar markets. German vineyard cooperatives and Dutch greenhouse operators command pricing power through dual-certification compliance, while spot-market purchasers of uncertified grades absorb feedstock volatility without carbon credit bundling.
Pricing Analysis
Input-cost pass-through from straw and manure feedstock volatility compresses margins for pyrolysis operators lacking captive supply agreements. Three-tier pricing structure across premium, standard, and economy levels separates EBC-certified agricultural grades from industrial remediation specifications and uncertified commodity batches. Cost compression in standard tiers is intensifying because competing biogas plants divert agricultural residues during grain harvest peaks. Spot-market buyers in Italy's Po Valley exhibit highest price sensitivity, while Rhine-Ruhr greenhouse operators purchasing bundled carbon removal services show least elasticity.
Supply Chain Analysis
Reverse-logistics flows for spent biochar from soil decontamination sites create secondary feedstock streams for reactivation processors in France and Germany. Geographic supply concentration centers on Germany, the Netherlands, and Sweden, with Nordic wood waste processors anchoring high-carbon-content grades. Raw material dependencies rest on straw availability near arable zones, manure collection networks, and Scandinavian forestry residues. Single-source vulnerability runs through German engineering consultancies controlling continuous pyrolysis reactor design expertise. Distribution runs through agricultural cooperative procurement channels and specialized soil amendment distributors rather than legacy fertilizer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Green Deal carbon accounting mandates force agricultural cooperatives to document soil carbon sequestration, creating structural procurement pull for certified biochar regardless of commodity price cycles.
For Market Incumbents: Lock in long-term agricultural residue supply contracts near Rhineland-Palatinate and Baden-Württemberg vineyard clusters before biogas plant competition intensifies. Anchor premium positioning through dual EBC and national soil protection certification investments that exceed baseline EU standards. Defend against integrated carbon removal service providers by building in-house CO2 credit verification capabilities rather than outsourcing to third-party platforms. For New Entrants and Emerging Players: The premium-to-economy price-point gap in French environmental remediation contracts offers white-space entry for certified producers meeting ANSM contaminant thresholds beyond ECHA REACH baselines. Target Italy's Po Valley arable zones where farm cooperative procurement remains fragmented and EBC certification penetration lags German benchmarks. Pursue go-to-market angles bundling biochar delivery with on-farm pyrolysis unit deployment to capture energy coproduct revenues. For Investors and Strategic Acquirers: Consolidation pressure builds where engineering talent scarcity in continuous pyrolysis reactor design limits facility replication speed across continental Europe. Long-term viability over the projection horizon favors integrated producers combining captive feedstock, in-house certification, and carbon credit verification capabilities. Acquisition target archetypes include Nordic wood waste processors with superior carbon content grades and stranded batch-reactor assets convertible to continuous systems. Monitor EU Emissions Trading System carbon removal methodology convergence with national soil amendment subsidies as the critical inflection signal for revenue stream bundling.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agricultural Residue Supply | German vineyard cooperatives secure straw and manure contracts to hedge biogas competition. |
| Dual Certification Investment | EBC plus Federal Environment Agency compliance opens premium pricing in Rhine-Ruhr greenhouse clusters. |
| Carbon Credit Verification Capability Buildout | Dutch Venlo horticulture operators now contract for tonnes of verified CO2 removal rather than commodity spot purchasing. |
| Continuous Pyrolysis Reactor Deployment | Thermal efficiency above 75 percent cuts parasitic losses and displaces batch reactor economics. |
| Environmental Remediation Application Expansion | French ANSM enforcement creates concentrated margin pools for heavy metal binding certified grades. |
Research Methodology
Multiple input streams — pyrolysis plant operators, agricultural cooperative procurement officers, soil remediation contractors, and carbon credit verification specialists — were reconciled against regulatory filing databases and EU Emissions Trading System methodology documents. Primary interviews with reactor engineering consultancies in Germany and Austria were cross-validated through secondary sources including ECHA REACH guidance documents, national soil protection agency implementation rules, and European Biochar Certificate auditing protocols. Bottom-up facility capacity assessments and top-down carbon removal demand projections were triangulated to establish market sizing boundaries.
Historical production capacity buildouts were cross-referenced against expert panel inputs from thermal process engineers and agricultural extension officers across the analysis window. Segmentation dimensions modeled include product certification tier, feedstock sourcing strategy, reactor technology configuration, and end-use application vertical. CAGRs were derived from supply-side capacity expansion schedules and demand-side procurement pattern shifts in Dutch and German agricultural cooperatives. Forecast inputs incorporated EU Green Deal implementation timelines and national soil protection law enforcement trajectories without assuming specific regulatory milestone dates.
Caveats apply where EBC certification timeline compression or pyrolysis engineering talent scarcity could materially shift the outlook for new entrant market access. Forecasts reflect assumptions regarding carbon credit methodology convergence and feedstock cost volatility patterns. Practitioners should monitor ANSM enforcement actions and Federal Environment Agency rulemaking for early signals of premium certification tier expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environment & Sustainability
UAE Industrial Waste Management Market
Environment & Sustainability
South America Residential Water Treatment Equipment Market
Environment & Sustainability
Waste Management Market
Environment & Sustainability
Sustainability Management Software Market
Environment & Sustainability
Global Waste Management Software Market
Environment & Sustainability
Carbon-Aware Slot Booking and Delivery Windows Platforms Market
Environment & Sustainability
Europe Medical Waste Management Market
Environment & Sustainability
Middle East and Africa Solar Panel Recycling Market
Environment & Sustainability
Testing, Inspection, and Certification for Natural Resources Market
Environment & Sustainability
Industrial Air Quality Control Systems Market
Environment & Sustainability
Qatar Solid Waste Management Market
Environment & Sustainability
Southeast Asia Air Purifier Market
Environment & Sustainability
Wheeled Bins Market
Environment & Sustainability
Product Stewardship Market
Environment & Sustainability
Recyclate PET Market
Environment & Sustainability
Global Solar Water Desalination Plants Market