
 Incinerator Market | 2026-2036
Incinerator Market Size, Share, and Industry Trends Forecast 2026-2036
Incinerator Market Intelligence
The EU Green Deal is restructuring procurement priorities for thermal waste treatment across member states. Veolia sustains its European footprint through integrated waste-to-energy operations. Babcock & Wilcox Enterprises specializes in high-capacity combustion systems for industrial clients. Hitachi Zosen Inova dominates the Asian project pipeline with advanced flue gas cleaning technology.
An incinerator is a thermal treatment device engineered to combust solid, liquid, or gaseous waste streams at controlled temperatures, typically utilizing combustion chambers with residence times exceeding two seconds and operating temperatures ranging from 850°C to 1,200°C depending on waste calorific value and regulatory requirements. Its primary industrial purpose is volume reduction, pathogen destruction, and energy recovery through steam or electricity generation. Rotary kiln configurations command premium positioning due to their adaptability across hazardous and medical waste streams with complex compositions. Fluidized bed technology leads growth in municipal applications where uniform combustion of mixed refuse delivers higher thermal efficiency. Pyrolysis technology occupies emerging niches seeking syngas recovery and reduced residual ash.
The EPA enforces Maximum Achievable Control Technology standards that dictate particulate, dioxin, and mercury emission limits for municipal and hazardous waste incinerators in the United States. The EU Industrial Emissions Directive harmonizes best available technique requirements across member state permitting regimes, directly shaping capital expenditure thresholds for new installations. China's MEE administers increasingly stringent GB standards for dioxin emissions from medical and municipal waste facilities. Stakeholders must monitor evolving carbon accounting methodologies that could recategorize waste-to-energy emissions under compliance markets.
Market Dynamics
The EU Green Deal's landfill diversion mandates are compressing investment timelines for thermal waste treatment infrastructure across member states, forcing municipalities to accelerate procurement of high-efficiency combustion systems.
Growth Catalysts
- EU Industrial Emissions Directive:Harmonized best available technique requirements are mandating facility upgrades across Germany, France, and Italy, creating replacement demand for advanced flue gas cleaning systems.
- Medical waste stream expansion:Post-pandemic healthcare infrastructure investment in Southeast Asia is driving hospital-grade incinerator installations with pathogen destruction protocols.
- Rotary kiln adaptability:Hazardous waste processors favor this configuration for complex industrial byproduct streams containing mixed organics and heavy metals.
Market Restraints
- Refractory material cost volatility:Magnesia-chrome brick supply concentration in China creates input price instability for combustion chamber construction.
- Permitting timeline friction:EPA Maximum Achievable Control Technology compliance reviews extend project development cycles by 18-36 months in the United States.
- Mechanical biological treatment substitution:Anaerobic digestion systems compete for municipal organic waste fractions with lower capital intensity.
Strategic Opportunities
- Indonesia municipal pipeline:Provincial governments in Java and Sumatra are tendering waste-to-energy capacity without established vendor relationships.
- Carbon accounting methodology evolution:Compliance market recategorization of biogenic CO2 from waste-to-energy could unlock offset revenue streams.
- Pyrolysis-syngas hybrid systems:Converging thermal cracking with gas turbine integration offers higher electrical efficiency than conventional grate combustion.
Industry Challenges
- Combustion engineering talent scarcity:Specialized expertise in computational fluid dynamics modeling for multi-fuel firing systems remains concentrated among retiring specialists.
- Flue gas analyzer certification delays:Continuous emissions monitoring system validation protocols extend commissioning timelines for new installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Incinerator Market |
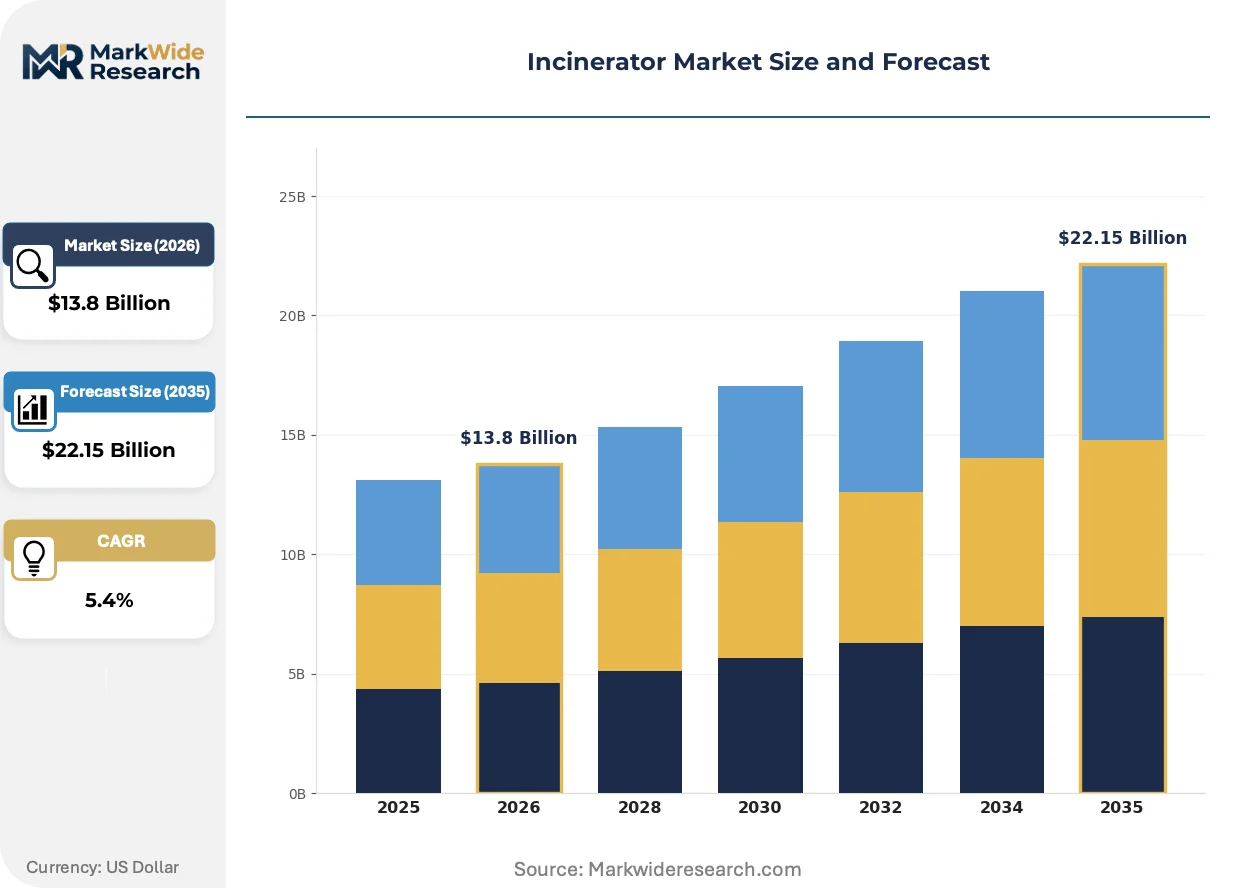
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $22.15 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Industrial Incinerators, Medical Waste Incinerators, Hazardous Waste Incinerators, Municipal Waste Incinerators Technology: Combustion Technology, Rotary Kiln, Fluidized Bed, Pyrolysis Technology Application: Energy Recovery, Waste Treatment, Emission Control, Environmental Management End User: Manufacturing Facilities, Hospitals, Government Agencies, Waste Management Companies |
| Companies Covered | Inciner8, Veolia, Babcock & Wilcox Enterprises, Keppel Seghers, Hitachi Zosen Inova, SUEZ, Thermax, Martin GmbH, Mitsubishi Heavy Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Incinerator Market Strategic Shifts & Innovations
Advanced emission control technologies and digital monitoring systems are compressing operational margins for legacy incinerator designs while enabling new service revenue models.
Plasma arc gasification is electrifying high-temperature waste destruction by converting feedstock into synthetic gas and vitrified slag without residual ash. Hazardous waste processors in Japan and South Korea are piloting commercial-scale units for industrial solvent streams. This technology is electrifying competitive positioning by eliminating landfill disposal costs entirely.
China's GB 18485-2014 standard revision is tightening dioxin emission limits from 0.1 ng TEQ/Nm³ to 0.05 ng TEQ/Nm³ for municipal waste facilities. Provincial environmental protection bureaus are requiring existing plants to install activated carbon injection systems and fabric filter upgrades. Medical waste incinerators in Guangdong and Jiangsu provinces face the most compressed retrofit timelines.
Performance-based service contracts are displacing equipment-only procurement in European municipal tenders. Operators in the Netherlands and Sweden now contract for guaranteed availability and emission compliance rather than capital purchase. This shift concentrates risk with technology providers while transferring operational expertise to specialized waste management firms.
Incinerator Market Segmentation
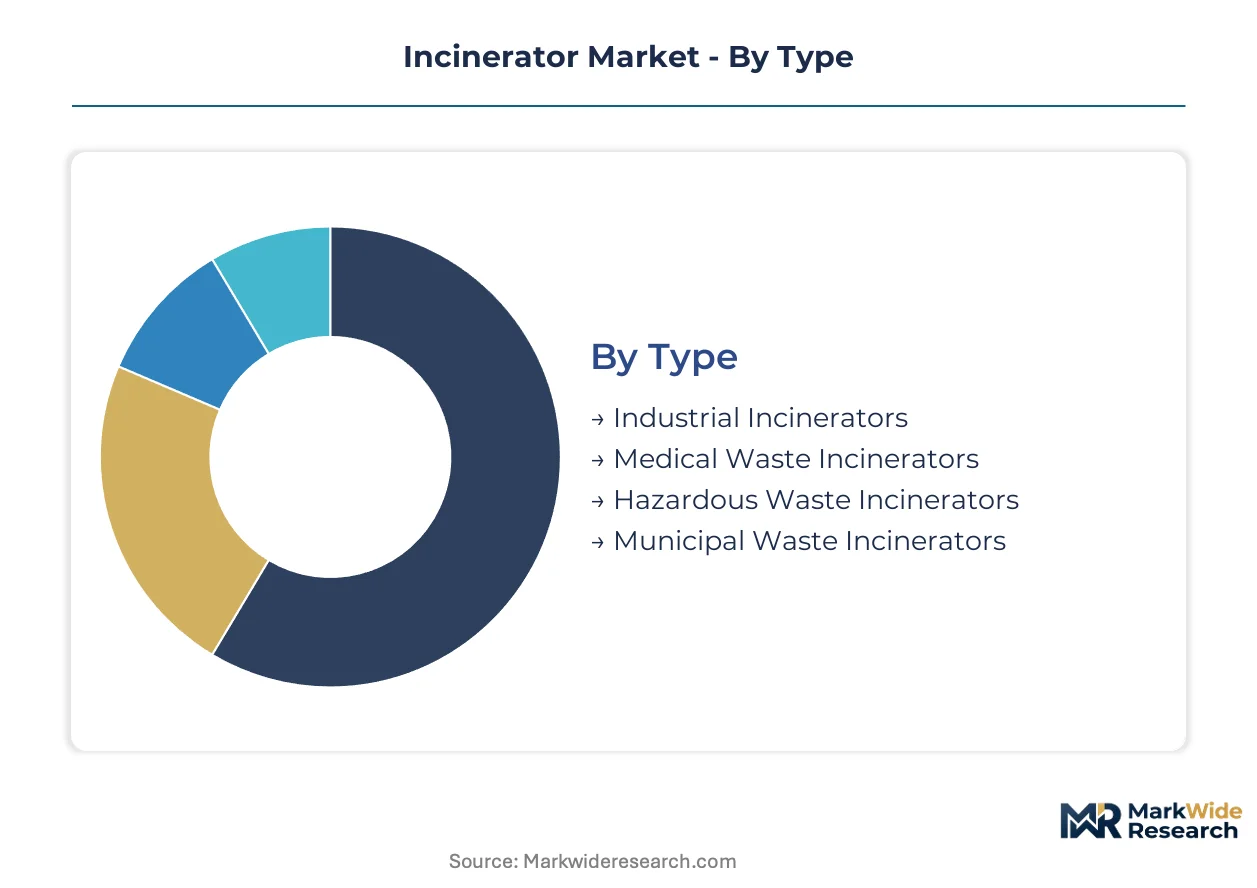
Incinerator procurement decisions hinge on waste stream composition, regulatory stringency, and energy recovery objectives. Technology selection varies sharply across municipal, medical, and hazardous waste applications. End-user sophistication determines whether buyers prioritize capital efficiency or operational flexibility.
Type:
Facility operators select incinerator type based on waste calorific value, pathogen risk classification, and residual ash disposal constraints.
- Municipal Waste Incinerators:Grate combustion systems process mixed household refuse at 850°C to 1,000°C, generating steam for district heating networks. Demand concentrates in China as provincial governments enforce GB 18485-2014 dioxin limits, forcing retrofit investments across Guangdong and Jiangsu facilities.
- Medical Waste Incinerators:Dual-chamber designs achieve 1,200°C in secondary combustion zones for complete pathogen destruction. Southeast Asian hospital infrastructure expansion drives procurement, with Indonesia's provincial health authorities tendering capacity without established vendor relationships.
- Industrial Incinerators:Specialized burners handle manufacturing byproducts with variable heating values. Steel and chemical plants in Germany and France deploy these for solvent recovery compliance under EU Industrial Emissions Directive requirements.
- Hazardous Waste Incinerators:Rotary kiln configurations dominate for complex industrial streams containing heavy metals and chlorinated organics. EPA Maximum Achievable Control Technology standards govern US facility permitting timelines.
Volume sits with municipal waste installations; growth tilts toward medical waste systems.
Technology:
Capital expenditure thresholds and fuel flexibility requirements determine technology adoption patterns across project pipelines.
- Rotary Kiln:Cylindrical refractory-lined drums rotate at 0.5 to 2 RPM, accommodating sludge, solids, and containerized waste in single campaigns. Hazardous waste processors in Japan favor this configuration for industrial solvent destruction under METI guidelines.
- Fluidized Bed:Sand particle suspension at 800°C to 900°C delivers uniform combustion of shredded municipal refuse. Swedish and Dutch operators achieve higher thermal efficiency than grate systems, supporting performance-based service contract structures.
- Combustion Technology:Conventional grate and chamber designs remain standard for high-volume municipal applications. Chinese MEE enforcement of tightened dioxin limits accelerates flue gas cleaning retrofits on existing units.
- Pyrolysis Technology:Oxygen-starved thermal cracking at 400°C to 800°C yields syngas for turbine integration. Emerging deployments in South Korea target electrical efficiency gains over conventional combustion.
Installed base concentrates in combustion technology; expansion tilts toward pyrolysis-syngas hybrids.
Application:
Revenue models diverge between energy sales, tipping fees, and emission compliance services.
- Waste Treatment:Core volume reduction and sterilization functions drive baseline demand. EU Green Deal landfill diversion mandates compress procurement timelines across member state municipalities.
- Energy Recovery:Steam and electricity generation from combustion heat. Waste-to-energy plants in Denmark and Switzerland supply district heating networks with guaranteed availability contracts.
- Emission Control:Activated carbon injection and fabric filter systems for dioxin and mercury capture. China's GB standard revision to 0.05 ng TEQ/Nm³ forces upgrade investments.
- Environmental Management:Integrated ash handling and wastewater treatment. Full-service operators in the Netherlands assume operational risk through performance-based agreements.
Revenue concentrates in waste treatment; margin expansion tilts toward energy recovery.
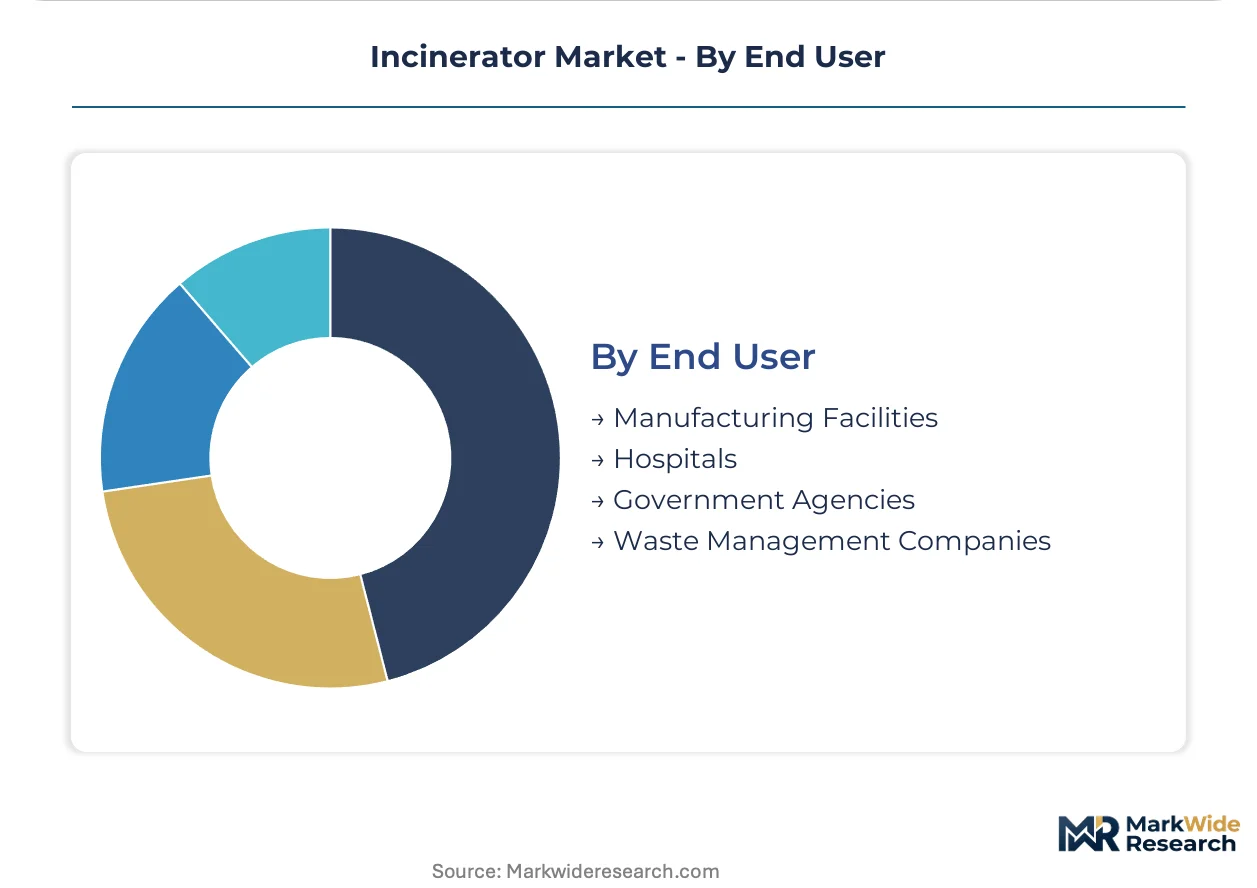
End User:
Procurement sophistication varies from technical specification compliance to outcome-based contracting.
- Waste Management Companies:Specialized operators aggregate feedstock and sell energy output. Veolia's integrated European footprint demonstrates scale advantages in performance-based municipal tenders.
- Government Agencies:Municipal and provincial authorities issue capacity tenders with emission guarantee requirements. Indonesia's Java and Sumatra governments lack established vendor relationships, creating entry opportunities.
- Hospitals:Healthcare facilities require pathogen destruction protocols with continuous operation guarantees. Post-pandemic infrastructure investment in Southeast Asia accelerates procurement cycles.
- Manufacturing Facilities:Industrial plants seek on-site disposal for proprietary waste streams. Chemical and pharmaceutical operations in Germany face ECHA compliance obligations for hazardous byproduct handling.
Contract volume sits with government agencies; commercial sophistication tilts toward waste management companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zhejiang province anchors thermal waste treatment expansion, with Hangzhou and Ningbo municipalities tendering grate combustion capacity under tightened environmental enforcement.
China
Provincial governments in Guangdong and Jiangsu enforce GB 18485-2014 dioxin limits at 0.05 ng TEQ/Nm³, compelling activated carbon retrofits across 200-plus municipal facilities. The Ministry of Ecology and Environment administers quarterly stack testing protocols. Shanghai's Pudong district hosts the densest concentration of waste-to-energy plants serving the Yangtze River Delta corridor.
Germany
Municipal utilities in North Rhine-Westphalia replace aging grate systems with fluidized bed configurations for higher thermal efficiency. The EU Industrial Emissions Directive mandates best available technique upgrades by 2027. The Rhine-Ruhr metropolitan cluster concentrates Europe's largest operational base of district heat-integrated incinerators.
United States
Industrial processors in Texas and Louisiana seek rotary kiln capacity for hazardous waste streams from petrochemical operations. EPA Maximum Achievable Control Technology compliance reviews extend permitting timelines 18-36 months. The Houston Ship Channel corridor generates concentrated demand for high-temperature destruction of chlorinated solvent byproducts.
Indonesia
Provincial health authorities in Java and Sumatra tender hospital-grade incinerators without established vendor relationships, creating procurement vacuums. The national Ministry of Environment and Forestry issues emission permits under decentralized authority. Jakarta's Cilincing district hosts pilot waste-to-energy projects targeting the capital's 7,000-ton daily municipal output.
Japan
Metropolitan governments in Tokyo and Osaka deploy plasma arc gasification for industrial solvent destruction. METI guidelines prioritize residue-free thermal treatment for electronic waste streams. The Keihin industrial belt concentrates next-generation facility deployment with integrated syngas recovery systems.
Incinerator Market Key Industry Players
The competitive structure tilts toward integrated environmental service conglomerates with captive project development capabilities. Equipment fabricators and waste management operators occupy distinct functional tiers with limited overlap. Strategic archetypes include full-service operators assuming operational risk through performance contracts, technology licensors monetizing combustion system designs, and regional EPC contractors executing municipal tenders. Dominant competitive moves encompass vertical integration into feedstock aggregation and geographic expansion via concession bidding in Southeast Asian markets.
Among European-integrated operators, Veolia and SUEZ exemplify the full-service archetype through concession-based municipal contracting. Babcock & Wilcox Enterprises represents North American equipment specialization in high-capacity combustion engineering. Hitachi Zosen Inova anchors the technology-licensing tier with advanced flue gas cleaning system deployment across Asian project pipelines.
| Leading Market Players |
|---|
| Inciner8 |
| Veolia |
| Babcock & Wilcox Enterprises |
| Keppel Seghers |
| Hitachi Zosen Inova |
| SUEZ |
| Thermax |
| Martin GmbH |
| Mitsubishi Heavy Industries |
| Others |
Cost & Logistics Intelligence
Refractory magnesia-chrome brick costs from Chinese suppliers cascade through combustion chamber fabrication into tiered equipment pricing, with grate system OEMs absorbing volatility while rotary kiln specialists pass through premiums to hazardous waste processors.
Pricing Analysis
Guaranteed availability contracts anchor value-based pricing for European municipal operators, with Veolia and SUEZ contracting for uptime percentages rather than capital purchase. Price differentiation hinges on flue gas cleaning certification tiers and after-sales service bundling. Cost compression in standard grate systems intensifies as Chinese MEE enforcement accelerates domestic vendor capacity. Government agencies in Indonesia exhibit highest price sensitivity due to untendered procurement experience, while Dutch waste management companies prioritize emission compliance over capital outlay.
Supply Chain Analysis
CE marking and EPA MACT qualification gating restrict combustion system component sourcing to certified refractory suppliers in Germany, Japan, and China. Critical inputs include magnesia-chrome brick, ceramic filter media, and continuous emissions monitoring sensors. Single-source vulnerability concentrates in Chinese refractory exports subject to environmental production curbs. Distribution runs through EPC contractors executing municipal concessions rather than direct equipment sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The incinerator market sits in a technology-transition phase as pyrolysis-syngas hybrids displace conventional grate combustion for higher electrical efficiency targets.
For Market Incumbents: Deploy backward integration into refractory material supply to offset Chinese magnesia-chrome price volatility. Babcock & Wilcox Enterprises and Hitachi Zosen Inova must accelerate fluidized bed R&D to defend against plasma arc gasification pilots in Japan and South Korea. EPA MACT permitting delays threaten North American project pipelines; incumbents should pre-certify modular designs to compress commissioning timelines. For New Entrants and Emerging Players: EU Industrial Emissions Directive upgrades by 2027 open a window for flue gas cleaning specialists to capture retrofit demand across German and Italian municipal facilities. Indonesia's Java and Sumatra provincial tenders lack established vendor relationships, creating entry points for hospital-grade incinerator suppliers. Target performance-based service contracting rather than equipment-only sales to differentiate from European integrated operators. For Investors and Strategic Acquirers: China's GB 18485-2014 revision to 0.05 ng TEQ/Nm³ is the leading indicator that activated carbon injection and fabric filter upgrade demand will concentrate among mid-tier technology licensors. Acquisition targets should combine combustion engineering expertise with captive flue gas cleaning IP. Watch for quarterly stack testing protocol expansion beyond Guangdong and Jiangsu as the signal for nationwide retrofit acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Performance-Based Service Contracting | Veolia's Dutch municipal concessions demonstrate risk transfer from operators to technology providers. |
| Flue Gas Cleaning Retrofit Capacity | Activated carbon injection installation responds to China's MEE quarterly stack testing enforcement. |
| Pyrolysis-Syngas Hybrid Development | South Korean pilots target electrical efficiency gains over conventional grate combustion systems. |
| Refractory Supply Backward Integration | Captive magnesia-chrome sourcing insulates margins from Chinese environmental production curbs. |
| Indonesia Provincial Concession Bidding | Java and Sumatra health authority tenders proceed without established vendor relationships. |
Research Approach
Multi-period observation of provincial tender awards, stack testing enforcement actions, and technology pilot announcements anchored the trend analysis, supplemented by interviews with combustion engineering directors, EPC project managers, municipal procurement officers, and aftermarket service heads. Secondary validation drew from EPA MACT dockets, EU Industrial Emissions Directive implementation reports, Chinese MEE quarterly compliance bulletins, and customs data on refractory material trade flows. Bottom-up project pipeline aggregation triangulated against top-down regulatory mandate scaling.
Segment-weighting applied technology type, waste stream application, and regional regulatory cluster as primary dimensions across the projection horizon. CAGRs derived from facility commissioning timelines tied to enforcement deadlines rather than demand elasticity. Forecast inputs incorporated provincial capacity targets from China's Yangtze River Delta corridor and EU landfill diversion compliance schedules.
The model assumes a particular technology adoption path; alternative pathways for plasma arc gasification commercialization would alter the outlook for conventional combustion system demand. Forecasts reflect assumptions regarding MEE enforcement continuity and EU Green Deal funding availability. A model refresh is warranted upon material change in carbon accounting methodology for biogenic CO₂ from waste-to-energy facilities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Sludge Management Equipment Market
Waste Management & Pollution Control
Africa Waste Management Market
Waste Management & Pollution Control
Asia-Pacific Waste Management Market
Waste Management & Pollution Control
Construction and Demolition Waste Management Market
Waste Management & Pollution Control
Waste Sorting Equipment Market
Waste Management & Pollution Control
Household Composters Market
Waste Management & Pollution Control
Europe Medical Waste Management Market
Waste Management & Pollution Control
Europe Municipal Solid Waste Management Market
Waste Management & Pollution Control
Automated Waste Collection System (AWCS) Market
Waste Management & Pollution Control
India Plastic Waste Management Market
Waste Management & Pollution Control
Europe Plastic Waste Management Market
Waste Management & Pollution Control
Food Waste Management Market
Waste Management & Pollution Control
Asia-Pacific Municipal Solid Waste Management Market
Waste Management & Pollution Control
Trash Rakes Market
Waste Management & Pollution Control
UAE Biomedical Waste Management Market
Waste Management & Pollution Control
North America Waste Recycling Services Market