
 India Recycling Market | 2026-2036
India Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
India Recycling Market Insights
Municipal corporations is rotating demand away from informal scrap aggregators toward integrated waste management firms. Ganesha Ecosphere anchors polyethylene terephthalate recycling through backward integration into collection networks. Gravita India Ltd dominates lead-acid battery recycling with smelting assets across multiple states. Namo eWaste Management Ltd specializes in precious metal recovery from printed circuit boards, differentiating through licensed dismantling facilities.
Recycling encompasses the collection, sorting, processing, and reintroduction of post-consumer and post-industrial materials into manufacturing supply chains, with mechanical shredding and melt filtration producing resin grades meeting melt flow index specifications between 2–30 g/10 min for injection molding applications. Plastic recovery leads volume throughput due to packaging waste generation, while chemical recycling of mixed polymer streams represents the fastest-growing processing technology as pyrolysis yields approach fossil-naphtha parity. Metal recovery maintains the deepest margin pools given copper and aluminum price arbitrage against virgin smelting costs.
BIS mandates minimum recycled content thresholds for rigid plastic packaging under evolving packaging waste rules, while CPCB enforces extended producer responsibility compliance through centralized online portals tracking material flow certificates. State pollution control boards in Maharashtra and Gujarat condition operating consents on zero-liquid-discharge norms and air emission stacks meeting PM10 limits. Stakeholders must monitor whether chemical recycling assets achieve commercial scale before mechanical capacity saturates in western India.
Market Dynamics
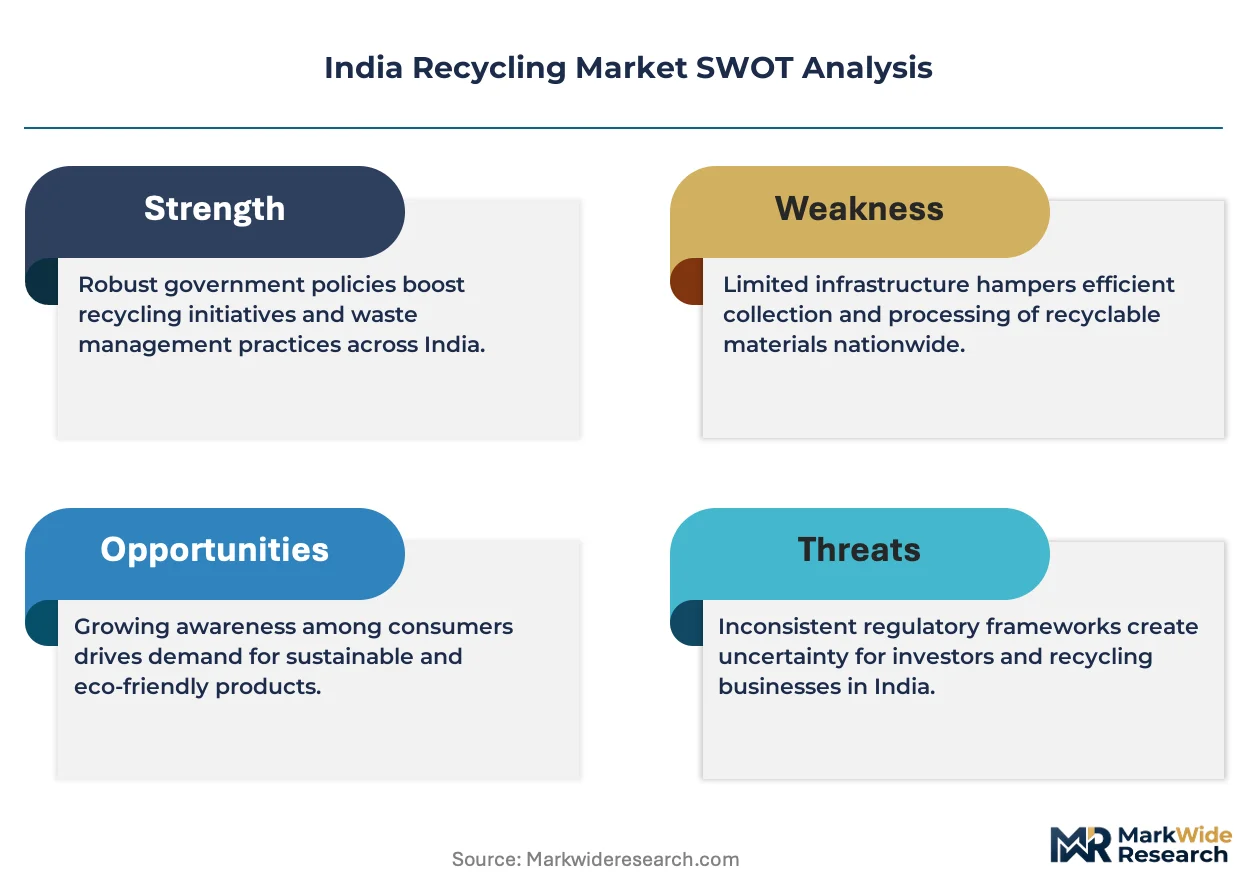
Mechanical recycling capacity saturation in western India is fragmenting competitive returns and redirecting capital toward chemical conversion assets. BIS mandates on recycled content thresholds are compressing compliance timelines for packaging converters.
Growth Catalysts
- Extended Producer Responsibility (EPR) Framework:CPCB's centralized online portal for material flow certificates is binding brand owners to registered recyclers, formalizing previously informal collection channels.
- Chemical Recycling Scale-Up:Pyrolysis yields approaching fossil-naphtha parity are attracting petrochemical majors to mixed polymer streams previously destined for landfills.
- Municipal Source-Segregation Contracts:Urban local bodies in Maharashtra and Gujarat are awarding exclusive collection rights to integrated waste management firms, displacing scrap aggregators.
Market Restraints
- Feedstock Cost Volatility:Post-consumer PET bale prices fluctuate with crude oil benchmarks, eroding margin stability for mechanical recyclers when virgin resin undercuts recycled grades.
- Western Infrastructure Concentration:Organized processing capacity clusters in Maharashtra and Gujarat, leaving eastern and northeastern states dependent on long-haul logistics with 15-20% cost penalties.
- Contamination Limits:Multi-layer packaging and adhesive labels degrade melt filtration efficiency, capping output quality for rigid packaging applications.
Strategic Opportunities
- Eastern State Greenfield Development:Odisha and West Bengal offer untapped municipal waste volumes with negligible organized competition and state-level single-window clearance schemes.
- Precious Metal Recovery from E-Waste:Printed circuit board dismantling licensed under State Pollution Control Board norms yields copper, gold, and palladium at margins exceeding base metal recycling.
- BIS Certification Tailwinds:Evolving packaging waste rules mandate minimum recycled content thresholds, creating captive offtake agreements for certified recyclers ahead of mechanical capacity saturation.
Industry Challenges
- Zero-Liquid-Discharge Compliance:State Pollution Control Boards in Gujarat and Maharashtra condition operating consents on wastewater recycling systems requiring 40-60% higher capex than conventional effluent treatment.
- Skill Gaps in Chemical Operations:Pyrolysis reactor operation and catalyst management demand process engineers scarce in India's traditional mechanical recycling workforce.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Recycling Market |
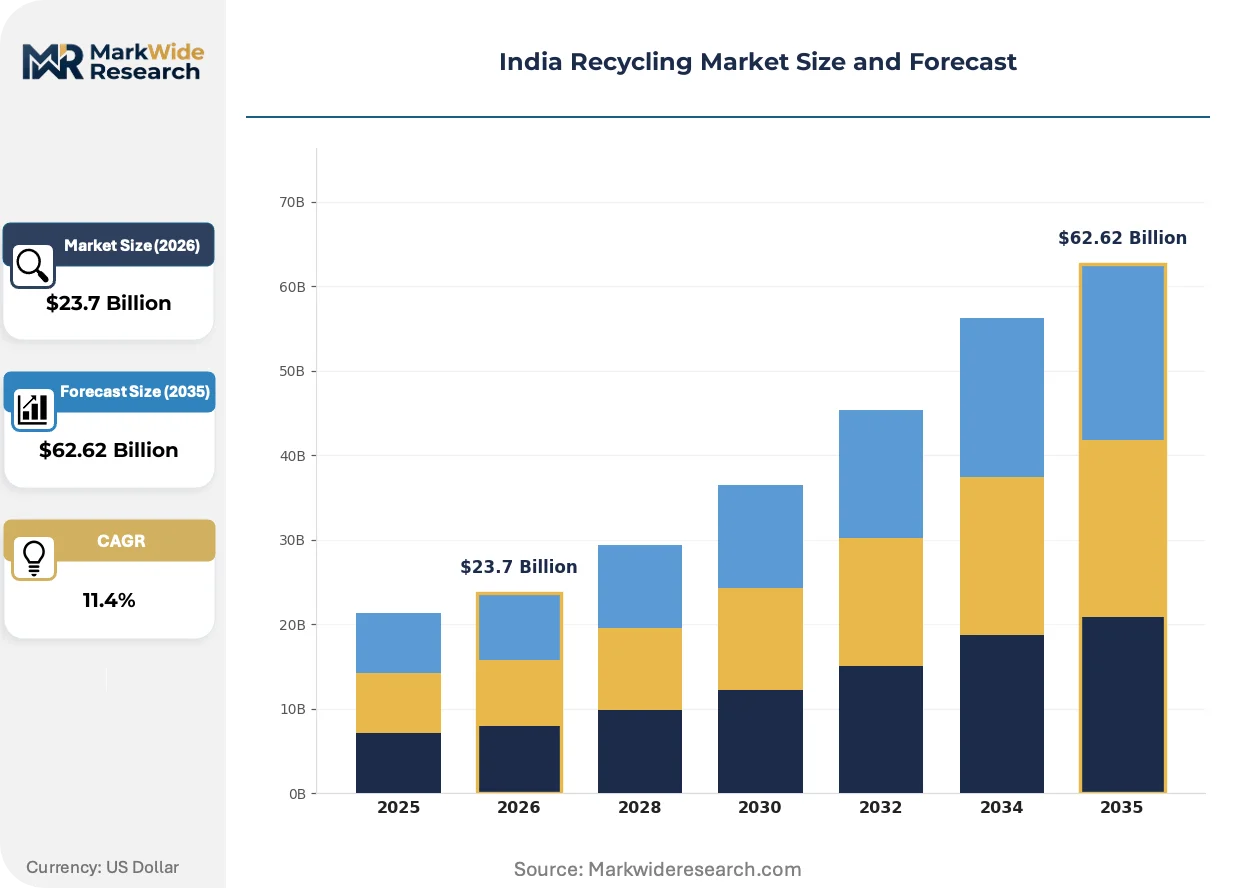
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $62.62 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Glass, Metal, Paper Collection Method: Door-to-Door, Drop-off, Curbside, Community Bin End User Type: Residential, Commercial, Industrial, Institutional Processing Technology: Mechanical, Chemical, Biological, Thermal |
| Companies Covered | Namo eWaste Management Ltd, Ganesha Ecosphere, Gravita India Ltd, Jain Resource Recycling Ltd, The Shakti Plastics Industries, Eco Recycling Ltd, Banyan Nation, Binbag Recycling, Antony Waste Handling Cell Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Recycling Market Trends and Innovations
Chemical conversion technologies are resegmenting competitive boundaries between mechanical recyclers and petrochemical incumbents. Digital traceability platforms are embedding compliance into material flows.
Pyrolysis-based chemical recycling is fragmenting the traditional mechanical recycling value chain by converting mixed polymer waste into synthetic crude and monomer feedstocks. FMCG brand owners with rigid packaging commitments are piloting offtake agreements with chemical recyclers to bypass quality constraints of mechanically recycled resins. This technology is fragmenting regional supply patterns as coastal refineries integrate pyrolysis units with existing steam cracker infrastructure.
BIS certification mandates for recycled content in rigid plastic packaging are compressing compliance timelines for converters. The Bureau of Indian Standards has established testing protocols for post-consumer resin grades, forcing packaging manufacturers to validate melt flow index specifications between 2-30 g/10 min. Flexible packaging converters in Maharashtra are responding by backward integrating into collection networks or securing long-term supply contracts with certified recyclers.
Buyer concentration among municipal corporations is rotating procurement toward integrated waste management firms with captive processing assets. Urban local bodies in Ahmedabad and Pune are abandoning spot contracts with informal aggregators in favor of decade-long concessions requiring guaranteed diversion rates from landfills. This shift is most visible in western India where municipal solid waste generation densities support scale economics for door-to-door collection fleets.
India Recycling Market Segmentation
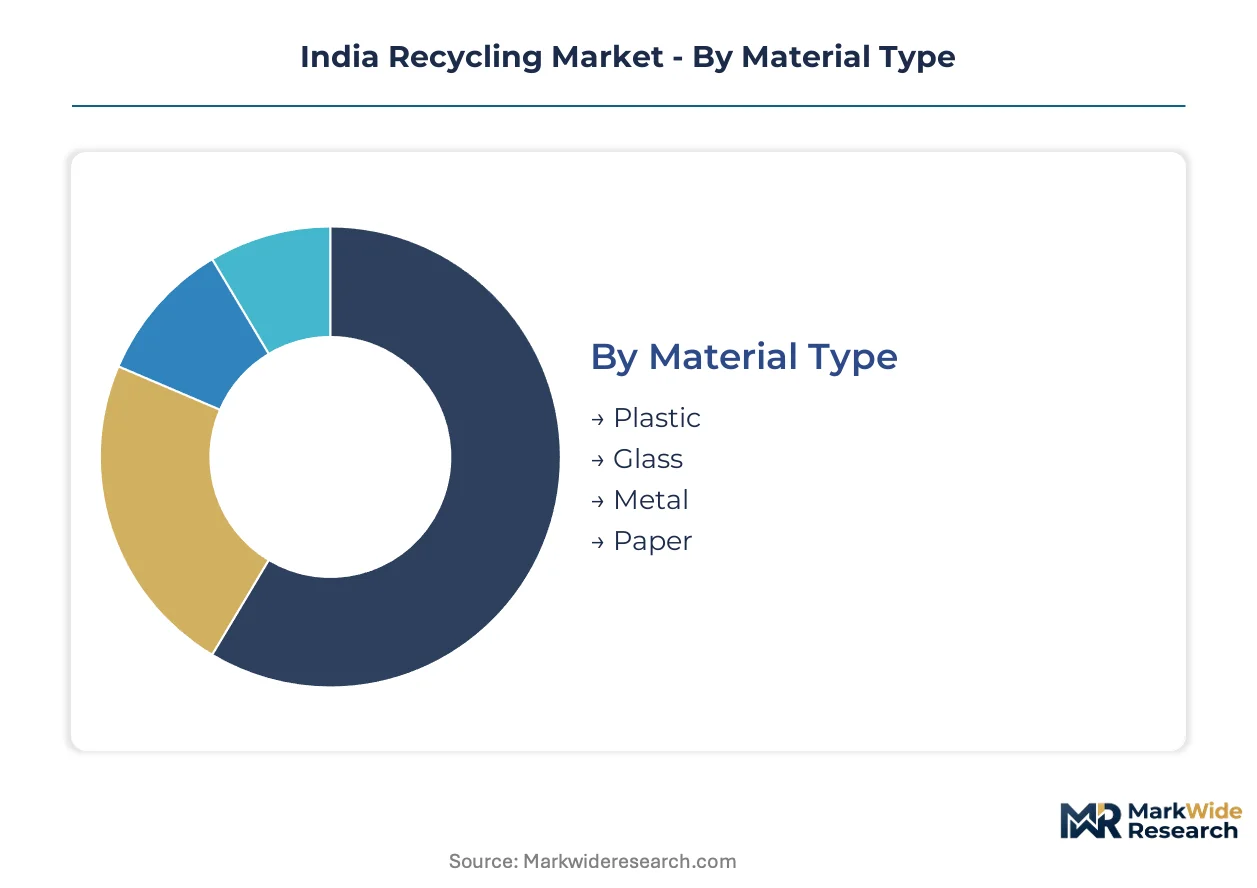
Segmentation in the India Recycling Market reveals how material flows, collection logistics, and processing technologies create distinct competitive arenas. Each dimension exposes different margin structures and regulatory exposure for operators.
Material Type:
Domestic consumption patterns dominate plastic and paper recovery, while metal recycling serves both local foundries and export arbitrage to Southeast Asian smelters.
- Plastic:Post-consumer PET, HDPE, and polypropylene streams undergo mechanical shredding and melt filtration to produce resin grades meeting BIS specifications for rigid packaging applications. Demand concentrates in Maharashtra and Gujarat where municipal source-segregation contracts feed integrated processors, though contamination from multi-layer packaging degrades melt efficiency and caps output quality.
- Metal:Copper, aluminum, and ferrous scrap recovery leverages price arbitrage against virgin smelting costs, with lead-acid battery recycling commanding the deepest margin pools through licensed smelting assets. Exports to Vietnam and Malaysia compete with domestic offtake from secondary aluminum producers in Odisha.
- Glass:Container cullet supplies bottle-to-bottle manufacturers in Firozabad and Mumbai, with color sorting determining end-use viability.
- Paper:Old corrugated containers and newsprint feed packaging board mills in Vapi and Morbi, competing with imported pulp on cost.
Plastic holds the largest share; momentum sits with metal recovery as battery and e-waste regulations tighten.
Collection Method:
Cost tiers separate informal aggregators from capital-intensive integrated operators, with municipal contracts favoring fleet-based models.
- Door-to-Door:Municipal corporations in Ahmedabad and Pune award exclusive concessions requiring guaranteed diversion rates, displacing informal scrap aggregators through decade-long contracts with integrated waste management firms.
- Drop-off:Retail reverse logistics and e-waste collection centers serve commercial generators with scheduled pickup frequencies, capturing higher-value homogeneous streams.
- Curbside:Urban local bodies in tier-2 cities pilot scheduled collection with RFID-tagged bins for traceability compliance under CPCB portals.
- Community Bin:High-density residential clusters in Mumbai and Delhi use centralized segregation infrastructure with informal picker networks feeding registered aggregators.
Door-to-Door commands premium economics; Drop-off is expanding most quickly as brand-owned EPR obligations formalize collection.
End User Type:
Volume concentration varies sharply across generator categories, with industrial waste offering homogeneous feedstock and residential streams requiring heavy sorting investment.
- Industrial:Manufacturing scrap from automotive and electronics sectors delivers pre-sorted metal and polymer streams with minimal contamination, supporting direct-to-smelter or direct-to-pelletizer economics.
- Commercial:Retail, hospitality, and office complexes generate cardboard, PET bottles, and food-service packaging with predictable volumes and lower collection frequency requirements.
- Residential:Municipal solid waste in dense urban corridors supplies mixed streams demanding capital-intensive MRF infrastructure, with source segregation mandates improving feedstock quality.
- Institutional:Hospitals, universities, and government facilities generate specialized e-waste and biomedical streams requiring licensed handling under State Pollution Control Board norms.
Industrial feeds the highest-margin recovery; residential offers the steepest volume expansion trajectory as urbanization accelerates.
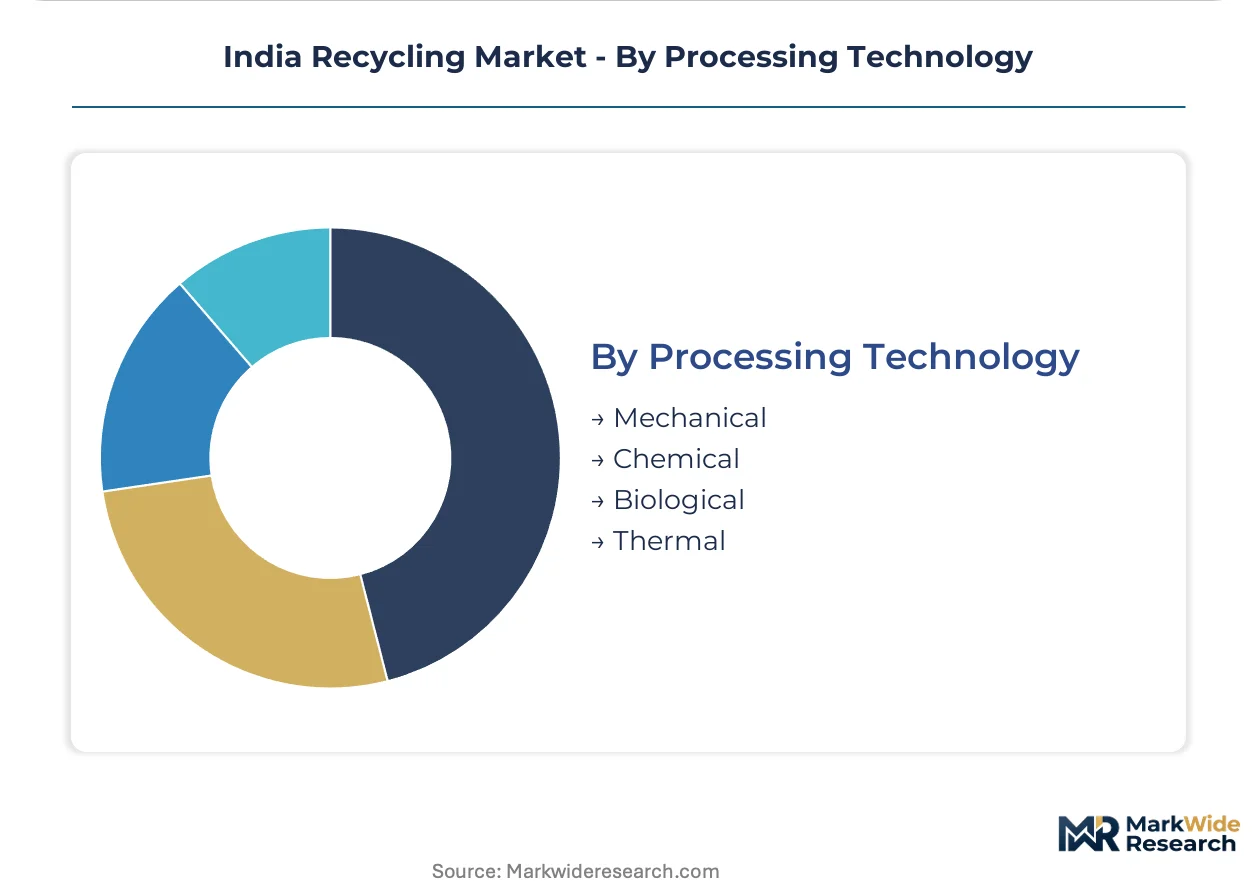
Processing Technology:
Technology maturity separates proven mechanical assets from emerging chemical and biological pathways attracting petrochemical and venture capital.
- Mechanical:Shredding, washing, and extrusion systems dominate installed capacity in western India, with melt flow index specifications between 2-30 g/10 min serving injection molding applications for rigid packaging converters.
- Chemical:Pyrolysis and depolymerization units convert mixed polymer waste into synthetic crude and monomer feedstocks, with yields approaching fossil-naphtha parity attracting Reliance and Indian Oil to coastal refinery integration.
- Biological:Anaerobic digestion and composting process organic fractions from municipal waste, with biogas upgrading to CNG quality standards in Pune and Indore.
- Thermal:Waste-to-energy incineration with flue gas treatment serves non-recyclable fractions, though air emission stack compliance with PM10 limits conditions operating consents in Gujarat and Maharashtra.
Mechanical retains volume leadership; chemical conversion is gaining share fastest as pyrolysis achieves commercial scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jawaharlal Nehru Port Trust in Maharashtra anchors India's organized recycling infrastructure, handling containerized scrap metal and plastic resin exports while feeding western India's processing clusters through dedicated freight corridors.
Maharashtra
Mumbai and Pune municipal corporations award decade-long source-segregation concessions to integrated waste management operators. The Maharashtra Pollution Control Board enforces zero-liquid-discharge norms for processing consents. MIDC industrial areas in Nashik and Aurangabad concentrate PET mechanical recycling assets serving rigid packaging converters.
Gujarat
Ahmedabad and Surat urban local bodies displace informal aggregators through exclusive collection rights tied to guaranteed landfill diversion rates. The Gujarat Pollution Control Board conditions air emission permits on PM10 stack compliance. Dahej and Hazira coastal corridors attract chemical recycling pilots as Reliance Industries integrates pyrolysis units with refinery infrastructure.
Tamil Nadu
Chennai's dense municipal solid waste generation supports door-to-door collection fleet economics for formal operators. The Tamil Nadu Pollution Control Board mandates e-waste dismantling licenses for precious metal recovery facilities. Sriperumbudur and Oragadam industrial belts host electronics manufacturing scrap streams feeding copper and aluminum recovery circuits.
Karnataka
Bengaluru's technology sector generates homogeneous e-waste streams from obsolete server and telecommunications equipment. The Karnataka State Pollution Control Board tracks extended producer responsibility compliance through centralized material flow portals. Peenya and Bommasandra industrial zones concentrate licensed printed circuit board dismantlers extracting gold and palladium.
West Bengal
Kolkata's municipal corporations pilot scheduled curbside collection with RFID-tagged bins for traceability under CPCB protocols. The West Bengal Pollution Control Board offers single-window clearance schemes for greenfield recycling investments. Haldia port infrastructure enables scrap metal arbitrage to Southeast Asian smelters competing with domestic Odisha foundries.
India Recycling Market Competitive Landscape
Listed leaders compete with private specialists across collection network scale and processing technology depth. The market fragments into three tiers: integrated waste management firms with municipal concessions, pure-play mechanical recyclers with BIS-certified resin output, and emerging chemical conversion operators backed by petrochemical capital. Strategic moves concentrate on backward integration into collection networks and technology licensing for pyrolysis reactor deployment.
Within the integrated concession tier, Antony Waste Handling Cell Ltd and Jain Resource Recycling Ltd exemplify operators securing long-term municipal contracts with guaranteed diversion obligations. Among specialized processors, Ganesha Ecosphere occupies a position representing backward-integrated PET recyclers with proprietary collection infrastructure, while Gravita India Ltd anchors the licensed metal recovery segment with multi-state smelting assets. These three names illustrate how competitive positioning depends on regulatory licensing depth and captive feedstock access rather than scale alone.
| Leading Market Players |
|---|
| Namo eWaste Management Ltd |
| Ganesha Ecosphere |
| Gravita India Ltd |
| Jain Resource Recycling Ltd |
| The Shakti Plastics Industries |
| Eco Recycling Ltd |
| Banyan Nation |
| Binbag Recycling |
| Antony Waste Handling Cell Ltd |
| Others |
Pricing and Supply Chain Analysis
Forty-five to sixty days of post-consumer PET bale inventory accumulation in Maharashtra and Gujarat processing clusters directly concentrates pricing power among integrated operators with captive collection networks, while compressing margins for spot-market-dependent mechanical recyclers when virgin resin arbitrage widens.
Pricing Analysis
Three-tier pricing structure across BIS-certified premium, standard mechanical, and uncertified economy resin grades separates municipal contract offtake from spot market transactions. Price differentiation hinges on melt flow index compliance and CPCB material flow certificate traceability. Cost compression in standard-grade mechanical recycling is intensifying because pyrolysis-based chemical alternatives approach fossil-naphtha parity. FMCG brand owners with rigid packaging commitments demonstrate least price sensitivity; small flexible packaging converters in tier-2 cities exhibit highest sensitivity.
Supply Chain Analysis
Inbound logistics costs from eastern and northeastern states to western processing clusters impose fifteen-to-twenty percent cost penalties due to container availability constraints at Kolkata and Visakhapatnam ports versus Jawaharlal Nehru Port Trust throughput advantages. Feedstock supply concentrates in Maharashtra, Gujarat, and Tamil Nadu, with Odisha and West Bengal emerging as greenfield collection frontiers. Raw material dependencies include post-consumer PET bales, mixed polymer waste streams, and lead-acid battery scrap. Single-source vulnerability to informal aggregator displacement by municipal concession awards threatens feedstock security. Distribution runs through registered recycler networks to BIS-certified packaging converters and petrochemical offtake agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mechanical recycling capacity saturation in western India fragments competitive returns, creating white-space opportunities as chemical conversion technologies and eastern state greenfield development absorb capital rotation.
For Market Incumbents: Fortify collection network control through exclusive municipal concession renewals in Ahmedabad and Pune, and accelerate BIS certification investment ahead of packaging waste rule compliance deadlines. Pyrolysis-based chemical recycling entrants threaten mechanical resin offtake; backward integration into source-segregation contracts is the defensive priority. For New Entrants and Emerging Players: Differentiate on licensed precious metal recovery from printed circuit boards under State Pollution Control Board norms, or on chemical recycling deployment in coastal refinery corridors. Eastern state municipal contracts in Odisha and West Bengal offer the most penetrable geography with single-window clearance schemes and negligible organized competition. Lead with decade-long concession bids guaranteeing landfill diversion rates. For Investors and Strategic Acquirers: Carve-out targets emerge from petrochemical majors spinning off non-core pyrolysis pilot assets, and from family-owned mechanical recyclers lacking succession capital for BIS compliance investment. Five-to-ten year viability favors operators with captive feedstock and licensed processing depth over pure trading plays. Watch whether chemical recycling yields achieve sustained fossil-naphtha parity as the inflection signal for mechanical capacity obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collection Networks | Exclusive municipal concessions in Maharashtra and Gujarat lock in captive feedstock supply. |
| Chemical Recycling Capacity Deployment | Pyrolysis units at Dahej and Hazira coastal corridors attract Reliance and Indian Oil integration. |
| BIS Certification Investment | Post-consumer resin validation opens rigid packaging offtake under evolving waste rules. |
| Eastern State Greenfield Expansion | Odisha and West Bengal single-window clearances bypass western infrastructure saturation. |
| Precious Metal Recovery Licensing | State Pollution Control Board dismantling permits enable gold and palladium extraction margins. |
Research Methodology
A spread of perspectives from municipal solid waste officers, integrated waste management firm operations directors, BIS certification auditors, CPCB compliance officers, and petrochemical procurement leads converged on the working assumptions. Secondary validation drew from CPCB material flow portal disclosures, Maharashtra and Gujarat Pollution Control Board consent records, municipal concession tender documents, and customs scrap metal trade data. Bottom-up installed capacity estimates and top-down consumption projections were triangulated.
Segmentation dimensions modeled encompass material type, collection method, end user category, and processing technology across the analysis window. Plastic, metal, glass, and paper material flows were cross-referenced with door-to-door, drop-off, curbside, and community bin collection economics. CAGR derivation incorporated feedstock availability curves, regulatory compliance cost trajectories, and petrochemical offtake agreement pricing.
Decision-makers should treat outputs as directional under assumptions of sustained EPR enforcement intensity and pyrolysis yield progression; material deviation would warrant model refresh. Forecasts reflect base-case regulatory timelines and chemical recycling commercialization assumptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Retail Food Waste-to-Biogas Logistics and Treatment Networks in Europe Market
Waste Management & Pollution Control
Smart Waste Sorting Bin Market
Waste Management & Pollution Control
APAC Bio-Medical Waste Management Market
Waste Management & Pollution Control
Asia-Pacific Waste Management Market
Waste Management & Pollution Control
UAE Biomedical Waste Management Market
Waste Management & Pollution Control
Waste Compactor Bins Market
Waste Management & Pollution Control
Landfill Compactor Market
Waste Management & Pollution Control
North America Bio-Medical Waste Management Market
Waste Management & Pollution Control
Construction Waste Market
Waste Management & Pollution Control
Animal Waste Incinerator Market
Waste Management & Pollution Control
Biomedical Waste Management Market
Waste Management & Pollution Control
Radioactive Waste Management System Market
Waste Management & Pollution Control
North America Solid Waste Management Market
Waste Management & Pollution Control
Saudi Arabia Medical Waste Management Market
Waste Management & Pollution Control
Reusable Sediment Control Wattles Market
Waste Management & Pollution Control
UAE Industrial Waste Management Market