
 Radioactive Waste Management System Market | 2026-2036
Radioactive Waste Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Radioactive Waste Management System Market Insights
ISO 19443 certification for nuclear quality management is collapsing the supplier base to a handful of qualified integrators. Orano leverages its vertically integrated fuel cycle capabilities to dominate European repository services. Bechtel Corporation anchors North American demand through its engineering-scale project execution at the Waste Isolation Pilot Plant and Savannah River Site. EnergySolutions competes on geographic coverage, sustaining treatment and disposal access across multiple US Department of Energy complexes.
A radioactive waste management system encompasses the engineered infrastructure, processes, and services required to characterize, treat, condition, transport, and isolate radioactive materials, with specifications typically requiring containment integrity verified over 300-year to 10,000-year horizons depending on waste classification. The system's primary purpose is to prevent radionuclide release into the biosphere while enabling continued operation of nuclear power generation, medical isotope production, and research activities. Storage solutions and disposal methods together capture the dominant value pool, though plasma treatment is expanding fastest as utilities seek volume reduction for intermediate-level waste streams. Deep geologic repositories remain the most capital-intensive technology category, with above-ground storage continuing to absorb operating expenditure from utilities awaiting permanent disposal pathways.
The US Nuclear Regulatory Commission and the EPA jointly govern commercial low-level waste disposal through 10 CFR Part 61 and environmental standards under 40 CFR Part 191, while the EU F-Gas Regulation and national nuclear safety authorities such as ASN in France shape European facility licensing timelines. These frameworks directly determine project approval durations, technology qualification requirements, and cross-border shipment permissions. Stakeholders must monitor repository siting decisions in Finland, Sweden, and Canada as these projects establish precedent for long-term liability transfer structures and contractor qualification benchmarks.
Market Dynamics
Deep geologic repository licensing timelines are compressing procurement cycles for treatment infrastructure as Finland's Onkalo facility and Sweden's Forsmark site establish operational precedents that utilities elsewhere must match.
Growth Catalysts
- Decommissioning schedules:Nuclear power plant operators in France and Japan are accelerating dismantlement of aging reactor fleets, generating sustained demand for intermediate-level waste conditioning and transport casks.
- 10 CFR Part 61:The US regulatory framework for low-level waste disposal is tightening waste classification standards, forcing utilities to upgrade treatment systems or face shipment restrictions to existing burial sites.
- Plasma arc treatment:Volume reduction technology for organic resins and ion-exchange media is achieving regulatory acceptance in multiple jurisdictions, displacing cement solidification for certain waste streams.
Market Restraints
- Repository siting paralysis:Political opposition and intergenerational liability concerns have stalled permanent disposal pathways in Germany, Italy, and the United Kingdom, forcing indefinite above-ground storage.
- Stainless steel and copper:Corrosion-resistant canister materials face price volatility and concentrated supply from Nordic and Japanese metallurgical producers, squeezing fabrication margins.
- Cross-border shipment permissions:The EU F-Gas Regulation and national nuclear safety authority protocols create multi-year approval timelines for transnational waste transport, fragmenting service markets.
Strategic Opportunities
- Small modular reactors:Emerging reactor designs in Canada and the United Kingdom generate distinct waste profiles requiring tailored treatment and packaging solutions not served by legacy light-water reactor infrastructure.
- ISO 19443 certification:The nuclear quality management standard creates qualification barriers that certified integrators can leverage to capture long-term service contracts from national waste management organizations.
- Medical isotope production:Cyclotron and research reactor facilities in Belgium and the Netherlands produce short-lived radioactive waste streams demanding specialized decay-storage and disposal services outside utility-centric supply chains.
Industry Challenges
- Welding and non-destructive examination:Canister fabrication and sealing operations require certified personnel pools that have aged out in multiple countries without adequate replacement pipelines.
- Legacy cementation plant retrofits:Existing solidification facilities face obsolescence as waste acceptance criteria tighten, yet brownfield upgrades compete with greenfield plasma treatment investments for limited capital allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radioactive Waste Management System Market |
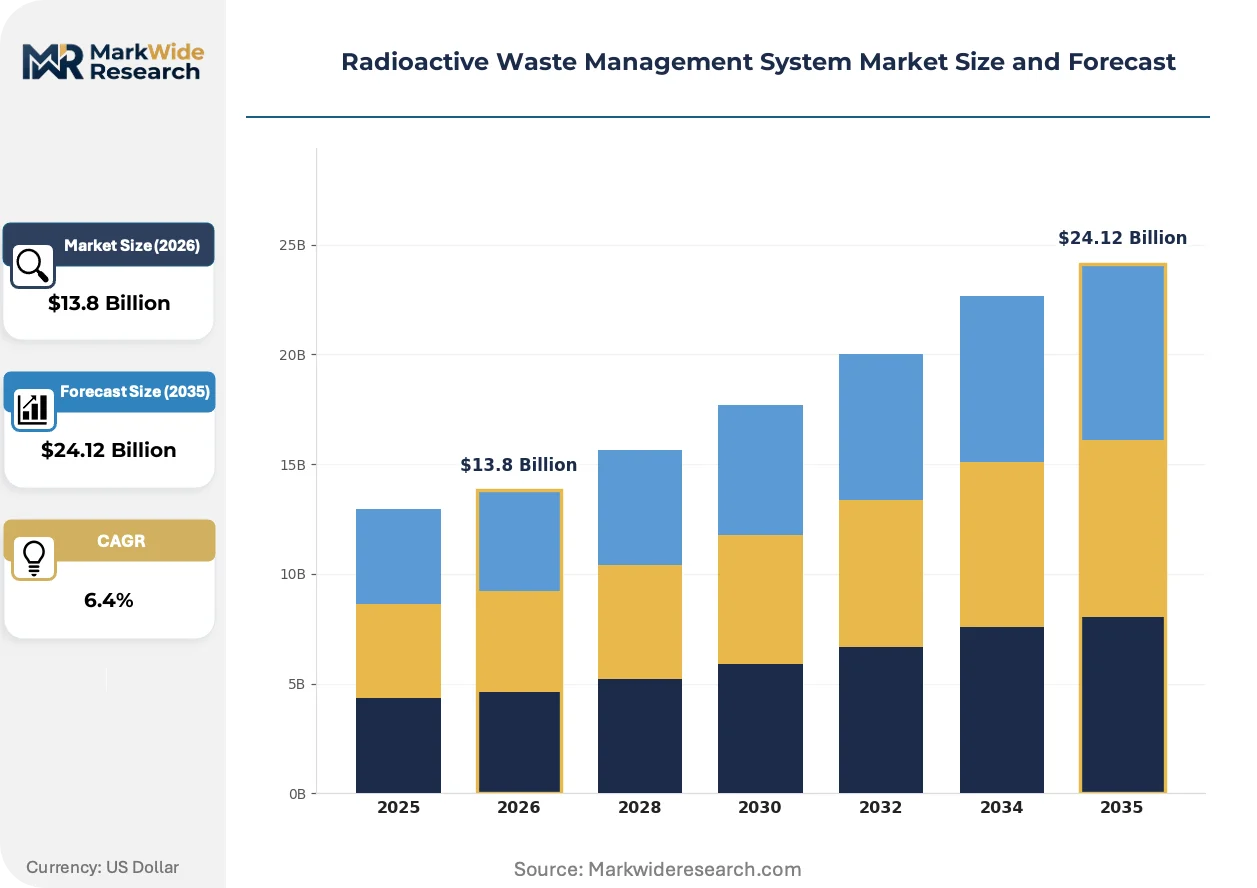
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $24.12 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Storage Solutions, Disposal Methods, Treatment Technologies, Transportation Services Application: Nuclear Power Plants, Medical Facilities, Research Institutions, Industrial Applications Technology: Deep Geologic Repositories, Above-ground Storage, Plasma Treatment, Cement Solidification End User: Government Agencies, Private Sector, Non-profit Organizations, Regulatory Bodies |
| Companies Covered | Veolia Environmental Services, EnergySolutions, Bechtel Corporation, Fluor Corporation, Orano, Perma-Fix Environmental Services, Inc., US Ecology, Inc., Jacobs Engineering Group Inc., Svensk Kärnbränslehantering AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radioactive Waste Management System Market Trends and Innovations
Repository engineering is converging with digital twin technology and advanced materials science to extend containment integrity verification horizons from centuries to millennia, reshaping contractor capability requirements.
Supercontainer designs incorporating bentonite buffer systems are fragmenting the engineered barrier market as Finland's Posiva and Sweden's SKB validate copper-steel composite canisters for high-level waste isolation. National waste management organizations in Switzerland and Canada are adapting these specifications for their own crystalline rock and clay repository concepts. The technology is compressing demand for simpler concrete vault storage as utilities anticipate direct disposal pathways.
The EU F-Gas Regulation is phasing out sulfur hexafluoride used in switchgear and particle accelerators, redirecting decommissioning waste streams toward specialized treatment facilities capable of capturing and neutralizing fluorinated compounds. Medical and research facilities across France, Germany, and the Netherlands face accelerated equipment replacement cycles. Treatment providers are scaling adsorption and thermal destruction capacity to handle the incoming volume.
Consolidated procurement by national waste management organizations is displacing fragmented utility-level contracting for repository construction and operation. SKB in Sweden and Ontario Power Generation in Canada now bundle engineering, construction, and century-scale monitoring into single-source agreements. This concentration is most visible in Nordic markets where state-owned entities control the entire back-end fuel cycle.
Radioactive Waste Management System Market Segmentation
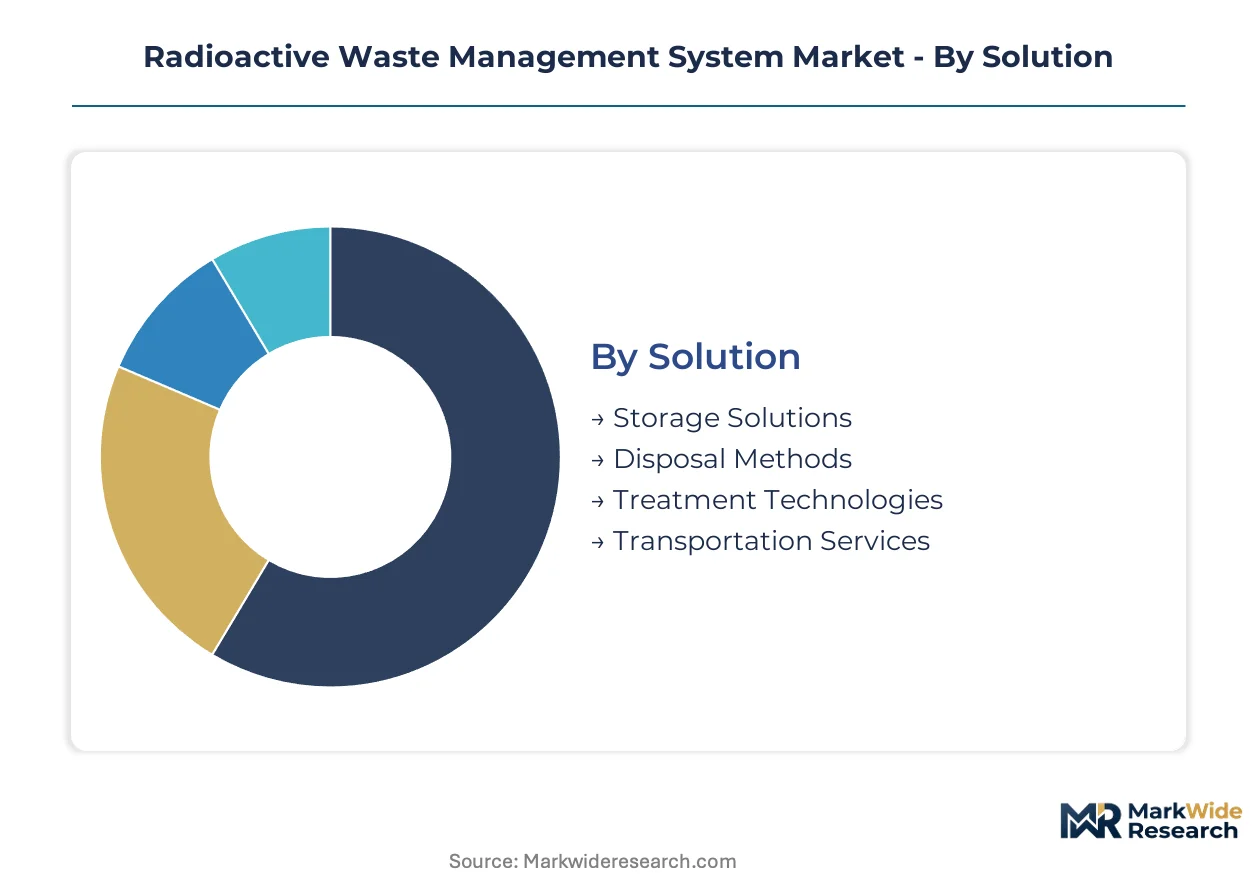
Radioactive waste management systems fragment across four distinct dimensions that determine procurement patterns and technology selection. Solution type governs capital allocation between treatment infrastructure and long-term containment. Application and technology categories reveal where regulatory pressure and volume concentration intersect.
Solution:
Storage Solutions face intensifying substitution pressure from advanced treatment technologies that reduce final disposal volumes.
- Storage Solutions:Engineered containment systems including dry cask storage and shielded vaults designed for interim holding periods. Demand concentrates at nuclear power plants in France and Japan where decommissioning schedules have accelerated, forcing utilities to secure additional cask capacity while awaiting permanent disposal pathways.
- Disposal Methods:Permanent isolation systems encompassing deep geologic repositories and near-surface engineered facilities. Finland's Onkalo facility and Sweden's Forsmark site are establishing operational precedents that national waste management organizations in Canada and Switzerland are adapting for their own crystalline rock concepts.
- Treatment Technologies:Volume reduction and conditioning processes including compaction, incineration, and chemical separation.
- Transportation Services:Licensed cask design, logistics coordination, and cross-border shipment execution.
Storage Solutions anchors the volume base while Treatment Technologies gains share at the steepest rate.
Application:
Cost tier differentiation separates high-volume utility procurement from specialized medical and research facility contracting.
- Nuclear Power Plants:Commercial reactor operators generating spent fuel and operational waste streams requiring comprehensive back-end services. Procurement in the United States tightens under 10 CFR Part 61 classification standards, compelling utilities to upgrade conditioning systems or face burial site access restrictions.
- Medical Facilities:Cyclotron and radiopharmaceutical production sites generating short-lived isotope waste. Belgium and the Netherlands facilities demand specialized decay-storage services outside utility-centric supply chains as production scales to serve diagnostic imaging markets.
- Research Institutions:University and government laboratory complexes with diverse waste chemistries and lower volume profiles.
- Industrial Applications:Manufacturing and materials testing operations using sealed sources and radiography equipment.
Nuclear Power Plants anchors the volume base while Medical Facilities climbs the fastest as isotope production expands.
Technology:
Maturity gradients separate proven near-term options from capital-intensive long-duration repository projects.
- Deep Geologic Repositories:Multi-barrier isolation systems in stable geological formations with engineered bentonite buffer and copper-steel canister designs. SKB in Sweden and Posiva in Finland validate specifications that Ontario Power Generation and Switzerland's Nagra are adapting for their respective clay and crystalline rock concepts.
- Above-ground Storage:Interim surface facilities including concrete vaults and shielded buildings. Political opposition in Germany, Italy, and the United Kingdom has stalled permanent pathways, forcing indefinite reliance on these systems despite intergenerational liability concerns.
- Plasma Treatment:Thermal destruction technology for organic resins and ion-exchange media achieving regulatory acceptance.
- Cement Solidification:Conventional immobilization process for low-level waste streams facing obsolescence as acceptance criteria tighten.
Above-ground Storage anchors the volume base while Plasma Treatment expands most quickly as utilities seek volume reduction for intermediate-level streams.
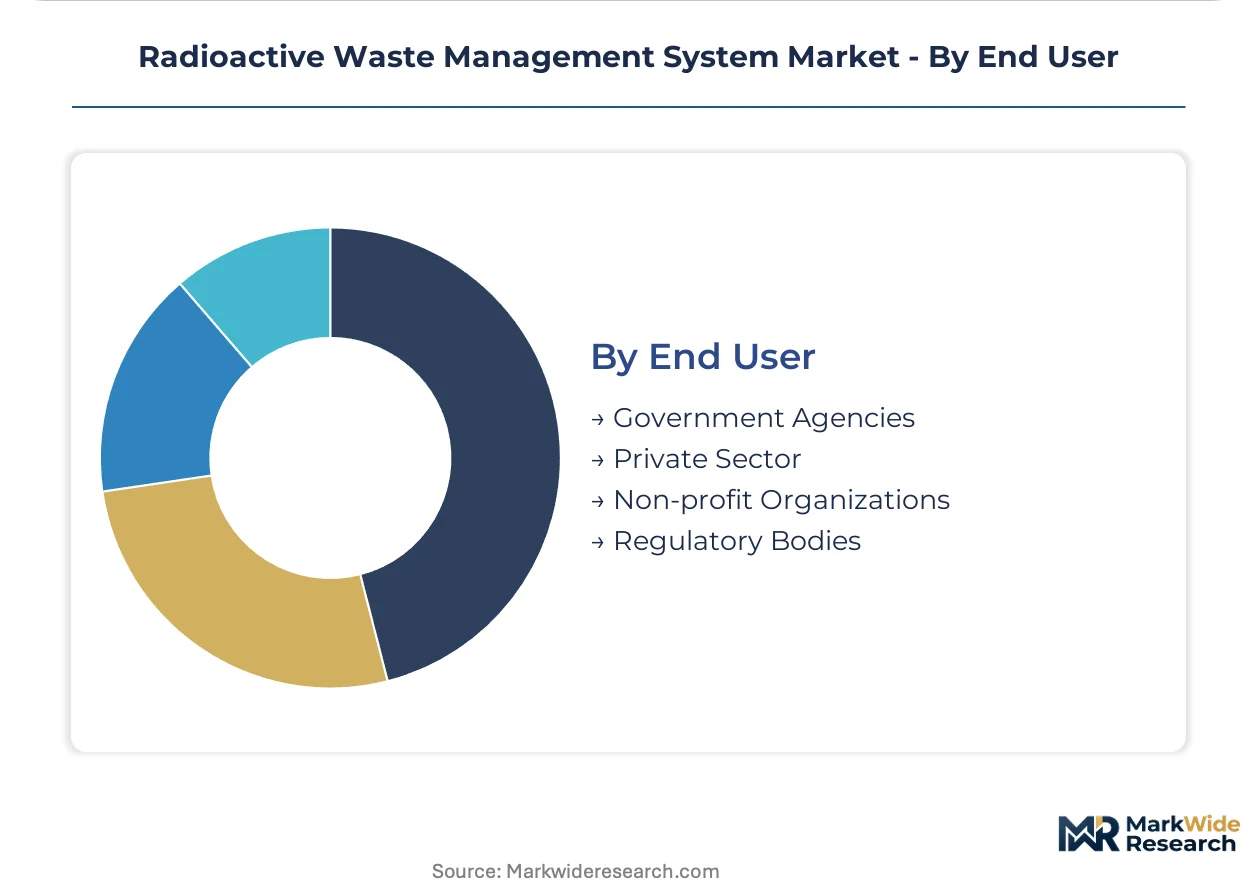
End User:
Customer type determines contract structure from century-scale government procurement to discrete commercial service agreements.
- Government Agencies:National waste management organizations and department of energy complexes bundling engineering, construction, and monitoring into single-source agreements. The US Department of Energy sustains treatment and disposal access across multiple sites through consolidated procurement.
- Private Sector:Commercial nuclear operators and industrial licensees contracting discrete treatment and transport services. ISO 19443 certification creates qualification barriers that certified integrators leverage for long-term service contracts.
- Non-profit Organizations:Research consortiums and international scientific facilities with specialized waste profiles.
- Regulatory Bodies:Oversight agencies defining waste acceptance criteria and licensing standards rather than direct procurement.
Government Agencies anchors the volume base while Private Sector gains share at the steepest rate as commercial decommissioning accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Repository licensing momentum in Finland and Sweden is compressing procurement timelines for treatment infrastructure as national waste management organizations elsewhere race to match operational precedents. The US Nuclear Regulatory Commission's tightening standards under 10 CFR Part 61 are forcing utilities to upgrade conditioning systems or face burial site restrictions. Japan's accelerated decommissioning schedule is generating sustained demand for intermediate-level waste casks and transport services.
United States
Commercial reactor operators are expanding procurement of dry cask storage capacity as decommissioning schedules accelerate across the aging fleet. The EPA's environmental standards under 40 CFR Part 191 govern permanent disposal pathways while the Department of Energy sustains treatment access across multiple complexes through consolidated procurement. Engineering-scale project execution concentrates at the Waste Isolation Pilot Plant in New Mexico and Savannah River Site in South Carolina.
Finland
Posiva's Onkalo facility is establishing the world's first operational deep geologic repository for spent nuclear fuel, validating copper-steel composite canister designs with bentonite buffer systems. The national nuclear safety authority STUK has licensed construction and operation phases that compress demand for specialized engineering and construction services. Repository development concentrates in Eurajoki near the Olkiluoto nuclear power plant cluster.
Sweden
SKB's Forsmark site is advancing toward operational status with supercontainer designs that fragment the engineered barrier market across crystalline rock formations. The Swedish Radiation Safety Authority has approved licensing phases that create concentrated demand for canister fabrication and sealing operations. Repository construction activity centers in Östhammar Municipality alongside existing nuclear infrastructure.
France
Orano leverages vertically integrated fuel cycle capabilities to dominate repository services as the national waste management agency ANDRA advances the Cigéo deep geologic project in Meuse/Haute-Marne. The Autorité de Sûreté Nucléaire shapes facility licensing timelines that determine contractor qualification benchmarks. Treatment and conditioning infrastructure concentrates at La Hague in Normandy and Marcoule in the Gard region.
Canada
Ontario Power Generation is adapting Nordic repository specifications for its deep geologic repository concept in crystalline rock, bundling engineering, construction, and century-scale monitoring into single-source agreements. The Canadian Nuclear Safety Commission governs waste acceptance criteria that influence technology selection. Nuclear waste management activity concentrates in Ontario with the Bruce, Darlington, and Pickering reactor sites.
Radioactive Waste Management System Market Competitive Landscape
Player mix skews toward vertically integrated nuclear service conglomerates and specialized environmental contractors with regulatory certification depth. The supplier base collapses around a handful of qualified integrators holding ISO 19443 certification for nuclear quality management. Two strategic archetypes dominate: fuel cycle operators with captive repository capabilities, and engineering-construction firms with government complex execution experience. Competitive moves center on qualification barrier leverage for long-term service contracts and geographic coverage expansion across multiple regulatory jurisdictions.
Within the integrated fuel cycle tier, Orano exemplifies repository service dominance through backward integration into waste conditioning and canister fabrication. Among North American engineering specialists, Bechtel Corporation and Fluor Corporation occupy positions anchored to Department of Energy complex execution and large-scale project delivery. EnergySolutions represents the geographic coverage archetype, sustaining treatment and disposal access across multiple regulatory jurisdictions through certified facility networks. Jacobs Engineering Group Inc. sits within the technical services tier, supporting decommissioning and waste characterization programs.
| Leading Market Players |
|---|
| Veolia Environmental Services |
| EnergySolutions |
| Bechtel Corporation |
| Fluor Corporation |
| Orano |
| Perma-Fix Environmental Services, Inc. |
| US Ecology, Inc. |
| Jacobs Engineering Group Inc. |
| Svensk Kärnbränslehantering AB |
| Others |
Pricing and Supply Chain Analysis
Plasma arc treatment displacing cement solidification in intermediate-level waste streams is redrawing procurement geography toward Nordic and Japanese metallurgical suppliers while compressing fabrication margins on corrosion-resistant canister materials. This substitution dynamic simultaneously elevates pricing power for qualified copper-steel composite fabricators and squeezes legacy cementation plant operators unable to meet tightening waste acceptance criteria.
Pricing Analysis
Certification level (ISO 19443-grade) creates the primary spread between premium repository integrators and standard treatment contractors, with three-tier pricing structure across certified, qualified, and provisional vendor tiers. Project-based long-term contracting dominates as national waste management organizations bundle engineering, construction, and century-scale monitoring into single-source agreements. Cost compression in provisional-tier cement solidification services is intensifying because utilities await permanent disposal pathways. Government agencies exhibit lowest price sensitivity due to liability transfer imperatives, while private sector utilities face acute pressure from burial site access restrictions.
Supply Chain Analysis
Strategic stockpiling of copper and stainless steel canister materials prevails over just-in-time approaches given multi-year fabrication cycles and concentrated Nordic and Japanese metallurgical supply. Finland, Sweden, and Canada anchor engineered barrier production for deep geologic repository programs. Raw material dependencies center on corrosion-resistant alloys, bentonite buffer materials, and specialized welding consumables. Single-source vulnerability in qualified canister fabrication creates structural risk as certified personnel pools age out without replacement pipelines. Distribution runs through national waste management organization procurement offices rather than open market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The radioactive waste management system market is recovering from repository siting paralysis as Finland's Onkalo and Sweden's Forsmark establish operational precedents that compress procurement timelines elsewhere. Decommissioning schedule acceleration across aging reactor fleets in France, Japan, and the United States provides the cyclical impetus.
For Market Incumbents: Fortify qualification barrier leverage by deepening backward integration into copper-steel canister fabrication and bentonite buffer supply chains. Orano's captive fuel cycle capabilities demonstrate how in-house production of engineered barriers captures repository service margins. Incumbents must also defend against plasma treatment specialists achieving regulatory acceptance for volume reduction services by accelerating ISO 19443 certification investments before competitor qualification windows close. For New Entrants and Emerging Players: Anchor in medical isotope production waste services outside utility-centric supply chains, where cyclotron and research reactor facilities in Belgium and the Netherlands generate short-lived radioactive waste streams demanding specialized decay-storage solutions. This segment remains underpenetrated by integrated fuel cycle operators focused on commercial reactor back-ends. A go-to-market angle emphasizing rapid regulatory approval for fluorinated compound treatment under EU F-Gas Regulation phase-out timelines offers fastest path to revenue. For Investors and Strategic Acquirers: Secondary-cycle assets sit with engineering-construction firms holding Department of Energy complex execution experience but lacking fuel cycle integration. Long-term viability across the analysis window hinges on exposure to repository construction pipelines rather than indefinite above-ground storage reliance. Watch Finland's STUK and Sweden's SSK licensing pace as the signal for when contractor qualification benchmarks compress procurement concentration further.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 19443 Certification Investment | Qualification barriers collapse supplier base to certified integrators eligible for national waste management organization contracts. |
| Deep Geologic Repository Licensing | Finland's Onkalo and Sweden's Forsmark precedents compress procurement timelines for treatment infrastructure elsewhere. |
| Plasma Treatment Capacity Expansion | Volume reduction technology achieves regulatory acceptance displacing cement solidification for organic resin waste streams. |
| Copper-Steel Canister Fabrication Scale-Up | Supercontainer designs with bentonite buffer systems fragment engineered barrier market across crystalline rock formations. |
| Medical Isotope Waste Service Entry | Cyclotron facilities in Belgium and Netherlands demand specialized decay-storage outside utility supply chains. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with repository program directors, nuclear safety authority licensing officers, waste conditioning plant managers, and national waste management organization procurement leads; and secondary validation through IAEA waste management databases, national regulatory filings with STUK, ASN, and the US Nuclear Regulatory Commission, OECD Nuclear Energy Agency reports, and company disclosures. Bottom-up project pipeline enumeration triangulated against top-down national decommissioning schedule aggregates.
Across the projection horizon, the analytical framework modeled solution type, application category, technology maturity tier, and end-user procurement structure segmentation dimensions. CAGRs derived from facility commissioning timelines, repository licensing pace, and treatment technology adoption curves. Industry-specific forecast inputs incorporated 10 CFR Part 61 classification standard revisions and EU F-Gas Regulation phase-out schedules.
Material uncertainties — repository siting political opposition, intergenerational liability framework changes, and qualified welding personnel replacement rates — sit outside the modeled envelope. Forecasts reflect assumptions regarding STUK and SSK licensing continuity. Revision becomes warranted when cross-border shipment permission timelines under EU F-Gas Regulation extend beyond current multi-year baselines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
North America Industrial Waste Management Market
Waste Management & Pollution Control
Metal Recycling Baler Market
Waste Management & Pollution Control
Waste Paper Management Market
Waste Management & Pollution Control
Singapore Waste Management Market
Waste Management & Pollution Control
North America Trash Bags Market
Waste Management & Pollution Control
Marine Waste Handling Equipment Market
Waste Management & Pollution Control
Wheeled Bins Market
Waste Management & Pollution Control
US Medical Waste Management Market
Waste Management & Pollution Control
Landfill Gas Market
Waste Management & Pollution Control
Compostable and Biodegradable Refuse Bags Market
Waste Management & Pollution Control
India Plastic Waste Management Market
Waste Management & Pollution Control
Reusable Sediment Control Wattles Market
Waste Management & Pollution Control
Global Smart Trash Bin Market
Waste Management & Pollution Control
Europe Industrial Waste Management Market
Waste Management & Pollution Control
Hazardous Waste Management Market
Waste Management & Pollution Control
India E-Waste Management Market