
 Europe Waste Management Market | 2026-2036
Europe Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Waste Management Market Insights
Skilled landfill engineering talent is collapsing across Eastern Europe just as capacity expansion accelerates. Veolia leverages its incineration technology leadership to dominate French metropolitan contracts. REMONDIS anchors German industrial waste streams through backward integration into sorting and metal recovery. SUEZ competes aggressively on municipal tenders in Iberia and Italy.
Europe waste management encompasses the collection, transport, treatment, and disposal of solid, liquid, and gaseous refuse through mechanical sorting, thermal oxidation, biological decomposition, and secure landfill containment with leachate recovery systems. Its primary purpose is to minimize environmental contamination while recovering secondary raw materials and energy vectors for reinsertion into industrial loops. Collection services command the largest revenue pool given their recurring contracted nature and municipal budget priority, while thermal treatment margins expand fastest as emission controls tighten and energy output qualifies for green certificates. E-waste processing represents the fastest-growing waste type segment as WEEE directives broaden producer responsibility and precious metal recovery economics improve.
The EU Green Deal, REACH, and F-Gas Regulation collectively mandate higher material recovery rates, stricter emission thresholds, and phased landfill diversion targets that reshape capital allocation across the sector. ECHA chemical hazard classifications and CE marking requirements for treatment equipment raise compliance costs for new market entrants. Stakeholders must monitor how the CSRD extends disclosure obligations to waste service providers and whether national transpositions of the EU AI Act affect automated sorting investment timelines.
Market Dynamics
Landfill capacity constraints across Eastern Europe are forcing capital reallocation toward thermal treatment infrastructure, while EU Green Deal circular economy mandates compress disposal windows and elevate material recovery economics.
Growth Catalysts
- EU Green Deal landfill diversion targets:National governments in Germany and France are accelerating incinerator permitting to meet phased reduction deadlines. Municipal budgets are prioritizing collection service expansion.
- WEEE directive precious metal recovery:E-waste processing economics are improving as automated dismantling technologies reduce labor costs. Producer responsibility schemes are broadening feedstock access.
- Benelux industrial waste concentration:Chemical and pharmaceutical manufacturing clusters in Belgium and the Netherlands are generating high-calorific refuse streams. Specialized treatment providers are securing long-term offtake contracts.
Market Restraints
- Skilled landfill engineering scarcity:Eastern European labor markets lack certified geotechnical specialists. Capacity expansion projects face recruitment bottlenecks.
- CE marking compliance costs:ECHA chemical hazard classifications and treatment equipment certification requirements raise barriers for new equipment suppliers.
- Energy price volatility:Incinerator revenue models depend on electricity and heat sales. Wholesale market fluctuations compress margin predictability.
Strategic Opportunities
- Polish and Romanian landfill modernization:EU cohesion funds are financing leachate recovery and gas capture retrofits. Private operators can secure build-operate-transfer concessions.
- AI-act automated sorting investment:Machine vision and robotic separation technologies are qualifying for green transition financing. National transposition timelines will determine first-mover advantage.
- Industrial symbiosis platforms:Cross-sector waste exchange networks in the Netherlands are redirecting byproduct streams to adjacent manufacturers. Digital matching platforms reduce transaction friction.
Industry Challenges
- CSRD disclosure preparation:Extended corporate sustainability reporting obligations require waste service providers to implement granular emissions tracking. Audit-ready data systems demand significant IT investment.
- Legacy landfill remediation liability:Historical disposal sites across Italy and Spain require costly containment upgrades. Operators face uncertain cost recovery through tariff mechanisms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Waste Management Market |
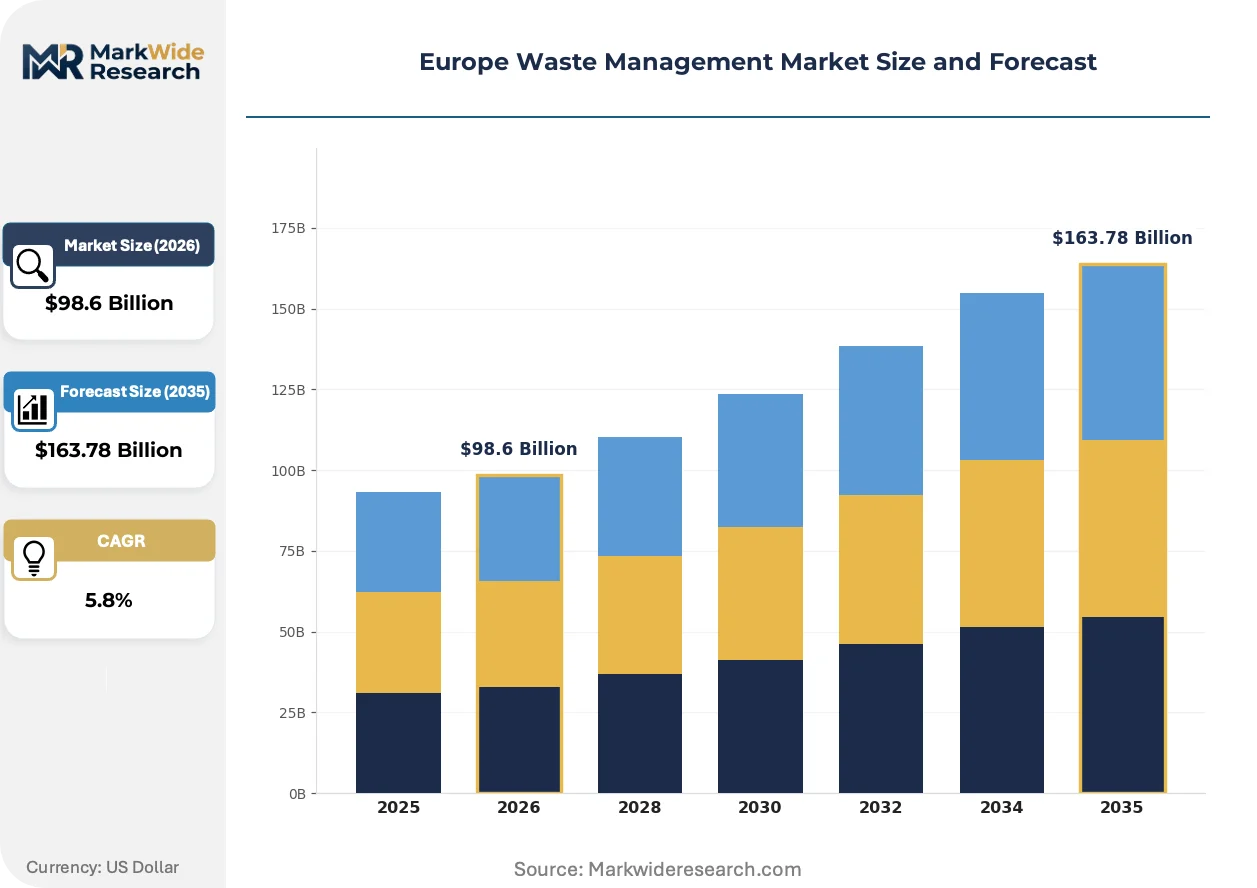
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $163.78 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Collection, Treatment, Disposal, Recycling Waste Type: Municipal, Industrial, Hazardous, E-waste Technology: Composting, Thermal Treatment, Anaerobic Digestion, Landfill End User: Households, Businesses, Governments, NGOs |
| Companies Covered | Veolia, SUEZ, Biffa, REMONDIS, Rentokil Initial, SembCorp, Waste Management Inc., Clean Harbors, Stericycle, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Waste Management Market Trends and Innovations
Digital thread technologies are penetrating waste logistics, while regulatory pressure on emission transparency and material provenance is reconfiguring competitive requirements across collection and treatment segments.
Robotic sorting systems employing near-infrared spectroscopy and AI-driven material recognition are fragmenting traditional manual separation economics. MRF operators in France and Germany are retrofitting lines to handle heterogeneous packaging streams. The technology is fragmenting incumbent equipment supplier relationships as specialized robotics vendors bypass conventional machinery channels.
REACH substance restriction expansions and F-Gas Regulation phase-down schedules are tightening hazardous waste classification thresholds. Industrial generators in the Benelux corridor are consolidating treatment contracts with certified specialists. Chemical sector facilities are most affected, accelerating investment in on-site pre-treatment capacity to reduce disposal cost exposure.
Performance-guaranteed service contracts are displacing unit-rate pricing in municipal procurement. French and Spanish cities are tendering collection operations with penalty clauses for contamination rates and recycling yield shortfalls. This shift is most visible in metropolitan regions where political accountability for circular economy targets intensifies contract scrutiny.
Europe Waste Management Market Segmentation
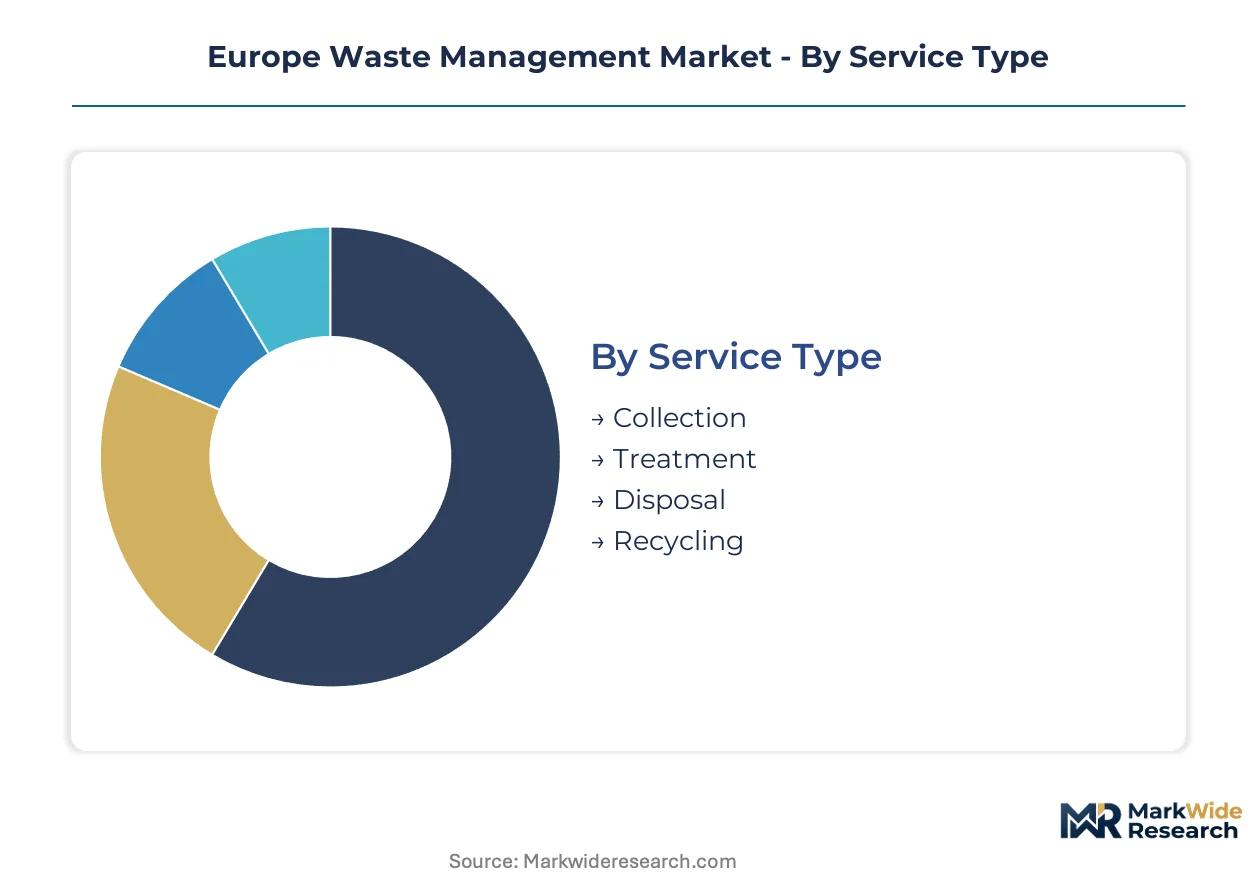
Segmentation in European waste management reveals how regulatory pressure and infrastructure maturity create divergent competitive arenas. Service providers must align capabilities with specific waste streams, treatment technologies, and end-user contracting patterns to capture value across fragmented national markets.
Service Type:
Substitution pressure runs strongest against Disposal services as landfill diversion mandates and thermal treatment economics erode traditional containment revenue models.
- Collection:Door-to-door refuse pickup and containerized aggregation services operate under recurring municipal contracts with tariff-indexed pricing. German and French metropolitan governments are expanding collection zones to meet EU Green Deal circular economy targets while integrating separate streams for organics and recyclables.
- Treatment:Mechanical sorting, chemical neutralization, and biological processing transform raw waste into secondary materials or stabilized residues. Benelux chemical and pharmaceutical clusters are concentrating demand for specialized industrial waste treatment through long-term offtake agreements with certified providers.
- Disposal:Secure landfill containment with leachate recovery and gas capture systems faces tightening capacity constraints across Eastern Europe. Polish and Romanian modernization projects rely on EU cohesion fund financing for environmental upgrades.
- Recycling:Material recovery facilities process paper, plastics, metals, and glass into feedstock for reinsertion into manufacturing loops. Automated sorting investments are qualifying for green transition financing under national transpositions of the EU AI Act.
Collection retains volume leadership; Recycling holds the steepest expansion curve.
Waste Type:
Cost tier differentiation separates high-margin hazardous streams from commoditized municipal flows with regulated tariff ceilings.
- Municipal:Household-generated mixed refuse and separately collected recyclables constitute the baseline volume pool. French and Spanish cities are tendering collection operations with penalty clauses for contamination rates and recycling yield shortfalls.
- Industrial:Manufacturing byproducts from chemical, pharmaceutical, and food processing operations require tailored treatment protocols. REACH substance restriction expansions are tightening hazardous classification thresholds and consolidating treatment contracts with certified specialists.
- Hazardous:Flammable, toxic, corrosive, or reactive wastes demand specialized handling, transport, and thermal destruction or secure containment. F-Gas Regulation phase-down schedules are accelerating investment in on-site pre-treatment capacity to reduce disposal cost exposure.
- E-waste:Discarded electrical and electronic equipment containing recoverable precious metals and rare earth elements. WEEE directive producer responsibility schemes are broadening feedstock access while automated dismantling technologies reduce labor costs and improve recovery economics.
Municipal waste dominates transaction volumes; E-waste is climbing the fastest as precious metal recovery economics improve.
Technology:
Application requirements vary sharply between rural regions with available land for biological processing and dense urban centers where thermal treatment addresses space constraints.
- Composting:Aerobic biological decomposition of organic matter into soil amendments for agricultural and landscaping use. Separate organic collection mandates in Germany and France are expanding feedstock availability for centralized and on-site composting operations.
- Thermal Treatment:Incineration with energy recovery and advanced emission controls generating electricity and district heat. National governments are accelerating permitting timelines to meet phased landfill reduction deadlines under EU Green Deal mandates.
- Anaerobic Digestion:Oxygen-free bacterial breakdown of organic waste producing biogas for grid injection or vehicle fuel and digestate for fertilizer. Agricultural and food processing waste streams in rural France and Germany supply dedicated digestion facilities.
- Landfill:Engineered containment with composite liners, leachate collection, and methane capture for energy utilization. Skilled geotechnical engineering scarcity across Eastern Europe is creating recruitment bottlenecks for capacity expansion projects.
Landfill retains installed capacity leadership; Thermal Treatment is gaining share fastest as emission controls tighten and energy output qualifies for green certificates.
End User:
Customer type determines contract structure, with government procurement dominating volume and businesses commanding premium pricing for specialized industrial services.
- Households:Residential waste generators served through municipal tax-funded or subscription-based collection systems. Performance-guaranteed service contracts with contamination penalties are displacing unit-rate pricing in metropolitan French and Spanish procurement.
- Businesses:Commercial and industrial waste producers negotiating customized collection frequencies and treatment specifications. Industrial symbiosis platforms in the Netherlands are redirecting byproduct streams to adjacent manufacturers through digital matching systems.
- Governments:Public sector entities including municipalities, regional authorities, and national agencies operating waste infrastructure. CSRD disclosure obligations are requiring granular emissions tracking and audit-ready data systems with significant IT investment.
- NGOs:Non-governmental organizations managing community recycling programs, environmental education, and informal sector integration. Extended producer responsibility schemes under WEEE directives are creating partnership opportunities for e-waste collection networks.
Government contracts anchor volume; Business segments command the highest margin premiums for hazardous and specialized treatment services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Benelux industrial waste commands premium pricing against Eastern European landfill rates, creating a 40-60% cost spread that drives cross-border treatment arbitrage and capital migration toward thermal infrastructure.
Germany
Municipal collection expansion in Berlin and Hamburg integrates separate organics streams under EU Green Deal mandates. The Federal Environment Agency enforces stricter sorting purity standards for packaging waste. Industrial symbiosis networks in the Rhine-Ruhr corridor redirect chemical byproducts to adjacent manufacturers, reducing disposal volumes.
France
Metropolitan incinerator permitting accelerates in Paris and Lyon to meet phased landfill reduction deadlines. ANSM chemical hazard classifications tighten hazardous waste handling protocols. Veolia anchors French metropolitan contracts through technology leadership in energy recovery systems.
Netherlands
Chemical and pharmaceutical clusters in Rotterdam and Eindhoven generate high-calorific industrial refuse streams. REACH substance restrictions consolidate treatment contracts with certified specialists. Digital waste exchange platforms reduce transaction friction for cross-sector byproduct matching.
Poland
EU cohesion funds finance leachate recovery and gas capture retrofits at legacy landfill sites. The national environmental inspectorate raises containment standards for new capacity. Private operators secure build-operate-transfer concessions in Warsaw and Kraków metropolitan zones.
Italy
Performance-guaranteed municipal contracts with contamination penalties displace unit-rate pricing in Milan and Rome. CSRD disclosure obligations force granular emissions tracking on waste service providers. Southern regions face costly legacy landfill remediation liabilities with uncertain tariff recovery.
Europe Waste Management Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the European waste management sector. The market structure consolidates around three to five vertically integrated groups controlling thermal treatment infrastructure, while regional specialists capture municipal collection niches through localized operational density. Strategic archetypes divide into incineration technology leaders, landfill estate owners, and automated sorting innovators. Dominant competitive moves include backward integration into metal recovery streams and geographic expansion through concession bidding in Eastern European markets.
Within the integrated infrastructure tier, Veolia and SUEZ occupy positions as archetypal technology-scale hybrids, while REMONDIS exemplifies the German industrial waste specialist model. Veolia represents the incineration technology leader archetype through its metropolitan contract concentration. SUEZ sits within the aggressive tendering specialist category for Iberian and Italian municipal markets. REMONDIS anchors the backward-integrated industrial stream controller position through sorting and metal recovery capabilities.
| Leading Market Players |
|---|
| Veolia |
| SUEZ |
| Biffa |
| REMONDIS |
| Rentokil Initial |
| SembCorp |
| Waste Management Inc. |
| Clean Harbors |
| Stericycle |
| Others |
Pricing and Supply Chain Analysis
CE marking requirements and ECHA chemical hazard classifications simultaneously gate supplier qualification and stratify price tiers across treatment equipment procurement. Municipal buyers in Germany and France face elevated compliance costs that compress margin pools for uncertified vendors while rewarding established incineration technology providers with pricing power.
Pricing Analysis
Benelux industrial waste treatment rates command 40-60% premiums over Eastern European landfill disposal pricing. Contract-based long-term offtake agreements dominate high-calorific chemical refuse streams, while unit-rate municipal collection services face cost compression from contamination penalty clauses. Price differentiation stems from certification tier and geographic delivery cost. Margins are tightening in standard collection services due to CSRD compliance investments. Municipal governments exhibit highest price sensitivity; pharmaceutical manufacturers in Belgium and the Netherlands show lowest sensitivity due to regulatory non-negotiability.
Supply Chain Analysis
Germany and France anchor thermal treatment infrastructure manufacturing, while Poland and Romania concentrate landfill engineering capacity expansion. Equipment supply draws from specialized incinerator component fabricators in the Netherlands and automated sorting technology developers in Germany. Single-source vulnerability runs through AI-act automated sorting system suppliers awaiting national transposition clarity. Distribution runs through municipal procurement frameworks in metropolitan France and concession-based build-operate-transfer structures in Eastern Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified geotechnical engineering talent scarcity across Poland and Romania threatens capacity expansion timelines, creating acquisition premiums for qualified labor pools and automated technology substitutes.
For Market Incumbents: Fortify metropolitan contract positions in Paris and Lyon through energy recovery technology upgrades that meet ANSM emission thresholds. Anchor backward control over precious metal recovery streams from WEEE directive feedstocks to defend against specialized e-waste dismantling entrants. Prioritize CSRD disclosure system investments ahead of audit-ready data mandates. For New Entrants and Emerging Players: Anchor in Polish and Romanian landfill modernization projects where EU cohesion fund financing reduces capital barriers. Target industrial symbiosis platform development in the Netherlands where digital matching infrastructure remains underdeveloped. Pursue equipment-as-a-service models for AI-act qualifying automated sorting systems to bypass upfront certification cost disadvantages. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across thermal treatment infrastructure as emission control tightening accelerates replacement cycles. Long-term viability centers on vertically integrated operators controlling both feedstock access and energy offtake agreements. Monitor national transposition timelines for the EU AI Act as the signal for automated sorting investment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Metal Recovery | REMONDIS anchors German industrial streams through captive sorting and precious metal extraction capabilities. |
| Thermal Treatment Capacity Expansion | Veolia secures Paris and Lyon metropolitan contracts via incinerator permitting acceleration under EU Green Deal deadlines. |
| Automated Sorting Technology Deployment | Machine vision retrofitting in French MRFs fragments traditional manual separation economics. |
| Landfill Modernization Concessions | Private operators capture Warsaw and Kraków build-operate-transfer structures via EU cohesion fund leverage. |
| Industrial Symbiosis Platform Development | Netherlands chemical clusters reduce disposal volumes through digital byproduct matching to adjacent manufacturers. |
Research Methodology
Two parallel data streams informed the analysis: structured interviews with thermal treatment plant managers, municipal procurement officers, and ECHA compliance specialists; and secondary validation through EU Green Deal implementation tracking, national environmental inspectorate filings, and CE marking certification databases. Bottom-up segment sizing triangulated against top-down infrastructure capacity assessments across Germany, France, Netherlands, Poland, and Italy.
Across the projection horizon, the analytical framework modeled service type, waste stream composition, technology application, and end-user contracting pattern dimensions. CAGRs derived from installed capacity expansion timelines, regulatory mandate phase-in schedules, and feedstock availability projections. Forecast inputs incorporated EU cohesion fund disbursement trajectories and WEEE directive producer responsibility scheme coverage expansion.
Material uncertainties — regulatory transposition delays, energy price volatility, and skilled engineering labor availability — sit outside the modeled envelope. Forecasts reflect documented assumptions on permitting velocity and technology adoption curves. Recalibration cycles align with material shifts in EU AI Act national implementations and CSRD disclosure obligation enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Automated Waste Collection System (AWCS) Market
Waste Management & Pollution Control
India Waste-To-Energy Market
Waste Management & Pollution Control
Paper Recycling Market
Waste Management & Pollution Control
North America Waste Recycling Services Market
Waste Management & Pollution Control
Asia-Pacific Hazardous Waste Handling Automation Market
Waste Management & Pollution Control
Global Automated Marine Debris Collection Equipment Market
Waste Management & Pollution Control
Asia Pacific Medical Waste Management Market
Waste Management & Pollution Control
India Recycling Market
Waste Management & Pollution Control
Alkaline Solid Waste Market
Waste Management & Pollution Control
North America Municipal Solid Waste Management Market
Waste Management & Pollution Control
Industrial Solid Waste Management Market
Waste Management & Pollution Control
Landfill Gas Market
Waste Management & Pollution Control
Waste Sorting Equipment Market
Waste Management & Pollution Control
Metal Recycling Baler Market
Waste Management & Pollution Control
Landfill Compactor Market
Waste Management & Pollution Control
US Medical Waste Management Market