
 Construction Waste Management Market | 2026-2036
Construction Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Waste Management Market Analysis
European recycling infrastructure is shifting toward closed-loop material recovery systems. Veolia Environnement S.A. leverages its integrated treatment network across France and the United Kingdom to dominate complex waste streams. Waste Management Inc. anchors North American operations through dense transfer station networks. Remondis SE & Co. KG differentiates via specialized concrete processing capabilities in German industrial corridors.
Construction waste management encompasses the collection, transportation, processing, and disposal of debris generated from building, demolition, and renovation activities, typically involving materials with particle sizes ranging from fine aggregates to large structural components exceeding one cubic meter. The practice serves to divert inert and hazardous materials from landfills while recovering usable resources for secondary construction applications. Concrete and wood waste types command the largest volume pools due to demolition activity intensity, though metals recovery generates disproportionate margin contributions from scrap valorization. Recycling services are expanding faster than disposal as landfill levies escalate, while demolition-phase waste outpaces new construction debris in mature urban markets where building replacement cycles dominate.
The EPA regulates construction debris under Subtitle D of RCRA, while the EU Green Deal and REACH frameworks mandate minimum recycled content thresholds for public infrastructure projects. China's MEE enforces dual carbon goals that penalize excessive landfill disposal of construction materials. Stakeholders must monitor evolving extended producer responsibility schemes and carbon border adjustments that will reshape cross-border waste trade economics.
Market Dynamics
The EU Green Deal's circular economy mandates are compressing landfill diversion timelines and forcing contractors to reconfigure material recovery workflows. Demolition-phase waste volumes in mature urban markets now exceed new construction debris, shifting service provider priorities toward decommissioning logistics.
Growth Catalysts
- REACH recycled content thresholds:EU public infrastructure mandates minimum secondary material incorporation, compelling contractors to source certified recycled aggregates. German urban redevelopment projects demonstrate compliance-driven demand acceleration.
- Concrete crushing automation:Mobile processing equipment reduces transportation costs for dense urban demolition sites. French commercial contractors deploy on-site pulverization to meet tight project schedules.
- China's eastern coastal provinces:Megacity demolition volumes in Shanghai and Guangzhou corridors concentrate demand for integrated collection-processing services. MEE enforcement of dual carbon goals penalizes excessive landfill disposal.
Market Restraints
- Diesel fuel cost volatility:Heavy hauling operations face margin compression from fossil fuel price swings. German haulers absorb fuel surcharge fluctuations that clients resist passing through.
- Specialized equipment supply concentration:Mobile screening plant manufacturing clusters in Bavaria and Baden-Württemberg create procurement bottlenecks during capacity crunches.
- Wood waste contamination limits:Treated lumber and composite materials degrade recycling yields. French sorting facilities reject loads exceeding hazardous substance thresholds under EU waste framework directives.
Strategic Opportunities
- India's smart city demolition wave:Urban renewal in Mumbai and Delhi corridors lacks organized waste infrastructure. First-mover operators can anchor collection networks before regulatory formalization.
- Carbon border adjustment mechanisms:EU import tariffs on embodied carbon create premium markets for locally recovered aggregates. British suppliers position secondary materials as compliance shortcuts.
- Digital twin + fleet telematics convergence:Real-time container tracking and predictive routing optimize asset utilization. French operators pilot integrated platforms linking generator sites to processing capacity.
Industry Challenges
- Certified demolition technician shortage:Hazardous material identification and safe dismantling require specialized training. German chambers of commerce struggle to fill apprenticeship pipelines.
- Legacy landfill liability exposure:Pre-regulation disposal sites face remediation obligations that drain capital from operational investments. British waste transfer operators allocate reserves for historical contamination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Waste Management Market |
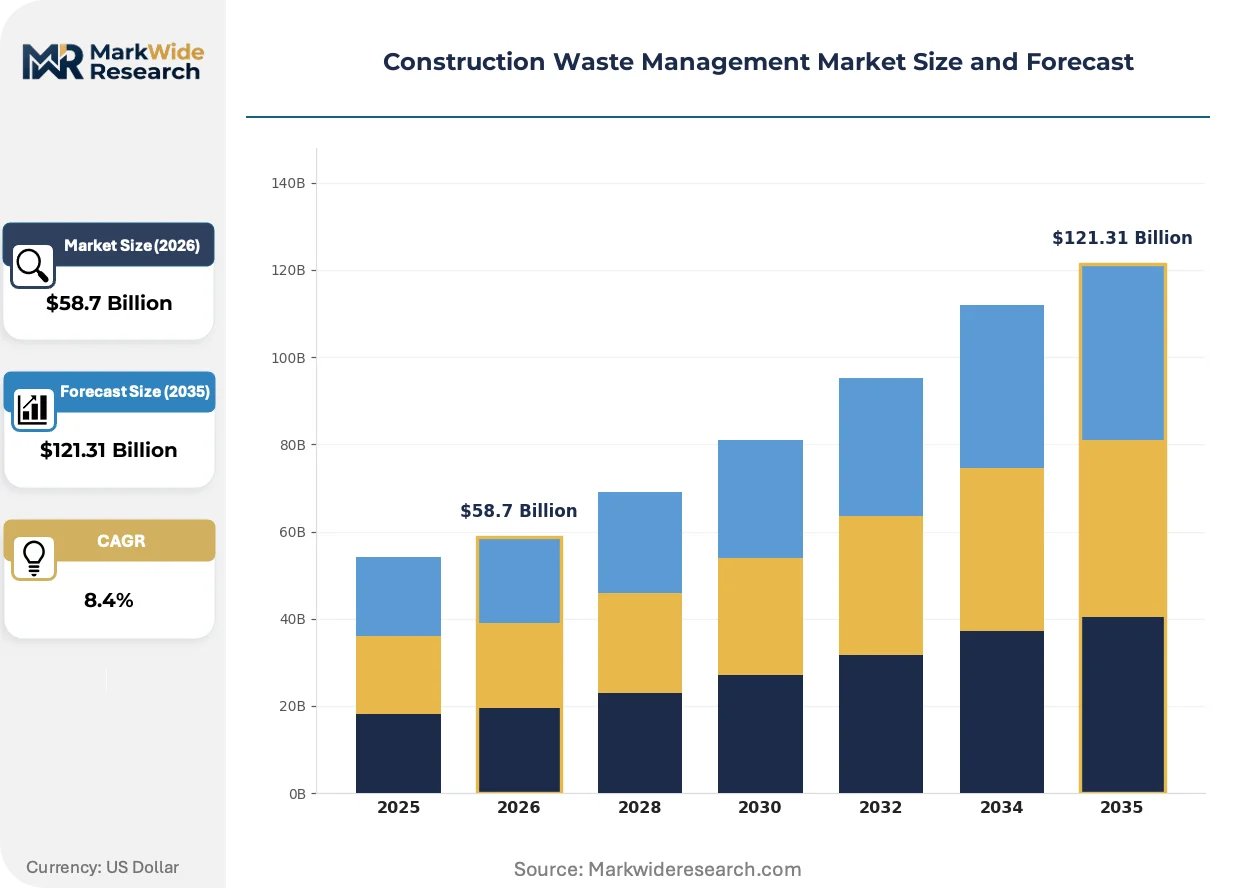
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $121.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Waste Type: Concrete, Wood, Metals, Gypsum Service Type: Disposal, Recycling, Reuse, Treatment Construction Phase: Demolition, Renovation, New Construction, Site Preparation End User: Contractors, Builders, Environmental Firms, Local Authorities |
| Companies Covered | Waste Connections Inc., Biffa plc, Veolia Environnement S.A., FCC Environment, Remondis SE & Co. KG, Waste Management Inc., Cleanaway Waste Management Limited, Casella Waste Systems Inc., Republic Services Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Waste Management Market Emerging Trajectories
Sensor-based sorting and artificial intelligence classification are compressing manual labor dependencies while improving material purity grades. Equipment manufacturers and software developers compete to own the data layer connecting generators to processors.
Near-infrared spectroscopy combined with robotic pickers is electrifying mixed construction debris separation. French recycling complexes deploy these systems to achieve 95% purity in recovered concrete fractions. Commercial contractors in the United Kingdom specify AI-sorted aggregates for LEED-equivalent certifications. The technology is electrifying competitive positioning by enabling premium pricing for certified secondary materials.
EPA Subtitle D enforcement intensification under revised definitions of solid waste is tightening generator accountability. Industrial construction sites in Texas and California now face mandatory waste characterization reporting. Demolition contractors absorb compliance costs through upfront project pricing adjustments.
Performance-based service contracts are displacing tonnage-based hauling agreements. British commercial developers now pay for landfill diversion rates rather than collection volumes. French municipal procurement frameworks reward operators achieving specified recovery percentages. This model compresses price transparency and shifts risk to service providers with superior sorting capabilities.
Construction Waste Management Market Segmentation
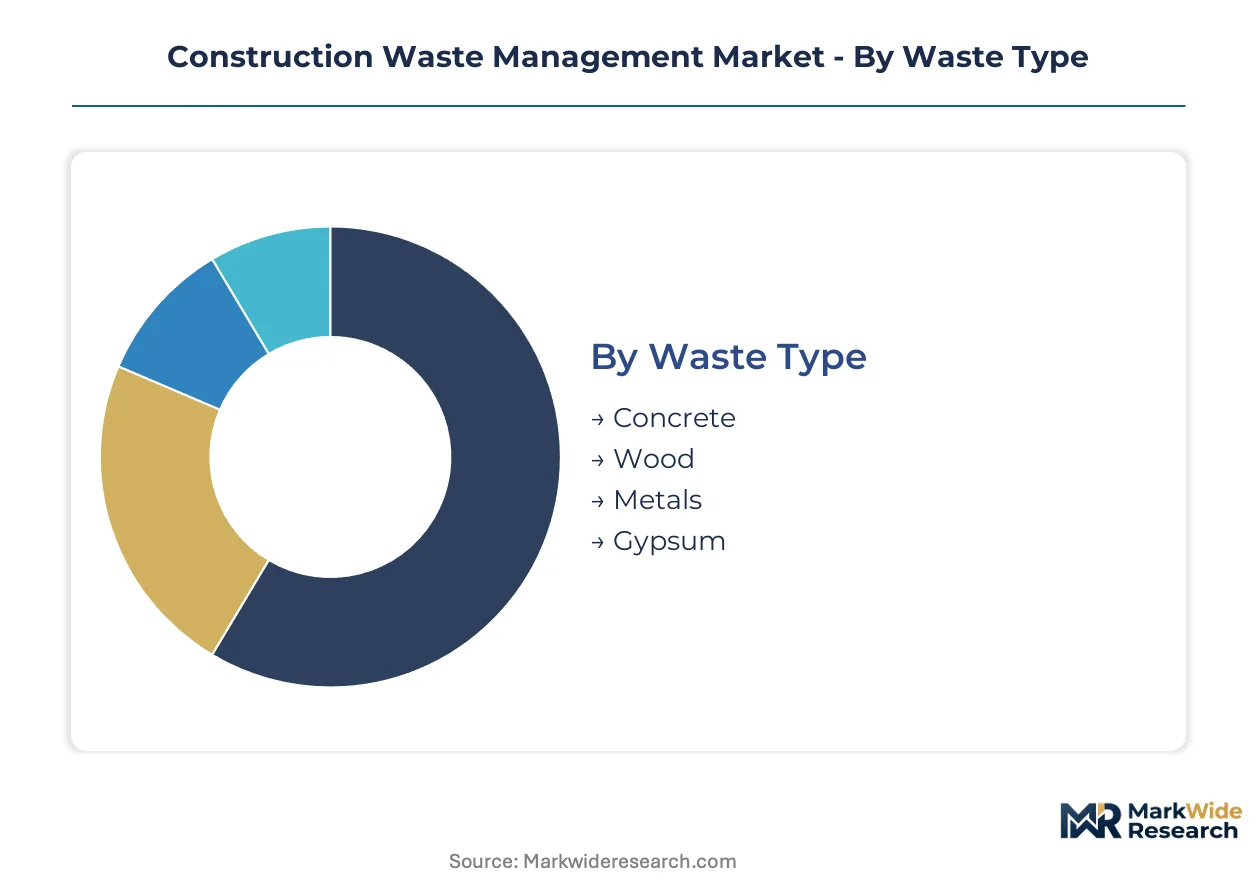
Construction waste management segmentation reflects the physical heterogeneity of debris streams and the regulatory complexity governing their handling. Each dimension—material composition, service intensity, project phase, and customer archetype—commands distinct operational capabilities and margin profiles.
Waste Type:
Building replacement cycles in mature urban centers concentrate demolition-phase debris into specific material categories with divergent recovery economics.
- Concrete:Crushed aggregate from structural demolition constitutes the dominant volume pool, with particle sizes ranging from fine dust to reinforced sections exceeding one cubic meter. Demand clusters in China's eastern coastal provinces where megacity redevelopment generates continuous feedstock for mobile pulverization units.
- Wood:Framing lumber and engineered timber products require hazardous substance screening before secondary use. French sorting facilities enforce strict contamination thresholds under EU waste framework directives, rejecting treated loads that degrade recycling yields.
- Metals:Structural steel and rebar scrap command premium valorization margins through established scrap metal networks.
- Gypsum:Wallboard debris faces limited reuse pathways due to sulfur contamination risks in soil applications.
Concrete sits at the top of the volume ranking, with metals climbing the fastest due to scrap price volatility and carbon border adjustment premiums.
Service Type:
Regulatory pressure on landfill diversion is compressing the addressable market for pure disposal while expanding processing-intensive alternatives.
- Disposal:Landfilling of inert construction debris faces escalating levies across EU member states and Chinese provinces. German haulers absorb fuel surcharge fluctuations that clients resist passing through, compressing margins on long-haul transport to residual landfill capacity.
- Recycling:Certified aggregate production commands price premiums over virgin materials in public infrastructure procurement. British commercial developers now contract for landfill diversion rates rather than collection volumes, shifting performance risk to operators with superior sorting capabilities.
- Reuse:Salvage of intact structural elements and fixtures requires decommissioning logistics expertise that German contractors struggle to staff.
- Treatment:Hazardous material stabilization and thermal processing address contaminated fractions that recycling cannot absorb.
Recycling services are expanding most quickly, while disposal contracts face structural decline as landfill levies escalate.
Construction Phase:
Project lifecycle positioning determines debris predictability, volume concentration, and the feasibility of on-site processing deployment.
- Demolition:Building decommissioning generates the highest single-site volume concentrations and the most complex mixed debris streams. Urban redevelopment projects across Germany and France demonstrate compliance-driven demand acceleration as contractors reconfigure material recovery workflows.
- Renovation:Selective dismantling produces cleaner waste streams with higher reuse potential but fragmented logistics.
- New Construction:Greenfield sites generate predictable inert waste profiles with lower hazardous content exposure.
- Site Preparation:Excavation and clearing activities concentrate soil and rock materials with limited processing requirements.
Demolition-phase waste sits at the top of the volume ranking, with renovation climbing the fastest as building stock ages in European and North American markets.
End User:
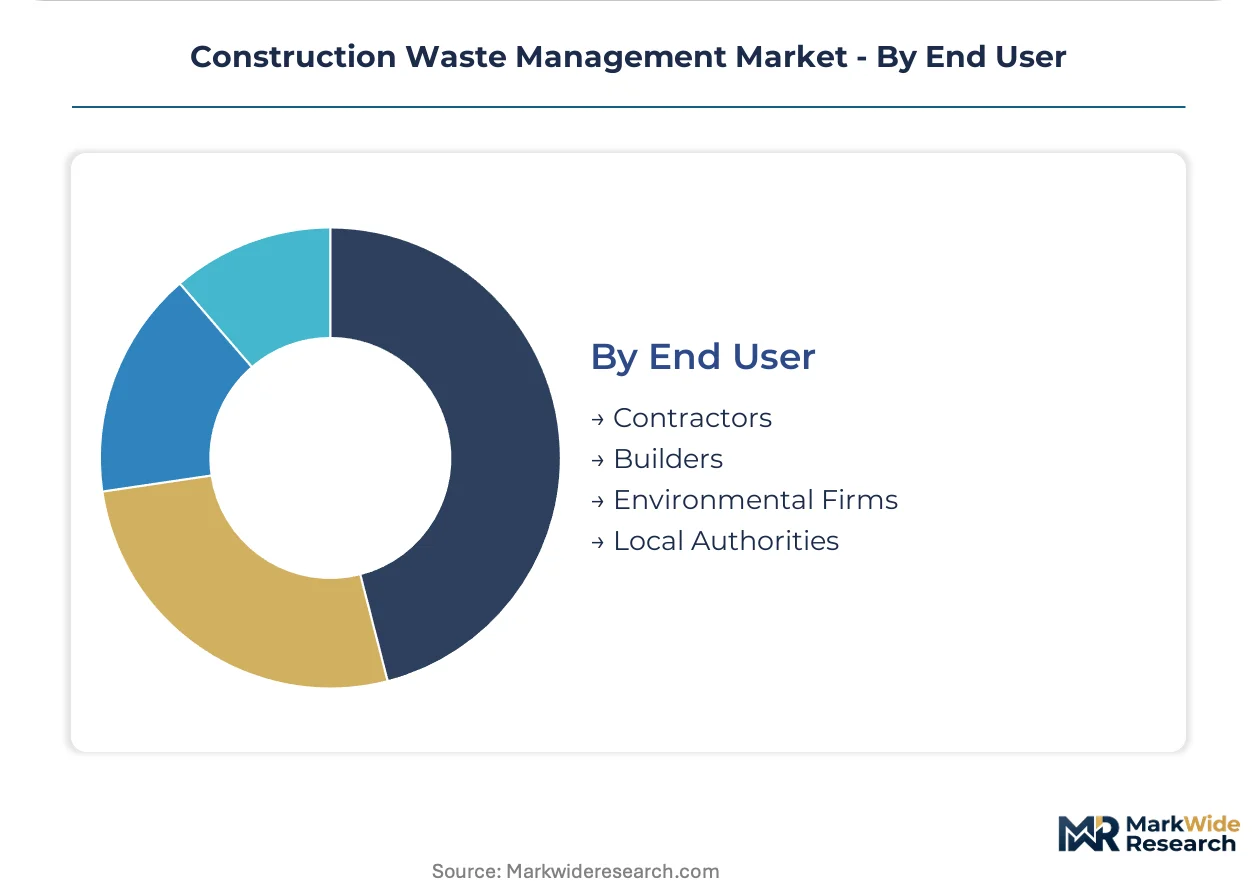
Customer sophistication and procurement authority shape contract structures, compliance obligations, and the feasibility of performance-based pricing models.
- Contractors:General and specialty construction firms bear direct liability for waste characterization under EPA Subtitle D and equivalent EU frameworks. Industrial construction sites in Texas and California now face mandatory waste reporting requirements that demolition contractors absorb through upfront project pricing.
- Builders:Residential and commercial developers specify certified recycled content for LEED-equivalent certifications.
- Environmental Firms:Specialized remediation contractors handle contaminated site clearance with hazardous material expertise.
- Local Authorities:Municipal procurement frameworks in France reward operators achieving specified recovery percentages through outcome-based contracting.
Contractors sit at the top of the volume ranking, with environmental firms climbing the fastest as brownfield redevelopment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting processing capacity toward jurisdictions with lighter landfill levies and faster permitting timelines. Operators in Poland and Romania absorb overflow from German and French demolition projects where compliance costs compress margins. This geographic divergence is accelerating cross-border waste trade infrastructure development.
China
MEE enforcement of dual carbon goals penalizes excessive landfill disposal across eastern coastal provinces. Shanghai and Guangzhou megacity corridors concentrate demand for integrated collection-processing services. Mobile pulverization units cluster in Yangtze River Delta industrial zones where demolition volumes feed continuous aggregate production.
Germany
Urban redevelopment projects in Berlin and Hamburg drive compliance-driven demand acceleration among commercial contractors. REACH recycled content thresholds mandate minimum secondary material incorporation in public infrastructure. Bavaria and Baden-Württemberg host mobile screening plant manufacturing clusters that create procurement bottlenecks during capacity crunches.
United States
EPA Subtitle D enforcement intensification under revised solid waste definitions tightens generator accountability. Industrial construction sites in Texas and California face mandatory waste characterization reporting. Dense transfer station networks anchor North American operations through strategic positioning near major metropolitan demolition corridors.
France
Commercial contractors deploy on-site pulverization to meet tight urban demolition schedules under EU Green Deal timelines. Municipal procurement frameworks reward operators achieving specified recovery percentages through outcome-based contracting. French recycling complexes near Lyon deploy near-infrared spectroscopy systems to achieve certified aggregate purity grades.
United Kingdom
Carbon border adjustment mechanisms create premium markets for locally recovered aggregates displacing high-embodied-carbon imports. British commercial developers contract for landfill diversion rates rather than collection volumes. Performance-based service contracts are displacing tonnage-based hauling agreements across Greater London redevelopment zones.
Construction Waste Management Market Vendor Landscape
European producers anchor one tier; North American specialists hold another through dense logistics networks. The market exhibits moderate consolidation around integrated treatment operators with cross-border capabilities. Three archetypes dominate: diversified environmental conglomerates with circular economy platforms, regional haulers with transfer station density, and specialized concrete processors with mobile crushing fleets. Competitive moves concentrate on strategic partnerships for technology licensing and geographic expansion through municipal contract capture.
Within the diversified conglomerate tier, Veolia Environnement S.A. and Waste Management Inc. exemplify contrasting geographic anchoring strategies. Remondis SE & Co. KG occupies a position among specialized processors with concentrated capabilities in German industrial corridors. These three entities represent the spectrum from integrated environmental services to material-specific recovery operations.
| Leading Market Players |
|---|
| Waste Connections Inc. |
| Biffa plc |
| Veolia Environnement S.A. |
| FCC Environment |
| Remondis SE & Co. KG |
| Waste Management Inc. |
| Cleanaway Waste Management Limited |
| Casella Waste Systems Inc. |
| Republic Services Inc. |
| Others |
Supply Flow & Price Mechanics
Mobile concrete pulverization technology is compressing transportation economics while concentrating processing capacity in Yangtze River Delta industrial zones. This equipment transition simultaneously reduces per-ton handling costs and locks in supplier relationships with fleet operators capable of on-site deployment.
Pricing Analysis
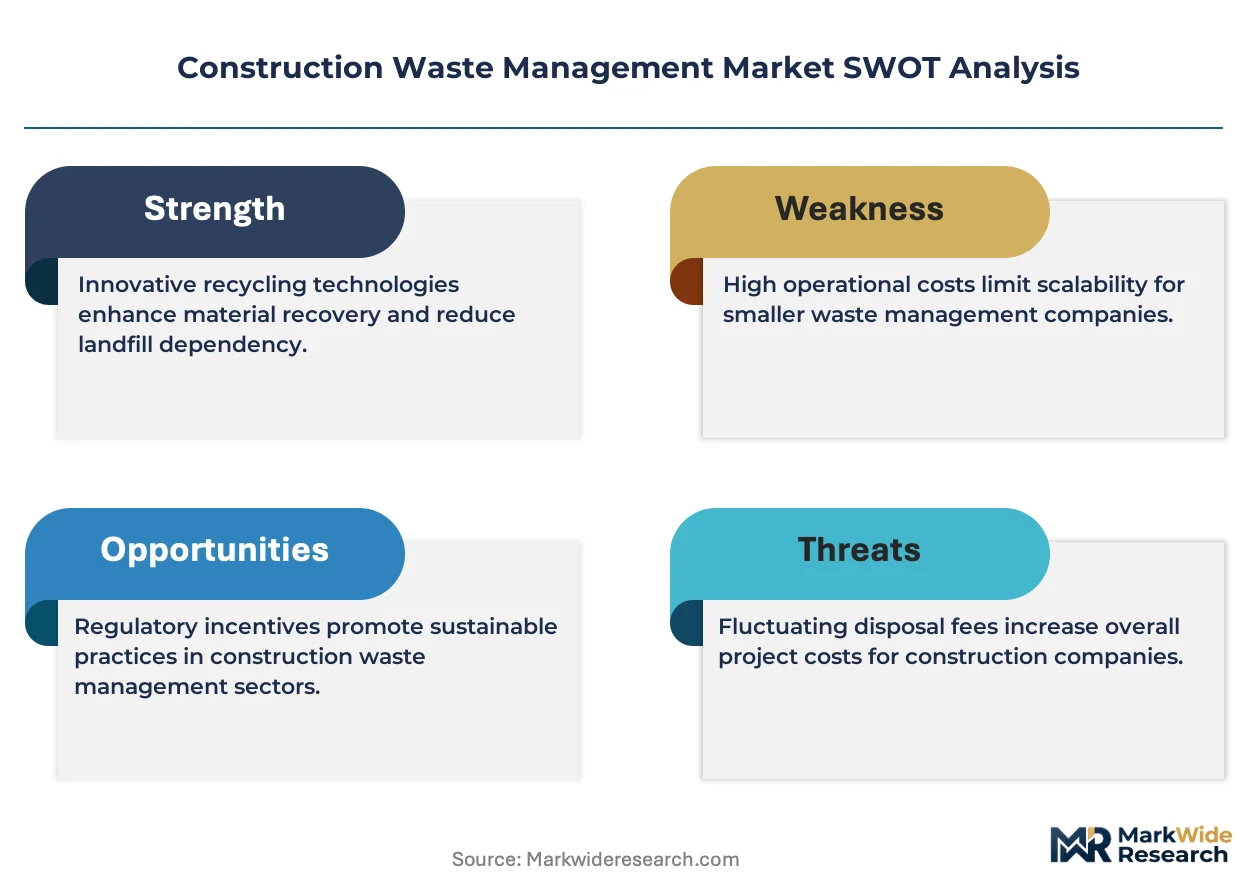
Project-based contracting dominates the service layer, with haulers absorbing fuel surcharge volatility that commercial contractors resist passing through. Price differentiation hinges on certification grade under EU waste framework directives and volume scale for megacity demolition corridors. Cost compression in standard recycling tiers is intensifying because diesel price swings erode fixed-margin contracts. Municipal procurement frameworks in France exhibit lowest price sensitivity due to outcome-based diversion mandates, while independent German contractors face acute pressure on hauling rates.
Supply Chain Analysis
Certified demolition technician shortages in Bavaria and Baden-Württemberg constrain mobile screening plant deployment timelines. Equipment manufacturing clusters in Germany, component fabrication in China, and specialized hauling fleets in France anchor supply concentration. Raw material flows draw from reinforced concrete feedstock, diesel fuel procurement, and replacement wear parts for crushing machinery. Single-source vulnerability runs through Bavarian mobile plant manufacturers during capacity crunches. Distribution runs through integrated collection-processing operators linking generator sites to certified aggregate outlets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The construction waste management market functions as a stable compounder anchored by landfill levy escalation that structurally expands recycling service demand.
For Market Incumbents: Extend mobile processing fleet coverage into China's eastern coastal provinces before regulatory formalization hardens competitive positions. Cement backward integration into certified aggregate production to capture margin compression from fuel price volatility. Defend against specialized concrete processors by anchoring municipal contract relationships in German urban redevelopment corridors. For New Entrants and Emerging Players: EU Green Deal circular economy mandates in France and Germany open a window for decommissioning logistics specialization. Target India's smart city demolition wave in Mumbai and Delhi corridors where organized waste infrastructure remains underdeveloped. Penetrate through performance-based contracting that rewards landfill diversion rates rather than tonnage volumes. For Investors and Strategic Acquirers: Valuations sit cheapest among regional haulers with transfer station density but limited processing certification. The five-to-ten-year viability window favors operators with integrated treatment networks capable of cross-border waste trade. Watch carbon border adjustment mechanism implementation as the inflection signal for premium pricing on locally recovered aggregates.| Strategic Initiative | Industry Significance |
|---|---|
| Mobile Crushing Fleet Expansion | On-site pulverization reduces Yangtze River Delta transportation costs for demolition contractors. |
| Certified Aggregate Production | REACH compliance enables premium positioning in German public infrastructure procurement. |
| Digital Twin Platform Deployment | French operators pilot real-time container tracking linking generator sites to processing capacity. |
| Cross-Border Processing Network | Polish and Romanian facilities absorb overflow from German compliance-cost compression. |
| Hazardous Material Specialization | Technician certification investments address German apprenticeship pipeline shortages. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with demolition contractors, municipal procurement officers, mobile equipment fleet managers, and certified aggregate buyers alongside secondary validation. Sources included MEE enforcement bulletins, EU Green Deal implementation progress reports, EPA Subtitle D guidance documents, and German chamber of commerce apprenticeship data. Bottom-up project pipeline analysis and top-down regulatory impact modeling were triangulated against equipment deployment databases.
Segment-weighting approaches distributed value across waste type, service intensity, construction phase, and end-user archetype throughout the forecast period. CAGRs were derived from regression analysis of historical landfill levy trajectories and projected demolition volume curves. Industry-specific inputs incorporated mobile pulverization unit deployment rates and carbon border adjustment mechanism implementation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under MEE enforcement intensity fluctuations and diesel price volatility spikes. Projections reflect assumptions about regulatory compliance cost pass-through and equipment financing availability. Material deviation in EU Green Deal timeline acceleration or Chinese dual carbon goal enforcement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
India Waste Management Market
Waste Management & Pollution Control
Landfill Gas Market
Waste Management & Pollution Control
India Bio-Medical Waste Management Market
Waste Management & Pollution Control
Saudi Arabia Waste Management Market
Waste Management & Pollution Control
PET Recycling Market
Waste Management & Pollution Control
Global Waste Management Software Market
Waste Management & Pollution Control
Global Waste Disposal Equipment Market
Waste Management & Pollution Control
Metal Recycling Baler Market
Waste Management & Pollution Control
Marine Waste Handling Equipment Market
Waste Management & Pollution Control
Europe Waste Recycling Services Market
Waste Management & Pollution Control
Waste Recycling Services Market
Waste Management & Pollution Control
Waste Management Market
Waste Management & Pollution Control
Reusable Oil Absorbents Market
Waste Management & Pollution Control
United States Trash Bags Market
Waste Management & Pollution Control
North America Solid Waste Management Market
Waste Management & Pollution Control
Qatar Solid Waste Management Market