
 US Medical Waste Management Market | 2026-2036
US Medical Waste Management Market Size, Share, and Industry Trends Forecast 2026-2036
US Medical Waste Management Market Analytics
Market Context
The US medical waste management sector is repositioning around a widening split between premium certified services and commodity pickup operations. Stericycle, Inc. leverages its nationwide incinerator network to command premium pricing for regulated medical waste destruction. Clean Harbors, Inc. anchors its position through backward integration into hazardous waste treatment infrastructure. Waste Management, Inc. competes on route density and municipal contract synergies in secondary markets.
Technical and Segment Structure
US medical waste management encompasses the collection, transport, treatment, and disposal of biohazardous materials generated by healthcare operations, with autoclaving and incineration serving as the primary pathogen-neutralization methods. The service type dimension shows treatment and disposal capturing the deepest margin pools due to capital intensity and permitting barriers, while collection remains fragmented with low switching costs. Application concentration tilts toward hospitals and laboratories where waste volumes and regulatory scrutiny are highest, though dental offices represent an underpenetrated segment with rising compliance awareness.
Regulatory Framework and Outlook
The EPA, DOT, and OSHA collectively govern cradle-to-grave handling standards, with state environmental agencies layering additional treatment and manifesting rules that shape local competitive dynamics. FDA oversight of pharmaceutical waste classification and DEA controlled-substance destruction protocols further segment service requirements and credentialing thresholds. Stakeholders must monitor emerging state legislation on pharmaceutical take-back mandates and electrification of transport fleets as these forces will reshape capital deployment and contract structures.
Market Dynamics
The EPA's updated hazardous waste generator improvements rule is compressing compliance timelines and forcing healthcare facilities to consolidate vendor relationships around cradle-to-grave certified operators rather than fragmented local haulers.
Growth Catalysts
- Outpatient surgical center expansion:Ambulatory facilities in Texas and Florida are doubling waste generation per site as procedure volumes migrate from hospitals, creating contracted service demand for specialized biohazard handling.
- OSHA Bloodborne Pathogens Standard enforcement:Workplace safety inspections are intensifying sharps container compliance mandates, driving replacement cycles and premium service attachments.
- Pharmaceutical waste reclassification:FDA guidance on hazardous drug disposal is expanding the regulated universe beyond traditional RMW into cytotoxic and antineoplastic streams requiring incineration.
Market Restraints
- Permitting scarcity for thermal treatment:New commercial incinerator construction faces multi-year EPA air quality permitting delays in California and Northeastern states, capping regional treatment capacity.
- Diesel transport cost volatility:Medical waste collection routes run on thin density economics; fuel price spikes compress margins on fixed-price municipal contracts.
- Autoclave residue limitations:Steam sterilization neutralizes pathogens but leaves bulky treated waste requiring landfill disposal, creating secondary handling costs and weight-based tipping fee exposure.
Strategic Opportunities
- Long-term care facility penetration:Nursing homes and assisted living operators in the Midwest remain underpenetrated by national vendors, presenting route consolidation plays.
- Electrified fleet mandates:California's Advanced Clean Trucks regulation is accelerating zero-emission vehicle deployment, enabling first-mover branding and municipal contract preference.
- Telehealth packaging waste streams:Remote care expansion is generating new categories of single-use diagnostic kit disposal requiring specialized reverse logistics infrastructure.
Industry Challenges
- DOT hazardous materials driver certification:The specialized commercial license requirement constrains labor pool depth and inflates wage premiums in tight trucking markets.
- Multi-jurisdictional manifesting complexity:Waste crossing state lines triggers overlapping Texas Commission on Environmental Quality, California Department of Public Health, and Florida Department of Health tracking rules, creating compliance friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Medical Waste Management Market |
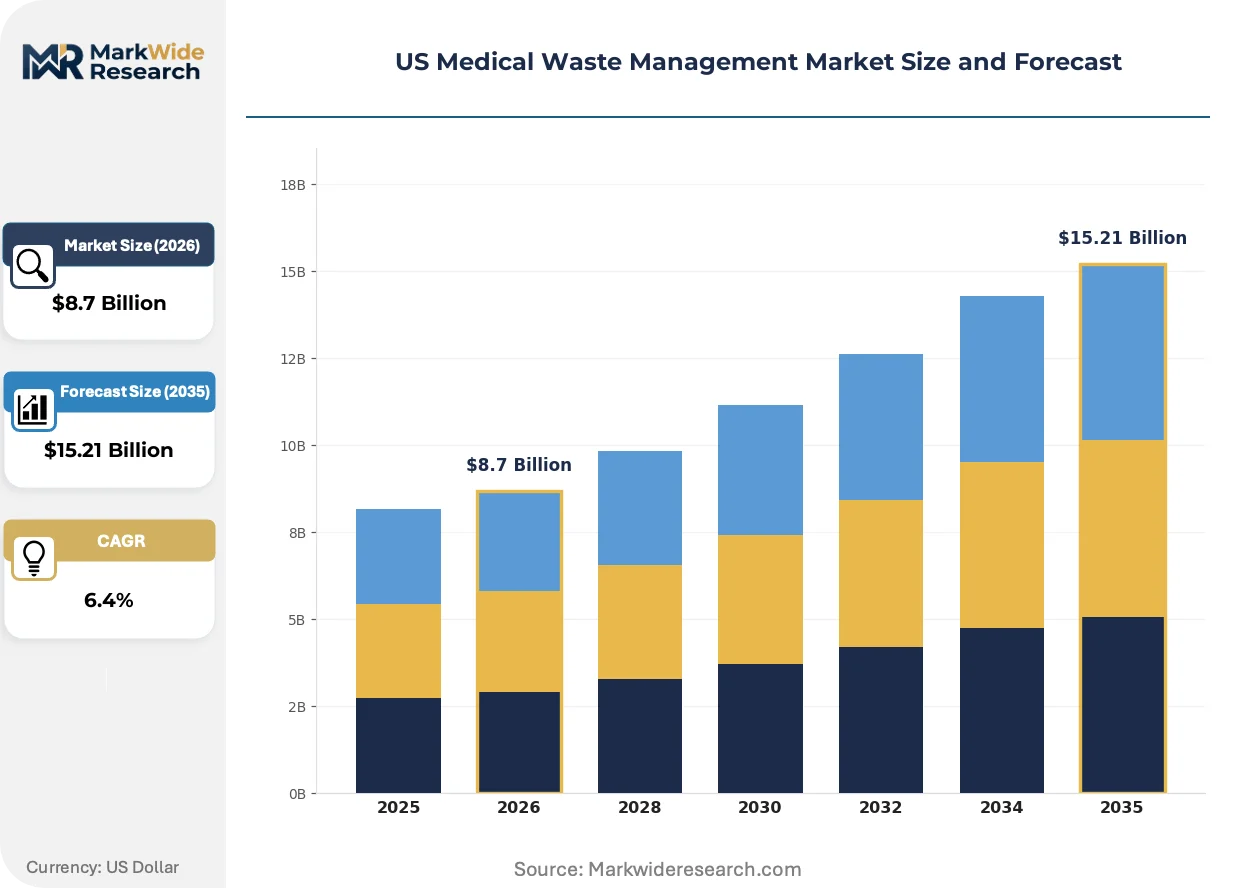
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Collection, Treatment, Disposal, Recycling Application: Hospitals, Clinics, Dental Offices, Laboratories Waste Type: Biohazardous, Sharps, Pharmaceutical, Non-Hazardous End User: Healthcare Providers, Research Facilities, Waste Management Companies, Government Agencies |
| Companies Covered | Stericycle, Inc., Clean Harbors, Inc., Waste Management, Inc., Veolia Environmental Services, Republic Services, Inc., MedPro Disposal, Triumvirate Environmental, Inc., Waste Connections, Inc., Curtis Bay Medical Waste Services, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Medical Waste Management Market Evolving Landscape
Digital tracking systems and alternative treatment chemistries are displacing paper manifests and steam sterilization as the baseline infrastructure for compliant medical waste handling across US healthcare networks.
Advanced oxidative process technology is integrating microwave and ultraviolet-C radiation with chemical catalysts to achieve pathogen kill at lower temperatures than conventional autoclaving. Regional hospital systems in the Southeast are piloting these units for on-site treatment of isolation waste. The technology is integrating decentralized processing capability into facility operations, compressing transport dependency and enabling same-day destruction cycles.
The EPA's e-Manifest system is mandating electronic submission of hazardous waste shipment data, replacing paper documentation that has governed cradle-to-grave tracking since the 1980s. Treatment facilities must upgrade data infrastructure to interface with federal databases or face manifest rejection. Small regional operators lacking IT development resources are outsourcing compliance to software vendors, creating a new service layer between generators and disposal sites.
Consolidated service agreements are displacing point-solution contracts as health systems centralize procurement under single-source vendor relationships. Hospital networks in the Northeast are bundling regulated medical waste, pharmaceutical waste, and sharps management under unified pricing structures with performance guarantees. The shift is most visible in multi-state Catholic health systems where standardization across facilities overrides local purchasing autonomy.
US Medical Waste Management Market Segmentation
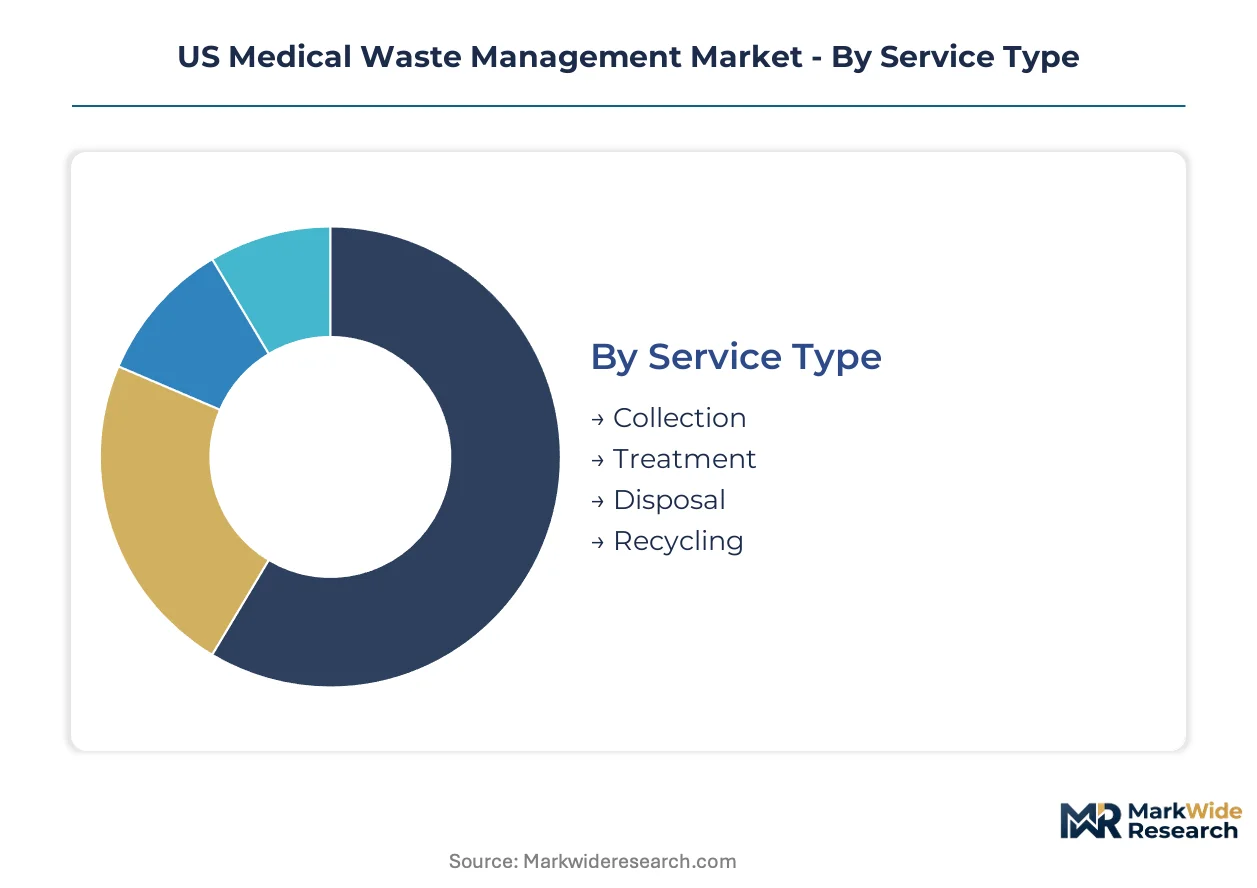
Medical waste management procurement varies sharply by operational scale, regulatory exposure, and waste stream complexity. Understanding these fault lines reveals where premium certified services command pricing power versus where commodity logistics dominate contract negotiations.
Service Type:
Capital intensity and permitting barriers create stark margin differentiation across the service stack.
- Collection:Route-density economics govern profitability, with fixed-price municipal contracts exposing operators to diesel cost volatility. Demand concentrates in Texas and Florida where outpatient surgical center expansion is fragmenting pickup schedules across smaller generators.
- Treatment:Autoclaving and incineration require EPA air quality permits that face multi-year delays in California and Northeastern states, capping regional capacity. Stericycle leverages its nationwide incinerator network to capture premium pricing for pathogen-neutralization services.
- Disposal:Landfill tipping fees and residue handling costs compress margins on autoclave-treated waste streams.
- Recycling:Plastics recovery from clean packaging waste remains nascent, constrained by contamination protocols and limited reprocessing infrastructure.
Volume sits with Collection; growth tilts toward Treatment as EPA cradle-to-grave tracking tightens.
Application:
Waste generation intensity scales with procedure volume and regulatory scrutiny intensity.
- Hospitals:High-volume generators with consolidated procurement functions. The Northeast's multi-state Catholic health systems are bundling regulated medical waste, pharmaceutical waste, and sharps management under unified vendor relationships with performance guarantees.
- Clinics:Ambulatory facilities in Texas and Florida are doubling waste generation per site as procedures migrate from inpatient settings, stretching contracted service capacity.
- Dental Offices:Sharps and amalgam waste streams dominate, with OSHA Bloodborne Pathogens Standard enforcement driving compliance attachment rates.
- Laboratories:Research operations generate cytotoxic and antineoplastic streams requiring incineration under FDA hazardous drug disposal guidance.
Hospitals anchor current revenue; clinics are expanding most quickly as care decentralizes.
Waste Type:
Pathogen risk and regulatory classification determine handling protocols and pricing tiers.
- Biohazardous:Infectious materials requiring autoclaving or incineration. EPA's updated hazardous waste generator improvements rule is compressing compliance timelines for healthcare facilities managing these streams.
- Sharps:Needles and lancets governed by OSHA containment mandates. Workplace safety inspections are intensifying replacement cycles for puncture-resistant containers.
- Pharmaceutical:DEA controlled-substance destruction protocols and FDA reclassification of hazardous drugs are expanding the regulated universe beyond traditional regulated medical waste.
- Non-Hazardous:General waste with lowest compliance burden, competing with municipal sanitation services on cost.
Biohazardous waste dominates tonnage; pharmaceutical streams are gaining share fastest as disposal rules tighten.
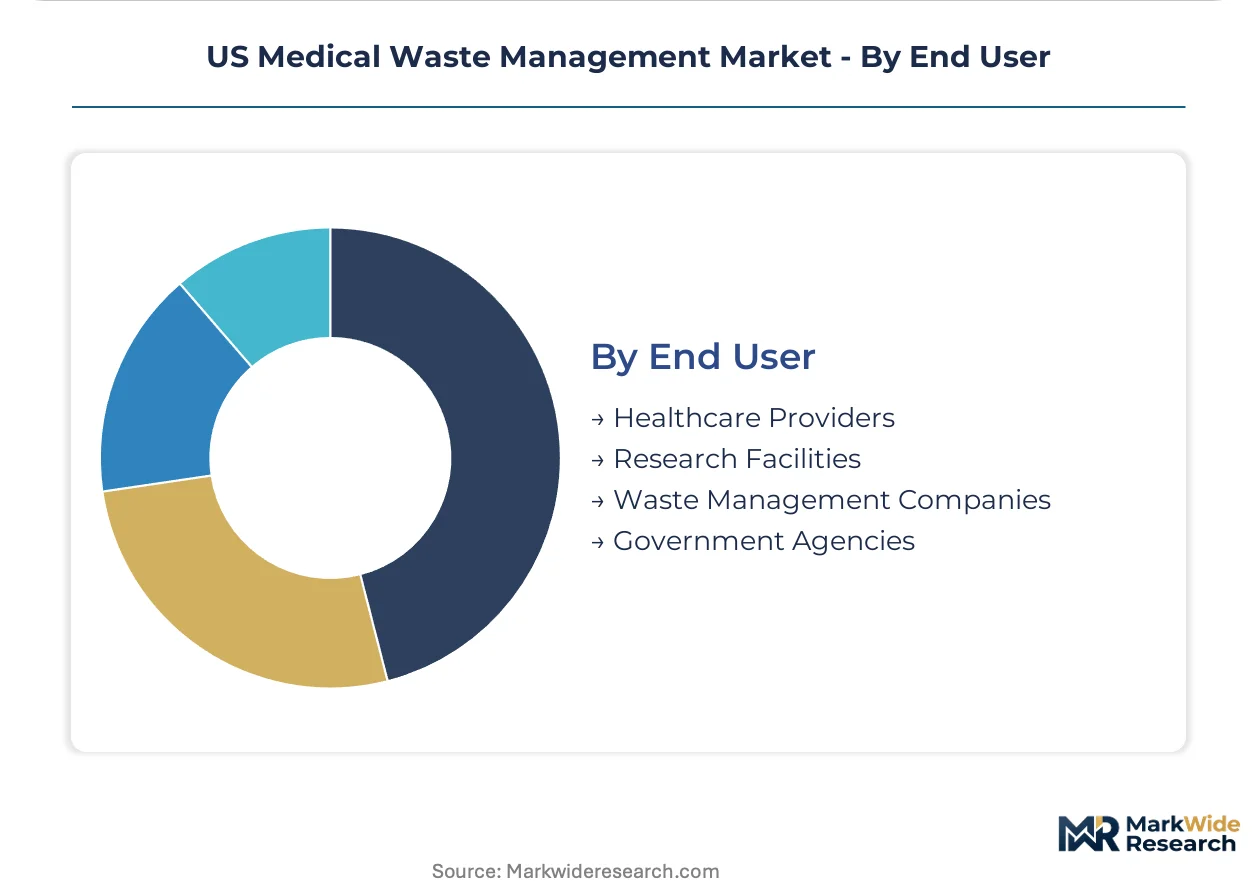
End User:
Procurement sophistication and contract scale separate national account opportunities from fragmented local sales.
- Healthcare Providers:Hospital networks and physician practices with consolidated purchasing. Clean Harbors anchors position through backward integration into hazardous waste treatment infrastructure.
- Research Facilities:Universities and biotech operations generating specialized chemical and biological waste requiring custom handling protocols.
- Waste Management Companies:Regional haulers outsourcing treatment to permitted facilities, creating intermediary relationships in the value chain.
- Government Agencies:VA hospitals and public health departments with mandated competitive bidding and small-business set-aside requirements.
Healthcare Providers represent the deepest contract values; Research Facilities show the steepest expansion trajectory as biotech investment concentrates in Boston and San Diego clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston anchors the densest concentration of medical waste management infrastructure, with Texas Medical Center generating volumes that attract specialized haulers and treatment operators from across the Gulf Coast corridor.
Texas
Outpatient surgical centers in Dallas-Fort Worth and Houston are fragmenting pickup schedules across smaller generators, stretching contracted service capacity. The Texas Commission on Environmental Quality enforces cradle-to-grave tracking rules that exceed federal baselines. The Austin-San Antonio corridor is seeing independent laboratories cluster near biotech incubators, creating localized pharmaceutical waste streams requiring incineration.
California
Los Angeles County hospital networks are bundling regulated medical waste, pharmaceutical waste, and sharps management under unified vendor relationships. The state's Advanced Clean Trucks regulation is accelerating zero-emission vehicle deployment for waste transport fleets. The San Francisco Bay Area faces multi-year EPA air quality permitting delays for new commercial incinerators, capping regional treatment capacity and forcing waste export to Nevada and Arizona.
Florida
Ambulatory facilities in Miami-Dade and Broward counties are doubling waste generation per site as procedures migrate from inpatient settings. The Florida Department of Health layers additional manifesting rules on interstate shipments, creating compliance friction for national operators. The Tampa-Orlando corridor is attracting long-term care facility consolidation plays as nursing home chains centralize procurement.
New York
Multi-state Catholic health systems in the Northeast are standardizing waste handling across facilities, overriding local purchasing autonomy. The state's Department of Environmental Conservation enforces stringent treatment facility licensing that limits new market entrants. The New York City metro area is piloting advanced oxidative process technology for on-site isolation waste treatment, compressing transport dependency.
Illinois
Chicago-area hospital networks are consolidating vendor relationships around cradle-to-grave certified operators. The Illinois Environmental Protection Agency aligns with EPA hazardous waste generator improvements rule timelines. The Rockford-Peoria corridor remains underpenetrated by national vendors, presenting route consolidation opportunities for regional haulers.
US Medical Waste Management Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and treatment infrastructure ownership. The market structure concentrates around three national operators with incinerator networks, while regional haulers compete on route density in secondary markets. Two strategic archetypes dominate: capital-intensive treatment owners and logistics-focused collection specialists. Competitive moves center on M&A for permit acquisition and strategic partnerships for e-Manifest compliance technology.
Among publicly traded waste services conglomerates, Stericycle, Inc. and Waste Management, Inc. occupy positions at opposite ends of the integration spectrum, with the former exemplifying treatment-forward positioning and the latter representing route-density logistics scale. Clean Harbors, Inc. anchors the hazardous waste backward integration archetype, leveraging captive infrastructure for pharmaceutical and chemical stream handling. These three represent the structural poles around which mid-cap regional operators and specialized dental-lab service firms organize their competitive responses.
| Leading Market Players |
|---|
| Stericycle, Inc. |
| Clean Harbors, Inc. |
| Waste Management, Inc. |
| Veolia Environmental Services |
| Republic Services, Inc. |
| MedPro Disposal |
| Triumvirate Environmental, Inc. |
| Waste Connections, Inc. |
| Curtis Bay Medical Waste Services |
| Others |
Value Network & Pricing Analysis
California's Advanced Clean Trucks regulation gates both qualified supply and premium-tier pricing access, as zero-emission fleet certification becomes a de facto barrier to municipal contract eligibility while commanding per-route pricing premiums from healthcare networks seeking sustainability-aligned vendors.
Pricing Analysis
Outcome-based pricing anchored to EPA-compliant destruction certificates dominates contract structures, with Stericycle and Clean Harbors capturing premiums through guaranteed pathogen-neutralization documentation. Price differentiation separates cradle-to-grave certified operators from regional haulers lacking incinerator ownership or multi-state manifesting capability. Cost compression in the collection tier is intensifying because diesel transport volatility exposes fixed-price municipal contracts to margin erosion. Outpatient surgical centers and long-term care facilities show the steepest price sensitivity, while multi-state hospital systems prioritize compliance guarantees over per-pound rates.
Supply Chain Analysis
Regional distribution centers in Texas, California, and Florida anchor hub-and-spoke collection networks, with Houston and Los Angeles serving as primary consolidation points for Gulf Coast and West Coast waste streams. Raw material dependencies center on diesel fuel for transport fleets, specialized container polymers for sharps and biohazard packaging, and chemical catalysts for advanced oxidative treatment systems. Single-source vulnerability concentrates in commercial incinerator capacity, where multi-year EPA air quality permitting delays in California and Northeastern states cap regional treatment infrastructure. Distribution runs through contracted route density models, with national operators leveraging owned treatment assets and regional haulers outsourcing to permitted third-party facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race, with incinerator ownership and hazardous waste treatment infrastructure serving as the decisive upstream lever separating premium-margin players from commodity logistics competitors.
For Market Incumbents: Deploy EPA e-Manifest compliance technology as the priority defensive lever to lock in health system contracts before smaller regional operators can upgrade data infrastructure. Consolidate around cradle-to-grave certified operations by acquiring permitted treatment capacity in California and Northeastern states where permitting scarcity caps new entrant supply. The threat of pharmaceutical waste reclassification under FDA hazardous drug guidance demands backward integration into cytotoxic stream handling capability. For New Entrants and Emerging Players: Independent laboratories clustered near biotech incubators in the Austin-San Antonio corridor represent the most penetrable white-space target, generating localized pharmaceutical waste streams requiring incineration but lacking dedicated vendor relationships. Long-term care facility chains in the Midwest present route consolidation opportunities where national operators remain underrepresented. A specialized reverse logistics angle targeting telehealth diagnostic kit disposal can bypass incumbent route density advantages in traditional healthcare settings. For Investors and Strategic Acquirers: California Department of Public Health treatment facility licensing delays exceeding thirty-six months are the leading indicator that permitted incinerator assets will command scarcity premiums across the analysis window. The long-term viability framing centers on operators with captive hazardous waste infrastructure capable of handling expanding pharmaceutical and chemical stream classifications. Acquisition targets should emphasize regional haulers with dense route networks in Texas or Florida that can be integrated with national treatment footprints.| Strategic Initiative | Industry Significance |
|---|---|
| Incinerator Network Expansion | EPA air quality permitting in California and Northeastern states creates multi-year capacity constraints for competitors. |
| e-Manifest Compliance Technology | Electronic hazardous waste tracking mandates from EPA force infrastructure upgrades across treatment facilities. |
| Zero-Emission Fleet Deployment | California's Advanced Clean Trucks regulation enables municipal contract preference for certified operators. |
| Pharmaceutical Waste Infrastructure | FDA hazardous drug reclassification expands regulated universe beyond traditional regulated medical waste streams. |
| Long-Term Care Route Consolidation | Midwest nursing home chains centralizing procurement present underpenetrated demand for national vendors. |
Research Methodology
Multi-period observation of EPA enforcement patterns, state-level manifesting rule changes, and health system procurement consolidation anchored the trend analysis, supplemented by interviews with waste treatment facility operators, hospital GPO contracts managers, biomedical engineers, and hazardous materials transport specialists. Secondary validation drew from EPA e-Manifest system disclosures, DOT hazardous materials incident reports, state environmental agency permitting databases, and SEC filings of publicly traded waste services conglomerates. Bottom-up route density modeling and top-down market sizing triangulated volume and value estimates.
Input-output matrix framing structured the analytical approach across the projection horizon, with segmentation dimensions spanning service type, application, waste classification, and end-user procurement sophistication. CAGRs were derived from trend extrapolation of outpatient surgical center expansion rates, long-term care facility penetration trajectories, and pharmaceutical waste stream growth under evolving FDA guidance. Industry-specific forecast inputs included diesel transport cost volatility assumptions and EPA air quality permitting queue projections for thermal treatment capacity.
Several conditions sit outside the modeled scope, including unforeseen federal preemption of state manifesting rules, breakthrough alternative treatment technologies achieving cost parity with incineration, and macroeconomic disruptions to healthcare utilization patterns. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
Asia-Pacific Municipal Solid Waste Management Market
Waste Management & Pollution Control
Waste Management Market
Waste Management & Pollution Control
Trash Pump Market
Waste Management & Pollution Control
Europe Plastic Waste Management Market
Waste Management & Pollution Control
Reusable Oil Absorbents Market
Waste Management & Pollution Control
Asia-Pacific Industrial Waste Management Market
Waste Management & Pollution Control
Scrap Metal Recycling Market
Waste Management & Pollution Control
PET Recycling Market
Waste Management & Pollution Control
India Commercial Food Waste Decomposer Market
Waste Management & Pollution Control
North America Solid Waste Management Market
Waste Management & Pollution Control
US Municipal Solid Waste Management Market
Waste Management & Pollution Control
Industrial Waste Management Market
Waste Management & Pollution Control
Global Oil Spill Management Market
Waste Management & Pollution Control
Global Smart Trash Bin Market
Waste Management & Pollution Control
Vietnam Waste Management Market
Waste Management & Pollution Control
Waste Compactor Bins Market